
 Orphan Diseases Market | 2026-2036
Orphan Diseases Market Size, Share, and Industry Trends Forecast 2026-2036
Orphan Diseases Market Analytics
Specialized clinical trial investigators is reorganizing how drug developers allocate resources across geographies. Vertex Pharmaceuticals leverages its cystic fibrosis franchise to sustain dominance in protein modulation therapies. Biogen anchors its position in neurological rare diseases through antisense oligonucleotide expertise. Amgen competes via biologics manufacturing scale that reduces cost per dose for ultra-rare patient populations.
Orphan diseases encompass conditions affecting fewer than 200,000 individuals in the United States, with therapies typically requiring recombinant DNA technology, viral vector platforms, or small-molecule chaperone mechanisms to address single-gene defects or enzyme deficiencies. Gene therapies represent the fastest-expanding product type as one-time curative interventions command premium reimbursement and reshape lifetime cost calculations for payers. Biologics maintain the largest revenue pool among product types due to established manufacturing infrastructure and broader prescriber familiarity, while small molecules face margin compression from biosimilar competition in select rare indications.
The FDA Orphan Drug Act, EMA orphan designation pathways, and Japan's PMDA priority review vouchers collectively determine market access timelines and exclusivity value for developers. These frameworks incentivize sponsors to pursue indications with extremely limited prevalence by offsetting clinical trial costs through tax credits and waived fees. Stakeholders must monitor how gene therapy durability data and outcomes-based contracting evolve to justify upfront costs against traditional chronic administration models.
Market Dynamics
The convergence of gene therapy durability data and outcomes-based contracting frameworks is restructuring how payers evaluate lifetime cost against chronic administration models, forcing developers to demonstrate sustained clinical benefit across multi-year horizons.
Growth Catalysts
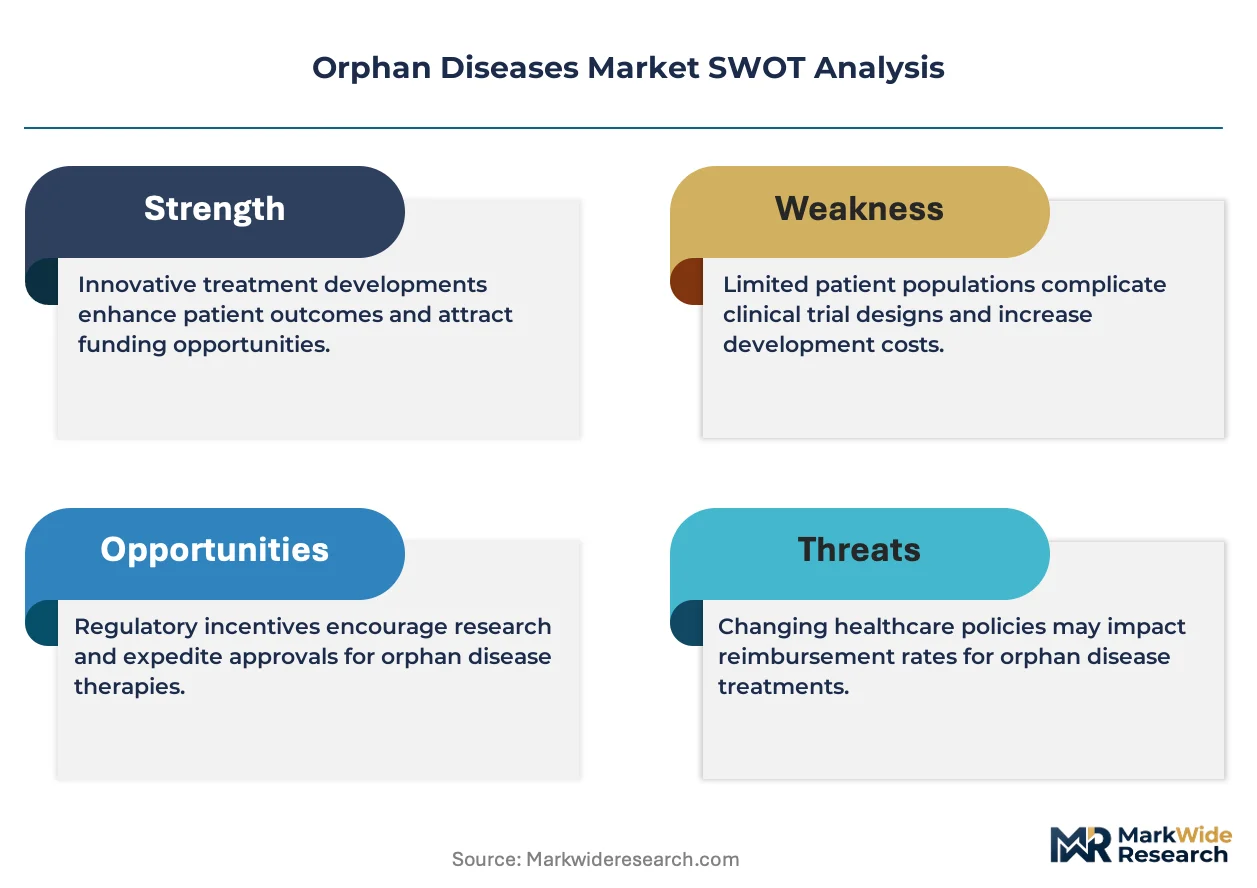
- FDA Orphan Drug Act:Tax credits and waived clinical trial fees offset development costs for sponsors pursuing indications below 200,000 patient prevalence, accelerating pipeline investment.
- Specialty clinic networks:Dedicated rare disease centers in Boston, San Diego, and Basel consolidate patient recruitment and longitudinal data capture for natural history studies.
- Recombinant enzyme replacement:Manufacturing advances in Chinese hamster ovary cell lines reduce production costs for ultra-rare lysosomal storage disorders.
Market Restraints
- Viral vector supply concentration:Suspension-based AAV production capacity clusters in Massachusetts and Pennsylvania, creating single-source dependency for gene therapy developers.
- Reimbursement timeline friction:Germany's G-BA benefit assessment process delays market access by 12-18 months post-EMA approval, compressing effective exclusivity windows.
- Small-molecule biosimilar erosion:Imatinib and other kinase inhibitor copies displace originator revenue in chronic myeloid leukemia and gastrointestinal stromal tumor indications.
Strategic Opportunities
- Japan's PMDA priority review vouchers:Accelerated approval pathways for pediatric rare diseases create first-mover advantages for sponsors with Japan-ready dossiers.
- Antisense oligonucleotide expansion:Neurological applications beyond spinal muscular atrophy target Huntington's disease and ALS with validated CNS delivery mechanisms.
- Direct-to-patient telemedicine:Virtual genetic counseling and remote monitoring platforms extend reach into dispersed rare disease populations across rural Australia and Canada.
Industry Challenges
- Gene therapy manufacturing workforce scarcity:Cell culture technicians with GMP viral vector experience command premium compensation in the Boston-Cambridge corridor.
- Real-world evidence collection infrastructure:Patient registries require multi-year investment to generate payer-acceptable durability data for one-time curative interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orphan Diseases Market |
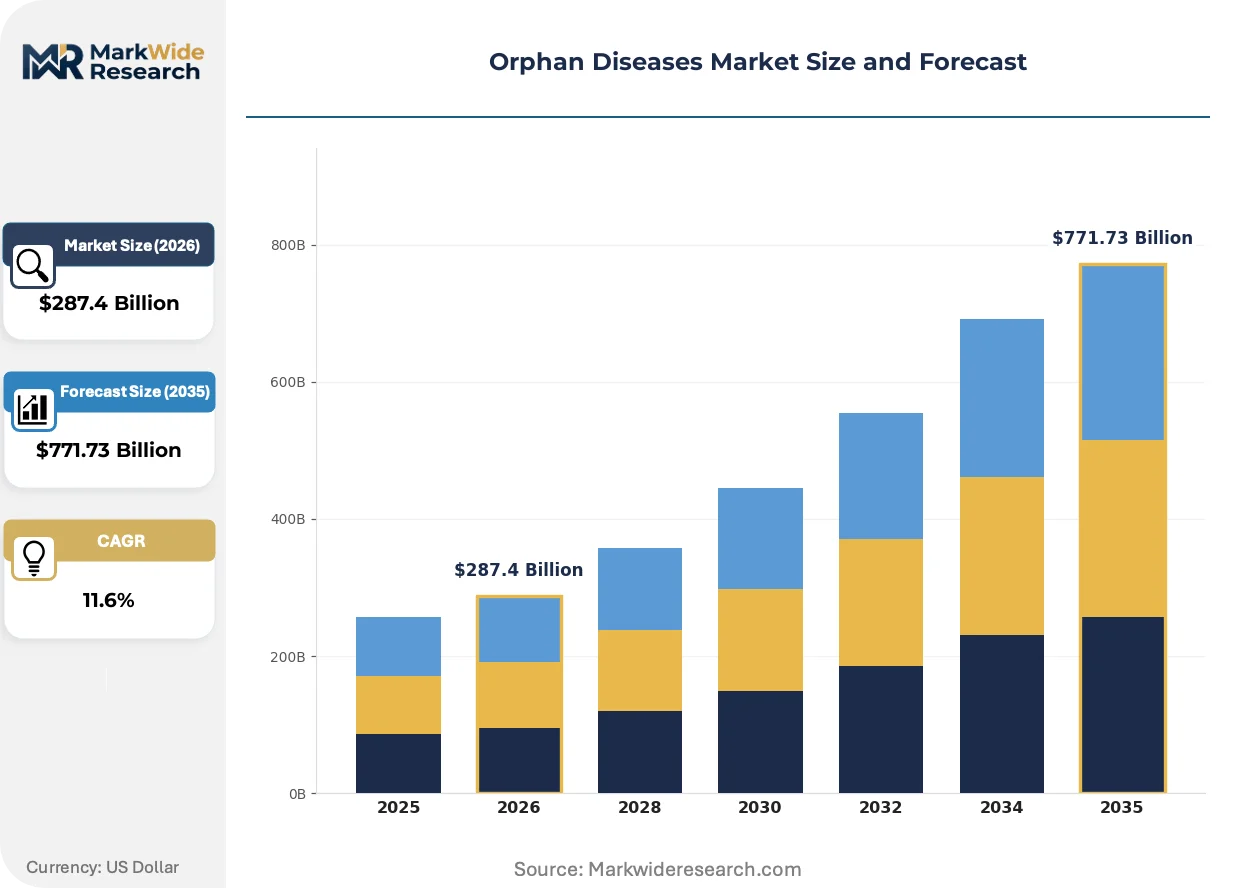
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $771.73 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Neurological Disorders, Autoimmune Conditions, Metabolic Disorders, Rare Cancers Delivery Mode: Oral, Injectable, Infusion, Transdermal End User: Pharmaceutical Companies, Research Institutions, Hospitals, Specialty Clinics Product Type: Biologics, Gene Therapies, Small Molecules, Combination Therapies |
| Companies Covered | Vertex Pharmaceuticals, Biogen, Amgen, Sanofi, Novartis, Roche, Regeneron Pharmaceuticals, AstraZeneca, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orphan Diseases Market Evolving Landscape
Platform standardization across viral vector manufacturing and the emergence of in vivo gene editing are compressing development timelines while raising the bar for clinical differentiation. These forces are reshaping competitive positioning around manufacturing scale versus therapeutic modality innovation.
Adeno-associated virus serotype engineering is miniaturizing payload constraints and tissue tropism limitations that previously restricted gene therapy applicability. Pediatric neurology centers at Children's Hospital of Philadelphia and Great Ormond Street Hospital are adopting next-generation AAV capsids for earlier intervention windows. This capsid diversification is enabling CNS-targeted delivery that was previously inaccessible with legacy serotypes.
Europe's Clinical Trials Regulation harmonizes submission procedures across member states, eliminating redundant national competent authority reviews that previously fragmented multi-country studies. Sponsors now file once through the CTIS portal for simultaneous authorization across Germany, France, and Italy. The regulation compresses study startup timelines by eight to twelve months for rare disease trials requiring cross-border patient recruitment.
Payers in the United States are unbundling gene therapy reimbursement from traditional pharmacy benefit structures, establishing distinct medical benefit carve-outs with outcomes-based stop-loss provisions. Massachusetts and New York Medicaid programs pilot annuity-style payment models spreading Zolgensma-class costs across five-year horizons. This financial engineering addresses budget impact concerns that previously blocked formulary access for one-time interventions exceeding two million dollars per patient.
Orphan Diseases Market Segmentation
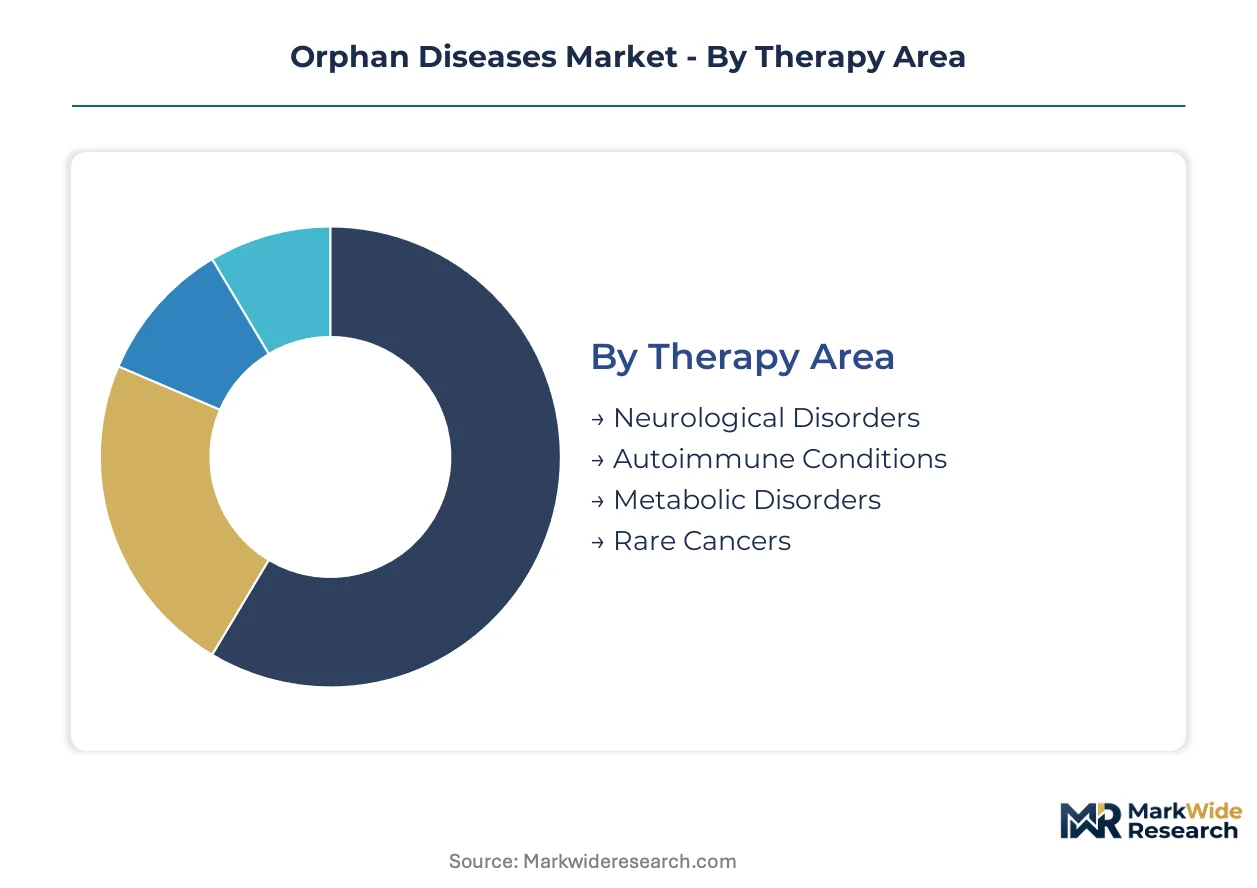
Orphan disease therapeutics fragment across therapy areas, delivery technologies, and institutional buyers with divergent procurement criteria. Segmentation reveals where manufacturing scale, regulatory exclusivity, and reimbursement infrastructure align to concentrate commercial returns.
Therapy Area:
FDA breakthrough therapy designations cluster disproportionately in neurological and metabolic categories, reflecting unmet need severity and biomarker validation maturity.
- Neurological Disorders:Antisense oligonucleotides and AAV-based gene therapies target spinal muscular atrophy, Huntington's disease, and ALS with validated CNS delivery mechanisms. Massachusetts General Hospital and University College London anchor natural history study recruitment for these indications. Payer willingness to accept premium pricing runs highest here due to irreversible disease progression and pediatric onset populations.
- Metabolic Disorders:Enzyme replacement therapies and substrate reduction approaches address lysosomal storage diseases including Gaucher, Fabry, and Pompe. Manufacturing in Chinese hamster ovary cell lines dominates, though plant-based expression systems are gaining traction for glycosylation-sensitive enzymes. Newborn screening expansion in California, New York, and Texas is compressing diagnostic delay.
- Autoimmune Conditions:Rare immunodeficiencies and autoinflammatory syndromes require biologics targeting IL-1, IL-6, and TNF pathways. Demand concentrates in academic medical centers with dedicated immunology units.
- Rare Cancers:Targeted small molecules and antibody-drug conjugates address molecularly defined subpopulations below 200,000 prevalence thresholds. Companion diagnostic requirements fragment addressable markets further.
Established volume favors metabolic disorders; emerging adoption favors neurological applications.
Delivery Mode:
Route selection determines manufacturing complexity, cold chain requirements, and prescriber administration training investment.
- Injectable:Subcutaneous and intramuscular delivery of monoclonal antibodies, fusion proteins, and gene therapy viral vectors. Prefilled syringe and autoinjector formats reduce clinic burden for chronic administration in hemophilia and enzyme replacement. Massachusetts and Pennsylvania host the concentrated fill-finish capacity for these formats.
- Infusion:Intravenous delivery of large-volume biologics and cellular therapies requiring hospital-based administration. Outpatient infusion center networks at Dana-Farber, MD Anderson, and Memorial Sloan Kettering anchor patient access. Capacity constraints in rural markets limit geographic penetration.
- Oral:Small-molecule chaperones and substrate reduction therapies offering patient-administered convenience. Bioavailability challenges in neurological indications restrict applicability.
- Transdermal:Patch-based delivery for hormone replacement and continuous medication delivery in rare endocrine disorders. Limited pipeline activity constrains commercial significance.
Infusion dominates revenue concentration; injectable formats are climbing the fastest.
End User:
Procurement authority and clinical trial sponsorship role determine pricing tolerance and contract structure.
- Specialty Clinics:Dedicated rare disease centers consolidate diagnosis, treatment, and longitudinal data capture. Boston Children's Hospital, Great Ormond Street Hospital, and the National Institutes of Health Clinical Center generate natural history data that shapes regulatory submissions. These institutions command preferred pricing through volume commitments and investigator-initiated trial participation.
- Pharmaceutical Companies:Sponsor-funded expanded access programs and compassionate use protocols reach patients outside commercial distribution. Internal manufacturing scale determines supply allocation priority.
- Research Institutions:Academic medical centers host phase I/II trials and gene therapy vector production for investigator-initiated studies. Institutional biosafety committees govern local approval timelines.
- Hospitals:General medical centers with limited rare disease expertise rely on telemedicine referral networks and hub-and-spoke models for complex therapy administration.
Specialty clinics capture the steepest expansion trajectory; hospitals retain the largest patient volume base.
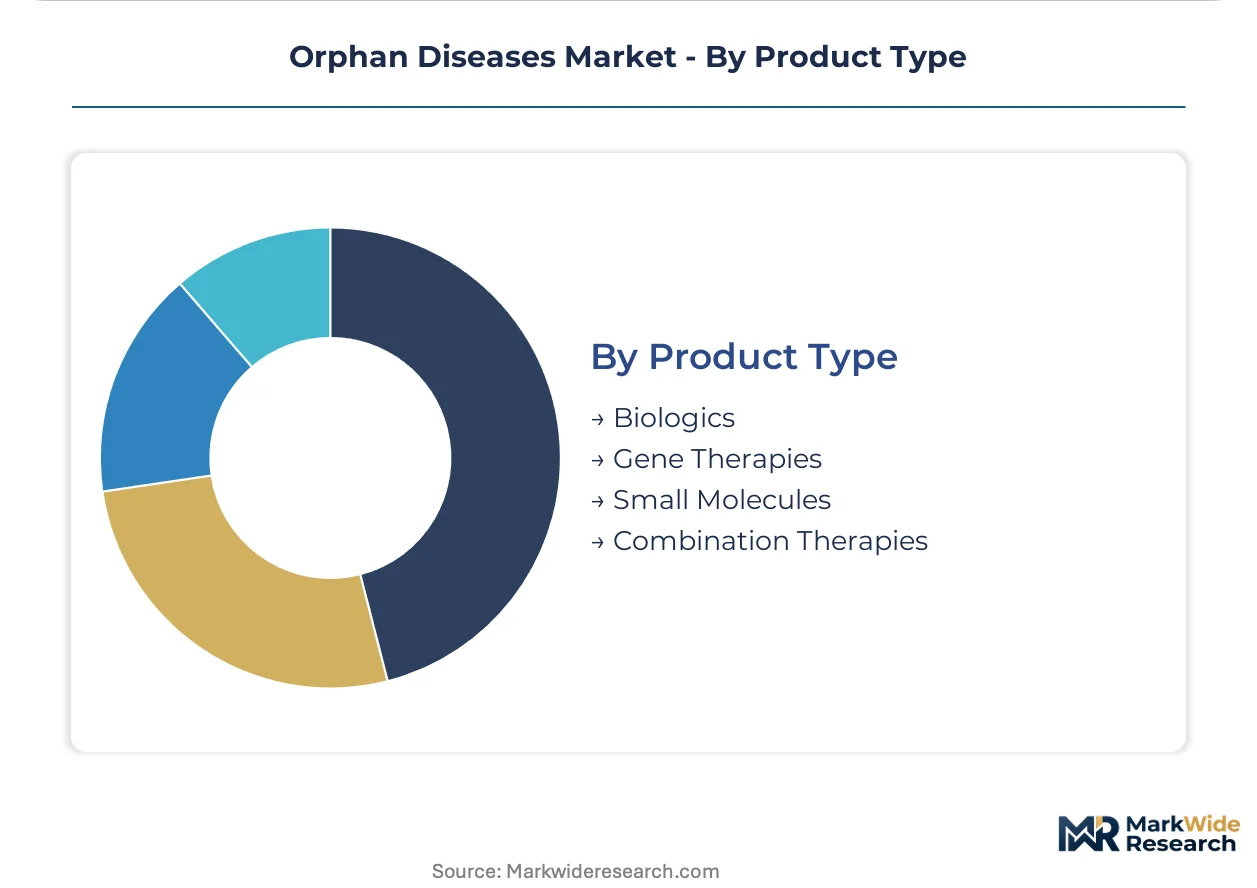
Product Type:
Technology platform selection determines development timeline, manufacturing capital intensity, and reimbursement negotiation leverage.
- Biologics:Recombinant proteins and monoclonal antibodies with established manufacturing infrastructure and prescriber familiarity. Biosimilar competition in chronic indications is compressing originator pricing power.
- Gene Therapies:One-time curative interventions using AAV and lentiviral vectors command premium reimbursement. Durability data requirements and manufacturing workforce scarcity constrain expansion.
- Small Molecules:Oral kinase inhibitors and chaperone therapies face margin pressure from generic substitution where patent cliffs have arrived. Novel targets in rare cancers sustain development interest.
- Combination Therapies:Co-formulated biologic-small molecule approaches and sequential gene therapy-enzyme replacement protocols. Regulatory complexity and manufacturing coordination challenges limit current adoption.
Biologics anchor current revenue; gene therapies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan disease therapy consumption varies sharply by geography. The United States prioritizes one-time curative interventions with premium reimbursement structures. Germany and Japan emphasize chronic management protocols with established enzyme replacement regimens. China and India concentrate on biosimilar manufacturing for cost-sensitive markets.
United States
FDA Orphan Drug Act tax credits and seven-year market exclusivity drive sponsor investment in ultra-rare indications. Massachusetts and California host the densest concentrations of gene therapy vector manufacturing and natural history study recruitment. Boston Children's Hospital and the National Institutes of Health Clinical Center anchor patient identification networks that compress diagnostic delay for lysosomal storage disorders.
Germany
G-BA benefit assessment processes create 12-18 month reimbursement delays post-EMA approval, compressing effective exclusivity windows for sponsors. The country's statutory health insurance funds negotiate outcomes-based contracts for Zolgensma-class therapies. Heidelberg and Munich academic medical centers generate real-world evidence registries that shape payer willingness to accept premium pricing for one-time interventions.
Japan
PMDA priority review vouchers for pediatric rare diseases create first-mover advantages for sponsors with Japan-ready dossiers. The country's national health insurance system maintains separate budget lines for high-cost curative therapies. Tokyo and Osaka specialty clinics concentrate patient recruitment for spinal muscular atrophy and Huntington's disease antisense oligonucleotide trials.
Switzerland
Swissmedic accelerated assessment pathways for medicines addressing unmet medical needs reduce regulatory review timelines for gene therapy submissions. The country's private insurance mandate supports premium pricing acceptance for ultra-rare indications. Basel anchors Roche and Novartis rare disease research operations with integrated manufacturing and clinical trial infrastructure.
United Kingdom
NICE highly specialized technologies evaluation framework separates orphan disease assessment from standard technology appraisal, enabling flexible pricing negotiations. The NHS England commercial medicines directorate pilots annuity-style payment models for gene therapies exceeding one million pounds per patient. London's Great Ormond Street Hospital and Manchester's genomic medicine centers drive pediatric rare disease diagnosis and treatment access.
Orphan Diseases Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the orphan diseases market. Vertex Pharmaceuticals, Biogen, and Amgen occupy positions that smaller gene therapy developers cannot replicate without manufacturing scale or longitudinal patient data assets. The competitive landscape organizes around three archetypes: large-cap biopharmaceuticals with rare disease franchises, mid-cap gene therapy specialists, and emerging platform technology companies. Consolidation pressure intensifies as viral vector manufacturing capacity constraints favor players with captive supply chains. Strategic partnerships between academic medical centers and sponsors replace traditional contract research organization relationships for natural history study execution.
Within the integrated biopharmaceutical tier, Vertex Pharmaceuticals exemplifies protein modulation expertise sustained through cystic fibrosis franchise economics. Biogen occupies a position anchored in antisense oligonucleotide delivery mechanisms for neurological rare diseases. Amgen represents biologics manufacturing scale that reduces per-dose costs for ultra-rare patient populations below thresholds that smaller competitors can achieve.
| Leading Market Players |
|---|
| Vertex Pharmaceuticals |
| Biogen |
| Amgen |
| Sanofi |
| Novartis |
| Roche |
| Regeneron Pharmaceuticals |
| AstraZeneca |
| Bristol-Myers Squibb |
| Others |
Value Network & Pricing Analysis
Outcomes-based annuity contracts for gene therapies lock in five-year payment visibility while securing manufacturing slot allocation for sponsors. Massachusetts Medicaid and New York's carve-out programs demonstrate how financial engineering binds supply access to reimbursement certainty for ultra-rare indications.
Pricing Analysis
Long-term offtake agreements dominate gene therapy procurement, with Massachusetts and New York Medicaid piloting annuity structures spreading Zolgensma-class costs across multi-year horizons. Price differentiation rests on durability data maturity and manufacturing exclusivity, with one-time curative interventions commanding premium positioning against chronic enzyme replacement. Cost compression in small-molecule kinase inhibitors intensifies as imatinib biosimilars displace originator revenue in chronic myeloid leukemia. Academic medical centers with natural history study participation exhibit lowest price sensitivity; rural hospitals dependent on hub-and-spoke referral models face highest budget impact constraints.
Supply Chain Analysis
Inventory lead times for clinical-grade AAV vectors extend twelve to eighteen months due to Massachusetts and Pennsylvania production concentration. Viral vector manufacturing draws from Chinese hamster ovary cell substrates, synthetic DNA templates, and specialized resin chromatography media. Single-source dependency on suspension-based AAV capacity in the Boston-Cambridge corridor creates vulnerability to workforce scarcity and equipment failure. Distribution runs through specialty pharmacy networks with cold chain custody requirements, anchored by Boston Children's Hospital and NIH Clinical Center procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orphan diseases market is entering a cyclical recovery phase as gene therapy durability data matures and outcomes-based contracting normalizes payer acceptance of premium one-time interventions.
For Market Incumbents: Consolidate manufacturing scale advantages through captive viral vector capacity in Massachusetts and Pennsylvania, securing supply chain control against emerging platform competitors. Deepen longitudinal patient data assets at Boston Children's Hospital and Great Ormond Street Hospital to reinforce regulatory exclusivity positioning. Prioritize antisense oligonucleotide expansion into Huntington's disease and ALS before patent cliffs erode spinal muscular atrophy franchise value. For New Entrants and Emerging Players: Differentiate on pediatric neurology applications using next-generation AAV capsids with enhanced CNS tropism, targeting earlier intervention windows at Children's Hospital of Philadelphia. Penetrate Japan's priority review voucher pathway for first-mover advantage in rare disease submissions to PMDA. Deploy direct-to-patient telemedicine platforms for dispersed populations across rural Australia and Canada, bypassing traditional specialty clinic gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap gene therapy developers with validated manufacturing partnerships and Japan-ready regulatory dossiers, positioned for acquisition by integrated biopharmaceuticals seeking platform scale. Long-term viability hinges on durability data generation infrastructure and payer contracting expertise across the five-to-ten year horizon. Monitor gene therapy manufacturing workforce compensation inflation in the Boston-Cambridge corridor as an inflection signal for supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Captive AAV vector capacity in Massachusetts reduces single-source dependency for sponsors. |
| PMDA Priority Review Voucher Pursuit | Accelerated pediatric rare disease approvals in Japan create first-mover exclusivity windows. |
| Outcomes-Based Contracting Infrastructure | Annuity payment models with Massachusetts Medicaid normalize premium gene therapy access. |
| Next-Generation AAV Capsid Development | Enhanced CNS delivery at Children's Hospital of Philadelphia expands addressable neurology indications. |
| Real-World Evidence Registry Investment | Heidelberg and Munich academic centers generate payer-accepted durability data for one-time interventions. |
Research Methodology
The analysis maps gene therapy, biologics, small-molecule, and combination therapy sub-sectors, each validated through regulatory affairs leads at FDA and EMA, formulary directors at Massachusetts and New York Medicaid, hospital procurement managers at Dana-Farber and Memorial Sloan Kettering, and payer access specialists at Germany's G-BA. Primary interview findings triangulate against FDA orphan drug filings, EMA designation databases, ClinicalTrials.gov recruitment records, and CMS Medicare Part D claims. Bottom-up patient population sizing and top-down revenue reconciliation ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models therapy area, delivery mode, end user, and product type segmentation alongside regional regulatory cluster differentiation. CAGRs derive from patient prevalence trajectories, newborn screening expansion rates, and reimbursement policy adoption curves. Manufacturing capacity utilization at Massachusetts and Pennsylvania viral vector facilities, plus PMDA priority review voucher award velocity, inform supply-side constraints.
Material uncertainties — gene therapy durability data revisions, G-BA benefit assessment delays, and viral vector manufacturing workforce attrition — sit outside the modeled envelope. Forecasts reflect documented assumptions about payer acceptance of one-time curative interventions and regulatory exclusivity period integrity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rett Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Sanfilippo Syndrome Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Turner Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Fabry Disease Market