
 Rare Neurodegenerative Disease Treatment Market | 2026-2036
Rare Neurodegenerative Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Neurodegenerative Disease Treatment Market Outlook
Specialty clinic demand for advanced neurology protocols is hardening as hospital outpatient departments lose complex case referrals to dedicated centers. Biogen leverages its spinal muscular atrophy franchise to sustain manufacturing scale in antisense oligonucleotides. Roche anchors its position through deep diagnostics-therapeutics integration in Huntington's disease pathways.
Rare neurodegenerative disease treatment encompasses disease-modifying and symptomatic interventions targeting low-prevalence, progressive nervous system disorders, typically requiring biologic manufacturing with cold-chain distribution and parenteral administration. Gene therapy segments occupy the highest margin pools due to one-time dosing paradigms and complex vector manufacturing requirements, while monoclonal antibodies dominate current prescription volumes across amyotrophic lateral sclerosis and Alzheimer's disease indications. Small molecules retain cost advantages in oral delivery but face pipeline competition from enzyme replacement therapies in lysosomal storage disorders with neurological manifestations.
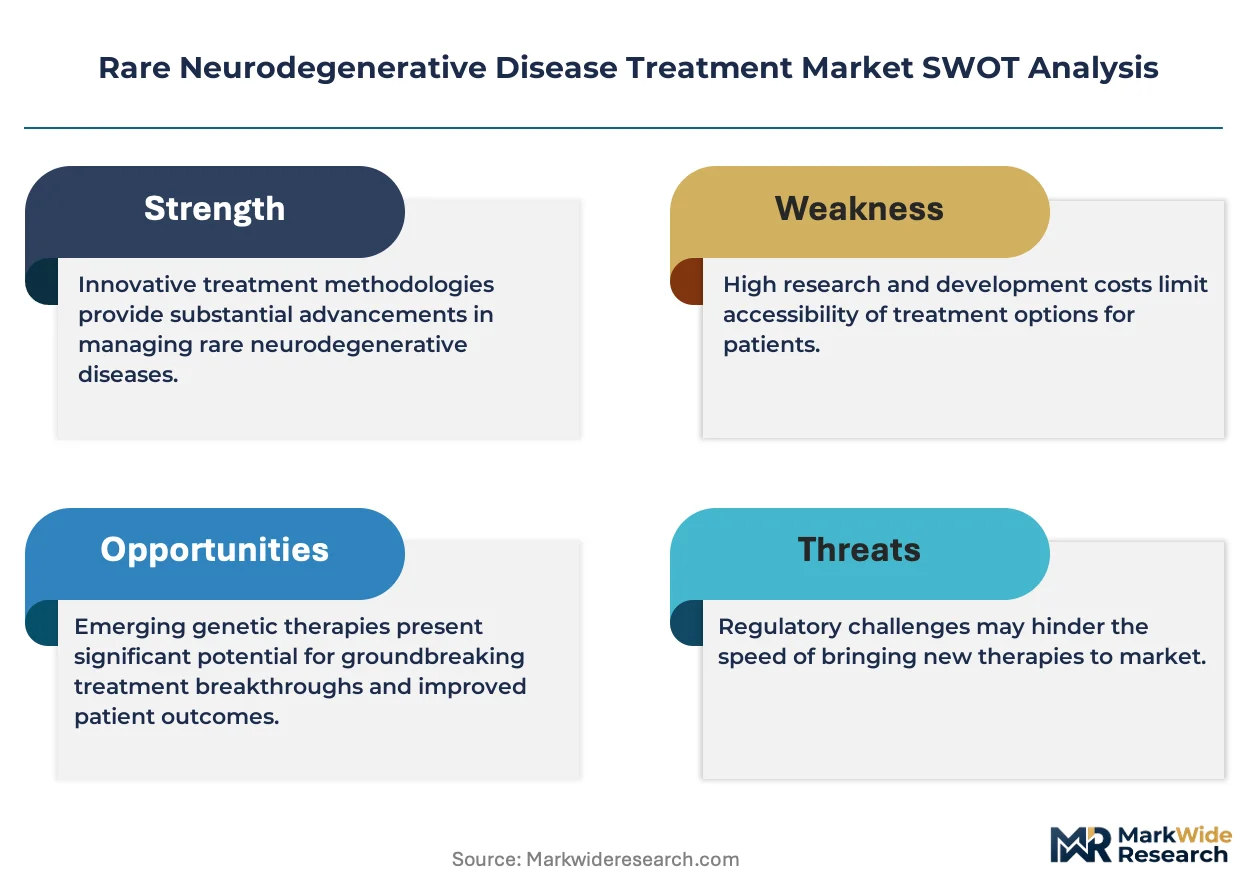
FDA orphan drug exclusivity provisions and EMA PRIME eligibility criteria shape clinical trial investment patterns and accelerate market access for qualifying therapies. The EU AI Act and FDA guidance on decentralized clinical trials are reshaping patient recruitment methodologies for geographically dispersed rare disease populations. Stakeholders must monitor how payer value-assessment frameworks evolve for single-administration gene therapies versus chronic monoclonal antibody regimens.
Market Dynamics
FDA orphan drug exclusivity provisions and EMA PRIME designations are redirecting clinical trial investment toward rare neurodegenerative indications, compressing development timelines and reshaping competitive entry patterns for gene therapy and antisense platforms.
Growth Catalysts
- Orphan Drug Incentives:FDA's seven-year market exclusivity and tax credits for clinical trial costs are accelerating sponsor commitment to ultra-rare indications with limited commercial precedent.
- Diagnostic-Therapeutic Integration:Biomarker-validated patient identification is expanding addressable populations in Huntington's disease and amyotrophic lateral sclerosis pathways.
- Cold-Chain Infrastructure Expansion:Dedicated biologics distribution networks in the United States, Germany, and Japan are enabling parenteral gene therapy administration at specialty clinic scale.
Market Restraints
- Vector Manufacturing Bottlenecks:AAV and lentiviral production capacity concentrates at single-source contract manufacturers, creating supply vulnerability for one-time dosing paradigms.
- Reimbursement Complexity:Payer value-assessment frameworks for single-administration gene therapies remain unsettled against chronic monoclonal antibody regimens in United States and German markets.
- Patient Recruitment Friction:Geographically dispersed rare disease populations require decentralized trial infrastructure that strains traditional site-based monitoring protocols.
Strategic Opportunities
- EU AI Act Compliance:Automated patient matching algorithms for rare disease trials represent a first-mover advantage for sponsors with validated real-world evidence pipelines.
- Japan's Sakigake Pathway:Priority review designation for innovative neurology therapies compresses regulatory timelines for qualified sponsors entering Japanese reimbursement negotiations.
- Specialty Clinic Consolidation:Hospital outpatient departments are losing complex case referrals to dedicated neurology centers, creating channel concentration for high-touch therapy administration.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:Viral vector production requires GMP facility investment exceeding $200 million per suite, constraining mid-cap sponsor entry.
- Cross-Border Trial Harmonization:Divergent informed consent requirements between FDA and EMA jurisdictions complicate multinational rare disease study execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Neurodegenerative Disease Treatment Market |
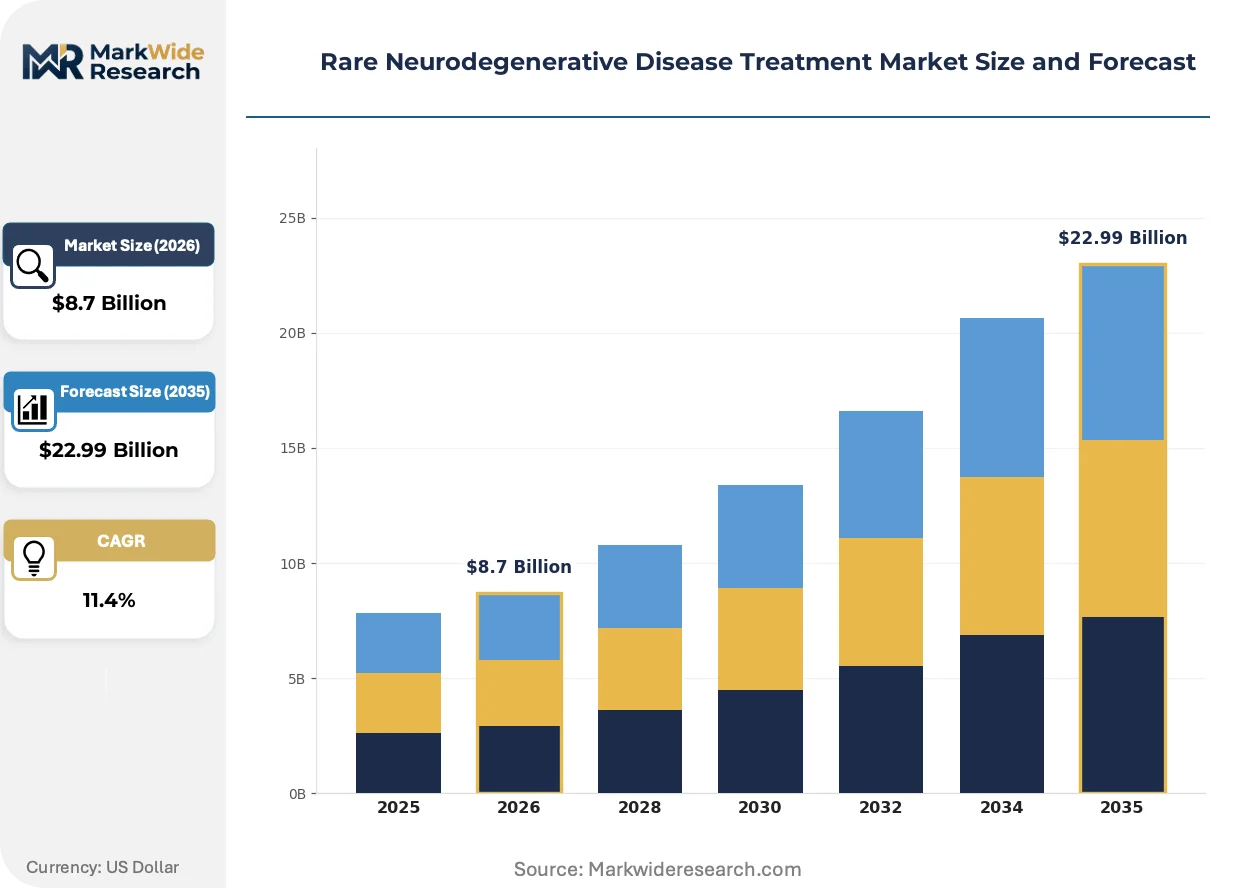
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Gene Therapy, Enzyme Replacement Therapy Area: Alzheimer's Disease, Huntington's Disease, Amyotrophic Lateral Sclerosis, Multiple System Atrophy Delivery Mode: Injectable, Oral, Intranasal, Transdermal End User: Hospitals, Specialty Clinics, Home Care, Research Laboratories |
| Companies Covered | Biogen, Roche, Novartis, Sanofi, Amgen, AbbVie, Pfizer, Teva, Ionis Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Neurodegenerative Disease Treatment Market Strategic Shifts
Decentralized clinical trial methodologies are compressing patient recruitment timelines for geographically dispersed rare disease populations, while vector manufacturing automation and payer contracting innovation reshape commercialization economics.
Decentralized trial platforms are decentralizing patient access by enabling home nursing for parenteral therapy administration and remote safety monitoring. Specialty clinics in the United States and Germany are adopting hybrid site-virtual models to capture patients outside major academic medical centers. This architecture is decentralizing clinical trial geography, expanding eligible patient pools beyond traditional urban recruitment hubs.
The EU AI Act's risk classification framework for clinical decision support is mandating algorithmic transparency in patient matching and endpoint assessment. Sponsors operating in European markets must document training data provenance and performance validation for AI-enabled trial tools. Gene therapy developers with European commercialization strategies are restructuring data governance to satisfy both EMA clinical standards and AI Act conformity requirements.
Specialty pharmacy networks are displacing traditional hospital outpatient purchasing for rare disease biologics, unbundling drug acquisition from infusion service reimbursement. Payers in the United States are contracting directly with limited distribution pharmacies to capture administrative discounts and improve adherence monitoring. This channel migration is most visible in spinal muscular atrophy and lysosomal storage disorder categories where patient concentration supports dedicated pharmacy investment.
Rare Neurodegenerative Disease Treatment Market Segmentation
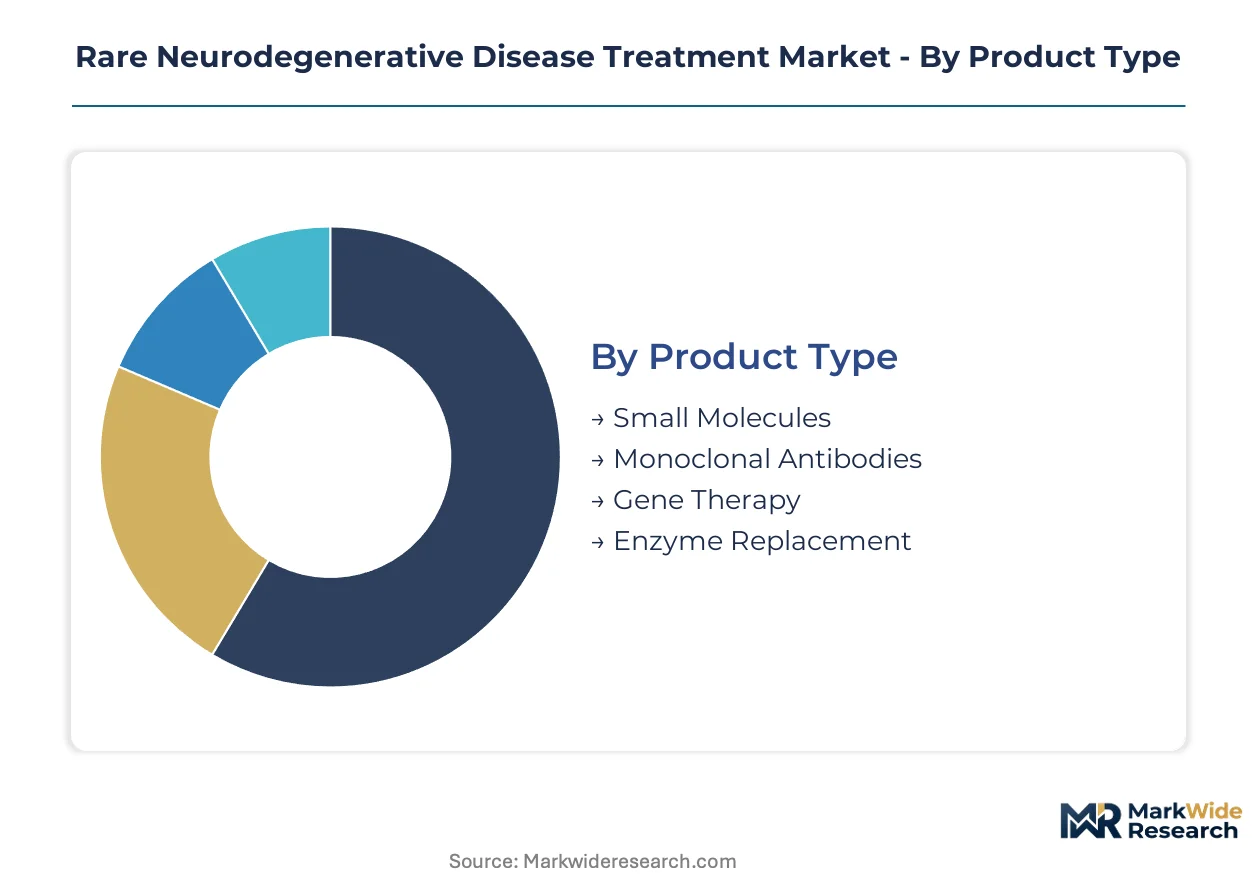
Segmentation in rare neurodegenerative disease treatment reveals how manufacturing complexity, reimbursement pathways, and patient concentration shape commercial strategy across modalities and care settings. Understanding these divides exposes where margin pools concentrate and which channels absorb innovation risk.
Product Type:
Customization intensity spans from standardized oral formulations to bespoke viral vector manufacturing, with each tier demanding distinct capital commitments and regulatory navigation.
- Gene Therapy:One-time administration using AAV or lentiviral vectors requires dedicated GMP suites exceeding $200 million per facility. Demand clusters at academic medical centers in the United States and Germany where surgical infrastructure and payer contracts for single-administration therapies have matured.
- Monoclonal Antibodies:Periodic intravenous or subcutaneous dosing dominates current prescription volumes across amyotrophic lateral sclerosis and Alzheimer's disease pathways. Manufacturing scale advantages concentrate at sponsors with existing biologics infrastructure, while chronic administration paradigms face payer pressure against gene therapy alternatives.
- Small Molecules:Oral bioavailability and established CMC pathways offer cost advantages in symptomatic management, though pipeline competition from biologics is intensifying in lysosomal storage disorders with neurological manifestations.
- Enzyme Replacement:Recombinant protein therapies address substrate accumulation in select lysosomal disorders, requiring cold-chain distribution and specialist infusion center networks.
Leading the category by volume: Monoclonal Antibodies. Expanding most quickly: Gene Therapy.
Therapy Area:
Prevalence gradients and biomarker validation maturity determine addressable patient pools and trial feasibility across indications.
- Alzheimer's Disease:Largest absolute patient population among neurodegenerative indications, though diagnostic complexity and heterogeneity complicate targeted therapy development. Anti-amyloid antibodies have established reimbursement precedent in the United States, reshaping investment patterns.
- Amyotrophic Lateral Sclerosis:Rapid disease progression compresses trial duration and accelerates regulatory review timelines. FDA's orphan drug framework and EMA PRIME designation have concentrated sponsor activity here, with antisense oligonucleotides gaining traction.
- Huntington's Disease:Genetic testing enables pre-symptomatic identification, expanding addressable populations beyond manifest patients. Roche's diagnostics-therapeutics integration has anchored competitive positioning in this pathway.
- Multiple System Atrophy:Diagnostic uncertainty and phenotypic overlap with Parkinson's disease limit trial enrollment, constraining commercial development despite unmet need.
Maximizing patient access: Alzheimer's Disease. Steepest expansion trajectory: Amyotrophic Lateral Sclerosis.
Delivery Mode:
Route of administration dictates site-of-care requirements, cold-chain intensity, and patient compliance architecture.
- Injectable:Parenteral administration dominates biologic delivery, requiring infusion center capacity or home nursing infrastructure. Specialty pharmacy networks in the United States are capturing volume through limited distribution contracts.
- Oral:Small molecule bioavailability enables outpatient dispensing and patient self-management, though blood-brain barrier penetration constraints limit applicability in many indications.
- Intranasal:CNS-directed delivery avoiding systemic exposure remains investigational, with formulation stability and deposition consistency challenges unresolved.
- Transdermal:Sustained release patches offer adherence advantages in chronic symptomatic management, though skin permeation limits molecular weight applicability.
Dominant by prescription volume: Injectable. Gaining technical investment: Intranasal.
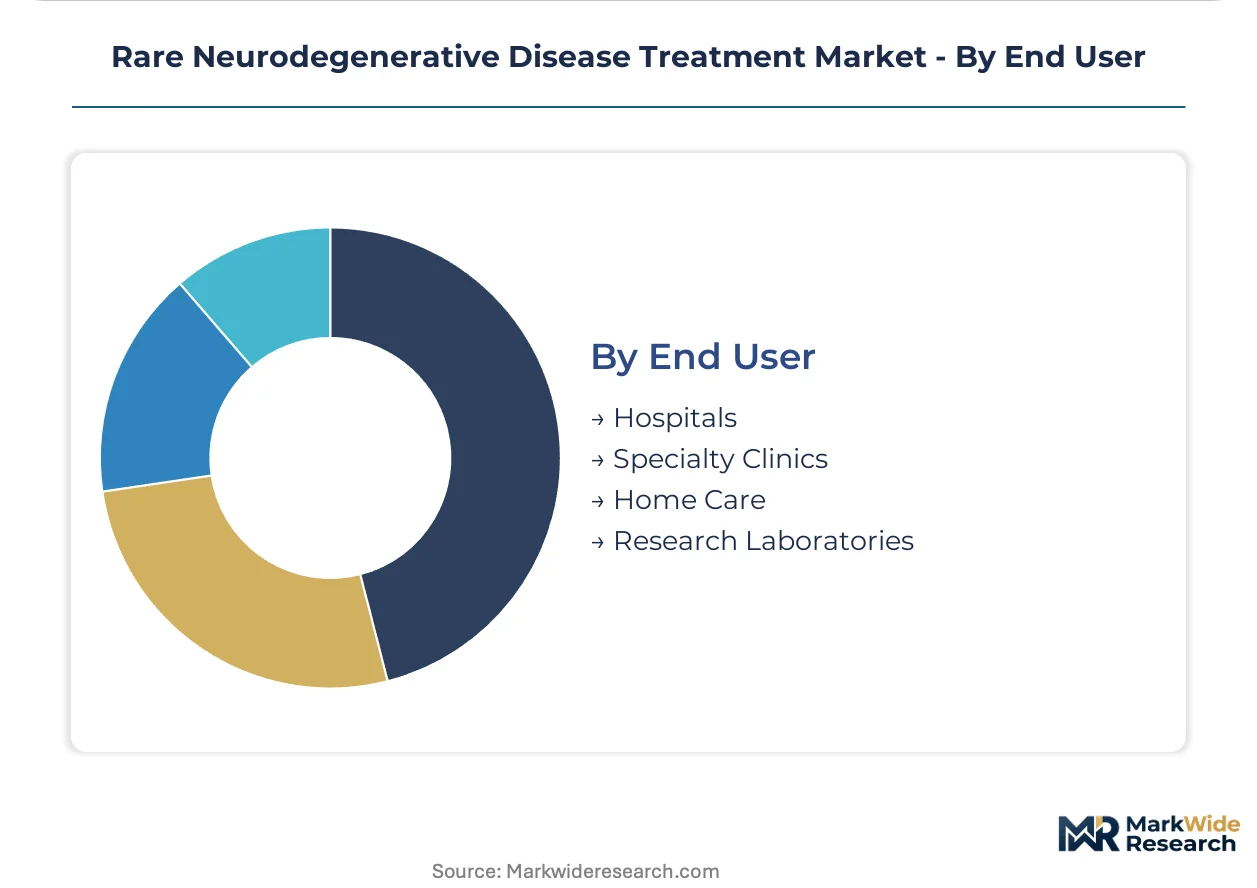
End User:
Care setting fragmentation reflects therapy complexity, reimbursement bundling, and patient acuity requirements.
- Specialty Clinics:Dedicated neurology centers concentrate complex case referrals and gene therapy administration capacity. Hospital outpatient departments are losing volume to these focused settings as referral networks harden.
- Hospitals:Academic medical centers retain gene therapy surgical infrastructure and principal investigator relationships for clinical trials, though biologic purchasing is unbundling to specialty pharmacy channels.
- Home Care:Subcutaneous biologics and oral therapies enable patient-managed administration, with remote monitoring platforms expanding eligibility for decentralized care.
- Research Laboratories:Preclinical and biomarker validation work supports diagnostic-therapeutic integration, particularly in Huntington's disease genetic testing pathways.
Capturing volume growth: Specialty Clinics. Expanding access reach: Home Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones for gene therapy manufacturing concentrate near FDA and EMA regulatory hubs, with tax incentives in Massachusetts and Basel-Land canton attracting GMP facility investment exceeding $200 million per viral vector suite.
United States
Massachusetts and North Carolina corridor anchors viral vector manufacturing, with FDA orphan drug exclusivity provisions accelerating sponsor commitment to ultra-rare indications. The 21st Century Cures Act framework streamlines regenerative medicine advanced therapy designation reviews. Boston-Cambridge cluster concentrates antisense oligonucleotide production capacity for spinal muscular atrophy pathways.
Germany
Bavaria and Baden-Württemberg host EMA centralized procedure expertise, with PRIME designation eligibility compressing development timelines for qualified neurology therapies. The German Hospital Structure Act reforms unbundle gene therapy reimbursement from DRG-based hospital financing. Munich-Stuttgart axis dominates cold-chain distribution infrastructure for parenteral biologics.
Japan
Kanto region concentrates PMDA Sakigake pathway submissions, with priority review designation compressing regulatory timelines for innovative neurology therapies. The Pharmaceutical and Medical Device Act amendments establish conditional early approval frameworks for rare disease gene therapies. Tokyo-Osaka corridor anchors specialty clinic networks for one-time administration paradigms.
Switzerland
Basel-Land and Zurich cantons leverage Swissmedic parallel review pathways with EMA, accelerating market access for qualified therapies. Federal Act on Research Involving Human Beings harmonizes informed consent requirements with EU Clinical Trials Regulation standards. Basel biotech cluster concentrates lentiviral vector manufacturing for Huntington's disease programs.
United Kingdom
Greater London and Oxford-Cambridge arc retain MHRA innovative licensing access pathway post-Brexit, with rolling review mechanisms compressing assessment timelines. The Life Sciences Vision program directs NHS England funding toward cell and gene therapy infrastructure. London-Edinburgh corridor maintains clinical trial density for amyotrophic lateral sclerosis biomarker validation studies.
Rare Neurodegenerative Disease Treatment Market Competitive Environment
Top-tier vendors anchor antisense and gene therapy platforms, while mid-cap specialists occupy vector manufacturing niches and diagnostic-therapeutic integration roles. The competitive structure stratifies across integrated pharmaceutical conglomerates, platform-technology biotechs, and contract development manufacturing organizations. Three archetypes dominate: large-cap sponsors with existing rare disease franchises, gene therapy pure-plays with captive viral vector capacity, and diagnostics-anchored developers pursuing Huntington's disease pathways. Consolidation pressure concentrates on vector manufacturing assets, with strategic partnerships bridging capability gaps in GMP suite access.
Within the integrated pharmaceutical tier, Biogen and Roche exemplify divergent platform strategies—Biogen anchoring antisense oligonucleotide scale through spinal muscular atrophy franchise economics, Roche occupying diagnostics-therapeutic convergence in Huntington's disease pathways. Among mid-cap platform specialists, Ionis Pharmaceuticals represents the pure-play antisense archetype with manufacturing partnerships rather than captive capacity. These three companies illustrate how competitive positioning depends on vertical control over manufacturing versus strategic outsourcing to contract manufacturers.
| Leading Market Players |
|---|
| Biogen |
| Roche |
| Novartis |
| Sanofi |
| Amgen |
| AbbVie |
| Pfizer |
| Teva |
| Ionis Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Payer consolidation around value-based contracts for single-administration gene therapies is forcing manufacturers to restructure reimbursement guarantees and risk-sharing arrangements, compressing net pricing flexibility while elevating supply chain reliability requirements for one-time dosing paradigms.
Pricing Analysis
Short lead-time premiums dominate gene therapy procurement, with academic medical centers paying substantial uplifts for expedited AAV vector delivery to meet surgical scheduling windows. Three-tier pricing structure across premium, standard, and economy levels segments by manufacturing slot priority, GMP certification tier, and after-sales monitoring bundling. Cost compression in the standard tier is intensifying because contract manufacturers are absorbing yield risk to secure multi-year offtake commitments. Hospital procurement committees exhibit highest price sensitivity, while specialty clinics with captive patient populations demonstrate lowest sensitivity due to reimbursement pass-through mechanisms.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle high-acuity gene therapy demand, bypassing traditional wholesale distribution to preserve cold-chain integrity and dosing schedule coordination. Viral vector production concentrates in the United States, Germany, and Switzerland, with GMP suite investment exceeding $200 million per facility creating formidable barriers to geographic diversification. Raw material dependencies span plasmid DNA, cell culture media, and purification resins, with single-source suppliers dominating critical input categories. Single-source vulnerability at contract manufacturing organizations represents the dominant structural risk, as AAV and lentiviral production capacity remains tethered to a handful of GMP-certified facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing scale requirements and reimbursement complexity are accelerating consolidation, with mid-cap sponsors lacking captive GMP capacity facing acquisition or partnership imperatives to remain viable.
For Market Incumbents: Deploy antisense oligonucleotide manufacturing scale as a defensive moat, expanding production capacity in the Boston-Cambridge corridor to capture spinal muscular atrophy franchise economics and deter platform competitors. Secure exclusive access to limited distribution specialty pharmacy networks to channel-block emerging gene therapy entrants before their reimbursement contracts mature. Biogen's manufacturing depth in this modality illustrates how captive capacity anchors pricing power against contract manufacturer-dependent rivals. For New Entrants and Emerging Players: Mid-sized European hospital systems with decentralized neurology departments represent the most penetrable buyer archetype, as these institutions lack gene therapy surgical infrastructure and seek partnership models for patient referral and administration. Target Germany's Baden-Württemberg region where Hospital Structure Act reforms are unbundling reimbursement from DRG financing, creating procurement flexibility for innovative contracting. Pursue EU AI Act-compliant patient matching platforms as a differentiated trial recruitment offering to sponsors lacking European real-world evidence capabilities. For Investors and Strategic Acquirers: The window for entry favors gene therapy pure-plays with validated viral vector production processes but underutilized GMP capacity, as platform technology valuations have compressed from peak levels while manufacturing assets retain strategic scarcity. Long-term viability hinges on sponsors demonstrating sustainable reimbursement pathways in United States and German markets, with payer contracting innovation serving as the critical capability differentiator. Watch for FDA regenerative medicine advanced therapy designation acceleration as the inflection signal indicating regulatory risk reduction and downstream valuation recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP suite investment in Massachusetts or Basel-Land secures vector supply for one-time dosing paradigms. |
| Regulatory Approval Pathway | EMA PRIME designation compresses development timelines for qualified neurology therapies entering European markets. |
| Reimbursement Strategy | Outcome-based contracts with CMS or NHS England establish precedent for single-administration gene therapy pricing. |
| Licensing Agreement | Antisense platform partnerships with Ionis Pharmaceuticals access validated manufacturing without captive facility investment. |
| Clinical Trial Advancement | Decentralized trial platforms leveraging EU AI Act compliance expand recruitment for geographically dispersed rare disease populations. |
Study Parameters
Multi-period observation of FDA orphan drug approval velocity, EMA PRIME designation trends, and specialty clinic referral network expansion anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork drew from FDA filings, EMA centralized procedure submissions, ClinicalTrials.gov enrollment data, and formulary database tracking across United States, German, and Japanese reimbursement systems. Bottom-up prescription volume modeling and top-down therapy class spend estimates were triangulated to validate market sizing.
Input-output matrices mapped gene therapy manufacturing capacity, antisense oligonucleotide production scale, and monoclonal antibody prescription volumes against patient population estimates and dosing frequency assumptions across the projection horizon. Segmentation dimensions spanned treatment modality, administration route, therapy area, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with cross-validation against historical analogs in spinal muscular atrophy and lysosomal storage disorder categories. Forecast inputs incorporated biomarker validation maturity, diagnostic expansion rates, and payer value-assessment framework evolution.
Revisions become necessary when vector manufacturing yield improvements materially alter supply assumptions, when major market payers adopt novel value-based contracting structures, or when regulatory designation criteria shift to exclude previously eligible therapy categories. Forecasts reflect documented assumptions regarding patient identification expansion, reimbursement persistence, and competitive entry timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Behcets Disease Market