
 Skeletal Dysplasia Market | 2026-2036
Skeletal Dysplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Skeletal Dysplasia Market Intelligence
The shift towards value-based reimbursement models for high-cost genetic therapies is narrowing the field of viable market participants, favoring companies with substantial clinical data. BioMarin specializes in enzyme replacement and other therapies for rare genetic diseases, including certain skeletal dysplasias. Regeneron leverages its extensive genetic research capabilities to develop novel treatments. Meanwhile, Ultragenyx Pharmaceutical positions its portfolio around therapies for severe orphan and ultra-orphan conditions, creating a distinct competitive niche.
Skeletal dysplasia encompasses a heterogeneous group of over 450 genetic disorders that affect bone and cartilage development, causing disproportionate short stature and structural abnormalities. These conditions often arise from mutations in genes like FGFR3, which are crucial for regulating chondrocyte differentiation. Therapeutic agents, especially biologic drugs targeting specific genetic pathways, constitute the highest value segment. The adoption of genetic testing panels, powered by next-generation sequencing technology, is accelerating early and accurate diagnosis across clinical settings.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) are central to market entry for new therapies. Their orphan drug designation pathways and accelerated approval processes are critical for commercializing new treatments. Future commercial success hinges on navigating disparate national reimbursement systems while demonstrating long-term clinical value and patient-reported outcomes.
Market Dynamics
The expansion of next-generation sequencing from research settings into routine clinical diagnostics is the central force shaping the skeletal dysplasia market. This technological shift enables earlier and more precise diagnoses, fundamentally altering patient management pathways and therapeutic development priorities.
Growth Catalysts
- Genetic Testing Adoption:The integration of next-generation sequencing panels into pediatric and prenatal care is accelerating early diagnosis, creating a larger addressable patient population for targeted therapies.
- Regulatory Incentives:Orphan drug designation pathways offered by the US FDA and the EMA provide critical financial and regulatory support, de-risking investment in therapies for rare skeletal disorders.
- Specialized Clinical Infrastructure:Growth in dedicated pediatric centers in developed countries like Germany and the United States provides the necessary infrastructure for complex genetic diagnostics and specialized patient care.
Market Restraints
- High Therapy Cost:The extreme cost of novel biologic drugs and gene therapies creates significant reimbursement hurdles and limits patient access, particularly in healthcare systems without established value-based frameworks.
- Disorder Heterogeneity:With over 450 distinct genetic subtypes, the fragmentation of the patient population complicates clinical trial recruitment and makes the development of broadly applicable therapies economically challenging.
- Reimbursement Complexity:Navigating disparate national reimbursement systems for high-cost genetic treatments presents a substantial barrier to commercialization, requiring extensive evidence of long-term clinical value.
Strategic Opportunities
- Targeted Gene Editing:Advances in gene-editing technologies present a long-term opportunity to develop curative therapies for monogenic skeletal dysplasias by correcting underlying mutations at the source.
- Expanded Newborn Screening:Policy initiatives to expand national newborn screening programs to include a wider panel of genetic disorders could systematically identify affected individuals at birth, enabling proactive intervention.
- Telemedicine for Genetic Counseling:Leveraging telehealth platforms to deliver genetic counseling services can overcome geographical barriers and shortages of specialized professionals, improving access to expert guidance in underserved regions.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of clinical geneticists and genetic counselors trained to interpret complex genomic data and manage rare disorders constrains diagnostic capacity and patient support.
- Longitudinal Data Management:Establishing and maintaining long-term patient registries to track outcomes is a significant operational challenge, yet it is essential for demonstrating the value of therapies to regulators and payers.
- Clinical Trial Recruitment:The rarity of individual skeletal dysplasias makes it difficult to enroll statistically significant numbers of patients for clinical trials, often requiring multicenter, international collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skeletal Dysplasia Market |
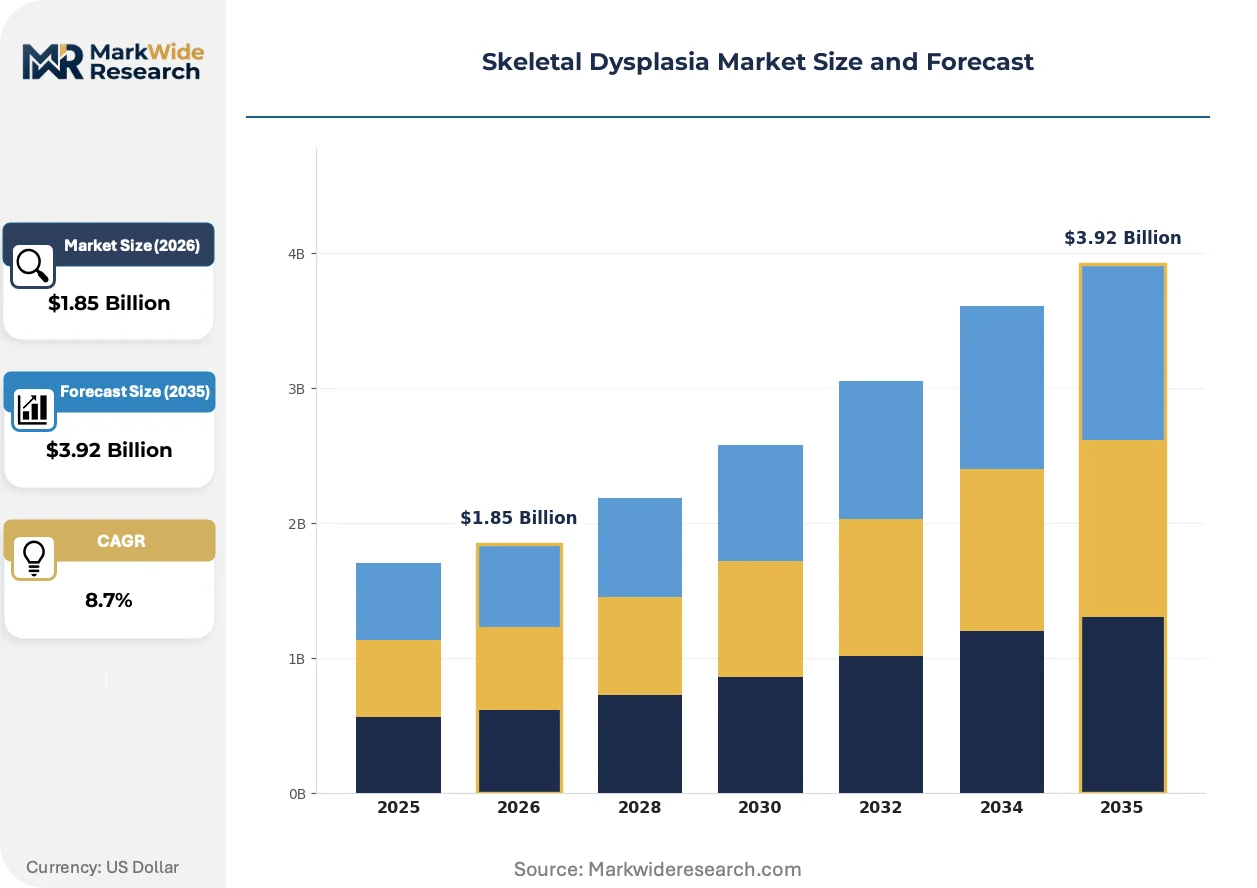
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutic Agents, Surgical Devices, Orthopedic Implants, Genetic Testing Panels Application: Growth Retardation Treatment, Bone Deformity Correction, Joint Mobility Enhancement, Pain Management End User: Specialty Clinics, Pediatric Centers, Rehabilitation Facilities, Research Institutes Technology: Next-Generation Sequencing, CRISPR Gene Editing, 3D Printing Implants, Biocompatible Materials |
| Companies Covered | BioMarin, Amgen Inc., Merck KGaA, Regeneron, Alexion Pharmaceuticals, Inc., BridgeBio Pharma, Ultragenyx Pharmaceutical, AstraZeneca plc, Pfizer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skeletal Dysplasia Market Strategic Shifts & Innovations
A fundamental shift toward personalized medicine is defining the therapeutic landscape, driven by the integration of genomic data with targeted drug development. This convergence is moving treatment paradigms away from symptom management and toward addressing the root genetic causes of disease.
Next-generation sequencing (NGS) panels allow for the simultaneous analysis of hundreds of genes, including FGFR3, implicated in skeletal disorders. Specialized pediatric centers and genetic clinics are the primary adopters, seeking earlier diagnostic clarity to guide intervention. This technology is digitizing the diagnostic pathway, replacing slower, sequential single-gene tests with comprehensive upfront genomic screening.
Regulatory frameworks like the European Medicines Agency's PRIME (PRIority MEdicines) scheme offer enhanced scientific and regulatory support for therapies targeting high unmet needs. This system accelerates the path to market authorization for innovative drugs, particularly biologics. Developers focusing on rare dysplasias are most affected, structuring clinical trials to meet PRIME eligibility criteria from early development stages.
Patient-centric data models are disrupting traditional research and development. Advocacy groups are creating and controlling patient registries, which gives communities more influence over research priorities and clinical trial design. This movement away from purely investigator-led data collection is most advanced in the United States and Europe for well-organized communities like those for achondroplasia.
Skeletal Dysplasia Market Segmentation
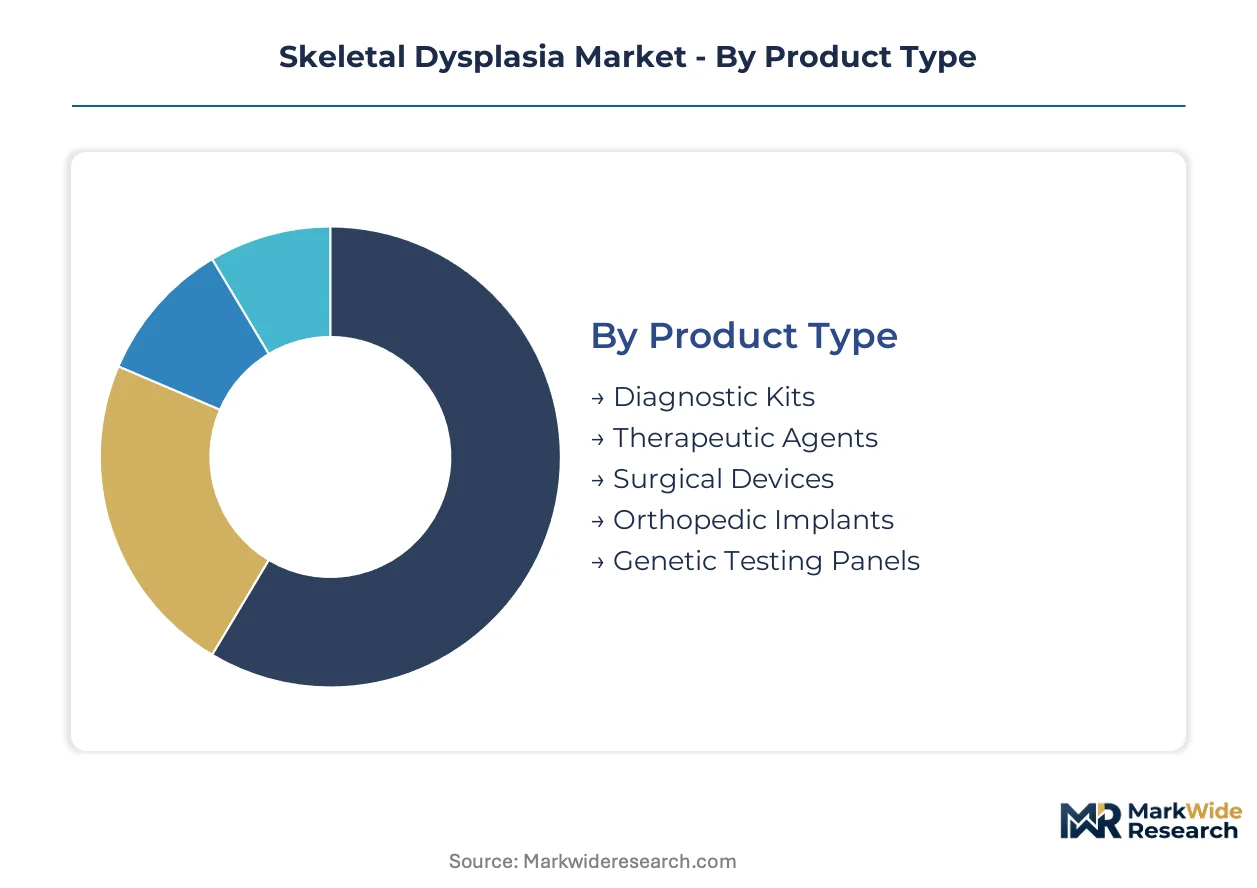
The skeletal dysplasia market segments reflect diverse approaches to diagnosis, treatment, and patient care. Understanding these distinct segments illuminates where innovation is concentrating and where healthcare infrastructure is adapting to meet specialized needs. Each segment plays a critical role in addressing the complex challenges posed by these rare genetic conditions.
Product Type:
The use-case spectrum for skeletal dysplasia products ranges from initial diagnosis to long-term therapeutic intervention.
- Therapeutic Agents:These biologics and small molecules target specific genetic pathways, aiming to modify disease progression or alleviate severe symptoms. Demand for these high-value agents concentrates in developed healthcare systems like the United States and Germany, driven by advanced infrastructure for genetic disorders.
- Genetic Testing Panels:These comprehensive panels, often powered by next-generation sequencing, enable the simultaneous analysis of multiple genes associated with skeletal dysplasias. Adoption is accelerating in pediatric centers due to the push for earlier and more precise diagnoses.
- Diagnostic Kits:These kits provide tools for initial screening and confirmation of various skeletal dysplasia subtypes.
- Surgical Devices:Specialized instruments support complex orthopedic procedures required for bone deformity correction in affected individuals.
- Orthopedic Implants:Custom-designed implants provide structural support and facilitate reconstruction following surgical interventions.
Established volume favors Diagnostic Kits; emerging adoption favors Genetic Testing Panels.
Application:
Application focus areas define the primary clinical objectives driving product development and service delivery within the market.
- Growth Retardation Treatment:Therapies focus on addressing disproportionate short stature, a hallmark symptom of many skeletal dysplasias, particularly achondroplasia. Clinical trials for novel biologic drugs are actively exploring this critical area.
- Bone Deformity Correction:Surgical and non-surgical interventions aim to rectify structural abnormalities in bones and joints, improving mobility and reducing pain. Developed healthcare systems with advanced orthopedic surgery capabilities lead in this application.
- Joint Mobility Enhancement:Procedures and physical therapies work to improve range of motion and reduce stiffness in affected joints.
- Pain Management:Pharmacological and supportive care strategies alleviate chronic pain associated with skeletal abnormalities.
Growth Retardation Treatment represents the fastest-growing trajectory, while Pain Management also gains attention.
End User:
Patient care delivery models shape the distribution and utilization of skeletal dysplasia products and services.
- Pediatric Centers:These specialized facilities offer comprehensive multidisciplinary care for children with genetic disorders, including advanced diagnostics and long-term management. Growth catalysts highlight the expansion of these centers in developed countries.
- Specialty Clinics:Focused clinics provide expert consultation, genetic counseling, and ongoing treatment for patients across all age groups. These clinics often serve as referral hubs for complex cases.
- Rehabilitation Facilities:These centers provide physical and occupational therapy to improve functional outcomes and quality of life for patients.
- Research Institutes:Academic and commercial institutes drive the discovery of new genetic markers and the development of innovative therapeutic approaches.
Pediatric Centers remain central to diagnosis, with Research Institutes driving future therapeutic advances.
Technology:
The technological innovation spectrum underpins advancements in both diagnostic precision and therapeutic efficacy.
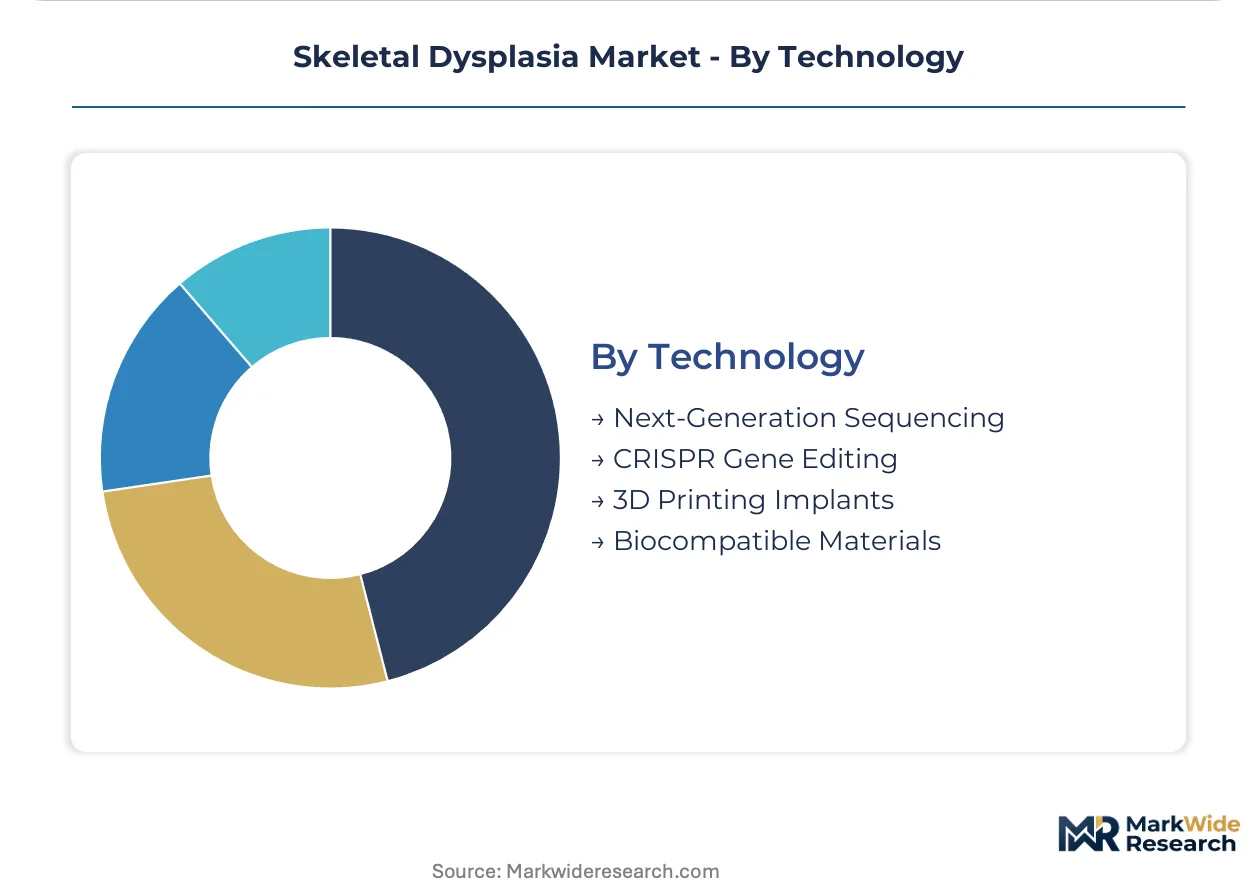
- Next-Generation Sequencing:This technology allows for rapid and comprehensive genetic analysis, enabling early and precise diagnosis of a wide array of skeletal dysplasias. Its integration into clinical diagnostics is a central force shaping the market.
- CRISPR Gene Editing:As an emerging technology, CRISPR holds the long-term potential to correct underlying genetic mutations responsible for monogenic skeletal dysplasias. Strategic opportunities exist for developing curative therapies using this method.
- 3D Printing Implants:Custom-fabricated implants offer personalized solutions for complex bone reconstruction and orthopedic support.
- Biocompatible Materials:Advanced materials are crucial for the development of durable and safe orthopedic devices and implants.
Next-Generation Sequencing underpins current diagnostic shifts, while CRISPR Gene Editing promises future curative interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory incentives like orphan drug designation and accelerated approval pathways significantly influence the global skeletal dysplasia market. These frameworks encourage pharmaceutical companies to invest in therapies for rare genetic conditions. Such policies are crucial for driving innovation and market entry for specialized treatments worldwide.
United States
The United States market sees high demand for advanced genetic testing and specialized pediatric care facilities. The US FDA's orphan drug designation provides significant incentives for therapy development, de-risking investment. Boston's biotech hub sees extensive research into novel gene therapies for monogenic disorders.
Germany
Germany benefits from a highly developed healthcare infrastructure and a strong focus on rare disease research. The European Medicines Agency (EMA) PRIME scheme facilitates accelerated market access for innovative treatments. Munich hosts specialized clinics and research centers dedicated to pediatric genetic conditions.
Japan
Japan exhibits high adoption of advanced diagnostics and a growing elderly population with related orthopedic needs. The Pharmaceuticals and Medical Devices Agency (PMDA) offers fast-track approval for orphan drugs. Tokyo's medical research institutions are actively pursuing new therapeutic approaches for skeletal dysplasias.
United Kingdom
A strong academic research base and a national healthcare system prioritizing rare disease management characterize the United Kingdom market. The National Institute for Health and Care Excellence (NICE) evaluates the cost-effectiveness of new genetic therapies. London's Great Ormond Street Hospital is a leading center for pediatric rare disease diagnosis and treatment.
China
China presents increasing access to genetic testing and a large patient population driving demand for new therapies. The National Medical Products Administration (NMPA) is streamlining approval processes for innovative drugs. Shanghai's biomedical parks are expanding capabilities in genomic sequencing and drug development for rare diseases.
Skeletal Dysplasia Market Key Industry Players
On the supply side, the industry is specialized and features a mix of established pharmaceutical giants and nimble biotech firms. This structure reflects the high R&D costs and niche patient populations inherent to rare diseases. Large pharmaceutical companies leverage broad R&D platforms, while specialized biotechs focus on orphan drug development. Companies engage in strategic partnerships for clinical development and pursue targeted acquisitions to expand their rare disease portfolios.
Specialists in orphan drug development include BioMarin, a company known for its enzyme replacement therapies. Regeneron, an Inc.-structured entity, leverages its genetic research capabilities to identify novel targets. Ultragenyx Pharmaceutical, another Inc.-structured firm, positions its portfolio around therapies for severe orphan and ultra-orphan conditions. These companies exemplify the strategic focus on rare disease markets.
| Leading Market Players |
|---|
| BioMarin |
| Amgen Inc. |
| Merck KGaA |
| Regeneron |
| Alexion Pharmaceuticals, Inc. |
| BridgeBio Pharma |
| Ultragenyx Pharmaceutical |
| AstraZeneca plc |
| Pfizer, Inc. |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoint created by complex approval processes for genetic therapies determines both premium pricing tiers and the highly specialized global supply chain shape. This environment favors developers with substantial clinical data and established regulatory navigation expertise.
Pricing Analysis
Clinical efficacy and regulatory approval status create the primary pricing spread for skeletal dysplasia therapies. Value-based pricing models dominate the market, reflecting the high development costs and specialized nature of these treatments. Price differentiation stems from orphan drug status, demonstrated long-term patient outcomes, and specific geographic reimbursement policies. Pricing pressure stems from payer demands for robust evidence of clinical value, while patient sensitivity to cost is lower given the lack of alternative curative treatments.
Supply Chain Analysis
Single-source vulnerability for specialized raw materials and complex manufacturing processes dominates the skeletal dysplasia supply chain. Production of advanced biologics and gene therapies concentrates in the United States, Germany, and Switzerland due to specialized infrastructure. The market draws from a limited number of highly specialized suppliers for critical components like viral vectors and recombinant proteins. Distribution runs through direct-to-hospital or specialty pharmacy channels, requiring stringent cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skeletal dysplasia market presents a defensive-moat story, primarily justified by significant regulatory entrenchment for novel therapies. High R&D costs and lengthy approval processes create substantial barriers to entry, protecting incumbent positions.
For Market Incumbents:Build an intellectual property moat around novel genetic therapies and diagnostic platforms. Incumbents must invest heavily in next-generation sequencing diagnostics to capture early patient identification and expand patient registries to demonstrate long-term value. This strategy counters the threat of emerging gene-editing technologies by integrating them into existing portfolios or through strategic acquisitions. Expanding global clinical trial networks also strengthens market position.
For New Entrants and Emerging Players:Pursue niche opportunities within ultra-orphan skeletal dysplasia subtypes with high unmet needs. The most penetrable segment involves developing advanced genetic testing panels for newly identified mutations. A successful go-to-market angle involves strategic partnerships with academic research institutions and patient advocacy groups to accelerate clinical trial recruitment. Focus on demonstrating clear clinical superiority in specific patient populations.
For Investors and Strategic Acquirers:Orphan drug designation pathways reshape the acquisition landscape, favoring companies with de-risked clinical pipelines. This market offers strong long-term viability over a 5-10 year window due to persistent unmet medical needs and high barriers to entry. Acquisition targets should include biotech firms with late-stage clinical assets or novel diagnostic platforms for specific monogenic disorders. The signal to watch is successful Phase 3 trial completions for gene therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel biologic and gene therapies. |
| Regulatory Approval Pathway Optimization | Streamlines access to critical markets like the United States and Europe. |
| Patient Registry Expansion | Provides essential long-term data for value-based reimbursement negotiations. |
| Genetic Testing Platform Integration | Enhances early diagnosis, expanding the addressable patient population. |
| Strategic Biotech Acquisitions | Consolidates intellectual property and specialized R&D capabilities. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from clinical geneticists, rare disease patient advocates, pharmaceutical R&D executives, and healthcare payers. Secondary data sources included US FDA filings, European Medicines Agency (EMA) reports, ClinicalTrials.gov, and peer-reviewed scientific literature. This approach enabled robust bottom-up and top-down triangulation of market data.
Forecast inputs considered included historical market performance and current technological adoption rates. The quantitative model segmented the market by product type, application, end user, technology, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical growth patterns and projected technological advancements over the projection horizon. Incidence rates of specific skeletal dysplasias and clinical trial success rates were key inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized biotechs or large pharmaceutical companies would shift outcomes. Forecasts reflect assumptions regarding unforeseen regulatory changes, breakthrough gene-editing discoveries, or shifts in reimbursement policies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Global Hemoglobinopathies Market
Rare Diseases
Orphan Diseases Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Niemann-Pick Disease Type C Therapeutics Market
Rare Diseases
Pompe Disease Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market