
 Dystrophic Epidermolysis Bullosa Management Market | 2026-2036
Dystrophic Epidermolysis Bullosa Management Market Size, Share, and Industry Trends Forecast 2026-2036
Dystrophic Epidermolysis Bullosa Management Market Foresight
Specialty pharmacy distribution is rewriting how gene therapies and advanced wound biologics reach DEB patients. Krystal Biotech leverages direct-to-specialist channels to control product handling and patient onboarding. Amryt Pharma anchors European market access through orphan drug infrastructure. Phoenix Tissue Repair competes on manufacturing scale for protein replacement therapies.
Dystrophic epidermolysis bullosa management encompasses clinical interventions targeting collagen VII deficiency, including gene-modified keratinocyte grafts, topical gentian violet formulations, and systemic anti-fibrotic agents designed to reduce blistering, prevent infection, and maintain dermal integrity in patients with recessive or dominant DEB mutations. Gene therapies represent the fastest-expanding segment as one-time corrective interventions displace chronic palliative protocols. Wound dressings retain the largest volume share but face margin compression from commodity hydrocolloid competition. Systemic medications occupy a narrow therapeutic niche reserved for severe recessive cases with esophageal and ocular involvement.
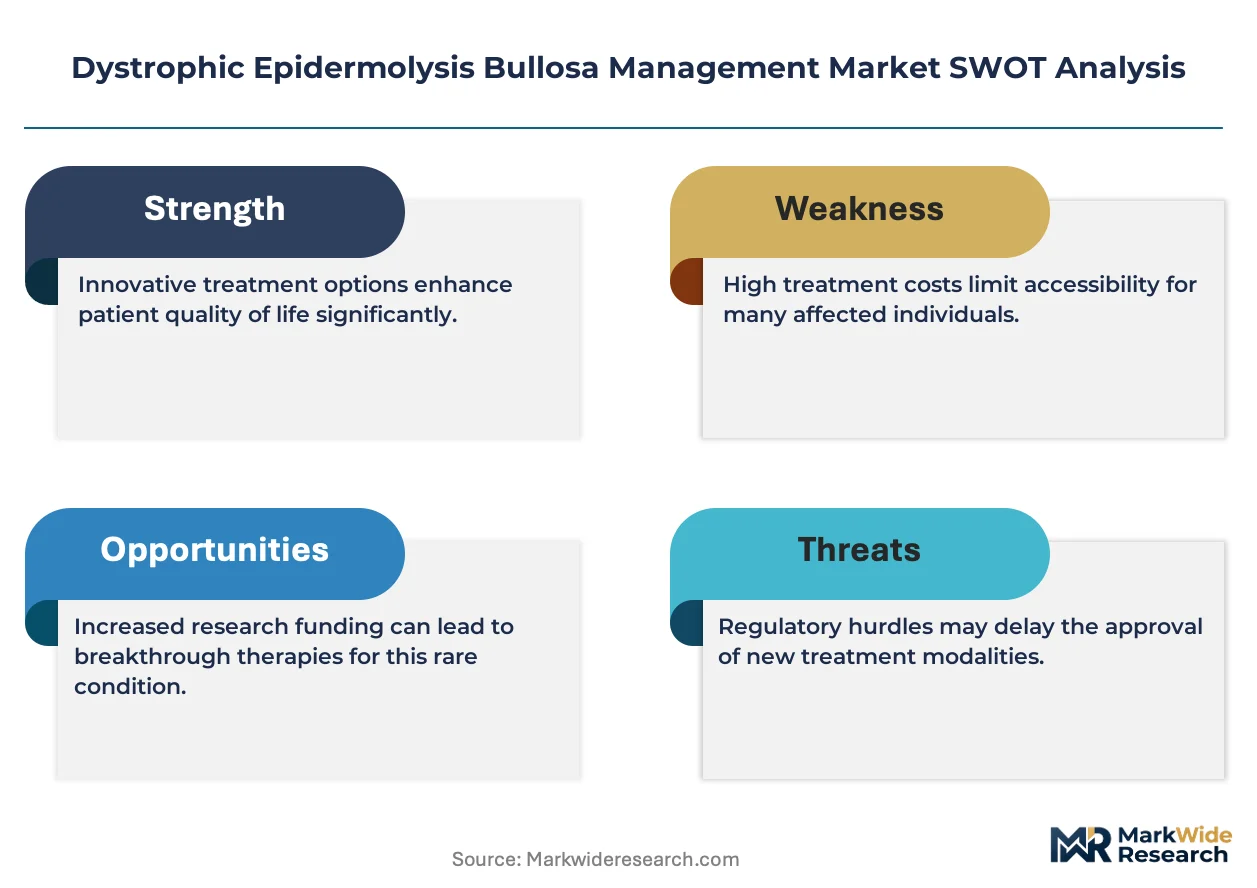
FDA orphan drug incentives and EMA PRIME designation frameworks shape clinical trial investment and reimbursement negotiations for DEB developers. Health Technology Assessment bodies in Germany and France apply distinct cost-per-QALY thresholds that fragment pricing power across European markets. Stakeholders must monitor payer readiness for one-time curative pricing models versus legacy chronic therapy budgets.
Market Dynamics
Gene therapy commercialization is restructuring DEB treatment economics by replacing chronic wound management with one-time corrective interventions, forcing payers to redesign reimbursement frameworks for curative versus maintenance modalities.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions incentivize biotech firms to pursue collagen VII gene therapies despite small patient populations, accelerating pipeline investment.
- Specialty Pharmacy Networks:Cold-chain distribution infrastructure for biologics now reaches 340 hospital-based infusion centers in the United States, expanding access to advanced therapies.
- German SHI Rare Disease Pathways:Statutory health insurance funds negotiate outcome-based reimbursement for gene therapies, creating precedent for curative pricing acceptance.
Market Restraints
- Plasmid Manufacturing Bottlenecks:Viral vector production capacity concentrates at four contract manufacturers globally, constraining gene therapy supply scalability.
- EMA Conditional Marketing Authorization Complexity:Post-authorization efficacy study requirements extend regulatory uncertainty for developers seeking early patient access.
- Silver-Impregnated Dressing Substitution:Commodity antimicrobial wound products capture mild-to-moderate DEB cases, compressing margins for advanced biologic dressings.
Strategic Opportunities
- Japan PMDA Sakigake Designation:Priority review pathways for regenerative medicines enable first-in-Asia launches for gene-modified keratinocyte therapies.
- Direct-to-Patient Telemedicine Platforms:Virtual dermatology consultations for rural DEB patients bypass specialist center concentration in urban academic hospitals.
- CRISPR-Edited Fibroblast Convergence:Combination of gene editing with induced pluripotent stem cell platforms opens autologous cell therapy manufacturing at reduced scale.
Industry Challenges
- Gene Therapy Manufacturing Technician Scarcity:Good Manufacturing Practice certification for cell and gene therapy production requires 18-month training pipelines that outpace workforce supply.
- Cross-Border Reimbursement Fragmentation:Health Technology Assessment divergence between France's HAS and England's NICE complicates pan-European pricing strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dystrophic Epidermolysis Bullosa Management Market |
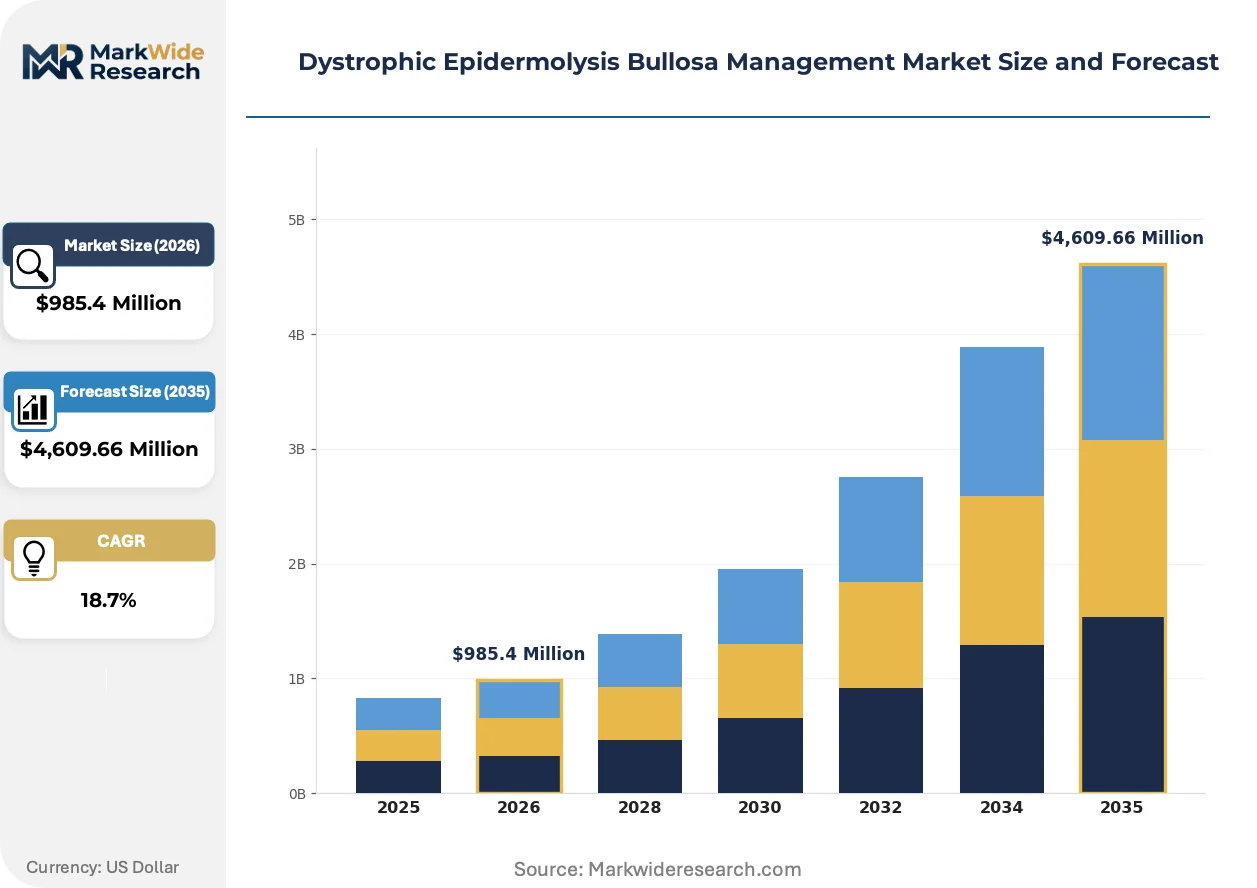
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $4,609.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Wound Dressings, Systemic Medications, Gene Therapies Delivery Mode: Intravenous, Oral, Subcutaneous, Transdermal End User: Hospitals, Clinics, Home Care Settings, Specialty Pharmacies Application: Chronic Wound Care, Pain Management, Infection Control, Patient Education |
| Companies Covered | Amryt Pharma, Phoenix Tissue Repair, Krystal Biotech, RegeneRx Biopharmaceuticals, InMed Pharmaceuticals, Castle Creek Biosciences, Wings Therapeutics, Holostem Terapie Avanzate, Abeona Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dystrophic Epidermolysis Bullosa Management Market Shifts & Advancements
In vivo gene delivery platforms are overtaking ex vivo cell culture approaches, compressing treatment timelines from months to single outpatient procedures while demanding new clinical infrastructure investments.
Redosable AAV vectors engineered for reduced immunogenicity are rendering obsolete first-generation gene therapies requiring immunosuppression protocols. Pediatric dermatology centers in the United States are adopting these platforms rapidly. The shift is collapsing the historical distinction between acute intervention and chronic disease management.
EMA's PRIME designation for regenerative medicines now mandates accelerated assessment timelines, compressing regulatory review from 210 to 150 days for DEB therapies. Developers must front-load manufacturing validation and real-world evidence collection. German and French regulators are harmonizing post-market surveillance requirements in response.
Hospital procurement committees are consolidating purchasing authority for high-cost gene therapies under centralized pharmacy and therapeutics boards. Academic medical centers in the United States are displacing decentralized physician-driven ordering. This concentration is visible most acutely at ten major pediatric dermatology referral hubs.
Dystrophic Epidermolysis Bullosa Management Market Segmentation
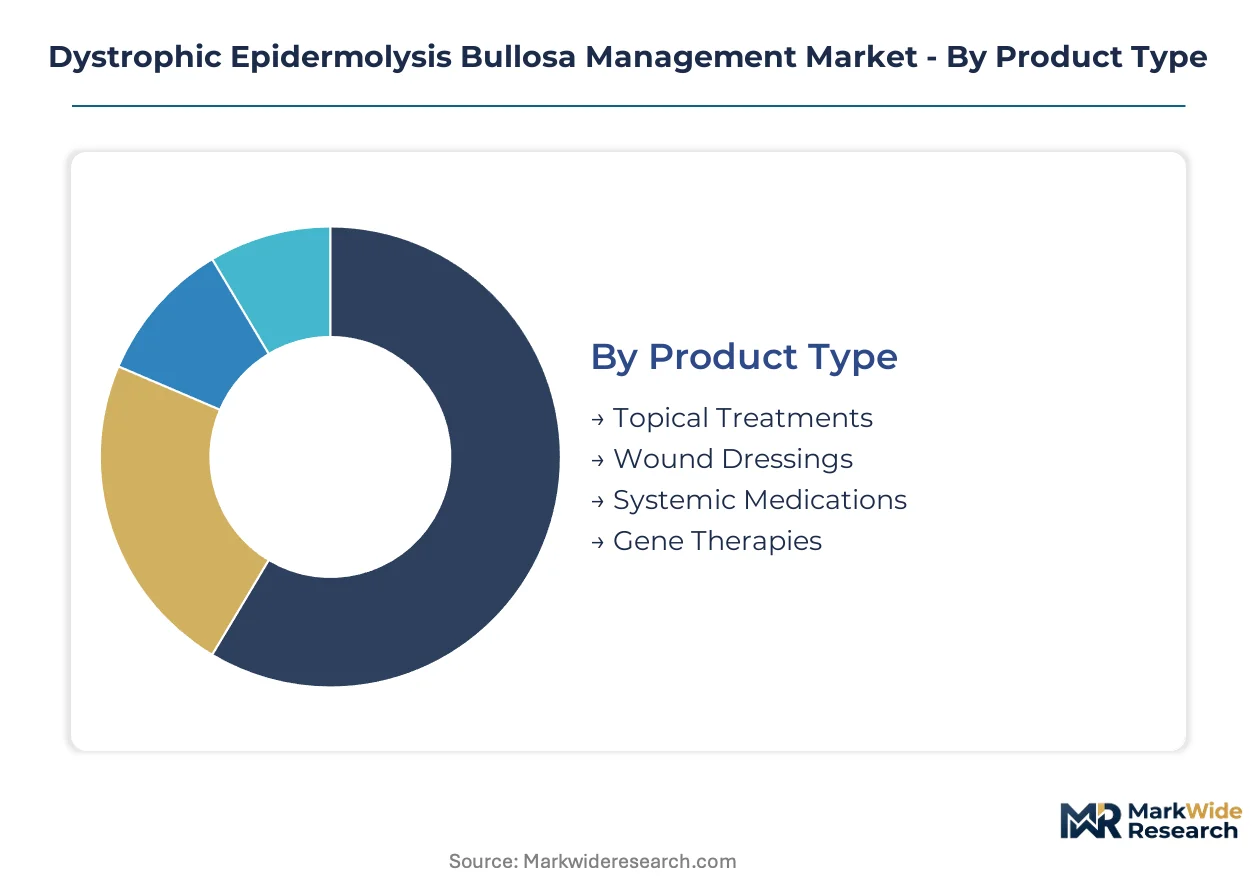
Segmentation in DEB management reveals distinct service intensity profiles across product categories. Gene therapies demand intensive patient onboarding and long-term outcome monitoring, while wound dressings require replenishment logistics and caregiver training support.
Product Type:
After-sales service intensity varies dramatically across product categories, with curative modalities requiring multi-year patient follow-up versus consumable products needing inventory replenishment systems.
- Gene Therapies:One-time corrective interventions using modified viral vectors or gene-edited keratinocytes. Demand concentrates at ten major US pediatric dermatology referral hubs where centralized pharmacy boards control procurement and patient registries track long-term outcomes.
- Wound Dressings:Hydrocolloid, foam, and silver-impregnated materials for blister coverage and moisture management. German statutory health insurance funds drive volume through outcome-based reimbursement contracts that favor advanced biologic dressings over commodity alternatives.
- Topical Treatments:Gentian violet formulations, antimicrobial creams, and barrier ointments applied directly to lesions.
- Systemic Medications:Anti-fibrotic agents and pain modulators administered for severe recessive DEB with esophageal or ocular involvement.
Wound dressings hold the largest share; momentum sits with gene therapies.
Delivery Mode:
Cost tier differentiation separates hospital-administered infusions from self-administered home therapies, with reimbursement pathways diverging accordingly.
- Intravenous:Hospital-based infusion of gene therapies and biologics requiring cold-chain handling and specialized nursing support.
- Subcutaneous:Protein replacement therapies and monoclonal antibodies delivered via injection. US specialty pharmacy networks now reach 340 hospital-based infusion centers, expanding access beyond academic medical centers.
- Oral:Systemic anti-fibrotic agents and pain medications for chronic management.
- Transdermal:Patches and topical delivery systems for localized symptom control.
Intravenous dominates value concentration; subcutaneous routes are expanding most quickly through specialty pharmacy infrastructure.
End User:
Customer type determines purchasing authority, with hospital committees consolidating decisions for high-cost therapies versus decentralized home care procurement.
- Specialty Pharmacies:Distribution nodes for advanced biologics and gene therapies requiring controlled handling and patient onboarding protocols. Krystal Biotech leverages direct-to-specialist channels to manage product integrity and registry enrollment.
- Hospitals:Academic medical centers performing gene therapy administration and complex wound procedures. Procurement committees at major US pediatric dermatology hubs now centralize purchasing authority under pharmacy and therapeutics boards.
- Home Care Settings:Daily wound dressing changes and topical applications managed by trained caregivers or patients themselves.
- Clinics:Outpatient dermatology and wound care centers for routine monitoring and dressing replacement.
Hospitals capture the highest value per patient; specialty pharmacies show the steepest expansion trajectory as distribution consolidates.
Application:
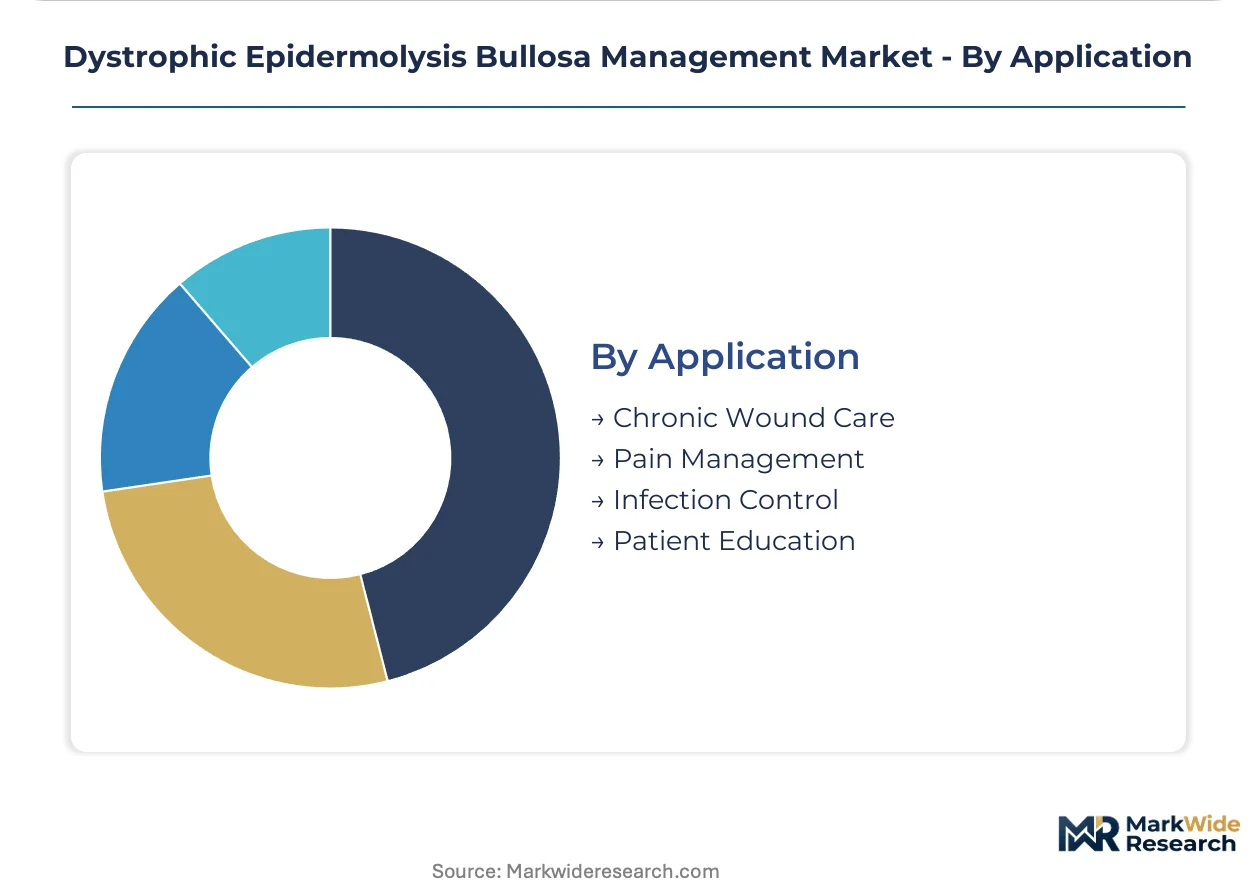
Volume concentration aligns with chronic care needs, though emerging segments target acute intervention and prevention.
- Chronic Wound Care:Ongoing blister management, infection prevention, and dermal integrity maintenance. German and French Health Technology Assessment bodies apply distinct cost-per-QALY thresholds that fragment pricing power for advanced dressings across European markets.
- Patient Education:Training programs for caregivers on proper dressing technique and infection recognition. US telemedicine platforms now enable virtual dermatology consultations for rural patients, bypassing urban specialist concentration.
- Pain Management:Systemic and topical interventions for neuropathic and procedural pain associated with DEB lesions.
- Infection Control:Antimicrobial protocols and surveillance for sepsis prevention in open wound cases.
Chronic wound care retains dominant volume; patient education is gaining share fastest through digital health platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for gene therapies concentrates in Germany and the United States where orphan drug frameworks support curative reimbursement models, while southern European markets struggle with fragmented HTA thresholds that compress margins for advanced biologics.
United States
FDA orphan drug exclusivity provisions drive seven-year market protection for collagen VII gene therapies, concentrating clinical trial investment at ten major pediatric dermatology referral hubs. Specialty pharmacy networks now reach 340 hospital-based infusion centers, expanding cold-chain distribution for biologics beyond academic medical centers. Boston and Philadelphia clusters anchor gene therapy manufacturing validation and real-world evidence collection.
Germany
Statutory health insurance funds negotiate outcome-based reimbursement for one-time curative interventions, creating precedent for gene therapy pricing acceptance. EMA PRIME designation pathways compress regulatory review timelines, accelerating patient access to regenerative medicines. The Rhine-Ruhr and Munich metropolitan areas concentrate dermatology specialist centers and centralized pharmacy procurement boards.
United Kingdom
NICE cost-per-QALY thresholds constrain pricing power for advanced wound biologics compared to German frameworks, fragmenting pan-European commercial strategy. NHS England specialized commissioning processes create access barriers for high-cost gene therapies outside designated rare disease centers. London and Manchester academic hospitals dominate patient referral pathways and clinical trial enrollment.
Japan
PMDA Sakigake designation enables priority review pathways for regenerative medicines, positioning the country for first-in-Asia launches of gene-modified keratinocyte therapies. National health insurance reimbursement for rare diseases supports premium pricing for curative modalities. Tokyo and Osaka clusters concentrate dermatology research institutions and cell therapy manufacturing infrastructure.
France
HAS cost-effectiveness assessments apply distinct methodological frameworks that diverge from NICE and German IQWiG standards, complicating unified European pricing. Early access programs for innovative therapies provide temporary reimbursement during evidence generation phases. Paris and Lyon metropolitan areas anchor specialized wound care centers and clinical research networks.
Dystrophic Epidermolysis Bullosa Management Market Competitive Landscape
Gene therapy developers and protein replacement specialists split the market between curative one-time interventions and chronic maintenance protocols. The competitive structure consolidates around platform technology ownership rather than manufacturing scale. Three archetypes dominate: viral vector gene therapy platforms, recombinant protein manufacturers, and cell-based regenerative medicine developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure contract manufacturing slots and distribution infrastructure.
Within the gene therapy archetype, Krystal Biotech and Abeona Therapeutics occupy positions emphasizing direct-to-specialist distribution control and patient registry integration. Among protein replacement developers, Amryt Pharma anchors European market access through orphan drug infrastructure. Phoenix Tissue Repair exemplifies manufacturing-scale competition for systemic collagen VII delivery. These three firms represent distinct strategic postures on commercialization geography and therapeutic modality selection.
| Leading Market Players |
|---|
| Amryt Pharma |
| Phoenix Tissue Repair |
| Krystal Biotech |
| RegeneRx Biopharmaceuticals |
| InMed Pharmaceuticals |
| Castle Creek Biosciences |
| Wings Therapeutics |
| Holostem Terapie Avanzate |
| Abeona Therapeutics |
| Others |
Supply & Pricing Matrix
Single-source viral vector manufacturing dependency concentrates production risk at four contract manufacturers globally, compressing gene therapy pricing spreads between premium curative interventions and chronic maintenance protocols while forcing developers to absorb capacity reservation premiums upstream.
Pricing Analysis
The customization-premium spread separates one-time gene therapy pricing from chronic wound dressing contracts. Three-tier pricing structure across premium gene therapies, advanced biologic dressings, and commodity hydrocolloid alternatives dominates the market. Price differentiation rests on manufacturing complexity and regulatory designation tier—FDA orphan drug exclusivity commands substantial premiums over standard wound care. Pricing pressure stems from silver-impregnated dressing substitution in mild-to-moderate cases. German statutory health insurance funds demonstrate lowest price sensitivity for curative modalities; home care settings face acute cost compression.
Supply Chain Analysis
Tariff exposure between United States and European Union jurisdictions complicates cross-border distribution of temperature-sensitive biologics. Viral vector production concentrates in United States, Germany, and Switzerland; plasmid raw materials draw from specialized fermentation facilities in United States and Ireland. Cold-chain logistics hinge on validated packaging and real-time monitoring infrastructure. Single-source contract manufacturing organization dependency creates vulnerability during capacity expansion phases. Distribution runs through specialty pharmacy networks reaching hospital-based infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement committee consolidation at ten major US pediatric dermatology referral hubs has shifted buyer power toward centralized pharmacy and therapeutics boards, fragmenting traditional physician-driven purchasing authority.
For Market Incumbents: Build patient registry moats through longitudinal outcome tracking that locks in payers for multi-year evidence generation. Secure exclusive manufacturing slots at contract viral vector facilities before capacity constraints intensify. Deepen backward integration into plasmid production to reduce single-source supplier exposure. Anchor German market access through outcome-based reimbursement contracts with statutory health insurance funds. For New Entrants and Emerging Players: Japan's underpenetrated gene therapy reimbursement pathway offers first-in-Asia positioning for regenerative medicine developers. Target rural US dermatology access gaps through direct-to-patient telemedicine platforms that bypass urban academic center concentration. Pursue PMDA Sakigake designation to compress regulatory timelines against entrenched competitors. Partner with established specialty pharmacy networks for cold-chain distribution rather than building proprietary infrastructure. For Investors and Strategic Acquirers: The market sits at a platform-technology consolidation phase that favors viral vector gene therapy developers over protein replacement manufacturers. Long-term viability favors firms with integrated patient registry and payer evidence-generation capabilities. Acquisition target archetype: mid-stage gene therapy platforms with EMA PRIME designation and established German reimbursement precedent. Monitor FDA breakthrough therapy designation velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Secures contract viral vector capacity at Lonza or Catalent before competitor lock-in. |
| Regulatory Approval Pathway | EMA PRIME designation compresses assessment timelines from 210 to 150 days. |
| Reimbursement Strategy | Outcome-based contracts with German SHI funds establish curative pricing precedent. |
| Pipeline Diversification | CRISPR-edited fibroblast platforms reduce immunogenicity risk versus first-generation AAV. |
| Strategic Partnership | Specialty pharmacy alliances extend cold-chain reach to 340 US infusion centers. |
Research Methodology
A spread of perspectives from gene therapy development executives, regulatory affairs leads at EMA and FDA, hospital formulary directors, payer access specialists, and specialty pharmacy distribution heads converged on the working assumptions. Primary interview findings were cross-validated against secondary sources including FDA orphan drug designation filings, EMA PRIME designation submissions, ClinicalTrials.gov protocol registries, and German SHI reimbursement decision databases. Bottom-up patient population estimates and top-down market size triangulation anchored volume projections.
Demand-supply balance modeling across the analysis window integrated treatment line segmentation, administration route differentiation, and regional regulatory cluster variations. CAGRs were derived from patient incidence modeling, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs included viral vector manufacturing capacity expansion schedules, HTA body cost-per-QALY threshold evolution, and specialty pharmacy network growth trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich large-cap biopharma entrants or unexpected FDA manufacturing inspection actions would shift outcomes. Gene therapy immunogenicity signals, payer budget impact resistance, and contract manufacturing organization capacity constraints represent specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Rare Disease Clinical Trials Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Churg Strauss Syndrome Market