
 Global Patient Portal Market | 2026-2036
Global Patient Portal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Portal Market Foresight
A shift from single-source EHR contracts toward multi-source ecosystem integration is expanding procurement flexibility for health systems. Epic Systems Corporation anchors enterprise deployments through deep EHR integration and captive provider networks. Oracle competes via cloud infrastructure scale and cross-industry data platform capabilities. Cerner Corporation sustains market presence through long-standing hospital system relationships and federal health IT contracts.
A patient portal constitutes a secure web-based or mobile interface that enables individuals to access personal health information, schedule clinical appointments, review laboratory results, and communicate with care teams through authenticated digital channels. These systems integrate with electronic health record backends via HL7 FHIR APIs or proprietary interoperability layers to ensure real-time data synchronization and audit-compliant access logging. Cloud-based deployment leads solution architecture due to lower capital overhead and faster implementation cycles, while integrated EHR systems capture the dominant share of provider budgets as health systems prioritize unified clinical workflows over standalone point solutions. Mobile applications represent the fastest-expanding solution type as smartphone-native patient populations expect on-demand health management tools.
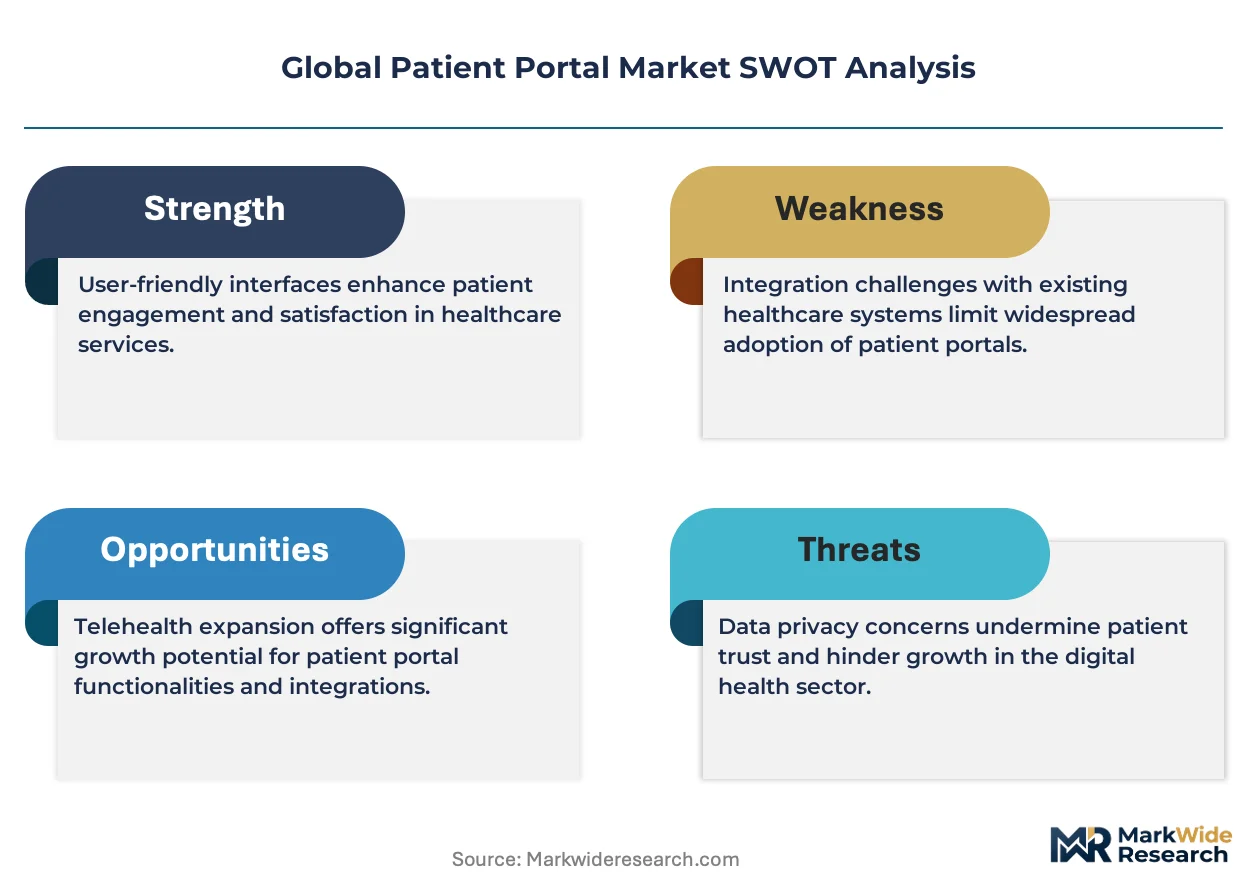
The ONC Cures Act Final Rule, HIPAA security requirements, and FDA guidance on software as a medical device collectively shape product development roadmaps and market access conditions for portal vendors operating across multiple jurisdictions. EMA's evolving digital health framework and GDPR-compliant data residency requirements in Europe add compliance layers that favor vendors with established regional infrastructure. Stakeholders must monitor how interoperability mandate enforcement timelines and emerging AI diagnostic integration standards reshape competitive differentiation and customer retention dynamics.
Market Dynamics
The ONC Cures Act Final Rule is forcing hospital systems to dismantle information-blocking practices and expose clinical data through standardized APIs, fundamentally restructuring vendor procurement criteria around interoperability certification rather than EHR brand loyalty.
Growth Catalysts
- FHIR API Standardization:The ONC Cures Act mandates HL7 FHIR R4 implementation, compelling providers to adopt interoperable architectures that accelerate third-party portal integration and reduce vendor lock-in.
- Smartphone-Native Patient Expectations:Healthcare consumers accustomed to mobile banking and retail applications now demand equivalent on-demand access to scheduling, results review, and asynchronous messaging with care teams.
- India:The country's national health regulator is expanding digital health infrastructure through the Ayushman Bharat Digital Mission, creating procurement opportunities for cloud-based patient engagement platforms in public hospital networks.
Market Restraints
- HIPAA Compliance Burden:The security rule's technical safeguards requirements impose substantial engineering overhead on portal developers, particularly for audit logging and access control implementations that satisfy state-level privacy variations.
- Cloud Infrastructure Concentration:Reliance on hyperscale cloud providers for HIPAA-compliant hosting creates vendor dependency risks and limits pricing leverage for mid-sized health IT vendors.
- Legacy EHR Proprietary Protocols:Closed integration layers maintained by dominant enterprise EHR vendors continue to fragment data exchange, forcing portal developers to maintain costly adapter codebases.
Strategic Opportunities
- Brazil:ANVISA's accelerating digital health framework adoption and underpenetrated private hospital sector create first-mover advantages for vendors establishing Portuguese-language platform localization.
- AI-Assisted Triage Integration:Convergence of large language models with symptom-checker modules enables portals to escalate appropriate cases to telehealth or emergency services, expanding platform utility beyond passive record access.
- Retail Clinic Channel Expansion:CVS Health, Walgreens, and Amazon One Medical are deploying patient portals as consumer acquisition tools, opening direct-to-patient distribution channels outside traditional health system procurement.
Industry Challenges
- Interoperability Engineer Scarcity:Health IT vendors face acute recruitment difficulty for developers proficient in FHIR implementation guides, SMART on FHIR authentication, and bulk data access protocols.
- State Privacy Law Fragmentation:California's CMIA, Washington's My Health My Data Act, and emerging state-level regulations create compliance multiplication costs that delay product roadmaps and inflate legal review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Portal Market |
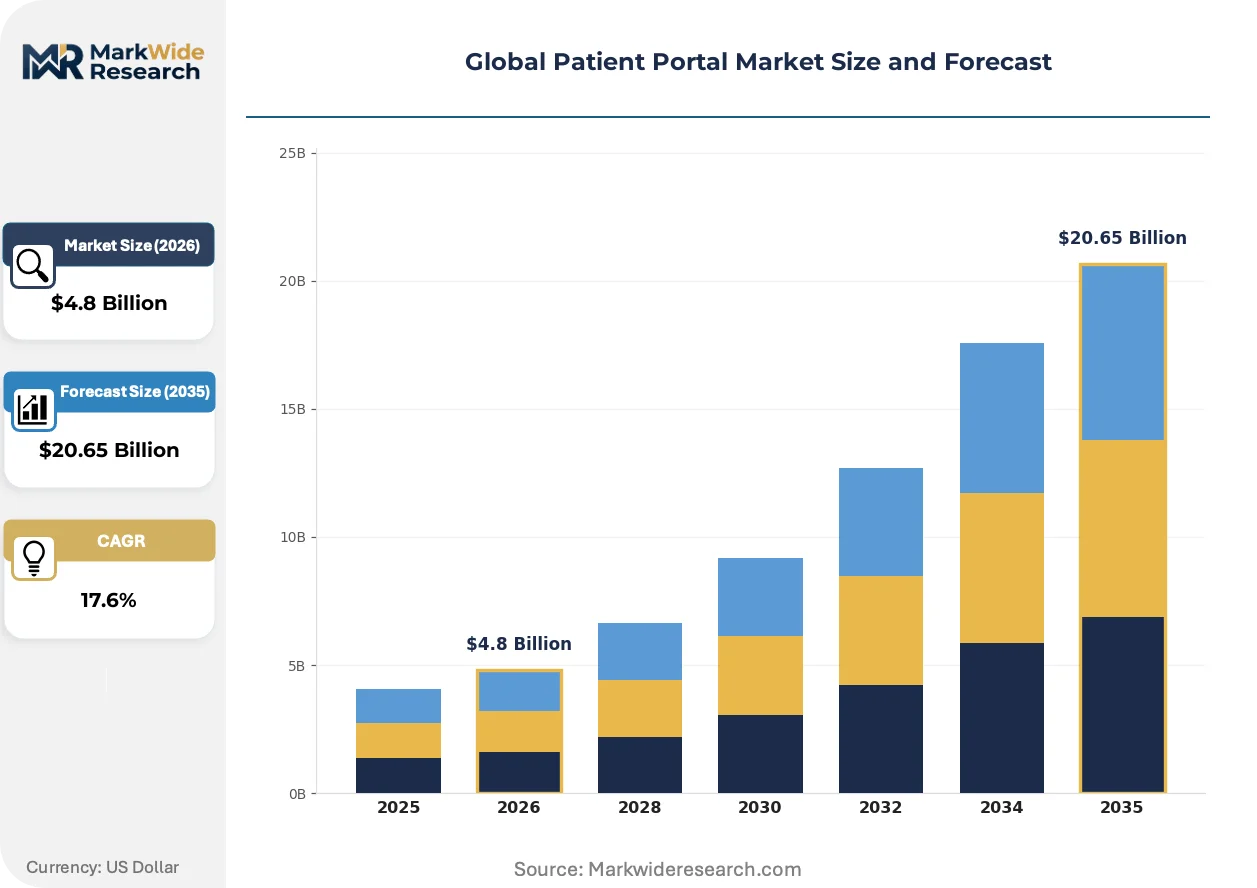
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Web-Hosted Solution Type: Standalone Portals, Integrated EHR Systems, Mobile Applications, Telehealth Platforms Use Case: Appointment Scheduling, Prescription Management, Lab Result Access, Billing Information, Health Tracking End User Segment: Health Plans, Clinics, Specialty Care Centers, Home Health Agencies |
| Companies Covered | Epic Systems Corporation, Oracle, athenahealth, Cerner Corporation, Allscripts Healthcare Solutions, Meditech, NextGen Healthcare, McKesson Corporation, eClinicalWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Portal Market Shifts & Advancements
Patient portal architecture is pivoting from EHR-tethered record viewers toward modular engagement platforms that embed third-party services through standardized APIs, reshaping competitive differentiation around ecosystem breadth rather than native feature depth.
Blockchain-based credential verification is decentralizing identity management in patient portals by enabling self-sovereign health records that patients control across disconnected provider networks. Large health systems in Germany and Switzerland are piloting Ethereum-compatible wallets for cross-border continuity of care documentation. This architecture is decentralizing data storage authority away from hospital-controlled repositories toward patient-mediated exchange protocols that reduce reconciliation costs.
EMA's Medical Device Regulation is reclassifying certain diagnostic decision-support modules embedded within patient portals as Class IIa medical devices, triggering conformity assessment requirements that favor established vendors with notified body relationships. Portal developers must now segregate regulated from unregulated functionality or pursue CE marking for integrated algorithms. European hospital procurement committees are prioritizing MDR-compliant platforms, disadvantaging point-solution entrants lacking quality management system certification.
Health systems are unbundling patient portal procurement from enterprise EHR contracts, creating separate RFP processes for engagement-specific capabilities like remote monitoring integration and patient-reported outcome collection. This purchasing pattern shift fragments vendor relationships that previously concentrated through single-source agreements. The United States exhibits the most pronounced unbundling behavior, where IDN consolidation has generated sufficient IT scale to negotiate modular best-of-breed stacks.
Global Patient Portal Market Segmentation
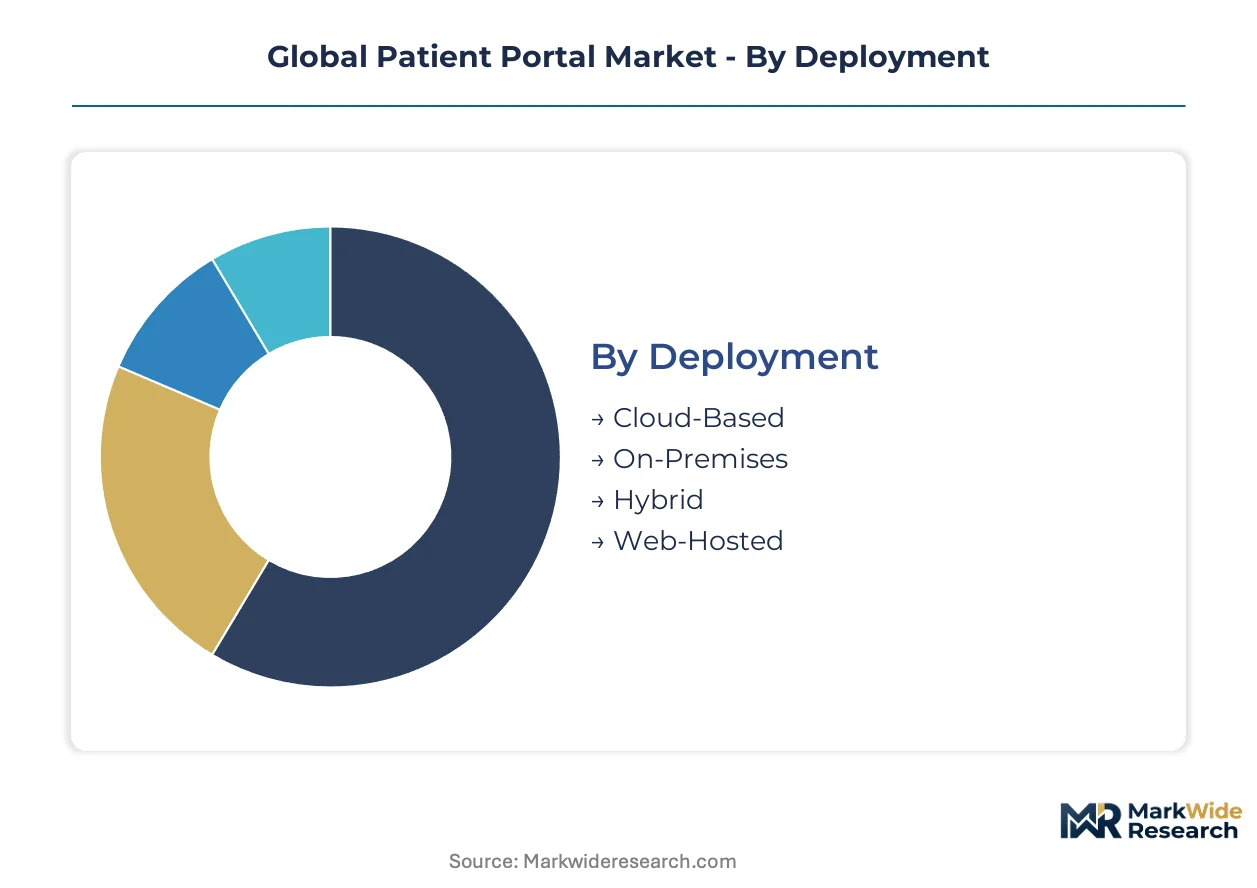
Patient portal procurement patterns diverge sharply across deployment architectures, solution configurations, and clinical use cases. Hospital systems prioritize segments that minimize HIPAA compliance overhead while satisfying ONC interoperability mandates. Vendor positioning depends on matching segment-specific technical requirements with existing infrastructure investments.
Deployment:
Standardization dominates cloud configurations, while on-premises and hybrid models retain customization latitude for security-sensitive installations.
- Cloud-Based:Multi-tenant architectures with automatic security patching and elastic compute scaling. Demand concentrates in United States community hospital networks seeking to defer capital expenditure while meeting HIPAA business associate agreement requirements through AWS, Azure, or Google Cloud contracted hosting.
- On-Premises:Dedicated hardware installations within hospital data centers with full administrative control over physical access and network segmentation. German and Swiss health systems favor this model under GDPR data residency enforcement and BfDI federal data protection authority guidance.
- Hybrid:Split architectures keeping protected health information on-premises while routing patient-facing interfaces through cloud edge nodes. United Kingdom NHS trusts deploy hybrid models to balance patient access latency with information governance requirements.
- Web-Hosted:Single-tenant managed hosting with vendor-controlled infrastructure but client-dedicated application instances. Smaller clinic chains in Brazil and Mexico select this middle-ground option where internal IT capacity is limited.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated health systems seek architectural compromise.
Solution Type:
Cost tier stratification separates enterprise-integrated suites from point solutions and mobile-native offerings.
- Standalone Portals:Best-of-breed platforms requiring custom HL7 FHIR integration with underlying EHR systems. United States independent physician associations and ambulatory surgery centers purchase standalone solutions to avoid Epic or Oracle enterprise licensing minimums.
- Integrated EHR Systems:Native modules embedded within Cerner, Epic, or Meditech environments with pre-configured data synchronization. Hospital systems in Canada prioritize integrated solutions under Health Canada interoperability guidance to minimize implementation risk.
- Mobile Applications:Smartphone-native interfaces with biometric authentication and push notification architectures. India's Ayushman Bharat Digital Mission procurement specifications emphasize mobile-first design for rural patient populations with limited desktop access.
- Telehealth Platforms:Converged video consultation and asynchronous messaging systems with embedded portal functionality. Brazil's ANVISA telemedicine regulatory expansion has accelerated telehealth-integrated portal adoption in São Paulo and Rio de Janeiro private hospital networks.
Integrated EHR Systems capture the largest share of provider technology budgets. Mobile Applications are gaining share fastest among new procurement decisions.
Use Case:
Application maturity varies from transactional scheduling workflows to longitudinal health data aggregation.
- Appointment Scheduling:Real-time calendar integration with automated waitlist management and no-show prediction algorithms. United States retail clinic chains including CVS MinuteClinic deploy scheduling-centric portals as patient acquisition channels.
- Prescription Management:Medication adherence tracking with pharmacy integration and refill request automation. Germany's electronic prescription mandate (E-Rezept) has made this functionality compulsory for statutory health insurance-contracted providers.
- Lab Result Access:Direct patient release of pathology and diagnostic imaging reports with clinician annotation layers. Australia's My Health Record system mandates lab result accessibility as a core portal requirement under TGA digital health guidance.
- Billing Information:Cost estimation tools, payment plan configuration, and insurance claim status tracking. United States health systems deploy billing-focused portals to reduce call center volume and accelerate revenue cycle collection.
- Health Tracking:Integration with consumer wearable devices and patient-reported outcome instruments for chronic disease management. Netherlands hospital networks incorporate health tracking into diabetes and cardiovascular remote monitoring programs.
Appointment Scheduling and Lab Result Access together constitute the majority of active patient portal sessions. Health Tracking exhibits the steepest expansion trajectory as remote patient monitoring reimbursement codes mature.
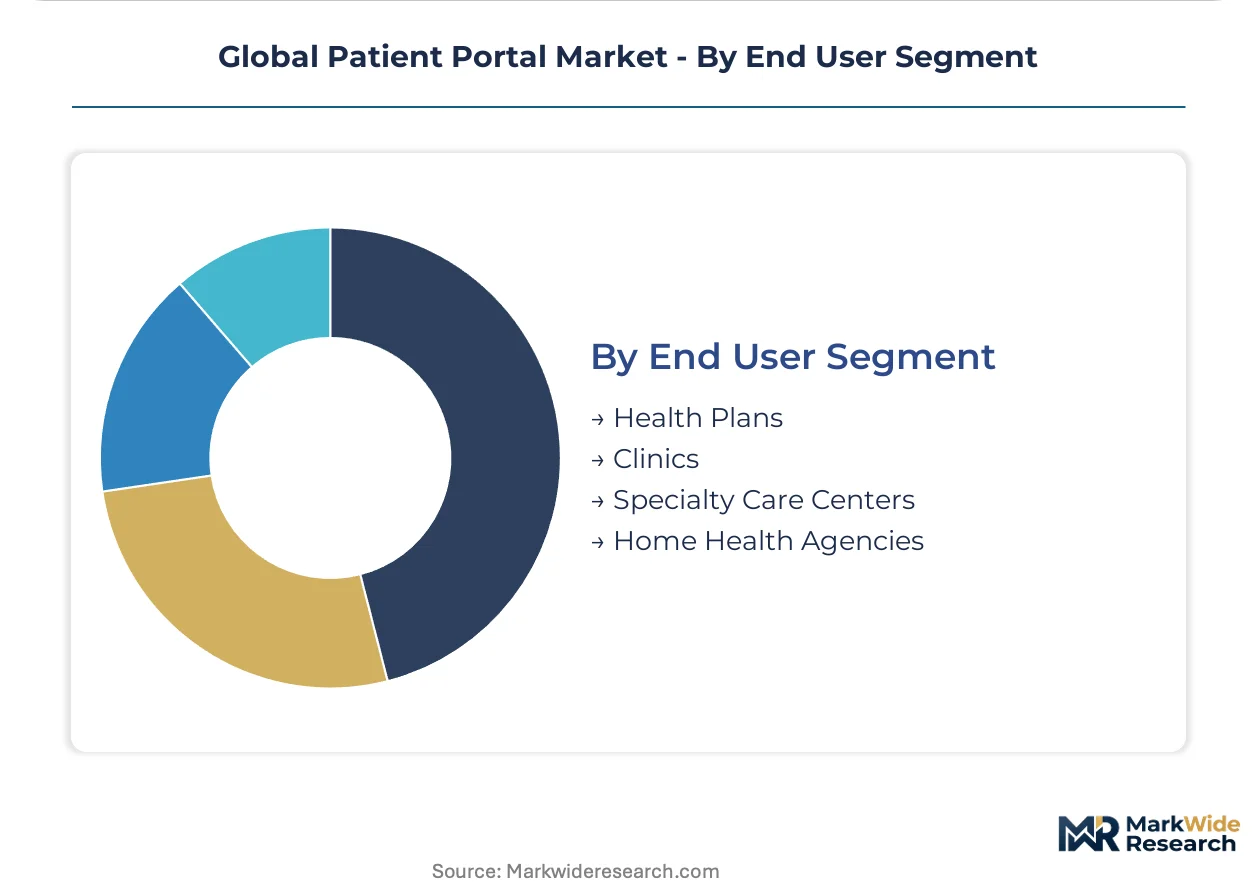
End User Segment:
Customer type determines procurement complexity, with health plans presenting the most fragmented decision-making environment.
- Health Plans:Payer-operated portals spanning member eligibility, provider directory search, and claims history across network participants. United States Medicare Advantage plans invest in portal differentiation to improve CMS Star Ratings and retention metrics.
- Clinics:Ambulatory care settings with lower patient volume but higher per-clinician portal utilization rates. India's urban primary health centers under the National Health Mission deploy simplified clinic portals with Hindi and regional language localization.
- Specialty Care Centers:Oncology, cardiology, and orthopedics practices requiring disease-specific content modules and care pathway integration. Germany's certified cancer centers (Onkologische Spitzenzentren) mandate portal-based patient navigation tools.
- Home Health Agencies:Post-acute and long-term care providers coordinating caregiver schedules, medication administration records, and family communication. United Kingdom domiciliary care providers integrate portal access with NHS Continuing Healthcare assessment workflows.
Health Plans operate the largest aggregate patient portal user bases. Specialty Care Centers show the fastest adoption acceleration as value-based reimbursement ties patient engagement to quality metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates patient portal procurement through federal incentive structures and large integrated delivery network consolidation. Hospital systems in Boston, Nashville, and the San Francisco Bay Area anchor enterprise deployment clusters.
United States
Medicare Merit-based Incentive Payment System and Medicaid Promoting Interoperability programs drive hospital IT procurement toward certified portal solutions. HIPAA Security Rule enforcement through OCR audits shapes vendor engineering priorities around access logging and encryption. Epic Systems Corporation's Verona headquarters anchors a Midwest health IT corridor extending through Chicago and Minneapolis health systems.
Germany
Gematik's electronic health card infrastructure and TI-Connector specifications mandate interoperable patient access interfaces for statutory insurance networks. BfDI federal data protection authority guidance enforces strict data residency requirements favoring on-premises or EU-sovereign cloud deployments. Berlin and Munich hospital clusters pilot blockchain-based credential verification for cross-border continuity of care.
India
Ayushman Bharat Digital Mission procurement specifications emphasize mobile-first design for rural patient populations with limited desktop infrastructure. The National Health Authority's Health Facility Registry creates standardized provider directories for portal integration. Bangalore and Hyderabad technology corridors host indigenous platform developers serving public hospital network tenders.
Brazil
ANVISA's telemedicine regulatory expansion accelerates portal adoption in São Paulo and Rio de Janeiro private hospital networks. The country's national health regulator mandates digital health framework compliance for patient engagement platforms serving supplementary health plans. Porto Alegre and Curitiba medical centers lead southern region deployment of integrated scheduling and telehealth modules.
United Kingdom
NHS England's App Library certification program and GP IT Futures procurement framework standardize patient portal functionality requirements across primary care networks. NHSX interoperability standards mandate FHIR API implementation for supplier qualification. London and Manchester integrated care systems pilot hybrid deployment models balancing patient access latency with information governance requirements.
Global Patient Portal Market Competitive Landscape
Global majors compete with regional champions across interoperability certification and EHR integration depth. The vendor base concentrates around three enterprise anchors with captive provider networks, while mid-tier specialists capture unbundled procurement opportunities. Three strategic archetypes dominate: EHR-native platform developers, cloud infrastructure hyperscalers, and standalone engagement specialists. Competitive moves center on API ecosystem expansion and modular best-of-breed stack assembly.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation exemplify platform consolidation through deep clinical workflow integration and long-standing hospital system relationships. Oracle occupies a position bridging cloud infrastructure scale with cross-industry data platform capabilities. Among standalone specialists, athenahealth and eClinicalWorks sit within the ambulatory-focused segment serving independent physician associations seeking to avoid enterprise licensing minimums. NextGen Healthcare represents the specialty-care vector with disease-specific module development.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle |
| athenahealth |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| Meditech |
| NextGen Healthcare |
| McKesson Corporation |
| eClinicalWorks |
| Others |
Supply & Pricing Matrix
HIPAA Security Rule technical safeguard mandates gate qualified supply for patient portal vendors, restricting premium-tier pricing access to platforms with certified audit logging and encryption implementations that satisfy OCR enforcement standards.
Pricing Analysis
Input-cost pass-through from hyperscale cloud infrastructure fees shapes SaaS-tiered subscription models across the patient portal market. Price differentiation hinges on FHIR API certification depth and HIPAA business associate agreement coverage, with enterprise health systems showing lowest sensitivity due to bundled EHR procurement, while independent physician associations face acute cost compression from per-seat licensing minimums.
Supply Chain Analysis
Cloud compute supply rests on AWS, Microsoft Azure, and Google Cloud data center networks concentrated in the United States and Western Europe. Raw material dependencies span server-grade silicon from Taiwan, encryption hardware modules from Germany, and identity verification APIs from specialized fintech providers. Single-source vulnerability concentrates around FHIR implementation guide maintenance by HL7 International, while distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient portal market functions as a stable compounder where federal interoperability mandate enforcement generates predictable procurement cycles across health system customers.
For Market Incumbents: Deepen vertical integration into cloud infrastructure through captive data center deployments or exclusive hyperscaler partnerships to defend margin position against modular best-of-breed entrants. Expand FHIR API ecosystem breadth to lock in provider workflow dependencies before ONC certification timelines harden procurement criteria. For New Entrants and Emerging Players: ONC Cures Act Final Rule implementation in the United States opens a window for standalone portal developers to capture unbundled procurement from IDNs seeking scheduling and remote monitoring modules outside Epic or Oracle enterprise contracts. Target ambulatory surgery centers and retail clinic chains with lightweight mobile-first deployments that bypass EHR-native minimums. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier engagement specialists because hospital system consolidation is fragmenting vendor relationships previously captured by single-source EHR agreements. Monitor AI diagnostic integration standards as the signal to watch for platform valuation inflection, with FDA software-as-medical-device guidance trajectories determining which symptom-checker modules achieve reimbursable status.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | ONC interoperability mandates make FHIR R4 implementation a non-negotiable procurement qualifier for hospital systems. |
| Mobile-First Platform Development | India's Ayushman Bharat Digital Mission specifications prioritize smartphone-native interfaces for rural patient access. |
| AI Triage Module Integration | FDA software-as-medical-device guidance reclassifies diagnostic decision-support as regulated functionality requiring conformity assessment. |
| Hybrid Deployment Architecture | Germany's BfDI data residency enforcement favors split cloud-edge models keeping protected health information on-premises. |
| Retail Clinic Channel Partnership | CVS Health and Amazon One Medical deploy portals as direct-to-patient acquisition tools outside health system procurement. |
Research Methodology
Multiple input streams — structured interviews with health system CIOs and biomedical engineers, GPO contract database analysis, and CMS Medicare reimbursement filings — were reconciled against secondary validation from FDA 510(k) clearances, ONC certification records, and hospital procurement RFP documents. Bottom-up sizing of vendor-reported deployments was cross-checked against top-down health IT spending estimates from federal incentive program disbursements.
Historical growth trajectories were cross-referenced against panel input from integration specialists and EHR implementation consultants to anchor projection assumptions. Segmentation modeling spanned deployment architecture, solution type, clinical use case, and end-user segment across the analysis window. CAGR derivation incorporated health system consolidation velocity, interoperability mandate enforcement timelines, and remote patient monitoring reimbursement code expansion as industry-specific demand drivers.
Revisions become necessary when ONC enforcement timelines shift, HIPAA state-level privacy fragmentation accelerates, or AI diagnostic integration standards trigger new regulatory classification requirements. A small set of named triggers — federal incentive program reauthorization, EMA Medical Device Regulation conformity assessment expansion, and hyperscale cloud pricing volatility — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Econsent in Healthcare Market