
 Global Smart Implantable Pumps Market | 2026-2036
Global Smart Implantable Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Implantable Pumps Market Foresight
The premium-commodity split in smart implantable pumps is repositioning around closed-loop algorithm sophistication versus basic programmable reservoir systems. Medtronic leverages its vertically integrated sensor-pump ecosystem to dominate high-acuity neurological applications. Flowonix Medical specializes in targeted intrathecal delivery platforms that anchor its position in chronic pain management segments.
Smart implantable pumps are sealed, biocompatible drug delivery systems incorporating microelectromechanical valves, telemetry modules, and rechargeable power cells to administer precise therapeutic doses subcutaneously or intrathecally over extended durations. Infusion pumps with wireless communication capabilities command the strongest margin pools as hospitals prioritize real-time dose tracking and remote titration, while Bluetooth-enabled insulin pumps represent the fastest-expanding technology segment amid ambulatory diabetes management adoption. Pain management pumps serving cancer pain relief applications retain mature, stable demand profiles in rehabilitation centers.
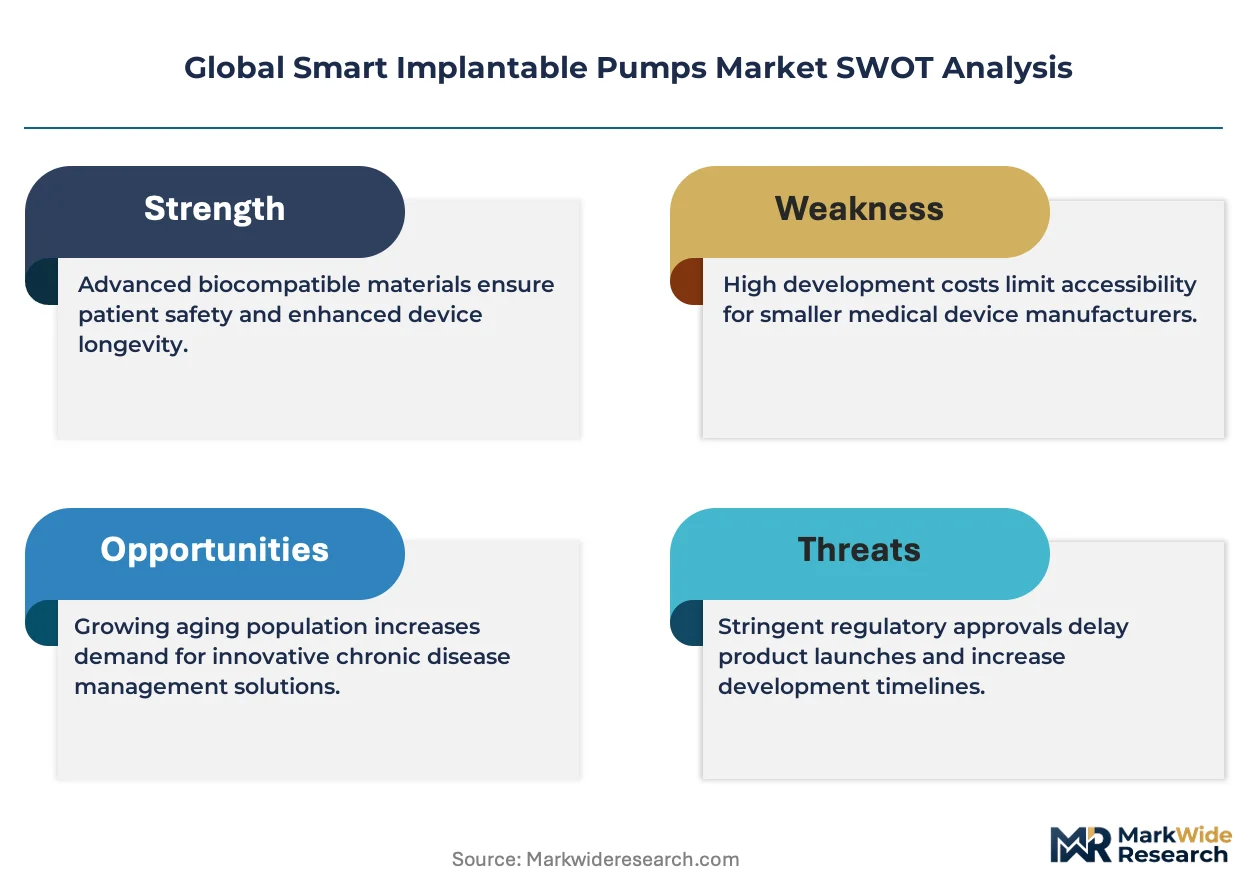
FDA premarket approval requirements, EU MDR technical documentation mandates, and ISO 14708 active implantable medical device standards collectively elevate barriers for new entrants while accelerating consolidation among established manufacturers. The EU AI Act's risk-classification framework for software-driven dosing algorithms will further differentiate market access trajectories across regulatory jurisdictions. Stakeholders must monitor evolving reimbursement parity between implantable pumps and conventional infusion modalities in key national health systems.
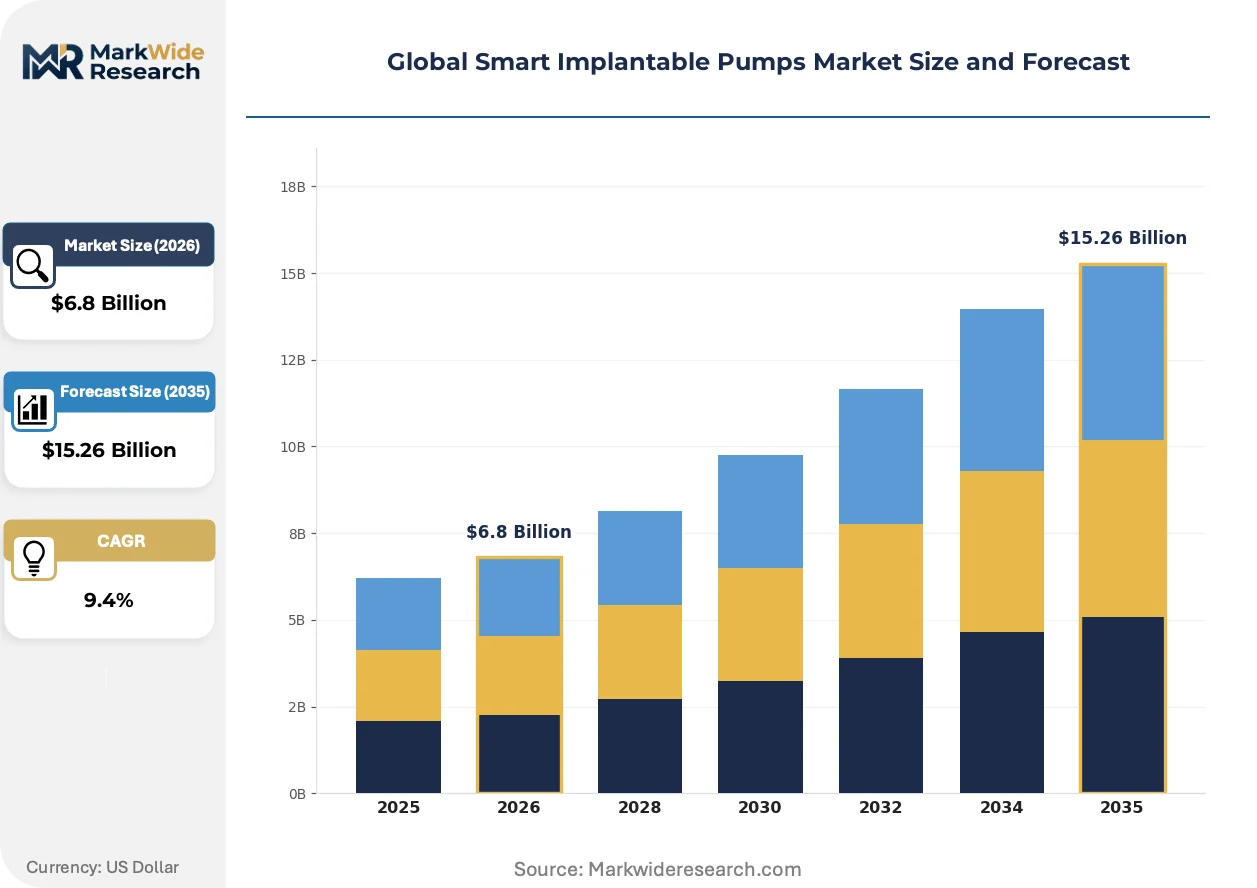
Market Dynamics
Closed-loop algorithm sophistication is bifurcating the smart implantable pumps landscape between premium sensor-integrated systems and basic programmable reservoirs, forcing manufacturers to choose between R&D intensity and cost engineering.
Growth Catalysts
- Oncology infusion expansion:Specialized cancer clinics in Germany and the United States are scaling intrathecal chemotherapy protocols, expanding device utilization for pain management and targeted drug delivery.
- EU MDR compliance acceleration:Technical documentation mandates for active implantable medical devices are compressing clearance timelines for established manufacturers with robust quality management systems.
- Bluetooth-enabled insulin delivery:Ambulatory diabetes management programs in Japan are adopting wireless communication modules for real-time glucose monitoring integration.
Market Restraints
- Lithium-ion cell supply concentration:Rechargeable power cell sourcing depends on concentrated Asian battery suppliers, exposing manufacturers to raw material volatility and geopolitical friction.
- FDA premarket approval timelines:Class III device pathways for novel dosing algorithms extend development cycles by 18-36 months, elevating capital requirements for new entrants.
- External infusion pump substitution:Hospital-based ambulatory infusion systems retain cost advantages for short-duration therapies, limiting implantable penetration in acute care settings.
Strategic Opportunities
- Pediatric neurostulation underpenetration:Intrathecal baclofen delivery for cerebral palsy spasticity remains underserved in French and Italian rehabilitation networks.
- EU AI Act algorithm classification:Risk-tiered frameworks for software-driven dosing create regulatory clarity that accelerates investment in autonomous titration capabilities.
- Remote patient monitoring convergence:Integration of telemetry modules with cloud-based dose tracking platforms enables subscription revenue models for device manufacturers.
Industry Challenges
- Biocompatibility engineering talent scarcity:Specialized expertise in long-term implantable materials and MEMS valve design concentrates among limited academic and industry research clusters.
- ISO 14708-1 certification complexity:Active implantable medical device electrical safety testing requires specialized laboratory infrastructure that extends product development timelines.
- Legacy hospital IT integration:Wireless pump telemetry protocols must interface with fragmented electronic health record systems across multi-site health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Implantable Pumps Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vascular Pumps, Infusion Pumps, Pain Management Pumps, Insulin Pumps Technology: Wireless Communication, Battery Powered, Programmable, Remote Monitoring, Bluetooth Enabled Application: Diabetes Management, Cancer Pain Relief, Neurological Disorders, Cardiovascular Therapy End User: Ambulatory Surgery Centers, Specialized Clinics, Rehabilitation Centers, Research Institutions |
| Companies Covered | Medtronic, Abbott Laboratories, Flowonix Medical, Berlin Heart, Insulet Corporation, Tandem Diabetes Care, B. Braun Melsungen, Fresenius Kabi, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Implantable Pumps Market Shifts & Advancements
Algorithmic dosing autonomy and sensor fusion are compressing the gap between implantable pumps and closed-loop therapeutic systems, reshaping competitive advantage around software capabilities rather than hardware reliability alone.
Solid-state MEMS valve technology is absorbing precision dosing functions previously handled by mechanical peristaltic mechanisms. Academic medical centers in Switzerland and the Netherlands are piloting these valves for intrathecal baclofen delivery. The shift is absorbing margin from conventional pump architectures while enabling sub-microliter dose accuracy that expands addressable therapeutic indices.
The EU AI Act's risk-classification framework for software-driven medical devices is forcing algorithm documentation standards that exceed current FDA predicate device pathways. Manufacturers must submit conformity assessments for machine-learning dosing models that adapt to patient physiology. Neurological applications face the steepest compliance burden, pushing development resources toward pain management segments with clearer regulatory precedents.
Hospital procurement departments are consolidating vendor contracts for implantable drug delivery systems under value-based frameworks that bundle device, implantation, and long-term management fees. German sickness funds and Japanese social insurance programs are piloting these arrangements for chronic pain patients. The restructuring favors manufacturers with vertically integrated service capabilities over pure device suppliers.
Global Smart Implantable Pumps Market Segmentation
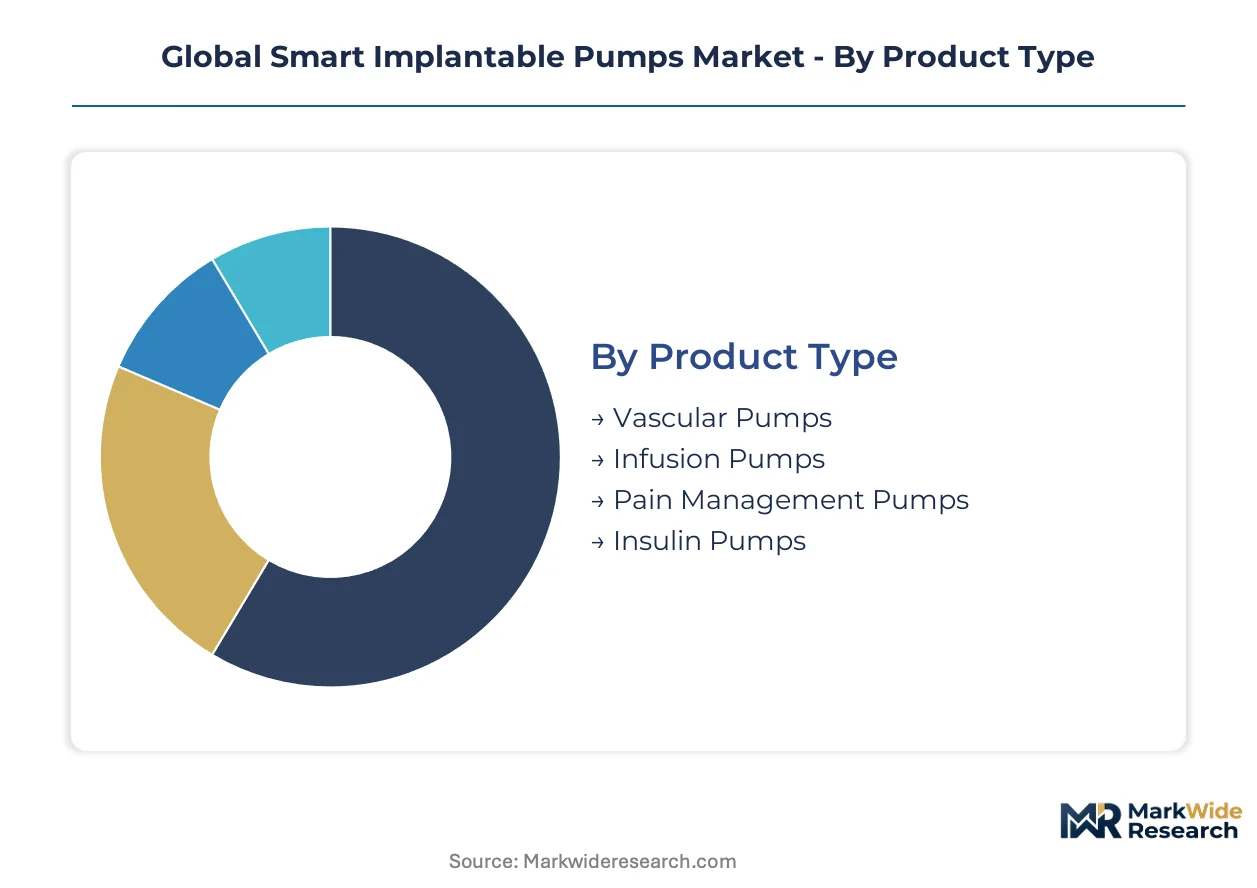
Smart implantable pumps serve heterogeneous clinical environments where dosing precision requirements, connectivity infrastructure, and reimbursement pathways diverge sharply. Segmentation reveals how manufacturers align R&D investments with specific therapeutic indices and care delivery settings.
Product Type:
Purchase decisions pivot on therapeutic duration and acuity level, with long-term implantation favoring sealed reservoir designs over external alternatives.
- Infusion Pumps:Sealed biocompatible systems incorporating microelectromechanical valves and rechargeable power cells deliver precise subcutaneous or intrathecal doses over extended durations. Demand concentrates in German and United States oncology clinics scaling intrathecal chemotherapy protocols, though lithium-ion supply concentration creates sourcing vulnerability.
- Insulin Pumps:Bluetooth-enabled devices with wireless communication modules integrate real-time glucose monitoring for ambulatory diabetes management. Japanese social insurance programs are piloting these systems fastest, where reimbursement parity with conventional infusion is establishing.
- Vascular Pumps:Catheter-directed delivery systems target cardiovascular therapeutic indices with programmable flow rates.
- Pain Management Pumps:Intrathecal baclofen and opioid delivery platforms anchor chronic pain segments in rehabilitation networks.
Infusion pumps lead on scale; insulin pumps lead on momentum.
Technology:
Margin pools track algorithmic sophistication, with closed-loop sensor integration commanding premium positioning over basic programmable reservoirs.
- Wireless Communication:Telemetry modules enabling real-time dose tracking and remote titration command the strongest hospital procurement interest. United States health networks prioritize these capabilities for multi-site care coordination, though legacy EHR integration fragments deployment.
- Bluetooth Enabled:Low-energy protocols support ambulatory patient monitoring with smartphone connectivity. Japanese diabetes management programs are adopting these modules fastest amid METI digital health initiatives.
- Remote Monitoring:Cloud-integrated platforms enable subscription revenue models for device manufacturers.
- Programmable:Basic reservoir systems with physician-set dosing schedules serve cost-sensitive therapeutic segments.
- Battery Powered:Rechargeable cell architectures depend on concentrated Asian suppliers, exposing manufacturers to raw material volatility.
Wireless communication captures the largest revenue pool; Bluetooth-enabled systems are climbing the fastest.
Application:
Regulatory pathway complexity varies by therapeutic area, with neurological applications facing steeper compliance burdens under EU AI Act algorithm classification.
- Diabetes Management:Ambulatory glucose control protocols leverage Bluetooth-enabled insulin delivery with continuous monitoring integration. Japanese and United States reimbursement frameworks are expanding coverage fastest, though FDA premarket timelines extend development cycles.
- Cancer Pain Relief:Intrathecal chemotherapy and analgesic delivery serves specialized clinic environments in Germany and the United States. German sickness funds are piloting value-based procurement bundling device and long-term management fees.
- Neurological Disorders:Intrathecal baclofen for spasticity management remains underpenetrated in French and Italian rehabilitation networks.
- Cardiovascular Therapy:Vascular-directed infusion targets acute therapeutic indices with shorter implantation durations.
Cancer pain relief leads on installed base; diabetes management leads on expansion trajectory.
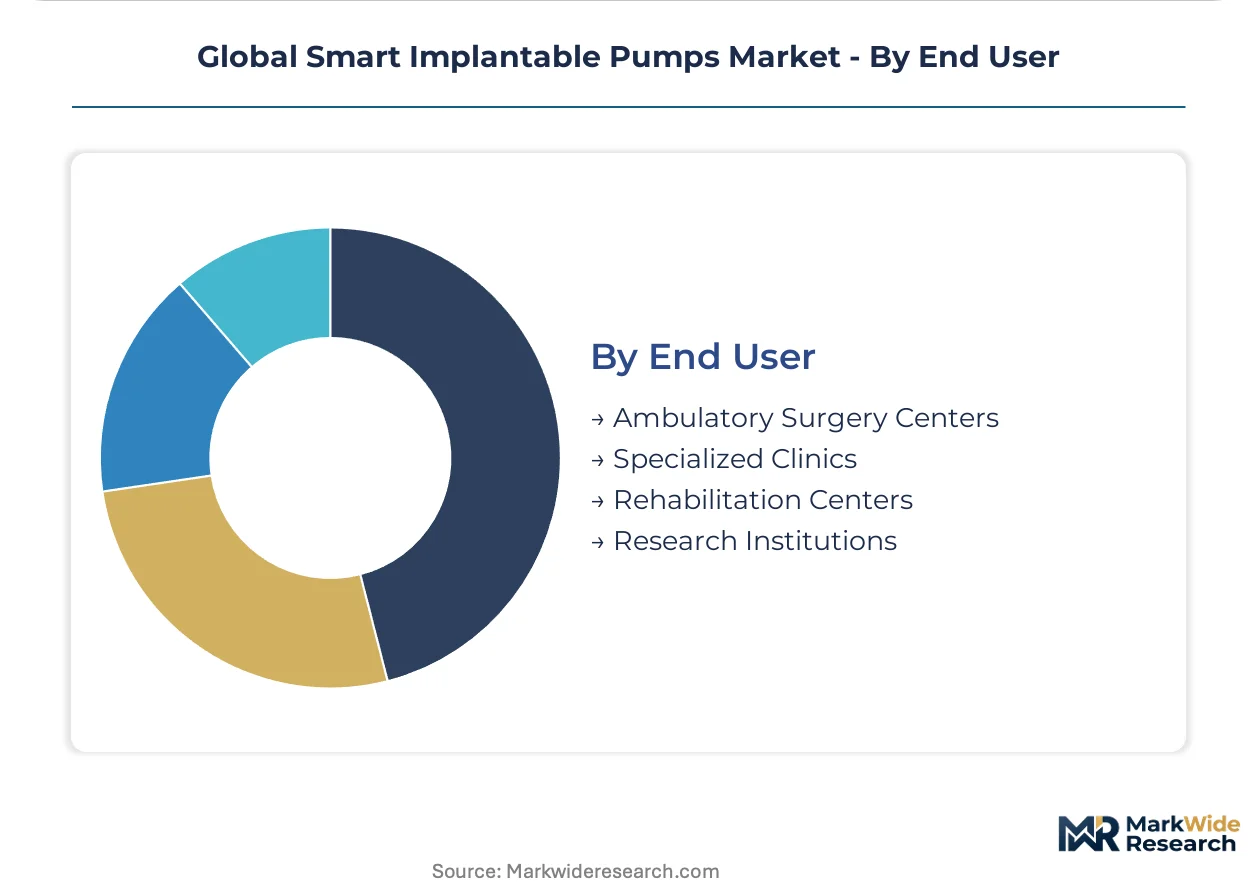
End User:
Procurement authority concentrates in integrated health networks, with value-based contracting favoring manufacturers with vertically integrated service capabilities.
- Specialized Clinics:Oncology and pain management facilities in Germany and the United States scale intrathecal protocols with dedicated infusion infrastructure. EU MDR technical documentation mandates are compressing clearance timelines for established suppliers.
- Rehabilitation Centers:Chronic pain and spasticity management programs in French and Italian networks represent underpenetrated demand for intrathecal baclofen delivery.
- Ambulatory Surgery Centers:Short-duration implantation procedures favor cost-optimized programmable systems over sensor-integrated alternatives.
- Research Institutions:Academic medical centers in Switzerland and the Netherlands pilot solid-state MEMS valve technology for sub-microliter dose accuracy.
Specialized clinics dominate current volume; rehabilitation centers offer the steepest penetration upside.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurosurgical and oncology nursing talent concentrates in German university hospitals, Japanese metropolitan medical centers, and United States academic health systems, anchoring regional adoption patterns for implantable drug delivery expertise.
United States
FDA premarket approval pathways for Class III active implantable devices compress clearance timelines for established manufacturers with robust quality management systems. Specialized cancer clinics in Texas and Massachusetts scale intrathecal chemotherapy protocols with dedicated infusion infrastructure. Boston's Longwood Medical Area anchors neurological application development through academic-industry partnerships.
Germany
German sickness funds pilot value-based procurement frameworks bundling device implantation with long-term management fees for chronic pain patients. EU MDR technical documentation mandates for active implantable medical devices accelerate consolidation among manufacturers with established notified body relationships. The Rhine-Ruhr medical technology cluster in North Rhine-Westphalia concentrates MEMS valve engineering expertise for precision dosing applications.
Japan
METI digital health initiatives accelerate Bluetooth-enabled insulin pump adoption through ambulatory diabetes management reimbursement expansion. PMDA consultation pathways for software-driven dosing algorithms compress development cycles for sensor-integrated systems. Tokyo's Kanto region anchors domestic manufacturing of rechargeable power cells for implantable devices.
Switzerland
Swissmedic expedited access pathways for breakthrough medical devices attract algorithm development for autonomous titration capabilities. Academic medical centers in Zurich and Basel pilot solid-state MEMS valve technology for sub-microliter dose accuracy. The country's precision engineering heritage concentrates biocompatibility materials expertise among specialized research clusters.
Netherlands
Dutch rehabilitation networks in Utrecht and Rotterdam expand intrathecal baclofen delivery for pediatric cerebral palsy spasticity management. EMA centralized procedures for high-risk implantable devices streamline EU-wide market access for manufacturers establishing European headquarters. The Eindhoven Brainport region anchors wireless telemetry module development for remote patient monitoring integration.
Global Smart Implantable Pumps Market Competitive Landscape
Top-tier vendors anchor high-acuity neurological and oncology segments, while mid-tier specialists occupy targeted chronic pain management niches. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with vertically integrated sensor-pump ecosystems, specialized intrathecal delivery platform developers, and emerging Bluetooth-enabled ambulatory diabetes players. Dominant competitive moves include strategic partnerships for cloud-based dose tracking platforms and selective geographic expansion into underpenetrated European rehabilitation networks.
Within the diversified medical technology tier, Medtronic and Abbott Laboratories exemplify vertically integrated players with captive supply chains spanning active implantable device components. Flowonix Medical occupies a specialist position in targeted intrathecal delivery platforms. These three anchors represent distinct competitive vectors: sensor-pump ecosystem control, precision neurological application focus, and chronic pain segment specialization respectively.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Flowonix Medical |
| Berlin Heart |
| Insulet Corporation |
| Tandem Diabetes Care |
| B. Braun Melsungen |
| Fresenius Kabi |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Captive supply of lithium-ion power cells and MEMS valve components anchors pricing power for established manufacturers with in-house production capabilities, while outsourced assembly operations in contract manufacturing geographies face margin compression from raw material volatility and certification overhead.
Pricing Analysis
The bundled-vs-unbundled service split separates device-only transactions from value-based contracts incorporating implantation, long-term management, and remote monitoring subscriptions. Three-tier pricing structure across premium sensor-integrated systems, standard programmable reservoirs, and economy basic pumps reflects algorithm sophistication and wireless capability tiers. Cost compression in the economy tier intensifies because hospital procurement departments consolidate vendor contracts under volume-based frameworks. Ambulatory surgery centers exhibit the highest price sensitivity due to short-duration therapy economics, while German sickness funds and Japanese social insurance programs demonstrate lowest sensitivity under bundled reimbursement pilots.
Supply Chain Analysis
Specialized biocompatibility engineering talent concentrates in Swiss precision research clusters, German MEMS fabrication facilities, and Japanese rechargeable cell manufacturing corridors. Raw material flows draw from concentrated Asian suppliers for lithium-ion cathodes, Taiwanese foundries for telemetry chipsets, and German specialty chemical producers for implant-grade polymers. Single-source vulnerability in battery cell sourcing exposes manufacturers to geopolitical friction and raw material price swings. Distribution runs through hospital procurement departments, specialized clinic networks, and GPO contracts with multi-site health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where closed-loop algorithm sophistication commands persistent premium positioning as oncology clinics and diabetes management programs shift demand toward sensor-integrated therapeutic systems.
For Market Incumbents: Deepen backward integration into MEMS valve fabrication and rechargeable power cell sourcing to defend against lithium-ion supply concentration risks. Fortify regulatory submission capabilities for EU AI Act algorithm classification to maintain clearance timeline advantages over emerging competitors. Prioritize hospital system partnerships that bundle device, implantation, and long-term management fees under value-based frameworks. For New Entrants and Emerging Players: Begin with pediatric intrathecal baclofen delivery for cerebral palsy spasticity in French and Italian rehabilitation networks, the most penetrable segment given established regulatory precedents and underpenetrated demand. Pursue Bluetooth-enabled insulin pump development for Japanese ambulatory diabetes programs where METI digital health initiatives accelerate reimbursement expansion. Anchor go-to-market strategy through academic medical center pilot partnerships that generate clinical evidence for subsequent commercial scale. For Investors and Strategic Acquirers: Roll-up economics work for specialized intrathecal delivery platform developers because EU MDR compliance acceleration compresses clearance timelines for established manufacturers while elevating barriers for de novo entrants. Five-to-ten year viability hinges on software-driven dosing algorithm capabilities rather than hardware manufacturing scale alone. Monitor FDA premarket approval timeline extensions for novel closed-loop systems as the primary inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates product clearance timelines through established notified body relationships. |
| Cloud-Based Dose Tracking Platform Development | Enables subscription revenue models for device manufacturers serving hospital networks. |
| Academic Medical Center Partnership Expansion | Generates clinical evidence for solid-state MEMS valve technology in Swiss and Dutch pilots. |
| Pediatric Neurostimulation Segment Entry | Captures underpenetrated demand for intrathecal baclofen in French rehabilitation networks. |
| Bluetooth-Enabled Insulin Pump Reimbursement Strategy | Secures coverage parity under Japanese social insurance program expansion. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and the Netherlands, with primary inputs from each market cluster combined with secondary validation. Interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at active implantable device manufacturers anchored demand-side and supply-side perspectives. Secondary sources incorporated FDA 510(k) and PMA filings, EMA centralized procedure documentation, hospital procurement databases, and ISO 14708 certification records. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulated market sizing across segments.
Granularity-level modeling disaggregated volume and value outputs by product type, technology tier, therapeutic application, and end-user setting throughout the forecast period. CAGRs derived from logistic diffusion curves for technology adoption, procedure volume growth rates in named clinical settings, and reimbursement expansion trajectories in priority national health systems. Industry-specific forecast inputs included intrathecal chemotherapy protocol expansion rates in German and United States oncology clinics, and METI digital health initiative implementation timelines in Japanese diabetes management.
Several conditions sit outside the modeled scope, including unanticipated FDA premarket approval pathway restructuring, EU AI Act algorithm classification tier reassignments, and lithium-ion supply chain disruption events beyond baseline geopolitical risk assumptions. Forecasts reflect documented assumptions regarding reimbursement parity establishment, regulatory clearance timeline stability, and hospital procurement consolidation patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Gamma Knife Market
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Animal Ultrasound Market
Medical Devices
India Clear Aligners Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Global Walking Assist Devices Market