
 Asia-Pacific Smart Medical Devices Market | 2026-2036
Asia-Pacific Smart Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Medical Devices Market Insights
Edge AI integration into portable diagnostics is reshaping how smart medical devices process biomarker data at the point of care. Abbott Laboratories leverages its freestyle Libre platform to anchor continuous glucose monitoring across Southeast Asian diabetes clinics. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. dominates patient monitoring hardware with manufacturing scale that sustains cost competitiveness across public hospital tenders.
Asia-Pacific smart medical devices comprise sensor-embedded instruments, wireless-enabled wearables, and cloud-connected diagnostic platforms that capture physiological data, transmit encrypted signals to clinical dashboards, and trigger algorithmic alerts for intervention. Bluetooth-enabled wearable devices lead volume deployment in fitness tracking and chronic disease management, while embedded devices command premium positioning in surgical assistance applications where real-time data fidelity determines clinical outcomes. Cloud computing infrastructure underpins telehealth scalability, though NFC-based authentication is gaining traction in Japan's rehabilitation center networks for secure patient-device pairing.
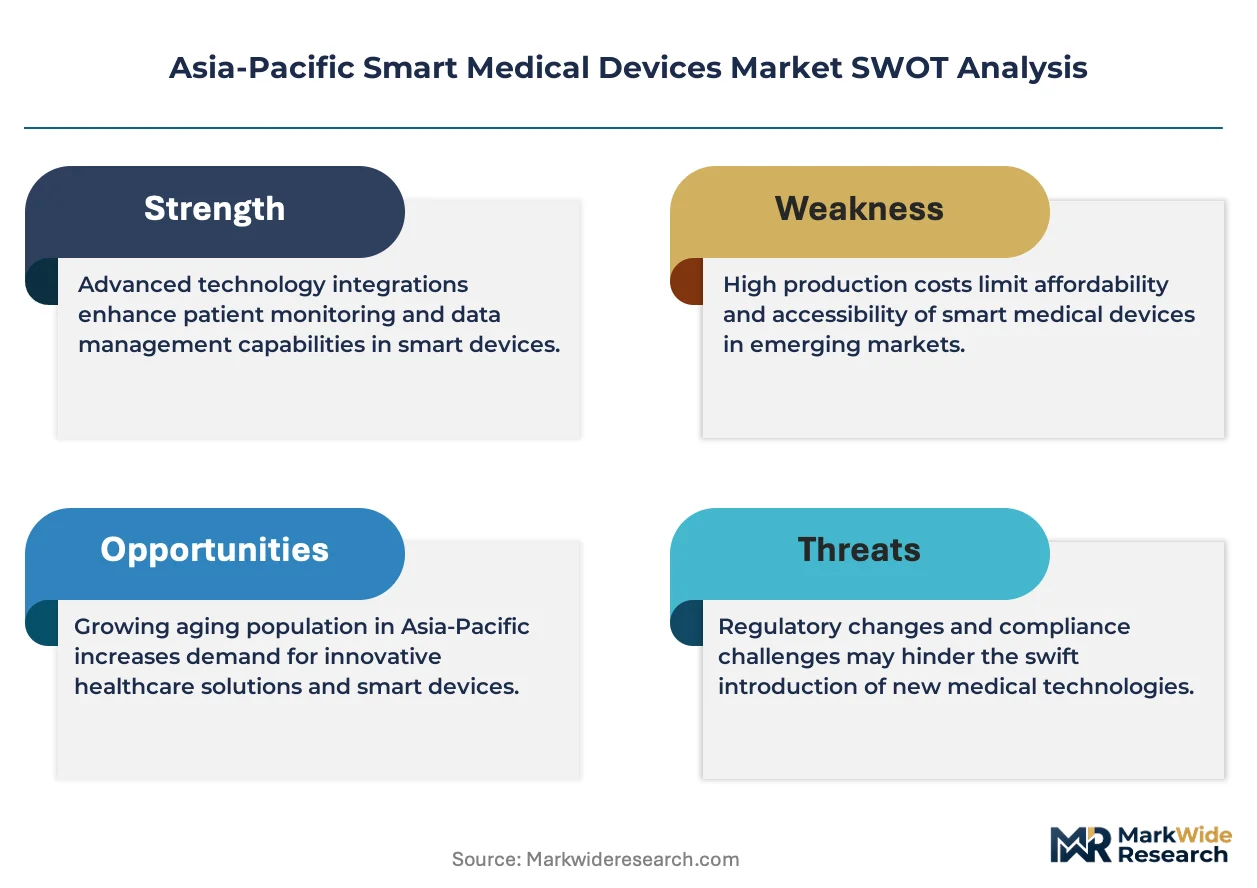
PMDA software-as-a-medical-device guidelines, India's CDSCO Medical Device Rules, and China's NMPA innovation approval pathways collectively determine product classification, clinical evidence requirements, and market access velocity across the region. These frameworks elevate compliance costs for foreign entrants but create structured pathways for domestic manufacturers to accelerate local registrations. Stakeholders must monitor evolving data localization mandates and cross-border health data flow restrictions that could fragment cloud architecture strategies.
Market Dynamics
Edge AI deployment into point-of-care diagnostics is compressing data processing latency and enabling real-time clinical decision support across Asia-Pacific hospital networks. This technology shift is restructuring competitive positioning around algorithmic performance rather than hardware specifications alone.
Growth Catalysts
- Japan's PMDA software-as-a-medical-device pathway:Accelerated clearance timelines for algorithm-based diagnostics reduce regulatory friction for AI-enabled platforms entering Japanese rehabilitation centers and diabetes clinics.
- Home care settings:Post-acute monitoring demand from aging populations in South Korea and Australia pulls wireless-enabled wearables into residential deployment, bypassing traditional hospital procurement channels.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable continuous biomarker transmission from rural patient locations to urban specialist hubs across Southeast Asian archipelagos.
Market Restraints
- Semiconductor foundry concentration:Taiwan-based fabrication capacity constraints create input volatility for sensor-embedded device manufacturers across the region.
- China's NMPA data localization mandates:Cross-border health data flow restrictions fragment cloud architecture strategies and elevate compliance costs for multinational platform operators.
- Reusable surgical instruments:Sterilization-validated alternatives threaten premium positioning of single-use connected surgical tools in cost-sensitive public hospital tenders.
Strategic Opportunities
- Vietnam's tier-two hospital networks:Underpenetrated provincial facilities present whitespace for integrated remote patient monitoring systems as infrastructure investment accelerates.
- India's CDSCO Medical Device Rules:Structured local registration pathways enable domestic manufacturers to accelerate product clearance relative to foreign entrants.
- NFC-Edge AI convergence:Secure patient-device pairing combined with on-chip inference creates differentiated positioning for rehabilitation applications in Japan's eldercare facilities.
Industry Challenges
- Embedded systems engineering talent:Scarce firmware developers with medical-grade validation experience constrain product iteration cycles for mid-cap device manufacturers.
- ISO 13485 certification timelines:Extended quality management system audits delay market entry for software-heavy platforms seeking multi-country registration.
- Legacy hospital IT integration:HL7 FHIR interoperability gaps force costly custom middleware development for cloud-connected diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Medical Devices Market |
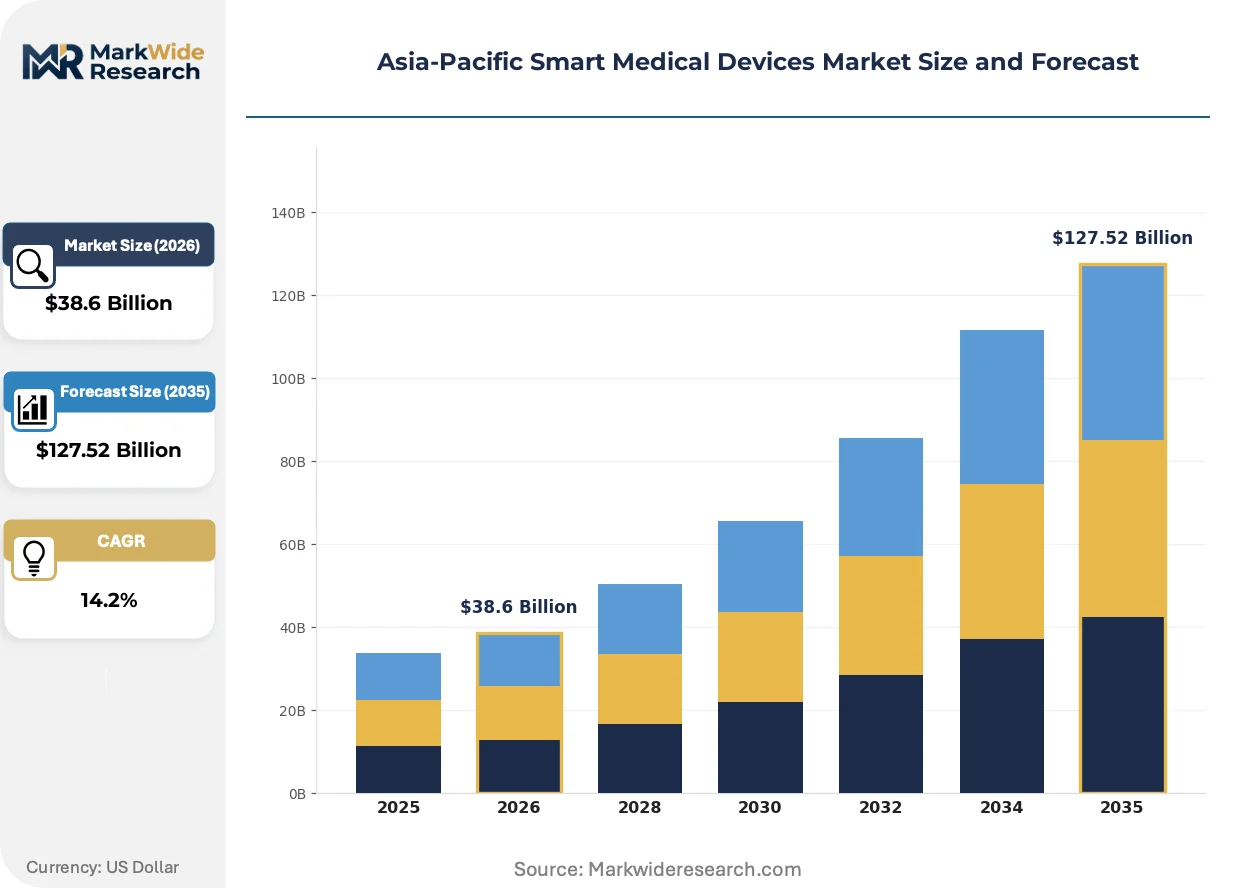
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Devices, Diagnostic Equipment, Embedded Devices Technology: Bluetooth, NFC, RFID, Cloud Computing End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Chronic Disease Management, Fitness Tracking, Telehealth, Surgical Assistance |
| Companies Covered | Abbott Laboratories, Medtronic PLC, Roche Holding AG, DexCom Inc, Masimo Corp, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Nipro Corporation, Olympus Corporation, Terumo Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Medical Devices Market Trends and Innovations
Computational migration from centralized servers to device-level processing is redefining where clinical intelligence resides. This architectural shift is compressing response times for critical alerts while raising new questions about validation protocols and liability frameworks.
Edge inference engines are digitizing biomarker interpretation at the point of collection. Cardiology wards in Singapore's public hospital clusters deploy portable ECG analyzers that process arrhythmia detection without cloud dependency. This capability is digitizing triage workflows and reducing specialist consultation bottlenecks in acute settings.
PMDA's 2023 software-as-a-medical-device guidance revision tightens algorithm change control requirements for machine learning-based diagnostics. Manufacturers must now submit predetermined modification protocols before market authorization, elevating documentation burdens but creating clarity for iterative AI improvement. Japanese diabetes management platforms face the steepest adaptation curve given their reliance on continuous glucose prediction models.
Hospital procurement departments across China's tier-one networks now bundle device acquisition with decade-long data analytics subscriptions. Equipment vendors must price hardware at marginal cost to secure recurring software revenue streams. This reconfiguration is most visible in Shanghai and Beijing where integrated delivery networks consolidate purchasing authority across multiple facilities.
Asia-Pacific Smart Medical Devices Market Segmentation
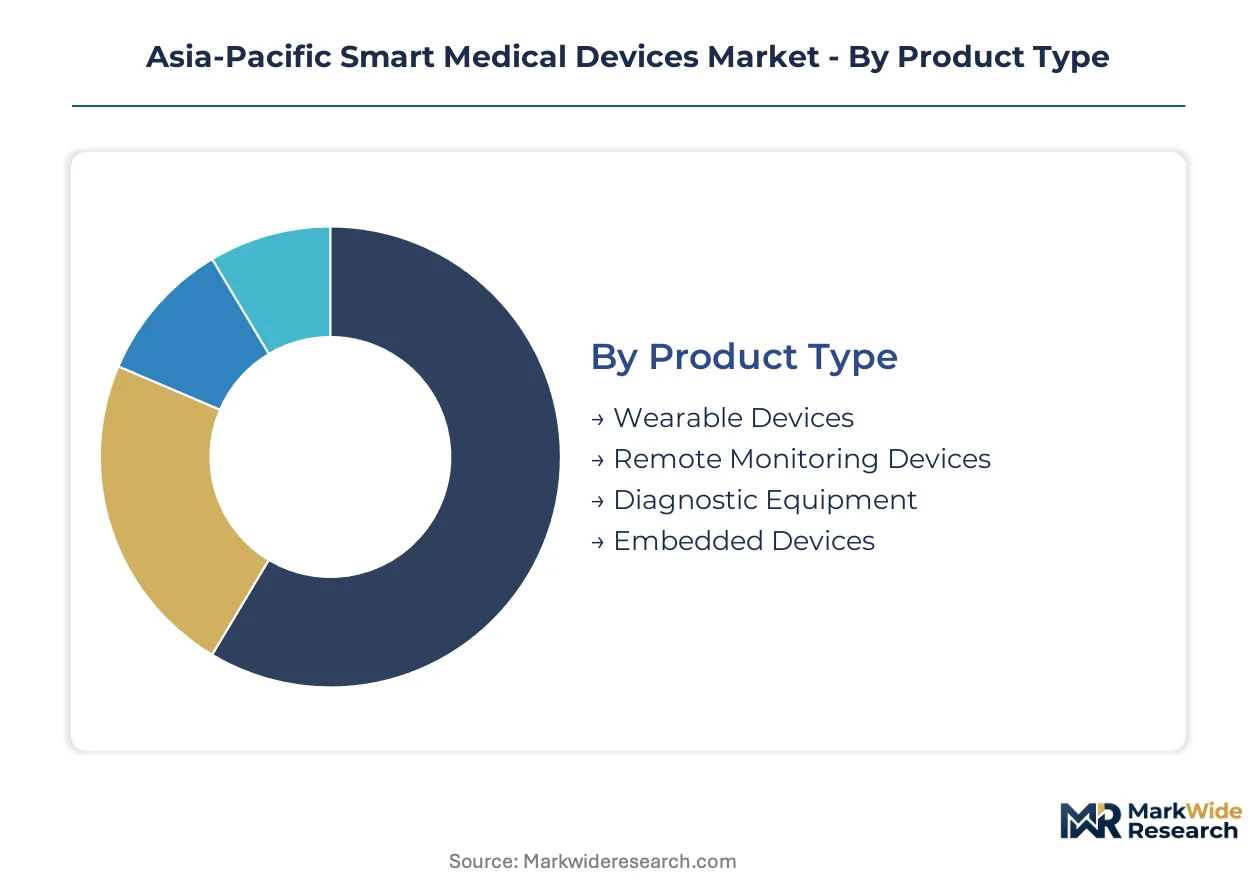
Segmentation in Asia-Pacific smart medical devices reveals how technology architecture, care delivery setting, and clinical application intersect to determine pricing power and regulatory pathway. Manufacturers must align product specifications with the dominant procurement channel in each segment to secure sustainable positioning.
Product Type:
Wearable devices anchor volume deployment across fitness tracking and chronic disease management, while embedded systems command premium positioning in surgical workflows where real-time data fidelity determines clinical outcomes.
- Wearable Devices:Bluetooth-enabled wristbands and patches transmit encrypted physiological signals to clinical dashboards for continuous glucose monitoring and cardiac arrhythmia detection. Demand concentrates in Australia's home care networks and South Korea's eldercare facilities, where aging populations pull monitoring outside traditional hospital channels.
- Remote Monitoring Devices:Cloud-connected hubs aggregate multi-parameter data streams from dispersed patient locations, enabling specialist oversight across Southeast Asian archipelagos where geographic fragmentation strains acute care access. China's tier-one hospital networks deploy these systems to manage post-discharge populations and reduce readmission penalties.
- Diagnostic Equipment:Portable analyzers with on-chip inference engines process biomarker interpretation at the point of collection, digitizing triage workflows in Singapore's public hospital clusters.
- Embedded Devices:Sensor-integrated surgical instruments provide real-time tissue feedback and navigation assistance, with sterility-validated single-use variants competing against reusable alternatives in cost-sensitive public tenders.
The dominant share belongs to wearable devices, while embedded devices are closing the gap fastest through premium pricing in robotic-assisted surgery applications.
Technology:
Wireless protocol selection determines power consumption, transmission range, and security architecture, with trade-offs shaping deployment feasibility across rural versus urban care settings.
- Bluetooth:Low Energy 5.3 specifications extend operational range while reducing power draw, enabling continuous biomarker transmission from rural patient locations to urban specialist hubs across Indonesian islands and Philippine provinces.
- Cloud Computing:Centralized data lakes underpin telehealth scalability and population health analytics, though China's NMPA data localization mandates fragment architecture strategies for multinational operators.
- NFC:Secure patient-device pairing protocols gain traction in Japan's rehabilitation center networks, where eldercare facilities prioritize authentication simplicity over transmission range.
- RFID:Asset tracking and inventory management applications dominate hospital supply chain automation, with passive tags reducing equipment loss rates in high-throughput emergency departments.
Bluetooth holds the installed base advantage, though NFC is expanding most quickly through eldercare-specific authentication requirements.
End User:
Procurement authority and reimbursement pathways diverge sharply across institutional settings, with home care bypassing traditional hospital purchasing committees entirely.
- Home Care:Post-acute monitoring demand from aging populations in South Korea, Australia, and Japan pulls wireless-enabled wearables into residential deployment, creating direct-to-consumer revenue streams outside tender-based procurement.
- Hospitals:China's tier-one networks consolidate purchasing authority across integrated delivery networks, bundling device acquisition with decade-long data analytics subscriptions that reconfigure vendor economics toward recurring software revenue.
- Clinics:Smaller footprint diagnostics and portable monitoring tools serve outpatient chronic disease management, with India's CDSCO registration pathways enabling domestic manufacturers to accelerate clearance relative to foreign entrants.
- Rehabilitation Centers:Japan's PMDA software-as-a-medical-device guidelines accelerate clearance timelines for algorithm-based diagnostics in physical therapy and mobility recovery applications.
Hospitals retain the largest revenue share, while home care is gaining share fastest through demographic tailwinds and reimbursement shifts toward preventive monitoring.
Application:
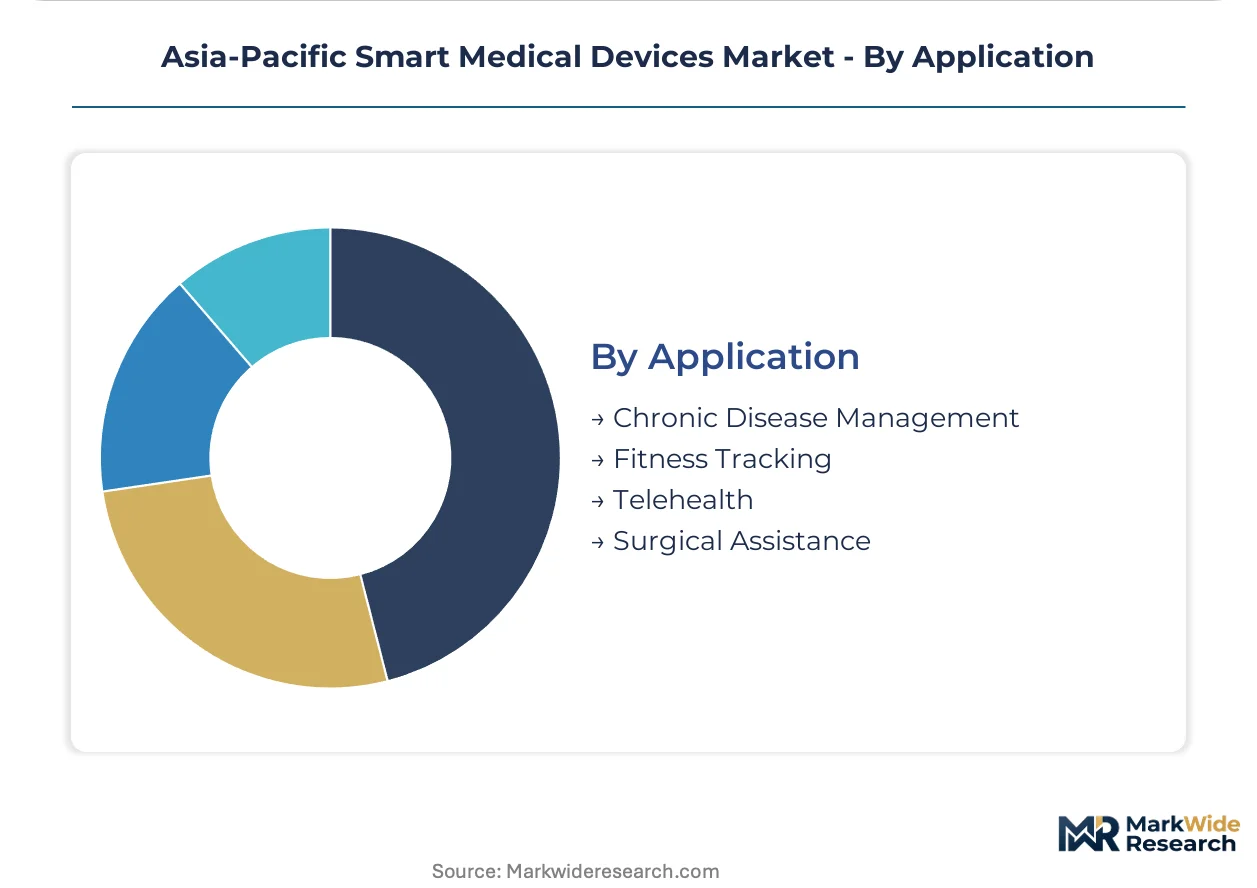
Clinical use case determines regulatory classification, evidence requirements, and pricing elasticity, with chronic disease management offering recurring revenue streams against surgical assistance's capital equipment model.
- Chronic Disease Management:Continuous glucose monitoring and hypertension tracking platforms generate subscription-based revenue through sensor replacement cycles, with Abbott Laboratories' Freestyle Libre platform anchoring diabetes clinic adoption across Southeast Asia.
- Surgical Assistance:Real-time navigation and tissue characterization tools command premium hardware pricing, though sterilization-validated reusable alternatives threaten single-use connected tools in public hospital tenders.
- Telehealth:Cloud-connected diagnostic platforms enable remote specialist consultation, with HL7 FHIR interoperability gaps forcing costly custom middleware development for legacy hospital IT integration.
- Fitness Tracking:Consumer-grade wearables face commoditization pressure, with differentiation shifting toward medical-grade validation for insurance reimbursement eligibility.
Chronic disease management leads by revenue volume, though surgical assistance shows the steepest expansion trajectory through robotic platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in China's tier-one cities drive premium equipment demand, while aging demographics in Japan and South Korea pull adoption toward home-based monitoring solutions. Vietnam's provincial hospital networks and India's domestic manufacturing incentives create secondary growth vectors across the region.
China
Integrated delivery networks in Shanghai and Beijing bundle device procurement with decade-long data analytics subscriptions, reconfiguring vendor economics toward recurring software revenue. NMPA data localization mandates fragment cloud architecture strategies for multinational operators. The Yangtze River Delta cluster anchors manufacturing scale for patient monitoring hardware serving public hospital tenders.
Japan
PMDA software-as-a-medical-device guidelines accelerate clearance timelines for algorithm-based diagnostics entering rehabilitation centers and diabetes clinics. Elder populations in Kanto and Kansai regions generate sustained demand for NFC-enabled patient-device pairing in eldercare facilities. Tokyo's hospital procurement departments prioritize embedded surgical instruments with real-time tissue feedback capabilities.
India
CDSCO Medical Device Rules enable domestic manufacturers to accelerate product clearance relative to foreign entrants, particularly for clinic-deployed portable diagnostics. Maharashtra and Karnataka host emerging firmware development clusters addressing embedded systems engineering scarcity. Tier-two city hospitals in Gujarat and Tamil Nadu present whitespace for remote patient monitoring system deployment.
South Korea
Post-acute monitoring demand from aging populations pulls wireless-enabled wearables into residential deployment, bypassing traditional hospital procurement channels. MFDS regulatory pathways align with international standards to streamline multi-country registration for export-oriented manufacturers. Seoul Capital Area medical centers pioneer edge AI integration into cardiology wards for arrhythmia detection without cloud dependency.
Vietnam
Underpenetrated tier-two hospital networks present whitespace for integrated remote patient monitoring systems as infrastructure investment accelerates. Provincial facilities in the Mekong Delta and Central Highlands lack specialist coverage, creating demand for telehealth-connected diagnostic platforms. Ho Chi Minh City and Hanoi anchor distribution channels for imported device components.
Asia-Pacific Smart Medical Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement-heavy hospital segments and direct-to-consumer home care channels. The vendor base organizes around three strategic archetypes: multinational platform operators with software-subscription economics, regional hardware specialists with manufacturing scale advantages, and domestic registrants exploiting accelerated local clearance pathways. Competitive moves concentrate on backward integration into sensor fabrication and strategic partnerships with cloud infrastructure providers.
Within the multinational platform tier, Abbott Laboratories and Medtronic PLC exemplify archetypes combining device hardware with recurring software revenue models. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies a position among Asia-Pacific-based hardware specialists leveraging manufacturing scale for public tender competitiveness. These three anchors illustrate how competitive positioning diverges between algorithmic performance differentiation and cost-driven procurement channel control.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic PLC |
| Roche Holding AG |
| DexCom Inc |
| Masimo Corp |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Nipro Corporation |
| Olympus Corporation |
| Terumo Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwan-based semiconductor fabrication concentration concentrates sensor-embedded device input costs, directing margin pools toward downstream software-subscription vendors in China's tier-one hospital networks and Japan's rehabilitation centers. This upstream bottleneck elevates procurement leverage for foundry-dependent hardware manufacturers while compressing margins for mid-cap device assemblers lacking captive silicon supply.
Pricing Analysis
Cost-plus contracts with semiconductor wafer indexation dominate component procurement for patient monitoring hardware manufacturers serving public hospital tenders across Southeast Asia. Three-tier pricing structure across premium embedded surgical systems, standard remote monitoring platforms, and economy wearable devices reflects ISO 13485 certification grade and after-sales service bundling. Pricing pressure stems from China's NMPA-mandated data localization compliance costs elevating total cost of ownership for cloud-connected diagnostics. Public hospital procurement committees exhibit highest price sensitivity, while integrated delivery networks in Shanghai and Beijing prioritize algorithmic performance over unit cost.
Supply Chain Analysis
Tariff exposure between Taiwan and mainland China dominates supply chain risk planning for sensor-embedded device manufacturers across the Asia-Pacific region. Component sourcing draws from Taiwan for advanced semiconductors, South Korea for display modules, and Japan for precision sensors. Single-source vulnerability concentrates in 12-inch wafer fabrication for edge AI inference chips. Distribution runs through tier-one city medical equipment distributors in China, direct hospital contracts in Japan, and clinic-focused channel partners in India and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in home care settings as aging demographics in South Korea, Australia, and Japan bypass traditional hospital procurement channels, creating niche positioning for direct-to-consumer wearable platforms outside tender-based purchasing systems.
For Market Incumbents: Harden cloud architecture resilience against NMPA data localization mandates through in-country server deployment partnerships. Deepen backward integration into sensor fabrication to reduce Taiwan foundry exposure. Prioritize ISO 13485 certification maintenance across multi-country registrations to defend against CDSCO-accelerated domestic competitors in India. For New Entrants and Emerging Players: Vietnam's tier-two provincial hospital networks present whitespace for integrated remote patient monitoring systems where specialist coverage gaps create telehealth demand. India's CDSCO registration pathways enable faster product clearance relative to foreign entrants for clinic-deployed portable diagnostics. Target NFC-Edge AI convergence applications in Japan's eldercare facilities as the most penetrable rehabilitation segment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-a-medical-device platforms as algorithm development scales across patient populations without proportional hardware manufacturing expansion. Long-term viability favors acquisition targets combining regulatory clearance velocity with recurring revenue models. Monitor PMDA software-as-a-medical-device guideline revisions as the primary inflection signal for AI-enabled diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures decade-long data analytics subscription bundles in China's tier-one integrated delivery networks. |
| Software Companion Development | Enables PMDA software-as-a-medical-device pathway acceleration for algorithm-based diagnostics in Japan. |
| CE Marking Pathway | Facilitates MFDS-aligned multi-country registration for South Korea export-oriented manufacturers. |
| Reimbursement Strategy | Unlocks insurance eligibility for medical-grade wearables in Australia's home care networks. |
| Backward Integration into Sensors | Reduces Taiwan foundry dependency for patient monitoring hardware serving public tenders. |
Research Methodology
The analysis maps wearable devices, remote monitoring systems, diagnostic equipment, and embedded surgical instruments, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads across the Asia-Pacific region. Primary interview findings triangulate against secondary sources including NMPA registration databases, PMDA approval records, CDSCO device listings, and hospital procurement contract disclosures. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder validation.
Assumptions held fixed include current regulatory pathway timelines, existing reimbursement frameworks, and prevailing data localization mandates, while semiconductor supply constraints and algorithm validation protocols were modeled as scenario variables. Segmentation dimensions span product architecture, wireless protocol selection, care delivery setting, and clinical application intensity. CAGRs derive from installed base expansion rates and replacement cycle analysis across chronic disease management and surgical assistance platforms.
Practitioners should monitor NMPA data localization enforcement intensity, PMDA algorithm change control protocol revisions, and Taiwan foundry capacity allocation shifts for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Global Electronic Drug Delivery Systems Market