
 Large Volume Parenteral (LVP) Market | 2026-2036
Large Volume Parenteral (LVP) Market Size, Share, and Industry Trends Forecast 2026-2036
Large Volume Parenteral (LVP) Market Intelligence
North American contract manufacturing is consolidating as hospitals seek dual-source supply security for sterile electrolyte and nutritional solutions. Baxter International leverages its integrated IV bag and solution production network across multiple FDA-registered sites. Fresenius Kabi anchors European supply through dedicated parenteral lines serving hospital group purchasing organizations. ICU Medical competes on closed-system transfer device integration with its infusion delivery portfolio.
Large Volume Parenterals are sterile aqueous solutions administered in volumes exceeding 100 milliliters, typically containing electrolytes, carbohydrates, or amino acids for fluid resuscitation and nutritional support; manufacturing requires aseptic filling in isolator-grade cleanrooms with terminal sterilization or filtration validation. IV Solutions dominate product type revenue due to perioperative and sepsis protocol standardization across emergency departments. Nutritional Solutions represent the fastest-expanding segment as home healthcare providers adopt peripheral parenteral nutrition for chronic gastrointestinal failure patients. Bag packaging controls the highest margin pool among packaging types because film and port-barrier innovation reduces particulate contamination liability.
FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals under 21 CFR Parts 210 and 211, mandating media-fill validation and environmental monitoring for LVP aseptic processing. The EU MDR and REACH frameworks govern plasticizer migration from PVC and non-PVC infusion containers into parenteral solutions. Stakeholders must monitor polymer material qualification timelines and sterility test method modernization as regulatory agencies align on particulate detection thresholds.
Market Dynamics
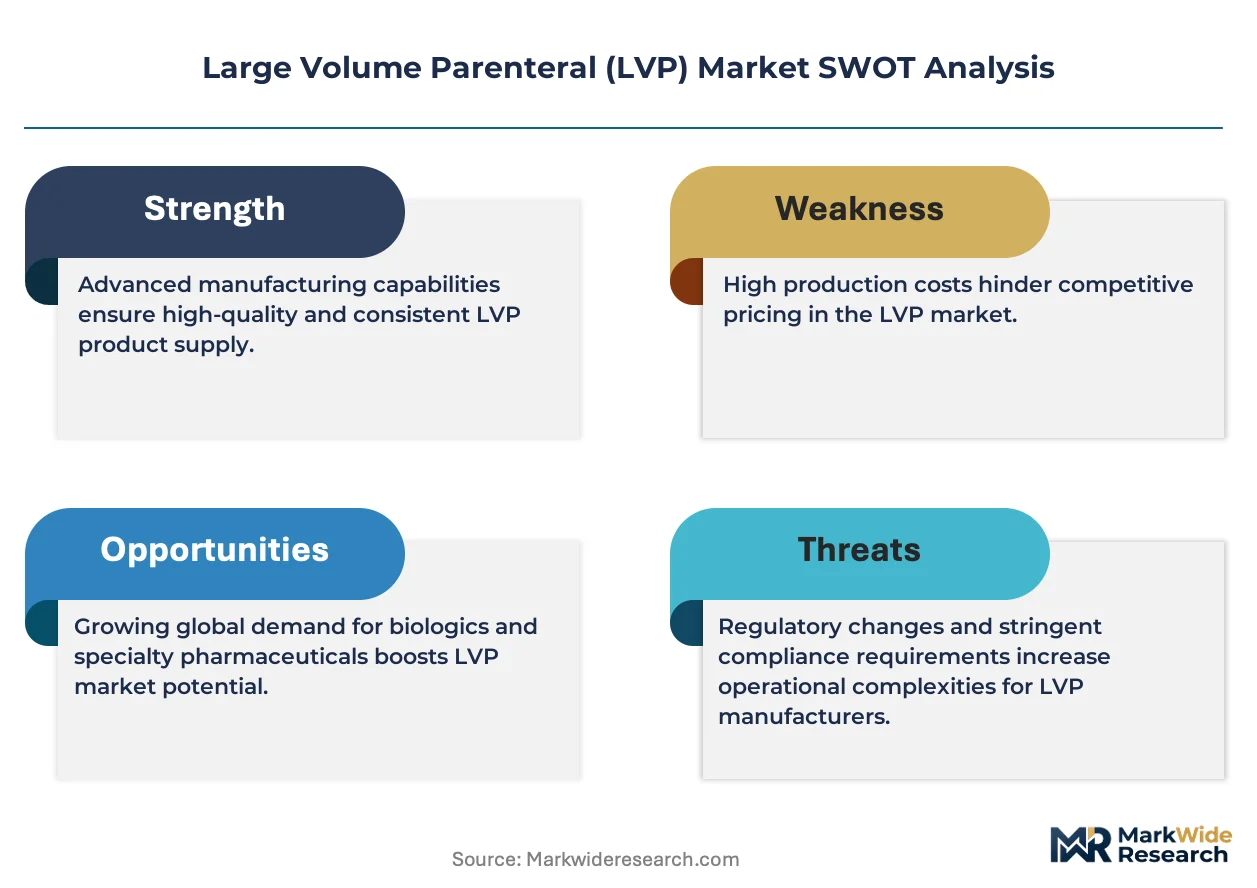
Hospital procurement groups are consolidating supplier panels for sterile electrolyte and nutritional solutions, forcing manufacturers to prove dual-source redundancy across FDA-registered facilities while absorbing escalating polymer qualification costs.
Growth Catalysts
- US FDA sterility assurance mandates:The agency's tightened 21 CFR Part 211 enforcement around media-fill validation and environmental monitoring is accelerating facility upgrades among contract manufacturers.
- Home parenteral nutrition expansion:Peripheral parenteral nutrition protocols for chronic gastrointestinal failure patients are extending therapy duration outside acute care settings.
- German hospital group purchasing centralization:Bundled tendering for IV fluid security by university hospital networks is concentrating procurement volume among qualified suppliers.
Market Restraints
- Medical-grade polymer supply concentration:Film resin for non-PVC infusion containers depends on a narrow supplier base in Western Europe, creating input cost volatility.
- EMA plasticizer migration thresholds:REACH-compliant DEHP-free material qualification timelines extend 18-24 months, freezing formulation changes.
- Terminal sterilization capacity scarcity:Steam sterilizer availability for 1-liter+ flexible containers constrains batch throughput at existing facilities.
Strategic Opportunities
- China's intravenous fluid security framework:National health preparedness policies are mandating domestic sterile solution stockpiles, opening local production partnerships.
- Closed-system transfer device convergence:Integration of needle-free connectors with pre-filled bag systems reduces contamination risk during compounding.
- India's PLI scheme for medical devices:Production-linked incentives for domestic parenteral manufacturing equipment are lowering capital barriers for greenfield sites.
Industry Challenges
- Aseptic processing technician scarcity:Isolator-grade cleanroom operation and environmental monitoring expertise commands premium wages in competitive labor markets.
- Legacy ERP integration with track-and-trace:Serialization requirements for unit-level bag identification strain decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Volume Parenteral (LVP) Market |
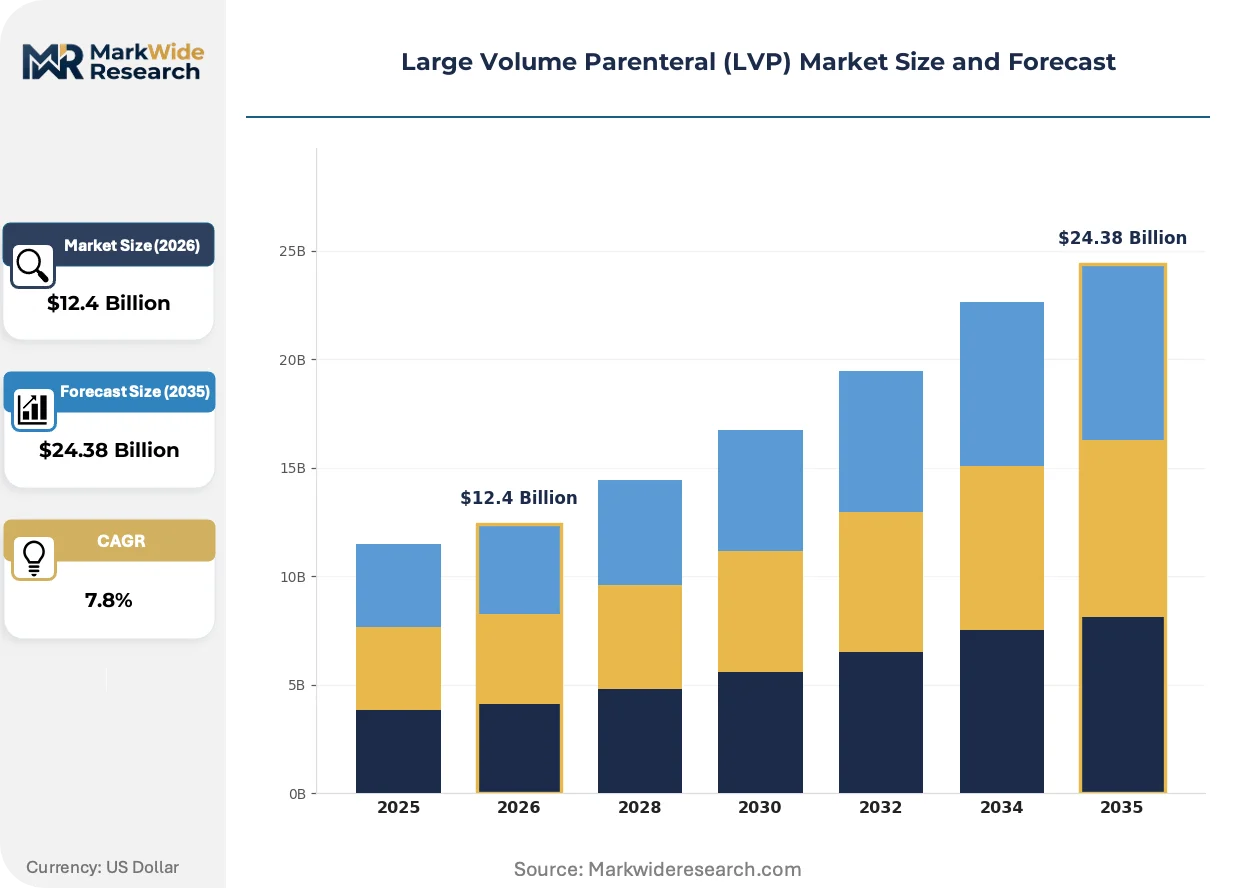
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Solutions, Nutritional Solutions, Antibiotics, Electrolytes Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Epidural End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Packaging Type: Bottles, Bags, Vials, Pre-filled Syringes |
| Companies Covered | Pfizer, Kelun Pharma, Baxter International, ICU Medical, Teva Pharmaceutical Industries, Fresenius Kabi, Otsuka Pharmaceutical, Terumo Corporation, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Volume Parenteral (LVP) Market Strategic Shifts & Innovations
Ready-to-use infusion systems are displacing traditional compounding workflows across emergency and perioperative settings, compressing preparation time and contamination exposure while reshaping supplier value propositions.
Multi-layer coextruded films for non-PVC infusion containers are consolidating material qualification pathways across pharmaceutical packaging. Hospital systems in the United States and Germany are adopting these barrier structures for electrolyte and nutritional solutions at accelerated procurement cycles. This consolidation is compressing legacy PVC container market share and forcing polymer suppliers to unify film specifications across regional pharmacopeias.
EMA's MDR framework for plasticizer migration testing is tightening extractables protocols for infusion container materials. Manufacturers must now submit comprehensive chemical characterization data for novel film formulations before market authorization. Nutritional solutions with lipid emulsions face the steepest compliance burden, as fat-soluble compound leaching risks trigger enhanced scrutiny from notified bodies.
Hospital pharmacy procurement is centralizing sterile solution purchasing through integrated delivery networks, displacing fragmented distributor relationships. Group purchasing organizations in the United States are mandating dual-source contracts with documented contingency production sites. This concentration is most visible among academic medical centers consolidating annual IV fluid spend under single-master agreements with penalty clauses for supply interruption.
Large Volume Parenteral (LVP) Market Segmentation
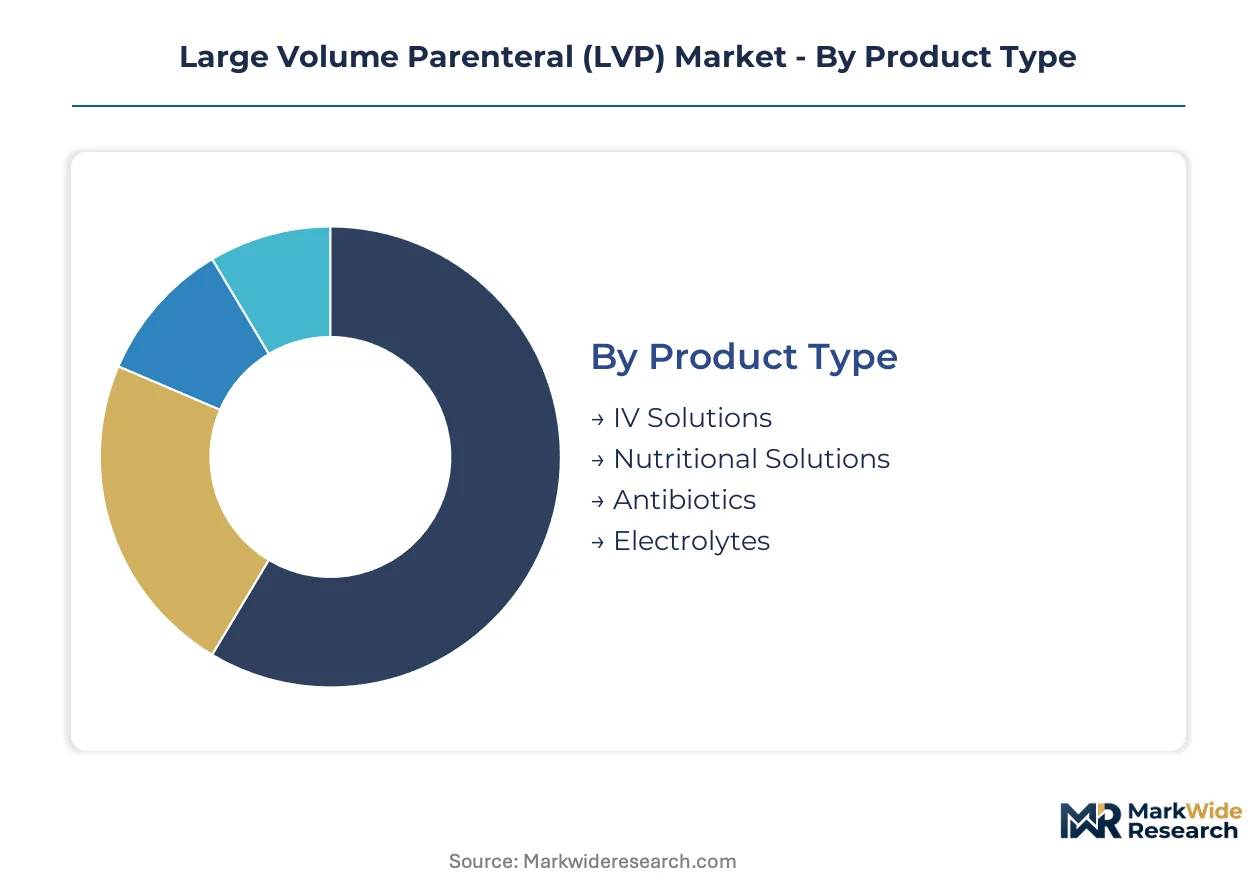
Product differentiation in large volume parenterals determines sterility assurance levels, compounding workflows, and procurement contract structures across acute and ambulatory settings. Each segmentation dimension carries distinct margin profiles and regulatory qualification burdens that reshape supplier competitive position.
Product Type:
Upgrade cycles in hospital formulary management are accelerating as perioperative protocols and sepsis bundles standardize fluid resuscitation requirements across emergency departments.
- IV Solutions:Sterile aqueous formulations containing electrolytes or carbohydrates for fluid resuscitation and maintenance therapy. Demand concentrates in United States academic medical centers where sepsis protocol standardization drives bulk procurement of lactated Ringer's and normal saline; FDA sterility assurance mandates under 21 CFR Part 211 intensify supplier qualification requirements.
- Nutritional Solutions:Parenteral nutrition formulations combining amino acids, dextrose, and lipid emulsions for patients with gastrointestinal failure. German university hospital networks are expanding peripheral parenteral nutrition protocols for chronic patients transitioning to home care; EMA plasticizer migration thresholds under REACH extend material qualification timelines for lipid-contact containers.
- Antibiotics:Large-volume sterile antibiotic preparations for hospital-administered antimicrobial therapy.
- Electrolytes:Concentrated electrolyte solutions for correction of metabolic imbalances in acute care.
Volume placements concentrate in IV Solutions; the faster expansion belongs to Nutritional Solutions.
Delivery Mode:
Application-specific delivery requirements determine container compatibility, flow rate precision, and compounding infrastructure investment across care settings.
- Intravenous:Direct administration into venous circulation via peripheral or central lines, requiring aseptic technique and flow-controlled infusion pumps. United States hospital group purchasing organizations mandate closed-system transfer device integration for all intravenous large volume parenterals; this delivery mode commands the highest sterility assurance investment per dose.
- Subcutaneous:Administration into subcutaneous tissue for hydration or medication delivery, typically at lower volumes than intravenous. Home healthcare providers in Germany are adopting subcutaneous infusion protocols for palliative hydration; reduced compounding complexity lowers barrier to ambulatory adoption.
- Intramuscular:Depot injection of antimicrobial or nutritional formulations into muscle tissue.
- Epidural:Delivery into epidural space for regional anesthesia and analgesia in surgical and obstetric settings.
Intravenous delivery anchors procurement volume; subcutaneous protocols are climbing the fastest as home care expands.
End User:
Customer-type concentration is reshaping distribution economics as integrated delivery networks consolidate sterile solution purchasing under single-master agreements.
- Hospitals:Acute care facilities performing emergency resuscitation, perioperative fluid management, and critical care nutrition. United States academic medical centers are consolidating annual IV fluid spend under dual-source contracts with documented contingency production sites; group purchasing organization centralization compresses supplier margins while demanding redundant FDA-registered manufacturing capacity.
- Home Healthcare:Ambulatory providers managing long-term parenteral nutrition and hydration for chronic gastrointestinal failure patients. China's intravenous fluid security framework is mandating domestic sterile solution stockpiles that extend to home infusion services; national health preparedness policies open local production partnerships for nutritional solution supply.
- Clinics:Outpatient facilities administering hydration and antimicrobial therapy.
- Rehabilitation Centers:Post-acute facilities managing nutritional support during functional recovery.
Hospitals dominate current volume; home healthcare shows the steepest expansion trajectory as peripheral parenteral nutrition protocols extend therapy duration outside acute settings.
Packaging Type:
Margin concentration in packaging innovation reflects film barrier development and particulate contamination liability reduction across polymer qualification pathways.
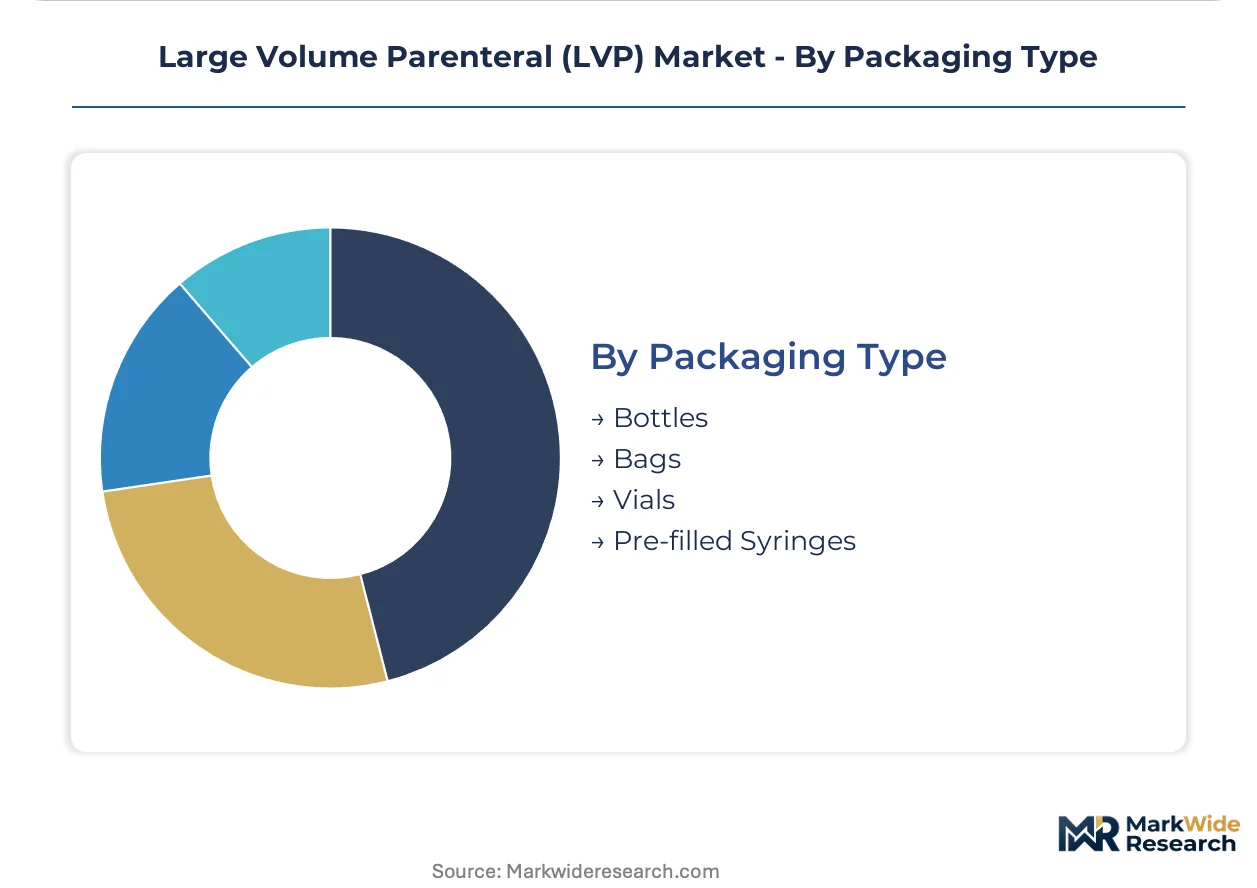
- Bags:Flexible film containers for electrolyte and nutritional solutions, available in PVC and non-PVC multi-layer coextruded formats. United States and German hospital systems are accelerating procurement of non-PVC barrier structures; EMA MDR extractables protocols and FDA material qualification requirements compress legacy PVC container market share while consolidating film specifications across regional pharmacopeias.
- Bottles:Rigid polymer or glass containers for terminal sterilization of large-volume solutions. Terminal sterilization capacity scarcity for 1-liter+ flexible containers constrains batch throughput; bottles retain position in markets with limited steam sterilizer infrastructure.
- Vials:Small-volume glass or polymer containers for antibiotic and concentrated electrolyte presentations.
- Pre-filled Syringes:Unit-dose presentations for emergency and ambulatory settings requiring minimal compounding.
Bags control the highest margin pool; pre-filled syringes are gaining share fastest as ready-to-use systems displace traditional compounding workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer resin production in Western Europe and medical-grade film manufacturing in East Asia anchor the LVP supply base. Hospital procurement centralization and national health security frameworks are reshaping demand geography across three continents.
United States
Academic medical centers are consolidating annual IV fluid spend under dual-source contracts with documented contingency production sites. FDA sterility assurance mandates under 21 CFR Part 211 intensify supplier qualification requirements for media-fill validation. The Boston-Cambridge corridor hosts contract manufacturing clusters serving hospital group purchasing organizations with redundant FDA-registered capacity.
Germany
University hospital networks are expanding bundled tendering for IV fluid security, concentrating procurement volume among qualified suppliers. EMA plasticizer migration thresholds under REACH extend DEHP-free material qualification timelines to 18-24 months. The Rhine-Ruhr industrial basin anchors European parenteral manufacturing with dedicated lines serving hospital group purchasing organizations.
China
National health preparedness policies are mandating domestic sterile solution stockpiles for intravenous fluid security. NMPA alignment with international GMP standards accelerates facility upgrades among local manufacturers. The Yangtze River Delta hosts production partnerships between multinational suppliers and domestic pharmaceutical groups targeting hospital and home infusion services.
India
Production-linked incentives under the PLI scheme for medical devices are lowering capital barriers for greenfield parenteral manufacturing sites. CDSCO sterility assurance requirements are tightening environmental monitoring protocols for aseptic processing facilities. The Mumbai-Pune pharmaceutical belt is attracting contract manufacturing investments targeting export markets and domestic hospital procurement.
Japan
Peripheral parenteral nutrition protocols for chronic gastrointestinal failure patients are extending therapy duration outside acute care settings. PMDA quality management system requirements govern aseptic filling validation for multi-chamber nutritional bags. The Kansai region maintains concentrated parenteral manufacturing infrastructure serving domestic hospital networks and regional export demand.
Large Volume Parenteral (LVP) Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and regulatory qualification depth. The market structure tiers between integrated pharmaceutical conglomerates with captive parenteral divisions and specialized infusion therapy suppliers. Three archetypes dominate: diversified healthcare conglomerates with sterile manufacturing networks, dedicated parenteral and nutrition specialists, and regional pharmaceutical groups with domestic market focus. Competitive moves concentrate on dual-source contract positioning and polymer material qualification acceleration.
Among diversified healthcare conglomerates, Baxter International and Fresenius Kabi exemplify the integrated manufacturing archetype with multi-site sterile production networks. ICU Medical occupies a position within the infusion delivery systems tier, representing convergence between container technology and closed-system transfer devices. Kelun Pharma anchors the regional pharmaceutical group archetype, exemplifying domestic market concentration with expanding regulatory qualification scope.
| Leading Market Players |
|---|
| Pfizer |
| Kelun Pharma |
| Baxter International |
| ICU Medical |
| Teva Pharmaceutical Industries |
| Fresenius Kabi |
| Otsuka Pharmaceutical |
| Terumo Corporation |
| B. Braun |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap polymer specialists in Western Europe anchor film resin supply for non-PVC infusion containers, translating narrow feedstock control into disciplined pricing power across multi-layer coextruded bag contracts. Their concentrated ownership structure limits speculative capacity expansion, reinforcing stable term pricing for hospital group purchasing organizations while compressing margin flexibility for downstream compounders.
Pricing Analysis
Warranty and validation-service bundling separates premium-tier suppliers from commodity competitors in LVP procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA registration tier, isolator-grade cleanroom certification, and geographic redundancy of manufacturing sites. Cost compression in standard-tier IV solutions intensifies because German university hospital networks are consolidating annual fluid spend under penalty-clad master agreements. Academic medical centers in the United States exhibit lowest price sensitivity due to sepsis protocol standardization mandating dual-source supply security.
Supply Chain Analysis
Medical-grade film resin supply rests on German and Belgian specialty chemical producers, with secondary concentration among Japanese polymer compounders serving Asian markets. Multi-layer coextruded ethylene-vinyl acetate films, DEHP-free plasticizers, and sterilization-grade port-barrier adhesives constitute critical input dependencies. Single-source vulnerability in terminal sterilization capacity for 1-liter+ flexible containers constrains batch throughput during demand surges. Distribution runs through hospital group purchasing organizations and integrated delivery networks consolidating sterile solution procurement under single-master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-use infusion systems are displacing traditional compounding workflows across emergency departments, compressing preparation time while elevating sterility assurance requirements for bag-and-connector integrated platforms.
For Market Incumbents: Anchor dual-source contract positioning by documenting redundant FDA-registered manufacturing capacity across multiple sites, insulating against hospital procurement consolidation. Accelerate polymer material qualification timelines to preempt REACH-compliant DEHP-free formulation mandates from EMA. Deepen backward integration into multi-layer film coextrusion to capture margin pool migrating from legacy PVC container suppliers.
For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for greenfield parenteral manufacturing sites targeting export markets and domestic hospital procurement. Peripheral parenteral nutrition for home healthcare represents the most penetrable segment, with chronic gastrointestinal failure patients extending therapy duration outside acute settings. Pursue production partnerships with established polymer suppliers to bypass 18-24 month material qualification barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with isolator-grade cleanroom infrastructure in the Boston-Cambridge corridor and Rhine-Ruhr industrial basin. Long-term viability hinges on regulatory qualification depth rather than volume scale alone. Watch FDA sterility assurance enforcement intensity as the inflection signal for facility upgrade capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Manufacturing Certification | FDA-registered redundant sites satisfy hospital GPO contingency requirements under 21 CFR Part 211. |
| Non-PVC Film Material Qualification | REACH-compliant DEHP-free pathways preempt EMA plasticizer migration threshold enforcement. |
| Closed-System Transfer Device Integration | Needle-free connector convergence reduces contamination liability in perioperative settings. |
| Home Infusion Service Partnership | Peripheral parenteral nutrition protocols extend therapy duration outside academic medical centers. |
| Terminal Sterilization Capacity Expansion | Steam sterilizer availability for 1-liter+ flexible containers alleviates batch throughput constraints. |
Research Approach
Independent corroboration across hospital procurement managers, GPO contracts specialists, aseptic processing engineers, and regulatory affairs leads underwrites the qualitative findings in this study. Primary interviews with formulary directors and biomedical engineers at academic medical centers in the United States and Germany were cross-referenced against FDA 483 observation databases, EMA marketing authorization submissions, and hospital group purchasing organization contract awards. Bottom-up volume estimates from polymer resin consumption and top-down triangulation against sterile solution production capacity reinforce segmentation outputs.
Rate-of-change decomposition across product type, delivery mode, end user, and packaging format dimensions structures the analytical framework over the projection horizon. CAGRs were derived from modeled volume placements by segment, incorporating FDA sterility assurance mandate compliance timelines and EMA material qualification pathway durations as industry-specific forecast inputs. The modeling period captures transition dynamics between legacy PVC containers and multi-layer coextruded non-PVC alternatives.
The model assumes a particular technology adoption path; alternative pathways for closed-system transfer device standardization would alter the outlook. Forecasts reflect assumptions around regulatory enforcement intensity and polymer supplier consolidation. A small set of triggers—FDA media-fill validation citation rates, REACH DEHP-free material approval timelines, and hospital GPO contract consolidation velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Leuprolide Acetate Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Prostaglandin Analogs Market