
 Solar Surgical Light Market | 2026-2036
Solar Surgical Light Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Surgical Light Market Analysis
Aftermarket service revenue is reconfiguring margin distribution across the Solar Surgical Light value chain. STERIS plc leverages its sterile processing installed base to cross-sell solar surgical lighting maintenance contracts. KONINKLIJKE PHILIPS N.V. anchors its position through proprietary LED driver architectures that reduce field failure rates. Getinge AB competes by bundling solar surgical lights with integrated operating room workflow systems.
Solar surgical lights combine photovoltaic capture modules with high-intensity LED arrays and battery storage to deliver shadowless illumination independent of grid power, typically achieving color rendering indices above 95 and illuminance levels of 160,000 lux at one meter. These systems serve critical surgical applications where power continuity directly impacts patient safety outcomes. LED product types dominate installed value due to superior efficacy and thermal management, while smart controls technology captures expanding margin pools through software-enabled intensity tuning and occupancy-based energy optimization. Ceiling mounted installation types sustain the largest replacement volume in mature healthcare infrastructure.
FDA enforcement of IEC 60601-1-41 luminaire safety standards and EPA energy efficiency guidelines shape product certification requirements and procurement eligibility across United States hospital systems. The EU Medical Device Regulation (MDR) and CE marking obligations extend compliance complexity for manufacturers serving European surgical centers. Stakeholders must monitor regulatory divergence between energy storage component classifications and medical device frameworks as solar-battery integration deepens.
Market Dynamics
Energy-independent surgical infrastructure is accelerating procurement cycles as hospitals prioritize resilience against grid instability and regulatory compliance mandates tighten replacement timelines for legacy luminaire systems.
Growth Catalysts
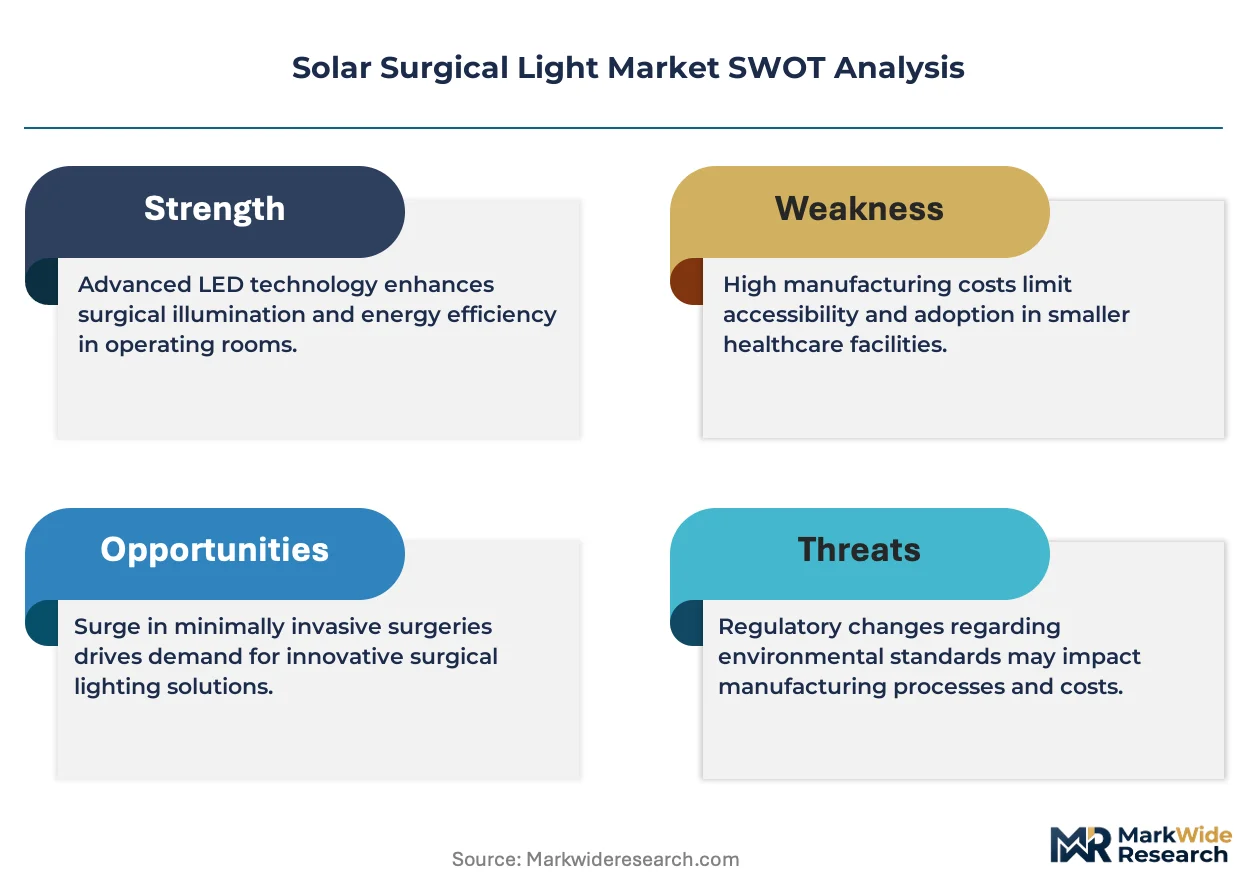
- IEC 60601-1-41 Enforcement:The FDA's sustained pressure on luminaire safety standards forces North American healthcare facilities into accelerated upgrade cycles for non-compliant legacy systems.
- Ambulatory Surgical Center Expansion:Freestanding surgical facilities in the United States prioritize solar-backed lighting to maintain accreditation during power disruptions without diesel generator dependency.
- German Hospital Modernization:Bavaria and Baden-Württemberg infrastructure programs explicitly fund solar-integrated surgical suites as part of regional healthcare resilience initiatives.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Raw material price swings for energy storage cells compress margin predictability for integrated solar-battery surgical systems.
- EU Medical Device Regulation Complexity:CE marking obligations for solar-battery hybrids create dual classification friction between energy storage frameworks and medical device pathways.
- LED Thermal Management Limits:High-intensity arrays above 160,000 lux generate heat dissipation constraints that restrict continuous operation in ambient temperatures above 35°C.
Strategic Opportunities
- Rural Indian Healthcare Electrification:District hospitals in Maharashtra and Tamil Nadu lack reliable grid access, creating first-mover advantage for solar surgical light deployment under national health infrastructure schemes.
- Smart Control Convergence:Integration of occupancy sensors with intensity tuning algorithms opens software-enabled recurring revenue streams beyond hardware sales.
- Australian Remote Surgery Networks:The Royal Flying Doctor Service and outback clinic chains require portable, grid-independent illumination for emergency surgical interventions.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hybrid photovoltaic-medical device expertise remains concentrated among a narrow specialist workforce, constraining field service scaling.
- Legacy OR Integration Complexity:Retrofitting ceiling-mounted solar luminaires into existing surgical suites requires structural reinforcement and HVAC recalibration that extends installation timelines.
- Dual Certification Timelines:Simultaneous IEC 60601-1-41 medical compliance and UN 38.3 lithium battery transport certification creates sequential approval bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Surgical Light Market |
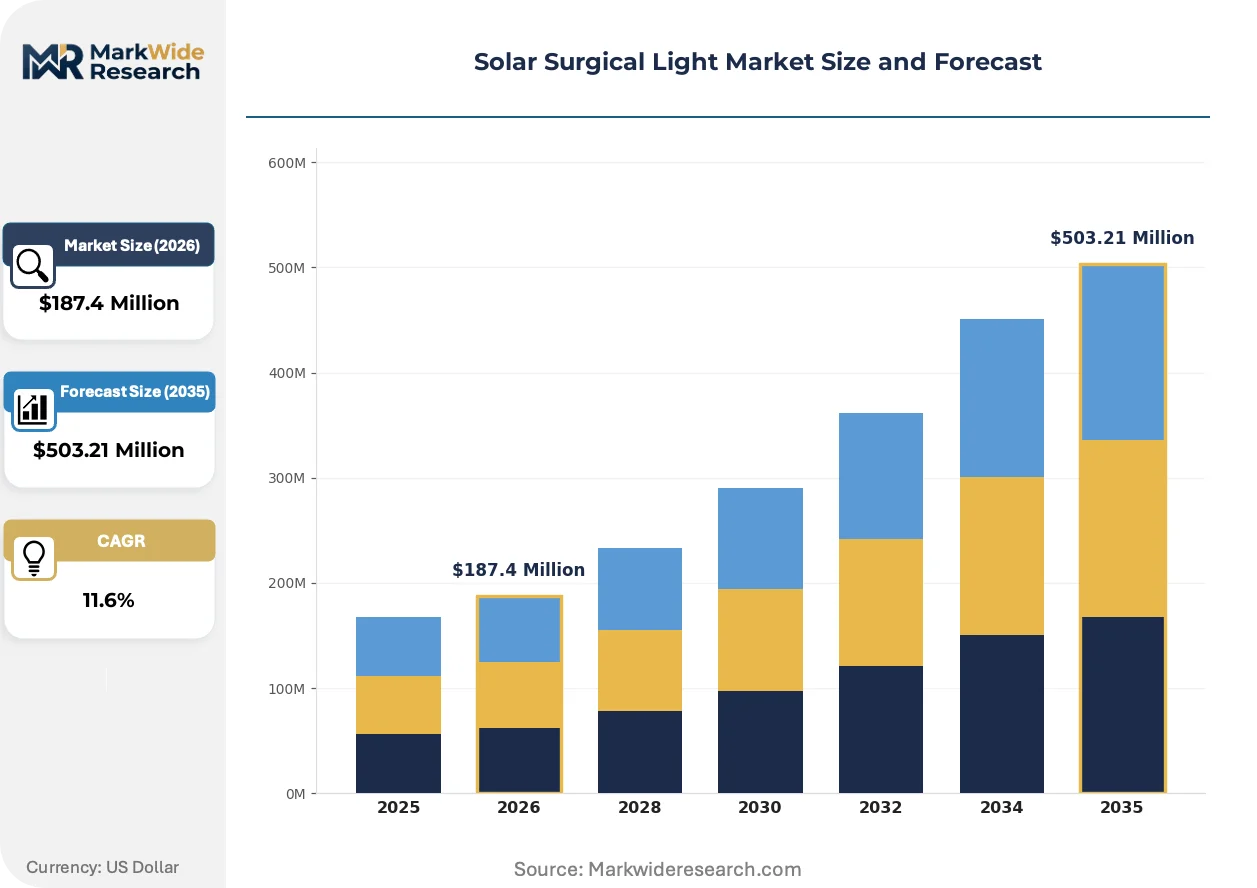
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
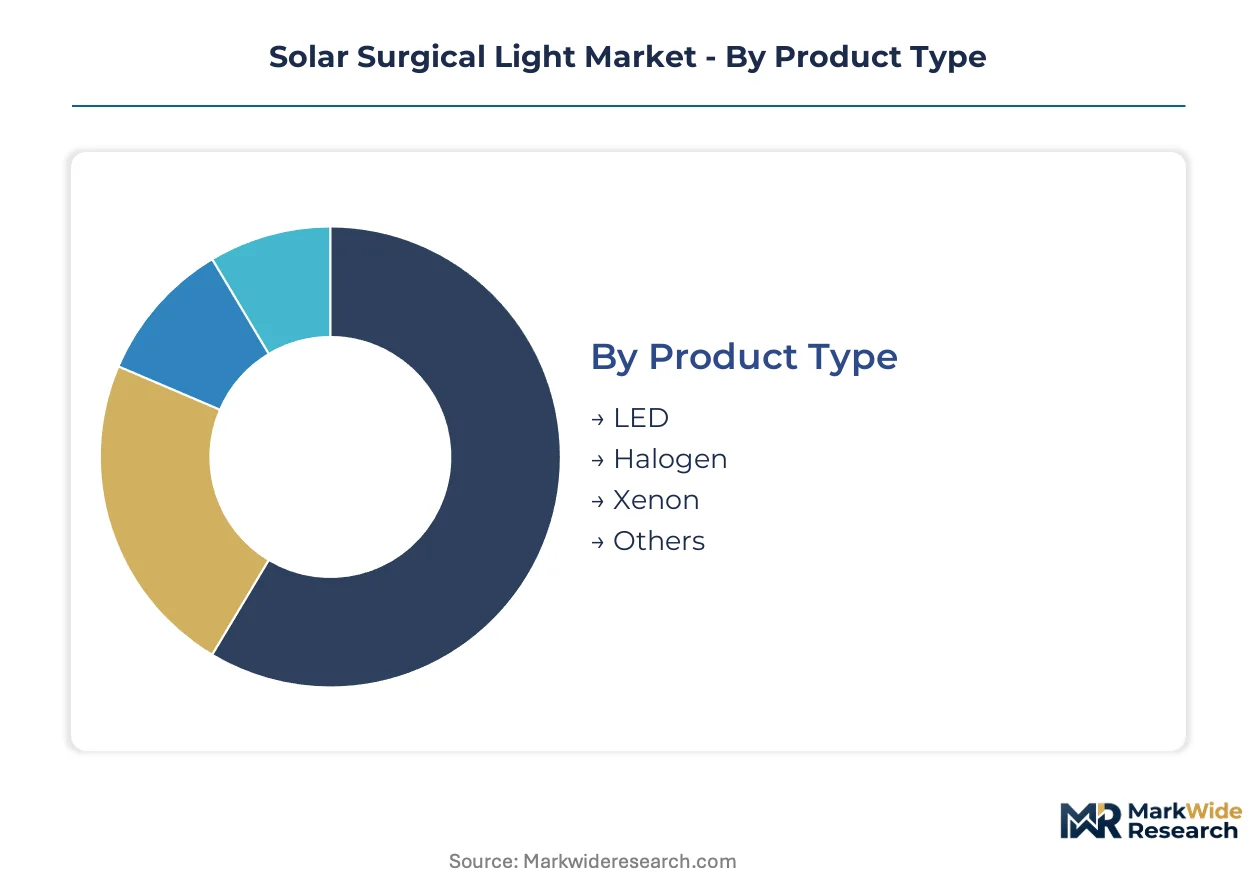
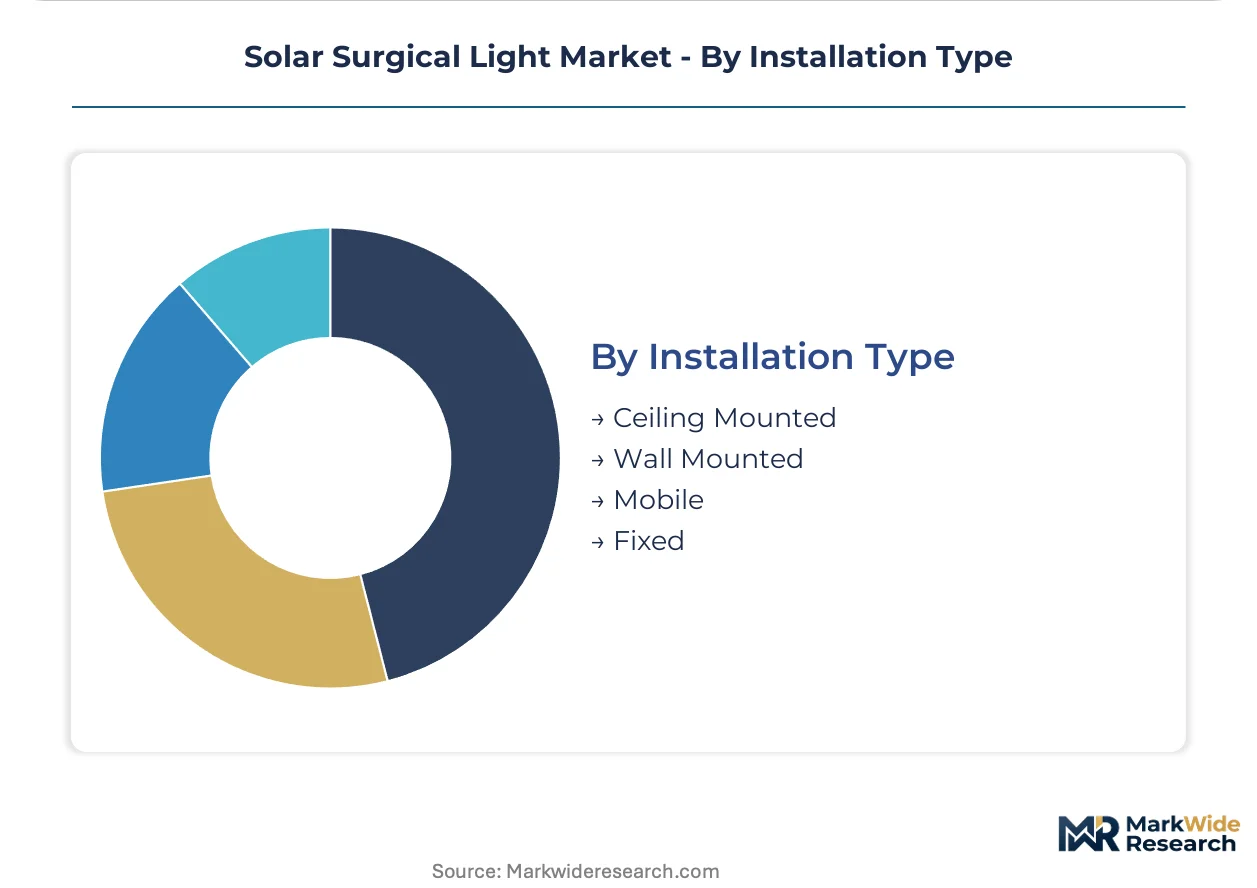
| Segmentation | Product Type: LED, Halogen, Xenon, Others Technology: Wireless, Wired, Hybrid, Smart Controls End User: Hospitals, Clinics, Surgical Centers, Emergency Rooms Installation Type: Ceiling Mounted, Wall Mounted, Mobile, Fixed |
| Companies Covered | STERIS plc, KONINKLIJKE PHILIPS N.V., Getinge AB, Hill-Rom Services Inc., Stryker, Skytron, BihlerMED, Integra LifeSciences Corporation, S.I.M.E.O.N. Medical GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Surgical Light Market Emerging Trajectories
Digital twin architectures are compressing development cycles for surgical lighting systems while regulatory convergence around energy storage safety reshapes product roadmaps across developed healthcare markets.
Photovoltaic capture modules with integrated micro-inverters are virtualizing the traditional separation between solar generation and surgical illumination hardware. German university hospitals in Heidelberg and Munich pilot all-in-one ceiling systems that eliminate external inverter cabinets. This convergence is virtualizing procurement decisions by collapsing separate vendor relationships into single-source contracts.
The EU Medical Device Regulation's expanded scope for battery-integrated devices is forcing manufacturers to restructure quality management systems around dual technical documentation. CE marking notified bodies now demand separate clinical evidence for solar-battery combinations that previously qualified under luminaire-only pathways. German and French surgical centers delay purchases until Q3 2025 as suppliers navigate reclassification.
Aftermarket service unbundling is fragmenting traditional equipment procurement across United States hospital networks. IDN procurement committees now separate hardware acquisition from 10-year maintenance obligations, pressuring manufacturers to compete on transparent lifecycle cost models rather than bundled financing. This shift concentrates in California and Texas health systems with mature value analysis committees.
Solar Surgical Light Market Segmentation
Solar surgical light procurement splits across technical specifications, infrastructure constraints, and clinical workflow requirements. Aftermarket service intensity varies dramatically by segment, with integrated battery systems demanding specialized photovoltaic-medical hybrid expertise that reshapes vendor selection criteria.
Product Type:
Service contract attachment rates diverge sharply across illumination technologies, with solid-state platforms enabling predictive maintenance algorithms that halve field dispatch frequency.
- LED:High-efficacy diode arrays achieve color rendering indices above 95 and 160,000 lux output at one meter with minimal thermal load. German hospital modernization programs in Bavaria and Baden-Württemberg specify LED solar surgical suites for infrastructure resilience mandates.
- Halogen:Tungsten-filament technology delivers continuous spectrum illumination but imposes higher thermal management burdens and shorter replacement cycles. Demand concentrates in budget-constrained rural Indian district hospitals under national electrification schemes where lower capital outlay overrides efficiency considerations.
- Xenon:Arc-discharge lamps provide intense, daylight-matched output for specialized microsurgical applications requiring precise tissue differentiation.
- Others:Emerging solid-state technologies including OLED panels and quantum dot enhancement layers remain pre-commercial for surgical-grade specifications.
By volume, LED leads. By growth pace, smart-integrated variants are climbing the fastest.
Technology:
Margin distribution tilts toward software-enabled platforms that capture recurring revenue through firmware subscriptions and remote diagnostics.
- Smart Controls:Occupancy sensors and intensity-tuning algorithms optimize battery discharge cycles while enabling outcome-linked service pricing. Australian Royal Flying Doctor Service deployments prioritize smart-controlled portability for outback emergency interventions.
- Hybrid:Dual-path power architectures maintain seamless failover between photovoltaic, battery, and grid sources with sub-10-millisecond switching. United States ambulatory surgical centers favor hybrid systems for accreditation compliance without diesel generator dependency.
- Wireless:Eliminated conduit requirements reduce installation disruption in retrofit scenarios but introduce electromagnetic compatibility certification complexity.
- Wired:Hardwired configurations persist in new construction where integrated ceiling infrastructure accommodates permanent photovoltaic feed.
By installed base, wired dominates. By margin expansion, smart controls is gaining share fastest.
End User:
Procurement authority concentration shapes vendor engagement models, with consolidated hospital networks demanding enterprise-level lifecycle cost guarantees.
- Hospitals:Acute-care facilities with 24/7 surgical throughput require redundant battery capacity and IEC 60601-1-41 compliance documentation. FDA enforcement timelines in the United States accelerate replacement cycles for legacy luminaire systems.
- Surgical Centers:Freestanding facilities prioritize compact, grid-independent configurations to maintain operations during utility failures without facility infrastructure investment. Texas and California health systems with mature value analysis committees unbundle hardware from decade-long maintenance obligations.
- Clinics:Lower-acuity settings adopt mobile solar units for minor procedure rooms with intermittent utilization patterns.
- Emergency Rooms:Trauma bays demand instant-on illumination with battery reserve for extended grid outages.
By revenue concentration, hospitals lead. By procurement velocity, surgical centers is expanding most quickly.
Installation Type:
Structural integration requirements determine project timeline and total cost of ownership, with ceiling retrofits demanding HVAC recalibration that extends commissioning schedules.
- Ceiling Mounted:Suspended armature systems with integrated photovoltaic capture dominate replacement volume in mature healthcare infrastructure. German university hospitals in Heidelberg and Munich pilot all-in-one ceiling units that eliminate external inverter cabinets.
- Mobile:Battery-integrated portable units serve temporary surgical setups and field deployments where permanent installation is impractical. Australian outback clinic chains and Indian district hospitals in Maharashtra and Tamil Nadu drive mobile adoption for unreliable grid environments.
- Wall Mounted:Space-constrained procedure rooms utilize vertical arm positioning for specialized ophthalmic or dental applications.
- Fixed:Permanent floor-stand configurations persist in austere settings with structural ceiling load limitations.
By replacement volume, ceiling mounted leads. By deployment flexibility, mobile is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitals deploy solar surgical lights for infrastructure resilience, while United States facilities prioritize accreditation compliance and Indian district hospitals seek grid-independent solutions for unreliable power environments.
United States
Ambulatory surgical centers in Texas and California drive procurement of hybrid power architectures that eliminate diesel generator dependency. FDA enforcement of IEC 60601-1-41 luminaire safety standards accelerates replacement cycles for legacy systems. Value analysis committees in mature health systems unbundle hardware acquisition from decade-long maintenance obligations.
Germany
Hospital infrastructure modernization programs in Bavaria and Baden-Württemberg explicitly fund solar-integrated surgical suites as regional healthcare resilience initiatives. EU Medical Device Regulation complexity creates dual classification friction between energy storage frameworks and medical device pathways. University hospitals in Heidelberg and Munich pilot all-in-one ceiling systems that eliminate external inverter cabinets.
India
District hospitals in Maharashtra and Tamil Nadu lack reliable grid access, creating first-mover opportunity for mobile solar surgical light deployment. National health infrastructure schemes prioritize lower capital outlay configurations in budget-constrained rural settings. Field installations concentrate in western and southern states where electrification gaps intersect with surgical capacity expansion.
Australia
The Royal Flying Doctor Service and outback clinic chains require portable, grid-independent illumination for emergency surgical interventions in remote territories. Smart control integration enables battery optimization for intermittent utilization patterns in austere environments. Procurement prioritizes mobility and rapid deployment over permanent infrastructure investment.
Solar Surgical Light Market Vendor Landscape
Capability concentration sits with specialized medical device manufacturers; scale advantage sits with diversified healthcare conglomerates. The vendor base organizes into three tiers: sterile processing specialists leveraging installed base cross-sell, diversified technology conglomerates with proprietary LED architectures, and integrated operating room workflow providers. Dominant competitive moves include bundling surgical lights with broader infrastructure systems and unbundling aftermarket service contracts from hardware sales.
Among diversified healthcare technology conglomerates, KONINKLIJKE PHILIPS N.V. and Stryker occupy positions anchored by scale and portfolio breadth. STERIS plc exemplifies the sterile processing specialist archetype, while Getinge AB sits within the integrated workflow systems tier. These three entities represent the primary competitive anchors, with S.I.M.E.O.N. Medical GmbH and Co. KG representing mid-cap German specialization in surgical illumination.
| Leading Market Players |
|---|
| STERIS plc |
| KONINKLIJKE PHILIPS N.V. |
| Getinge AB |
| Hill-Rom Services Inc. |
| Stryker |
| Skytron |
| BihlerMED |
| Integra LifeSciences Corporation |
| S.I.M.E.O.N. Medical GmbH and Co. KG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lithium-ion cell manufacturing is compressing battery pack costs while simultaneously eroding margin predictability for integrated solar surgical light suppliers, forcing vendors toward long-term service contract structures that stabilize revenue streams independent of hardware price cycles.
Pricing Analysis
Long-term offtake agreements with hospital procurement groups dominate contract structures, though spot purchasing persists for emergency replacement scenarios. Pricing stratifies across premium, standard, and economy tiers based on IEC 60601-1-41 certification grade and bundled maintenance duration. Cost compression in mid-tier LED driver assemblies is intensifying because of wafer-scale manufacturing consolidation in East Asia. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German university hospitals prioritize lifecycle cost guarantees over upfront expenditure.
Supply Chain Analysis
Export-control regimes limiting gallium nitride wafer shipments from the United States and Japan are constraining high-efficacy LED sourcing for premium surgical illumination tiers. Manufacturing concentrates in China, Germany, and South Korea, with photovoltaic module assembly drawing heavily from polysilicon feedstock anchored in Xinjiang and Hohhot. Supply chain risk centers on single-source dependency for medical-grade battery management systems. Distribution runs through specialized medical device distributors with sterile processing expertise rather than general electrical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity where regulatory entrenchment through IEC 60601-1-41 compliance documentation creates substantial switching costs for hospital procurement committees.
For Market Incumbents: Entrench position by deepening backward integration into proprietary LED driver architectures that reduce field failure rates below competitor benchmarks. Expand capacity addition in Bavaria to capture German hospital modernization program allocations. Certification investment in dual IEC 60601-1-41 and UN 38.3 pathways accelerates approval timelines against emerging Asian entrants.
For New Entrants and Emerging Players: Pursue white-space deployment in Maharashtra and Tamil Nadu district hospitals where grid unreliability creates first-mover advantage without competing against entrenched sterile processing incumbents. Target mobile configuration segments for rural Indian healthcare electrification schemes. Go-to-market leverage rests on partnerships with national health infrastructure procurement bodies rather than direct hospital sales channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sterile processing specialists with installed base cross-sell capabilities. Long-term viability favors vendors with software-enabled smart control platforms that capture firmware subscription streams beyond hardware replacement cycles. Acquisition target archetype: mid-cap German surgical illumination specialists with CE marking expertise and Heidelberg-Munich hospital reference sites. Signal to monitor: EU MDR reclassification timelines for solar-battery hybrid devices.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Dual classification navigation unlocks European ambulatory surgical center procurement eligibility. |
| Hospital System Partnership | IDN value analysis committee engagement secures decade-long maintenance contract unbundling. |
| Software Companion Development | Smart control integration enables occupancy-based battery optimization and recurring firmware revenue. |
| Backward Integration into LED Drivers | Proprietary architectures reduce field failure rates and differentiate against commoditized competitors. |
| Reimbursement Strategy | Outcome-linked pricing models align with United States health system value-based care transitions. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers; and secondary validation against FDA 510(k) filings, IEC technical documentation, hospital procurement databases, and CMS Medicare equipment expenditure records. Bottom-up triangulation across installation type volumes and top-down reconciliation against healthcare infrastructure investment flows anchored market sizing.
Forecast inputs span product type, technology architecture, end-user facility category, installation configuration, and regional regulatory cluster. CAGRs derive from segmented growth rate application with cross-validation against historical replacement cycle data and enforcement timeline impacts. Modeled variables include IEC 60601-1-41 compliance acceleration effects, lithium-ion cost curves, and ambulatory surgical center expansion trajectories across the analysis window.
Sensitivities concentrate around EU MDR reclassification timelines, raw material price volatility in energy storage cells, and biomedical engineering workforce scarcity constraining field service scaling. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hospital capital expenditure continuity. Material shifts in battery transport certification requirements or German federal healthcare infrastructure allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laryngoscopes Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Global Vessel Sealing Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Slit Lamps Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Memory Implants Market
Medical Devices
Global Uterine Manipulation Devices Market