
 China Minimally Invasive Surgery Devices Market | 2026-2036
China Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Minimally Invasive Surgery Devices Market Outlook
NMPA's priority review pathway for innovative medical devices is hardening the cost-of-entry calculus for foreign manufacturers seeking China market access. Medtronic Plc leverages its established regulatory affairs infrastructure to navigate complex Type III registration requirements. Boston Scientific Corporation sustains competitive positioning through deep specialization in interventional cardiology and peripheral interventions.
Minimally invasive surgery devices encompass instruments, visualization systems, and energy platforms designed for procedures through small incisions under 2 cm, typically employing laparoscopic trocars with 5-12 mm diameters and high-definition camera stacks operating at 1080p or 4K resolution. These systems reduce patient trauma, shorten hospital stays, and lower postoperative complication rates versus open surgery across abdominal, thoracic, and joint procedures. Endoscopes and laparoscopes anchor the product landscape due to their ubiquity across hospital surgical departments and replacement cycle intensity. Robotic surgery technology captures disproportionate R&D investment as domestic players like Shanghai MicroPort Surgical compete against established systems in tier-one hospital tenders.
NMPA's Medical Device Classification Catalog and GB standard compliance requirements shape product registration timelines and clinical trial obligations for both imported and domestically manufactured devices. The National Healthcare Security Administration's DRG/DIP payment reform is altering hospital procurement calculus, favoring devices that demonstrably reduce length-of-stay metrics. Stakeholders must monitor how provincial centralized procurement expansions rebalance pricing power between multinational suppliers and emerging domestic champions.
Market Dynamics
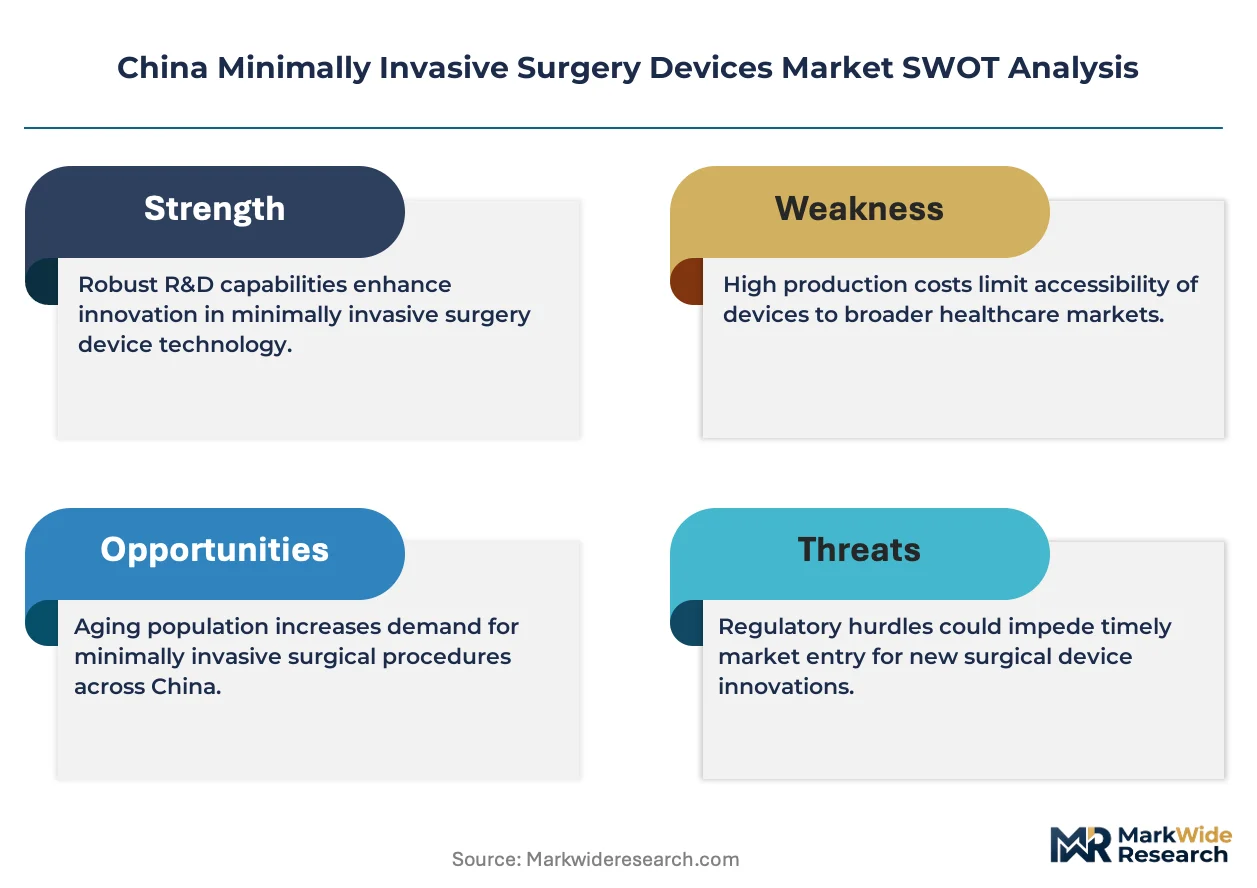
NMPA's priority review pathway for innovative medical devices is compressing registration timelines and intensifying competitive pressure on foreign manufacturers to localize R&D and production within China's hospital procurement ecosystem.
Growth Catalysts
- DRG/DIP Payment Reform:The National Healthcare Security Administration's diagnosis-related group payment system rewards shorter hospital stays, accelerating minimally invasive procedure adoption across Jiangsu and Guangdong tier-three facilities.
- Domestic Robotic Platform Development:Shanghai MicroPort Surgical and comparable manufacturers are fielding competitive surgical robotics for urology and gynecology, reducing import dependency in tier-one hospital tenders.
- GB Standard Harmonization:China's alignment of national medical device standards with international technical specifications is streamlining Type III registration pathways for visualization systems and energy platforms.
Market Restraints
- Optical Component Supply Concentration:High-definition camera stacks and 4K imaging sensors rely on concentrated sourcing from German and Japanese precision optics suppliers, creating vulnerability to trade friction.
- Capital Equipment Intensity:Robotic surgery platforms require RMB 20-35 million upfront investment per unit, limiting deployment to top-tier hospitals with dedicated surgical volume guarantees.
- Clinical Validation Burden:NMPA's Medical Device Classification Catalog mandates extended domestic clinical trials for novel energy platforms, extending time-to-revenue for foreign entrants.
Strategic Opportunities
- Central-Western Hospital Network Expansion:Sichuan and Shaanxi provinces are constructing minimally invasive surgery centers with government infrastructure subsidies, opening procurement channels outside saturated eastern markets.
- Single-Port Laparoscopy Convergence:Integration of articulating instruments with advanced 3D visualization is creating next-generation surgical platforms for bariatric and colorectal applications.
- Provincial Centralized Procurement:Volume-based procurement pilots in Anhui and Jiangsu are favoring suppliers with localized manufacturing and service networks over pure import models.
Industry Challenges
- Surgeon Training Pipeline Constraints:Laparoscopic and robotic surgery require 200+ case proctoring for credentialing, creating bottlenecks as procedure volumes expand faster than qualified instructor availability.
- Legacy System Integration Complexity:New energy platforms must interface with existing hospital information systems and surgical workflow software, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Minimally Invasive Surgery Devices Market |
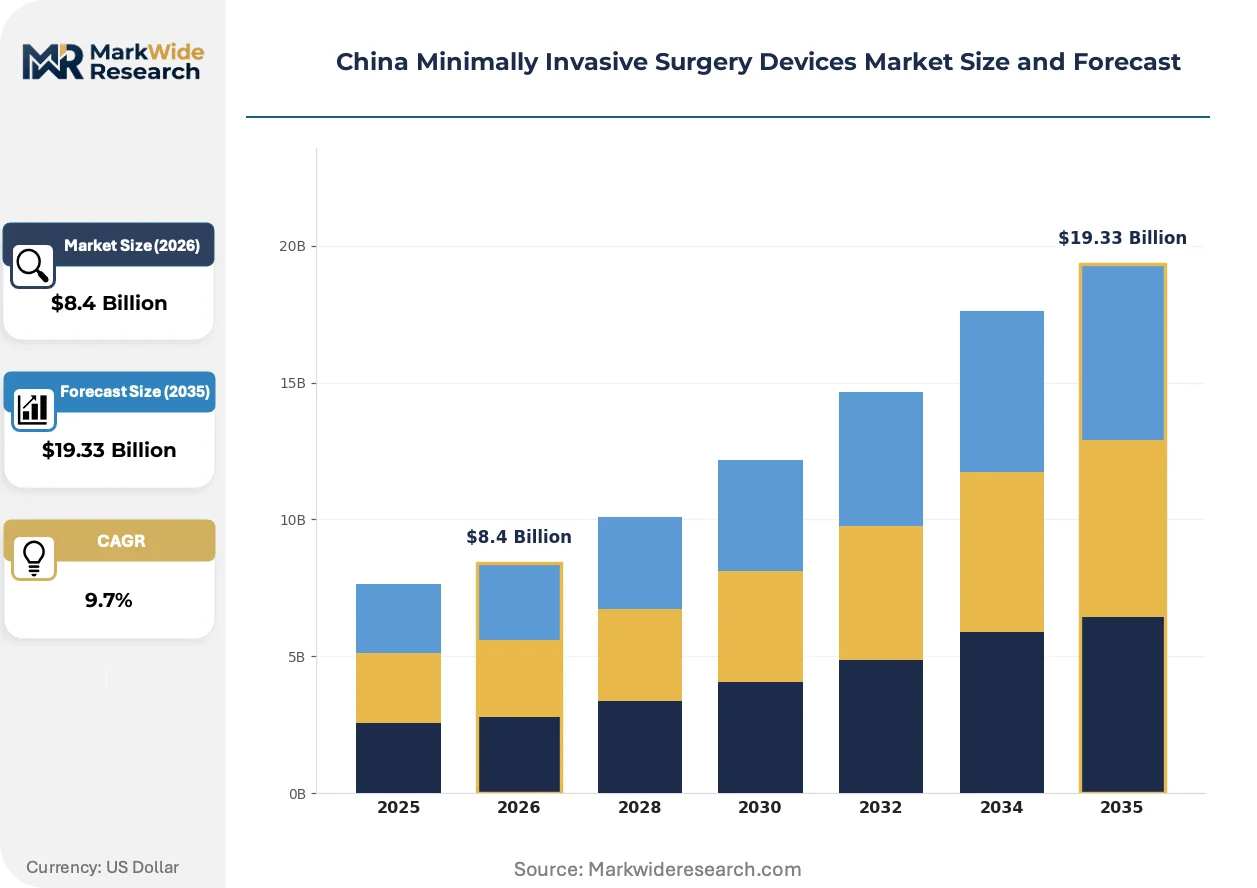
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Laparoscopes, Surgical Instruments, Imaging Devices Application: Urology, Gynecology, Gastroenterology, Orthopedics Technology: Robotic Surgery, Image-guided Surgery, Tele-surgery, Augmented Reality End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Stryker Corporation, Boston Scientific Corporation, Medtronic Plc, Zimmer Biomet, FUJIFILM Corporation, Abbott Laboratories, CONMED Corporation, Smith+Nephew Plc, B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Minimally Invasive Surgery Devices Market Strategic Shifts
Surgical device architecture is fragmenting into interoperable subsystems, enabling hospital purchasing departments to mix domestic and foreign components within integrated operating room environments.
Disposable laparoscopic trocar systems with integrated insufflation valves are modularizing the instrument stack, allowing tier-two hospitals in Henan and Hubei to upgrade visualization capabilities without full platform replacement. Provincial procurement consortia are bundling these components with service contracts, compressing the traditional capital equipment sales cycle into consumable subscription models.
NMPA's 2023 guidance on AI-assisted surgical navigation has triggered pre-submission consultations for computer-vision enabled camera systems, accelerating regulatory clarity for machine learning integration in real-time tissue recognition. Domestic manufacturers are prioritizing algorithm training on Chinese anatomical datasets to satisfy localization requirements ahead of foreign competitors.
Hospital purchasing committees are unbundling after-sales service from equipment contracts, creating standalone technical support markets where third-party engineering firms compete with original manufacturers for maintenance revenue. This shift is most pronounced in Zhejiang and Fujian, where public hospital budget transparency rules expose lifetime cost differentials between service models.
China Minimally Invasive Surgery Devices Market Segmentation
Surgical device procurement in China stratifies sharply across hospital tiers and provincial reimbursement frameworks. NMPA registration pathways diverge meaningfully by product risk classification, creating distinct commercialization timelines for visualization platforms versus consumable instruments.
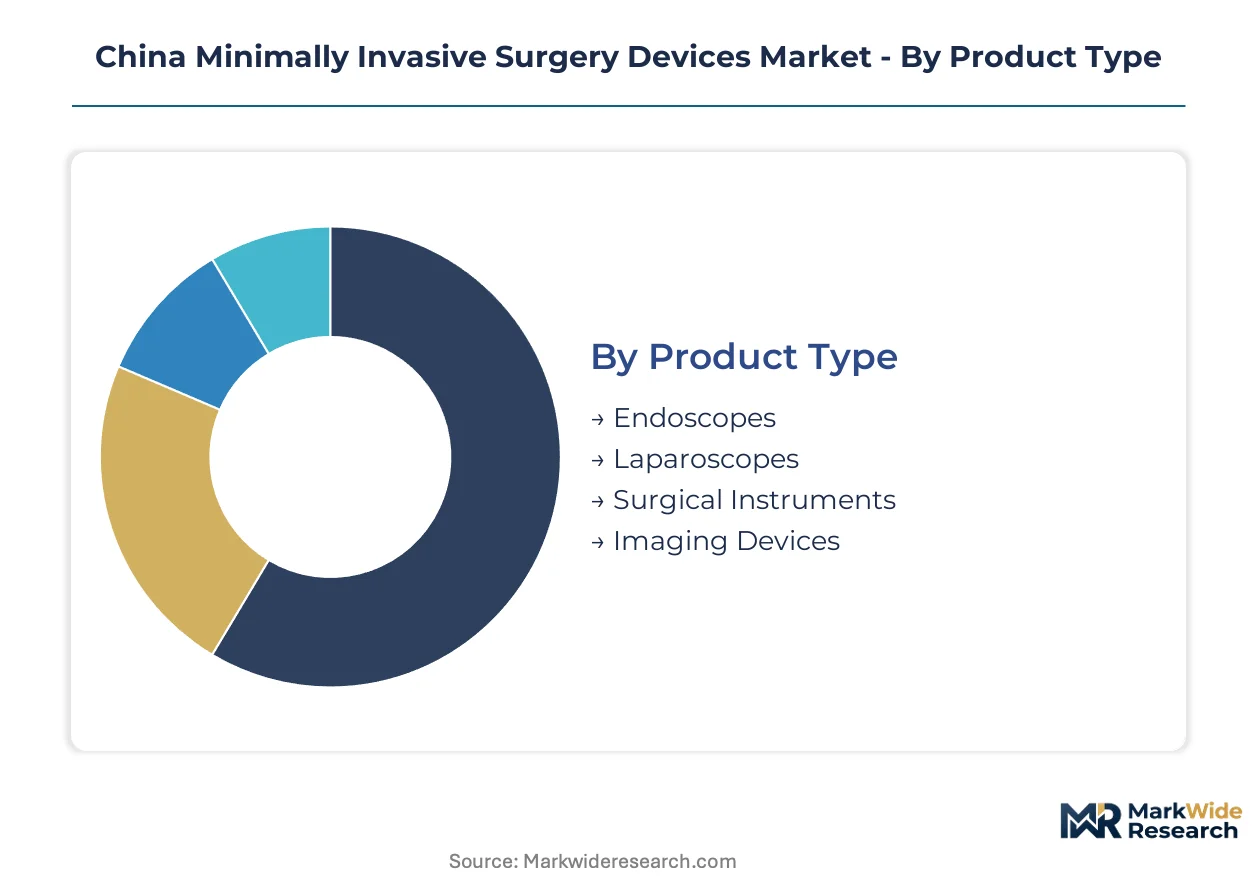
Product Type:
Endoscopes and laparoscopes trigger NMPA Class II or III certification depending on sterilization modality and imaging resolution, while surgical instruments face lighter Type I or II burdens. Imaging devices with AI-integrated processing encounter extended clinical trial obligations under the 2023 AI-enabled device guidance.
- Endoscopes:Flexible and rigid fiber-optic systems with 1080p to 4K resolution capabilities, incorporating CMOS or CCD sensor arrays. Demand concentrates in Jiangsu and Guangdong tier-three hospitals expanding gastrointestinal screening programs under DRG payment incentives.
- Laparoscopes:Rigid rod-lens systems with 0° and 30° viewing angles, typically 5-10mm diameter. Sichuan and Shaanxi provincial procurement consortia are bundling these with trocar sets for new minimally invasive surgery centers receiving infrastructure subsidies.
- Surgical Instruments:Graspers, scissors, and needle holders in reusable and disposable configurations.
- Imaging Devices:High-definition camera stacks, light sources, and insufflation systems with integrated documentation software.
Leading the category by volume: Surgical Instruments. Growing fastest: Imaging Devices with integrated AI-assisted navigation capabilities.
Application:
Procedure-specific device configurations align with provincial disease burden patterns and surgeon training availability. Eastern China hospitals cluster around urology and gynecology robotics, while central provinces prioritize gastroenterology screening infrastructure.
- Urology:Robotic and laparoscopic platforms for prostatectomy and nephrectomy procedures. Shanghai and Beijing tier-one hospitals drive procurement of da Vinci-compatible instruments and domestic alternatives from MicroPort Surgical.
- Gynecology:Hysteroscopy and laparoscopy systems for myomectomy and endometriosis treatment. Zhejiang and Fujian public hospitals are unbundling service contracts from equipment purchases, exposing lifetime cost differentials between robotic and conventional platforms.
- Gastroenterology:Flexible endoscopy systems with narrow-band imaging and chromoendoscopy capabilities.
- Orthopedics:Arthroscopic shavers, scopes, and fixation devices for joint repair procedures.
Volume concentration: Urology in eastern coastal provinces. Steepest expansion trajectory: Gastroenterology as Henan and Hubei tier-two hospitals upgrade screening capacity.
Technology:
Capital intensity and regulatory novelty create a three-tier technology adoption curve. Robotic platforms demand RMB 20-35 million upfront investment and dedicated surgical volume guarantees, while image-guided and tele-surgery systems spread through leasing and subscription models.
- Robotic Surgery:Multi-arm platforms with 3D visualization and wristed instrumentation for precision tissue manipulation. Domestic manufacturers are gaining tier-one hospital tenders in urology and gynecology as NMPA streamlines priority review for locally developed systems.
- Image-guided Surgery:Real-time navigation combining preoperative imaging with intraoperative tracking. Anhui and Jiangsu volume-based procurement pilots favor suppliers with localized technical support networks over pure import models.
- Tele-surgery:Low-latency robotic control over 5G networks for remote procedure assistance.
- Augmented Reality:Heads-up displays overlaying anatomical guidance onto the surgical field.
Highest revenue per unit: Robotic Surgery. Gaining share fastest: Image-guided Surgery as mid-tier hospitals seek precision without full robotic capital commitment.
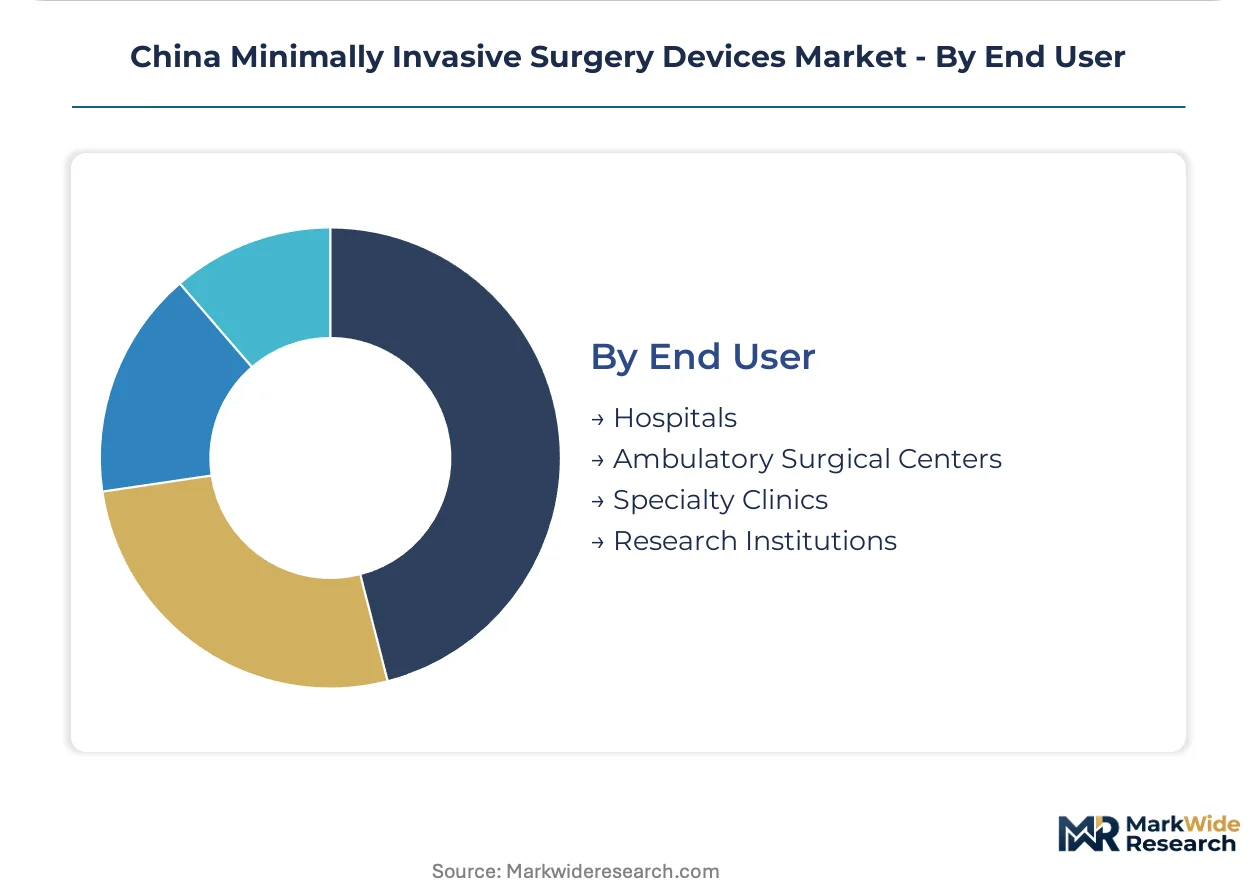
End User:
Procurement authority and reimbursement access fragment across China's multi-tier healthcare system. Tier-three hospitals retain capital equipment decision power, while ambulatory surgical centers face stricter NDRC pricing controls.
- Hospitals:Tier-three facilities with 500+ beds and dedicated surgical departments controlling the majority of robotic and advanced laparoscopic procurement. NMPA Type III registration requirements and extended domestic clinical trials favor established players with regulatory affairs infrastructure.
- Ambulatory Surgical Centers:Day-procedure facilities concentrated in urban clusters with streamlined discharge protocols. DRG/DIP payment reform rewards shorter stays, accelerating disposable instrument adoption in Jiangsu and Guangdong.
- Specialty Clinics:Focused facilities for ophthalmology, dentistry, and cosmetic procedures with limited MIS device penetration.
- Research Institutions:Academic medical centers conducting clinical trials for NMPA registration and post-market surveillance studies.
Procurement volume leader: Hospitals. Expanding most quickly: Ambulatory Surgical Centers as provincial governments license new day-surgery facilities in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate minimally invasive surgery device manufacturing through NMPA-certified production facilities. Provincial health commissions in Jiangsu and Zhejiang coordinate centralized procurement pilots that reshape distribution economics for domestic and foreign suppliers.
Jiangsu Province
Tier-three hospitals in Nanjing and Suzhou expand laparoscopic surgery volumes under DRG payment incentives from the National Healthcare Security Administration. NMPA streamlines innovative device approvals through priority review pathways for locally manufactured visualization systems. The Suzhou Industrial Park hosts domestic robotic surgery platform developers competing for hospital tenders.
Guangdong Province
Shenzhen and Guangzhou hospital clusters drive demand for single-port laparoscopy systems in bariatric and colorectal applications. Provincial centralized procurement consortia favor suppliers with localized technical service networks over pure import models. The Pearl River Delta manufacturing corridor supplies disposable trocar sets to tier-two facilities across southern China.
Sichuan Province
Chengdu anchors western China's minimally invasive surgery center expansion with government infrastructure subsidies for new facilities. GB standard compliance requirements shape product registration timelines for visualization platforms entering the market. The Sichuan-Chongqing economic zone attracts domestic manufacturers seeking lower operational costs than eastern coastal zones.
Beijing Municipality
Academic medical centers in Beijing conduct clinical trials for NMPA Type III registration of robotic surgery platforms and AI-enabled camera systems. SAMR coordinates with NMPA on medical device classification catalog updates affecting energy platform approvals. The Beijing-Tianjin-Hebei cluster concentrates surgeon training programs addressing credentialing bottlenecks.
Zhejiang Province
Hangzhou and Ningbo public hospitals unbundle after-sales service from equipment contracts under budget transparency rules. Provincial procurement pilots expose lifetime cost differentials between robotic and conventional laparoscopic platforms. The Ningbo-Zhoushan port logistics network supports import component distribution for German and Japanese precision optics.
China Minimally Invasive Surgery Devices Market Competitive Environment
United States producers anchor the premium-tier segment through established regulatory affairs infrastructure; European specialists hold differentiated positions in precision optics and energy platforms. The vendor base stratifies across three tiers: multinational conglomerates with full portfolio coverage, regional champions with application-specific depth, and domestic challengers leveraging NMPA priority review pathways. Two dominant competitive moves define current positioning: backward integration into optical component manufacturing to reduce supply concentration risk, and geographic expansion through provincial procurement consortia relationships.
Within the multinational tier, Medtronic Plc and Boston Scientific Corporation exemplify archetypes of regulatory navigation specialists and interventional cardiology-focused operators respectively. Stryker Corporation occupies a position representing diversified surgical device portfolios spanning visualization and instrumentation. These three anchors demonstrate how foreign manufacturers defend positioning through NMPA Type III registration expertise and deep specialization in high-barrier application segments.
| Leading Market Players |
|---|
| Stryker Corporation |
| Boston Scientific Corporation |
| Medtronic Plc |
| Zimmer Biomet |
| FUJIFILM Corporation |
| Abbott Laboratories |
| CONMED Corporation |
| Smith+Nephew Plc |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
A sharp bifurcation between NMPA priority-review-eligible robotic platforms and commodity-grade disposable instruments manifests in both procurement economics and upstream sourcing configurations. Premium systems command extended payment terms bundled with technical service contracts, while provincial centralized procurement pilots compress margins on trocar sets and basic laparoscopic instruments through volume-based tenders.
Pricing Analysis
Short lead-time premiums for German and Japanese precision optics components sustain pricing power among established visualization system suppliers, while spot-market sourcing of CMOS sensors from South Korean foundries enables aggressive discounting on mid-tier camera stacks. Three-tier pricing structure across premium, standard, and economy levels separates robotic surgery platforms with 3D articulation from conventional laparoscopic towers and disposable-only instrument sets. Cost compression in the standard tier intensifies because Anhui and Jiangsu volume-based procurement pilots expose lifetime cost differentials between bundled and unbundled service models. Tier-two hospitals in Henan and Hubei demonstrate highest price sensitivity, while Beijing and Shanghai tier-one facilities prioritize performance specifications over procurement cost.
Supply Chain Analysis
Reverse-logistics flows for refurbished robotic arms and remanufactured endoscope light sources create secondary market channels that undercut new equipment pricing in Sichuan and Shaanxi. Manufacturing concentration centers on China, Germany, and Japan, with Yangtze River Delta facilities assembling final systems from imported optical subassemblies. High-definition camera stacks draw from specialized CMOS foundries in South Korea and precision glass suppliers in Germany. Single-source vulnerability around 4K imaging sensors creates exposure to trade friction affecting Japanese component exports. Distribution runs through provincial procurement consortia in Jiangsu and Guangdong, with tier-three hospitals increasingly bypassing traditional distributor networks for direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's minimally invasive surgery devices sector is consolidating around regulatory affairs scale and localized manufacturing footprints as NMPA priority review pathways and provincial procurement centralization squeeze subscale foreign competitors from tier-one hospital tenders.
For Market Incumbents: Extend service contract unbundling strategies pioneered in Zhejiang and Fujian to capture standalone technical support revenue streams as public hospital budget transparency rules expose lifetime cost differentials. Deepen backward integration into precision optics manufacturing to reduce dependency on German and Japanese sensor suppliers facing trade friction exposure. Fortify NMPA Type III registration infrastructure against emerging domestic robotic platform developers leveraging streamlined priority review pathways for locally developed systems. For New Entrants and Emerging Players: Tier-two hospitals in central-western provinces represent the most penetrable buyer archetype, with Sichuan and Shaanxi infrastructure subsidies creating procurement channels outside saturated eastern markets. Single-port laparoscopy convergence in bariatric applications offers white-space positioning between established multi-port robotic systems and conventional laparoscopic towers. A leasing-based go-to-market model bypasses the RMB 20-35 million capital equipment barrier limiting tier-two hospital adoption. For Investors and Strategic Acquirers: Re-rating potential sits with domestic manufacturers possessing NMPA priority review track records and established surgeon training partnerships given DRG/DIP payment reform acceleration across Jiangsu and Guangdong. Long-term viability over the analysis window hinges on regulatory affairs infrastructure depth and provincial procurement consortium relationships rather than pure technology differentiation. Acquisition targets should demonstrate sustained tier-one hospital tender participation in urology and gynecology robotics. Monitor NMPA guidance updates on AI-enabled surgical navigation as the inflection signal for algorithm-trained domestic platforms displacing foreign visualization systems.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Priority Review Pathway Navigation | Compressed registration timelines reward manufacturers with established regulatory affairs infrastructure in Beijing and Shanghai. |
| Provincial Procurement Consortium Partnership | Anhui and Jiangsu volume-based pilots favor suppliers with localized technical service networks over import-only models. |
| Surgeon Training Program Expansion | Chengdu and Beijing credentialing bottlenecks create competitive moats for platforms with 200+ case proctoring pipelines. |
| Optical Component Backward Integration | Captive supply of CMOS sensors and precision glass reduces exposure to German and Japanese trade friction. |
| AI-Enabled Navigation Pre-Submission | NMPA 2023 guidance on computer-vision systems creates first-mover advantage for Chinese anatomical dataset training. |
Study Parameters
NMPA registration filings, provincial procurement consortium tender databases, and hospital capital expenditure records formed the secondary backbone, cross-referenced against primary interviews with hospital purchasing committee directors, biomedical engineers managing surgical workflow integration, GPO contracts managers, and regulatory affairs leads at multinational device manufacturers. Bottom-up and top-down triangulation validated segment-level estimates against aggregate market sizing derived from tier-three hospital surgical volume expansion in Jiangsu and Guangdong.
Bottom-up modeling anchored volume projections to hospital bed expansion in Sichuan and Shaanxi minimally invasive surgery centers, while top-down analysis calibrated value estimates against DRG/DIP payment reform adoption curves across eastern China. Segmentation dimensions spanned product type, application specialty, technology tier, and end-user facility class, with additional modeling of NMPA registration pathway timelines affecting commercialization velocity. CAGRs emerged from procedure volume elasticity to reimbursement incentives and capital equipment replacement cycles, incorporating surgeon training pipeline constraints as a demand-side governor.
Revisions become necessary when NMPA updates its Medical Device Classification Catalog affecting energy platform approval timelines, or when provincial centralized procurement pilots expand beyond current Anhui and Jiangsu boundaries. Forecasts reflect assumptions about continued DRG/DIP payment reform implementation and sustained infrastructure subsidy flows to western provinces. Practitioners should monitor NMPA guidance on AI-assisted surgical navigation and SAMR coordination on standard harmonization for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market
Medical Devices
Global Hi-Tech Medical Devices Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Canada Anesthesia Devices Market