
 Europe Disposable Endoscopes Market | 2026-2036
Europe Disposable Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Disposable Endoscopes Market Intelligence
Hospital procurement consortia across Northern Europe is reshaping how disposable endoscopes reach end users, with direct sales teams now competing against centralized purchasing platforms. Ambu leverages its manufacturing footprint in Denmark to sustain rapid fulfillment cycles for bronchoscope orders. Stryker anchors its position through specialized urological portfolios that dominate contracted supply agreements. Olympus competes by extending its service infrastructure to support disposable-adjacent workflows in high-volume endoscopy units.
Europe disposable endoscopes are single-use optical instruments constructed from medical-grade polymers with integrated CMOS or CCD imaging sensors, designed for insertion into body cavities for visualization, biopsy, or minor intervention without reprocessing between patients. Gastrointestinal endoscopes occupy the largest product segment due to the sheer procedure volume across European hospital systems, though bronchoscopes represent the fastest-growing category as intensive care units adopt single-use protocols for ventilator-associated pneumonia prevention. Among end users, surgical centers capture expanding share as outpatient procedure migration accelerates, while hospitals retain the deepest margin pools through bundled contracting.
The EU Medical Device Regulation (MDR) and CE marking framework impose stringent biocompatibility and sterility validation requirements that elevate barriers for new disposable endoscope entrants. France's ANSM and Germany's BfArM coordinate post-market surveillance, creating differentiated compliance obligations across national jurisdictions. Stakeholders must monitor how notified body capacity constraints delay MDR certifications and whether national health technology assessments in Italy and Spain will expand reimbursement for single-use alternatives.
Market Dynamics
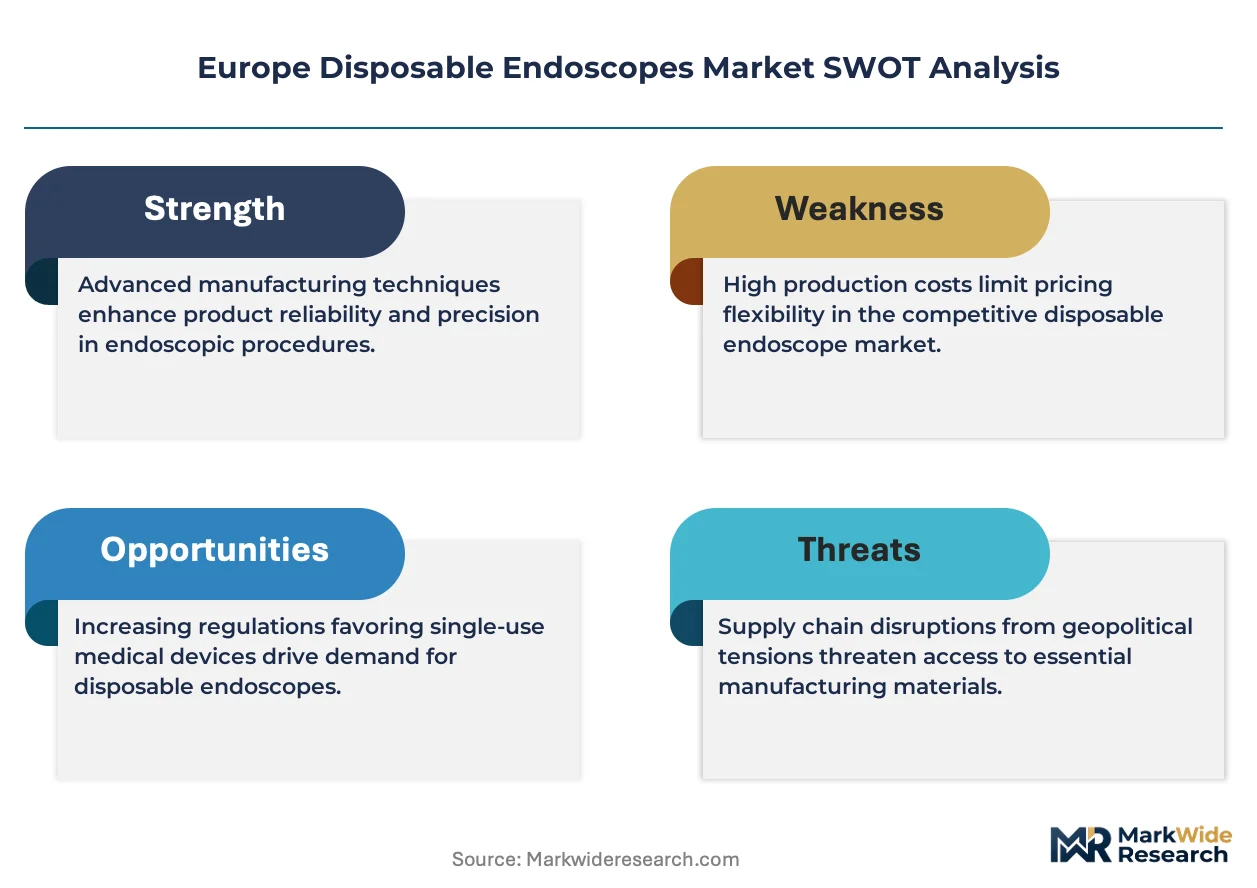
The EU Medical Device Regulation (MDR) is compressing sterility validation timelines while German hospital procurement consortia consolidate purchasing power, forcing manufacturers to choose between direct sales investment or platform compliance.
Growth Catalysts
- CE marking sterility mandates:The EU MDR elevates single-use validation requirements, eliminating reusable reprocessing alternatives in acute care settings.
- Ventilator-associated pneumonia protocols:Intensive care units across France and the Netherlands mandate single-use bronchoscopes for intubated patients.
- CMOS sensor cost compression:Semiconductor manufacturing scale is reducing imaging component costs for disposable urological instruments.
Market Restraints
- Medical-grade polymer input volatility:Polypropylene and polycarbonate supply concentration in Middle East petrochemical complexes exposes European converters to feedstock price swings.
- Notified body certification bottlenecks:MDR implementation has strained TÜV SÜD and BSI capacity, extending CE marking timelines for new entrants.
- Reusable endoscope refurbishment economics:Established service infrastructure for Olympus and Pentax reprocessing equipment creates switching cost inertia in budget-constrained Spanish and Italian facilities.
Strategic Opportunities
- Poland and Romania hospital modernization:EU structural fund investments in Eastern European acute care infrastructure create first-mover advantages for disposable platform suppliers.
- Outpatient surgical center expansion:France's J2 ambulatory surgery authorization framework accelerates single-use adoption in settings lacking reprocessing capacity.
- AI-assisted diagnostic integration:Convergence of disposable endoscopy with real-time computer vision algorithms enables premium pricing for pathology-detection workflows.
Industry Challenges
- Polymer extrusion technician scarcity:Medical device manufacturing regions in Denmark and Germany face workforce gaps in precision micro-molding for flexible endoscope shafts.
- Legacy hospital IT integration:Electronic health record systems in British NHS trusts require custom API development to accommodate disposable endoscope usage tracking and billing codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Disposable Endoscopes Market |
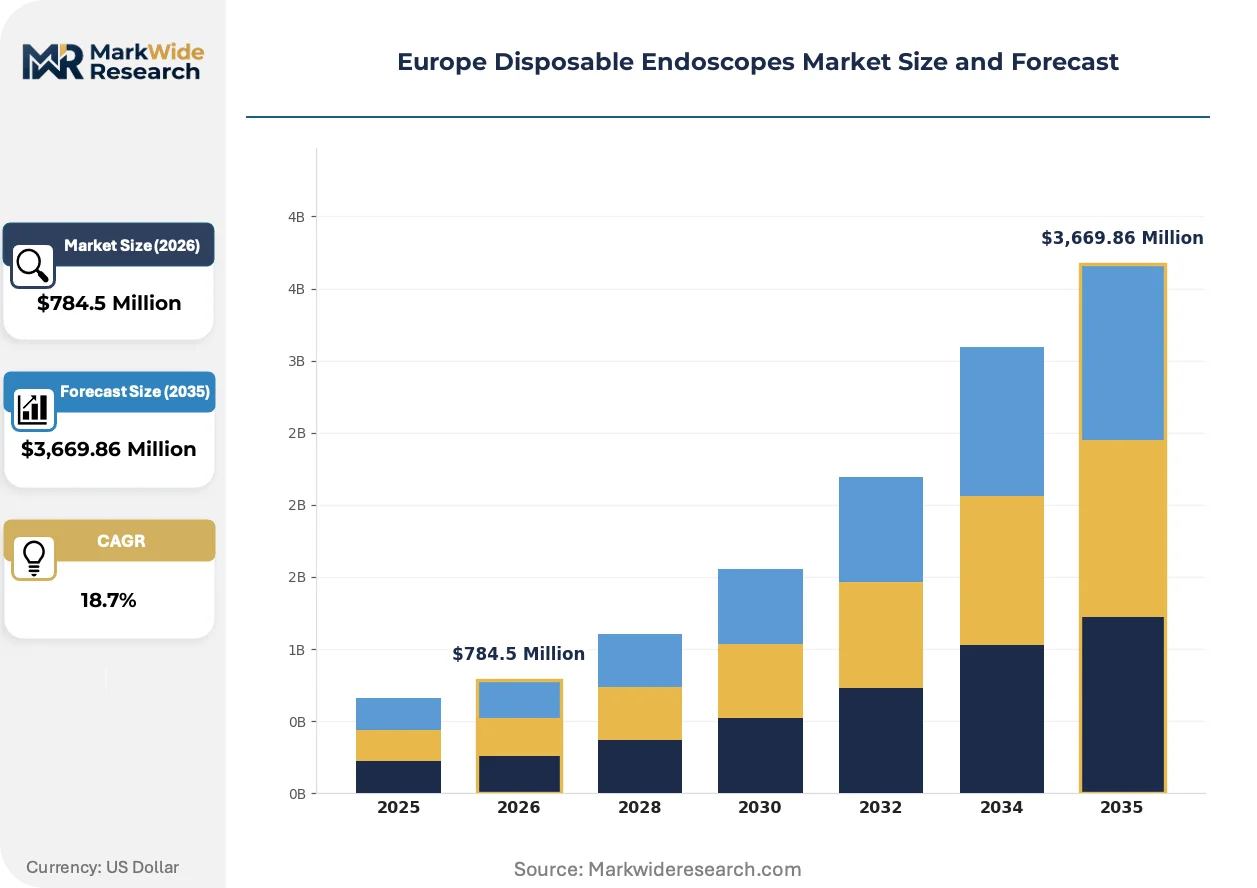
| Market Size in 2026 | $784.5 Million |
| Market Size in 2035 | $3,669.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gastrointestinal Endoscopes, Bronchoscopes, Urological Endoscopes, Laparoscopes End User: Hospitals, Surgical Centers, Clinics, Home Care Procedure Type: Diagnostic, Therapeutic, Screening, Surgical Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Fujifilm Holdings, Stryker, Olympus, Ambu, Medtronic, Boston Scientific, Karl Storz, STERIS, Pentax Medical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Disposable Endoscopes Market Strategic Shifts & Innovations
Disposable endoscope architecture is converging with semiconductor miniaturization and cloud-based image management, compressing the traditional capital equipment model into per-procedure consumption economics.
CMOS imaging sensors with integrated LED illumination are digitizing diagnostic workflows by embedding high-definition capture directly into single-use bronchoscope distal tips. German intensive care units are adopting these platforms within 18-month procurement cycles. The technology is digitizing patient data capture, eliminating the capital expenditure barrier that previously constrained smaller European hospitals from advanced pulmonary diagnostics.
The EU MDR's post-market surveillance requirements are mandating unique device identification (UDI) traceability across all sterile single-use instruments. Manufacturers must now maintain electronic records linking each disposable endoscope to patient procedure data for 10-15 years. Gastrointestinal endoscope producers face the steepest compliance investment, as their highest procedure volumes multiply data infrastructure requirements.
Hospital purchasing cooperatives in Northern Europe are consolidating tender participation into centralized digital platforms, displacing traditional manufacturer field sales relationships. Denmark's AMGROS and Norway's Sykehusinnkjøp now handle disposable endoscope procurement for 80+ facilities through standardized e-auction mechanisms. British NHS Supply Chain is piloting similar aggregation, compressing vendor margins while accelerating single-use product standardization across regional hospital groups.
Europe Disposable Endoscopes Market Segmentation
Disposable endoscope procurement patterns diverge sharply across clinical settings and distribution pathways, with after-sales service intensity varying from intensive field engineering support in hospital consortia to minimal-touch fulfillment for outpatient surgical centers. Understanding these segment boundaries clarifies where manufacturers must invest in technical service infrastructure versus streamlined logistics.
Product Type:
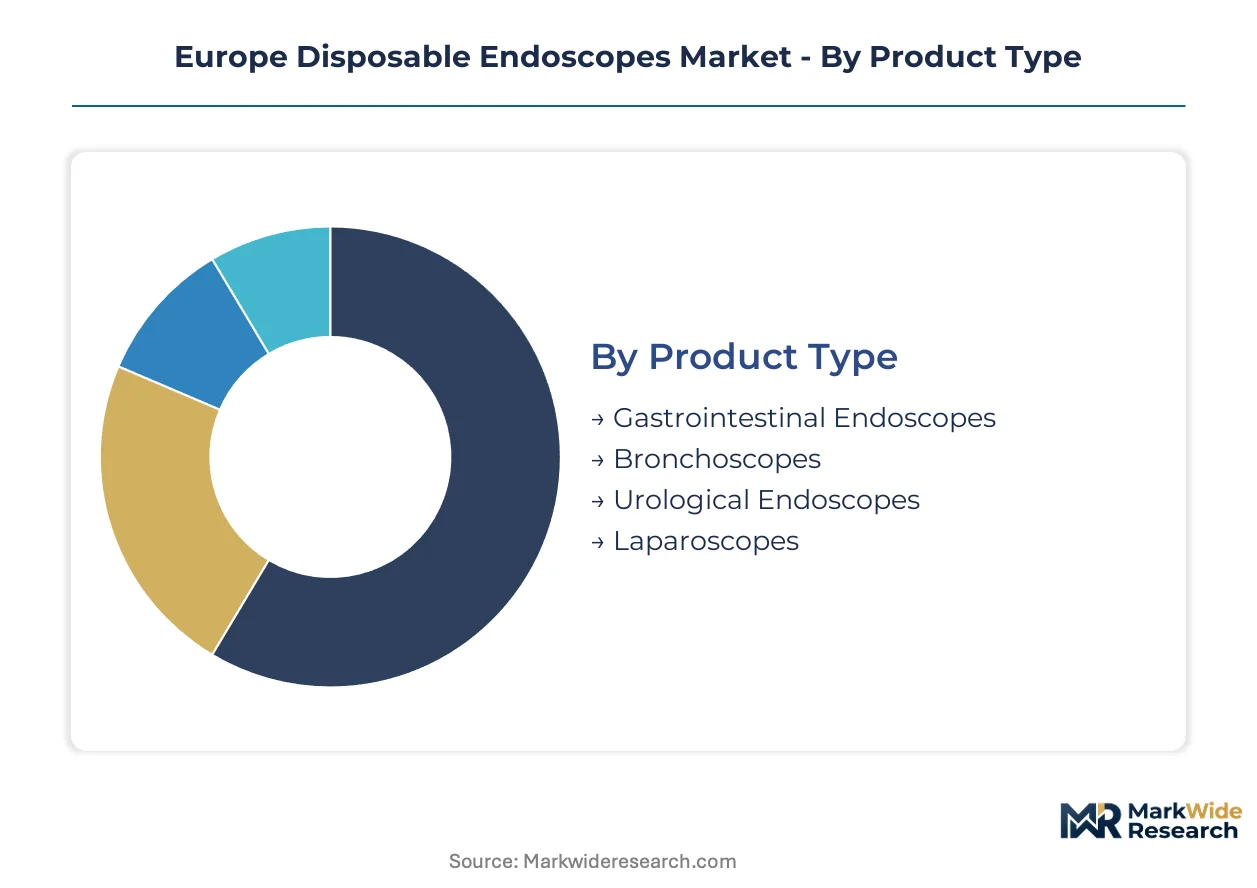
After-sales service intensity peaks with gastrointestinal endoscopes, where procedure volume and imaging complexity demand dedicated clinical application specialists and rapid replacement protocols.
- Gastrointestinal Endoscopes:These flexible instruments incorporate CMOS imaging sensors and LED illumination within polymer shafts designed for esophageal, gastric, and colonic visualization. German acute care hospitals concentrate procurement through centralized consortia, driven by EU MDR sterility mandates that eliminate reprocessing alternatives in high-volume endoscopy units.
- Bronchoscopes:Single-use pulmonary instruments feature distal-tip cameras and working channels for airway examination and specimen collection. French and Dutch intensive care units are accelerating adoption as ventilator-associated pneumonia prevention protocols mandate disposable protocols for intubated patients, creating demand concentration in tertiary respiratory centers.
- Urological Endoscopes:Cystoscopes and ureteroscopes constructed from medical-grade polymers with integrated optics for urinary tract examination. Surgical centers in France's J2-authorized ambulatory facilities drive volume.
- Laparoscopes:Rigid single-use abdominal instruments for minimally invasive surgical visualization. Eastern European hospital modernization programs in Poland and Romania represent emerging demand pockets.
Gastrointestinal endoscopes hold the largest share; momentum sits with bronchoscopes.
End User:
Cost tier stratification separates capital-rich hospital systems from budget-constrained outpatient facilities, with reimbursement pathways determining viable price points across each channel.
- Hospitals:Acute care institutions across Germany, France, and the United Kingdom anchor volume through bundled contracting and established reimbursement for single-use alternatives to reusable reprocessing.
- Surgical Centers:Ambulatory facilities lacking sterilization infrastructure capture expanding share as France's J2 authorization framework accelerates outpatient procedure migration.
- Clinics:Smaller diagnostic practices with limited capital budgets favor disposable instruments to avoid reprocessing equipment expenditure.
- Home Care:Emerging segment for portable disposable endoscopy in palliative and remote monitoring applications, currently limited by reimbursement uncertainty.
Hospitals retain the deepest margin pools; surgical centers are expanding most quickly.
Procedure Type:
Application urgency differentiates segments, with diagnostic procedures prioritizing speed and throughput while therapeutic interventions demand enhanced instrument functionality.
- Diagnostic:Visualization and biopsy procedures dominate volume across European hospital systems, with CMOS-enabled disposable platforms digitizing patient data capture.
- Therapeutic:Interventional procedures requiring working channels for tool deployment command premium pricing in specialized centers.
- Screening:Population-scale colorectal and pulmonary screening programs in Northern Europe drive standardized, high-volume procurement through cooperative purchasing platforms.
- Surgical:Operating room applications for disposable laparoscopes and advanced bronchoscopes concentrate in tertiary referral centers with complex case mixes.
Diagnostic procedures hold the largest share; therapeutic applications show the steepest expansion trajectory.
Distribution Channel:
Customer type determines channel economics, with large hospital consortia demanding direct manufacturer relationships while fragmented outpatient settings tolerate intermediary markups for convenience.
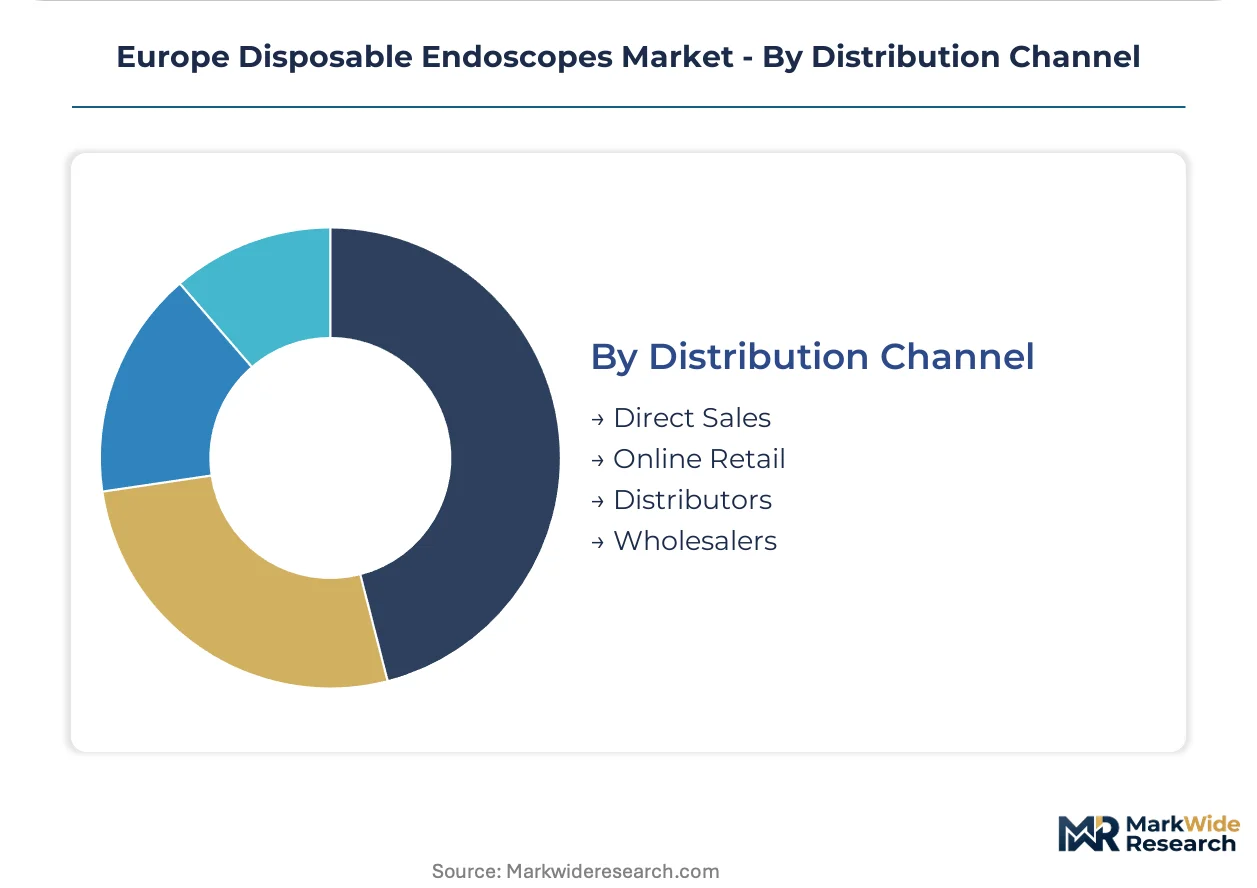
- Direct Sales:Manufacturer field teams manage relationships with hospital purchasing cooperatives in Denmark, Norway, and Germany, where centralized tender participation requires dedicated account management.
- Distributors:Regional medical device distributors serve mid-sized hospitals and clinics in Spain and Italy, where budget constraints favor reprocessing alternatives and disposable adoption lags.
- Online Retail:Digital procurement platforms are piloting for standardized disposable instruments in British NHS Supply Chain regional aggregation programs.
- Wholesalers:Bulk procurement intermediaries handle logistics for high-volume consumables in Eastern European markets with developing regulatory infrastructure.
Direct sales hold the largest share; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR's sterility mandates and national reimbursement pathways are redistributing procurement intensity across European acute care networks. Hospital purchasing cooperatives now filter market access through centralized digital platforms.
Germany
Bundled contracting through regional hospital consortia concentrates disposable endoscope procurement in Bavaria and North Rhine-Westphalia. BfArM coordinates post-market surveillance with France's ANSM, accelerating CE marking reciprocity for single-use bronchoscopes. Berlin-Brandenburg medical technology clusters house precision polymer extrusion facilities serving Danish manufacturers.
France
The J2 ambulatory surgery authorization framework drives single-use adoption in Île-de-France surgical centers lacking reprocessing infrastructure. ANSM enforces MDR sterility validation timelines that compress manufacturer certification cycles. Lyon-based purchasing cooperatives aggregate tender participation for 40+ facilities across Auvergne-Rhône-Alpes.
United Kingdom
NHS Supply Chain pilots digital procurement aggregation for standardized disposable instruments across regional hospital groups. British intensive care units mandate single-use bronchoscopes for ventilator-associated pneumonia protocols. Greater Manchester and London trusts lead contract standardization for gastrointestinal endoscope bundles.
Netherlands
Dutch intensive care networks align with French ventilator-associated pneumonia prevention standards, creating cross-border procurement coordination. The Eindhoven Region hosts CMOS sensor integration facilities supporting disposable urological instrument production. Amsterdam-based hospital purchasing platforms consolidate 80+ facility orders through e-auction mechanisms.
Poland
EU structural fund investments in Eastern European acute care infrastructure modernize Warsaw and Kraków hospital endoscopy units. National health technology assessments evaluate reimbursement expansion for single-use alternatives to reusable reprocessing. Polish distributors serve as logistics intermediaries for German manufacturers entering developing regulatory markets.
Europe Disposable Endoscopes Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: diversified medical technology conglomerates with service infrastructure depth, specialized single-use platform developers with manufacturing proximity advantages, and regional distributors with regulatory navigation expertise. Competitive positioning depends on M&A activity targeting polymer extrusion capabilities and strategic partnerships with hospital purchasing cooperatives for tender compliance.
Among diversified medical technology conglomerates, Fujifilm Holdings, Stryker, and Olympus occupy positions anchored by established service networks and capital equipment installed bases. These companies exemplify archetypes ranging from imaging-integrated platform suppliers to surgical portfolio specialists, each representing different pathways for disposable-adjacent workflow capture in high-volume European endoscopy units.
| Leading Market Players |
|---|
| Fujifilm Holdings |
| Stryker |
| Olympus |
| Ambu |
| Medtronic |
| Boston Scientific |
| Karl Storz |
| STERIS |
| Pentax Medical |
| Others |
Cost & Logistics Intelligence
Polymer feedstock volatility in Middle East petrochemical complexes determines both tier spreads for gastrointestinal endoscopes and the geographic shape of converter networks serving European manufacturers. German hospital consortia exploit this concentration to extract volume discounts while Danish producers absorb margin compression through captive extrusion capacity.
Pricing Analysis
Certification level (MDR/CE-grade versus transitional legacy marking) creates the primary spread between premium bronchoscopes and standard urological instruments. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and field engineering support depth. Cost compression in economy tiers is intensifying because Dutch and British purchasing cooperatives standardize procurement through e-auction mechanisms. Surgical centers in France's J2-authorized facilities exhibit highest price sensitivity; German acute care hospitals with bundled contracts show least.
Supply Chain Analysis
Dual-use technology export controls on advanced CMOS imaging sensors limit flows from Eindhoven Region facilities to non-EU assembly partners. Medical-grade polypropylene and polycarbonate supply concentrates in Saudi Arabia, Germany, and Belgium, while CMOS sensor integration feeds from Dutch semiconductor fabs. Single-source vulnerability sits with Middle East polymer complexes exposed to regional logistics disruptions. Distribution runs through hospital purchasing cooperatives in Northern Europe and regional distributors in Southern and Eastern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision polymer extrusion technician scarcity in Denmark and Germany constrains capacity expansion regardless of capital availability, making workforce development the binding constraint for supply-side growth.
For Market Incumbents: Insulate service infrastructure advantages by embedding clinical application specialists within German hospital consortia before procurement platforms disintermediate field relationships. Pursue backward integration into polymer extrusion capabilities in Berlin-Brandenburg medical technology clusters to reduce Middle East feedstock exposure. MDR certification investment represents the critical lever against emerging single-use platform developers lacking notified body relationships. For New Entrants and Emerging Players: Build out reimbursement strategy capabilities targeting Poland and Romania hospital modernization programs where EU structural funds create procurement windows before incumbent platform lock-in. Poland's developing regulatory infrastructure offers the most penetrable geography for first-mover disposable platform suppliers. Partner with Warsaw-based distributors for logistics coverage rather than direct sales investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized single-use platform developers with manufacturing proximity to Nordic purchasing cooperatives. Long-term viability across the analysis window hinges on MDR certification throughput and hospital purchasing cooperative tender compliance rather than pure technology differentiation. Acquisition target archetype: Danish or German precision polymer extrusion specialists with medical device qualifications. Watch notified body capacity expansion at TÜV SÜD and BSI as inflection indicator for new entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | Accelerated CE marking at TÜV SÜD unlocks German hospital consortium access before competitors complete validation. |
| Hospital System Partnership | Direct integration with Denmark's AMGROS purchasing cooperative secures 80+ facility procurement aggregation. |
| Backward Integration into Polymer Extrusion | Captive medical-grade polymer shaft production in Berlin-Brandenburg clusters insulates against Middle East feedstock volatility. |
| Software Companion Development | AI-assisted diagnostic algorithms for real-time pathology detection enable premium pricing in high-volume endoscopy units. |
| Reimbursement Strategy | Polish health technology assessment alignment positions single-use alternatives for EU structural fund hospital modernization. |
Research Approach
Desk research of EU MDR guidance documents, notified body certification databases, and hospital procurement tender records preceded structured interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and precision polymer extrusion facility operators. Primary fieldwork across German, French, and British acute care networks was cross-validated against secondary data from BfArM post-market surveillance reports, ANSM sterility validation guidelines, and NHS Supply Chain aggregation pilots. Bottom-up procedure volume estimates were triangulated with top-down manufacturer shipment data.
The analytical framework held MDR implementation timelines and notified body capacity constraints fixed across the projection horizon while varying national reimbursement pathway expansion assumptions. Segmentation dimensions modeled include product type, end user facility tier, procedure urgency classification, and distribution channel structure. CAGRs were derived from logistic adoption curves fitted to single-use protocol penetration rates in intensive care and endoscopy units. Industry-specific inputs incorporated polymer feedstock price indices and CMOS sensor cost compression trajectories from semiconductor manufacturing scale.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified medical technology conglomerates would shift outcomes through accelerated polymer extrusion capture. Material shifts in EU MDR enforcement intensity or notified body certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Duodenoscope Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Non-Invasive Colon Cancer Screening Market