
 Vietnam Insulin Drug and Delivery Device Market | 2026-2036
Vietnam Insulin Drug and Delivery Device Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Insulin Drug and Delivery Device Market Insights
Hospital procurement departments are reorganizing insulin purchasing protocols as home care and clinic-based diabetes management gain share alongside traditional inpatient channels. Novo Nordisk leverages its biosynthetic insulin portfolio to sustain dominance in Vietnam's public tender system. Sanofi competes through differentiated glargine formulations and established relationships with provincial health departments. Eli Lilly anchors its position via concentrated insulin products and partnerships with local distributors reaching secondary cities.
Vietnam Insulin Drug and Delivery Device encompasses recombinant human and analog insulin formulations packaged with mechanical or electronic delivery systems for controlled subcutaneous administration, typically requiring refrigeration at two to eight degrees Celsius and precise unit dosing calibrated to patient glycemic profiles. Insulin pens dominate current volumes due to physician familiarity and patient portability, while smart injectors and connected devices represent the fastest-expanding technology tier as Vietnamese healthcare providers seek remote monitoring capabilities. Manual devices retain substantial share in rural provinces where cost sensitivity limits connected device penetration.
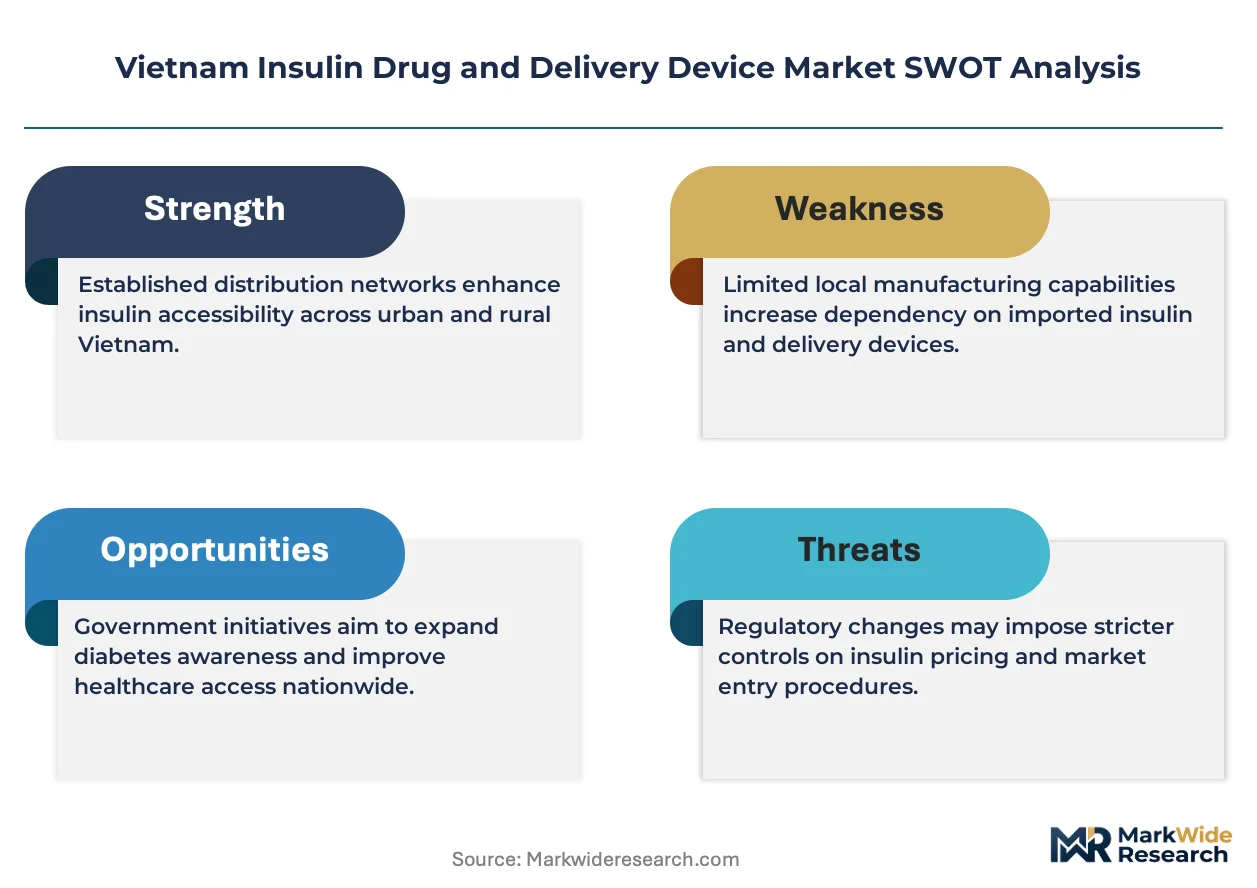
Vietnam's Ministry of Health and the Drug Administration of Vietnam regulate insulin as essential medicines subject to price controls and import licensing, while the country's national pharmaceutical regulator oversees medical device registration under ASEAN harmonized standards. CDSCO-aligned pharmacovigilance requirements and local clinical trial data mandates shape market access timelines for new insulin analogs. Stakeholders must monitor reimbursement list revisions and provincial tender consolidation to anticipate volume shifts between public hospital and private channel procurement.
Market Dynamics
Hospital procurement consolidation across Vietnam's provincial health networks is compressing supplier margins while elevating volume concentration in Ho Chi Minh City and Hanoi. The Drug Administration of Vietnam's tightened import licensing timelines are forcing distributors to restructure inventory positions.
Growth Catalysts
- Essential Medicines Classification:The Ministry of Health's circulars mandate insulin inclusion on provincial reimbursement lists, guaranteeing public hospital volumes and reducing patient out-of-pocket exposure in tier-two cities.
- Connected Delivery Platforms:Bluetooth-enabled pens with dose-logging capabilities are penetrating endocrinology clinics seeking remote glycemic monitoring for dispersed rural patients.
- Provincial Tender Consolidation:Centralized procurement across Mekong Delta provinces is aggregating demand pools that previously fragmented across district hospitals.
Market Restraints
- Cold Chain Infrastructure Gaps:Temperature excursions during last-mile distribution to Central Highlands provinces degrade insulin potency and trigger wastage claims against distributors.
- Import Dependency Concentration:Active pharmaceutical ingredient sourcing concentrates among three global fermentation suppliers, exposing Vietnam formulators to freight cost volatility and currency fluctuation.
- Substitution Limitations:Oral GLP-1 agonists remain unavailable through Vietnam's registration pathway, blocking physicians from deploying non-insulin alternatives for type 2 progression.
Strategic Opportunities
- Central Coast Underpenetration:Da Nang and Hue hospital networks maintain lower insulin prescribing intensity per capita than southern counterparts, presenting whitespace for specialist endocrinology investment.
- Public-Private Partnership Models:Provincial health departments are piloting risk-sharing arrangements where device manufacturers deploy connected pens in exchange for multi-year exclusive supply contracts.
- Telemedicine Integration:Remote consultation platforms are creating parallel prescription channels that bypass traditional hospital pharmacy gatekeepers in remote northern provinces.
Industry Challenges
- Specialized Pharmacy Staffing:Certified diabetes educators remain scarce outside Hanoi and Ho Chi Minh City, limiting patient training on advanced delivery device features.
- Registration Timeline Compression:CDSCO-aligned pharmacovigilance submissions for new insulin analogs extend market access timelines by 18-24 months versus comparator markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Insulin Drug and Delivery Device Market |
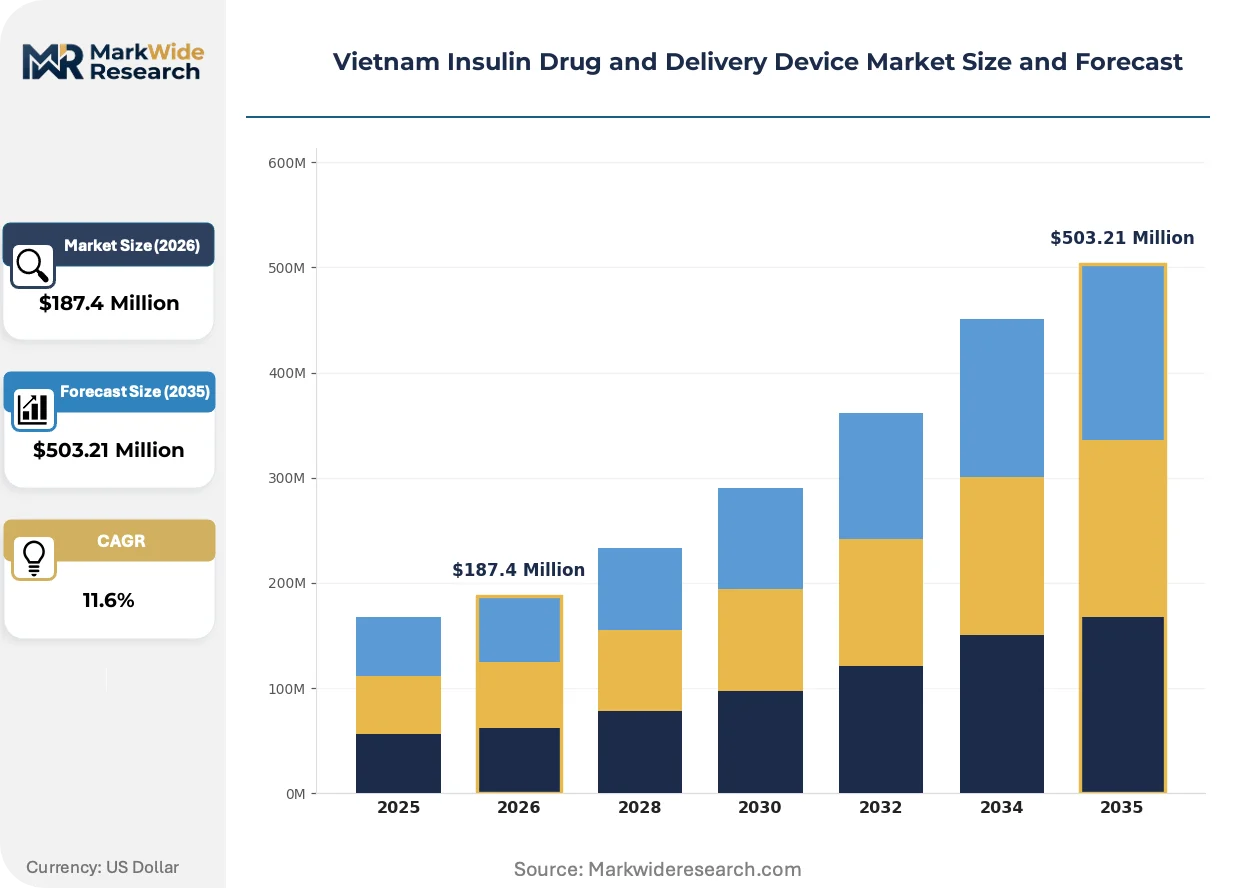
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pen, Insulin Pump, Vial, Pre-filled Syringe Administration Method: Subcutaneous Injection, Intravenous Injection, Inhalation, Transdermal Delivery Device Technology: Smart Injector, Wearable Device, Manual Device, Connected Device End User: Hospitals, Home Care, Pharmacies, Clinics |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly, Medtronic, Roche, Takeda, Pfizer, Janssen Pharmaceuticals, Astellas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Insulin Drug and Delivery Device Market Trends and Innovations
Device connectivity and data integration are displacing standalone mechanical delivery systems across Vietnam's specialist clinic networks. Manufacturers are repositioning around software-enabled adherence tracking rather than hardware differentiation alone.
Smart injector platforms with embedded dose sensors and smartphone synchronization are fragmenting the traditional pen market into connected and non-connected tiers. Endocrinology centers in Ho Chi Minh City are adopting these devices for patient cohorts requiring intensive insulin titration. The technology is fragmenting purchasing authority between hospital pharmacy departments and newly formed digital health procurement committees.
The Drug Administration of Vietnam's alignment with ASEAN MDR harmonization is compressing technical documentation requirements for Class B and C delivery devices. Local distributors are accelerating registration submissions to capture first-mover positioning ahead of provincial tender windows. Pen manufacturers with existing ISO 13485 certifications are adapting quality management systems to satisfy the streamlined pathway.
Specialist clinics are unbundling device procurement from insulin vial contracts, separating hardware purchasing from pharmaceutical supply agreements. Private hospital chains in Hanoi are negotiating direct device sourcing while maintaining insulin volume commitments with established distributors. This pattern is most visible in the northern Red River Delta corridor where hospital groups operate centralized procurement functions.
Vietnam Insulin Drug and Delivery Device Market Segmentation
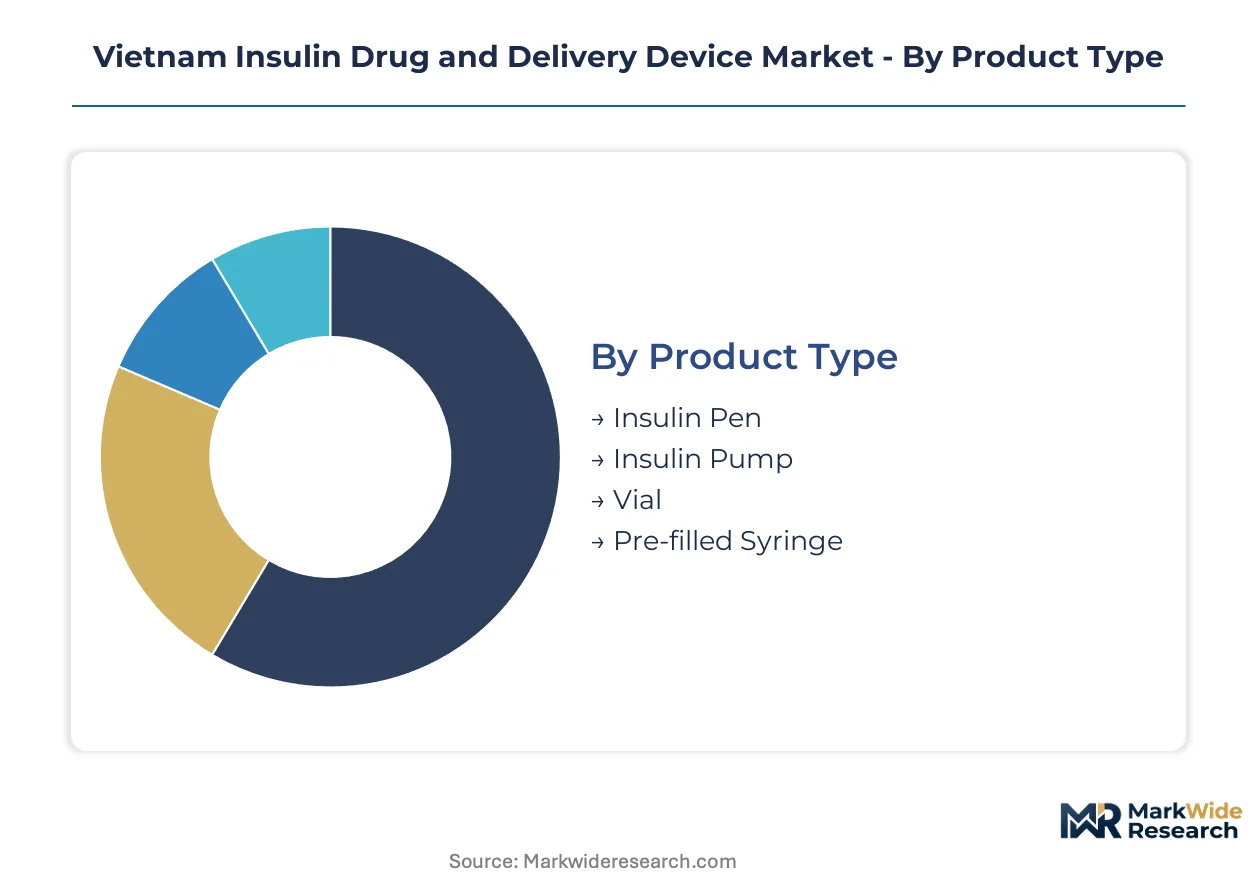
Insulin delivery in Vietnam fragments across four distinct axes that reshape procurement authority and margin capture. Product type determines cold chain investment intensity, while device technology separates premium-connected hardware from commodity mechanical alternatives. Administration method and end user channel further stratify pricing power between hospital tenders and retail pharmacy networks.
Product Type:
Margin pools concentrate in portable delivery systems that reduce patient training burden and minimize pharmacy inventory complexity.
- Insulin Pen:Reusable and disposable pen systems combine cartridge-based insulin reservoirs with calibrated dosing mechanisms. Demand clusters in Ho Chi Minh City and Hanoi endocrinology clinics where physician familiarity drives prescribing preference. Provincial tender consolidation is elevating volume concentration for disposable variants.
- Insulin Pump:Continuous subcutaneous infusion devices with programmable basal-bolus algorithms. Adoption concentrates in private hospital chains offering intensive diabetes management programs; reimbursement gaps limit penetration in public tier-two facilities.
- Vial:Traditional glass containers requiring syringe-based extraction. Rural provinces with cost-sensitive procurement maintain substantial volumes despite portability disadvantages.
- Pre-filled Syringe:Single-use devices with fixed insulin doses eliminating patient calibration. Pharmacies in Central Highlands provinces stock these for patients lacking manual dexterity for pen operation.
Insulin pens hold installed capacity. Insulin pumps are rotating up the share rankings.
Administration Method:
Volume distribution follows patient glycemic control requirements and clinical setting infrastructure availability.
- Subcutaneous Injection:Abdominal or thigh tissue deposition via pen, pump, or syringe. Home care channels in Mekong Delta provinces favor this method for its minimal training requirements.
- Intravenous Injection:Hospital-only delivery for diabetic ketoacidosis and perioperative glycemic management. Intensive care units in Hanoi academic medical centers anchor demand.
- Inhalation:Pulmonary insulin absorption eliminating needle dependency. The Drug Administration of Vietnam's registration pathway gaps block commercial availability despite global approval status.
- Transdermal Delivery:Microneedle patch systems in early clinical evaluation. No current procurement volume exists pending local efficacy trials.
Subcutaneous injection dominates current prescribing. Inhalation represents the steepest expansion trajectory contingent on regulatory pathway opening.
Device Technology:
Premium capture concentrates in connectivity-enabled platforms that generate recurring software revenue streams.
- Smart Injector:Pens with embedded sensors logging dose timing and volume to smartphone applications. Endocrinology centers in Ho Chi Minh City deploy these for remote rural patient monitoring.
- Wearable Device:Patch pumps and continuous glucose monitor-integrated systems. Private hospital chains pilot these in risk-sharing arrangements with device manufacturers.
- Manual Device:Mechanical pens and syringes without electronic components. Central Highlands and northern mountainous provinces maintain procurement concentration due to price sensitivity.
- Connected Device:Bluetooth-enabled platforms with cloud-based adherence analytics. Digital health procurement committees in Red River Delta hospital groups are separating these from pharmaceutical contracts.
Manual devices retain volume leadership. Smart injectors are climbing the fastest as telemedicine integration accelerates.
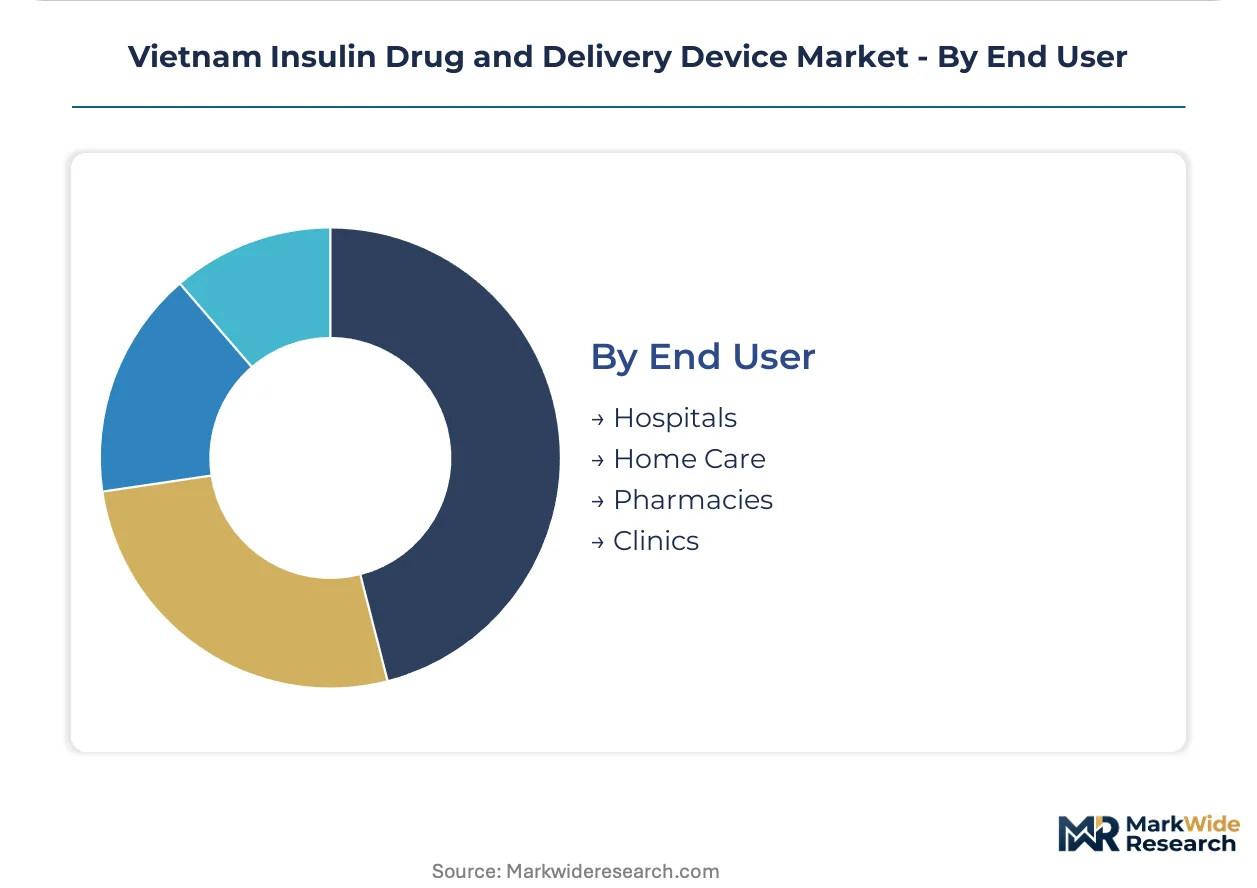
End User:
Channel margins diverge between consolidated hospital tenders and fragmented retail pharmacy networks.
- Hospitals:Public and private acute care facilities with centralized pharmacy operations. Provincial health department tender consolidation is compressing supplier margins while elevating volume concentration.
- Home Care:Patient-managed delivery outside clinical settings. Da Nang and Hue networks show lower per-capita prescribing intensity than southern counterparts, presenting whitespace.
- Pharmacies:Community and hospital outpatient dispensaries with direct patient interaction. Certified diabetes educator scarcity limits advanced device feature training outside major cities.
- Clinics:Specialist endocrinology and primary care facilities. Telemedicine platforms are creating parallel prescription channels bypassing traditional pharmacy gatekeepers in remote northern provinces.
Hospitals anchor procurement volume. Home care is gaining share fastest as remote monitoring platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cai Mep-Thi Vai deep-water port complex anchors Vietnam's cold chain pharmaceutical distribution, enabling temperature-controlled insulin imports from European and Asian fermentation hubs to reach provincial health networks within 48 hours.
Ho Chi Minh City
Cho Ray Hospital and University Medical Center anchor insulin prescribing volumes across the southern economic corridor. The Ministry of Health's Circular 05/2021 on essential medicines procurement mandates public hospital tender participation. District 5 pharmaceutical wholesale clusters concentrate cold chain logistics capacity serving Mekong Delta provinces.
Hanoi
Bach Mai Hospital and Viet Duc University Hospital drive northern region endocrinology referrals and insulin initiation protocols. Drug Administration of Vietnam registration requirements for Class C medical devices shape product availability timelines. Cau Giay district hosts distributor headquarters coordinating Red River Delta provincial tenders.
Da Nang
Da Nang Hospital and Hoan My Medical Corporation facilities show lower per-capita insulin prescribing intensity than southern counterparts. Provincial health department pilot programs for connected delivery device deployment target this whitespace. The city sits at the midpoint of the North-South expressway pharmaceutical distribution corridor.
Hue
Hue Central Hospital serves as the northern Central Highlands referral hub for complex diabetes management. Limited certified diabetes educator staffing constrains advanced device feature training outside major endocrinology departments. The Perfume River corridor hosts emerging private clinic networks exploring telemedicine-integrated prescription channels.
Can Tho
Can Tho University Hospital anchors Mekong Delta diabetes care with catchment extending to Ca Mau and An Giang provinces. Provincial tender consolidation across southwestern provinces aggregates previously fragmented district hospital demand. The Hau River port facilities support last-mile cold chain distribution to riverine communities.
Vietnam Insulin Drug and Delivery Device Market Competitive Landscape
Listed leaders compete with private specialists across tender participation and specialty clinic channel access. The vendor base clusters around three strategic tiers: multinational pharmaceutical conglomerates with biosynthetic fermentation capacity, diversified medical technology conglomerates with device manufacturing scale, and regional distribution specialists with provincial health department relationships. Archetypes include integrated insulin-device bundlers, standalone delivery system innovators, and pure-play formulation suppliers. Competitive moves concentrate on provincial tender consolidation responses and risk-sharing partnership structures with hospital chains.
Among integrated pharmaceutical-device bundlers, Novo Nordisk, Sanofi, and Eli Lilly exemplify archetypes spanning biosynthetic insulin production through connected delivery platform deployment. Novo Nordisk occupies a position reflecting Danish fermentation heritage and pen system standardization. Sanofi sits within the diversified European healthcare conglomerate structure with glargine formulation specialization. Eli Lilly anchors the concentrated insulin product category through Indianapolis-based research lineage. These three entities represent distinct approaches to public tender system navigation and private hospital chain relationship cultivation.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly |
| Medtronic |
| Roche |
| Takeda |
| Pfizer |
| Janssen Pharmaceuticals |
| Astellas |
| Others |
Pricing and Supply Chain Analysis
Forty-eight-to-seventy-two-hour cold chain lead times from European fermentation hubs to Mekong Delta district hospitals compress distributor margins while elevating procurement concentration in Ho Chi Minh City and Hanoi. This inventory velocity concentrates pricing power among incumbents with captive logistics networks, forcing provincial tender participants to absorb temperature excursion risks or cede volume to integrated suppliers.
Pricing Analysis
Volume-discount tiering structures separate multinational insulin suppliers with biosynthetic fermentation capacity from local distributors competing on provincial tender participation. Pricing stratifies across premium connected-pen systems, standard disposable pen contracts, and economy vial-syringe bundles serving Central Highlands cost-sensitive procurement. Cost compression in the economy tier is intensifying because provincial health departments are consolidating previously fragmented district hospital demand pools. Public hospital pharmacy departments exhibit highest price sensitivity, while private hospital chains in Hanoi demonstrate willingness to pay connectivity premiums for remote monitoring capabilities.
Supply Chain Analysis
Denmark, France, and the United States anchor active pharmaceutical ingredient production for Vietnam's insulin market through biosynthetic fermentation and analog formulation expertise. Finished dosage forms and delivery device components draw from Chinese injection molding capacity, German precision engineering for pen mechanisms, and Japanese sensor technology for connected platforms. Single-source vulnerability concentrates in active pharmaceutical ingredient sourcing among three global fermentation suppliers, exposing Vietnamese formulators to freight cost volatility and currency fluctuation. Distribution runs through Cai Mep-Thi Vai deep-water port cold chain facilities to provincial health department warehouses, with last-mile delivery to district hospitals and retail pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's insulin market sits in cyclical recovery as provincial tender consolidation drives volume concentration toward integrated suppliers with captive cold chain infrastructure. Hospital procurement reorganization following Ministry of Health circulars on essential medicines creates cyclical margin pressure that favors scaled incumbents.
For Market Incumbents: Secure multi-year exclusive supply contracts with provincial health departments piloting public-private partnership risk-sharing arrangements for connected delivery device deployment. Deepen backward integration into cold chain logistics serving Central Highlands and northern mountainous provinces where temperature excursion claims erode distributor margins. Counter emerging telemedicine-integrated prescription channels by embedding software-enabled adherence tracking into existing pen system installed bases. For New Entrants and Emerging Players: ASEAN MDR harmonization fast-track pathways compress technical documentation requirements for Class B and C delivery devices, enabling first-mover positioning ahead of provincial tender windows. Target Da Nang and Hue hospital networks showing lower per-capita insulin prescribing intensity than southern counterparts, where specialist endocrinology investment presents whitespace. Enter through unbundled device procurement contracts separating hardware purchasing from pharmaceutical supply agreements with private hospital chains in the Red River Delta corridor. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because provincial tender aggregation will compress supplier margins and elevate volume concentration among three to four integrated insulin-device bundlers with fermentation capacity and Vietnamese regulatory expertise. Acquisition target archetypes include regional distribution specialists with established provincial health department relationships and ISO 13485-certified device manufacturers adapting quality management systems to ASEAN MDR alignment. Signal to monitor: Drug Administration of Vietnam reimbursement list revisions that shift volume between public hospital and private channel procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Provincial Tender Consolidation Response | Aggregates fragmented district hospital demand pools across Mekong Delta provinces into centralized procurement. |
| Connected Device Risk-Sharing Partnership | Deploys Bluetooth-enabled pens in exchange for multi-year exclusive supply contracts with hospital chains. |
| ASEAN MDR Harmonization Fast-Track | Accelerates Class B and C medical device registration timelines ahead of provincial tender windows. |
| Telemedicine Platform Integration | Creates parallel prescription channels bypassing traditional hospital pharmacy gatekeepers in remote northern provinces. |
| Certified Diabetes Educator Training Investment | Addresses staffing scarcity constraining advanced device feature adoption outside Hanoi and Ho Chi Minh City. |
Research Methodology
A standing panel of hospital procurement managers, provincial health department tender administrators, endocrinology clinic directors, and cold chain logistics specialists provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against Drug Administration of Vietnam registration filings, Ministry of Health essential medicines circulars, hospital procurement databases, and ASEAN MDR harmonization documentation. Bottom-up volume modeling across product type, device technology, administration method, and end user segments triangulated against top-down market sizing from import licensing records and distributor revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including provincial tender award announcements, hospital pharmacy inventory disclosures, and cold chain logistics capacity utilization reports. The analytical framework modeled segmentation dimensions spanning insulin formulation type, delivery device technology tier, administration method, and end user channel across the projection horizon. CAGRs derived from trend extrapolation of historical procurement volumes adjusted for penetration assumptions of connected devices and telemedicine-integrated prescription channels. Forecast inputs incorporated Drug Administration of Vietnam registration timeline assumptions and Ministry of Health reimbursement list revision cycles.
The analysis sits within stated boundaries; outcomes outside sustained provincial tender consolidation, stable ASEAN MDR harmonization implementation, and continued essential medicines classification would require recalibration. Forecasts reflect assumptions regarding cold chain infrastructure investment, certified diabetes educator staffing expansion, and telemedicine platform regulatory clarity. Specific risk factors that could revise projections include Drug Administration of Vietnam import licensing delays, active pharmaceutical ingredient supply disruptions, and oral GLP-1 agonist registration pathway openings. Recalibration cycles align with material shifts in provincial procurement consolidation patterns, reimbursement list revisions, and connected device adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Latin America Insulin Infusion Pump Market