
 Global Electronic Stethoscope Market | 2026-2036
Global Electronic Stethoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Stethoscope Market Foresight
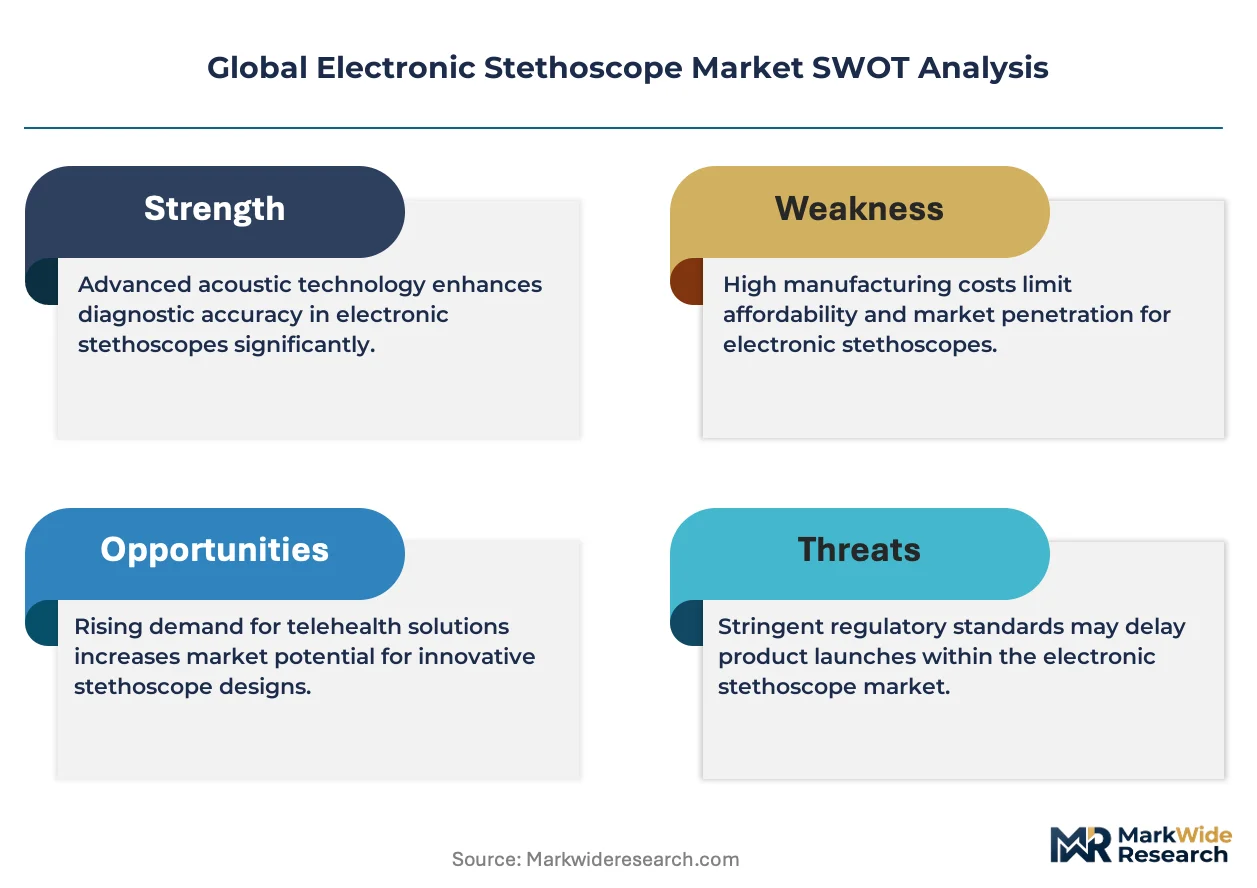
The EU MDR is expanding pre-market clinical evidence requirements for acoustic medical devices, compelling manufacturers to invest in controlled validation studies. 3M Littmann leverages its acoustic sensor R&D pipeline to sustain premium positioning across hospital procurement channels. Eko Health differentiates through AI-augmented auscultation software that anchors its telemedicine partnerships. Thinklabs Medical specializes in high-fidelity digital signal processing, occupying a niche among research laboratories demanding raw waveform capture.
An electronic stethoscope converts acoustic body sounds into electrical signals via piezoelectric or microphone-based sensors, with digital amplification, noise filtering, and Bluetooth transmission enabling remote diagnosis and spectral analysis for clinical decision support. Bluetooth-enabled stethoscopes lead product type revenue as healthcare systems prioritize wireless integration with electronic health records and telehealth platforms. The telemedicine application segment commands widening margin pools as reimbursement frameworks in multiple countries formalize remote auscultation billing codes. Acoustic sensor technology dominates unit volume while piezoelectric variants capture premium pricing in cardiology settings demanding superior low-frequency response.
FDA 510(k) clearance pathways shape US market entry timelines, while EU MDR technical documentation requirements extend conformity assessment durations for acoustic performance claims. Japan's PMDA enforces JIS-compliant electromagnetic compatibility standards that filter out lower-tier manufacturers lacking in-house testing facilities. Stakeholders must monitor evolving reimbursement eligibility for remote patient monitoring codes that determine whether telehealth providers absorb device costs or pass them to health systems.
Market Dynamics
Telehealth reimbursement formalization is compressing procurement cycles for Bluetooth-enabled auscultation devices, forcing manufacturers to align acoustic validation timelines with health system EHR integration roadmaps.
Growth Catalysts
- EU MDR acoustic performance mandates:Tighter pre-market clinical evidence requirements for Class IIa medical devices are filtering out non-compliant suppliers and consolidating procurement toward validated manufacturers.
- Remote patient monitoring billing codes:Formalized reimbursement frameworks in Germany, the United States, and Japan enable health systems to absorb device costs rather than passing them to physicians.
- Piezoelectric sensor advancement:Superior low-frequency response characteristics are displacing microphone-based alternatives in cardiology departments demanding precise murmur detection.
Market Restraints
- EU MDR conformity assessment duration:Extended technical documentation timelines for acoustic performance claims delay market entry by 12-18 months relative to legacy Medical Device Directive pathways.
- Electromagnetic compatibility testing concentration:Japan's PMDA JIS-compliant EMC standards require in-house testing facilities that filter out lower-tier manufacturers lacking capital-intensive anechoic chambers.
- Disposable acoustic diaphragm substitution:Single-use traditional stethoscopes retain cost advantage in infectious disease wards prioritizing contamination control over digital feature sets.
Strategic Opportunities
- India's tertiary hospital digitization:Government hospital infrastructure programs create first-mover advantage for Bluetooth-integrated devices aligned with national telemedicine guidelines.
- AI-augmented spectral analysis convergence:Machine learning pattern recognition for heart murmur classification is expanding into primary care settings lacking specialist cardiology coverage.
- Raw waveform research licensing:Academic medical centers in the United States and Germany seek unprocessed digital signal access for algorithm development partnerships.
Industry Challenges
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel acoustic sensor configurations require extensive comparative testing against legacy Littmann digital submissions.
- Legacy EHR integration complexity:Health system procurement committees prioritize HL7 FHIR compatibility, forcing middleware development for stethoscopes lacking native interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Stethoscope Market |
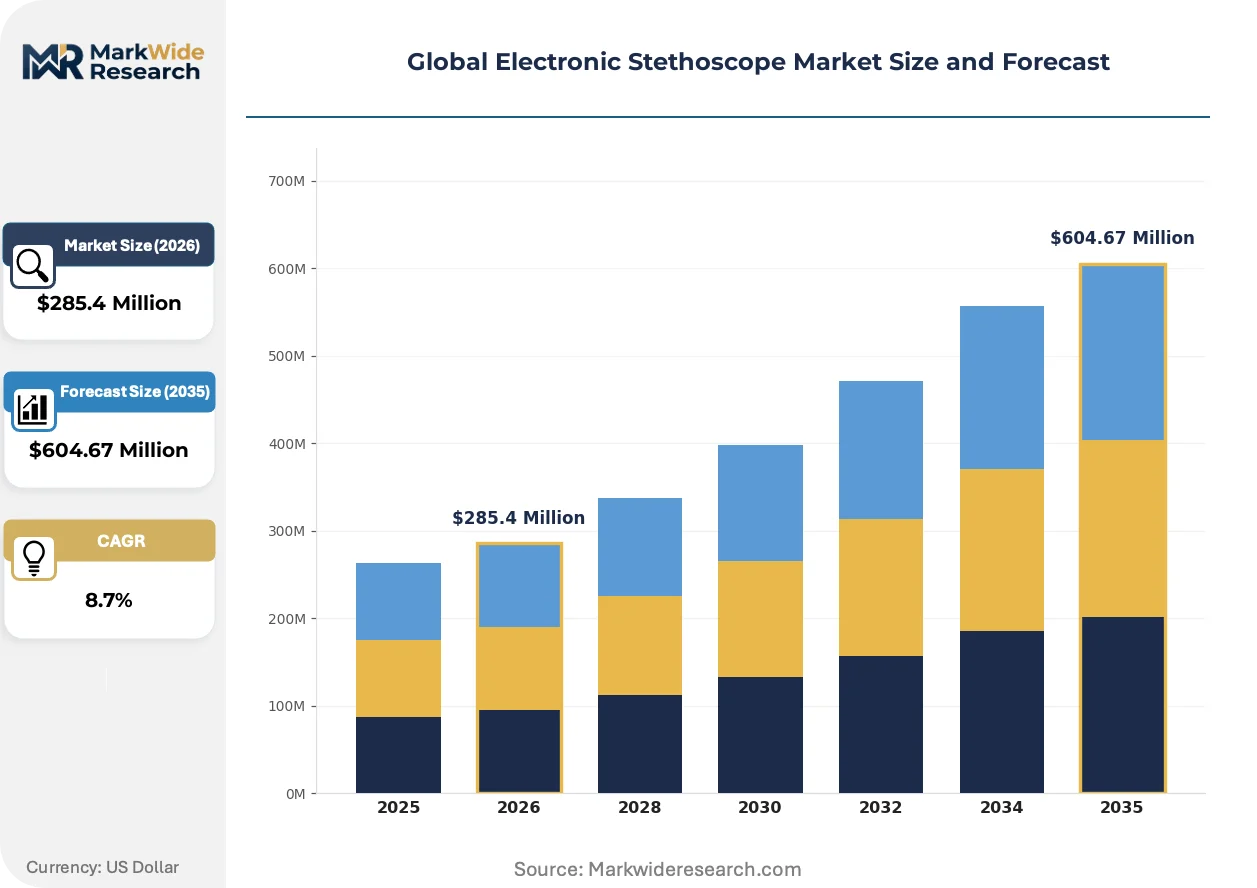
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stethoscope, Bluetooth-enabled Stethoscope, Wireless Stethoscope, Traditional Electronic Stethoscope Application: Cardiology, Pulmonology, Veterinary, Pediatrics, Telemedicine End User: Clinics, Diagnostic Centers, Research Laboratories, Telehealth Providers Technology: Acoustic Sensors, Piezoelectric Sensors, Microphone-based Sensors, Bluetooth Connectivity |
| Companies Covered | 3M Littmann, Eko Health, Thinklabs Medical, American Diagnostic Corporation, Welch Allyn, Cardionics, HD Medical, eKuore, Contec Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Stethoscope Market Shifts & Advancements
Acoustic sensor digitization is compressing the boundary between diagnostic hardware and clinical decision support software, with spectral analysis capabilities migrating from specialist cardiology suites toward generalist point-of-care settings.
Piezoelectric transducer arrays with multi-frequency response tuning are expanding into emergency medicine and primary care workflows. Rural health networks in the United States and Japan are adopting these devices to enable remote specialist consultation without patient transport. The technology is expanding into subscription-based service models where hardware margins compress in favor of recurring software licensing revenue.
Japan's PMDA revised electromagnetic compatibility standards for wireless medical devices are extending pre-market testing timelines. Manufacturers must demonstrate JIS-compliant shielding against 5G base station interference in dense urban hospital environments. Cardiology-focused suppliers with existing Tokyo testing partnerships are accelerating certification relative to entrants dependent on third-party laboratories.
Hospital procurement committees are consolidating vendor relationships around integrated telehealth platforms rather than standalone devices. Health systems in Germany and the United States now require Bluetooth stethoscopes to ship with pre-configured EHR connectivity, displacing point-solution vendors lacking enterprise software partnerships. This preference shift concentrates contract awards toward suppliers with established health information technology alliances.
Global Electronic Stethoscope Market Segmentation
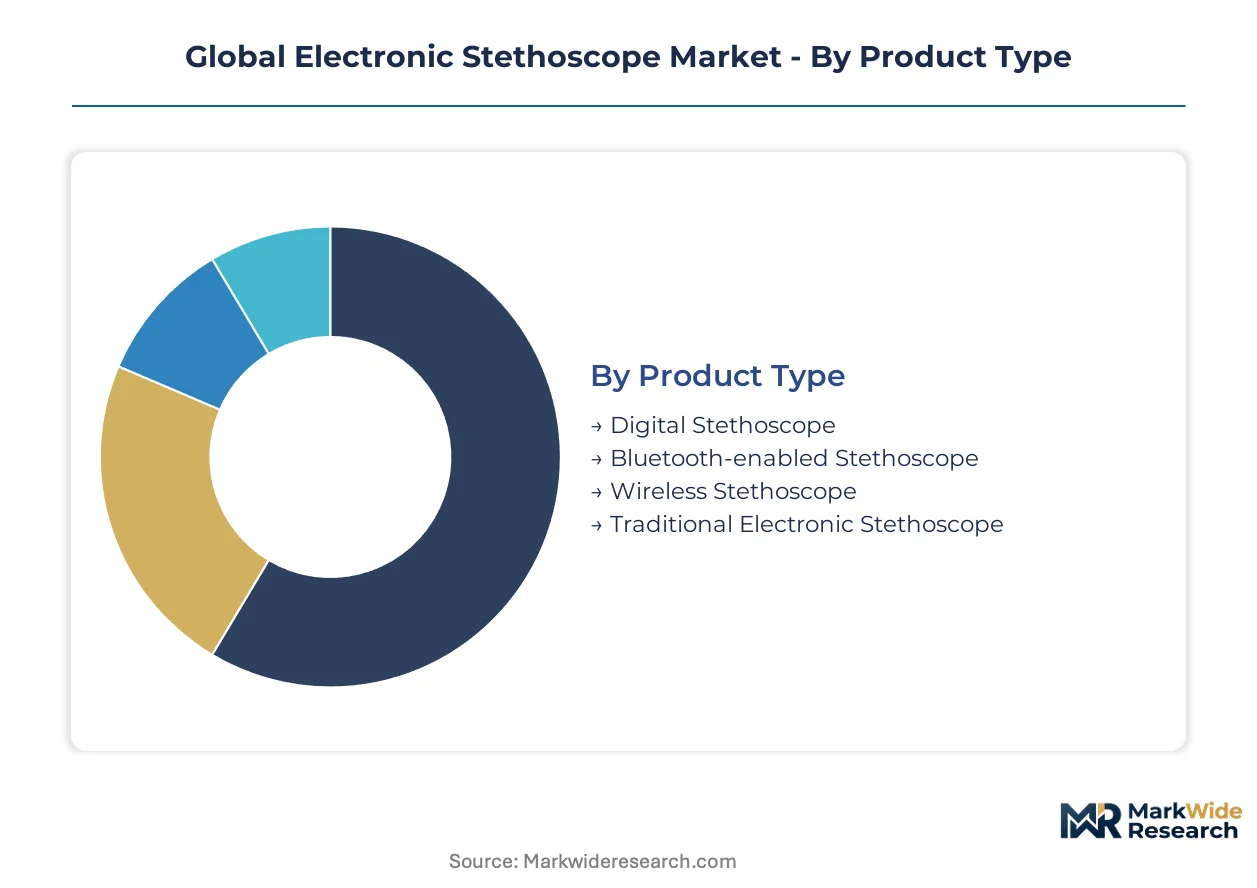
Electronic stethoscope segmentation reveals divergent technology maturities across clinical settings. Procurement committees prioritize wireless integration capabilities while research laboratories demand raw signal fidelity. Understanding these axes clarifies where hardware margins compress versus where software licensing revenue accumulates.
Product Type:
Bluetooth integration capabilities separate enterprise-ready devices from legacy electronic formats.
- Bluetooth-enabled Stethoscope:Wireless transmission protocols enable seamless EHR integration and real-time specialist consultation. Hospital procurement in Germany, the United States, and Japan concentrates here as telehealth reimbursement frameworks formalize remote auscultation billing.
- Digital Stethoscope:Onboard amplification and noise filtering circuitry without wireless transmission suits cost-conscious clinics. Demand clusters in India's tertiary hospital digitization programs where national telemedicine guidelines prioritize affordable baseline connectivity.
- Wireless Stethoscope:Proprietary radio frequency or Wi-Fi connectivity targets specialized telemetry applications.
- Traditional Electronic Stethoscope:Wired amplification without digital signal processing retains presence in veterinary and educational settings.
Mature deployment sits with Traditional Electronic Stethoscope. Newer deployment is concentrated in Bluetooth-enabled Stethoscope.
Application:
Clinical workflow complexity determines sensor specification requirements and software integration depth.
- Telemedicine:Remote diagnostic platforms require HIPAA-compliant audio streaming and spectral analysis tools. Reimbursement formalization in the United States and Germany enables health systems to absorb device costs rather than passing them to individual physicians.
- Cardiology:Precise murmur detection demands piezoelectric sensors with superior low-frequency response. Tertiary hospital departments in Japan and Germany drive premium pricing for multi-frequency tuning capabilities.
- Pulmonology:Crackle and wheeze pattern recognition benefits from AI-augmented spectral analysis.
- Pediatrics:Smaller diaphragm diameters and frequency-optimized filters address neonatal acoustic signatures.
- Veterinary:Species-specific frequency response profiles and durable construction suit agricultural and companion animal practice.
Established volume sits with Cardiology. Steepest expansion trajectory belongs to Telemedicine.
End User:
Capital availability and technical sophistication create distinct procurement behaviors across facility types.
- Telehealth Providers:Subscription-based service models prioritize HL7 FHIR compatibility and cloud-native architecture. United States health networks consolidate vendor relationships around integrated platforms rather than standalone hardware.
- Research Laboratories:Unprocessed waveform access enables algorithm development partnerships with academic medical centers. Raw signal licensing agreements generate recurring revenue streams beyond device margins.
- Diagnostic Centers:High patient throughput demands durable construction and rapid sanitization protocols.
- Clinics:Budget constraints favor microphone-based sensors over piezoelectric alternatives for general auscultation.
Hardware-centric purchasing dominates Diagnostic Centers. Software-anchored procurement is expanding fastest among Telehealth Providers.
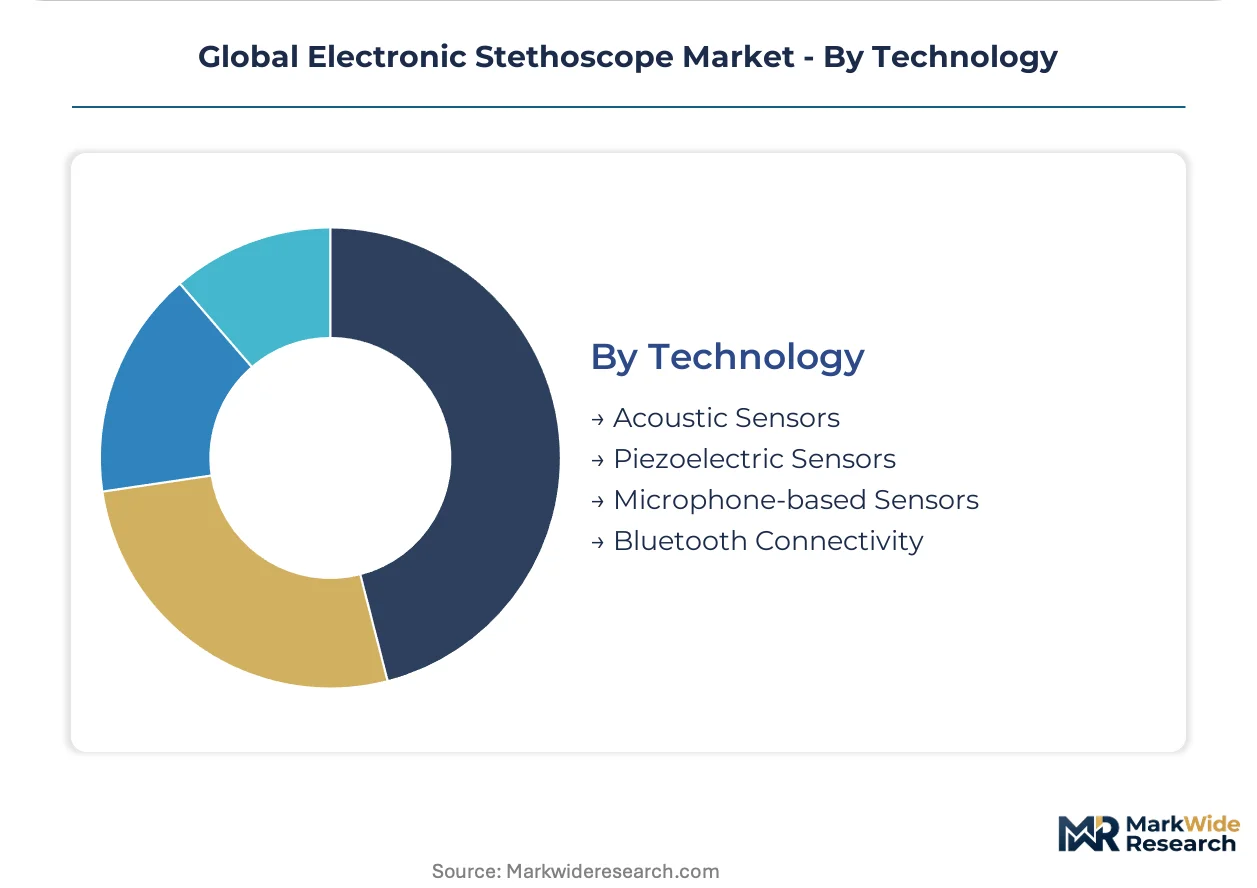
Technology:
Sensor physics and connectivity protocols define performance ceilings and regulatory pathways.
- Piezoelectric Sensors:Ceramic transducer arrays deliver superior low-frequency response for murmur detection. EU MDR acoustic performance mandates filter out non-compliant suppliers, consolidating procurement toward validated manufacturers with controlled validation studies.
- Bluetooth Connectivity:Wireless protocol implementation determines electromagnetic compatibility testing burdens. Japan's PMDA JIS-compliant standards require in-house anechoic chamber facilities that exclude lower-tier entrants.
- Acoustic Sensors:Conventional microphone-based conversion dominates unit volume through cost efficiency.
- Microphone-based Sensors:Electret condenser elements suit generalist point-of-care settings lacking specialist cardiology coverage.
Volume concentration rests with Acoustic Sensors. Premium positioning and fastest share gains attach to Piezoelectric Sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate electronic stethoscope component manufacturing, while Germany's MedTech clusters anchor European regulatory compliance infrastructure. These geographic anchors shape where acoustic validation studies, electromagnetic compatibility testing, and telehealth platform integration occur.
United States
Telehealth reimbursement formalization through CMS remote patient monitoring codes drives hospital procurement of Bluetooth-enabled devices. FDA 510(k) clearance pathways for acoustic medical devices require substantial equivalence testing against predicate submissions. The Minneapolis medical device corridor hosts acoustic sensor R&D facilities serving cardiology-focused health systems.
Germany
EU MDR conformity assessment for Class IIa acoustic devices filters non-compliant suppliers from hospital procurement channels. Germany's national telemedicine guidelines mandate HL7 FHIR compatibility for reimbursed remote auscultation services. The Tübingen-Stuttgart medical technology cluster houses electromagnetic compatibility testing laboratories serving European market entrants.
Japan
PMDA JIS-compliant electromagnetic compatibility standards for wireless medical devices require in-house anechoic chamber facilities. METI funding for rural telehealth infrastructure accelerates adoption of piezoelectric sensor devices in prefectural hospital networks. Tokyo's Shinagawa district concentrates testing partnerships that compress certification timelines for cardiology-focused manufacturers.
India
Government tertiary hospital digitization programs create procurement windows for affordable digital stethoscopes aligned with national telemedicine guidelines. CDSCO medical device registration requirements are harmonizing with IMDRF standards for acoustic performance claims. Bangalore's Electronics City SEZ hosts contract manufacturers serving both domestic hospital procurement and export markets.
China
NMPA Class II medical device registration for electronic stethoscopes requires domestic clinical trial data for wireless transmission claims. MIIT standards for Bluetooth medical devices enforce electromagnetic compatibility testing in designated national laboratories. Shenzhen's Nanshan district concentrates piezoelectric sensor component suppliers serving both domestic telehealth platforms and export manufacturing.
Global Electronic Stethoscope Market Competitive Landscape
United States producers anchor the premium software-integrated tier; German and Japanese specialists hold positions in acoustic validation and electromagnetic compliance. The market structure concentrates around three to five validated manufacturers with established regulatory dossiers, filtering lower-tier entrants lacking controlled clinical evidence. Two strategic archetypes dominate: acoustic sensor R&D houses with hospital procurement relationships, and AI-augmented software platforms licensing spectral analysis tools. Competitive moves center on telehealth platform partnerships and raw waveform research licensing agreements with academic medical centers.
Within the acoustic validation tier, 3M Littmann and Thinklabs Medical occupy positions shaped by decades of clinical adoption. Eko Health represents the AI-augmented software convergence, exemplifying how telemedicine partnerships can anchor market positioning beyond hardware margins. These three entities illustrate the bifurcation between legacy acoustic engineering expertise and cloud-native diagnostic platforms.
| Leading Market Players |
|---|
| 3M Littmann |
| Eko Health |
| Thinklabs Medical |
| American Diagnostic Corporation |
| Welch Allyn |
| Cardionics |
| HD Medical |
| eKuore |
| Contec Medical Systems |
| Others |
Supply & Pricing Matrix
Hospital procurement committees in Germany, the United States, and Japan concentrate contract awards around validated manufacturers with EU MDR dossiers, anchoring pricing power in regulatory compliance tiers rather than raw component costs. This buyer concentration compresses margins for non-compliant suppliers while enabling premium capture by acoustic validation leaders.
Pricing Analysis
Short lead-time premiums of four to six weeks command fifteen to twenty-five percent markups over standard twelve-week delivery cycles as EU MDR conformity assessment backlogs extend procurement timelines. Three-tier pricing structure across premium piezoelectric, standard Bluetooth-enabled, and economy digital amplification levels separates cardiology-grade sensors from generalist point-of-care devices. Pricing pressure stems from disposable acoustic diaphragm substitution in infectious disease wards prioritizing contamination control. Budget-constrained clinics in India's tertiary digitization programs exhibit highest price sensitivity, while Japan's cardiology departments demonstrate lowest sensitivity due to METI-funded rural telehealth infrastructure mandates.
Supply Chain Analysis
Certification gating through FDA 510(k) clearance and EU MDR Class IIa acoustic performance validation filters out lower-tier component suppliers lacking controlled clinical evidence infrastructure. Piezoelectric ceramic arrays concentrate in Shenzhen's Nanshan district, Bluetooth module assembly clusters in Bangalore's Electronics City SEZ, and electromagnetic compatibility testing facilities in Germany's Tübingen-Stuttgart corridor. Raw material dependencies span lithium niobate crystals for transducer fabrication, medical-grade silicone for diaphragm construction, and ARM-based microcontrollers for signal processing. Single-source vulnerability concentrates in anechoic chamber testing capacity for Japan's PMDA JIS-compliant EMC standards. Distribution runs through hospital procurement committees and GPO contracts in developed markets, with direct government tender participation dominating India's public hospital digitization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR acoustic performance mandates and extended conformity assessment timelines filter non-compliant suppliers from hospital procurement channels.
For Market Incumbents: Cement regulatory dossier advantages by deepening acoustic sensor R&D partnerships with Tokyo-based EMC testing facilities and Stuttgart-area validation laboratories. Prioritize backward integration into piezoelectric ceramic supply to defend margin position against microphone-based sensor commoditization. Threat substitution from AI-augmented software platforms licensing spectral analysis tools demands pre-emptive cloud-native architecture development. For New Entrants and Emerging Players: Begin with India's government tertiary hospital digitization programs where CDSCO registration harmonization with IMDRF standards creates lower barriers than FDA 510(k) predicate navigation. Target affordable digital stethoscope segments aligned with national telemedicine guidelines before attempting EU MDR Class IIa certification. Go-to-market angle should emphasize HL7 FHIR compatibility for health system EHR integration roadmaps. For Investors and Strategic Acquirers: Distressed-cycle entries favor acoustic validation specialists with existing EU MDR dossiers and Tokyo PMDA testing partnerships in Germany and Japan. Long-term viability over the next decade hinges on telehealth platform integration capabilities and raw waveform research licensing relationships with academic medical centers. Signal to watch is CMS remote patient monitoring code expansion formalizing reimbursement for AI-augmented auscultation services.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification | Extended acoustic performance validation timelines filter non-compliant competitors from German hospital procurement. |
| HL7 FHIR Integration Development | Pre-configured EHR connectivity satisfies United States health network vendor consolidation preferences. |
| Piezoelectric Sensor R&D Expansion | Superior low-frequency response captures premium positioning in Japan's cardiology-focused METI-funded rural networks. |
| Raw Waveform Licensing Agreements | Unprocessed digital signal access generates recurring revenue from academic medical centers in Germany and the United States. |
| Tokyo EMC Testing Partnership | JIS-compliant shielding certification compresses pre-market timelines for 5G base station interference validation. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineer consultations, and GPO contracts manager discussions underwrites the qualitative findings. Primary fieldwork engaged regulatory affairs specialists at acoustic device manufacturers, clinical validation study directors, and telehealth platform integration engineers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation summaries, CMS Medicare reimbursement coding bulletins, and Japan's PMDA medical device approval registers. Bottom-up unit shipment estimates triangulated against top-down health system capital expenditure surveys.
Comparable-period anchoring to historical EU MDR transition timelines and FDA 510(k) predicate device clearance patterns established the forecast window boundaries. Segmentation modeling spanned product type, application, end user, and technology dimensions with geographic regulatory cluster overlays. CAGR derivation incorporated acoustic sensor adoption curves, telehealth reimbursement formalization trajectories, and piezoelectric versus microphone-based sensor displacement rates. Industry-specific inputs included hospital EHR integration roadmap surveys and rural telehealth infrastructure investment disclosures from METI and CMS.
Underlying measurement precision varies by segment; Bluetooth-enabled stethoscopes and telemedicine applications carry tighter precision than traditional electronic formats and veterinary settings. Forecasts reflect assumptions about EU MDR notified body capacity expansion, FDA substantial equivalence determination consistency, and CMS remote patient monitoring code stability. A model refresh is warranted upon material change in telehealth reimbursement eligibility frameworks or PMDA electromagnetic compatibility standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Telehealth Device Market
Medical Devices
Flow Diverters Market
Medical Devices
Syringeless Injector Market
Medical Devices
Japan Respiratory Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Global Thrombectomy Devices Market