
 Cryoablation Devices Market | 2026-2036
Cryoablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoablation Devices Market Intelligence
Multi-source procurement for cryogen supply and probe manufacturing is expanding across the cryoablation devices industry. Medtronic leverages its integrated cardiovascular portfolio to dominate catheter-based cardiac cryoablation. Boston Scientific Corporation anchors its position through sustained R&D intensity in targeted cryoablation platforms. IceCure Medical specializes in percutaneous probe systems for interventional oncology, competing against larger diversified manufacturers.
Cryoablation devices deliver controlled tissue destruction through pressurized gas expansion, typically using argon or nitrous oxide to achieve temperatures below minus 40 degrees Celsius at probe tips for precise necrosis of cardiac arrhythmia foci or malignant lesions. Catheters command the largest product segment due to recurring replacement cycles and expanding electrophysiology lab volumes. Robotic-assisted cryoablation represents the fastest-growing technology category as surgical centers seek to reduce operator variability and procedure times. Hospitals absorb the majority of end-user demand, though ambulatory surgical centers gain share where same-day discharge protocols mature.
FDA 510(k) clearance requirements shape product development timelines and clinical evidence thresholds for US market entry, while the EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight on European commercialization. ISO 13485 quality management certification functions as a baseline predicate for supplier qualification by major hospital purchasing consortia. Stakeholders must monitor evolving reimbursement coding for office-based versus facility-based cryoablation as site-of-service economics increasingly dictate procurement decisions.
Market Dynamics
Robotic-assisted cryoablation is compressing procedure times and operator variability, forcing hospitals to upgrade capital equipment faster than traditional replacement cycles would dictate.
Growth Catalysts
- Site-of-service economics:Hospital outpatient departments in the United States aggressively adopt same-day tumor ablation protocols, reducing inpatient bed utilization while maintaining reimbursement parity.
- FDA 510(k) clearance pathways:Streamlined premarket notification requirements for minimally invasive cryoprobes accelerate product introductions and compress time-to-revenue for manufacturers.
- Electrophysiology lab expansion:Academic medical centers replace older thermal ablation systems with next-generation cryoablation platforms to treat cardiac arrhythmia foci.
Market Restraints
- Cryogen supply concentration:Pressurized argon and nitrous oxide sourcing depends on a limited supplier base, exposing manufacturers to input cost volatility and delivery disruptions.
- EU MDR compliance burden:Stricter post-market surveillance and notified body oversight under the Medical Device Regulation extend European commercialization timelines and inflate regulatory costs.
- Thermal ablation substitution:Radiofrequency and microwave ablation systems compete for oncology applications, particularly in cost-constrained hospital purchasing environments.
Strategic Opportunities
- Ambulatory surgical center penetration:Same-day discharge protocols mature in United States outpatient settings, creating channel expansion beyond traditional hospital procurement.
- Interventional oncology convergence:Integration of imaging navigation with percutaneous probe systems enables precision targeting of malignant lesions previously requiring open surgery.
- ISO 13485 certification differentiation:Quality management certification functions as a baseline predicate for supplier qualification by major hospital purchasing consortia, favoring prepared entrants.
Industry Challenges
- Reimbursement coding fragmentation:Divergent site-of-service economics between office-based and facility-based cryoablation complicates pricing strategy and demand forecasting.
- Electrophysiology specialist scarcity:Trained operators capable of catheter-based cardiac cryoablation remain concentrated at academic medical centers, limiting procedure volume growth.
- Legacy system integration:New cryoablation platforms must interface with existing hospital IT infrastructure and imaging systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoablation Devices Market |
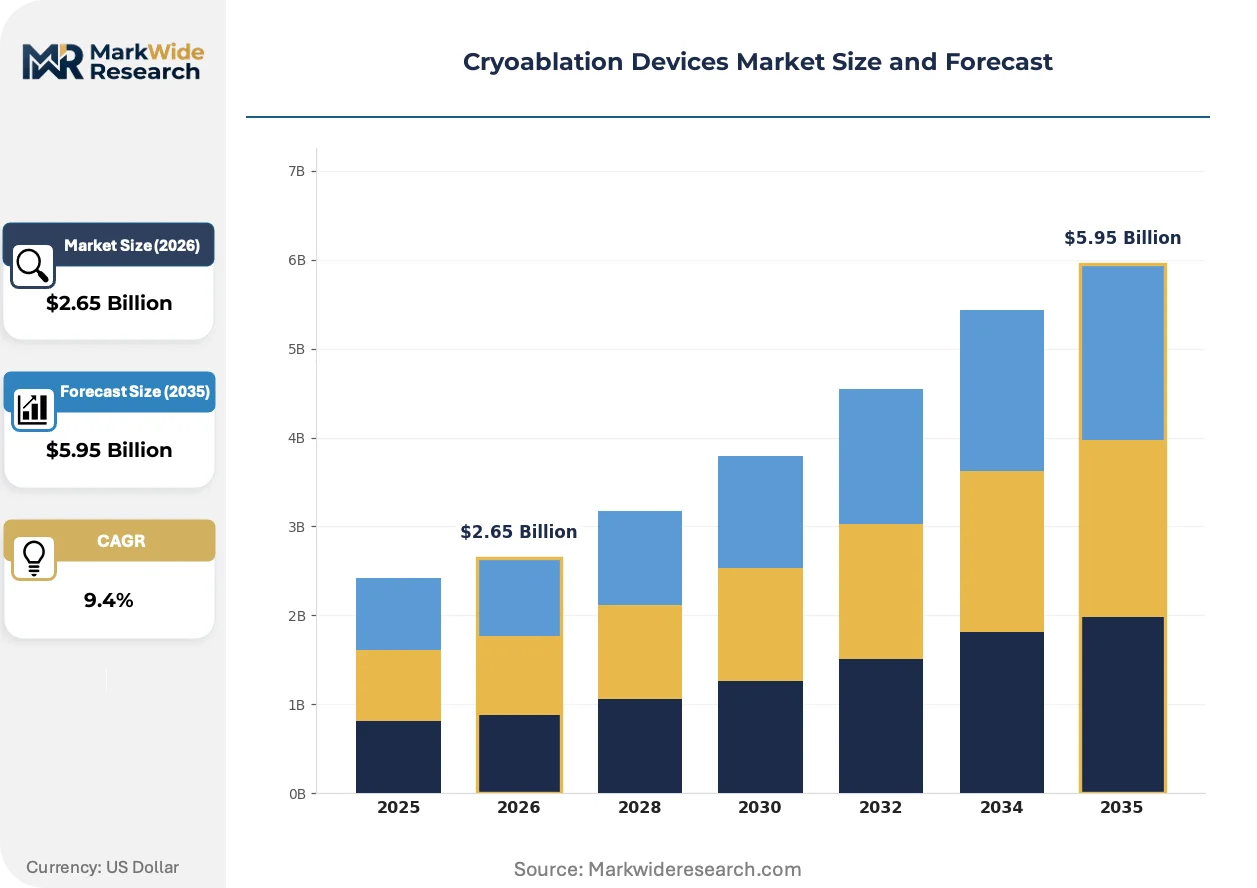
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Probes, Equipment, Accessories Application: Cardiac Ablation, Tumor Treatment, Pain Management, Cosmetic Procedures End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Clinics Technology: Conventional Cryoablation, Targeted Cryoablation, Robotic-Assisted Cryoablation, Minimally Invasive Techniques |
| Companies Covered | Medtronic, Boston Scientific Corporation, IceCure Medical, CooperSurgical, Atricure, CPSI Biotech, BVM Medical Limited, MicroPort Scientific Corporation, METRUM CRYOFLEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoablation Devices Market Strategic Shifts & Innovations
Three concurrent developments are restructuring competitive advantage in cryoablation: precision engineering advances, regulatory pathway evolution, and procurement model transformation.
Closed-loop gas recovery systems are rewriting capital equipment economics in high-volume electrophysiology labs. These systems recapture and recycle argon during cardiac ablation procedures, reducing per-case consumable costs by half. Academic medical centers in the United States are adopting this technology fastest, compressing the total cost of ownership gap between cryoablation and radiofrequency alternatives.
The EU Medical Device Regulation is tightening clinical evidence requirements for cryoprobe longevity claims. Manufacturers must now submit post-market performance data to notified bodies for renewal of CE certificates. Catheter-based cardiac applications face the steepest compliance burden, driving consolidation in European product portfolios as smaller firms exit the market.
Hospital purchasing consortia are consolidating supplier relationships around full-service contracts that bundle equipment, disposables, and preventive maintenance. This behavior compresses vendor margins while locking in multi-year volume commitments. The shift is most visible in United States oncology departments, where integrated delivery networks now dominate capital allocation decisions.
Cryoablation Devices Market Segmentation
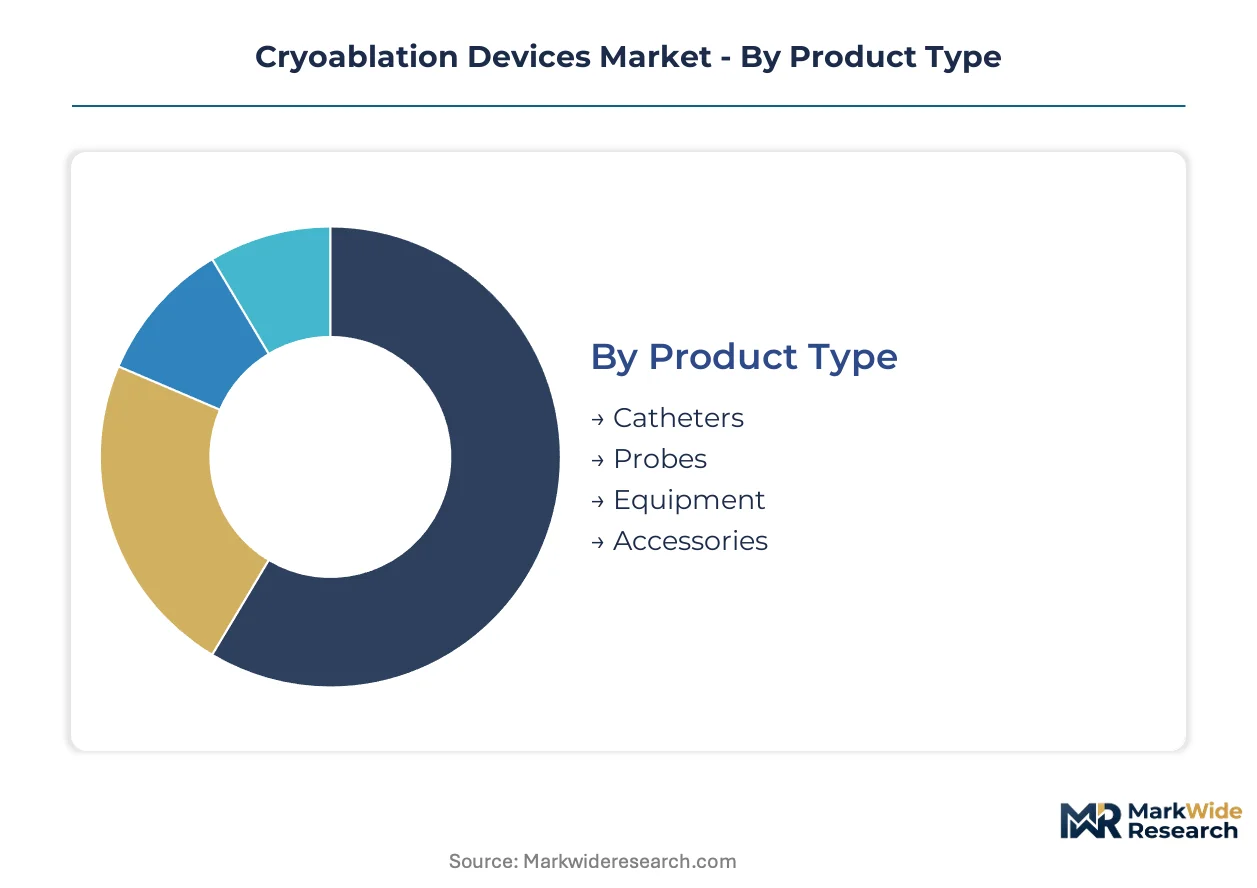
Segmentation in cryoablation devices reveals how purchasing power and clinical workflow requirements fragment across procedure types and care settings. Understanding these divisions exposes where manufacturers must tailor evidence generation, pricing architecture, and service models to capture wallet share.
Product Type:
Capital intensity and replacement cadence drive buyer segmentation across the hardware-disposables continuum.
- Catheters:Flexible, steerable delivery systems engineered for transvascular access to cardiac tissue. Electrophysiology labs at academic medical centers in the United States generate concentrated demand as procedure volumes expand and catheter replacement cycles accelerate.
- Probes:Rigid or semi-rigid percutaneous instruments designed for direct tissue contact in oncology applications. Interventional radiology departments prioritize probe compatibility with CT and ultrasound navigation systems when evaluating procurement.
- Equipment:Central console units managing gas delivery, temperature monitoring, and electrical control. Hospitals with established ablation programs favor modular platforms permitting technology upgrades without full system replacement.
- Accessories:Consumables including sheaths, introducers, and grounding pads supporting procedure execution. Purchasing consortia increasingly bundle accessory procurement with catheter and probe contracts to compress vendor margins.
Catheters lead on scale; robotic-compatible probes lead on momentum.
Application:
Reimbursement stability and clinical evidence maturity determine where manufacturers concentrate commercial resources.
- Cardiac Ablation:Treatment of atrial fibrillation and ventricular tachycardia through transcatheter cryothermal energy delivery. United States hospital outpatient departments aggressively adopt same-day discharge protocols for these procedures, preserving reimbursement parity with inpatient settings.
- Tumor Treatment:Percutaneous destruction of renal, hepatic, pulmonary, and breast malignancies. Oncology departments at academic medical centers represent the fastest-expanding buyer segment as facilities retire older radiofrequency systems.
- Pain Management:Cryoneurolysis for chronic neuropathic conditions and palliative care. Pain clinics in ambulatory settings drive demand where nerve ablation offers opioid-sparing alternatives.
- Cosmetic Procedures:Dermatological applications including cryolipolysis and lesion removal. Medical spas and aesthetic clinics in metropolitan United States markets absorb volume despite limited insurance coverage.
Cardiac ablation anchors revenue concentration; tumor treatment climbs the fastest.
End User:
Site-of-service economics and capital availability fragment demand across institutional categories.
- Hospitals:Integrated delivery networks with electrophysiology and interventional radiology service lines. These institutions absorb majority equipment demand and negotiate multi-year full-service contracts bundling capital, disposables, and preventive maintenance.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day procedures. United States outpatient settings gain share as CMS reimbursement policies favor site-neutral payment for select ablation procedures.
- Research Institutions:Academic medical centers and university hospitals conducting clinical trials. These buyers prioritize investigational device access and data-sharing agreements over standard commercial terms.
- Clinics:Office-based practices including cardiology and pain management groups. Smaller capital footprints and flexible leasing arrangements determine procurement feasibility for this segment.
Hospitals dominate installed base; ambulatory surgical centers expand most quickly.
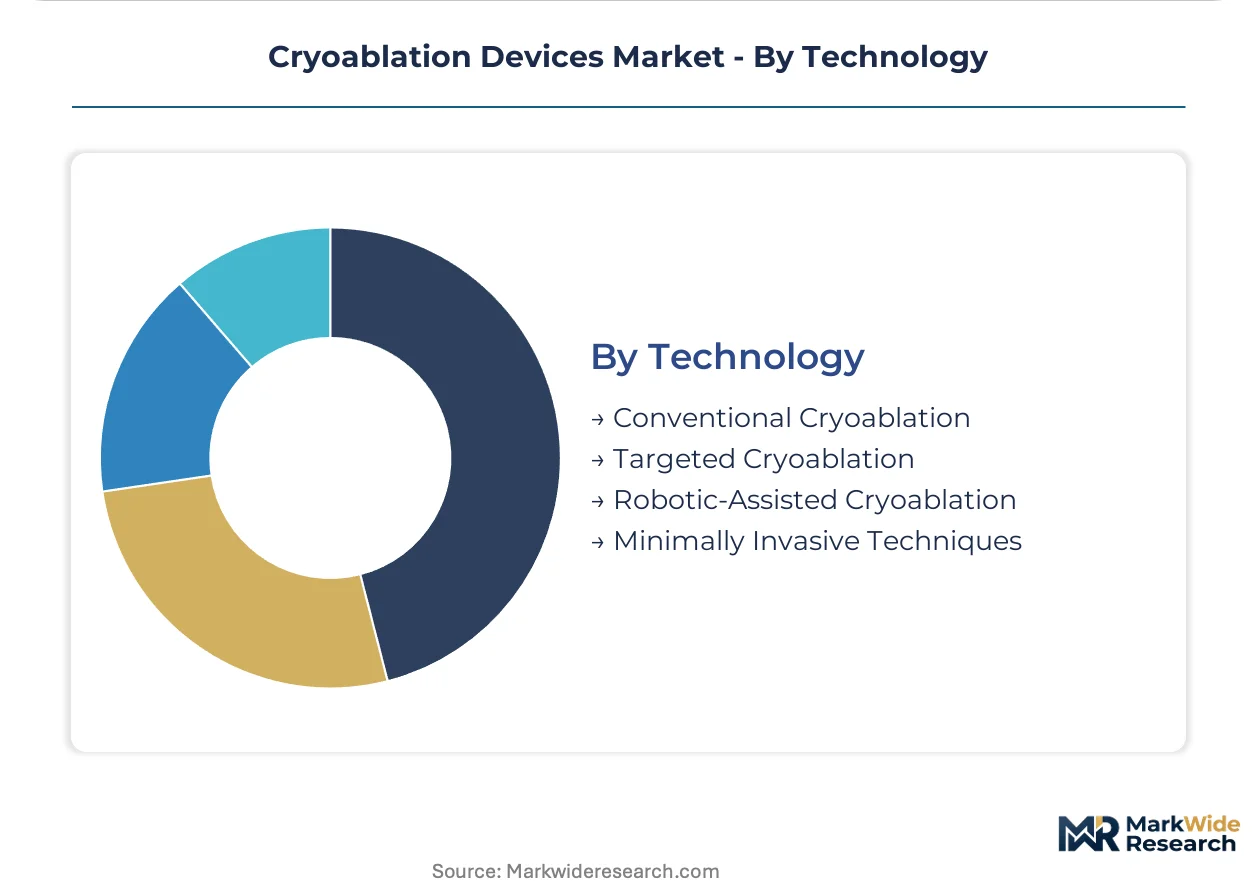
Technology:
Precision requirements and operator skill constraints shape adoption trajectories across the innovation spectrum.
- Conventional Cryoablation:Established systems utilizing manual probe placement and open-loop gas delivery. Cost-constrained facilities and emerging markets retain these platforms where capital replacement cycles extend.
- Targeted Cryoablation:Image-guided systems integrating real-time thermometry and navigation. These platforms command premium positioning in oncology departments requiring sub-millimeter targeting accuracy.
- Robotic-Assisted Cryoablation:Automated probe positioning with reduced operator variability and compressed procedure times. Surgical centers seeking standardization across operator skill levels drive adoption fastest.
- Minimally Invasive Techniques:Percutaneous and natural-orifice approaches reducing tissue trauma. Patient selection criteria and recovery protocol standardization determine diffusion speed across hospital systems.
Conventional systems retain volume leadership; robotic-assisted platforms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota's medical device corridor anchors cryoablation device innovation, with the United States absorbing majority global demand through hospital outpatient departments and academic medical centers replacing legacy thermal ablation systems.
United States
FDA 510(k) clearance pathways streamline product introductions for minimally invasive cryoprobes, compressing time-to-revenue for manufacturers targeting electrophysiology lab expansion. Hospital outpatient departments in metropolitan markets aggressively adopt same-day tumor ablation protocols. The Minneapolis-Saint Paul corridor concentrates catheter manufacturing and cardiovascular device R&D.
Germany
EU Medical Device Regulation imposes stricter post-market surveillance and notified body oversight, extending commercialization timelines for cryoprobe longevity claims. The country's interventional radiology departments prioritize probe compatibility with CT and ultrasound navigation systems. Baden-Württemberg hosts precision engineering clusters supplying cryogenic gas handling components.
Japan
PMDA regulatory frameworks shape clinical evidence thresholds for cardiac ablation device approvals, with electrophysiology specialist scarcity concentrated at university hospitals. METI industrial policy supports minimally invasive surgical technology adoption. The Kansai region around Osaka maintains manufacturing capabilities for medical gas delivery systems.
China
NMPA medical device registration requirements govern market entry for imported cryoablation platforms, with domestic manufacturers expanding percutaneous probe production. The country's dual carbon goals pressurize gas recovery system adoption in high-volume hospitals. The Yangtze River Delta clusters interventional oncology device assembly and imaging navigation integration.
United Kingdom
MHRA post-Brexit regulatory autonomy creates divergence from EU MDR compliance pathways, affecting cryoprobe certification timelines for manufacturers. NHS procurement consortia consolidate supplier relationships around full-service contracts bundling equipment and disposables. The Oxford-Cambridge arc concentrates academic medical centers conducting cryoablation clinical trials.
Cryoablation Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue robotic-assisted positioning and closed-loop gas recovery systems. The vendor base stratifies across diversified cardiovascular conglomerates, interventional oncology specialists, and regional equipment fabricators. Three archetypes dominate: integrated portfolio holders leveraging cross-selling infrastructure; pure-play cryoablation developers betting on procedure-specific innovation; and contract manufacturers supplying private-label probe systems. Competitive moves concentrate on M&A for imaging navigation capabilities and strategic partnerships for cryogen supply security.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify the integrated portfolio archetype, anchoring positions through cardiovascular device cross-selling infrastructure and electrophysiology lab relationships. IceCure Medical occupies a specialist position within the interventional oncology tier, representing pure-play developers focused on percutaneous probe systems for tumor ablation applications. These three entities illustrate the competitive spectrum from diversified scale to focused innovation.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| IceCure Medical |
| CooperSurgical |
| Atricure |
| CPSI Biotech |
| BVM Medical Limited |
| MicroPort Scientific Corporation |
| METRUM CRYOFLEX |
| Others |
Cost & Logistics Intelligence
Closed-loop gas recovery systems are compressing per-procedure consumable costs by half in high-volume electrophysiology labs, simultaneously reshaping capital equipment economics and concentrating procurement power among integrated delivery networks capable of absorbing upfront platform investments.
Pricing Analysis
Argon and nitrous oxide pass-through volatility anchors pricing dynamics across catheter and probe tiers. Three-tier pricing structure across premium, standard, and economy levels separates robotic-compatible platforms from conventional systems and refurbished legacy units. Price differentiation hinges on ISO 13485 certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying as purchasing consortia consolidate multi-year full-service contracts. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with established ablation programs show lowest.
Supply Chain Analysis
Domestic-content mandates under China's dual carbon goals and NMPA localization requirements are reshaping sourcing for cryogenic gas handling components. Manufacturing concentrates in the United States, Germany, and China. Production draws from precision-machined probe assemblies, medical-grade argon supply, and temperature monitoring sensors. Single-source vulnerability in pressurized gas supply exposes manufacturers to input cost spikes. Distribution runs through hospital purchasing consortia and GPO contracts rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cryoablation devices rests on closed-loop gas recovery technology diffusion, which halves per-case consumable spend and shifts value capture toward platform holders with integrated service contracts.
For Market Incumbents: Extend catheter replacement cycle capture through preventive maintenance bundling that locks electrophysiology labs into multi-year consumable commitments. Deepen backward integration into cryogenic gas supply to neutralize argon cost volatility threatening margin stability in the probe segment.
For New Entrants and Emerging Players: Capture ambulatory surgical center penetration where same-day discharge protocols mature fastest and purchasing authority remains fragmented. Target pain management clinics with flexible leasing arrangements and smaller capital footprints underserved by hospital-focused incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for interventional oncology specialists because imaging navigation integration requirements are consolidating vendor relationships around full-service platform providers. Watch FDA 510(k) clearance velocity for robotic-assisted systems as the inflection signal indicating which technology bets are converting to commercial traction.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates catheter introductions for electrophysiology lab expansion. |
| CE Marking Pathway | EU MDR compliance investment filters smaller competitors from European cryoprobe longevity claims. |
| Hospital System Partnership | Integrated delivery network contracts bundle equipment, disposables, and maintenance across multi-year commitments. |
| Software Companion Development | Real-time thermometry integration enables sub-millimeter targeting accuracy in oncology applications. |
| Reimbursement Strategy | Site-of-service economics alignment preserves outpatient parity for same-day tumor ablation protocols. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster. The analysis combines interviews with electrophysiology lab directors, interventional radiologists, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up procedure volume estimates and top-down equipment shipment data undergo triangulation to anchor market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, application, end user, and technology dimensions alongside regional regulatory cluster variations. CAGRs derive from fitted growth curves applied to segment-level base values. Forecast inputs incorporate electrophysiology lab expansion rates, cryogen supply cost trajectories, and site-of-service policy shifts.
Regulatory pathway delays, cryogen supply disruptions, and reimbursement coding fragmentation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding clearance timelines and purchasing consortia behavior. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Morcellators Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Transilluminators Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Electronic Pill Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Global Smart Implants Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Radial Compression Devices Market