
 Japan Insulin Drugs and Delivery Devices Market | 2026-2036
Japan Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Insulin Drugs and Delivery Devices Market Foresight
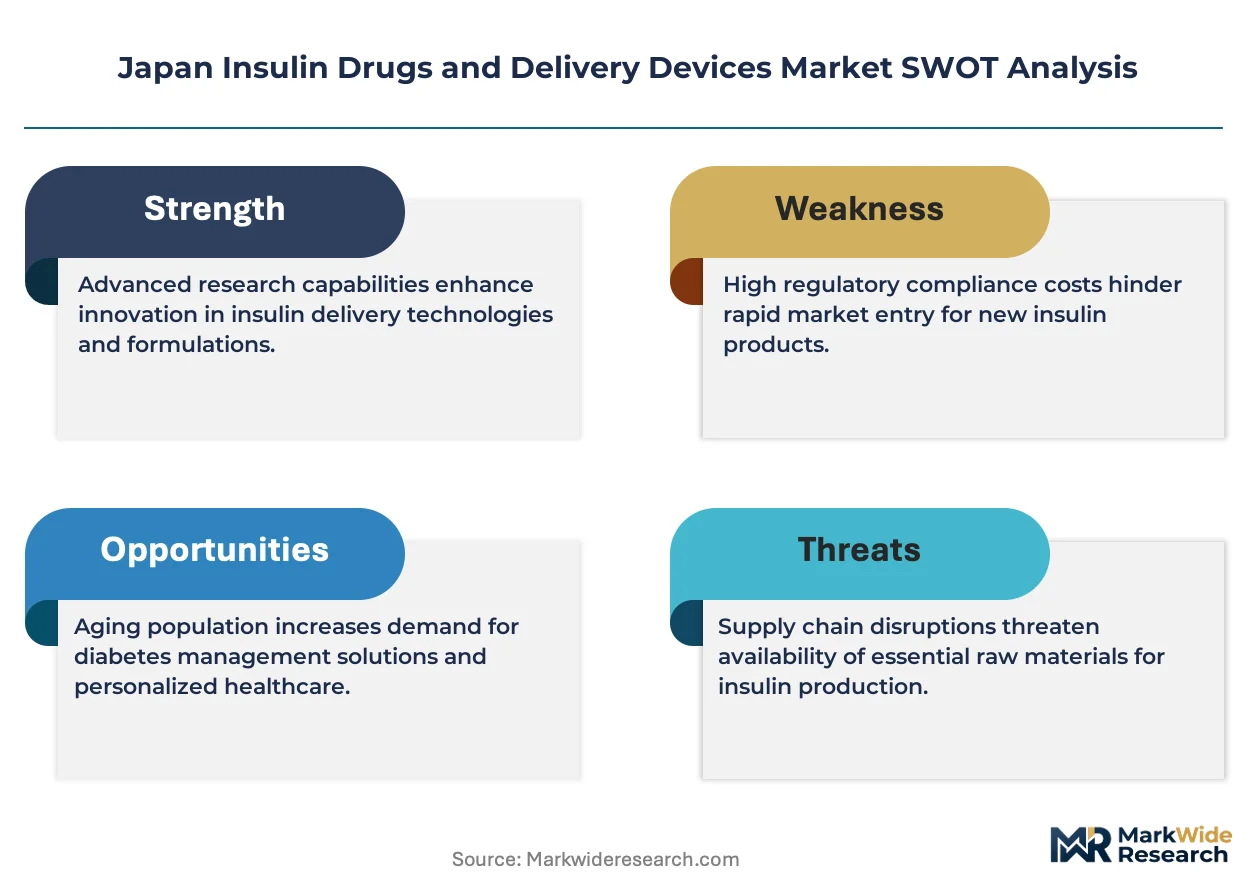
Human insulin analogue grade specifications is collapsing toward biosimilar-equivalent purity thresholds. Novo Nordisk leverages its recombinant protein manufacturing scale to sustain supply chain dominance across prefectural hospital systems. Sanofi anchors its position through differentiated glargine formulations that compete on dosing flexibility. Eli Lilly and Company specializes in rapid-acting analogues that occupy the outpatient clinic channel.
Insulin drugs and delivery devices encompass recombinant peptide therapeutics and precision injection systems engineered for controlled subcutaneous absorption with pharmacokinetic profiles targeting 0.3–0.5 nmol/L therapeutic thresholds, serving glycemic management in diabetic populations. Insulin pens dominate unit volume due to prefilled cartridge convenience and dose accuracy. Insulin pumps command premium positioning as closed-loop algorithm integration advances. Home care end users represent the fastest-expanding channel as self-monitoring blood glucose systems pair with Bluetooth-enabled delivery devices.
PMDA approval pathways and MHLW reimbursement schedules govern market access timelines and pricing bands for novel delivery mechanisms. JIS standards for medical electrical equipment enforce interoperability and safety benchmarks that manufacturers must satisfy before commercial distribution. METI industrial policy on medical device innovation influences domestic production incentives and export qualification protocols. Stakeholders must monitor how PMDA's accelerated review designations for artificial pancreas systems reshape competitive entry barriers and partnership structures.
Market Dynamics
Japan's MHLW reimbursement revisions for continuous glucose monitoring paired insulin pumps are accelerating technology transitions across prefectural hospital networks. This regulatory recalibration is compressing traditional insulin pen dominance while elevating closed-loop system procurement.
Growth Catalysts
- PMDA Accelerated Review Pathways:The Pharmaceuticals and Medical Devices Agency's fast-track designations for artificial pancreas systems shorten market entry timelines. Domestic manufacturers gain competitive positioning against imported devices.
- Metropolitan Hospital Network Expansion:Tokyo's Kanto region hospital clusters are consolidating diabetes management programs. These institutions drive bulk procurement of precision delivery devices.
- Bluetooth-Enabled Self-Monitoring Integration:Home care patients are pairing blood glucose sensors with smartphone-connected pens. This convergence expands the outpatient channel beyond clinic-dependent administration.
Market Restraints
- Recombinant Protein Input Concentration:Active pharmaceutical ingredient supply chains concentrate among a limited set of microbial fermentation specialists. Biosimilar-grade purity requirements strain domestic bioproduction capacity.
- PMDA Safety Benchmark Stringency:JIS medical electrical equipment standards enforce extended interoperability testing. Device manufacturers face prolonged certification cycles before commercial distribution.
- Prefilled Cartridge Cost Structure:Glass primary packaging and silicone lubrication materials face volatile petrochemical pricing. These input costs transmit directly to hospital procurement budgets.
Strategic Opportunities
- Kansai Region Underpenetration:Osaka and Kyoto metropolitan areas lag Tokyo in closed-loop pump adoption. Regional health bureaus present first-mover expansion potential for algorithm-integrated systems.
- METI Medical Device Innovation Incentives:The Ministry of Economy, Trade and Industry offers production subsidies for domestic manufacturing of precision injection mechanisms. Qualifying firms gain export qualification protocol advantages.
- Home Care Channel Disintermediation:Direct-to-patient subscription models for insulin cartridge replenishment are bypassing wholesale pharmaceutical distributors. Pharmacy chains are piloting automated dispensing lockers in Hokkaido prefecture.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Recombinant insulin production requires specialized microbial strain development expertise. Japanese universities produce insufficient fermentation scientists relative to biopharma demand.
- Legacy Device Integration Complexity:Hospital information systems in rural prefectures operate on outdated HL7 protocols. Closed-loop pump data streams require expensive middleware adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Insulin Drugs and Delivery Devices Market |
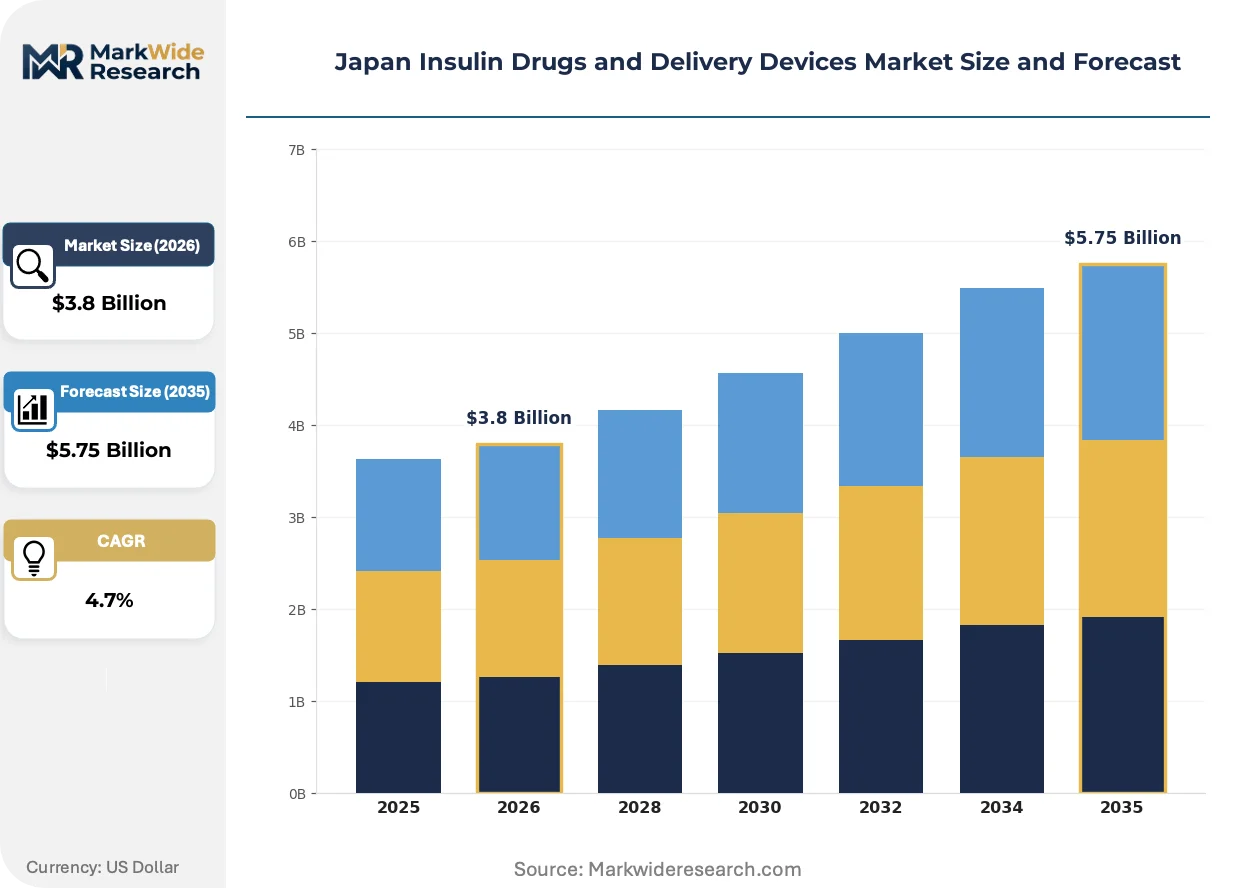
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Syringes, Infusion Sets Delivery Mode: Subcutaneous, Inhalation, Intravenous, Oral End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Medtronic, Roche, Ypsomed, Becton Dickinson, Embecta Corp, Takeda Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Insulin Drugs and Delivery Devices Market Shifts & Advancements
Algorithm-driven insulin delivery is compressing the gap between automated glucose control and manual dose calculation. This technological trajectory is redrawing competitive boundaries between pharmaceutical and medical device specialists.
Closed-loop artificial pancreas systems is displacing conventional insulin pump architectures across Japan's tertiary care institutions. Endocrinology departments in Tokyo Metropolitan Hospital and Osaka University Hospital are piloting dual-hormone configurations. This displacement is compressing market share for basal-bolus programming interfaces that require patient-calculated corrections.
MHLW's 2024 reimbursement expansion for real-time continuous glucose monitoring paired with automated insulin delivery has triggered device procurement waves. Prefectural governments are revising their medical equipment subsidy catalogs to include these integrated systems. Pediatric diabetes centers and perinatal clinics represent the most affected segments, accelerating technology transitions in maternal-fetal medicine applications.
Subscription-based cartridge replenishment programs are restructuring patient-pharmacy relationships in Japan's home care segment. Patients in Fukuoka and Sapporo are bypassing monthly clinic visits for automated delivery scheduling. This behavioral shift concentrates most visibly among working-age Type 1 diabetics who prioritize dosing discretion over traditional provider-supervised management.
Japan Insulin Drugs and Delivery Devices Market Segmentation
Segmentation in Japan's insulin market reveals how reimbursement policy and care setting economics allocate demand across device architectures. PMDA approval pathways and MHLW subsidy tiers create distinct procurement behaviors for each category, shaping manufacturer portfolio priorities.
Product Type:
Domestic production concentrates on insulin pen assembly in Shizuoka and Osaka prefectures, while pump mechanism imports dominate closed-loop system supply.
- Insulin Pens:Prefilled disposable and reusable cartridge systems with dose-dialing mechanisms calibrated to 0.5-unit increments. Tokyo metropolitan hospital networks and Kanto region clinics drive procurement volume through centralized tenders. MHLW reimbursement stability sustains pen dominance despite pump technology advances.
- Insulin Pumps:Electromechanical infusion devices with basal-bolus programming and Bluetooth connectivity for continuous glucose monitor pairing. Adoption concentrates in tertiary endocrinology centers where MHLW's expanded CGM reimbursement accelerates procurement. PMDA accelerated review pathways compress market entry timelines for algorithm-integrated systems.
- Syringes:Conventional vial-and-syringe administration persists in rural prefectures with limited pump reimbursement coverage.
- Infusion Sets:Subcutaneous cannula and tubing assemblies for pump systems face JIS medical electrical equipment interoperability testing requirements.
Insulin pens command the established base. The steepest expansion runs through insulin pumps.
Delivery Mode:
Cost tier differentiation separates premium subcutaneous device systems from experimental administration routes facing extended PMDA safety evaluation.
- Subcutaneous:Injection into adipose tissue via pen, pump, or syringe with established pharmacokinetic profiles. Home care patients in Fukuoka and Sapporo prefer this route for self-administration convenience paired with Bluetooth-enabled glucose monitoring.
- Inhalation:Pulmonary insulin delivery via dry powder or aerosol formulations. PMDA respiratory safety benchmarks and limited MHLW reimbursement restrict adoption to specialized diabetes centers in Osaka and Kyoto.
- Intravenous:Hospital-only administration for perioperative glycemic control and diabetic ketoacidosis management in Tokyo Metropolitan Hospital networks.
- Oral:Gastrointestinal insulin formulations remain experimental with no commercial PMDA approvals for diabetes therapy.
Subcutaneous delivery anchors current revenue. Inhalation delivery shows the most volatile regulatory pathway dependence.
End User:
Customer type determines procurement scale and reimbursement complexity, with institutional buyers leveraging volume against fragmented home care purchasing.
- Hospitals:Tertiary care institutions with consolidated diabetes management programs and bulk device procurement authority. Tokyo's Kanto region hospital clusters drive closed-loop pump adoption through centralized technology assessment committees.
- Home Care:Individual patients managing Type 1 and intensive insulin-requiring Type 2 diabetes outside clinical supervision. Subscription-based cartridge replenishment models in Hokkaido and Fukuoka prefectures are disintermediating traditional pharmacy channels.
- Clinics:Outpatient endocrinology practices with lower capital budgets favor insulin pens and conventional glucose monitoring systems.
- Pharmacies:Retail dispensing points face margin compression from direct-to-patient delivery models and automated locker pilots in Sapporo.
Hospitals dominate value concentration. Home care channels are expanding most quickly through self-monitoring technology integration.
Therapy Area:
Disease severity and treatment intensity stratify device requirements, with autoimmune Type 1 diabetes demanding precision delivery systems that prediabetes management does not justify economically.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin for survival. Pediatric diabetes centers and perinatal clinics in Tokyo and Osaka represent priority segments for closed-loop artificial pancreas system deployment.
- Type 2 Diabetes:Progressive insulin resistance with variable insulin dependency. Outpatient clinic channels in Kansai region metropolitan areas concentrate demand for rapid-acting analogue pens.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring tight glycemic targets. Maternal-fetal medicine applications in perinatal clinics drive demand for continuous glucose monitoring paired delivery.
- Prediabetes:Elevated glucose below diabetes thresholds with lifestyle intervention as primary management. Minimal device demand concentrates in preventive screening programs.
Type 1 diabetes anchors premium device revenue. Gestational diabetes applications are gaining share fastest through perinatal clinic technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's insulin device trade balance tilts toward precision mechanism imports, while domestic assembly concentrates in Shizuoka and Osaka prefectures. Prefectural health bureaus drive regional demand variation through divergent equipment subsidy tiers.
Kanto/Tokyo
Tokyo Metropolitan Hospital networks and adjacent prefectural clusters generate the nation's densest closed-loop pump procurement. MHLW's 2024 reimbursement expansion for CGM-paired systems channels funding through Kanto regional health authorities. Endocrinology departments at Tokyo University Hospital pilot dual-hormone artificial pancreas configurations.
Kansai/Osaka
Osaka and Kyoto metropolitan areas trail Tokyo in algorithm-integrated pump adoption, creating first-mover expansion terrain for device manufacturers. PMDA's Osaka branch office accelerates local clinical trial review for domestic manufacturers. Osaka University Hospital's perinatal clinic network drives gestational diabetes device demand.
Chubu/Nagoya
Nagoya's medical device manufacturing base supplies insulin pen assembly components to national distributors. METI's Tokai regional bureau administers production subsidies for precision injection mechanism fabrication. Shizuoka prefecture hosts domestic cartridge filling operations serving hospital procurement consortia.
Hokkaido
Sapporo's pharmacy chains pilot automated insulin dispensing lockers for subscription-based home care delivery. The prefectural government's rural health equipment subsidy program lags metropolitan reimbursement rates. Home care patients in Fukuoka and Sapporo bypass traditional clinic visits through Bluetooth-enabled self-monitoring integration.
Kyushu
Fukuoka's diabetes management programs concentrate in municipal hospital networks with limited pump procurement budgets. The Kyushu regional health bureau revises medical equipment catalogs to include continuous glucose monitoring systems. Pediatric diabetes centers in Fukuoka represent priority segments for technology transition acceleration.
Japan Insulin Drugs and Delivery Devices Market Competitive Landscape
Concentration sits with multinational pharmaceutical conglomerates possessing recombinant protein manufacturing scale and device fabrication partnerships. The vendor base stratifies across three tiers: integrated drug-device specialists, pure-play delivery mechanism manufacturers, and domestic distributors with regional hospital relationships. Strategic moves center on PMDA accelerated review pathway navigation and METI subsidy qualification for domestic production facilities.
Among the integrated specialists, Novo Nordisk, Sanofi, and Eli Lilly and Company exemplify the dominant competitive archetype combining analogue supply with pen mechanism distribution. These entities occupy positions where recombinant manufacturing scale intersects with prefilled cartridge assembly partnerships. Medtronic and Roche represent the device-centric tier, anchoring closed-loop system development through algorithm and sensor integration rather than pharmaceutical supply. Domestic players including Takeda Pharmaceuticals sit within regional distribution networks, leveraging prefectural hospital relationships against multinational direct sales forces.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Roche |
| Ypsomed |
| Becton Dickinson |
| Embecta Corp |
| Takeda Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Recombinant protein manufacturing scale economies in microbial fermentation concentrate active pharmaceutical ingredient supply among a limited set of global specialists, creating asymmetric pricing power that elevates biosimilar-grade purity thresholds as de facto price floors for insulin analogue procurement across Japan's prefectural hospital networks.
Pricing Analysis
Hospital procurement consortia anchor Japan's insulin device pricing structure through centralized tenders that extract volume discounts from multinational suppliers. Three-tier pricing separates closed-loop artificial pancreas systems from conventional insulin pumps from disposable pen cartridges, with MHLW reimbursement tiers as the primary differentiation driver. Cost compression in the pen cartridge segment is intensifying because glass primary packaging and silicone lubrication materials face volatile petrochemical input pricing. Home care patients demonstrate highest price sensitivity due to out-of-pocket cartridge replenishment burdens, while tertiary endocrinology centers exhibit lowest sensitivity where bundled CGM-pump systems command premium positioning.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Yokohama trade lane periodically strain inbound logistics for precision pump mechanisms and sensor assemblies sourced from contract manufacturers. Active pharmaceutical ingredient production concentrates in Denmark, France, and the United States, while device mechanism fabrication centers on Switzerland, Germany, and select Japanese domestic facilities in Shizuoka and Osaka prefectures. Raw material dependencies span recombinant protein fermentation media, medical-grade glass for cartridges, silicone lubricants, and lithium-ion cells for pump power systems. Single-source vulnerability in microbial strain development expertise creates supply chain risk as Japanese universities produce insufficient fermentation scientists relative to biopharma demand. Distribution runs through pharmaceutical wholesale networks for hospital channels, with direct-to-patient subscription models emerging in Hokkaido and Fukuoka prefectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's insulin market sits at a platform-economics inflection where Bluetooth-enabled self-monitoring integration and closed-loop algorithm interoperability are restructuring competitive boundaries between pharmaceutical supply and device control ecosystems.
For Market Incumbents: Shield formulary positioning at Tokyo Metropolitan Hospital and Osaka University Hospital networks by deepening backward integration into recombinant protein fermentation capacity and securing PMDA accelerated review designations for next-generation artificial pancreas submissions. Priority levers include captive supply of biosimilar-grade insulin analogues and algorithm-integrated pump data partnerships that raise switching costs for endocrinology departments. For New Entrants and Emerging Players: Differentiate on gestational diabetes applications in perinatal clinics where maternal-fetal medicine protocols demand continuous glucose monitoring paired delivery systems with less entrenched incumbent relationships. Target Kansai region metropolitan areas, specifically Kyoto and Osaka, where closed-loop pump adoption trails Tokyo and regional health bureaus present first-mover expansion terrain for algorithm-integrated systems. Go-to-market angle centers on METI production subsidy qualification for domestic precision injection mechanism fabrication. For Investors and Strategic Acquirers: Algorithm-integrated device specialists with PMDA pre-submission feedback and established relationships with domestic cartridge filling operations in Shizuoka represent the most defensible acquisition archetype. Long-term viability over the projection horizon hinges on MHLW reimbursement expansion continuity for CGM-paired systems and the pace of pediatric diabetes center technology transitions. The signal to watch is prefectural government medical equipment subsidy catalog revisions that include or exclude specific closed-loop system configurations.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Accelerated Review Pathway Navigation | Shortens market entry timelines for artificial pancreas systems against imported device competition. |
| METI Domestic Production Subsidy Qualification | Unlocks precision injection mechanism fabrication incentives and export protocol advantages for qualifying firms. |
| Hospital System Partnership Consolidation | Tokyo Kanto region procurement consortia drive bulk device purchasing and technology assessment committee influence. |
| Bluetooth-Enabled Self-Monitoring Integration | Pairs blood glucose sensors with smartphone-connected pens to expand outpatient channel beyond clinic dependence. |
| Subscription-Based Cartridge Replenishment Model | Bypasses wholesale pharmaceutical distributors through direct-to-patient automated dispensing locker pilots in Hokkaido. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across Tokyo, Osaka, and Fukuoka; and secondary validation through PMDA approval filings, MHLW reimbursement schedule publications, METI industrial policy directives, and JIS medical electrical equipment standards documentation. Bottom-up and top-down triangulation reconciled prefectural hospital procurement volume estimates with national diabetes prevalence and treatment intensity benchmarks.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, delivery mode, end user, and therapy area, with regional regulatory cluster variations as an additional pharmaceutical-specific dimension. CAGRs were derived through trend extrapolation calibrated to MHLW reimbursement policy trajectories and PMDA review pathway velocity, incorporating insulin analogue purity specification evolution and closed-loop algorithm integration adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained MHLW reimbursement expansion for CGM-paired systems, stable microbial fermentation input supply, and continued PMDA accelerated review pathway availability would require recalibration. Forecasts reflect documented assumptions regarding prefectural health bureau equipment subsidy continuity and bioprocess engineering talent pipeline development. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Glycated Albumin Market