
 Drone Parachute System Market | 2026-2036
Drone Parachute System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Parachute System Market Insights
EASA's drone-specific type-certification framework is recalibrating the cost-of-entry calculus for parachute system manufacturers seeking European market access. ParaZero Technologies Ltd leverages its Israeli R&D base to sustain certification-first product development across multiple jurisdictions. Fruity Chutes Inc. anchors its position through specialized nylon canopy manufacturing with domestic US sourcing. Skycat.pro OY competes on rapid-deployment pyrotechnic systems designed for cold-climate operations.
A drone parachute system is an active safety mechanism comprising a packed canopy, deployment actuator, and altitude-sensing trigger designed to arrest uncontrolled descent of unmanned aerial vehicles. These systems typically activate below 400 feet AGL using barometric or accelerometer-based triggers to prevent ground impact damage. Automatic parachute systems command the dominant share of product-type revenue due to regulatory mandates for beyond-visual-line-of-sight operations. Multirotor drone deployment platforms generate the fastest growth trajectory as delivery fleets scale in urban corridors. Infrastructure inspection applications sit at the mature end of the application spectrum with established procurement cycles and standardized performance benchmarks.
The FAA, EASA, and China's CAAC collectively shape demand through divergent certification pathways that fragment product development roadmaps. ASTM F3322-22 and ISO 21895 establish the baseline performance thresholds that determine market access eligibility across jurisdictions. Stakeholders must monitor the convergence trajectory of national parachute performance standards to anticipate which testing protocols will dominate cross-border commerce.
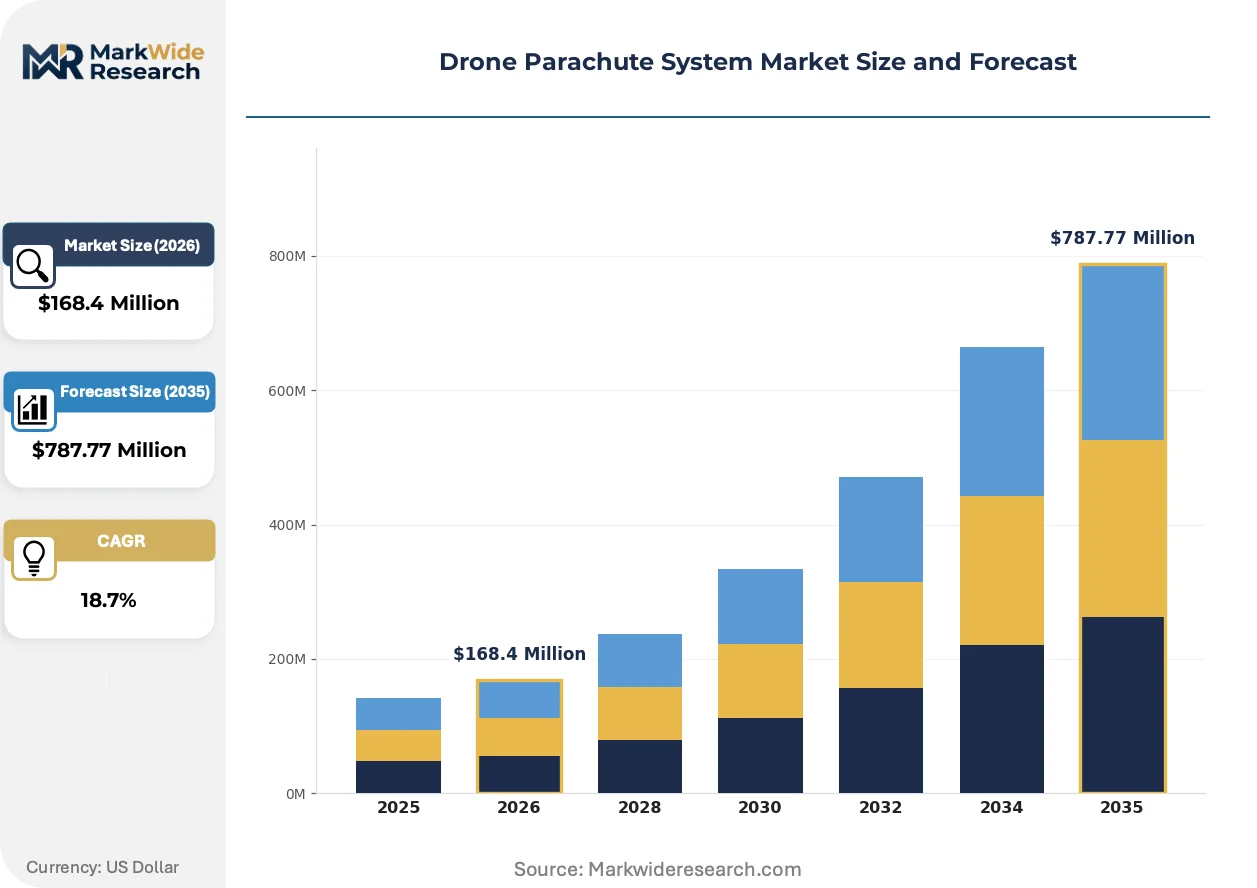
Market Dynamics
The FAA's Remote ID mandate and EASA's type-certification framework are compressing product development cycles, forcing manufacturers to engineer multi-jurisdiction compliance into core architectures rather than retrofitting for regional variants.
Growth Catalysts
- Beyond-Visual-Line-of-Sight mandates:Commercial logistics operators in the United States face operational clearance requirements that automatically trigger parachute system procurement for fleet insurance eligibility.
- Urban air mobility corridors:Municipal regulators in Germany are embedding active recovery requirements into vertiport operating licenses, creating captive demand from passenger drone developers.
- Pyrotechnic deployment actuators:Cold-climate operators in Scandinavia require sub-zero activation reliability that spring-loaded alternatives cannot guarantee, driving specification upgrades.
Market Restraints
- Carbon fiber composite cost volatility:Canopy frame manufacturers face input price swings from aerospace-grade material suppliers concentrated in Japan and the United States.
- Testing facility concentration:ASTM F3322-22 certification requires drop-test validation from a shrinking pool of accredited centers, creating queue bottlenecks for new entrants.
- Barometric sensor altitude drift:Trigger accuracy degrades in rapid-weather-change environments, limiting deployable altitude windows below 200 feet AGL in certain operational profiles.
Strategic Opportunities
- India's drone PLI scheme:Local assembly incentives for unmanned aerial systems create downstream demand for indigenized safety subsystems with domestic certification pathways.
- Agricultural spraying fleets:Crop protection operators in Brazil require over-water recovery capabilities that maritime-rated parachute configurations can address.
- Blockchain-enabled maintenance logging:Immutable deployment records are absorbing interest from insurance underwriters seeking verified risk data for premium calibration.
Industry Challenges
- Multi-jurisdiction certification staffing:Engineering teams capable of navigating simultaneous FAA, EASA, and CAAC documentation requirements command scarcity premiums that strain mid-tier R&D budgets.
- Legacy fleet retrofit integration:Existing multirotor platforms lack standardized mounting interfaces, forcing custom mechanical engineering for each airframe variant.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Parachute System Market |
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $787.77 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Parachute, Manual Parachute, Semi-automatic Parachute, Hybrid Parachute Application: Surveillance, Emergency Response, Agricultural Monitoring, Infrastructure Inspection, Environmental Research Deployment: Fixed-wing Drones, Multirotor Drones, Hybrid VTOL Drones, Tethered Drones End User: Logistics Providers, Film & Entertainment, Law Enforcement, Scientific Research Organizations, Construction Firms |
| Companies Covered | Skycat.pro OY, Fruity Chutes Inc., ParaZero Technologies Ltd, Butler Parachute Systems, Galaxy GRS, Drone Rescue Systems GmbH, Aerial Vehicle Safety Solutions Inc. (AVSS), BRS Aerospace, Indemnis Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Parachute System Market Trends and Innovations
Active safety architectures are absorbing computational load from standalone trigger modules into centralized flight controllers, collapsing component count while raising software liability exposure. This integration wave is redrawing supplier boundaries and certification scopes.
Machine-vision descent assessment is absorbing altitude-sensing functions from barometric triggers, enabling terrain-relative deployment decisions rather than fixed-height activation. Agricultural and infrastructure inspection operators in Australia are piloting camera-based systems that delay canopy release until obstacle clearance is verified. The technology is absorbing regulatory attention as aviation authorities debate whether visual confirmation satisfies equivalent-safety thresholds.
EASA's Specific Category framework is compressing operational approval timelines for parachute-equipped platforms, creating regulatory arbitrage against the FAA's Part 107 waiver process. Drone service providers in the Netherlands and France are restructuring fleet procurement around EASA-first certification strategies. The policy divergence is absorbing cross-Atlantic product planning resources as manufacturers maintain parallel documentation streams.
Insurance bundling is restructuring procurement economics for commercial operators, with underwriters in the United Kingdom and Germany offering premium reductions that offset hardware acquisition costs within eighteen-month payback windows. Risk-transfer mechanisms are displacing capital-expense justification as the primary purchase trigger. Large logistics contractors in the Midlands and Rhine-Ruhr corridor are consolidating safety-system procurement through fleet-level master service agreements.
Drone Parachute System Market Segmentation
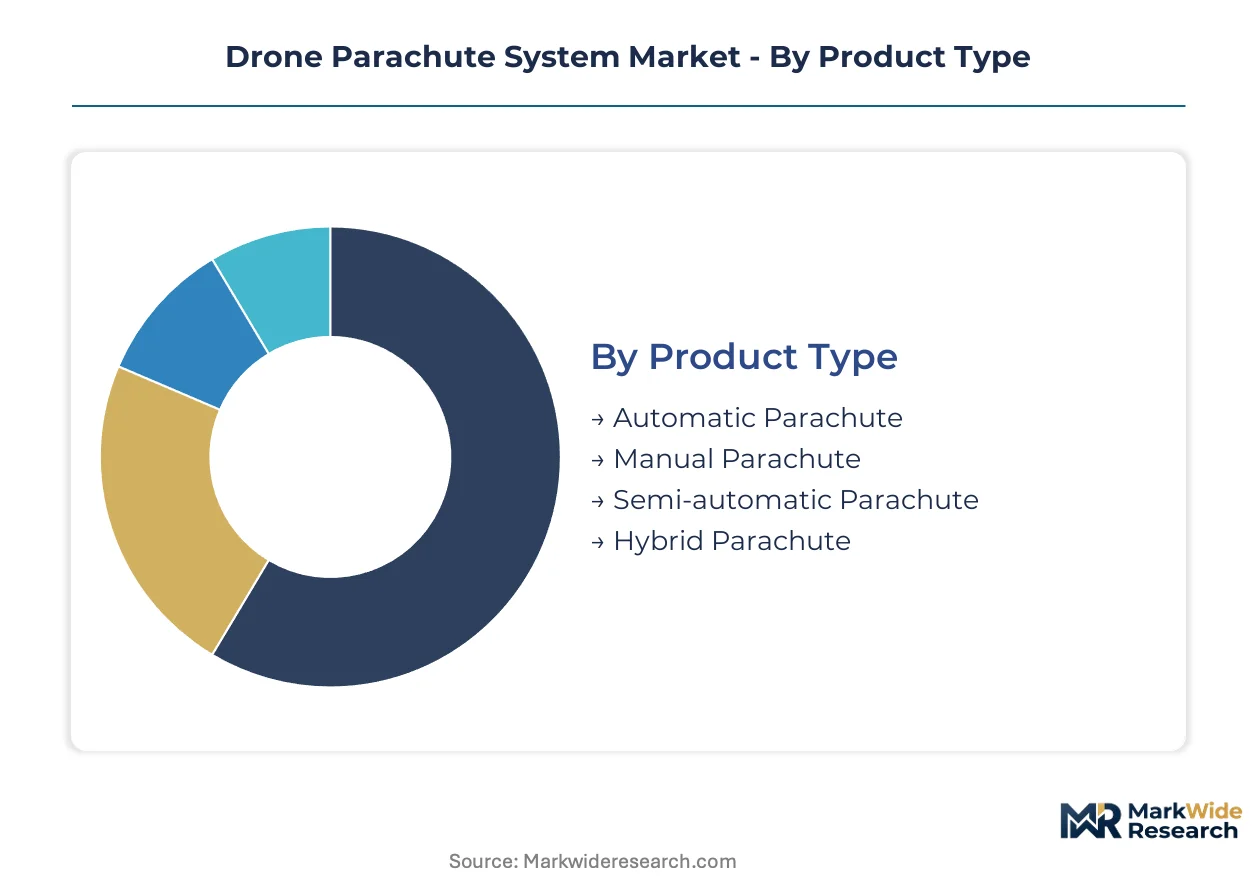
Parachute system procurement patterns diverge sharply across operational contexts. Regulatory mandates, payload economics, and fleet insurance requirements reshape how buyers evaluate deployment mechanisms and integration complexity.
Product Type:
Buyers differentiate primarily on crew training burden and activation reliability under stress conditions.
- Automatic Parachute:Barometric or accelerometer-based triggers activate canopy release without pilot intervention. Commercial logistics operators in the United States face FAA beyond-visual-line-of-sight mandates that make this configuration mandatory for fleet insurance eligibility.
- Manual Parachute:Pilot-commanded deployment systems retain human decision authority over activation timing. Film and entertainment crews in Germany favor this option for controlled descent over populated sets where premature deployment risks equipment loss.
- Semi-automatic Parachute:Hybrid trigger architecture allows pilot override of automated altitude-based release. Scientific research organizations operating in variable terrain use this flexibility for mission-critical payload recovery.
- Hybrid Parachute:Modular systems permitting field configuration between automatic and manual modes. Construction firms with mixed fleet compositions value this adaptability across surveying and inspection operations.
Volume sits with Automatic Parachute; growth tilts toward Hybrid Parachute.
Application:
Mission criticality and payload value density determine specification stringency and replacement frequency.
- Surveillance:Continuous flight patterns over sensitive zones demand failsafe recovery for classified sensor payloads. Law enforcement agencies in China specify military-grade activation reliability for border monitoring fleets.
- Emergency Response:Rapid deployment scenarios require sub-zero activation guarantees and maritime-rated canopy materials. Scandinavian rescue services specify pyrotechnic actuators that spring-loaded alternatives cannot match.
- Agricultural Monitoring:Chemical exposure and humidity corrosion accelerate component degradation. Brazilian crop protection operators prioritize over-water recovery capabilities for spraying operations near reservoirs.
- Infrastructure Inspection:Established procurement cycles and standardized performance benchmarks dominate this mature segment. German energy utilities specify ASTM F3322-22 compliance as baseline for transmission line survey contracts.
- Environmental Research:Remote deployment locations demand extended shelf life and minimal maintenance protocols. Australian Antarctic programs specify cold-storage compatibility for polar research missions.
Revenue concentrates in Infrastructure Inspection; expansion accelerates fastest in Emergency Response.
Deployment:
Airframe aerodynamics and descent velocity profiles dictate actuator force requirements and canopy sizing.
- Multirotor Drones:Vertical thrust loss triggers immediate uncontrolled tumble, demanding rapid-deployment pyrotechnics. Urban logistics corridors in the United States and Germany are scaling delivery fleets that embed this platform type.
- Fixed-wing Drones:Gliding descent characteristics permit larger canopy deployment windows and lighter actuator specifications. Environmental research organizations favor this efficiency for long-endurance mapping missions.
- Hybrid VTOL Drones:Dual-mode flight envelopes complicate trigger logic for transition-state failures. Passenger drone developers in France and the Netherlands face EASA vertiport licensing requirements that specify active recovery systems.
- Tethered Drones:Cable-assisted descent limits free-fall distance but requires cutaway mechanisms for emergency release. Border surveillance programs in India specify this configuration for persistent aerial monitoring.
Fixed-wing Drones hold installed base; Multirotor Drones are climbing the fastest.
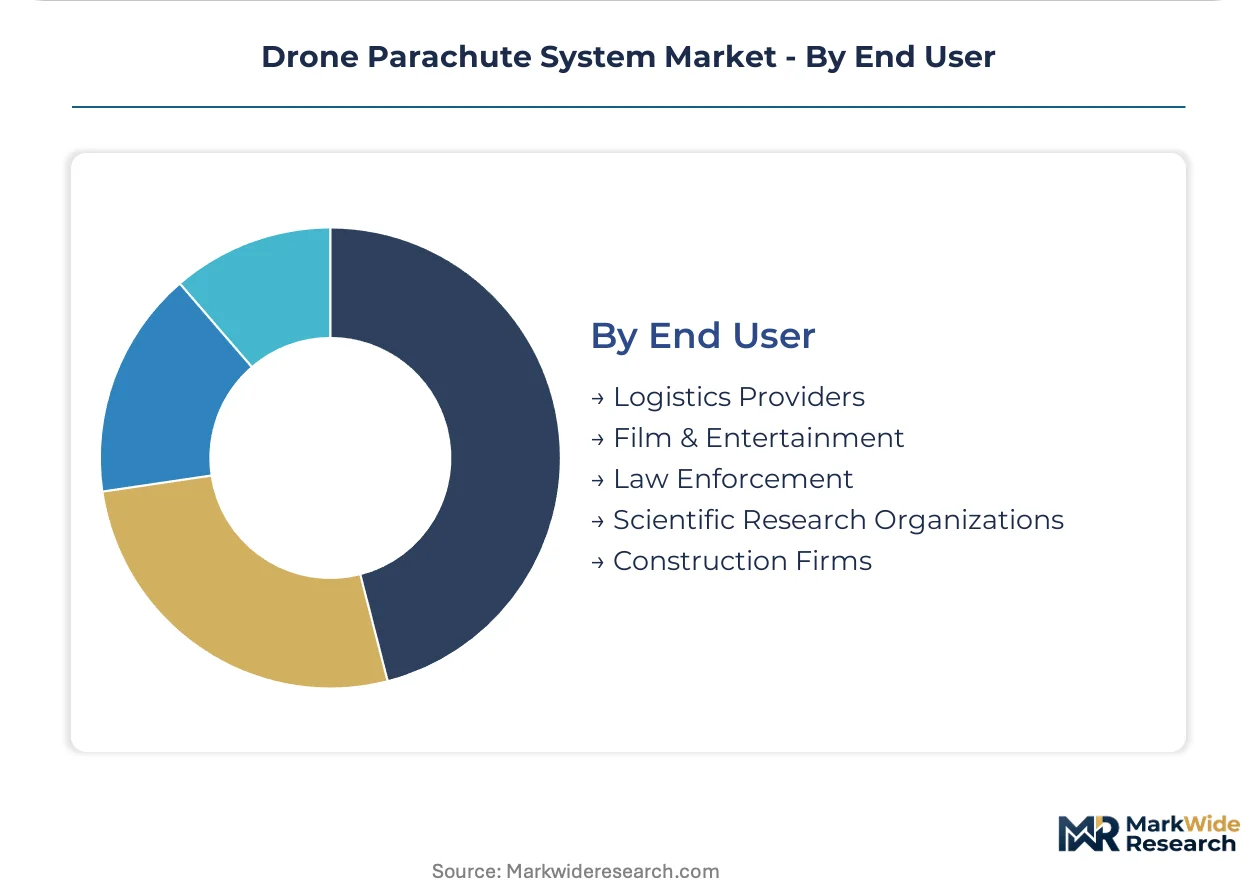
End User:
Procurement centralization and insurance bundling economics reshape contract structures and vendor selection criteria.
- Logistics Providers:Fleet-level master service agreements consolidate safety-system procurement across hundreds of units. United Kingdom underwriters offer premium reductions that offset hardware costs within eighteen-month payback windows.
- Film & Entertainment:Production insurance mandates drive specification compliance for aerial cinematography over cast and crew. California-based studios require FAA Part 107 waiver documentation that parachute systems expedite.
- Law Enforcement:Chain-of-custody requirements for evidence-grade sensor payloads demand tamper-proof deployment logging. Blockchain-enabled maintenance records are absorbing interest from municipal procurement officers.
- Scientific Research Organizations:Grant-funded acquisition cycles prioritize capital efficiency over operational optimization. India's drone PLI scheme is creating downstream demand for indigenized safety subsystems with domestic certification pathways.
- Construction Firms:Project-based equipment utilization favors rental and leasing models over outright purchase. German Rhine-Ruhr corridor contractors consolidate procurement through regional equipment cooperatives.
Logistics Providers dominate contract value; Scientific Research Organizations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's technology transfer zones and aerospace R&D clusters concentrate parachute system engineering talent, drawing procurement attention from multi-jurisdiction operators seeking certification-ready platforms.
United States
Commercial logistics providers scaling urban delivery fleets drive procurement volume, with FAA Part 107 waiver requirements mandating active recovery systems for beyond-visual-line-of-sight insurance eligibility. The Remote ID rule compresses compliance timelines for fleet operators. California-based studios and Texas energy utilities anchor demand across film production and infrastructure inspection verticals.
Germany
Municipal vertiport licensing in the Rhine-Ruhr corridor embeds parachute requirements into passenger drone operating permits, creating captive demand from EASA type-certification applicants. KBA oversight intersects with federal aviation policy on unmanned systems. Bavaria's aerospace supplier network feeds component fabrication for cold-climate actuator specifications.
China
CAAC certification pathways for commercial drone fleets prioritize domestically manufactured safety subsystems, with logistics operators in the Yangtze River Delta upgrading fleet protection mandates. MIIT standards on unmanned aerial vehicle airworthiness shape procurement specifications. Shenzhen's hardware ecosystem accelerates pyrotechnic actuator prototyping for multirotor platforms.
India
The PLI scheme for drone manufacturing creates downstream demand for indigenized parachute systems with BIS certification pathways, as agricultural spraying fleets expand in Maharashtra and Gujarat. DGFT import substitution policies favor local assembly of safety subsystems. Karnataka's aerospace parks host testing facilities for tropical-climate deployment validation.
Drone Parachute System Market Competitive Landscape
Israeli producers anchor one tier with certification-first engineering capabilities; German specialists hold another through precision actuator manufacturing and cold-climate reliability benchmarks. The vendor base stratifies across three tiers: integrated platform OEMs with captive safety divisions, independent subsystem specialists with multi-jurisdiction certification portfolios, and regional fabricators serving domestic compliance requirements. Consolidation pressure concentrates among mid-tier specialists facing R&D cost escalation. Strategic moves center on backward integration into canopy material supply and technology licensing for rapid geographic expansion.
Specialists in multi-jurisdiction certification include ParaZero Technologies Ltd, Fruity Chutes Inc., and Skycat.pro OY. ParaZero occupies a position exemplifying the certification-first archetype with Israeli R&D anchoring. Fruity Chutes represents domestic US sourcing specialization in canopy manufacturing. Skycat.pro sits within the cold-climate deployment tier, with Finnish engineering addressing sub-zero actuator reliability requirements that spring-loaded alternatives cannot match.
| Leading Market Players |
|---|
| Skycat.pro OY |
| Fruity Chutes Inc. |
| ParaZero Technologies Ltd |
| Butler Parachute Systems |
| Galaxy GRS |
| Drone Rescue Systems GmbH |
| Aerial Vehicle Safety Solutions Inc. (AVSS) |
| BRS Aerospace |
| Indemnis Inc |
| Others |
Pricing and Supply Chain Analysis
Backward integration into pyrotechnic actuator manufacturing anchors both supply security and margin protection for parachute system specialists navigating multi-jurisdiction certification demands. Israeli and German producers with captive sourcing of cold-climate deployment mechanisms command pricing power against competitors dependent on third-party spring-loaded alternatives.
Pricing Analysis
Short lead-time premiums separate ASTM F3322-22 certified inventory from spot-market alternatives with extended queue bottlenecks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with logistics providers bundling fleet-level master service agreements capturing standard-tier economics. Cost compression in economy-tier spring-loaded systems is intensifying because Brazilian and Indian agricultural operators prioritize capital efficiency over sub-zero reliability. Film and entertainment crews in California exhibit lowest price sensitivity due to production insurance mandates that override hardware cost considerations.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given the single-use nature of pyrotechnic deployment charges, though canopy material recovery programs in Germany and the United States are absorbing regulatory attention for sustainability compliance. Aerospace-grade carbon fiber composite supply concentrates in Japan and the United States, with canopy frame fabrication tethered to these upstream inputs. Single-source vulnerability from Japanese Toray-grade material suppliers creates exposure for premium-tier manufacturers. Distribution runs through direct OEM integration for fleet-scale logistics providers and regional equipment cooperatives serving German construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into canopy material supply and pyrotechnic actuator manufacturing is accelerating as mid-tier specialists seek margin defense against R&D cost escalation and certification queue bottlenecks.
For Market Incumbents: Cement multi-jurisdiction certification portfolios by maintaining parallel FAA and EASA documentation streams, insulating against regulatory arbitrage from EASA's compressed Specific Category timelines. Backward integration into cold-climate actuator production addresses the scarcity premium engineering teams currently command. ParaZero Technologies Ltd's Israeli R&D anchoring exemplifies the certification-first positioning that frustrates retrofit-dependent challengers.
For New Entrants and Emerging Players: India's PLI scheme for drone manufacturing opens a window for indigenized parachute systems with BIS certification pathways, targeting agricultural spraying fleets in Maharashtra and Gujarat that lack domestic safety subsystem options. Brazil's over-water recovery requirements for crop protection operators represent a penetrable white-space where maritime-rated configurations face limited incumbent attention. A leasing-model go-to-market structure aligns with construction firm procurement patterns in the German Rhine-Ruhr corridor.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform OEM acquisition of independent subsystem specialists with multi-jurisdiction certification portfolios. Long-term viability hinges on software liability exposure from integrated flight controller architectures displacing standalone trigger modules. The signal to watch is EASA-FAA certification convergence trajectory, which would collapse parallel documentation costs and reshape target valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | Parallel FAA and EASA documentation streams capture regulatory arbitrage from divergent approval timelines. |
| Backward Integration into Pyrotechnic Actuators | Captive supply of cold-climate deployment mechanisms defends margin position against Japanese carbon fiber volatility. |
| Blockchain-Enabled Maintenance Logging | Immutable deployment records satisfy UK and German insurance underwriter demands for verified risk data. |
| Leasing Model Development | Equipment cooperatives in Germany's construction sector absorb project-based utilization patterns without capital burden. |
| Machine-Vision Trigger Integration | Camera-based descent assessment addresses barometric sensor drift limitations in Australian rapid-weather-change environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with UAV fleet managers, parachute system engineering leads, aviation insurance underwriters, and certification testing facility directors. FAA Part 107 waiver documentation, EASA type-certification databases, and CAAC commercial drone fleet registries provided compliance pathway validation. Bottom-up procurement volume estimates from logistics providers and top-down market sizing from aerospace component trade flows were triangulated for convergence.
Data-stream reconciliation across shipment volumes, certification queue lengths, and insurance premium bundling economics informed the analytical framework. Segmentation dimensions modeled include product type, deployment platform, application vertical, and end-user procurement centralization across the projection horizon. CAGRs were derived from fleet protection mandate trajectories and regulatory compliance timeline compression. Industry-specific forecast inputs incorporated ASTM F3322-22 adoption curves and EASA Specific Category operational approval velocity.
The model assumes a particular technology adoption path; alternative pathways for machine-vision descent assessment replacing barometric triggers would alter the outlook for standalone trigger module suppliers. Forecasts reflect underlying assumptions about certification convergence and fleet insurance bundling penetration. Practitioners should monitor EASA-FAA harmonization negotiations and Indian PLI scheme implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
United States ROV Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Armored Unmanned Underwater Vehicle Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Military Autonomous Robot Market