
 Autonomous Precision Guided Munition Market | 2026-2036
Autonomous Precision Guided Munition Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Precision Guided Munition Market Outlook
Platform lifecycle sustainment revenue is reshaping how prime contractors capture value beyond initial procurement. Lockheed Martin leverages its integrated battlespace management systems to extend platform utility across multiple operational domains. RTX anchors its position through dense supplier networks in guidance electronics and propulsion subsystems. Boeing competes by controlling aerial delivery certification pathways that govern NATO interoperability standards.
Autonomous precision guided munitions are self-propelled or glide weapons integrating inertial measurement units, multi-spectral seekers, and onboard decision algorithms to strike coordinates or moving targets with circular error probable below ten meters; manufacturers machine titanium alloy airframes and composite wings to survive high-G maneuvers while thermal batteries power mission computers through electromagnetic-contested environments. Loitering munitions now represent the fastest-expanding product category as endurance thresholds push past six hours and swarm coordination protocols mature. Artificial Intelligence navigation segments command premium positioning due to classification sensitivity and firmware update cycles that lock buyers into vendor ecosystems.
The US Department of Defense mandates MIL-STD-810 environmental testing and ITAR compliance for all exported autonomous munition systems, while the EU AI Act imposes human-in-the-loop verification requirements on member-state procurement of target-recognition-enabled weapons. Israel's national regulator enforces end-use monitoring agreements that restrict re-export of image-recognition guidance modules to third parties. Stakeholders must track how divergent AI weapon governance between Washington and Brussels fragments supplier certification burdens.
Market Dynamics
Artificial intelligence-enabled target recognition is compressing development cycles while fragmenting supplier certification requirements across Washington and Brussels, forcing primes to maintain parallel compliance architectures for the same hardware platforms.
Growth Catalysts
- NATO contested airspace doctrine:Alliance procurement guidelines now mandate loitering munition inventories for forward-deployed units, accelerating national replenishment programs across member states.
- Thermal battery chemistry advances:Solid-state power systems extending mission endurance past electromagnetic-contested thresholds are unlocking operational concepts previously limited by electronic warfare vulnerability.
- ITAR compliance infrastructure:The US Department of Defense's mandated export control framework creates captive demand for domestically cleared supply chains, insulating certified primes from price-based competition.
Market Restraints
- Titanium alloy supply concentration:Aerospace-grade Ti-6Al-4V forging capacity clusters in a limited supplier base, exposing airframe producers to input volatility and allocation risk.
- EU AI Act human-in-the-loop mandates:Brussels' verification requirements for target-recognition-enabled weapons impose firmware architecture constraints that increase unit cost and extend qualification timelines.
- Legacy platform substitution:Precision-guided artillery shells with extended range are reclaiming mission profiles previously ceded to autonomous systems in permissive electromagnetic environments.
Strategic Opportunities
- Swarm coordination protocol standardization:Interoperability frameworks for multi-vehicle collaborative targeting remain undefined, creating first-mover advantage for primes that establish de facto industry protocols.
- Platform lifecycle sustainment unbundling:Firmware update ecosystems and mission computer refresh cycles offer recurring revenue streams detached from hardware procurement cycles.
- Turkey's domestic production acceleration:Ankara's import substitution policies for guidance electronics create partnership openings for component suppliers seeking NATO-adjacent market access.
Industry Challenges
- Multi-spectral seeker calibration expertise:The specialized workforce capable of integrating infrared, millimeter-wave, and electro-optical sensors in compact packages remains concentrated in defense primes with decades of captive development.
- MIL-STD-810 environmental qualification timelines:Extended thermal, shock, and humidity testing protocols compress program schedules and delay revenue recognition for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Precision Guided Munition Market |
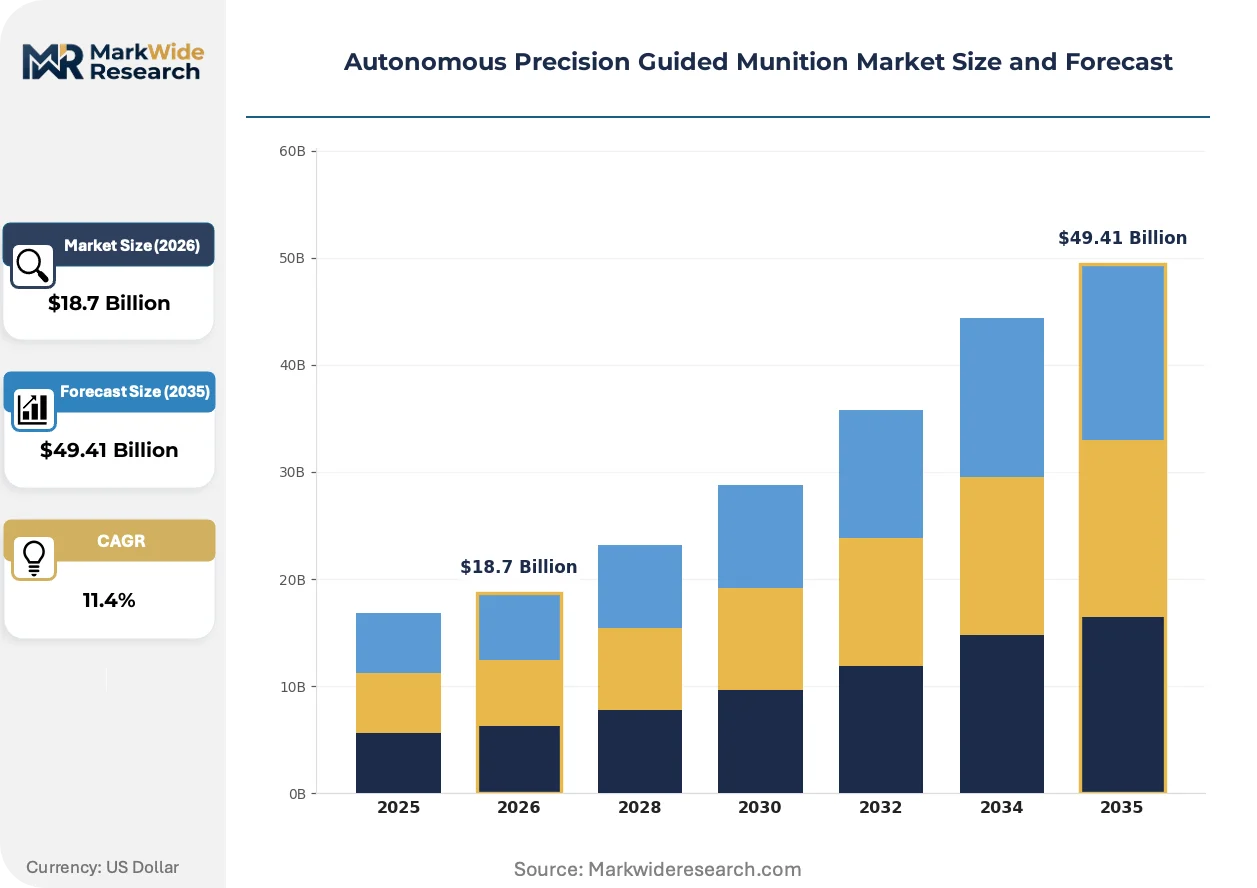
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bombs, Guided Missiles, Loitering Munitions, Targeting Drones Technology: Inertial Navigation, GPS Navigation, Image Recognition, Artificial Intelligence End User: Military Forces, Defense Contractors, Government Agencies, Private Security Firms Delivery Mode: Aerial Delivery, Ground Launch, Shipborne Launch, Underwater Launch |
| Companies Covered | Lockheed Martin Corporation, RTX, Northrop Grumman, BAE Systems, General Dynamics Corporation, Boeing, MBDA, Israel Aerospace Industries, Aselsan AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Precision Guided Munition Market Strategic Shifts
Navigation and guidance architectures are converging toward modular, firmware-upgradable systems that decouple hardware procurement from capability refresh cycles, restructuring how military buyers evaluate total cost of ownership.
Multi-spectral seeker technology is hybridizing previously separate infrared and millimeter-wave targeting channels into unified sensor packages. Israeli and Turkish forces are fielding these systems at squad-level procurement scales. This convergence is hybridizing supplier ecosystems as electronics houses previously focused on single-spectrum solutions must now master fusion algorithms or exit the segment.
Washington's ITAR compliance mandates and Brussels' EU AI Act human-in-the-loop requirements are diverging on autonomous target engagement protocols. Primes must now maintain parallel firmware branches—one with operator-confirmation gates for European delivery, one with delegated engagement authority for US special operations units. Loitering munitions with AI navigation modules face the stiffest dual-certification burden, compressing margins on premium product lines.
Defense ministries are consolidating procurement authority into centralized program offices that unbundle hardware acquisition from sustainment services. Traditional prime-contractor relationships with individual service branches are giving way to enterprise-level framework agreements covering multi-year platform support. This concentration is most visible in US Special Operations Command and Israel's Ministry of Defense, where single-source indefinite-delivery vehicles now dominate autonomous munition acquisition.
Autonomous Precision Guided Munition Market Segmentation
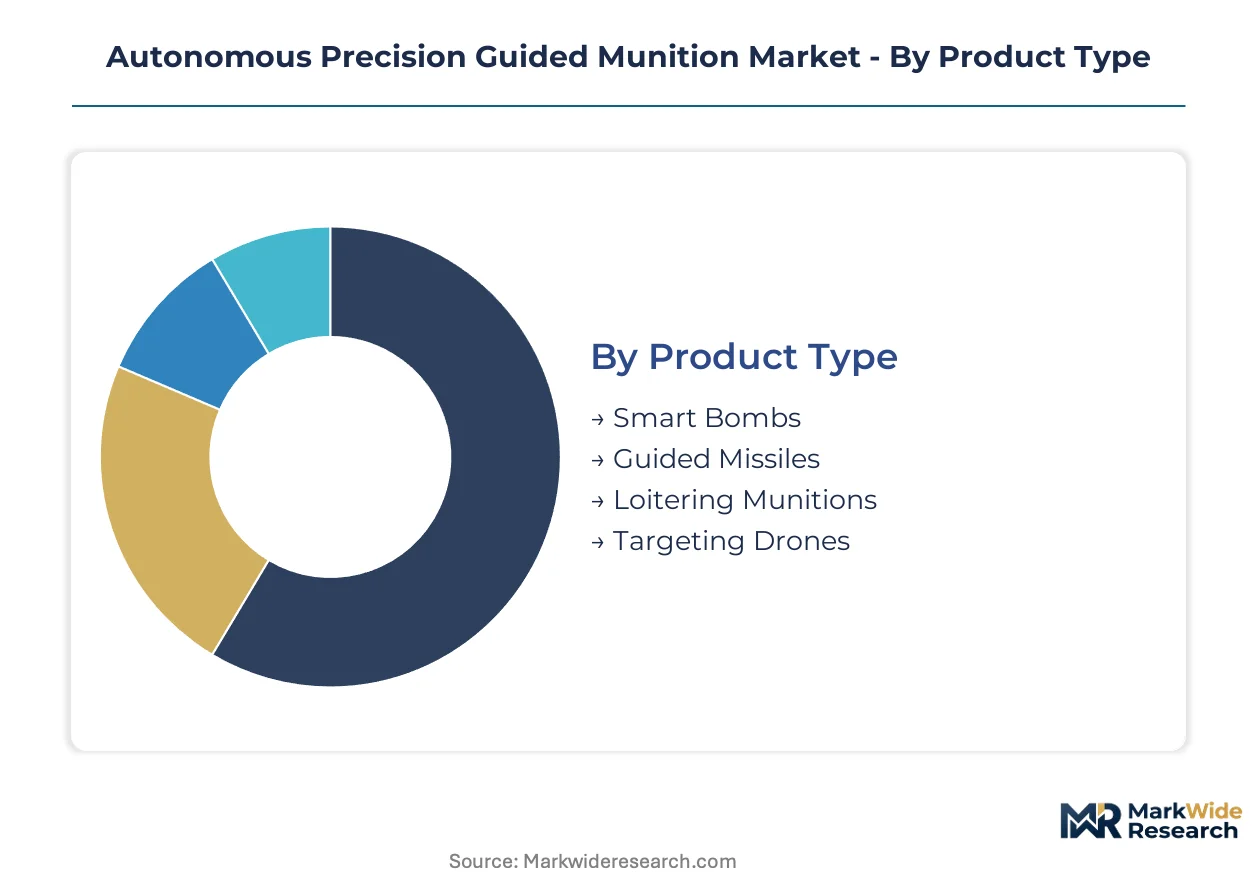
Segmentation in autonomous precision guided munitions reveals how procurement cycles, certification burdens, and operational concepts fragment addressable demand. Buyers evaluate platforms through divergent lenses—endurance thresholds for loitering systems, seeker sophistication for smart bombs, and launch modality for contested logistics.
Product Type:
Loitering munitions turn over fastest as endurance benchmarks reset every eighteen months, while smart bomb inventories rotate slowest due to fused warhead shelf-life constraints and storage certification costs.
- Smart Bombs:Fixed-wing glide weapons with strap-on guidance kits converting unguided ordnance into precision platforms. United States Air Force procurement concentrates here for contested airspace suppression, though GPS-denial vulnerability drives seeker diversification.
- Loitering Munitions:Endurance platforms with abort capability and man-in-the-loop recall. Israeli and Turkish military forces field these at squad level, compressing development cycles as swarm protocols mature and six-hour endurance thresholds become baseline.
- Guided Missiles:Self-propelled interceptors with active radar or infrared terminal guidance for point defense and deep strike missions.
- Targeting Drones:Non-kinetic ISR platforms that designate coordinates for separate strike systems rather than carrying warheads.
Smart bombs dominate installed base. Loitering munitions are where expansion concentrates.
Technology:
Cost tiers separate navigation architectures—image recognition and AI modules command three to five times the unit economics of inertial systems due to firmware lock-in and classification overhead.
- Artificial Intelligence:Onboard target classification algorithms enabling delegated engagement authority. EU AI Act human-in-the-loop mandates fragment procurement as Brussels requires operator confirmation gates that US special operations units bypass.
- Image Recognition:Electro-optical and infrared seekers with template-matching software for moving target identification. Israeli forces deploy these extensively, though end-use monitoring agreements restrict re-export of guidance modules.
- GPS Navigation:Satellite-dependent positioning vulnerable to jamming but lowest cost for permissive electromagnetic environments.
- Inertial Navigation:Self-contained gyroscopic and accelerometer-based guidance resistant to electronic warfare but accumulating drift error over time.
Inertial navigation holds the deepest installed base. Artificial intelligence is climbing the fastest.
End User:
Customer type determines contract structure—military forces drive volume through multi-year framework agreements while private security firms purchase sporadically with limited technical support.
- Military Forces:National armed services with centralized procurement authority and MIL-STD-810 qualification requirements. NATO contested airspace doctrine mandates loitering munition inventories, accelerating replenishment programs.
- Defense Contractors:Prime manufacturers integrating subsystems for government clients, capturing value through platform lifecycle sustainment and firmware update ecosystems.
- Government Agencies:Non-military state entities with border security and counter-terrorism missions, often restricted to less sophisticated seeker technologies.
- Private Security Firms:Commercial entities with limited ITAR clearance and constrained access to AI-enabled target recognition systems.
Military forces dominate installed base. Defense contractors are where margin expansion concentrates.
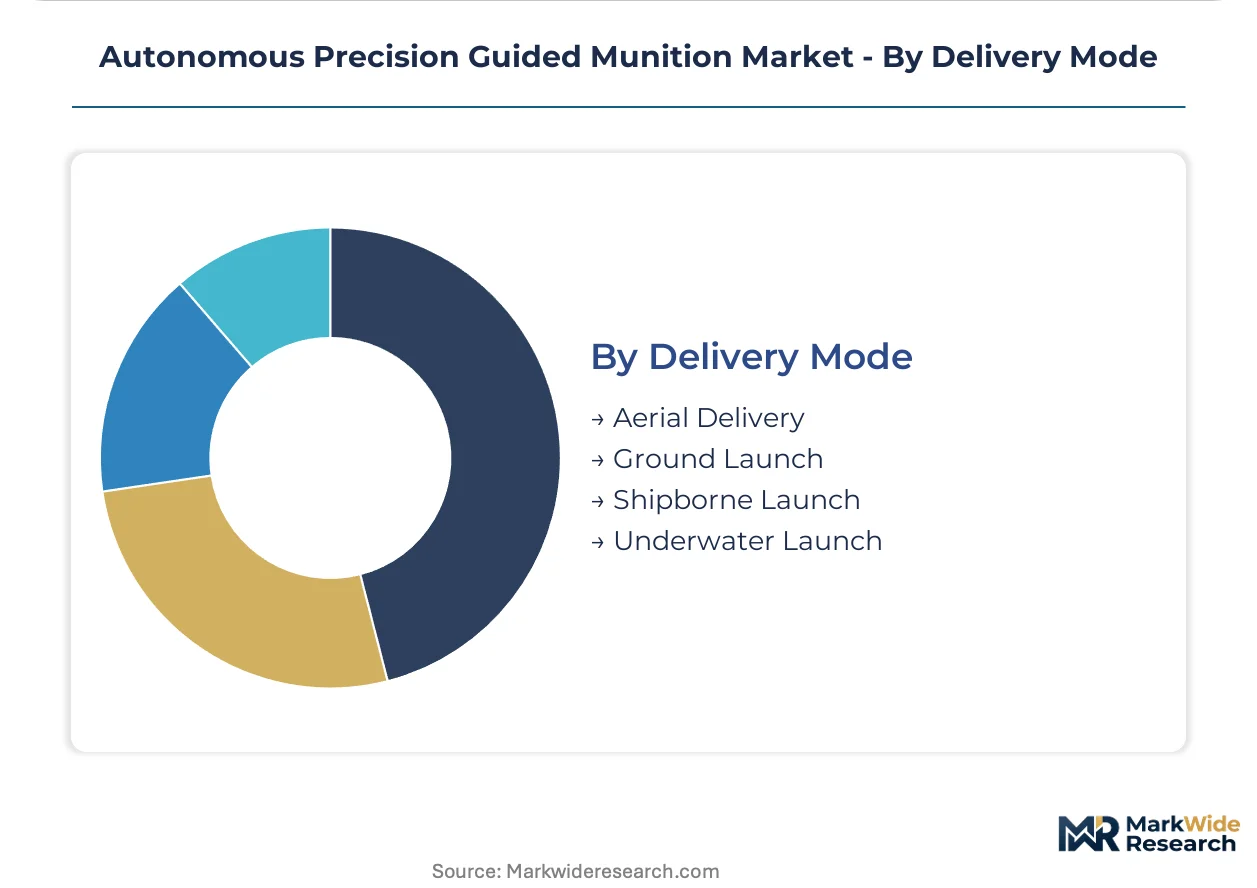
Delivery Mode:
Application context dictates launch modality—aircraft integration requires FAA and military airworthiness certification, while ground launch systems face lower barrier-to-entry but reduced range-payload tradeoffs.
- Aerial Delivery:Fixed-wing and rotary-wing aircraft deployment with NATO interoperability standards governing release envelope certification. Boeing controls certification pathways that govern alliance-wide procurement.
- Ground Launch:Vehicle-mounted or dismounted tube launch systems for forward-deployed units. Turkish domestic production acceleration centers here, creating partnership openings for component suppliers.
- Shipborne Launch:Naval vertical launch or deck-mounted systems for maritime strike and area denial missions.
- Underwater Launch:Submarine tube or encapsulated delivery for covert deep-strike capabilities with specialized pressure-hull requirements.
Aerial delivery dominates installed base. Ground launch is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Turkey and Israel demonstrate the highest price elasticity as domestic production accelerates, while United States and German procurement offices prioritize performance over unit cost under multi-year framework agreements.
United States
US Special Operations Command drives loitering munition demand through indefinite-delivery vehicles that bundle hardware with firmware sustainment. The Department of Defense mandates ITAR compliance and MIL-STD-810 environmental testing for all exported autonomous systems. Tucson, Arizona hosts dense supplier networks in guidance electronics where RTX anchors propulsion subsystem production.
Israel
Israeli Defense Forces field electro-optical seekers at squad-level procurement scales unmatched elsewhere. The national regulator enforces end-use monitoring agreements that restrict re-export of image-recognition guidance modules. Haifa's defense corridor concentrates multi-spectral sensor integration expertise that feeds both domestic and selective NATO supply chains.
Turkey
Ankara's import substitution policies for guidance electronics compress development cycles for ground-launched loitering systems. Defense procurement offices prioritize NATO-adjacent certification pathways for export-oriented production lines. Ankara and Istanbul host emerging domestic primes that partner with European component suppliers seeking regional market access.
Germany
The Bundeswehr's contested airspace doctrine mandates loitering munition inventories for forward-deployed units under NATO alliance guidelines. The EU AI Act imposes human-in-the-loop verification requirements that fragment firmware architecture for European delivery. Bavaria's aerospace cluster around Munich hosts precision machining capacity for titanium alloy airframe components.
United Kingdom
UK Ministry of Defence procurement consolidates authority into centralized program offices that unbundle hardware from sustainment services. BAE Systems leverages integrated battlespace management relationships to extend platform utility across operational domains. Stevenage and Bristol host guidance electronics development where dense supplier networks compete for prime contractor tier-one status.
Autonomous Precision Guided Munition Market Competitive Environment
Capability concentration sits with primes possessing decades of multi-spectral seeker calibration expertise; scale advantage sits with defense conglomerates controlling NATO certification pathways and export license infrastructure. The market structures around three archetypes: integrated battlespace managers, guidance electronics specialists, and airframe certification controllers. Consolidation pressure intensifies as firmware update ecosystems create recurring revenue streams that lock buyers into vendor relationships. Competitive moves center on strategic partnerships for swarm coordination protocol development and geographic expansion through NATO-adjacent production licensing.
Within the integrated battlespace tier, Lockheed Martin Corporation and Northrop Grumman exemplify primes that extend platform utility across multiple operational domains through dense supplier network control. RTX occupies a position among guidance electronics specialists, anchoring propulsion and seeker subsystem supply chains that feed prime contractor assembly lines. Boeing sits within the certification-control archetype, leveraging aerial delivery pathway governance that shapes NATO interoperability standards and release envelope protocols for alliance-wide procurement.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX |
| Northrop Grumman |
| BAE Systems |
| General Dynamics Corporation |
| Boeing |
| MBDA |
| Israel Aerospace Industries |
| Aselsan AS |
| Others |
Value Chain & Pricing Dynamics
The Antwerp-Rotterdam freight corridor's elevated container rates compress margins for titanium alloy airframe components moving from Bavarian machining centers to Turkish assembly plants, while simultaneously amplifying price differentiation between ITAR-certified and non-certified guidance electronics tiers.
Pricing Analysis
Firmware update subscriptions and mission computer refresh contracts drive lifetime value capture beyond hardware procurement. Three-tier pricing structure across premium AI-enabled, standard image-recognition, and economy inertial navigation levels reflects certification grade and seeker sophistication. Cost compression in economy tiers intensifies as Turkish domestic production scales ground-launched platforms. Private security firms exhibit highest price sensitivity; US Special Operations Command demonstrates lowest elasticity under indefinite-delivery vehicle structures.
Supply Chain Analysis
Extended payment terms from prime contractors to titanium forging houses in Germany and sensor packaging facilities in Israel stabilize working capital through electromagnetic-contested production cycles. Supply draws from United States guidance electronics clusters, Israeli multi-spectral seeker integration corridors, and Turkish ground-launch assembly lines. Solid-state thermal battery chemistry and aerospace-grade Ti-6Al-4V forgings represent critical input dependencies. Single-source vulnerability concentrates in millimeter-wave sensor calibration expertise. Distribution runs through NATO-aligned defense procurement offices with centralized program authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of engineers capable of fusing infrared, millimeter-wave, and electro-optical sensors in compact munition packages concentrates competitive advantage with primes possessing decades of captive development investment.
For Market Incumbents: Build firmware ecosystem lock-in by accelerating swarm coordination protocol standardization before de facto industry norms solidify. Capture platform lifecycle sustainment revenue through unbundled mission computer refresh cycles. Counter Turkish domestic production acceleration by anchoring NATO certification pathway control. For New Entrants and Emerging Players: Build out ground-launched loitering munition partnerships with Ankara's import substitution programs to secure NATO-adjacent market access. Target squad-level procurement scales in Israeli and Turkish forces where development cycles compress fastest. Pursue component supplier tier-one status through guidance electronics specialization rather than full-platform competition. For Investors and Strategic Acquirers: Multi-spectral seeker calibration specialists with captive defense prime relationships represent the most defensible acquisition profile across the projection horizon. Monitor divergence between Washington ITAR mandates and Brussels EU AI Act requirements as the critical inflection signal for parallel compliance architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Swarm Coordination Protocol Standardization | First-mover advantage in undefined interoperability frameworks locks competitors out of NATO procurement. |
| Firmware Ecosystem Development | Recurring revenue streams detach value capture from hardware procurement cycles for prime contractors. |
| Turkish Domestic Production Partnership | European component suppliers gain NATO-adjacent market access through Ankara's import substitution policies. |
| Dual-Certification Architecture Investment | Parallel ITAR and EU AI Act compliance branches capture both US special operations and European military demand. |
| Platform Lifecycle Sustainment Unbundling | Enterprise framework agreements with centralized program offices reshape prime-contractor relationships. |
Study Parameters
Operator-level perspectives from guidance electronics procurement officers, multi-spectral seeker calibration engineers, defense prime program managers, and Turkish domestic production specialists anchored the qualitative base. Primary interview findings triangulated against ITAR compliance filings, EU AI Act regulatory texts, NATO contested airspace doctrine publications, and US Department of Defense indefinite-delivery vehicle announcements. Bottom-up platform deployment estimates and top-down defense budget allocation analysis converged through iterative validation.
Scenario-bracketing framed optimistic, baseline, and constrained demand paths across the projection horizon. Segmentation dimensions spanned product type, navigation architecture, end-user procurement authority, and delivery modality. CAGRs derived from deployment trajectory modeling and replacement cycle analysis. Thermal battery chemistry advancement curves and electromagnetic-contested environment operational concept diffusion served as munition-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Turkish domestic primes or accelerated EU AI Act enforcement would shift outcomes. Macroeconomic defense budget contraction, export control regime fragmentation, or breakthrough precision-guided artillery shell performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Integrated Range Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Subsea Navigation and Tracking Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Military Robots Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
Europe Aerostat Systems Market