
 Aviation Connector Market | 2026-2036
Aviation Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Connector Market Intelligence
The European Union's Green Deal, with its mandates for sustainable aviation, is restructuring component selection criteria toward lighter and more efficient designs. Amphenol Corporation leverages its broad portfolio to serve diverse requirements from commercial to military aviation end-users. TE Connectivity differentiates through its development of high-speed and fiber optic solutions tailored for modern avionics data networks.
Aviation connectors are specialized electromechanical devices designed to provide secure, reliable electrical and data connections within aircraft systems. These components feature robust shells, often made of aluminum or composites, and must withstand extreme vibration, temperature fluctuations, and fluid exposure per standards like ARINC 801. Circular connectors remain the dominant product type for power and signal applications in commercial aviation. However, fiber optic connectors represent the fastest-growing segment, driven by bandwidth demands in new avionics and drone applications.
Compliance with stringent airworthiness standards from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) is mandatory. These regulations, alongside ISO 9100 for quality management, govern material specifications, performance testing, and manufacturing traceability for all flight-critical components. Suppliers must now navigate a complex decision matrix balancing next-generation performance requirements against persistent pressures on cost and supply chain resilience.
Market Dynamics
The imperative to electrify aircraft systems, balanced against the non-negotiable demands of airworthiness certification from bodies like the FAA and EASA, forms the central dynamic shaping component design and material selection in the aviation connector market.
Growth Catalysts
- Drone Applications:The expansion of unmanned aerial vehicle use in commercial delivery, agricultural monitoring, and military intelligence, surveillance, and reconnaissance missions is creating substantial new demand for lightweight, high-vibration connectors.
- More-Electric Aircraft (MEA):The architectural shift toward MEA designs replaces hydraulic and pneumatic systems with electrical ones, necessitating a higher density of reliable power and signal connectors throughout the airframe.
- Chinese Industrial Policy:Dedicated national policies in China supporting the growth of indigenous aerospace manufacturing, including for commercial airliners, are creating a concentrated and fast-growing geographic market for certified components.
Market Restraints
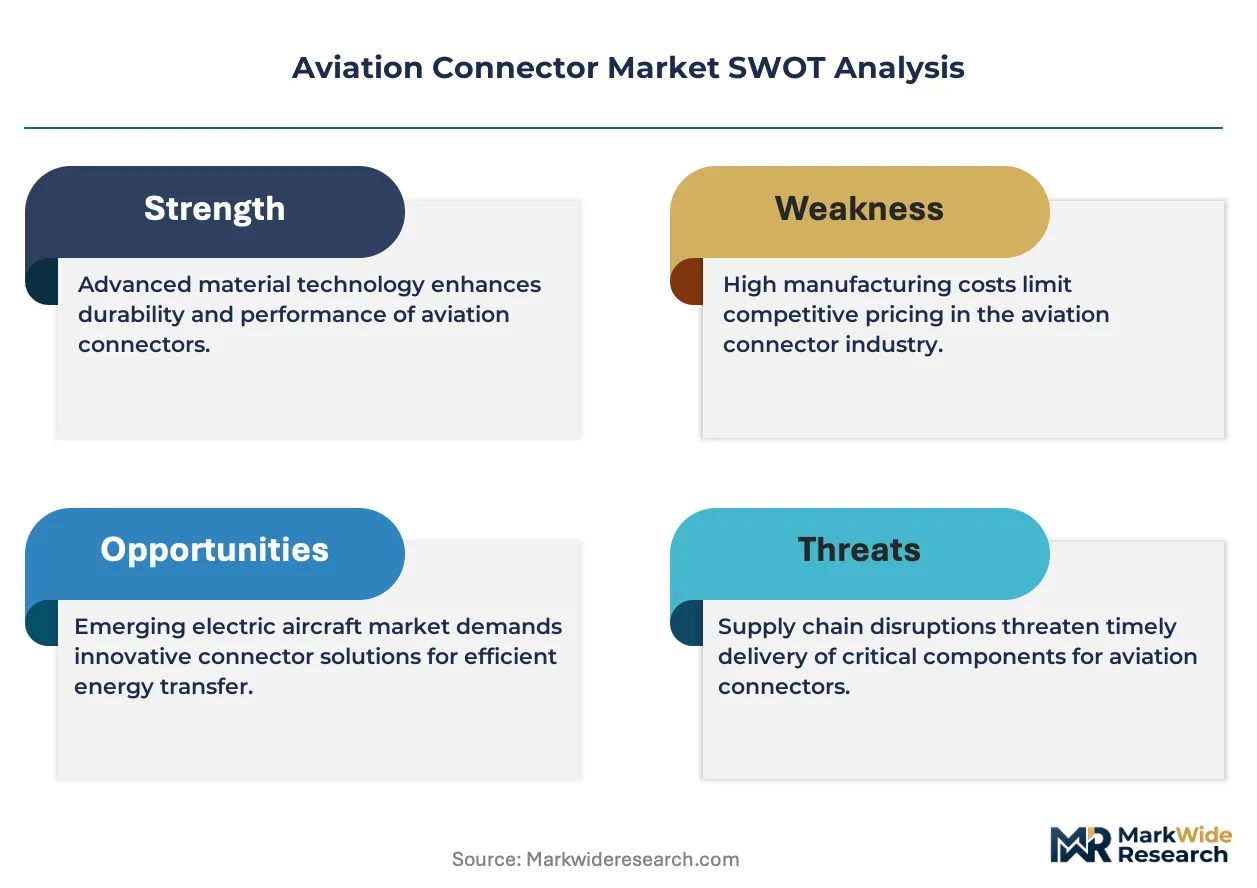
- Long Qualification Cycles:New connector materials and designs, particularly those using advanced composites for weight reduction, face multi-year qualification and testing periods to prove compliance with stringent aerospace performance standards.
- Stringent Certification:The complex and costly process of achieving and maintaining certification from airworthiness authorities like the US Federal Aviation Administration and EASA acts as a significant barrier to entry and slows the adoption of innovation.
- Supply Base Concentration:A limited number of suppliers are qualified to produce flight-critical interconnects under standards like ISO 9100, leading to potential supply chain bottlenecks and reduced negotiating power for aircraft OEMs.
Strategic Opportunities
- Urban Air Mobility (UAM):The emerging market for electric vertical take-off and landing (eVTOL) aircraft for UAM presents a white-space opportunity for novel, high-voltage, and lightweight connector solutions tailored to their unique power distribution needs.
- Hybrid Connector Development:Integrating fiber optic contacts into traditional circular connector shells offers a pathway to provide both high-speed data and electrical power within a single, space-saving interconnect for modern avionics suites.
- Sustainable Aviation Mandates:The European Union's Green Deal and related initiatives create a strong commercial incentive for developing lighter connectors from recyclable or sustainable materials that contribute to overall aircraft fuel efficiency.
Industry Challenges
- Legacy System Integration:Integrating modern, high-speed fiber optic and miniaturized connectors into existing aircraft platforms during retrofits presents significant technical challenges related to wiring compatibility and space constraints.
- Material Traceability Compliance:Suppliers face an ongoing operational burden to maintain meticulous documentation and traceability for all raw materials and manufacturing processes to satisfy the rigorous audits of aviation safety agencies.
- Specialized Skills Gap:A shortage of engineers with combined expertise in high-frequency RF design, materials science, and the mechanical engineering of ruggedized components hampers new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Connector Market |
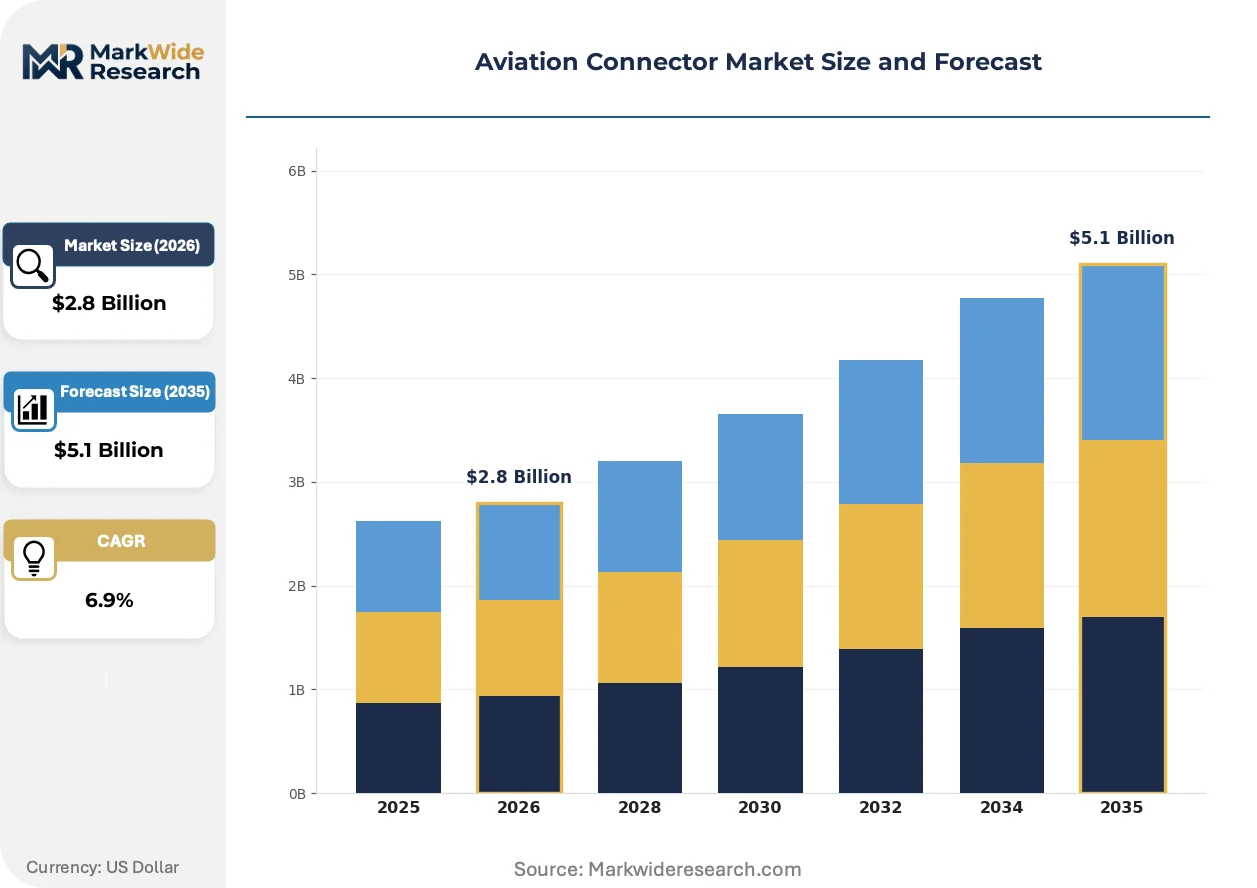
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.1 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Connectors, Circular Connectors, Fiber Optic Connectors, Coaxial Connectors Technology: Electrical Connectors, Optical Connectors, Radio Frequency Connectors, Hybrid Connectors End User: Commercial Aviation, Military Aviation, General Aviation, Drone Applications Installation: Onboard Systems, Ground Support Equipment, Avionics, Power Distribution Systems |
| Companies Covered | Amphenol Corporation, TE Connectivity, Eaton, Smiths Group plc, ITT Inc., Radiall, Bel Fuse Inc., IEH Corporation, Apollo Aerospace Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Connector Market Strategic Shifts & Innovations
Component design is pivoting toward higher data density and power efficiency to support next-generation avionics. This evolution creates tension between the need for miniaturization and the established requirements for extreme environmental and mechanical resilience.
Smart connectors incorporating embedded sensors provide real-time monitoring of temperature, vibration, and connection integrity. These intelligent components are seeing adoption in new commercial airliners and advanced military platforms to enable predictive maintenance strategies. This embedded sensing capability is automating fault detection and diagnostic processes, which helps reduce costly aircraft on ground (AOG) events and streamlines maintenance scheduling.
The European Union's REACH regulation is restricting the use of certain chemicals, including hexavalent chromium which has been a standard for corrosion-resistant plating on connector shells. This forces manufacturers to invest in qualifying alternative coatings that meet performance requirements without using banned substances. The military and long-lifecycle commercial aerospace segments are most affected, as they require extensive re-testing to validate new materials.
Aircraft manufacturers are increasingly sourcing pre-tested, integrated cable assemblies rather than procuring individual connectors and wires. This model disrupts the traditional component-level distribution channel, favoring suppliers that offer value-added design, assembly, and testing services. The shift is most prominent within the business jet and advanced drone manufacturing sectors in North America and Europe, where supply chain simplification accelerates production timelines.
Aviation Connector Market Segmentation
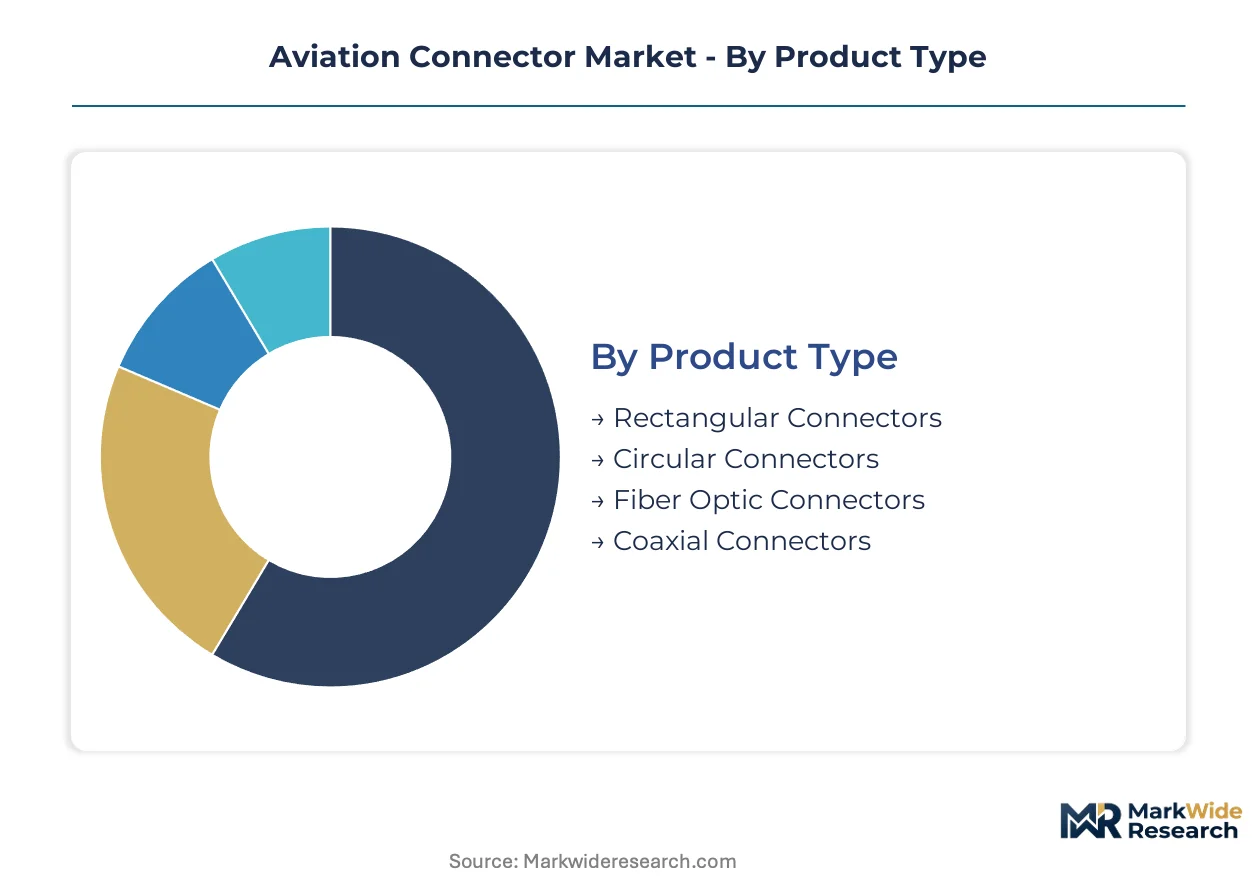
Segmentation analysis within the aviation connector market clarifies the diverse technical requirements and application-specific demands across various aircraft platforms. This detailed breakdown helps identify areas of high growth, specialized needs, and differing regulatory compliance burdens for component manufacturers.
Product Type:
Product type segmentation in aviation connectors highlights the diverse technical specifications required, differentiating between high-volume standard components and specialized premium solutions.
- Fiber Optic Connectors:These connectors transmit data via light pulses, offering high bandwidth and immunity to electromagnetic interference. Demand concentrates within new avionics systems and drone applications, driven by increased data transfer needs.
- Circular Connectors:Circular connectors feature robust cylindrical shells, providing secure power and signal connections in harsh environments. Commercial aviation applications show significant demand for these components, ensuring reliability in flight-critical systems.
- Rectangular Connectors:Rectangular connectors offer high pin density within a compact form factor, suitable for space-constrained modules.
- Coaxial Connectors:Coaxial connectors provide shielded connections for radio frequency signals, essential for aircraft communication systems.
Mature deployment sits with Circular Connectors. Newer deployment is concentrated in Fiber Optic Connectors.
Technology:
Technology segmentation reveals the functional specialization of connectors across various aircraft systems, from basic power delivery to complex data transmission.
- Hybrid Connectors:Hybrid connectors combine multiple signal types, such as electrical, optical, and RF, within a single housing. Urban Air Mobility (UAM) platforms leverage these components for integrated power and data needs, simplifying wiring harnesses.
- Optical Connectors:Optical connectors facilitate high-speed, interference-free data transfer using fiber optic cables. New commercial airliners and advanced military platforms drive demand for these components, supporting next-generation avionics.
- Electrical Connectors:Electrical connectors transmit power and low-frequency signals, forming the backbone of aircraft electrical systems.
- Radio Frequency Connectors:Radio Frequency connectors handle high-frequency signals for communication and radar systems, requiring impedance matching.
These technologies support both foundational aircraft functions and emerging advanced capabilities.
End User:
End-user segmentation clarifies distinct performance requirements and procurement channels across different aviation sectors, from regulated commercial fleets to specialized military applications.
- Drone Applications:Connectors for drones prioritize miniaturization, lightweight design, and resistance to high vibration. Commercial delivery and military intelligence, surveillance, and reconnaissance missions significantly drive demand for these specialized components.
- Military Aviation:Military connectors require extreme ruggedness, environmental sealing, and resistance to harsh fluids and temperatures. Global defense spending and the modernization of military aircraft sustain consistent demand for highly durable interconnects.
- Commercial Aviation:Commercial aviation connectors emphasize reliability, long service life, and compliance with stringent airworthiness standards.
- General Aviation:General aviation connectors balance performance with cost-effectiveness, serving a broad range of private and business aircraft.
Each segment exhibits unique certification pathways and operational priorities.
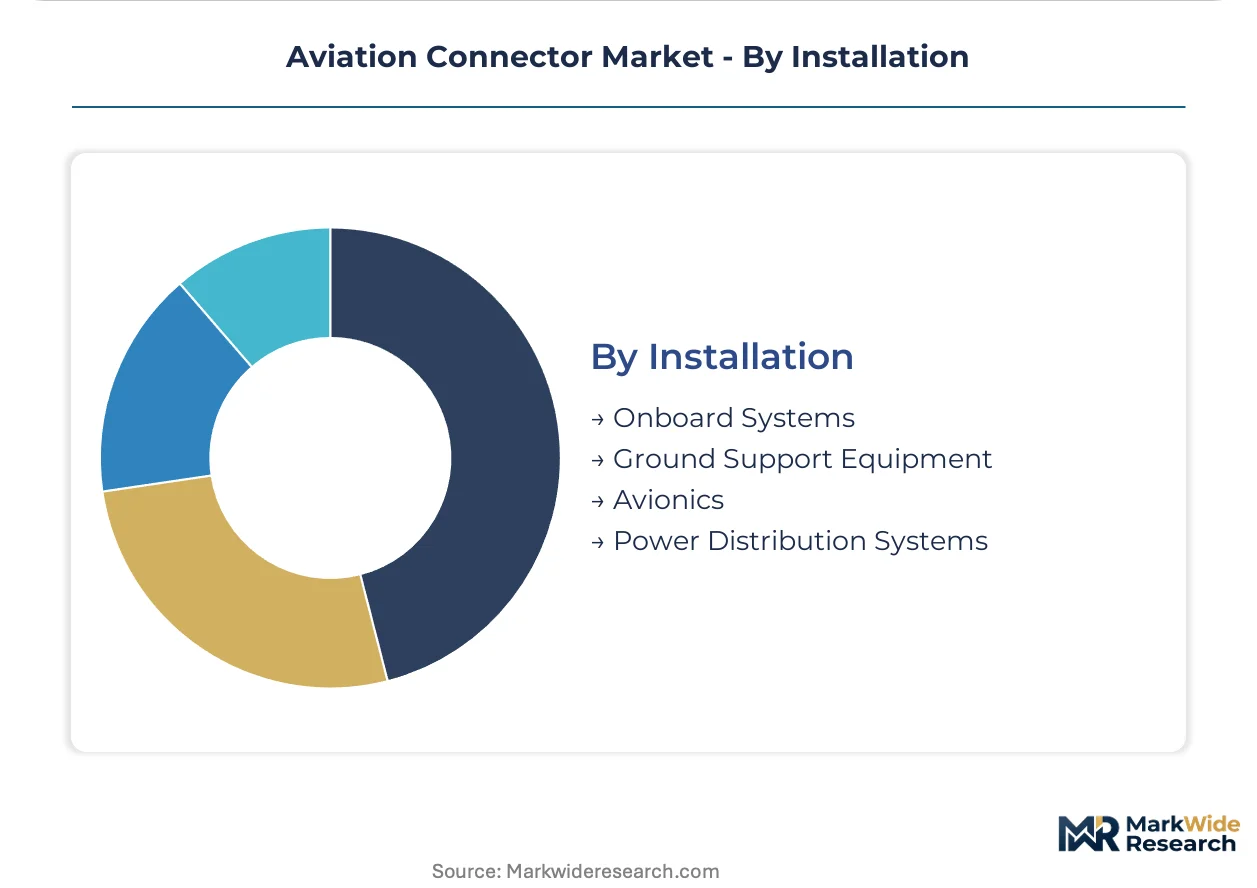
Installation:
Installation segmentation delineates where connectors are deployed within the aircraft ecosystem, reflecting their functional integration into specific systems.
- Avionics:Avionics connectors facilitate data and power transfer for flight control, navigation, and communication systems. The shift towards more-electric aircraft and advanced digital cockpits increases demand for high-speed, high-density solutions in this area.
- Power Distribution Systems:These connectors manage high current and voltage for aircraft power networks, requiring robust insulation and thermal management. Electrification initiatives in both commercial and military aircraft drive demand for high-power, reliable connectors.
- Onboard Systems:Onboard systems connectors support various internal aircraft functions, from cabin lighting to entertainment units.
- Ground Support Equipment:Ground support equipment connectors enable power and data links between aircraft and ground operations, demanding durability for repeated use.
Connector specifications vary significantly depending on their proximity to flight-critical functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace manufacturing hubs globally drive demand for specialized aviation connectors. The Seattle metropolitan area, home to major aircraft manufacturers, exemplifies a key center for innovation and procurement. European aerospace clusters also contribute significantly.
United States
The United States experiences strong demand from commercial and defense sectors for high-density, reliable interconnects. US Federal Aviation Administration (FAA) regulations dictate rigorous performance and traceability. The aerospace corridor in Southern California develops next-generation fiber optic solutions for advanced avionics.
China
China's indigenous aerospace manufacturing sector fuels substantial demand for certified aviation connectors. Dedicated national industrial policies prioritize local sourcing and technological self-sufficiency. The Yangtze River Delta region, particularly Shanghai, serves as a hub for production and integration of advanced interconnects.
France
French aerospace manufacturers require lightweight, efficient connector designs, driven by European Union Green Deal mandates. European Union Aviation Safety Agency (EASA) standards govern component qualification. The Toulouse region, a major aerospace hub, concentrates on developing hybrid connector solutions for next-generation avionics systems.
Germany
Germany's aviation sector, particularly in advanced manufacturing, seeks connectors for Urban Air Mobility (UAM) and sophisticated avionics. German national aviation authorities ensure stringent adherence to EASA regulations for aerospace components. The Munich area, with its strong engineering base, researches high-voltage, miniaturized connector solutions for eVTOL aircraft.
Aviation Connector Market Key Industry Players
The competitive structure tilts toward established, vertically integrated manufacturers with extensive product portfolios. The market exhibits a tiered consolidation, with a few large players dominating critical segments and numerous specialized firms serving niche applications. Strategic archetypes include diversified industrial conglomerates leveraging broad engineering expertise and focused aerospace interconnect specialists providing high-performance solutions. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
On the premium-tier vector, Amphenol Corporation exemplifies a diversified industrial conglomerate with a broad product offering for various end-user requirements. TE Connectivity, a global technology company, occupies a strong position in developing advanced high-speed and fiber optic solutions. French-based Radiall, as an interconnect specialist, represents a key player in providing robust circular and rectangular connectors for demanding aerospace applications. These companies anchor the market through their extensive qualification processes and adherence to stringent airworthiness standards.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Eaton |
| Smiths Group plc |
| ITT Inc. |
| Radiall |
| Bel Fuse Inc. |
| IEH Corporation |
| Apollo Aerospace Components |
| Others |
Cost & Logistics Intelligence
Aluminum futures pricing directly influences the cost of robust connector shells. This impact cascades through the supply chain, shaping the pricing tiers for certified aviation components.
Pricing Analysis
Aircraft uptime and system reliability anchor pricing for aviation connectors. The dominant structure involves contract-based long-term offtake agreements with OEMs. Price differentiation stems from stringent FAA/EASA certification levels and the degree of customization for specific aircraft platforms. Pricing softness reflects increased competition from emerging Chinese suppliers. General aviation buyers exhibit the highest price sensitivity, while military aviation prioritizes performance over cost.
Supply Chain Analysis
Direct-to-OEM channels handle the majority of aviation connector distribution for critical systems. Supply concentration centers in the United States, China, and Germany, reflecting aerospace manufacturing hubs. The industry relies on high-purity copper, specialized composite materials, and rare earth elements. Single-source vulnerability for highly specialized, certified interconnects poses a significant supply chain risk. Aftermarket distribution primarily serves MRO operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aviation connector market is undergoing a technology-transition phase, with fiber optic connectors steadily displacing legacy electrical interconnects in new aircraft platforms. This shift reflects the increasing demand for high-speed data transfer within modern avionics.
For Market Incumbents: Anchor existing market share by accelerating investment in new material qualification processes, particularly for REACH-compliant coatings. Deepen vertical integration into advanced manufacturing capabilities to counter margin pressure from emerging Chinese suppliers. Prioritize R&D in hybrid connector solutions to address the evolving needs of more-electric aircraft architectures. Strengthen relationships with airworthiness authorities to maintain certification advantages.
For New Entrants and Emerging Players: Online component marketplaces provide a direct route to penetrate the fragmented general aviation and drone manufacturing segments. Target white-space opportunities in Urban Air Mobility (UAM) for novel high-voltage and lightweight connector solutions. Focus on specialized drone applications where miniaturization and high-vibration resistance are paramount. Offer rapid prototyping and modular designs to accelerate product development cycles for agile customers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized component manufacturers in Europe, particularly those with strong certification portfolios. The market demonstrates long-term viability, underpinned by aerospace safety and performance requirements over the next decade. Acquisition targets include mid-cap specialists excelling in fiber optic and hybrid connector R&D. A key signal to watch is the acceleration of investment in Urban Air Mobility (UAM) infrastructure and eVTOL production.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in REACH-compliant material R&D | Ensures long-term market access in Europe due to environmental regulations. |
| Develop high-speed fiber optic solutions | Addresses escalating data bandwidth demands in next-generation avionics systems. |
| Expand capabilities for integrated cable assemblies | Captures value-added design and testing services for aircraft OEMs. |
| Pursue certification for UAM-specific connectors | Positions for early market leadership in the emerging eVTOL aircraft sector. |
| Strengthen supply chain resilience through dual sourcing | Mitigates single-source vulnerability for flight-critical interconnects. |
Research Approach
Multi-period observation of connector shipment volumes and new aircraft delivery rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with aerospace engineers, procurement managers at OEMs, and component suppliers. This was validated against secondary sources including FAA/EASA directives, ISO 9100 certification data, and company annual reports. Bottom-up and top-down triangulation ensured data integrity.
A segment-weighting approach synthesized demand across product type, technology, end-user, and installation segments throughout the forecast period. The quantitative modeling framework integrated historical growth patterns and projected market accelerators to derive compound annual growth rates. Key forecast inputs included aircraft production backlogs and drone market penetration rates. This approach provided a granular market outlook.
The model holds under conditions of stable geopolitical environments and consistent regulatory frameworks; deviation in global defense spending or new airworthiness standards would shift market trajectories. Forecasts reflect underlying assumptions regarding technological adoption and material availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aircraft Wires and Cables Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market