
 Space and Space Station Robotics Market | 2026-2036
Space and Space Station Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Space and Space Station Robotics Market Insights
Modular payload interfaces is hardening as the dominant configuration pattern, forcing buyers to evaluate compatibility across multiple mission architectures rather than selecting monolithic systems. MDA Space leverages its heritage in Canadarm-style manipulators to anchor long-term government contracts. Northrop Grumman Corporation competes through integrated servicing vehicles that extend satellite operational lifespans. Honeybee Robotics specializes in miniature drilling and sampling tools that occupy niche positions within planetary exploration portfolios.
Space and space station robotics encompasses electromechanical systems engineered for extraterrestrial manipulation, locomotion, and servicing under thermal extremes ranging from minus 150 to plus 120 degrees Celsius, with primary purposes spanning orbital assembly, satellite maintenance, and planetary surface operations. Manipulator arms command the largest installed base due to decades of ISS heritage and proven reliability in vacuum environments. Autonomous systems represent the fastest-expanding category as latency-tolerant architectures reduce dependency on ground-in-the-loop control. Payload handling functionality captures concentrated margin pools because precision berthing and transfer operations carry mission-critical failure costs.
FAA licensing requirements for commercial launch and reentry shape market access for robotics payloads destined for orbital deployment, while NASA's technical standards for crew-rating and fault tolerance set baseline engineering specifications that filter vendor eligibility. ESA's growing involvement in lunar gateway programs introduces parallel certification pathways that European and international suppliers must navigate. Stakeholders need to monitor how dual-use export control frameworks evolve as national security classifications increasingly overlap with commercial space robotics capabilities.
Market Dynamics
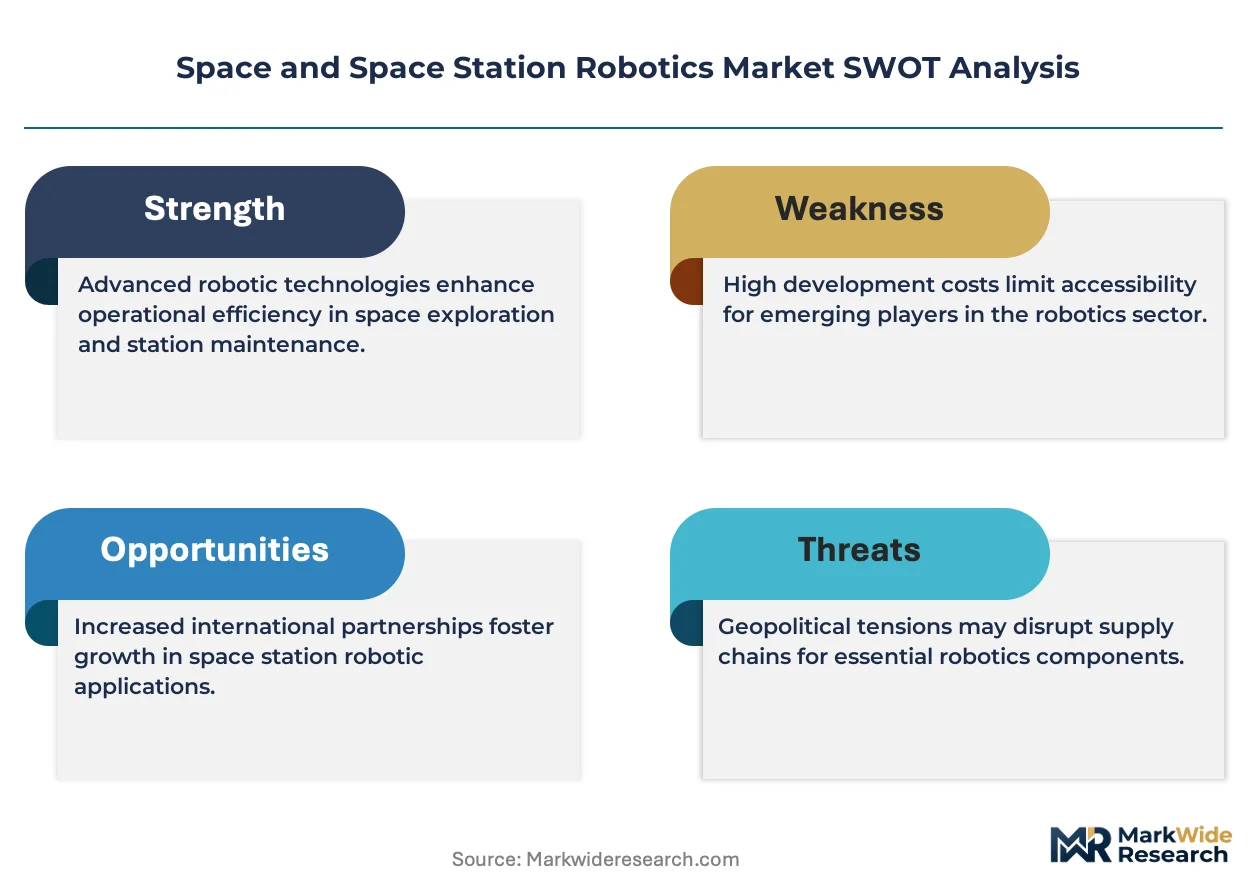
Autonomous control architectures are compressing ground-in-the-loop dependency, forcing hardware suppliers to embed edge-computing capabilities and fault-tolerant algorithms directly into manipulator systems. This shift is redistributing engineering investment from mechanical reliability toward software-defined redundancy, altering how contractors qualify for government programs.
Growth Catalysts
- Artemis procurement protocols:NASA's crew-rating standards for lunar gateway robotics are expanding the addressable contract base for fault-tolerant manipulator vendors.
- Satellite servicing commercialization:Private orbital refueling and repair missions are generating recurring demand for precision berthing systems and tool-change mechanisms.
- Modular payload interfaces:Standardized mechanical and electrical connection schemes are reducing mission-specific engineering, accelerating reflight rates for multi-purpose robotic platforms.
Market Restraints
- Radiation-hardened electronics supply:Foundry capacity for space-qualified semiconductors concentrates in a handful of defense-tier suppliers, creating single-source vulnerability for actuator controllers.
- Dual-use export controls:National security classifications for robotic manipulation precision are tightening technology transfer restrictions, fragmenting vendor access to international programs.
- Thermal cycling degradation:Materials science limitations in bearing lubricants and cable insulation impose hard operational limits on mission duration in high-thermal-variance orbits.
Strategic Opportunities
- Lunar surface operations:Permanently shadowed region resource extraction is opening demand for cryogenic-rated drilling and sample handling systems without terrestrial analogs.
- In-orbit manufacturing:Semiconductor and fiber-optic fabrication experiments aboard commercial stations are creating novel requirements for precision positioning in microgravity assembly.
- ESA gateway participation:European lunar program procurement is establishing parallel certification pathways that qualified non-US suppliers can leverage for Artemis-adjacent contracts.
Industry Challenges
- Ground-to-orbit latency tolerance:Autonomous decision architectures must achieve deterministic response times without human intervention, demanding specialized verification methodologies absent from terrestrial robotics.
- Cross-mission software reuse:Each target platform carries unique kinematic constraints and sensor suites, fragmenting development economies and extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space and Space Station Robotics Market |
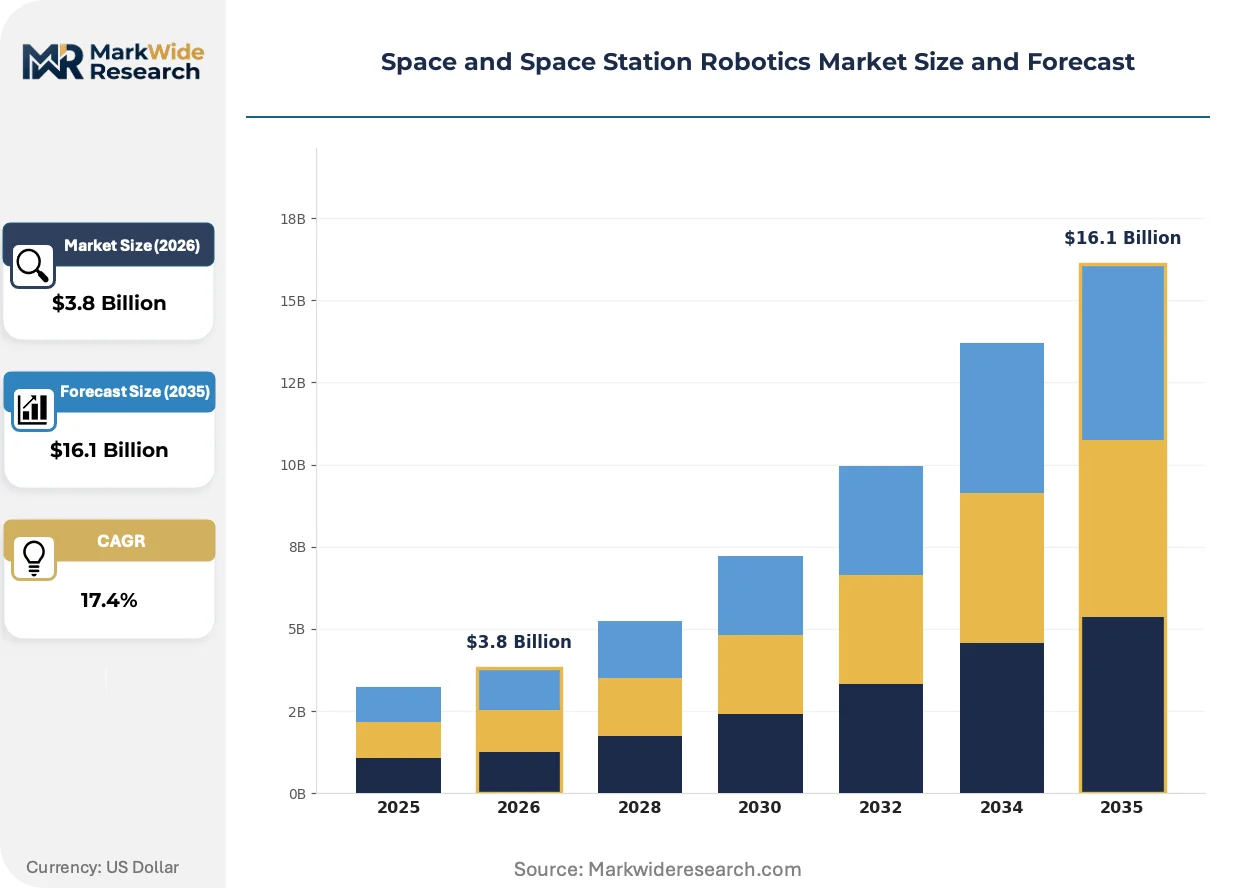
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Manipulator Arms, Rovers, Drones, Autonomous Systems Functionality: Maintenance, Exploration, Research, Payload Handling End User: Government Agencies, Private Companies, Research Institutions, Defense Contractors Operating Environment: Low Gravity, Microgravity, Vacuum, Atmosphere |
| Companies Covered | MDA Space, Astrobotic Technology, Motiv Space Systems, Northrop Grumman Corporation, Maxar Technologies, Astroscale Holdings, Honeybee Robotics, Redwire Corporation, Oceaneering International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space and Space Station Robotics Market Trends and Innovations
Software-defined robotics is displacing fixed-function hardware architectures across orbital and planetary platforms. Control systems now reconfigure through firmware updates rather than mechanical redesign, compressing mission adaptation cycles and altering supplier value capture toward recurring software revenue models.
Edge intelligence integration is unifying perception, planning, and execution within single embedded compute nodes. Satellite servicing operators are deploying these architectures for debris capture and client spacecraft docking without ground-segment intervention. This unifying trend is collapsing the traditional separation between manipulator hardware vendors and autonomy software providers, forcing partnership structures or internal capability acquisition.
FAA commercial launch licensing is tightening payload qualification documentation for robotics destined to the ISS and commercial stations. The regulator now requires detailed fault-tree analysis for autonomous systems operating in crewed proximity. Small satellite deployer segments are absorbing compliance costs through dedicated regulatory affairs functions, while established station contractors leverage existing NASA technical standards relationships to accelerate approval timelines.
Fixed-price mission contracting is displacing cost-plus engineering development for routine orbital servicing. Defense and commercial satellite operators are transferring performance risk to robotics vendors, who must price thermal vacuum testing and on-orbit demonstration into initial proposals. This pattern concentrates most visibly in United States federal procurement, where NASA's Commercial LEO Destinations program is modeling the shift for international partner agencies.
Space and Space Station Robotics Market Segmentation
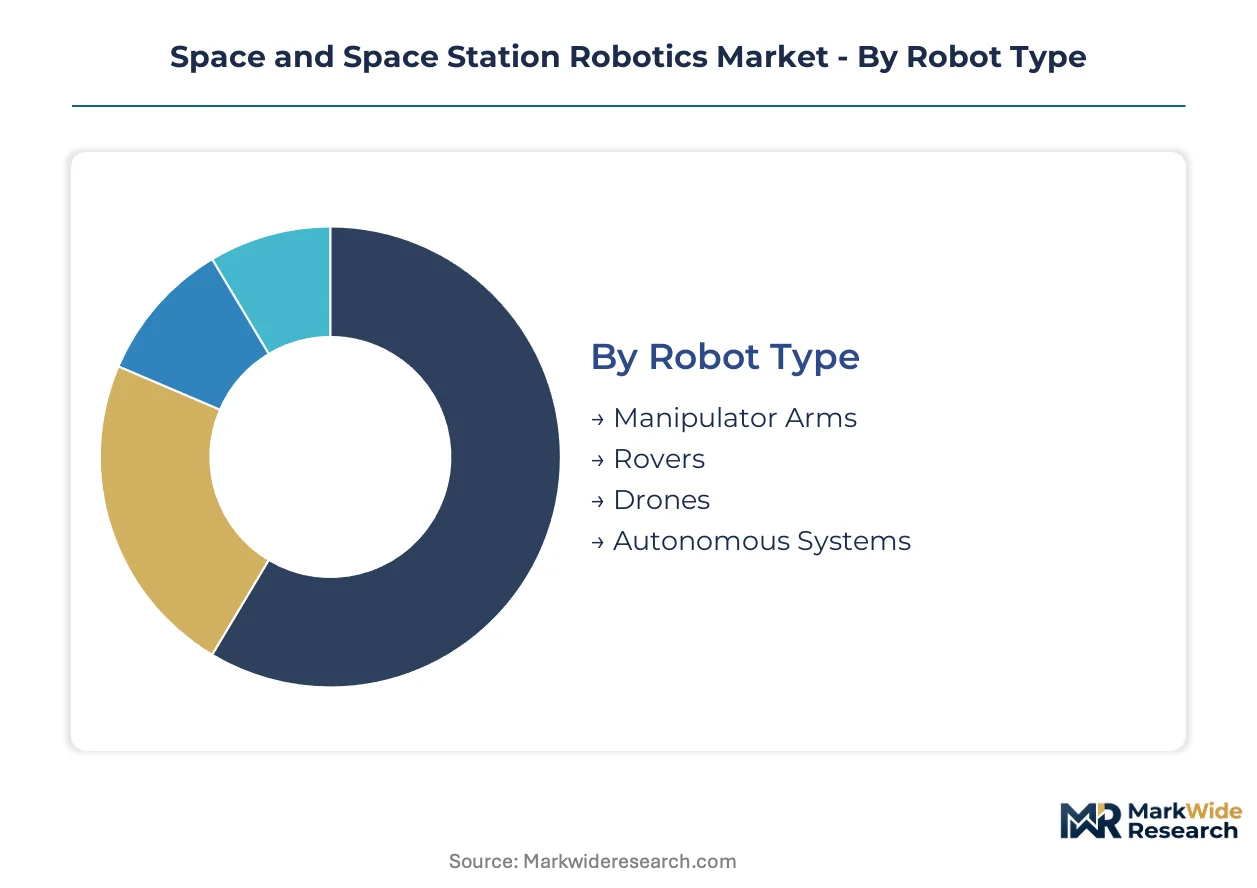
Segmentation in space robotics reveals how engineering requirements fragment across mission profiles. Thermal tolerance, latency constraints, and payload precision demands create distinct procurement categories that vendors must address separately.
Robot Type:
Volume concentrates in heritage-proven architectures, while premium capture shifts toward autonomous platforms eliminating ground-control dependency.
- Manipulator Arms:Electromechanical articulators with multi-degree-of-freedom joints engineered for precision berthing and orbital assembly. NASA ISS contracts and Artemis gateway procurement in the United States anchor demand, though thermal cycling limits in high-variance orbits constrain mission duration extension.
- Autonomous Systems:Edge-computing platforms executing closed-loop control without terrestrial intervention. Satellite servicing operators in the United States are deploying these for debris capture and client docking, compressing response times that ground-in-the-loop architectures cannot match.
- Rovers:Wheeled locomotion platforms for planetary surface traverses and sample collection.
- Drones:Aerial mobility systems for atmospheric exploration and reconnaissance.
Today's leader: Manipulator Arms. Tomorrow's challenger: Autonomous Systems.
Functionality:
Application maturity separates routine orbital servicing from frontier operations lacking terrestrial analogs.
- Payload Handling:Precision berthing, transfer, and stowage operations with mission-critical failure costs. Commercial space stations in the United States are standardizing modular interfaces, accelerating reflight rates for multi-purpose platforms.
- Maintenance:Satellite refueling, component replacement, and repair missions extending operational lifespans. Northrop Grumman's integrated servicing vehicles demonstrate recurring revenue potential in geostationary orbit.
- Exploration:Surface traverse and subsurface access for planetary science objectives.
- Research:On-orbit experimentation support and laboratory automation.
Payload Handling commands current margins. Exploration holds steepest expansion trajectory as lunar surface operations mature.
End User:
Procurement authority splits between federal milestone-based contracting and commercial fixed-price risk transfer.
- Government Agencies:NASA Artemis crew-rating standards and ESA lunar gateway programs establishing qualification baselines. Fault-tolerance requirements filter vendor eligibility through multi-year demonstration timelines.
- Private Companies:Satellite operators and commercial station developers absorbing performance risk through fixed-price robotics procurement. FAA licensing requirements for autonomous crew-proximity operations tighten documentation burdens.
- Defense Contractors:National security classifications restricting technology transfer through dual-use export controls.
- Research Institutions:University and laboratory-led technology demonstration missions.
Government Agencies set technical standards. Private Companies are gaining share fastest as orbital servicing commercializes.
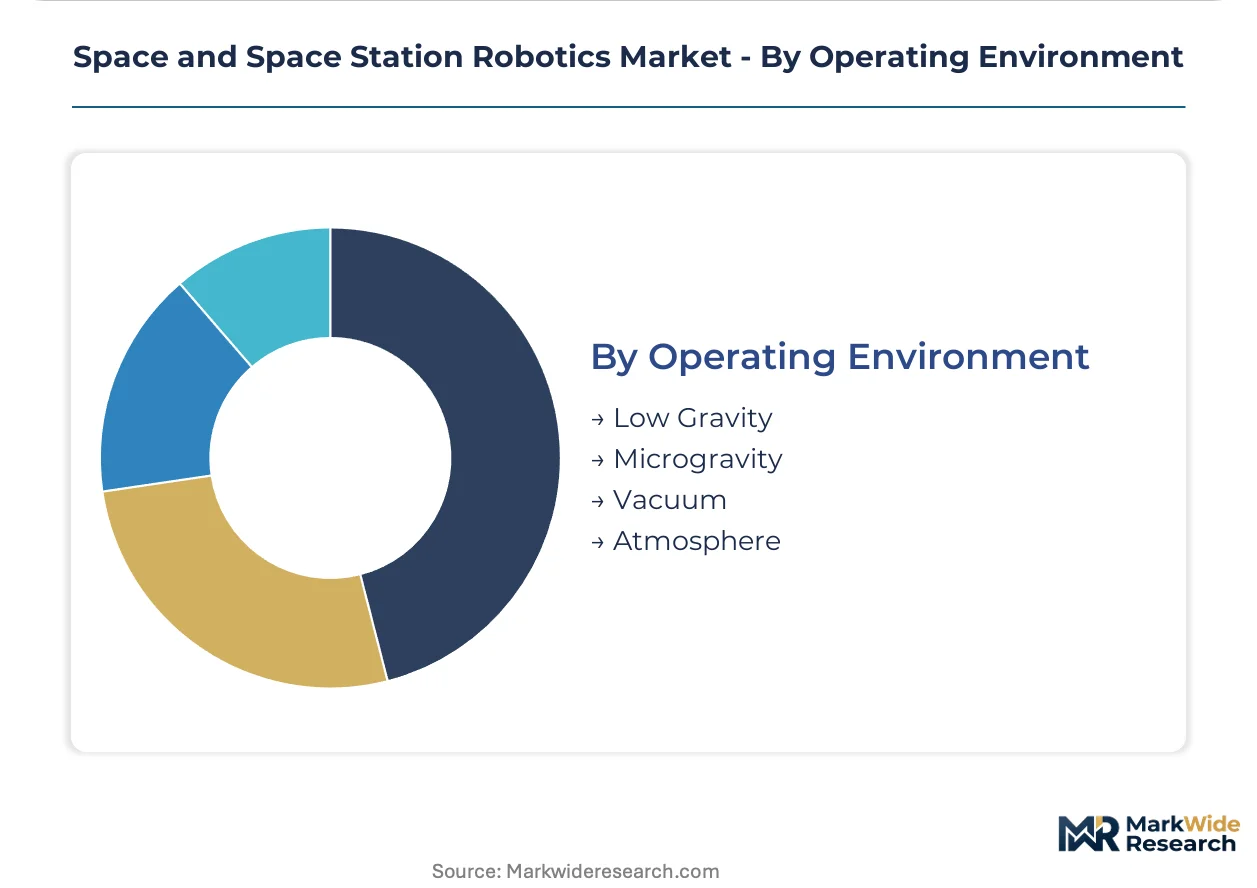
Operating Environment:
Environmental severity dictates materials science investment and thermal management architecture.
- Vacuum:Absence of convective heat transfer requiring radiative thermal control and specialized lubrication. ISS heritage validates bearing and cable insulation performance across decades of exposure.
- Microgravity:Near-zero gravitational acceleration demanding reaction-force management and momentum control. In-orbit manufacturing experiments aboard commercial stations create novel precision positioning requirements.
- Low Gravity:Reduced but non-zero gravitational fields on planetary surfaces.
- Atmosphere:Aerodynamic drag and pressure environments for aerial platforms.
Vacuum dominates installed base. Microgravity applications are expanding most quickly as commercial station construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital robotics heritage traces to Canadian contributions on early space shuttle missions and subsequent International Space Station assembly, establishing North American technical leadership that persists through Artemis-era procurement.
United States
NASA's Commercial LEO Destinations program and Artemis gateway robotics contracts anchor federal demand for fault-tolerant manipulators. FAA commercial launch licensing tightens payload qualification documentation for autonomous crew-proximity operations. Houston and the broader Texas Gulf Coast cluster host mission control infrastructure and contractor engineering centers supporting orbital servicing development.
Canada
Canadarm heritage sustains government commitment to space robotics through MDA Space's long-term contracts for next-generation manipulator systems. The Canadian Space Agency coordinates with NASA on lunar gateway contribution agreements. Greater Toronto and Brampton industrial corridors concentrate precision manufacturing capabilities for space-qualified electromechanical systems.
Japan
JAXA's ISS participation and HTV cargo vehicle experience inform domestic demand for orbital berthing and transfer mechanisms. METI technology development programs support autonomous systems for debris removal and satellite servicing. Tsukuba Science City and Nagoya industrial zones host robotics research institutes and precision component suppliers.
Germany
ESA lunar gateway procurement opens parallel certification pathways for European robotics vendors seeking Artemis-adjacent contracts. The national space agency DLR validates autonomous manipulation algorithms through orbital demonstration missions. Munich and Bremen aerospace clusters concentrate system integrators and subsystem suppliers for planetary exploration platforms.
United Kingdom
UK Space Agency funding for in-orbit servicing and manufacturing experiments generates demand for precision positioning systems. Regulatory alignment with ESA technical standards facilitates vendor access to continental procurement programs. Harwell Space Cluster in Oxfordshire anchors satellite servicing startup formation and robotics testing infrastructure.
Space and Space Station Robotics Market Competitive Landscape
The competitive structure tilts toward heritage-anchored system integrators with multi-decade government relationships. Prime contractors with ISS flight-proven platforms command qualification advantages that filter vendor eligibility for crew-rated missions. Two archetypes dominate: established defense-aerospace conglomerates with integrated servicing vehicle portfolios, and specialized robotics houses with niche manipulation or sampling tool expertise. Consolidation pressure operates through strategic technology licensing partnerships rather than large-scale acquisition activity, as fault-tolerance IP and flight heritage resist rapid transfer.
Among heritage-anchored Canadian operators, MDA Space exemplifies the long-term government contract archetype built on Canadarm lineage. Northrop Grumman Corporation represents the integrated servicing vehicle tier extending satellite operational lifespans through orbital refueling and repair missions. Honeybee Robotics occupies the specialized tool developer position within planetary exploration portfolios, anchoring miniature drilling and sampling system supply chains.
| Leading Market Players |
|---|
| MDA Space |
| Astrobotic Technology |
| Motiv Space Systems |
| Northrop Grumman Corporation |
| Maxar Technologies |
| Astroscale Holdings |
| Honeybee Robotics |
| Redwire Corporation |
| Oceaneering International |
| Others |
Pricing and Supply Chain Analysis
NASA's crew-rating standards for Artemis gateway robotics are compressing supplier qualification timelines and forcing foundry investments in radiation-hardened electronics, which concentrates pricing power among defense-tier semiconductor vendors with certified wafer capacity.
Pricing Analysis
Fixed-price mission contracting for routine orbital servicing transfers performance risk to vendors who must embed thermal vacuum testing and on-orbit demonstration costs into initial proposals. Price differentiation rests on flight heritage certification and fault-tolerance validation rather than hardware specifications alone. Margins are tightening in satellite servicing segments as commercial operators consolidate procurement volumes and demand recurring software update revenue models. Government agencies show lowest price sensitivity due to crew-safety mandates, while commercial station developers absorb cost compression through modular payload interface standardization.
Supply Chain Analysis
Specialized aerospace engineering talent concentrates in the Houston-Texas Gulf Coast cluster, Greater Toronto-Brampton corridors, and Munich-Bremen aerospace zones, creating recruitment bottlenecks for precision electromechanical manufacturing. Critical inputs draw from radiation-hardened semiconductor foundries in the United States, space-qualified bearing suppliers in Germany, and thermal control material specialists in Japan. Single-source vulnerability in actuator controller chipsets exposes vendors to foundry allocation disruptions. Distribution runs through prime contractor integration chains where ISS heritage validates subsystem eligibility for crew-rated missions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening across procurement protocols as autonomous crew-proximity operations demand deterministic fault-response architectures without terrestrial intervention.
For Market Incumbents: Lock in long-term supply agreements for radiation-hardened electronics before foundry capacity constraints intensify. Deepen backward integration into thermal management subsystem production to capture margin pools currently leaking to specialized material suppliers. Defend against software-defined robotics entrants by accelerating firmware update revenue models and embedding edge-computing capabilities directly into manipulator platforms. For New Entrants and Emerging Players: Enter via ESA lunar gateway procurement pathways that establish parallel certification credentials for Artemis-adjacent contracts. Target permanently shadowed region resource extraction tooling where cryogenic-rated drilling systems lack established supply chains. Pursue university-led technology demonstration missions as qualification accelerators before scaling to commercial station robotics. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized autonomy software houses possessing deterministic verification methodologies absent from terrestrial robotics. Long-term viability favors vendors with dual-use export control clearances and NASA technical standards relationships extending across the projection horizon. Watch for FAA commercial launch licensing rulings on autonomous crew-proximity operations as inflection indicators for market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Flight Heritage Acquisition | ISS-proven subsystem validation accelerates NASA crew-rating qualification timelines for Artemis contracts. |
| Edge Computing Integration | Embedded autonomy architectures reduce ground-in-the-loop dependency for satellite servicing operators. |
| Modular Interface Standardization | Mechanical and electrical connection schemes accelerate reflight rates for multi-purpose robotic platforms. |
| Radiation-Hardened Electronics Sourcing | Defense-tier foundry relationships secure actuator controller supply against single-source vulnerability. |
| ESA Gateway Certification Pathway | European lunar program credentials unlock Artemis-adjacent procurement for non-US robotics vendors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotics program managers at NASA and ESA, procurement leads at commercial station developers, thermal systems engineers at prime contractors, and regulatory affairs specialists at FAA-licensed launch operators with secondary validation against NASA technical standards documentation, ESA lunar gateway procurement notices, FAA commercial space licensing records, and ISS operational experience databases. Bottom-up segment sizing and top-down market reconciliation anchored value estimates.
Historical reference periods spanning ISS assembly through Artemis program initiation anchored the projection horizon across robot type, functionality, end user, and operating environment dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating satellite servicing commercialization rates, autonomous system deployment timelines, and modular payload interface adoption curves. Forecast inputs included federal space budget appropriation patterns and commercial launch manifest densities.
Inputs from government procurement databases and commercial operator technical specifications were available through the study window; gaps in proprietary fault-tolerance algorithm performance data introduce uncertainty bands around autonomous system penetration assumptions. Forecasts reflect documented assumptions about Artemis timeline adherence and radiation-hardened foundry capacity expansion. Material deviation in FAA crew-proximity licensing rulings or dual-use export control classification shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Tethered Manned Submersible Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Dismounted Soldier Systems Market