
 Europe Aerostat Systems Market | 2026-2036
Europe Aerostat Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerostat Systems Market Intelligence
The capability gap between helium envelope manufacturers and systems integrators is reorganizing competitive tiers across the European aerostat landscape. HEMERIA leverages its French defense heritage to sustain long-duration naval surveillance contracts. A-NSE anchors the southern European market with specialized tethered platforms for Mediterranean maritime patrol. ILC Dover LP competes through advanced laminate envelope technology that extends operational altitude ranges.
Aerostat systems are lighter-than-air platforms restrained by ground tethers, typically employing helium-filled envelopes constructed from laminated polyester or vectran fabrics with operational altitudes spanning 300 to 4,500 meters for persistent surveillance and communications relay. The military end user segment dominates procurement volumes, though environmental monitoring applications within research institutions represent the fastest-expanding demand pool as climate sensing requirements intensify. Sensor platforms lead product type margins due to integrated payload complexity, while static aerostats occupy the volume base through standardized border security deployments.
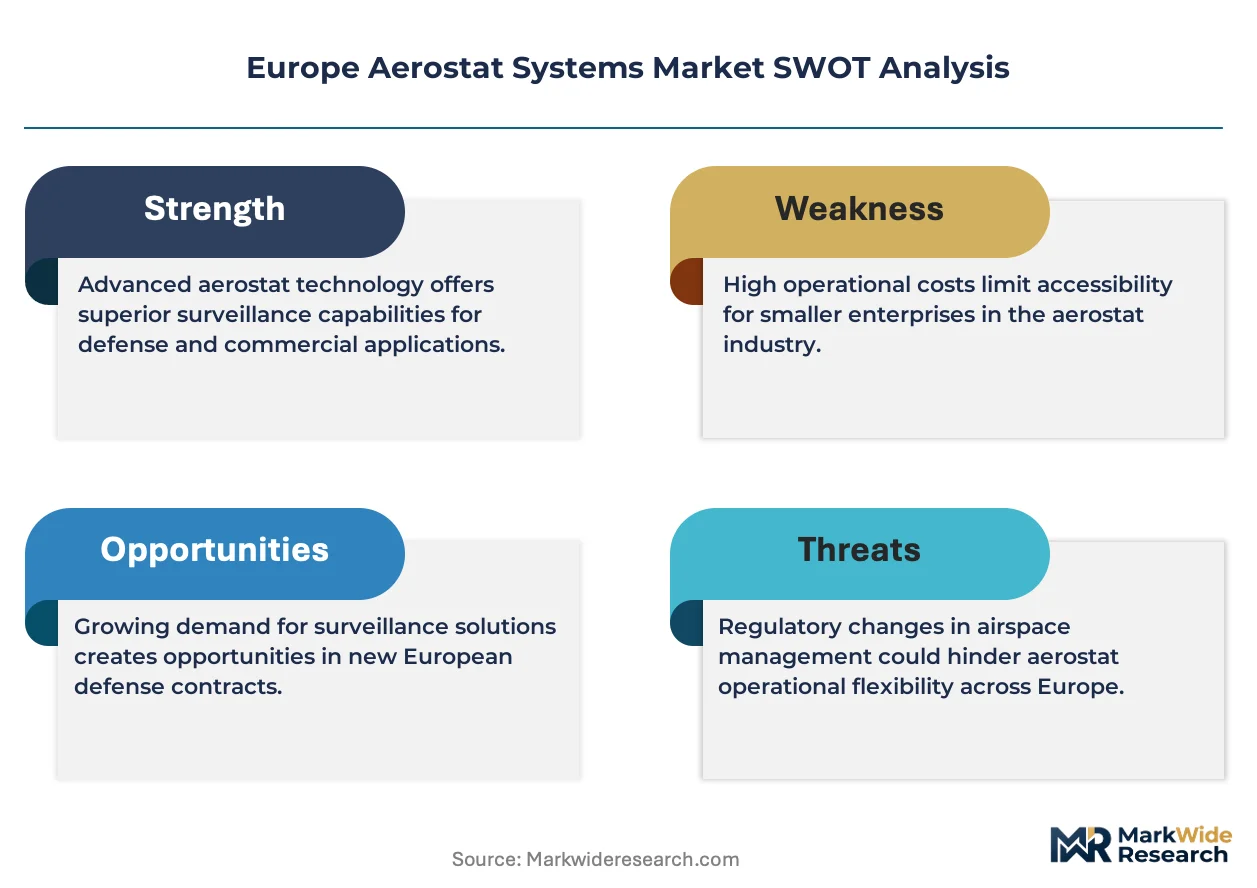
EU Green Deal emission benchmarks and CE marking requirements under the ECHA framework are reshaping procurement specifications toward lower-carbon operational profiles. The F-Gas Regulation governs helium recovery systems, directly influencing envelope design standards and lifecycle compliance costs. Stakeholders must monitor evolving MDR-aligned safety certifications for civilian urban deployments as regulatory scope broadens beyond traditional military applications.
Market Dynamics
The EU Green Deal's emission benchmarks are redirecting defense procurement budgets from manned patrol aircraft toward tethered aerostat platforms, compressing operational carbon footprints while extending persistent aerial coverage across Mediterranean and Baltic corridors.
Growth Catalysts
- Border surveillance mandates:France and Germany are expanding aerostat procurement for persistent aerial monitoring of migration corridors, with agencies prioritizing tethered platforms over rotary-wing alternatives for cost-efficiency.
- Helium recovery compliance:The F-Gas Regulation is driving envelope redesign toward closed-loop gas management systems, creating upgrade cycles across installed bases.
- Maritime patrol expansion:Mediterranean coastal agencies are deploying sensor-equipped aerostats for migration monitoring, generating concentrated demand in Italy, Spain, and Greece.
Market Restraints
- Helium supply concentration:European helium refining capacity remains concentrated in Poland and Algeria, exposing procurement to geopolitical supply disruptions and price volatility.
- Weather operational limits:Wind shear thresholds above 25 knots ground aerostat fleets across North Sea deployments, creating coverage gaps during winter storm seasons.
- Airspace integration friction:CE marking under the ECHA framework and national aviation authority coordination create multi-month deployment timelines for cross-border operations.
Strategic Opportunities
- Environmental monitoring pivot:Research institutions across Scandinavia are expanding climate sensing aerostat contracts, representing an underpenetrated civilian application vertical.
- Urban air mobility corridors:The EU AI Act's framework for autonomous systems is opening certification pathways for tethered communications relay in smart city deployments.
- Sensor payload convergence:Synthetic aperture radar integration with electro-optical systems is creating premium platform tiers for naval surveillance contracts.
Industry Challenges
- Composite fabrication skills gap:Laminated vectran envelope manufacturing requires specialized technician training that outpaces vocational program output in France and Germany.
- MDR certification timelines:Medical device regulation alignment for civilian emergency response aerostats extends approval cycles by 8-14 months.
- Legacy communications integration:NATO-standard datalink compatibility demands expensive retrofitting for national variants deployed in joint operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerostat Systems Market |
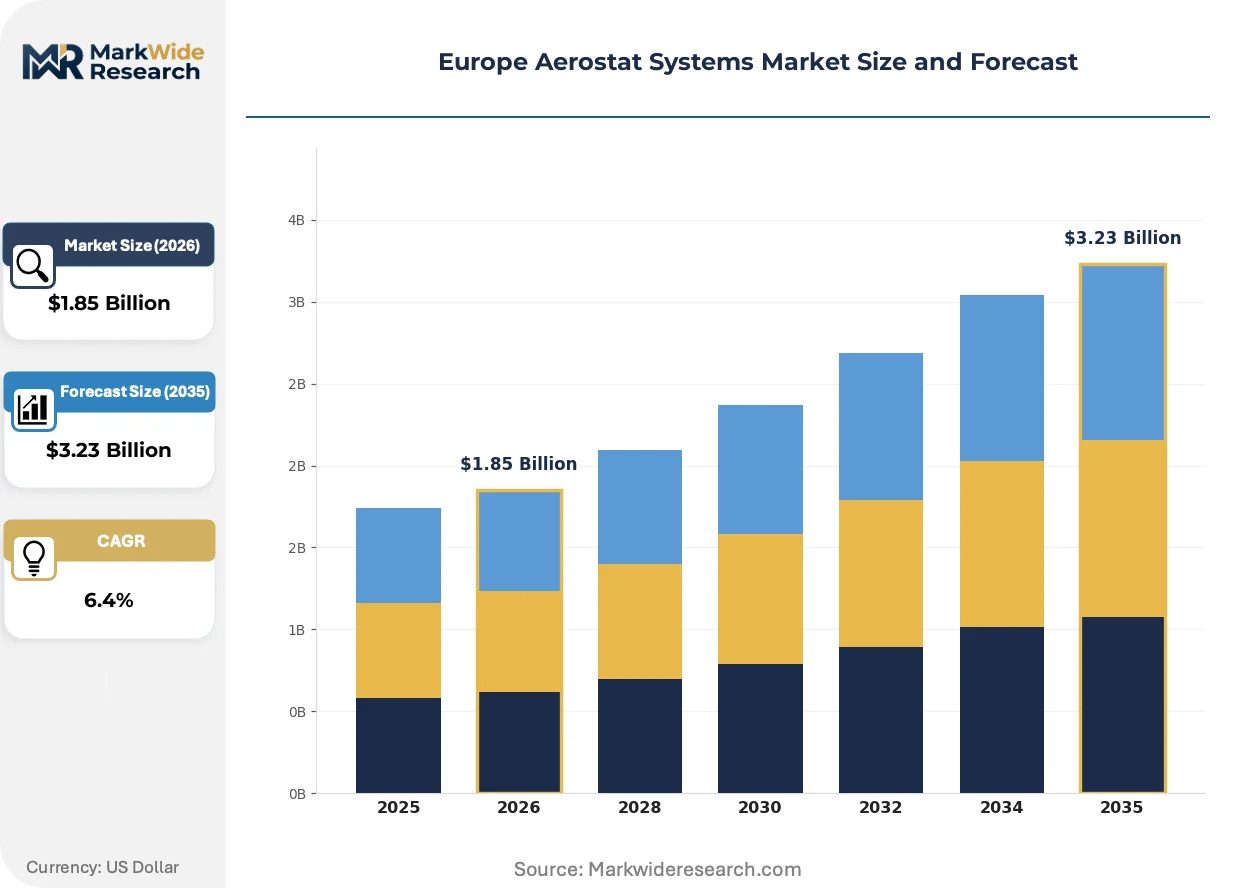
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Aerostats, Tethered Blimps, Unmanned Aerostats, Sensor Platforms Application: Surveillance, Communications, Environmental Monitoring, Disaster Management End User: Military, Government, Commercial, Research Institutions Deployment: Onshore, Offshore, Urban Areas, Remote Locations |
| Companies Covered | ILC Dover LP, A-NSE, CNIM, Aeronord Sas, HEMERIA, TCOM, L.P., Altaeros, ALLSOPP HELIKITES LTD., Raven Industries, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerostat Systems Market Strategic Shifts & Innovations
Envelope material science and autonomous tether management are compressing operational cost structures while expanding altitude ceilings, reshaping competitive differentiation across European defense procurement.
Laminated vectran-polyester hybrid envelopes are fragmenting traditional polyester-only supply chains. Naval surveillance programs in France and Italy are adopting these composites for extended altitude ranges above 3,500 meters. The technology is fragmenting procurement specifications, with premium tenders now mandating vectran content thresholds that exclude legacy suppliers.
The F-Gas Regulation's phasedown schedules are forcing helium recovery system retrofits across operational fleets. Manufacturers must integrate closed-loop purification to maintain compliance, raising platform unit costs by 12-18 percent. Mediterranean maritime patrol contracts are absorbing these premiums fastest, with Italian and Spanish agencies specifying recovery-equipped platforms in new tenders.
Service contracts are unbundling from hardware sales as procurement offices seek operational expenditure flexibility. French defense procurement is leading this shift, with DGA contracts now separating platform purchase from 10-year maintenance and payload upgrade schedules. The model is compressing initial capital outlays while extending vendor revenue visibility across program lifecycles.
Europe Aerostat Systems Market Segmentation
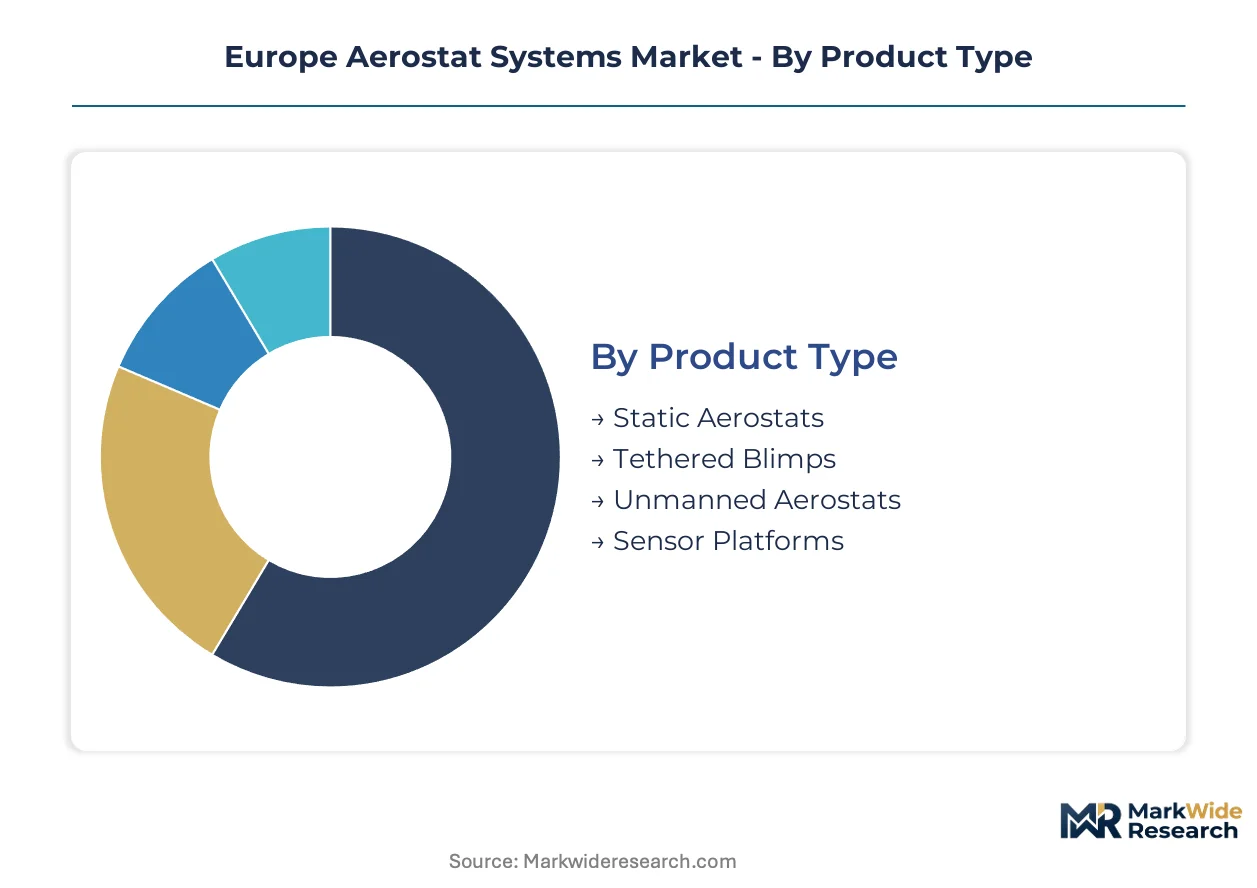
Product architecture and application specificity determine margin capture across European aerostat procurement. Segmentation reveals where laminated envelope technology commands premium positioning versus standardized static deployments.
Product Type:
Margin pools concentrate in integrated sensor platforms where payload complexity elevates pricing power beyond raw envelope fabrication.
- Static Aerostats:Standardized helium-filled envelopes with fixed mooring systems dominate volume procurement for border security installations. French and German agencies deploy these across Mediterranean and Baltic corridors for persistent migration monitoring, prioritizing cost efficiency over altitude flexibility.
- Sensor Platforms:Integrated electro-optical and radar payload architectures command premium tiers through synthetic aperture radar convergence. Naval surveillance contracts in Italy and France specify these composite systems for extended maritime patrol above 3,500 meters.
- Tethered Blimps:Maneuverable envelope designs with dynamic lift modulation serve communications relay missions.
- Unmanned Aerostats:Autonomous tether management systems reduce ground crew requirements for remote deployments.
The dominant share belongs to Static Aerostats, while Sensor Platforms is closing the gap fastest.
Application:
Deployment purpose shapes procurement specifications from military datalink compatibility to civilian CE marking requirements.
- Surveillance:Persistent aerial monitoring configurations integrate electro-optical and infrared sensors for border and maritime patrol. Mediterranean coastal agencies in Spain, Italy, and Greece drive concentrated demand for tethered surveillance aerostats as migration corridor coverage expands.
- Environmental Monitoring:Climate sensing payloads with atmospheric sampling instruments are expanding most quickly across Scandinavian research institutions. The EU Green Deal's emission benchmarking redirects funding toward lower-carbon aerial data collection platforms.
- Communications:Relay platforms extend network coverage in remote or contested electromagnetic environments.
- Disaster Management:Rapid-deployment aerostats restore connectivity and situational awareness following infrastructure disruption.
Surveillance retains the largest deployment base, though Environmental Monitoring shows the steepest expansion trajectory.
End User:
Procurement authority determines compliance burden from NATO datalink standards to MDR-aligned civilian certifications.
- Military:Defense procurement offices specify NATO-standard interoperability and encrypted datalink architectures. French DGA contracts separate platform acquisition from decade-long maintenance schedules, compressing capital outlays while extending vendor revenue visibility.
- Research Institutions:Climate science funding across Norway, Sweden, and Finland is accelerating civilian aerostat adoption for atmospheric research. CE marking under ECHA frameworks and national aviation coordination create multi-month deployment timelines.
- Government:Border agencies and maritime authorities procure standardized surveillance configurations.
- Commercial:Private sector adoption concentrates in telecommunications infrastructure and precision agriculture sensing.
Military procurement maintains volume leadership, while Research Institutions are gaining share fastest.
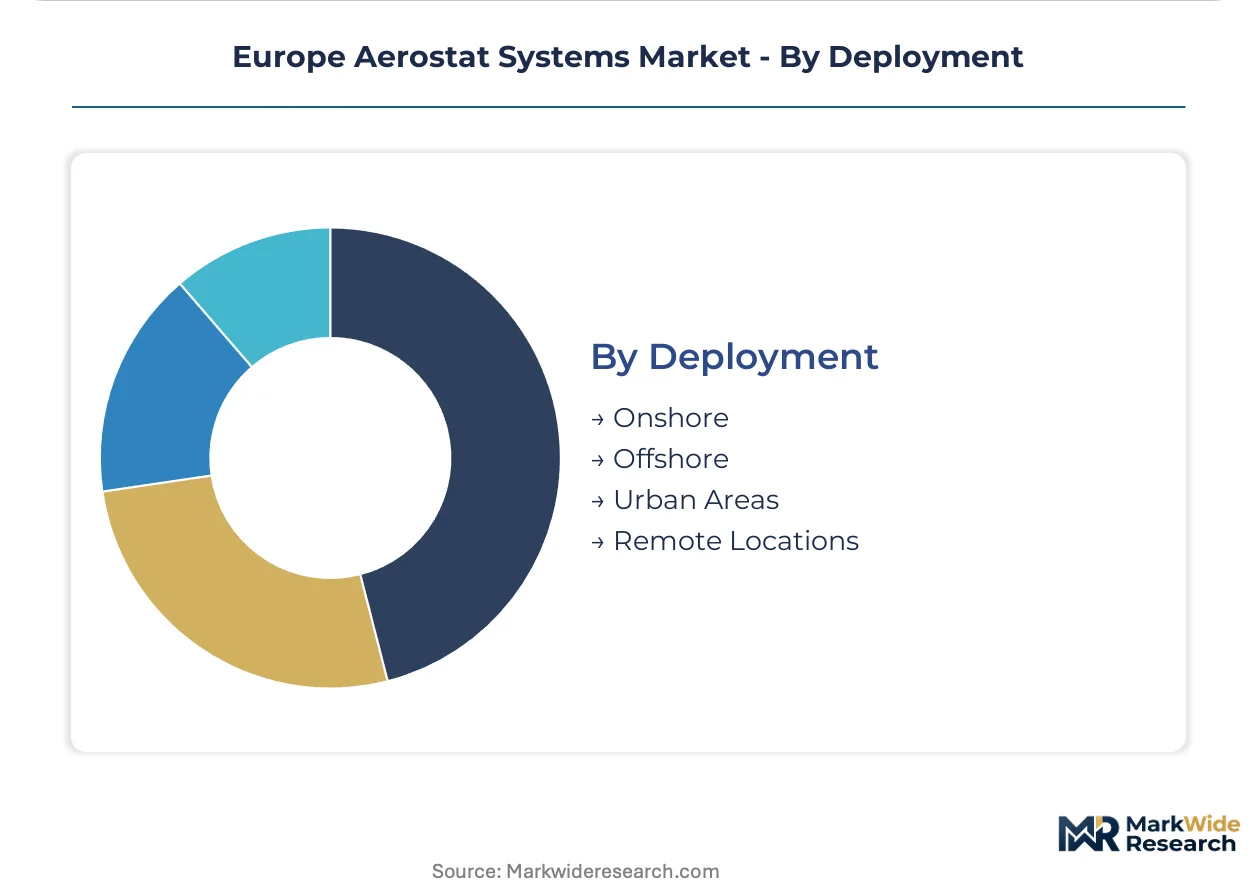
Deployment:
Operating environment dictates envelope material specifications and tether engineering requirements.
- Onshore:Fixed mooring installations at established border stations and military facilities constitute the operational base. Wind shear thresholds above 25 knots ground fleets across North Sea deployments during winter storm seasons.
- Offshore:Naval surveillance platforms require corrosion-resistant laminates and dynamic positioning compensation for maritime patrol. Italian and Spanish maritime agencies specify helium recovery-equipped systems to satisfy F-Gas Regulation compliance.
- Urban Areas:Low-altitude deployments face airspace integration friction with civil aviation authorities.
- Remote Locations:Self-contained mooring and power systems enable operations beyond grid infrastructure.
Onshore deployment holds the established position, while Offshore is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in French and Italian naval surveillance contracts while German border agencies extract cost efficiencies through standardized static aerostat procurement. Mediterranean maritime migration pressures sustain premium platform demand across southern Europe. Baltic corridor nations absorb volume-tier pricing for persistent aerial monitoring.
France
Direction Générale de l'Armement contracts separate platform acquisition from decade-long maintenance schedules, compressing capital outlays while extending vendor revenue visibility. The EU Green Deal redirects defense procurement from manned patrol aircraft toward tethered aerostat platforms. Toulouse and Marseille anchor naval surveillance program delivery for Mediterranean maritime patrol.
Germany
Federal Police and customs agencies expand aerostat procurement for persistent Baltic border monitoring, prioritizing cost efficiency over altitude flexibility. CE marking under ECHA frameworks creates multi-month deployment timelines for cross-border operations. Bavaria hosts the primary integration cluster for NATO-standard datalink compatibility requirements.
Italy
Maritime agencies specify helium recovery-equipped platforms to satisfy F-Gas Regulation compliance for Mediterranean migration corridor coverage. The F-Gas Regulation's phasedown schedules force envelope redesign toward closed-loop gas management systems. Rome and Naples concentrate naval surveillance contract awards for extended maritime patrol above 3,500 meters.
Spain
Coastal authorities deploy sensor-equipped aerostats for maritime migration monitoring, generating concentrated demand in the Mediterranean corridor. National aviation authority coordination with CE marking requirements extends deployment timelines. Barcelona and Valencia anchor the southern European market for specialized tethered platforms.
United Kingdom
Research institutions across Scotland and northern England expand climate sensing aerostat contracts for atmospheric research applications. MDR-aligned safety certifications for civilian urban deployments extend approval cycles. The Cambridge-Oxford corridor concentrates environmental monitoring technology development for Scandinavian export markets.
Europe Aerostat Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European aerostat landscape. Premium platform tiers concentrate among French defense heritage specialists and laminate envelope technology providers, while standardized static deployments favor scale-driven fabricators with streamlined supply chains. Two strategic archetypes dominate: integrated systems specialists with naval surveillance legacies, and component-focused envelope manufacturers with advanced material science capabilities. Competitive moves center on service contract unbundling from hardware sales and helium recovery system retrofits for F-Gas Regulation compliance.
Within the integrated systems tier, HEMERIA and A-NSE occupy positions shaped by geographic defense procurement concentration. HEMERIA exemplifies the French defense heritage archetype sustaining long-duration naval surveillance contracts through DGA-aligned procurement structures. A-NSE anchors the southern European market position for Mediterranean maritime patrol specialization. ILC Dover LP represents the advanced laminate envelope technology archetype competing through extended operational altitude range capabilities. These three players illustrate how capability differentiation across envelope fabrication, systems integration, and geographic procurement alignment fragments competitive positioning.
| Leading Market Players |
|---|
| ILC Dover LP |
| A-NSE |
| CNIM |
| Aeronord Sas |
| HEMERIA |
| TCOM, L.P. |
| Altaeros |
| ALLSOPP HELIKITES LTD. |
| Raven Industries, Inc. |
| Others |
Cost & Logistics Intelligence
Envelope fabrication scale economies in Poland and Algeria concentrate helium refining capacity, compressing procurement leverage for downstream systems integrators while elevating cost floors for laminate-dependent naval surveillance contracts.
Pricing Analysis
Configured-to-order sensor platforms command 40-60 percent premiums over standardized static aerostat configurations. Three-tier pricing structure across premium, standard, and economy levels separates vectran-composite naval systems from polyester-only border installations from basic helium-filled mooring balloons. Cost compression in static deployments is intensifying because German and Baltic agencies prioritize volume procurement over altitude performance. Government border agencies exhibit highest price sensitivity, while French DGA naval programs absorb premiums for synthetic aperture radar integration.
Supply Chain Analysis
Helium feedstock concentration in Poland and Algeria exposes European envelope manufacturers to geopolitical transit disruptions and Algerian export quota volatility. Laminated vectran-polyester composite fabrication draws from Japanese vectran fiber suppliers, German laminate bonding equipment, and French mooring system engineering. Single-source vulnerability in vectran yarn production creates bottleneck risk for altitude-extended naval platforms. Distribution runs through defense procurement offices with decade-long maintenance unbundling, compressing initial capital outlays while extending vendor revenue visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized laminate bonding technician training programs in France and Germany lag fleet expansion timelines, creating a persistent capability gap that constrains envelope production scaling and elevates labor cost structures for premium platform tiers.
For Market Incumbents: Consolidate laminate envelope manufacturing capabilities through captive vectran-polymer bonding facilities to offset technician scarcity and secure altitude-extended naval contract access. Prioritize F-Gas Regulation compliance retrofit services for installed Mediterranean fleets to capture maintenance unbundling revenue streams. For New Entrants and Emerging Players: Anchor in Scandinavian environmental monitoring applications where CE marking requirements and climate research funding create lower competitive density than saturated defense procurement channels. Target Norwegian and Swedish atmospheric research institutions with rapid-deployment aerostat configurations bypassing NATO datalink complexity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors envelope material science specialists with vectran-laminate IP over systems integrators facing margin compression from service contract unbundling. Long-term viability hinges on helium recovery system integration capabilities as F-Gas Regulation phasedown schedules tighten. Monitor Italian and Spanish maritime agency tender specifications for vectran content thresholds as inflection indicators for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery System Integration | F-Gas Regulation compliance secures Mediterranean maritime patrol contract eligibility for Italian and Spanish agencies. |
| Laminate Envelope Capacity Expansion | Vectran-polyester hybrid fabrication captures altitude-extended naval surveillance premiums above 3,500 meters. |
| Service Contract Unbundling | Separating platform sales from decade-long maintenance compresses DGA capital outlays while extending vendor revenue visibility. |
| Environmental Monitoring Pivot | Scandinavian climate research funding redirects procurement toward lower-carbon atmospheric sensing platforms. |
| Synthetic Aperture Radar Convergence | Integrated electro-optical and radar payloads command premium positioning in French and Italian naval programs. |
Research Approach
Initial hypotheses were tested against primary input from DGA procurement officers, maritime agency technical directors, envelope manufacturing engineers, and climate research facility managers and refined through secondary validation against ECHA regulatory filings, EU Green Deal implementation documents, F-Gas Regulation compliance databases, and NATO standardization agreements. Bottom-up segment sizing triangulated with top-down defense budget allocation analysis across the analysis window.
Variance decomposition across product type, application purpose, end-user procurement authority, and deployment environment shaped the analytical framework. CAGRs were derived from segment-level demand buildups incorporating Mediterranean migration corridor expansion rates, Baltic border surveillance procurement schedules, and Scandinavian climate research funding trajectories. Helium supply concentration risk and laminate technician training pipeline constraints informed scenario-weighted projections.
Decision-makers should treat outputs as directional under sustained EU Green Deal emission benchmark enforcement and stable Algerian helium export flows; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation phasedown schedules and vectran fiber supply availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Tethered Drone System Market