
 Explosive Ordnance Disposal (EOD) Robot Market | 2026-2036
Explosive Ordnance Disposal (EOD) Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Explosive Ordnance Disposal (EOD) Robot Market Insights
Specialized robotics engineering talent is rotating toward defense contractors as commercial autonomous vehicle hiring cools. L3Harris Technologies leverages its communications heritage to dominate integrated command-and-control payloads for EOD platforms. QinetiQ sustains British military relationships through long-running support contracts for tracked robot fleets. Northrop Grumman Corporation anchors its position via unmanned systems expertise spanning airborne and ground robotics divisions.
Explosive Ordnance Disposal robots are remotely operated or semi-autonomous ground vehicles equipped with manipulator arms, disruptors, and spectral sensors to neutralize improvised explosive devices and unexploded ordnance without direct human contact. Tracked configurations lead procurement volumes due to superior obstacle traversal in rubble-strewn urban environments, while wheeled variants compete on transportability and speed for airport and venue security applications. Artificial Intelligence and Sensor Fusion technologies represent the fastest-expanding technology pairing as militaries demand reduced operator cognitive load during high-stress disposal sequences.
FAA regulations govern airspace integration for drone-based EOD reconnaissance support in the United States, while EU procurement directives under the European Defence Fund shape cross-border standardization requirements for NATO interoperable systems. The UK's Ministry of Defence publishes capability standards through the Defence Equipment and Support organization that influence robot durability specifications. Stakeholders must monitor how export control classifications under the Wassenaar Arrangement constrain technology transfer for AI-enabled autonomous navigation subsystems.
Market Dynamics
Artificial intelligence integration into sensor fusion architectures is compressing operator decision cycles and redefining platform procurement specifications across NATO defense ministries.
Growth Catalysts
- Defense Modernization Budgets:NATO members are expanding EOD robot procurement as part of broader counter-IED capability upgrades, with tracked configurations prioritized for urban warfare scenarios.
- FAA Regulatory Clarity:Airspace integration rules for drone-based EOD reconnaissance support in the United States are enabling combined ground-air neutralization tactics previously restricted by operational uncertainty.
- AI-Enabled Autonomy:Machine learning algorithms for threat classification are reducing cognitive load on operators during high-stress disposal sequences, accelerating adoption in special operations units.
Market Restraints
- Export Control Friction:Wassenaar Arrangement classifications constrain technology transfer for autonomous navigation subsystems, limiting vendor access to certain national markets.
- Specialized Component Concentration:High-torque manipulator actuators and hardened spectral sensors rely on concentrated supply sources in Germany and Japan, creating input vulnerability.
- Power Density Limitations:Battery energy density for extended mission endurance in GPS-denied environments remains below operational thresholds for multi-hour autonomous operations.
Strategic Opportunities
- Australian Force Structure Expansion:The Australian Defence Force's accelerated robotics investment under its 2023 Defence Strategic Review creates demand for interoperable EOD platforms compatible with US systems.
- EU Defence Fund Standardization:Cross-border procurement directives are mandating NATO-interoperable command interfaces, favoring vendors with modular software architectures.
- Convergence of Lidar and Thermal Imaging:Sensor fusion combining 3D spatial mapping with heat signature detection is opening concealed-threat identification capabilities in buried ordnance scenarios.
Industry Challenges
- Robotics Engineering Talent Scarcity:Defense contractors face recruitment pressure as commercial autonomous vehicle hiring competition intensifies for embedded systems specialists.
- Multi-Domain Integration Complexity:EOD platforms must interface with existing battlefield management systems, creating software certification bottlenecks under varying national security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosive Ordnance Disposal (EOD) Robot Market |
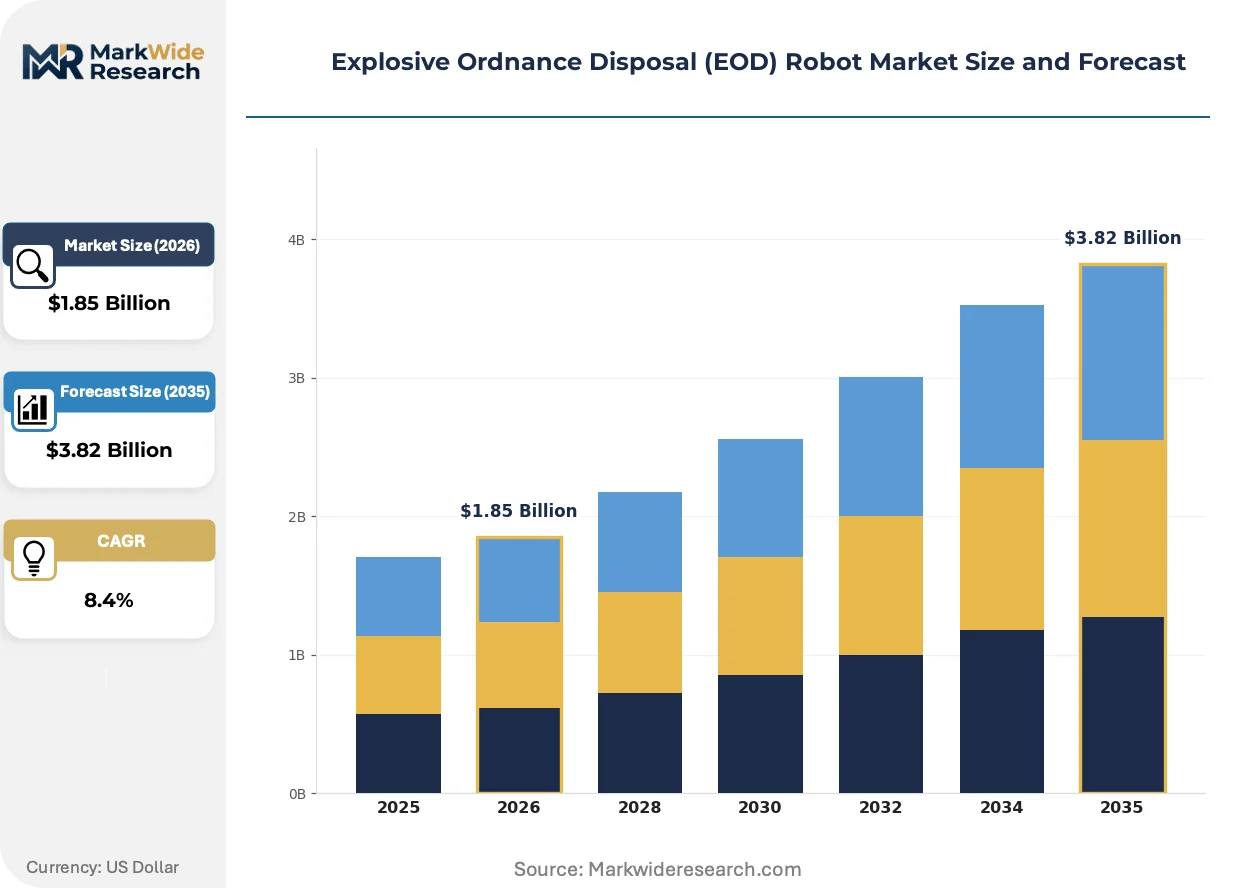
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Tracked, Wheeled, Hybrid, Legged Technology: Remote Control, Autonomous Navigation, Teleoperation, Artificial Intelligence, Sensor Fusion Application: Bomb Disposal, Hazardous Material Handling, Surveillance, Counter-Terrorism End User: Military Units, Bomb Squads, Law Enforcement Agencies, Private Security Contractors |
| Companies Covered | L3Harris Technologies, QinetiQ, iRobot Corporation, Northrop Grumman Corporation, Peraton, Cobham plc, Teledyne FLIR, Chemring Group, Safariland LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosive Ordnance Disposal (EOD) Robot Market Trends and Innovations
Operational requirements are pivoting toward reduced-manning disposal sequences, with technology investment concentrating on autonomy layers that compress decision timelines under contested conditions.
Semi-autonomous manipulation systems with haptic feedback loops are supplanting purely teleoperated arm control in high-threat environments. Special operations commands across NATO are fielding platforms with supervised autonomy for approach and positioning phases. This shift is compressing training pipelines while raising hardware reliability requirements for mission-critical actuators.
EU AI Act risk classification frameworks are imposing documentation burdens on vendors deploying machine learning for threat identification in European defense procurement. The regulation mandates algorithmic transparency for safety-critical autonomous functions. German and French defense ministries are responding with phased procurement clauses that separate AI-enabled platforms from legacy teleoperated systems.
Defense ministries are unbundling platform acquisition from multi-year support contracts, creating direct competition among maintenance providers. Traditional system integrators face pressure from specialized robotics service firms offering predictive diagnostics. This pattern is most pronounced in British Ministry of Defence procurements managed through Defence Equipment and Support frameworks.
Explosive Ordnance Disposal (EOD) Robot Market Segmentation
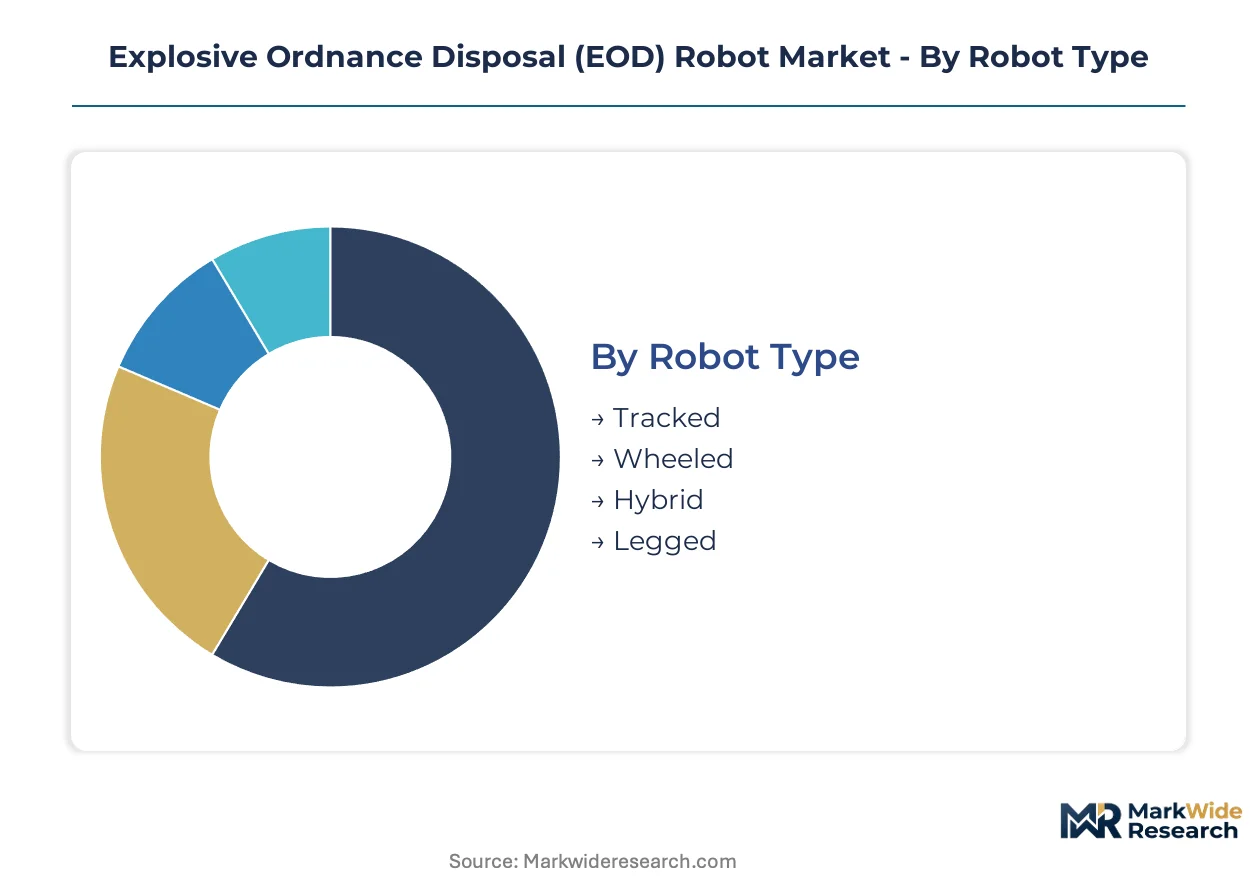
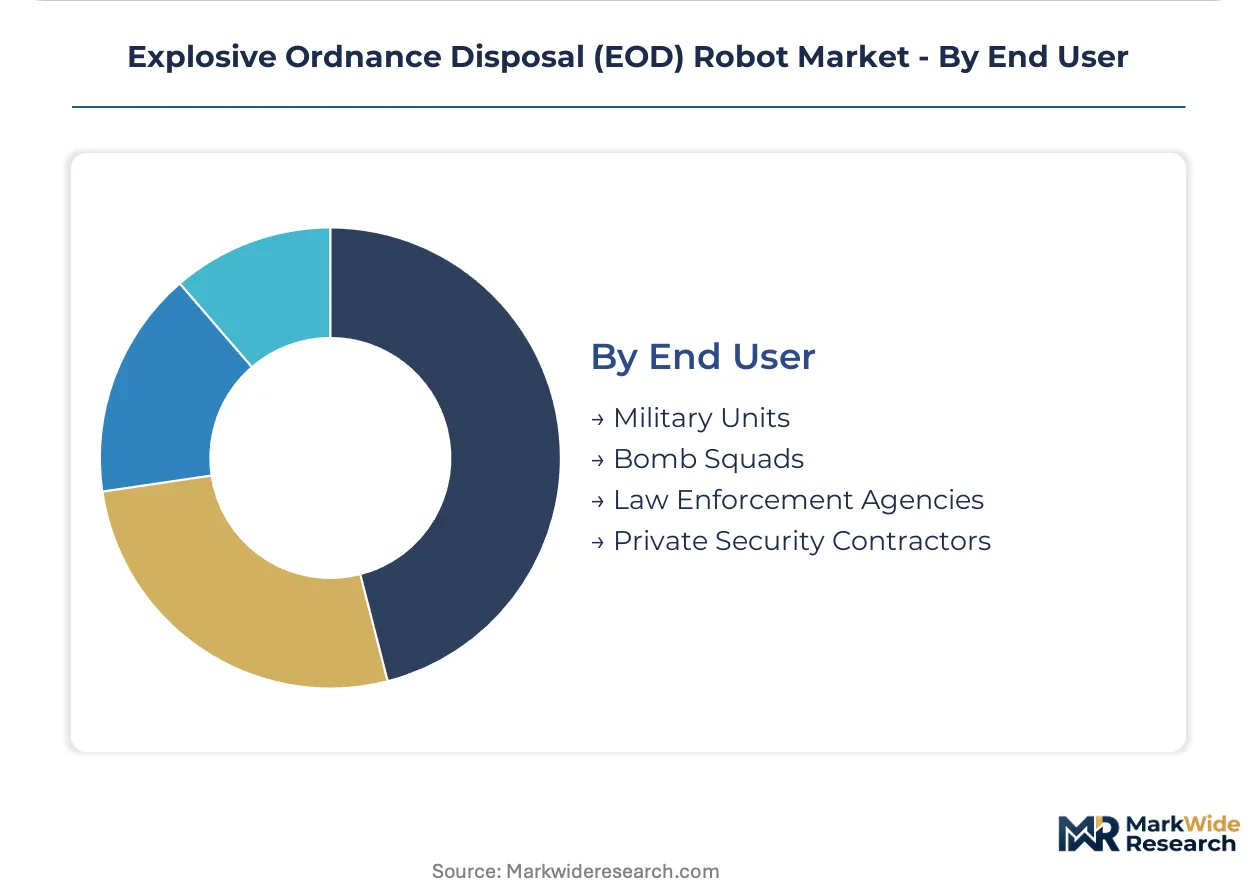
EOD robot procurement specifications diverge sharply across operational contexts, with mobility requirements and autonomy levels driving fundamentally different platform architectures. Defense ministries segment investments by mission profile rather than hardware alone, creating distinct competitive arenas for tracked urban warfare systems versus rapid-deployable wheeled units.
Robot Type:
FAA airspace rules for drone-based EOD reconnaissance in the United States have intensified ground platform specialization, with mobility configurations now calibrated to specific terrain access constraints rather than generic all-terrain claims.
- Tracked:Continuous track systems distribute weight across rubble, stairs, and debris fields in urban combat zones. NATO procurement prioritizes these configurations for counter-IED operations in built-up environments where obstacle density exceeds wheeled platform limits.
- Wheeled:Skid-steer and Ackermann geometries dominate airport perimeter security and venue protection deployments requiring rapid transit across prepared surfaces. German federal police specifications favor compact wheeled units for rapid deployment via standard vehicle transport.
- Hybrid:Articulated leg-track combinations access confined spaces impossible for pure track systems, including collapsed structure voids and narrow stairwells. Australian Defence Force evaluations under the Defence Strategic Review are testing hybrid platforms for subterranean facility clearance.
- Legged:Quadruped and hexapod architectures remain developmental, constrained by actuator reliability and power consumption for extended missions. Japanese research programs through METI funding are advancing legged mobility for nuclear facility inspection derivatives.
Established volume favors Tracked; emerging adoption favors Hybrid.
Technology:
Cost tier stratification separates legacy teleoperated systems from AI-enabled platforms, with procurement budgets fragmenting across capability levels rather than converging on single technology standards.
- Remote Control:Radio-frequency and fiber-tethered direct operator control remains the baseline for cost-constrained law enforcement budgets. British Ministry of Defence sustainment contracts through Defence Equipment and Support maintain large fleets of purely remote-controlled units for training and low-threat scenarios.
- Autonomous Navigation:GPS-denied simultaneous localization and mapping enables approach sequences without continuous operator attention. Special operations commands across NATO are fielding supervised autonomy for initial positioning phases, compressing exposure time.
- Teleoperation:High-bandwidth video relay with haptic feedback manipulator control dominates high-stakes disposal sequences where human judgment remains indispensable. EU AI Act documentation burdens are pushing some European procurement toward teleoperation as an interim compliance pathway.
- Artificial Intelligence:Machine learning threat classification algorithms reduce cognitive load during device identification. Wassenaar Arrangement export controls constrain autonomous navigation subsystem transfers, limiting vendor access to certain national markets.
- Sensor Fusion:Lidar-thermal-radar integration enables concealed threat detection in buried ordnance scenarios. This pairing is climbing the fastest as militaries demand reduced operator decision cycles under contested electromagnetic conditions.
Procurement concentration favors Remote Control; capability investment favors Sensor Fusion.
Application:
Customer type differentiation separates military-grade specifications from commercial security tolerances, with certification requirements and liability frameworks creating distinct product tiers.
- Bomb Disposal:Primary mission profile encompassing IED neutralization, unexploded ordnance clearance, and suspicious package investigation. Military and police bomb squads in the United States, Germany, and Australia account for dominant procurement volumes.
- Hazardous Material Handling:Chemical, biological, and radiological sample collection without human exposure. Japanese nuclear regulatory requirements through METI mandate robotic handling for certain facility maintenance operations.
- Surveillance:Reconnaissance and perimeter monitoring in contaminated or hostile zones. FAA regulations govern airspace integration for drone-based EOD reconnaissance support, enabling combined ground-air tactics.
- Counter-Terrorism:Rapid response to active threat scenarios including hostage rescue support and barricaded suspect containment. French GIGN and German GSG9 special intervention units specify platforms with ballistic protection and high-speed mobility.
Institutional procurement favors Bomb Disposal; emerging doctrine favors Counter-Terrorism.
End User:
Maturity gradients separate established military acquisition systems from emerging private sector demand, with contract structures and payment terms varying substantially across buyer categories.
- Military Units:Army, Marine, and special operations forces with formal counter-IED tasking. Tracked configurations with integrated disruptors and spectral sensors dominate these specifications.
- Bomb Squads:Municipal and state-level explosive ordnance technicians with dual military-civilian training backgrounds. Wheeled transportability and rapid deployment capability prioritize these acquisitions.
- Law Enforcement Agencies:Police tactical units with occasional EOD requirements rather than dedicated mission focus. Budget constraints favor teleoperated systems over AI-enabled platforms.
- Private Security Contractors:Corporate and critical infrastructure protection services in high-threat environments. This segment is expanding most quickly as mining, energy, and maritime operators adopt military-derived robotics for site protection.
Contract volume favors Military Units; growth trajectory favors Private Security Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airspace integration rules for drone-based EOD reconnaissance support in the United States anchor procurement specifications across NATO defense ministries. Military modernization budgets in Australia, Germany, and the United Kingdom are accelerating tracked robot deployment for urban counter-IED operations.
United States
Army and Marine Corps counter-IED task forces drive procurement volumes for tracked configurations with integrated disruptors. FAA regulations governing drone-based reconnaissance support enable combined ground-air neutralization tactics previously restricted by operational uncertainty. Pittsburgh-based robotics engineering clusters concentrate talent migration from commercial autonomous vehicle sectors toward defense contractors.
Germany
Federal police specifications for compact wheeled units prioritize rapid deployment via standard vehicle transport for airport perimeter security. EU AI Act risk classification frameworks impose documentation burdens on vendors deploying machine learning for threat identification in European defense procurement. Bavarian industrial centers supply high-torque manipulator actuators concentrated in specialized component manufacturing.
Australia
The Australian Defence Force's accelerated robotics investment under its 2023 Defence Strategic Review creates demand for interoperable EOD platforms compatible with US systems. TGA-equivalent defense procurement frameworks mandate durability specifications for subterranean facility clearance operations. Melbourne and Sydney defense technology corridors host evaluation programs for hybrid leg-track platforms.
United Kingdom
Ministry of Defence sustainment contracts through Defence Equipment and Support maintain large fleets of remote-controlled units for training and low-threat scenarios. British capability standards influence robot durability specifications across Commonwealth procurement systems. London and Midlands defense engineering bases sustain long-running support relationships with tracked robot fleet operators.
Japan
METI-funded research programs advance legged mobility architectures for nuclear facility inspection derivatives constrained by actuator reliability limitations. Japanese nuclear regulatory requirements mandate robotic handling for certain facility maintenance operations. Tokyo-Osaka industrial corridors concentrate developmental quadruped platforms for confined-space access applications.
Explosive Ordnance Disposal (EOD) Robot Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the EOD robot market. Tier-one vendors leverage communications heritage and unmanned systems expertise to dominate integrated command-and-control payloads. Tier-two specialists compete on modular software architectures and predictive diagnostics capabilities. Dominant competitive moves include strategic partnerships for NATO-interoperable interfaces and technology licensing for sensor fusion subsystems.
Among US-based defense contractors, L3Harris Technologies and Northrop Grumman Corporation occupy positions within the integrated systems tier. QinetiQ represents the specialist tier anchored by long-running support contract relationships. These three exemplify contrasting archetypes: communications-heritage integration, airborne-ground robotics convergence, and sustainment-focused fleet management respectively.
| Leading Market Players |
|---|
| L3Harris Technologies |
| QinetiQ |
| iRobot Corporation |
| Northrop Grumman Corporation |
| Peraton |
| Cobham plc |
| Teledyne FLIR |
| Chemring Group |
| Safariland LLC |
| Others |
Pricing and Supply Chain Analysis
Wassenaar Arrangement export classifications gate both vendor qualification and price tiering in the EOD robot market, restricting autonomous navigation subsystem transfers to approved destinations while permitting legacy teleoperated systems to flow more freely. This regulatory filter stratifies the supply base into AI-enabled premium vendors and cost-optimized remote-control suppliers serving law enforcement budgets.
Pricing Analysis
German federal police contracts for compact wheeled units command 15-20% premiums over comparable US municipal bomb squad procurements due to EU AI Act compliance documentation burdens. Three-tier pricing structure across premium, standard, and economy levels separates NATO-interoperable tracked systems with integrated disruptors from teleoperated training platforms and basic law enforcement configurations. Cost compression in the economy tier is intensifying because battery energy density limitations force hardware redundancy for mission assurance. Military units exhibit lowest price sensitivity due to operational risk tolerance, while private security contractors negotiate aggressively on per-unit acquisition costs.
Supply Chain Analysis
Defense contractors maintain strategic stockpiles of high-torque manipulator actuators and hardened spectral sensors rather than just-in-time sourcing given lead time volatility from German and Japanese component specialists. Manufacturing concentrates in the United States, Germany, and Australia for final platform assembly, with critical inputs drawing from Bavarian precision actuator clusters and Tokyo-Osaka sensor fabrication corridors. Single-source vulnerability in GPS-denied navigation chipsets creates supply chain risk given concentrated semiconductor fabrication. Distribution runs through defense ministry procurement frameworks and specialized robotics service firms offering predictive diagnostics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are recovering from pandemic-era budget compression as NATO members accelerate counter-IED capability upgrades under revised threat assessments. This cyclical upturn favors vendors with established military relationships and modular software architectures.
For Market Incumbents: Shield market position by deepening backward integration into high-torque actuator production in Germany, reducing exposure to Japanese supply concentration. Invest in EU AI Act certification pathways ahead of phased procurement clauses separating AI-enabled platforms from legacy systems. Channel control through multi-year support contracts remains the priority lever against specialized robotics service firms.
For New Entrants and Emerging Players: Anchor in private security contractor demand for site protection applications, the fastest-expanding end-user segment with lower certification barriers than military procurement. Target Australian Defence Force evaluations under the 2023 Defence Strategic Review for interoperable platform opportunities. A go-to-market angle emphasizing predictive diagnostics capabilities bypasses incumbent advantages in fleet scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates with underperforming ground robotics divisions lacking AI-enabled autonomy roadmaps. Long-term viability hinges on sensor fusion integration capabilities across the 5-10 year procurement horizon. The signal to watch is EU Defence Fund standardization mandates crossing procurement volume thresholds that favor modular software architectures over proprietary systems.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Autonomy Investment | Machine learning threat classification reduces operator cognitive load during NATO disposal sequences. |
| Sensor Fusion Subsystem Licensing | Lidar-thermal-radar integration opens concealed-threat identification in buried ordnance scenarios. |
| NATO-Interoperable Interface Partnership | Modular command architectures capture EU Defence Fund cross-border standardization mandates. |
| Predictive Diagnostics Capability Buildout | Service-based revenue streams displace traditional system integrators in British Ministry of Defence frameworks. |
| Hybrid Mobility Platform Development | Leg-track combinations access subterranean facility clearance opportunities in Australian Defence Force evaluations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of defense ministry procurement databases, Wassenaar Arrangement control lists, and FAA regulatory filings. EOD program managers at NATO defense ministries, robotics engineering leads at tier-one contractors, and procurement officers at Defence Equipment and Support provided operational requirement perspectives. Customs trade data for tracked vehicle components, SEC filings from publicly traded defense contractors, and EU AI Act implementation guidance supplied secondary validation. Bottom-up platform shipment estimates triangulate against top-down defense budget allocation analysis.
Segmentation dimensions modeled span robot type, technology tier, application mission profile, and end-user category across the projection horizon. CAGRs derive from weighted scenario analysis incorporating procurement pipeline visibility and regulatory implementation timelines. Forecast inputs include NATO counter-IED task force expansion plans, EU Defence Fund disbursement schedules, and Australian Defence Strategic Review robotics investment commitments.
Material uncertainties — Wassenaar Arrangement classification revisions, EU AI Act enforcement intensity, and battery energy density breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about sustained NATO defense modernization commitments and stable export control frameworks. Revision becomes warranted when autonomous navigation subsystem declassification crosses policy thresholds enabling vendor market expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Micro Tactical Ground Robot Market
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Unmanned Ground Vehicle Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market