
 UAV Propulsion System Market | 2026-2036
UAV Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Propulsion System Market Outlook
FAA Remote ID rules are repositioning the cost-of-entry calculus for commercial UAV developers by mandating certified propulsion traceability from design through operation. RTX leverages its aerospace pedigree to dominate turbine-electric architectures for Group 5 military platforms. Honeywell International Inc. anchors hybrid-electric development through its dedicated unmanned systems division in Phoenix. BRP-Rotax GmbH & Co KG competes in the light-fuel-engine segment where its 912iS series powers mid-tier surveillance drones.
A UAV propulsion system integrates energy conversion, thermal management, and thrust generation hardware to sustain controlled flight across varying payload and endurance profiles, with specific power densities now exceeding 5 kW/kg in leading electric motor designs. The system serves commercial inspection, precision agriculture, and defense ISR missions where loiter time and acoustic signature determine operational utility. Electric Motors and Battery components lead current shipment volumes but Fuel Cells within the Technology dimension represent the fastest-expanding margin pool as developers pursue multi-hour endurance. Hybrid Systems across the Component axis occupy the premium tier where military end-users pay for redundancy and extended range.
The FAA, EASA, and ISO are converging on propulsion certification standards that will bifurcate the supplier base between civil-compliant and defense-only architectures. EASA's Special Condition for VTOL and ISO 21384-3 unmanned aircraft system standards are forcing manufacturers to document mean time between failures for critical rotating components. Stakeholders must monitor which regulatory jurisdiction certifies first-mover hybrid platforms, as mutual recognition agreements will determine export market access for propulsion OEMs.
Market Dynamics
The FAA's Remote ID mandate and NATO's expanding Group 5 drone procurement are compressing development timelines for certified propulsion architectures, forcing suppliers to bifurcate between civil-compliant and defense-only product lines.
Growth Catalysts
- Remote ID Compliance Deadlines:The FAA's 2024 operational mandate for Remote ID traceability is accelerating replacement cycles for legacy propulsion systems in commercial fleets.
- Long-Endurance ISR Demand:NATO members are expanding procurement for Group 4-5 platforms requiring turbine-electric and hybrid architectures with multi-hour loiter capability.
- UTM Framework Maturation:Urban Air Mobility corridors in the United States and European testbed cities are creating certified demand for redundant propulsion configurations.
Market Restraints
- Critical Mineral Supply Concentration:Rare earth magnet supply for high-performance electric motors concentrates in Chinese processing facilities, exposing OEMs to export control volatility.
- Certification Cost Escalation:EASA's Special Condition for VTOL and ISO 21384-3 documentation requirements for mean time between failures are inflating development budgets for rotating components.
- Hydrocarbon Fuel Access Limitations:Forward-deployed military operators face logistics constraints for aviation gasoline, limiting Rotax-powered platform deployment in contested environments.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for drones and unmanned systems is creating localized demand for propulsion OEMs willing to establish domestic assembly.
- Hydrogen Fuel Cell Convergence:Integration of PEM fuel cells with lithium-sulfur batteries is opening endurance segments beyond current lithium-ion limitations for maritime patrol applications.
- Modular Swappable Architectures:Battery-swapping networks for commercial delivery drones in the United Arab Emirates and Singapore are creating aftermarket service revenue pools.
Industry Challenges
- Thermal Management Expertise Scarcity:The intersection of aerospace cooling design and high-voltage power electronics requires hybrid skill sets that remain concentrated in legacy automotive and defense primes.
- Dual-Use Export Control Complexity:ITAR and EU dual-use regulations are fragmenting supply chains as suppliers segregate civil and defense production lines to maintain market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Propulsion System Market |
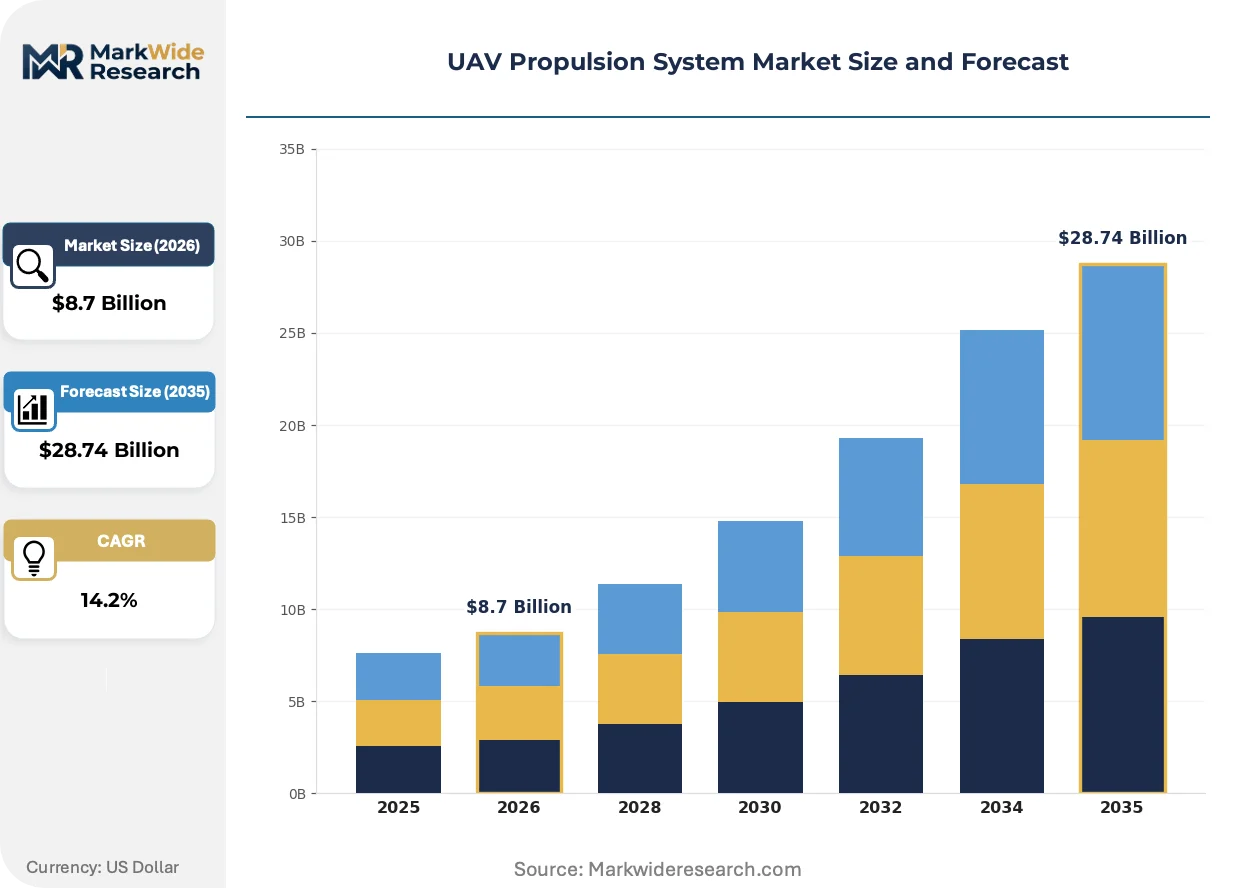
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Electric Motors, Internal Combustion Engines, Hybrid Systems, Batteries Power Rating: Low Power, Medium Power, High Power, Ultra High Power Technology: LiPo Batteries, Fuel Cells, Solar Energy, Turbine Engines Application: Commercial Drones, Military Drones, Surveillance, Agricultural Use |
| Companies Covered | RTX, Honeywell International Inc., Rolls-Royce Holdings PLC, General Electric Company, 3W International GmbH, BRP-Rotax GmbH & Co KG, UAV Engines Ltd., Hirth Engines GmbH, Sky Power GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Propulsion System Market Strategic Shifts
Propulsion architectures are fragmenting into modular, mission-specific configurations as electric, hybrid, and fuel-cell technologies compete across endurance and payload tiers without a dominant standard emerging.
Silicon carbide power electronics are modularizing inverter and motor controller designs for high-voltage electric propulsion. Defense primes and eVTOL developers in the United States and Germany are adopting these topologies for 800V architectures. This compression of power conversion mass is modularizing platform design, allowing airframe engineers to swap propulsion scales without redesigning thermal management.
EASA's Special Condition for VTOL and the FAA's evolving Type Certification basis for unmanned aircraft are mandating documented failure modes for critical rotating components. These frameworks are forcing propulsion OEMs to adopt aerospace-grade quality systems previously reserved for manned aviation. European developers pursuing UAM certification are absorbing the highest compliance burden, creating a two-year lead time gap versus US experimental category operations.
Defense procurement offices are unbundling propulsion systems from airframe contracts, creating direct vendor relationships with motor and battery suppliers previously shielded by systems integrators. This disintermediation is visible in US Army FTUAS and Marine Corps MUX programs, where propulsion performance guarantees now sit in separate contractual vehicles from platform awards. The shift compresses supplier margins while expanding addressable market access for component specialists.
UAV Propulsion System Market Segmentation
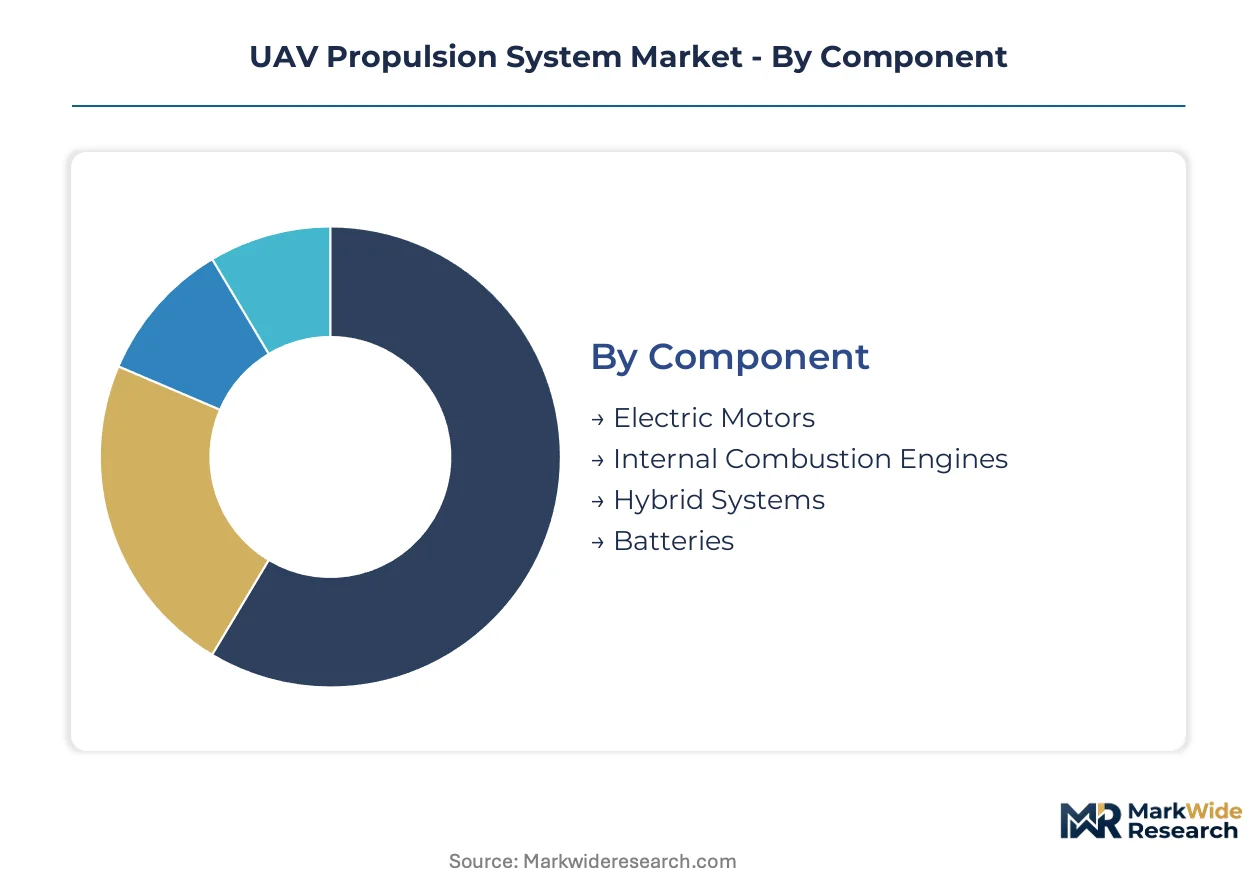
UAV propulsion architectures fragment across energy conversion methods, power density thresholds, and mission endurance requirements. Procurement patterns diverge sharply between commercial operators prioritizing unit economics and defense integrators demanding redundancy and extended loiter capability.
Component:
Electric motor topology and energy storage chemistry define platform weight, thermal envelope, and maintenance interval.
- Electric Motors:Brushless DC and permanent magnet synchronous designs now achieve specific power densities exceeding 5 kW/kg, enabling multi-rotor platforms for commercial inspection and last-mile delivery in the United States. FAA Remote ID compliance deadlines are accelerating fleet replacement cycles for legacy brushed motor systems.
- Batteries:Lithium-polymer and emerging lithium-sulfur cell chemistries dominate commercial shipment volumes, though energy density limitations constrain endurance beyond 90 minutes for most payload configurations. Maritime patrol and long-range ISR operators are pressuring suppliers for higher gravimetric performance.
- Hybrid Systems:Turbine-electric and piston-electric architectures occupy the premium tier where NATO Group 5 platforms require multi-hour endurance with propulsion redundancy.
- Internal Combustion Engines:Rotax and similar light-fuel powerplants persist in mid-tier surveillance drones where refueling infrastructure exists and acoustic signature constraints are secondary.
Mature deployment sits with Internal Combustion Engines. Newer deployment is concentrated in Electric Motors.
Power Rating:
Power class determines airframe scale, regulatory certification pathway, and supplier qualification requirements.
- Low Power:Systems below 5 kW output serve consumer and light commercial drones for photography and short-range inspection. ISO 21384-3 documentation requirements for mean time between failures are inflating development budgets even at this tier.
- Medium Power:5-25 kW architectures address agricultural spraying and infrastructure survey markets where payload mass and flight duration balance against capital cost.
- High Power:25-100 kW systems enable Group 3-4 military platforms and emerging eVTOL prototypes in German and US urban air mobility testbeds. EASA's Special Condition for VTOL imposes the highest compliance burden on developers in this class.
- Ultra High Power:Exceeding 100 kW, these systems support Group 5 ISR platforms and cargo UAVs where turbine-electric or hydrogen fuel cell architectures compete for contract awards.
Volume concentrates in Low Power. Value expansion is climbing the fastest in Ultra High Power.
Technology:
Energy source selection trades recharge speed, logistics footprint, and signature characteristics against endurance requirements.
- LiPo Batteries:Lithium-polymer cells dominate commercial and light military applications with established supply chains and rapid charge capability. Rare earth magnet supply concentration in Chinese processing facilities exposes OEMs to export control volatility.
- Fuel Cells:Proton exchange membrane systems integrated with lithium-sulfur buffers are gaining share in maritime patrol and long-endurance ISR where multi-hour loiter is non-negotiable.
- Turbine Engines:Micro-turbines and small gas turbines anchor Group 5 military platforms requiring jet fuel commonality with manned aviation logistics.
- Solar Energy:Photovoltaic-augmented systems serve high-altitude pseudo-satellite platforms and stratospheric relay drones with multi-day endurance requirements.
Installed base centers on LiPo Batteries. Technology transition is accelerating most quickly in Fuel Cells.
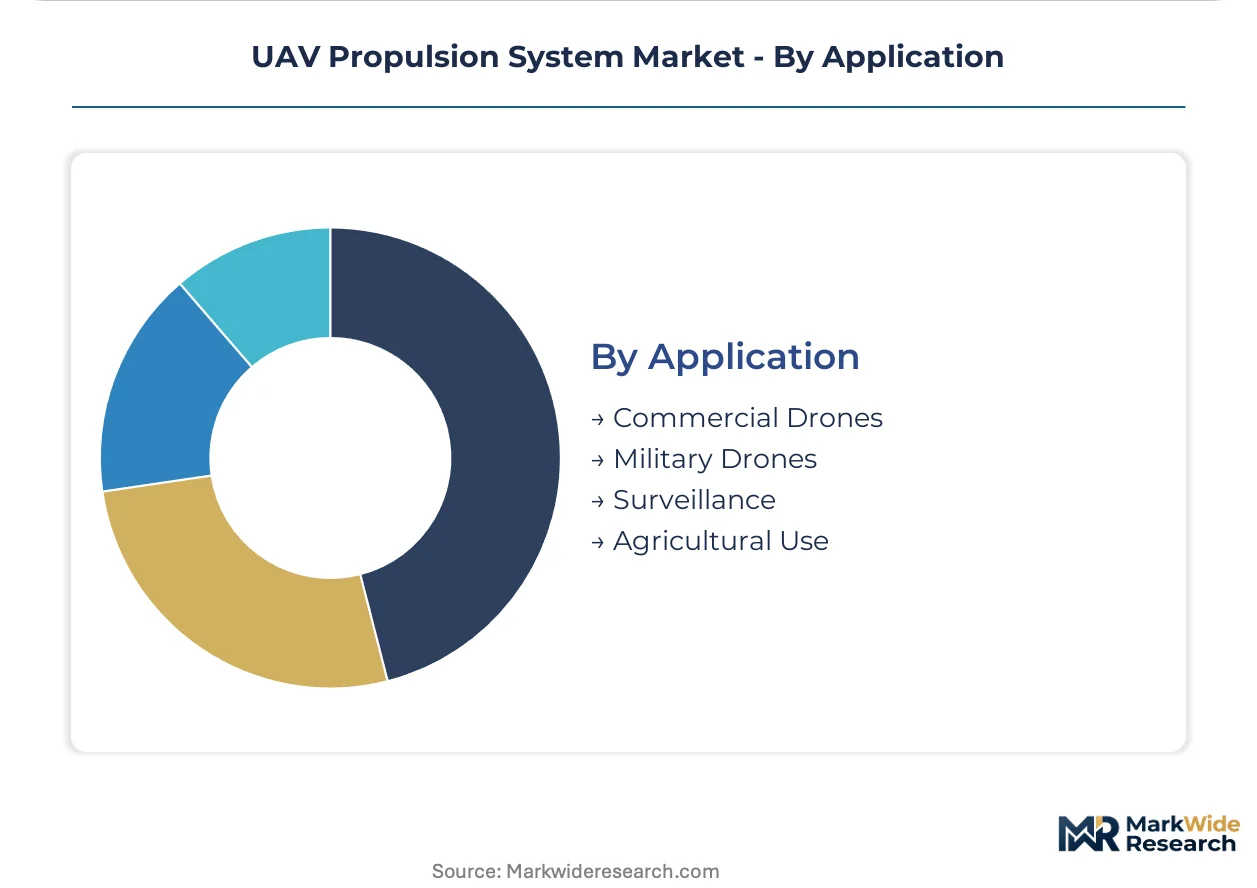
Application:
Mission profile dictates propulsion architecture selection through endurance, payload, and environmental operating envelope requirements.
- Military Drones:Group 4-5 platforms require turbine-electric or hybrid architectures with documented failure modes for critical rotating components under EASA and FAA certification frameworks. US Army FTUAS and Marine Corps MUX programs are disintermediating propulsion suppliers from airframe integrators.
- Commercial Drones:Last-mile delivery and infrastructure inspection drive demand for battery-swappable electric architectures in the United Arab Emirates and Singapore.
- Surveillance:Law enforcement and border security applications balance acoustic signature against endurance, favoring electric and hybrid systems for urban operations.
- Agricultural Use:Crop spraying and precision agriculture platforms prioritize payload capacity and dust ingress protection over extended range.
Procurement scale favors Military Drones. Civil certification urgency is expanding most rapidly in Commercial Drones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the United States, Germany, and India are concentrating UAV propulsion manufacturing through targeted tax incentives and defense procurement localization requirements.
United States
Defense primes and eVTOL developers in Phoenix and Austin drive demand for certified hybrid-electric architectures. The FAA's Remote ID mandate and evolving Type Certification basis for unmanned aircraft compress development timelines for propulsion OEMs. RTX and Honeywell anchor turbine-electric development in Arizona and Massachusetts corridors.
Germany
EASA's Special Condition for VTOL imposes rigorous documentation requirements on Munich and Stuttgart-based developers pursuing urban air mobility certification. The country's aerospace supply chain leverages automotive power electronics expertise from Baden-Württemberg. Rolls-Royce and Hirth Engines occupy positions in the turbine and light-fuel engine segments.
China
Rare earth magnet processing concentration in Jiangxi and Inner Mongolia shapes electric motor supply security for domestic and export markets. MIIT standards and dual carbon goals accelerate fuel cell development for long-endurance maritime patrol platforms. Shenzhen and Beijing clusters host integrated propulsion-airframe developers.
India
The PLI scheme for drones and unmanned systems creates localized assembly demand in Karnataka and Telangana. DGFT export incentives and defense indigenization targets attract joint ventures with foreign propulsion specialists. Bangalore and Hyderabad emerge as testbeds for tropical-environment propulsion validation.
United Kingdom
UAV Engines Ltd. anchors light-fuel powerplant manufacturing in Staffordshire for NATO-aligned defense programs. The country's military procurement offices are disintermediating propulsion suppliers from airframe integrators under FTUAS-influenced contracting models. Bristol and Southampton clusters focus on maritime patrol propulsion integration.
UAV Propulsion System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where defense-grade aerospace heritage separates premium suppliers from commercial commodity players. Tier-one positions concentrate among US and European conglomerates with established airworthiness qualification pathways. Three archetypes dominate: turbine-electric systems integrators, hybrid-electric subsystem developers, and light-fuel engine specialists. Competitive moves center on disintermediation—direct vendor relationships with defense procurement offices—and geographic localization through joint ventures in India and the Middle East.
Within the diversified conglomerate tier, RTX and Honeywell International Inc. exemplify aerospace heritage positioning for Group 5 military platforms and emerging eVTOL applications. BRP-Rotax GmbH & Co KG occupies a specialist position in the light-fuel engine segment where its GmbH structure reflects European engineering concentration. These three entities represent distinct competitive vectors: turbine-electric dominance, hybrid-electric subsystem integration, and mid-tier surveillance powerplants.
| Leading Market Players |
|---|
| RTX |
| Honeywell International Inc. |
| Rolls-Royce Holdings PLC |
| General Electric Company |
| 3W International GmbH |
| BRP-Rotax GmbH & Co KG |
| UAV Engines Ltd. |
| Hirth Engines GmbH |
| Sky Power GmbH |
| Others |
Value Chain & Pricing Dynamics
EASA's Special Condition for VTOL and FAA Type Certification mandates gate qualified supply access for propulsion OEMs, concentrating premium-tier pricing power among aerospace-grade suppliers with documented failure-mode libraries while excluding commodity motor vendors from certified platform bids.
Pricing Analysis
Lead-time-driven pricing stratification rewards certified suppliers with 24-month order backlogs, while spot inventory for commercial-grade electric motors trades at steep discounts. Three-tier pricing structure across aerospace-certified, industrial-grade, and consumer-tier segments reflects documentation burden and mean-time-between-failures guarantees. Pricing pressure stems from rare earth magnet cost volatility as Chinese export controls tighten. Defense integrators exhibit lowest price sensitivity; commercial delivery operators in the United Arab Emirates and Singapore demand unit-economy optimization.
Supply Chain Analysis
Workforce scarcity in aerospace-cooling design and high-voltage power electronics concentrates manufacturing in Phoenix, Austin, and Stuttgart where automotive-electronics talent pools overlap with defense prime operations. Rare earth magnet processing draws from Jiangxi and Inner Mongolia; silicon carbide substrates source from Japan and Germany; lithium-sulfur cell chemistry development centers on South Korea and the United States. Single-source vulnerability in Chinese rare earth refining exposes OEMs to export control disruption. Distribution runs through defense procurement offices disintermediating propulsion from airframe contracts, plus commercial UAV OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: thermal management expertise scarcity props pricing for qualified hybrid-electric architectures while uncertified commodity suppliers face margin compression.
For Market Incumbents: Acquire thermal management engineering teams with automotive power electronics pedigrees to close capability gaps in 800V architecture design. Consolidate certification documentation libraries to accelerate EASA and FAA approval cycles before emerging eVTOL developers build captive in-house propulsion divisions. Lock long-term rare earth magnet offtake with non-Chinese processors to hedge export control exposure. For New Entrants and Emerging Players: Begin with modular battery-swapping architectures for commercial delivery fleets in India and the Middle East where PLI incentives and desert-climate validation requirements create white-space entry. Target agricultural spraying platforms in Brazil and Australia where dust-ingress protection specifications remain underspecified versus defense certification tiers. Partner with existing airframe OEMs rather than pursuing direct defense procurement qualification. For Investors and Strategic Acquirers: First-mover hybrid platform certification under EASA's Special Condition is the leading indicator that a propulsion supplier has achieved defensible aerospace-grade positioning. Five-to-ten-year viability favors specialists with documented failure-mode libraries over diversified conglomerates exposed to defense budget cycle volatility. Monitor FAA Type Certification award announcements for unmanned aircraft as inflection signals for qualified supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in EASA Special Condition | Documentation of mean-time-between-failures for rotating components separates aerospace-grade suppliers from commodity vendors. |
| Backward Integration into Rare Earth Magnet Processing | Captive supply of neodymium-iron-boron magnets insulates OEMs from Chinese export control volatility in Jiangxi facilities. |
| Joint Venture in Indian PLI Corridors | Localized assembly in Karnataka and Telangana satisfies DGFT indigenization targets for defense procurement access. |
| Silicon Carbide Power Electronics Adoption | 800V inverter architectures from Baden-Württemberg automotive suppliers compress power conversion mass for eVTOL scaling. |
| Direct Defense Procurement Relationship | Unbundled propulsion contracts under US Army FTUAS and Marine Corps MUX programs expand addressable market for component specialists. |
Study Parameters
Independent corroboration across primary interviews with propulsion system engineering directors, defense procurement officers, and commercial UAV fleet operators, plus secondary validation through FAA Type Certification filings, EASA Special Condition documentation, and SEC 10-K disclosures from diversified aerospace conglomerates, underwrites the qualitative findings. Bottom-up shipment estimates for electric motor and battery component volumes triangulate against top-down defense budget appropriations and commercial fleet replacement cycles driven by Remote ID compliance deadlines.
Rate-of-change decomposition across the projection horizon models segment-level CAGRs by disaggregating volume shifts in Group 3-5 military platform procurement, eVTOL prototype development timelines, and agricultural spraying fleet electrification. Segmentation dimensions include power rating tier, energy conversion technology, certification grade, and regional regulatory cluster. Forecast inputs incorporate rare earth magnet price indices, lithium-sulfur cell energy density improvement curves, and turbine-electric architecture adoption rates in NATO member states.
Export control expansion in Chinese rare earth processing, EASA-FAA mutual recognition agreement delays, and hydrogen fuel cell stack cost breakthroughs are the dominant revision risks to propulsion technology mix assumptions. Forecasts reflect documented certification timelines and procurement program award schedules. Material deviation in named triggers warrants pause and re-evaluation of hybrid-electric versus fuel-cell transition trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Aircraft Cooling Turbines Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
Aircraft Micro Turbine Engine Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aircraft Lift Control Devices Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aviation Actuator System Market