
 Unmanned Aerial Vehicle Payload and Subsystems Market | 2026-2036
Unmanned Aerial Vehicle Payload and Subsystems Market Size, Share, and Industry Trends Forecast 2026-2036
Unmanned Aerial Vehicle Payload and Subsystems Market Insights
Aftermarket sensor calibration and firmware upgrade revenue is reconfiguring margin pools away from initial hardware sales across the UAV payload ecosystem. Lockheed Martin Corporation leverages its classified program integration experience to sustain premium positioning in signals intelligence payloads. AeroVironment, Inc. anchors its growth in small unmanned systems where modular swappable payloads dominate procurement specifications. Elbit Systems competes through vertical integration from gimbal mechanics to mission software.
Unmanned Aerial Vehicle Payload and Subsystems encompass the mission-critical equipment modules—electro-optical/infrared cameras, synthetic aperture radar, electronic warfare packages, and data-link transceivers—mounted aboard drones to execute specific operational tasks, typically operating across radio frequencies from L-band to Ku-band with stabilized pointing accuracy below 50 microradians. Camera Systems and Sensor Arrays command the largest installed base due to persistent intelligence requirements, while Communication Equipment experiences accelerated procurement as mesh networking and SATCOM integration become standard for beyond-line-of-sight missions. Control Systems retain mature margins in defense applications but face price pressure from open-architecture standards pushing interoperability across platforms.
FAA regulations under Part 107 and evolving beyond-visual-line-of-sight waivers shape commercial payload certification timelines, while ITAR controls and EAR dual-use classifications govern cross-border transfers of military-grade subsystems. The EU AI Act and proposed autonomous systems liability frameworks introduce compliance layers for AI-enabled targeting and navigation payloads exported to European operators. Stakeholders must monitor fragmentation between national airworthiness regimes and emerging NATO standardization agreements for interchangeable payload interfaces.
Market Dynamics
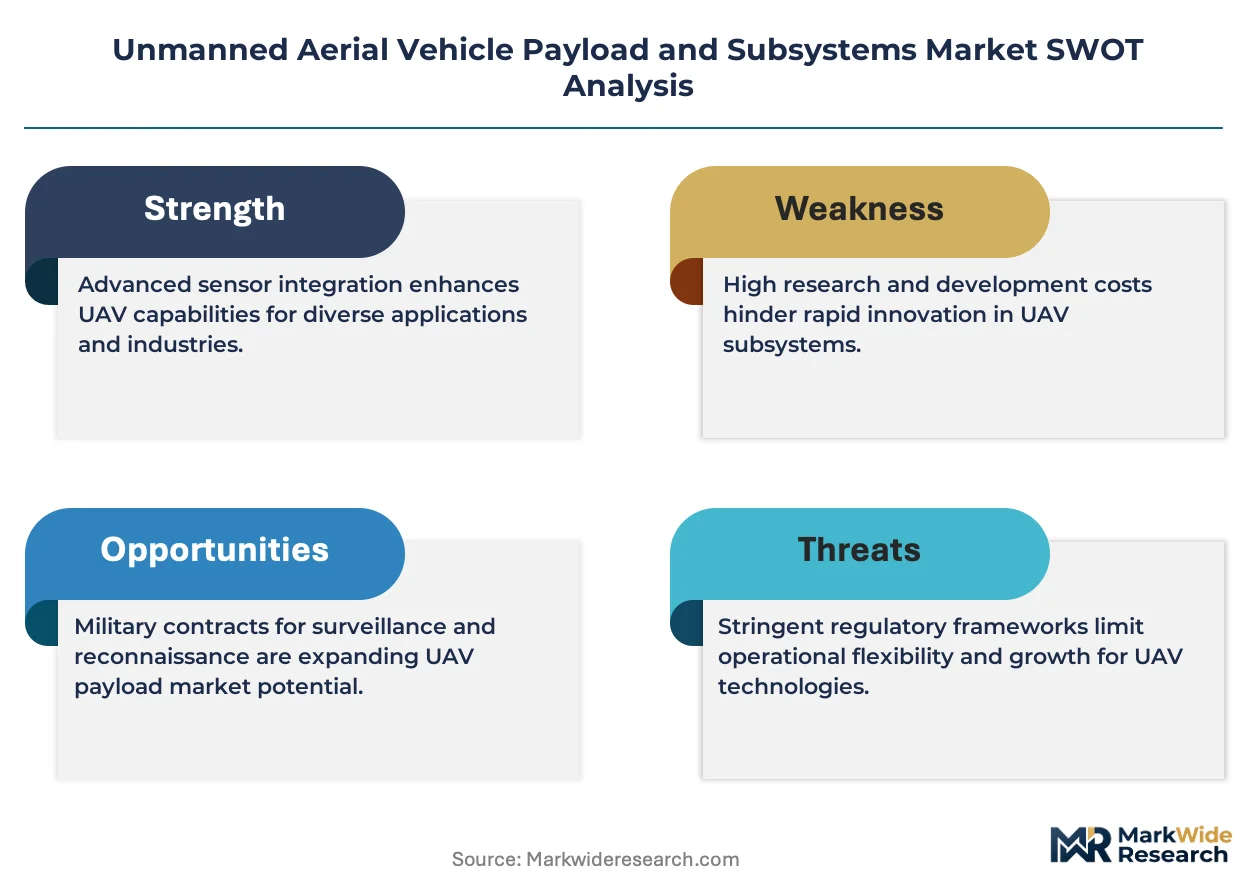
Defense procurement agencies in NATO member states are consolidating contracts around modular, software-defined payloads that swap mission profiles without hardware replacement, compressing supplier qualification cycles and privileging vendors with classified integration clearances.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Waivers:FAA Part 107 exemptions and EASA equivalent certifications for commercial drone operations are expanding addressable use cases for long-range communication subsystems in infrastructure inspection and agricultural monitoring.
- Synthetic Aperture Radar Miniaturization:Gallium nitride semiconductor advances are reducing SWaP-C constraints for all-weather imaging payloads, opening penetration into tactical small unmanned systems previously limited to electro-optical sensors.
- NATO Standardization Agreements:STANAG 4671 and related interoperability mandates for unmanned systems are creating pull-through demand for interchangeable gimbal interfaces and common data-link architectures across allied defense procurement.
Market Restraints
- ITAR-Controlled Component Concentration:Export licensing requirements for thermal imaging cores and encrypted data-links concentrate supply among cleared US manufacturers, extending lead times for non-US platform integrators by 8-14 months.
- Rare Earth Magnet Pricing Volatility:Neodymium and dysprosium price swings for precision gimbal motors introduce 12-18% cost variance in stabilized payload production, compressing margins for mid-tier subsystem suppliers.
- Ku-Band Spectrum Congestion:Military SATCOM frequency allocation overlaps with commercial satellite services are creating interference management complexity for high-bandwidth intelligence payloads operating in contested electromagnetic environments.
Strategic Opportunities
- Urban Air Mobility Payload Integration:Emerging eVTOL cargo and passenger platforms in Germany and the United Arab Emirates require lightweight detect-and-avoid sensors, creating greenfield demand for solid-state lidar and millimeter-wave radar subsystems.
- AI-Enabled Target Recognition:Convergence of edge-computing inference accelerators with electro-optical streaming is enabling onboard object classification without ground station dependency, reducing latency for time-sensitive strike coordination.
- Open Architecture Mandates:US Army's Future Vertical Lift and NATO allied equivalents are mandating MOSA-compliant payload interfaces, creating replacement-cycle opportunities for proprietary legacy systems in attack reconnaissance helicopter programs.
Industry Challenges
- Electromagnetic Environmental Effects Certification:Platform-level hardening requirements for high-altitude electromagnetic pulse resilience are extending qualification timelines for new payload introductions by 18-24 months.
- Cross-Domain Data Fusion Expertise:Shortage of systems engineers capable of integrating signals intelligence, electro-optical, and electronic warfare streams into unified mission software is constraining prime contractor delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unmanned Aerial Vehicle Payload and Subsystems Market |
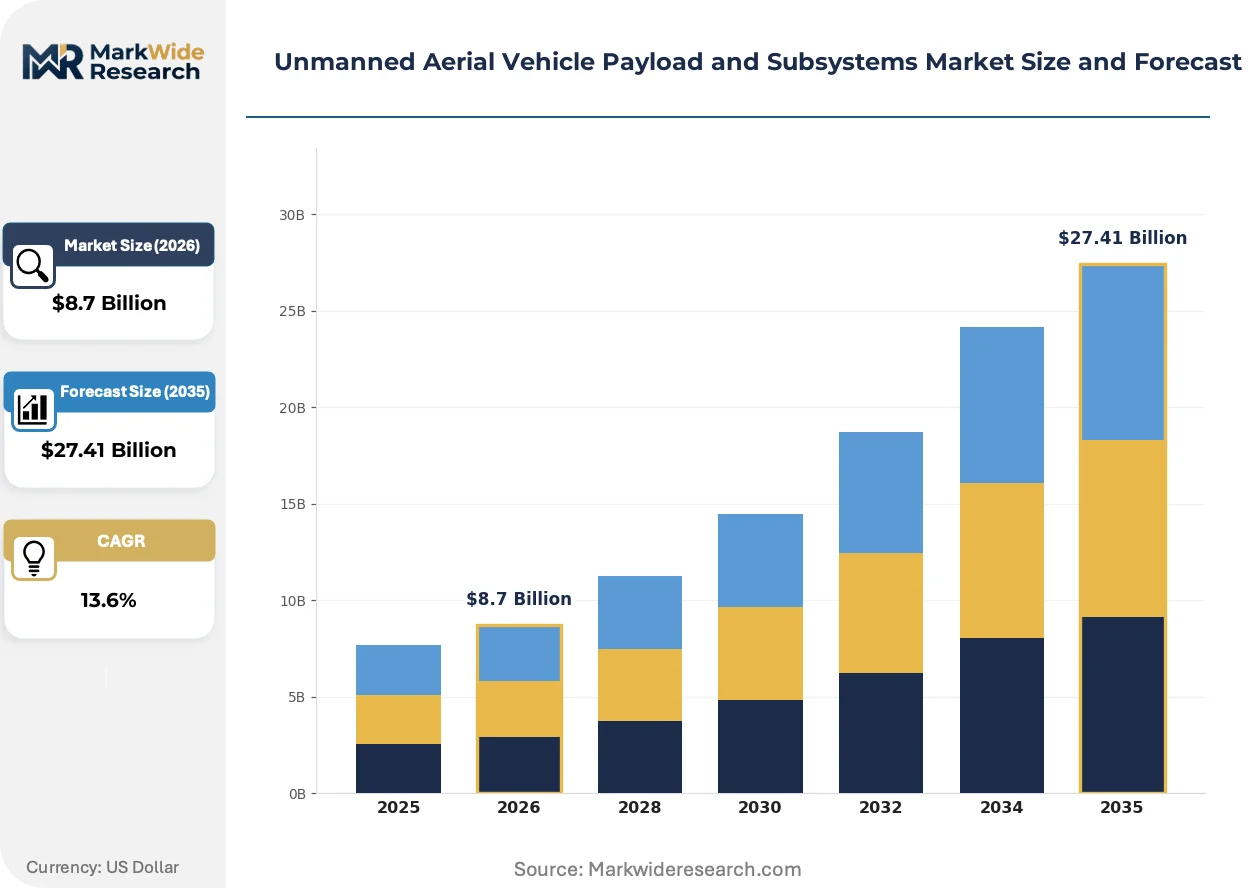
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Sensor Arrays, Communication Equipment, Control Systems Application: Agriculture, Surveillance, Mapping, Delivery End User: Defense, Civilian, Research Institutions, Commercial Enterprises Technology: Gas Engines, Electric Motors, Hybrid Systems, Autonomous Navigation |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, AeroVironment, Inc., Elbit Systems, Israel Aerospace Industries Ltd., General Atomics Aeronautical Systems, Teledyne Technologies Incorporated, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unmanned Aerial Vehicle Payload and Subsystems Market Trends and Innovations
Payload architectures are converging around software-defined radio principles and edge AI inference, displacing fixed-function hardware with reprogrammable subsystems that adapt mission parameters through firmware updates rather than physical swap.
Multi-spectral sensor fusion is hybridizing electro-optical, short-wave infrared, and laser designator capabilities into single-aperture payloads. Special operations commands in NATO member states are fielding these consolidated systems for reduced signature and simplified targeting workflows. The compression of discrete sensor volumes is enabling integration onto Group 1-2 unmanned platforms previously restricted to single-modality payloads.
EASA's proposed regulatory framework for autonomous systems and the EU AI Act's risk classification for AI-enabled targeting subsystems are imposing conformity assessment requirements on European defense exports. Manufacturers serving European operators must now document algorithmic decision transparency and human-machine interface validation. This regulatory layering is diverging certification pathways between European and US payload suppliers, fragmenting interoperability assumptions.
Defense procurement agencies are unbundling sensor hardware from embedded software maintenance, creating separate contracting vehicles for firmware sustainment and threat library updates. This disaggregation is shifting revenue recognition toward recurring service streams and privileging vendors with secure software distribution infrastructure. The United Kingdom's Defence Equipment and Support organization has pioneered this model in its Protector RG1 program, establishing precedent for allied follow-on contracts.
Unmanned Aerial Vehicle Payload and Subsystems Market Segmentation
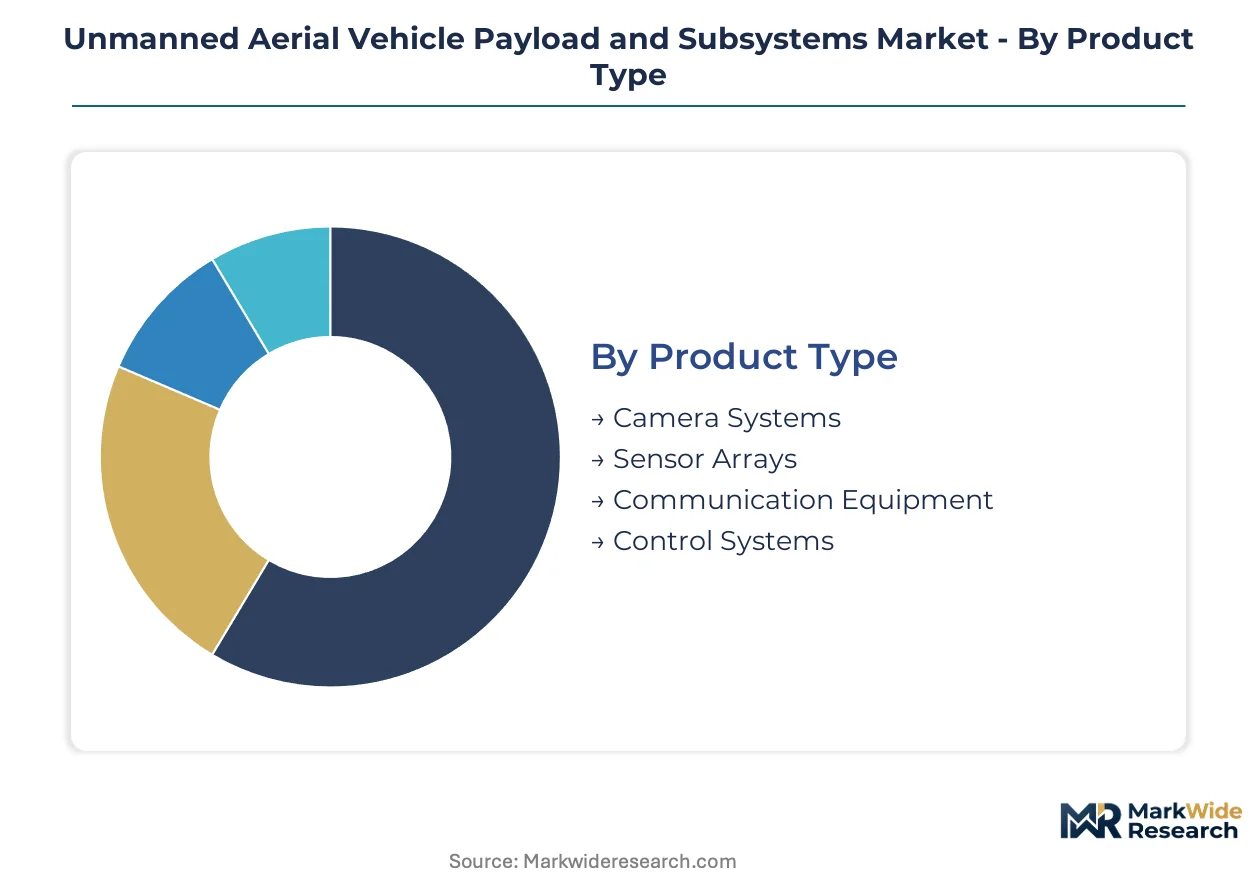
Payload replacement cycles vary dramatically across unmanned aerial vehicle subsystems, with sensor modules refreshing every 18-24 months while airframe-integrated control systems persist for 8-12 years. Understanding these divergent lifecycles enables suppliers to align inventory, R&D pipelines, and service revenue models with actual procurement rhythms rather than platform-level replacement schedules.
Product Type:
Camera Systems turn over fastest due to megapixel and low-light sensitivity advances, while Control Systems exhibit the longest replacement cycles tied to platform airworthiness certifications.
- Camera Systems:Electro-optical and infrared modules with stabilized gimbal mounting, typically delivering sub-50 microradian pointing accuracy for intelligence missions. Procurement concentrates in California and Texas defense corridors, driven by NATO ISR modernization programs requiring higher resolution at reduced SWaP-C.
- Sensor Arrays:Multi-spectral and synthetic aperture radar packages enabling all-weather penetration and foliage-penetrating imaging. Demand clusters around Virginia-based systems integrators, constrained by ITAR licensing timelines for thermal imaging cores.
- Communication Equipment:Data-link transceivers spanning L-band through Ku-band frequencies for beyond-line-of-sight connectivity.
- Control Systems:Flight computers and mission management processors governing autonomous navigation and payload tasking.
Camera Systems anchors the volume base while Sensor Arrays gains share at the steepest rate.
Application:
Cost tiers separate military-grade payloads with hardened environmental specifications from commercial alternatives prioritizing unit economics.
- Surveillance:Persistent intelligence, reconnaissance, and target acquisition missions requiring stabilized multi-spectral imaging and encrypted data-links. NATO special operations commands in Germany and the United Kingdom drive specification intensity, with EASA autonomous systems regulations adding compliance layers for European exports.
- Agriculture:Crop health monitoring and precision spraying guidance using normalized difference vegetation index sensors and multispectral cameras. Adoption concentrates in the American Midwest and Australian wheat belts, accelerated by FAA Part 107 beyond-visual-line-of-sight waivers enabling large-area coverage.
- Mapping:Photogrammetry and lidar-based terrain modeling for construction and environmental monitoring.
- Delivery:Package transport platforms requiring detect-and-avoid sensors and redundant navigation systems.
Surveillance commands the premium tier while Agriculture expands most quickly as commercial certification pathways mature.
End User:
Customer type determines procurement modality, with defense agencies favoring indefinite-delivery contracts and commercial enterprises purchasing through distributor channels.
- Defense:Military procurement agencies specifying MOSA-compliant interfaces and STANAG 4671 interoperability for allied coalition operations. The US Army's Future Vertical Lift program and United Kingdom Protector RG1 establish reference architectures, with software unbundling creating recurring revenue streams for firmware sustainment.
- Commercial Enterprises:Infrastructure inspectors, energy utilities, and logistics operators acquiring payloads through value-added resellers. Demand localizes around FAA-approved test sites in North Dakota and Nevada, constrained by electromagnetic environmental effects certification timelines.
- Civilian:Public safety and emergency response agencies with simplified procurement authority.
- Research Institutions:Academic and government laboratories advancing sensor fusion and edge AI algorithms.
Defense anchors procurement value while Commercial Enterprises climbs the fastest as beyond-line-of-sight regulatory barriers erode.
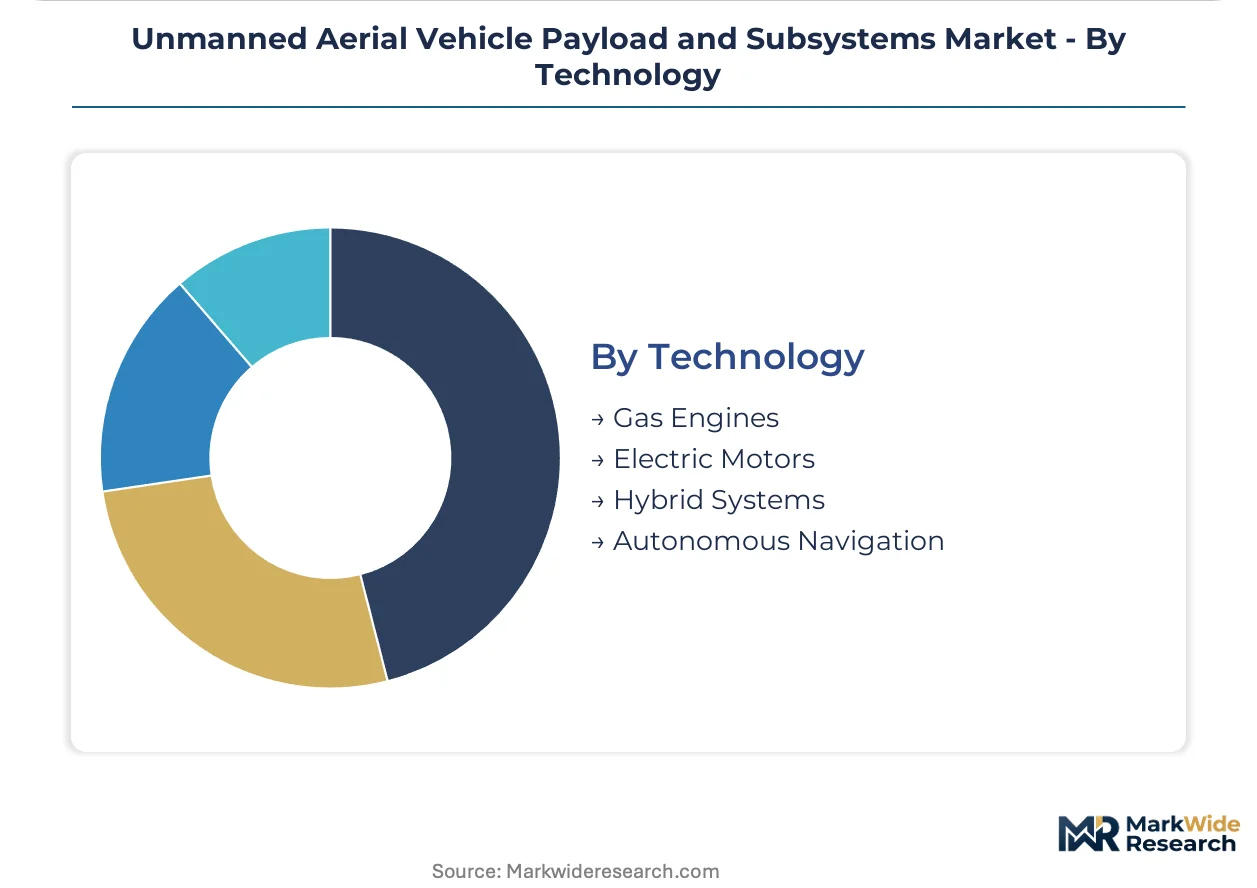
Technology:
Propulsion and autonomy architectures segment by energy density requirements and mission endurance profiles.
- Electric Motors:Brushless DC and permanent magnet synchronous motors powering Group 1-3 tactical platforms with 30-90 minute endurance. Gallium nitride power electronics reduce thermal management overhead, enabling integration into hand-launched systems previously restricted to gas propulsion.
- Autonomous Navigation:GPS-denied positioning through visual-inertial odometry and celestial navigation backups. Development concentrates in Israeli and Swiss defense electronics clusters, with EU AI Act risk classifications imposing algorithmic transparency requirements on European deployments.
- Gas Engines:Two-stroke and Wankel rotary engines for medium-altitude long-endurance missions.
- Hybrid Systems:Series-hybrid architectures combining combustion generators with electric propulsion for extended range.
Electric Motors dominates unit shipments while Autonomous Navigation shows the steepest expansion trajectory as contested environment operations become standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in the United States tolerates premium pricing for ITAR-cleared payloads, while agricultural operators in Australia and Brazil demand unit economics that compress commercial subsystem margins by 30-40 percent.
United States
The Pentagon's Replicator initiative and Army Futures Command are accelerating procurement of attritable unmanned systems with modular payloads. FAA Part 107 beyond-visual-line-of-sight waivers are expanding commercial use cases for long-range communication subsystems. Defense corridors in California, Texas, and Virginia concentrate prime contractor integration facilities and classified program offices.
Germany
The Bundeswehr's special operations commands are driving specification intensity for multi-spectral sensor fusion in reduced-signature payloads. EASA's proposed autonomous systems framework and EU AI Act risk classifications impose algorithmic transparency requirements on targeting subsystems. Munich and Stuttgart host clusters of precision gimbal mechanics suppliers serving NATO standardization agreements.
Israel
Israel Defense Forces requirements for GPS-denied navigation and electronic warfare packages sustain domestic demand for hardened subsystems. The country's national defense regulator maintains strict export controls on signals intelligence technologies. Tel Aviv and Haifa anchor development clusters for visual-inertial odometry and edge AI inference accelerators.
United Kingdom
The Protector RG1 program has pioneered software unbundling from sensor hardware, establishing precedent for recurring firmware sustainment contracts across allied procurement. Defence Equipment and Support organization mandates MOSA-compliant interfaces for future unmanned programs. Bristol and Lancashire concentrate systems integrators serving NATO STANAG 4671 interoperability requirements.
United Arab Emirates
Emerging eVTOL cargo platforms in Dubai and Abu Dhabi are creating greenfield demand for lightweight detect-and-avoid sensors and redundant navigation systems. The General Civil Aviation Authority is adapting certification pathways for autonomous cargo operations. Dubai South and Masdar City host urban air mobility testbeds requiring solid-state lidar and millimeter-wave radar integration.
Unmanned Aerial Vehicle Payload and Subsystems Market Competitive Landscape
Defense primes and specialized subsystem houses split the market into consolidated program integration tiers and fragmented component supply layers. Tier-one contractors with classified facility clearances capture multi-year indefinite-delivery contracts for ISR payloads, while mid-tier suppliers compete on gallium nitride semiconductor integration and SWaP-C optimization. Dominant competitive moves include backward integration into thermal imaging core manufacturing and strategic partnerships for rare earth magnet supply security.
Among US-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the classified program integration archetype, occupying positions where ITAR-controlled component access creates qualification barriers for non-domestic competitors. Elbit Systems represents the vertically integrated specialist model, with in-house production spanning gimbal mechanics through mission software. AeroVironment, Inc. anchors the small unmanned systems segment where modular swappable payloads dominate procurement specifications.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| AeroVironment, Inc. |
| Elbit Systems |
| Israel Aerospace Industries Ltd. |
| General Atomics Aeronautical Systems |
| Teledyne Technologies Incorporated |
| Boeing |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in gallium nitride semiconductor fabrication for miniaturized radar subsystems concentrates pricing power among cleared US manufacturers, while extended ITAR licensing timelines force non-NATO integrators to absorb 8-14 month delays or pay premiums for alternative sourcing.
Pricing Analysis
Aftermarket firmware sustainment and threat library updates now capture the dominant share of lifetime value, displacing upfront hardware margins. Three-tier pricing structure across ITAR-cleared defense, dual-use commercial, and uncertified export tiers reflects certification grade and encrypted data-link inclusion. Cost compression in commercial electro-optical modules intensifies as open-architecture standards proliferate. Agricultural operators in Australia and Brazil exhibit highest price sensitivity, while Pentagon procurement tolerates premium positioning for signals intelligence payloads with classified integration clearances.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for rare earth magnet sourcing in precision gimbal motors. Manufacturing concentrates in the United States, Israel, and Germany, with thermal imaging cores and encrypted data-links drawing from ITAR-cleared domestic production. Neodymium and dysprosium price volatility for stabilized payload motors introduces cost variance that compresses mid-tier supplier margins. Distribution runs through prime contractor integration facilities in California, Texas, and Virginia defense corridors, with firmware updates delivered via secure software distribution infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Systems engineers capable of integrating signals intelligence, electro-optical, and electronic warfare streams into unified mission software remain scarce, constraining prime contractor delivery schedules and creating asymmetric advantage for vendors with proven cross-domain data fusion expertise.
For Market Incumbents: Pre-empt open-architecture displacement by accelerating MOSA-compliant payload interface development before US Army Future Vertical Lift mandates force legacy system replacement. Capture recurring revenue streams through software unbundling from sensor hardware, following the United Kingdom Protector RG1 precedent for firmware sustainment contracting. ITAR-controlled component access remains the defensive moat against non-cleared competitors.
For New Entrants and Emerging Players: Pursue urban air mobility payload integration for eVTOL cargo platforms in the United Arab Emirates and Germany, where detect-and-avoid sensor requirements lack established supplier relationships. Target agricultural beyond-visual-line-of-sight applications in the American Midwest and Australian wheat belts as FAA Part 107 waivers erode regulatory barriers. Lead with solid-state lidar and millimeter-wave radar subsystems optimized for weight-constrained autonomous navigation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsystem houses with secure software distribution infrastructure and classified program integration clearances. Long-term viability hinges on positioning within NATO standardization agreement ecosystems rather than proprietary platform dependencies. Acquisition targets should demonstrate proven gallium nitride semiconductor integration and STANAG 4671 interoperability. The signal to watch is EASA autonomous systems framework implementation, which will fragment certification pathways and privilege vendors with EU AI Act compliance documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Unbundling from Hardware | Creates recurring firmware sustainment revenue streams following UK Protector RG1 precedent. |
| MOSA-Compliant Interface Development | Positions vendors for US Army Future Vertical Lift and NATO STANAG 4671 replacement cycles. |
| Gallium Nitride Semiconductor Integration | Reduces SWaP-C constraints for synthetic aperture radar miniaturization in tactical platforms. |
| Urban Air Mobility Sensor Partnerships | Captures greenfield eVTOL cargo demand in Dubai and Abu Dhabi testbeds. |
| EU AI Act Compliance Documentation | Enables European defense export access as algorithmic transparency requirements harden. |
Research Methodology
Initial hypotheses were tested against primary input from payload engineering directors, defense procurement officers at NATO member agencies, commercial drone fleet operators, and precision gimbal mechanics suppliers and refined through secondary validation against FAA Part 107 waiver databases, EASA regulatory filings, ITAR licensing records, SEC 10-K disclosures from tier-one contractors, and NATO standardization agreement documentation. Bottom-up unit economics for sensor module replacement cycles were triangulated against top-down defense procurement budget allocations.
Demand-supply-balance framing anchored the forecast framework, with segmentation across product type, application, end user, and technology dimensions modeled throughout the forecast period. CAGRs were derived from replacement cycle velocity differentials between 18-24 month sensor refresh rates and 8-12 year control system persistence. Industry-specific inputs included gallium nitride semiconductor fabrication capacity utilization, rare earth magnet price indices, and beyond-visual-line-of-sight regulatory waiver progression rates.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities, rare earth commodity pricing, or electromagnetic spectrum allocation disputes would shift the trajectory. Forecasts reflect documented assumptions regarding NATO procurement consolidation timelines and EASA autonomous systems framework implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
UAV Parachute Recovery Systems Market
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Drone Detection Optical Systems Market