
 Asia-Pacific Aerospace Robotics Market | 2026-2036
Asia-Pacific Aerospace Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aerospace Robotics Market Analytics
Software-defined predictive maintenance platforms are recalibrating what aerospace robotics vendors monetize beyond hardware sales. FANUC Corporation leverages its CNC-robotics integration to dominate precision machining cells for turbine blade production. Yaskawa Electric Corporation anchors its position through high-payload articulated arms purpose-built for fuselage assembly in Japanese facilities. Kawasaki Heavy Industries Ltd competes by extending its legacy in aircraft manufacturing into collaborative robot deployments for MRO service providers across the region.
Aerospace robotics encompasses programmable multi-axis manipulators, autonomous unmanned systems, and intelligent control architectures engineered to perform material handling, joining, surface treatment, and non-destructive testing operations in aircraft production and aftermarket service environments. These systems typically achieve positional repeatability within 0.02 millimeters and operate in cleanroom conditions compliant with AS9100 quality standards. Robotic arms and collaborative robots lead solution-level revenue due to entrenched deployment in drilling and fastening workflows, while autonomous drones represent the fastest-expanding category as airframe inspection protocols shift from scaffold-based manual methods to automated visual systems. Artificial intelligence and computer vision technologies are capturing disproportionate R&D investment as OEMs and tier-1 suppliers demand real-time defect recognition during composite layup and final assembly operations.
Japan's METI sets domestic automation roadmaps that directly shape procurement criteria for robotics in aerospace applications, while China's SAMR enforces GB standards for industrial robot safety and interoperability that condition market access for foreign suppliers. REACH and RoHS compliance requirements from European trade frameworks indirectly constrain material selections for robotics components exported from Asia-Pacific facilities. Stakeholders must monitor how emerging EU AI Act classifications for autonomous inspection systems will reshape certification burdens for vendors serving dual-region supply chains.
Market Dynamics
Japan's METI industrial automation roadmaps and China's dual carbon mandates are compressing factory retooling timelines across the Asia-Pacific aerospace cluster, forcing tier-1 suppliers to accelerate collaborative robot deployments for precision drilling and riveting workflows.
Growth Catalysts
- Dual carbon goals:China's binding emissions targets are compelling aerospace OEMs to replace energy-intensive manual assembly with electrified robotic cells in Yangtze River Delta facilities.
- Narrow-body aircraft demand:Commercial aviation production backlogs are driving automated assembly line expansion for single-aisle programs across Chinese and Japanese manufacturing sites.
- Composite material proliferation:Automated fiber placement and tape laying systems are capturing investment as airframe designs shift toward carbon fiber reinforced polymer structures.
Market Restraints
- High-payload robot supply concentration:Precision articulated arm production for fuselage assembly remains concentrated among Japanese and German industrial robotics specialists, creating procurement bottlenecks.
- GB standards compliance costs:China's SAMR interoperability and safety certifications impose lengthy validation cycles on foreign robotics vendors seeking market access.
- Specialized technician scarcity:Multi-axis robot programming and AI-vision system calibration require skills that outpace regional vocational training output.
Strategic Opportunities
- MRO service automation:Airframe inspection drones and collaborative robots for engine overhaul represent underpenetrated demand within Southeast Asian maintenance hubs.
- AI-vision convergence:Real-time defect recognition during composite layup is opening software-defined revenue streams beyond hardware sales for control architecture vendors.
- Australian defense aerospace:Sovereign capability initiatives are creating procurement preference for automated manufacturing systems in military airframe programs.
Industry Challenges
- AS9100 certification timelines:Quality management system validation for robotic cells in cleanroom environments extends deployment schedules by months.
- Legacy system integration:Brownfield facilities struggle to synchronize new collaborative robots with existing CNC machining cells and enterprise resource planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aerospace Robotics Market |
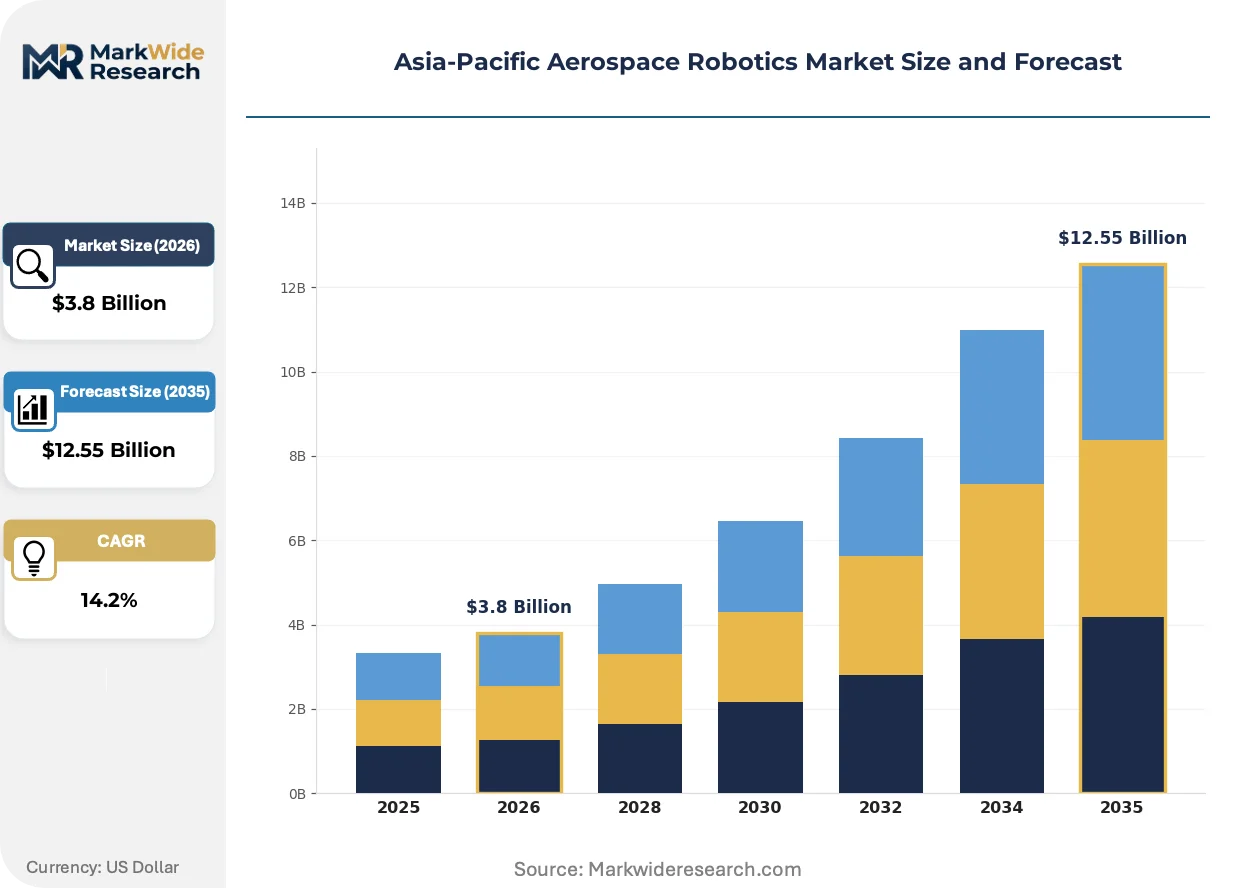
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Manufacturing, Assembly, Maintenance, Inspection Technology: Artificial Intelligence, Machine Learning, Computer Vision, Control Systems End User: OEMs, Tier-1 Suppliers, MRO Service Providers, Research Institutions Solution: Robotic Arms, Autonomous Drones, Collaborative Robots, Simulation Software |
| Companies Covered | FANUC Corporation, Yaskawa Electric Corporation, Kawasaki Heavy Industries Ltd, ABB Group, Kuka AG, Mitsubishi Electric Corporation, Nachi Fujikoshi Corporation, Seiko Epson Corporation, Omron Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aerospace Robotics Market Evolving Landscape
Software-defined architectures and computer vision integration are displacing hardware-centric business models across the Asia-Pacific aerospace robotics value chain, compressing the traditional boundaries between automation equipment and intelligent control systems.
Digital twin simulation platforms are rewriting how OEMs validate robotic trajectories before physical deployment. Commercial aviation manufacturers in China are adopting virtual commissioning tools to compress assembly line setup cycles. This capability is compressing capital deployment risk and accelerating factory retooling decisions across the region.
METI's updated industrial automation directives are mandating interoperability standards that reshape procurement specifications for Japanese aerospace facilities. Tier-1 suppliers must now demonstrate GB standard alignment for any robotic system integrated into dual-region supply chains. Foreign vendors are responding by establishing localized certification laboratories in Yokohama and Shanghai.
Aftermarket service unbundling is fragmenting traditional robotics vendor relationships across the Asia-Pacific maintenance sector. MRO providers in Singapore and Seoul are sourcing AI-inspection modules separately from hardware platforms, favoring open-architecture control systems. This pattern is most pronounced in airframe non-destructive testing applications where specialized vision algorithms command premium pricing independent of robot arm origin.
Asia-Pacific Aerospace Robotics Market Segmentation
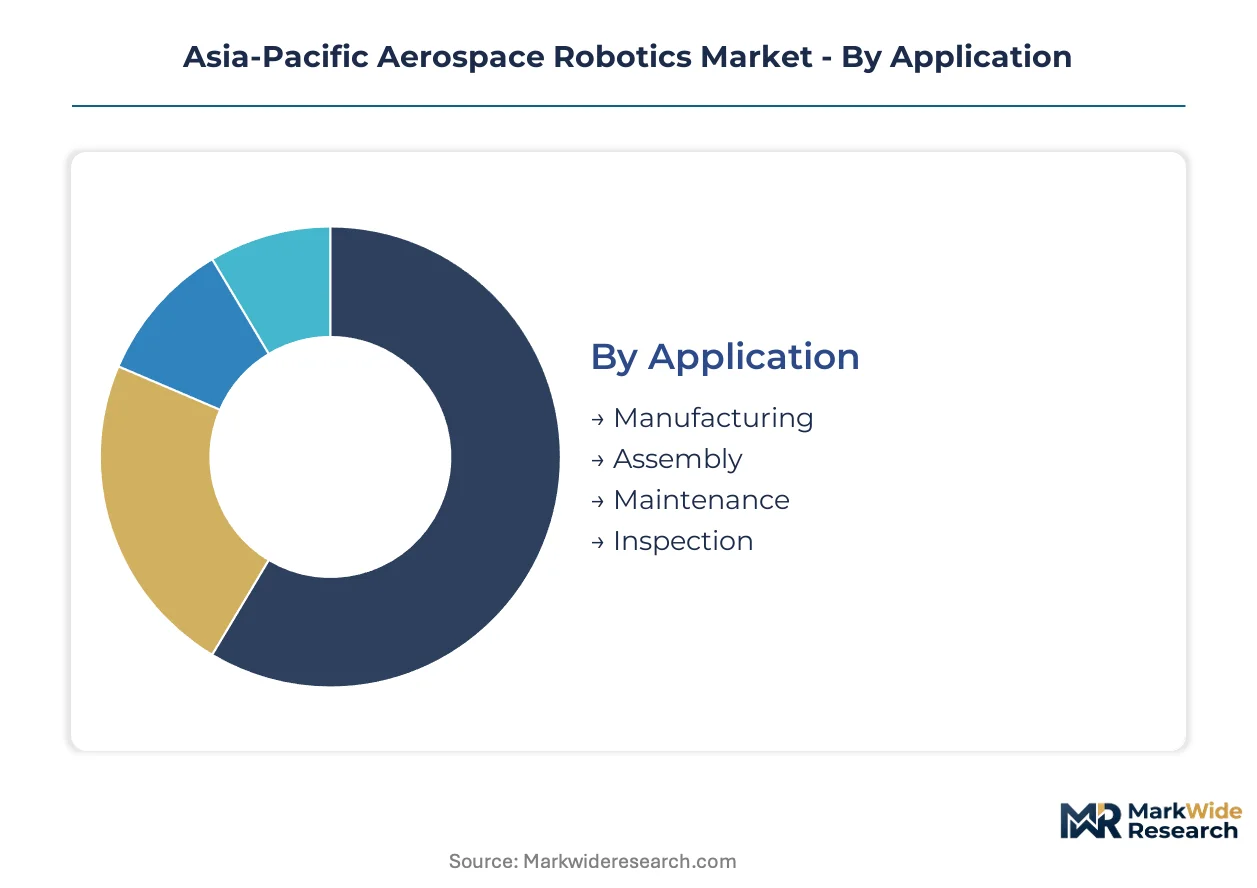
Segmentation in aerospace robotics reveals how capital deployment priorities differ across production stages and buyer types. Procurement patterns in the Asia-Pacific cluster diverge sharply between OEMs seeking full-line automation and MRO providers targeting modular inspection capabilities.
Application:
Standalone robotic cells dominate high-volume manufacturing lines, while embedded vision systems penetrate inspection workflows requiring real-time data fusion with quality management platforms.
- Manufacturing:Automated fiber placement and tape laying systems execute composite layup for wing skins and fuselage sections. Yangtze River Delta facilities deploy these systems under China's dual carbon mandates to replace energy-intensive manual processes.
- Assembly:Multi-axis manipulators perform precision drilling and riveting with positional repeatability within 0.02 millimeters. Japanese narrow-body production lines concentrate demand here as METI roadmaps compress retooling timelines.
- Maintenance:Robotic cells automate engine component overhaul and landing gear refurbishment. MRO hubs in Singapore and Seoul source these systems to address technician scarcity.
- Inspection:Autonomous drones and vision-guided manipulators execute non-destructive testing of airframe structures. This segment climbs fastest as scaffold-based manual methods phase out.
Manufacturing leads volumes today; Inspection is gaining share fastest.
Technology:
Cost tiers separate foundational control architectures from premium AI-vision stacks, with mid-range machine learning modules capturing investment from tier-1 suppliers seeking defect recognition without full autonomy.
- Artificial Intelligence:Deep learning models enable real-time anomaly detection during composite layup and final assembly operations. China's SAMR interoperability standards condition deployment architectures for foreign vendors.
- Machine Learning:Predictive algorithms optimize robotic trajectory planning and maintenance scheduling. These modules penetrate mid-tier supplier facilities seeking incremental automation without control system replacement.
- Computer Vision:High-resolution imaging systems with sub-millimeter defect resolution guide precision drilling and surface quality assessment. Australian defense aerospace programs drive specialized procurement here.
- Control Systems:PLC and CNC-robotics integration platforms coordinate multi-cell operations. Japanese facilities favor these for legacy equipment synchronization under METI standardization directives.
Control Systems anchor installed base; Artificial Intelligence shows steepest expansion trajectory.
End User:
Customer type determines integration depth, with OEMs demanding enterprise-wide orchestration while research institutions pilot emerging modalities before production transfer.
- OEMs:Commercial aviation manufacturers in China and Japan deploy full-line automation for narrow-body programs. These buyers specify AS9100-compliant cleanroom systems with enterprise resource planning integration.
- Tier-1 Suppliers:Component specialists in the Yangtze River Delta cluster adopt collaborative robots for fuselage section assembly. GB standards compliance costs extend their procurement validation cycles.
- MRO Service Providers:Maintenance operators across Southeast Asian hubs unbundle hardware from AI-inspection software. Open-architecture preferences here fragment traditional vendor relationships.
- Research Institutions:National laboratories and university consortia prototype next-generation autonomous systems. These buyers prioritize experimental flexibility over production reliability metrics.
OEMs dominate capital deployment; MRO Service Providers are expanding procurement most quickly.
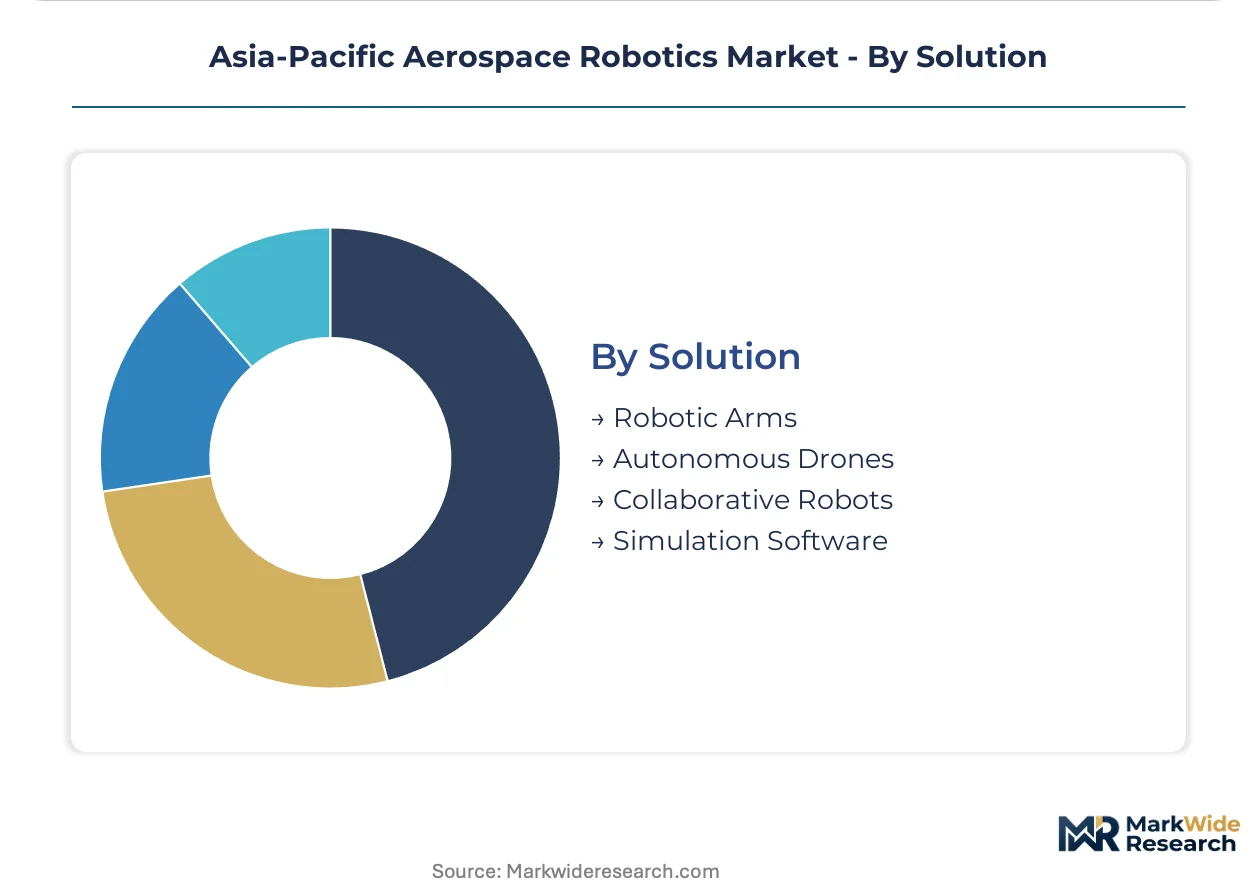
Solution:
Maturity gradients separate established robotic arm categories from emerging software-defined revenue streams, with simulation platforms capturing disproportionate R&D investment relative to current revenue scale.
- Robotic Arms:High-payload articulated systems execute material handling and joining operations in fuselage assembly. Japanese and German specialists concentrate supply, creating procurement bottlenecks for tier-1 suppliers.
- Autonomous Drones:Aerial and ground-based unmanned systems perform airframe inspection without scaffolding. These systems expand most quickly as visual inspection protocols automate across regional MRO networks.
- Collaborative Robots:Force-limited manipulators enable human-robot coexistence in precision drilling workflows. China's dual carbon goals accelerate deployment in Yangtze River Delta facilities seeking electrified cells.
- Simulation Software:Digital twin platforms validate robotic trajectories before physical commissioning. Chinese OEMs adopt these tools to compress assembly line setup cycles and reduce capital deployment risk.
Robotic Arms lead installed value; Autonomous Drones are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Asia-Pacific tracks regulatory-arbitrage opportunities, with aerospace robotics deployment accelerating where dual carbon compliance costs and METI standardization create competitive manufacturing bases. Tier-1 suppliers recalibrate facility locations based on GB certification timelines and cleanroom infrastructure availability.
China
Yangtze River Delta aerospace clusters deploy collaborative robots for precision drilling under binding dual carbon mandates from MEE. SAMR enforces GB standards for industrial robot safety that extend foreign vendor validation cycles. Shanghai and Suzhou facilities concentrate automated fiber placement systems for narrow-body composite wing production.
Japan
METI industrial automation roadmaps compress retooling timelines for fuselage assembly lines in Nagoya and Hiroshima prefectures. JIS standards harmonization with AS9100 quality protocols shapes procurement specifications for domestic OEMs. Chubu region machine builders supply high-payload articulated arms to narrow-body production facilities.
South Korea
MFDS medical-device regulatory expertise transfers to aerospace quality systems in Busan-Ulsan manufacturing zones. Seoul Capital Area research institutes prototype AI-vision inspection modules for composite defect recognition. Daegu-Gyeongbuk suppliers specialize in CNC-robotics integration for turbine blade machining cells.
Australia
Sovereign capability initiatives under TGA-aligned defense procurement frameworks favor automated manufacturing for military airframe programs. Victoria and New South Wales maintenance hubs adopt autonomous drones for airframe inspection to address technician scarcity. Australian facilities serve as testbeds for open-architecture control systems before regional deployment.
Singapore
Seletar Aerospace Park MRO providers unbundle AI-inspection software from hardware platforms, fragmenting traditional vendor relationships. The country's national aviation regulator mandates interoperability standards that condition robotics procurement. Southeast Asian maintenance hubs concentrate collaborative robot deployments for engine overhaul operations.
Asia-Pacific Aerospace Robotics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated automation houses capturing OEM relationships and modular software vendors penetrating MRO unbundling trends. Market structure concentrates around Japanese and German industrial robotics heritage, creating procurement bottlenecks for high-payload articulated systems. Three archetypes dominate: full-line automation integrators, AI-vision software specialists, and collaborative robot pure-plays. Competitive moves center on localized certification laboratory establishment and open-architecture control system development.
Among Japanese industrial robotics houses, FANUC Corporation, Yaskawa Electric Corporation, and Kawasaki Heavy Industries Ltd occupy positions reflecting decades of CNC-robotics integration heritage. These Tokyo and Osaka-based entities exemplify the full-line automation archetype, with their corporate structures embedding aircraft manufacturing lineage into contemporary collaborative robot offerings. Their market presence anchors premium-tier positioning for precision machining and fuselage assembly applications across regional aerospace clusters.
| Leading Market Players |
|---|
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries Ltd |
| ABB Group |
| Kuka AG |
| Mitsubishi Electric Corporation |
| Nachi Fujikoshi Corporation |
| Seiko Epson Corporation |
| Omron Corporation |
| Others |
Value Network & Pricing Analysis
Steel price volatility on the Shanghai Futures Exchange cascades through precision gearbox and servo motor costs, compressing margins for mid-tier articulated arm suppliers while Japanese specialists with captive component production maintain pricing power in fuselage assembly applications.
Pricing Analysis
Distributor margins absorb 12-18 points in collaborative robot sales to tier-1 suppliers, while direct-to-OEM contracts for high-payload systems command project-based pricing with AS9100 certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates FANUC-level precision machining cells from Chinese collaborative robot alternatives. Cost compression in mid-range control systems is intensifying because SAMR interoperability validation extends foreign vendor cost structures. Tier-1 suppliers in the Yangtze River Delta exhibit highest price sensitivity; Japanese OEMs prioritize performance metrics over unit economics.
Supply Chain Analysis
Ocean freight rates from Yokohama to Singapore condition landed costs for precision harmonic drives and linear encoders. Supply concentrates in Japan for high-torque servo motors, Germany for precision reducers, and Taiwan for machine vision sensors. Raw material dependencies span rare-earth magnets for motor assemblies, high-grade aluminum castings for arm structures, and specialized optical glass for vision systems. Single-source vulnerability runs through Japanese precision gearbox specialists. Distribution runs through authorized integrators for OEM accounts and direct digital channels for MRO unbundled software procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific aerospace robotics market functions as a geographic-arbitrage play where METI-standardized Japanese facilities absorb 15-20% cost premiums over Yangtze River Delta operations, yet SAMR certification timelines erode Chinese cost advantages for foreign vendors.
For Market Incumbents: Deepen backward integration into precision reducer manufacturing to offset German supply concentration. Lock in long-term rare-earth magnet offtake agreements with Australian miners. The threat of open-architecture MRO software unbundling demands defensive certification laboratory expansion in Shanghai and Seoul. For New Entrants and Emerging Players: The 40-50% price-point gap between premium Japanese articulated arms and economy Chinese collaborative robots creates entry space for mid-tier AI-vision specialists. MRO service automation in Southeast Asian hubs represents the most penetrable white-space. A software-first go-to-market angle bypasses hardware supply bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with Australian defense aerospace automation specialists positioned for TGA-aligned sovereign capability procurement. The 5-10 year viability window favors control architecture vendors with open-protocol stacks. Watch for GB standard harmonization with AS9100 as inflection signal for foreign vendor market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Certification Laboratory Establishment | Shanghai and Yokohama facilities compress SAMR and METI validation cycles for foreign vendors. |
| Open-Architecture Control System Development | MRO unbundling trends favor vendors separating AI-vision software from hardware platforms. |
| Rare-Earth Magnet Supply Agreement | Australian mining partnerships secure motor assembly inputs against Chinese export restrictions. |
| Digital Twin Platform Integration | Virtual commissioning tools reduce capital deployment risk for Yangtze River Delta OEMs. |
| Collaborative Robot Payload Expansion | Force-limited systems penetrate fuselage drilling workflows under China's dual carbon mandates. |
Research Methodology
Bottom-up OEM and tier-1 supplier modeling reconciled against top-down robotics shipment tracking forms the analytical core of this study. Primary interviews with plant engineers at Yangtze River Delta facilities, procurement leads at Japanese narrow-body manufacturers, MRO operations heads in Singapore and Seoul, and control system integration specialists informed demand-side calibration. Secondary validation drew from SAMR GB standard filings, METI industrial automation roadmap publications, JIS certification registries, and customs trade data for precision gearbox and servo motor imports.
Input-output matrices mapped robotic arm, collaborative robot, and autonomous drone deployment against narrow-body production backlogs, composite airframe penetration rates, and MRO technician scarcity indices across the projection horizon. Segmentation dimensions spanned application stage, technology tier, end-user archetype, and solution type. CAGRs derived from installation run-rate trajectories, replacement cycle analysis, and software attach-rate assumptions. Forecast inputs incorporated dual carbon compliance cost curves and METI standardization timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-vision inspection autonomy would alter the outlook if regulatory frameworks accelerate or retard unmanned system certification. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
Rotary-Wing Lidar Drone Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Drone Parachute System Market