
 Commercial Drone Market | 2026-2036
Commercial Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Drone Market Analysis
Chinese battery and airframe supply is hardening as the dominant cost determinant for commercial drone manufacturers worldwide. SZ DJI Technology Co. Ltd leverages its Shenzhen manufacturing base to sustain component cost advantages across the consumer-to-professional transition. Skydio, Inc. anchors American autonomous flight software development, while AeroVironment Inc. dominates defense-adjacent fixed-wing platforms for government end users.
A commercial drone is an unmanned aerial vehicle with a maximum takeoff weight typically between 250 grams and 25 kilograms, powered by lithium-polymer battery packs or combustion engines, designed for payload delivery, remote sensing, or autonomous data collection in commercial environments. Rotary-wing configurations lead current unit shipments due to vertical takeoff flexibility in confined construction and media sites, while fixed-wing platforms capture extended-range agricultural monitoring missions where endurance exceeds maneuverability requirements. Autonomous technology represents the fastest-expanding capability layer as BVLOS regulatory frameworks mature across operational jurisdictions.
FAA Part 107 and EASA drone regulations establish pilot certification and operational altitude boundaries that directly gate market access for service providers and hardware vendors. The EU AI Act and emerging ISO standards for autonomous systems are layering additional compliance burdens onto software-intensive platforms. Stakeholders must monitor regulatory divergence between American risk-based categorization and European precautionary frameworks when configuring product roadmaps and geographic deployment priorities.
Market Dynamics
Chinese battery and airframe supply concentration is hardening as the dominant cost determinant for commercial drone manufacturers worldwide, compressing margin structures for non-integrated assemblers and forcing geographic sourcing recalibration.
Growth Catalysts
- BVLOS regulatory maturation:FAA Part 107 waivers and EASA drone framework expansions are unlocking logistics and infrastructure inspection missions previously restricted to visual line-of-sight operations.
- Precision agriculture:Large-scale farming operations across the United States and Brazil are deploying rotary-wing platforms for variable-rate input application and multispectral crop monitoring.
- Autonomous flight software:Machine vision and edge-computing advances are reducing pilot dependency for repeatable data collection workflows in construction and energy sectors.
Market Restraints
- Lithium-polymer supply concentration:Cathode and cell production clusters in China's Guangdong and Fujian provinces create input cost volatility exposure for non-captive assemblers.
- Airframe import tariffs:Trade policy friction between the United States and China elevates landed costs for carbon-fiber composite structures and gimbal assemblies.
- Payload endurance limitations:Energy density constraints in current battery chemistry cap flight times below thresholds required for long-range maritime patrol and inter-facility logistics.
Strategic Opportunities
- Indian agricultural mechanization:Subsidy frameworks under the country's PLI scheme and state-level drone procurement programs are opening fleet deployment opportunities for crop-spraying services.
- EU AI Act compliance services:Autonomous system certification requirements are creating a secondary market for software audit, documentation, and risk-assessment tooling.
- Beyond-visual-line-of-sight infrastructure:Ground-based radar and cellular detect-and-avoid networks in Germany and France are enabling corridor-based delivery pilot programs.
Industry Challenges
- Remote pilot certification throughput:FAA Part 107 testing center capacity and EASA theoretical examination backlogs are constraining operator pool expansion for seasonal agricultural demand spikes.
- Legacy system integration:Enterprise asset management platforms in energy and utilities sectors require custom API development to ingest drone-derived inspection data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Drone Market |
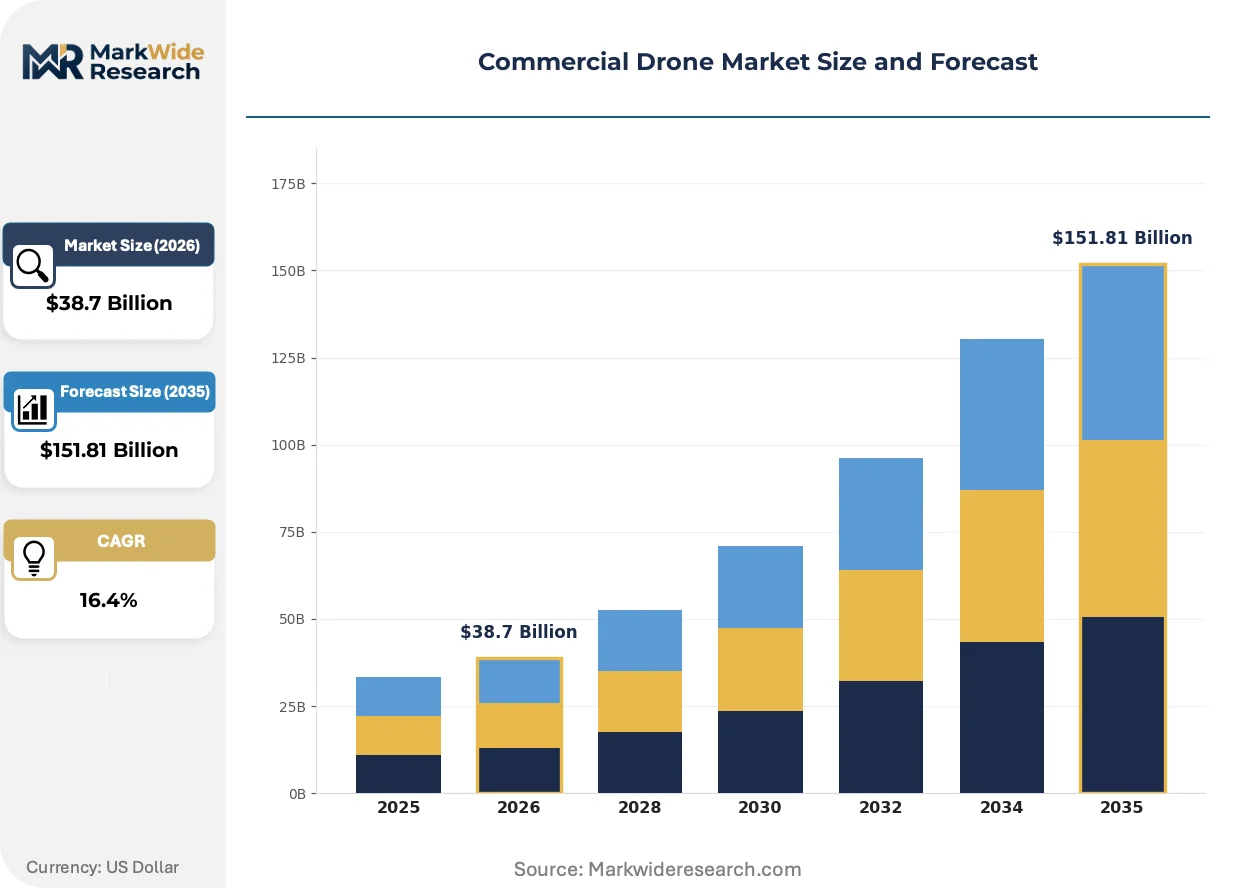
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agricultural Monitoring, Surveillance, Delivery Services, Infrastructure Inspection Technology: Fixed-Wing, Rotary-Wing, Hybrid, Autonomous End User: Logistics, Agriculture, Construction, Media Regulatory Compliance: BVLOS, Visual Line of Sight, Part 107, Drone Regulations |
| Companies Covered | SZ DJI Technology Co. Ltd, Skydio, Inc., AeroVironment Inc., Yuneec Holding Ltd, Autel Robotics, Parrot Group, Intel Corporation, Teal Drones, PrecisionHawk, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Drone Market Emerging Trajectories
Autonomous capability layers are compressing operator-to-aircraft ratios and reshaping procurement economics across commercial end-uses, while regulatory sandboxes accelerate operational envelope expansion.
Hybrid hydrogen-electric propulsion is overtaking pure battery architectures for extended-range agricultural and maritime patrol missions. Forestry operators in Scandinavia and plantation managers in Southeast Asia are piloting fuel-cell retrofits that triple endurance without payload sacrifice. This technology is overtaking conventional lithium-polymer dominance in applications where downtime costs exceed capital premium.
EASA's risk-based drone category system and the EU AI Act's conformity assessment requirements are layering software documentation burdens onto autonomous platform vendors. Hardware manufacturers must now maintain algorithmic audit trails and human-override protocols to maintain CE marking eligibility. European logistics operators are responding by consolidating procurement around vertically integrated suppliers with captive compliance teams.
Drone-as-a-service contracting is displacing capital purchase models for intermittent-use sectors. Mining and construction firms in Australia and Canada are unbundling aircraft ownership from data deliverables, preferring per-acre or per-inspection pricing with guaranteed uptime SLAs. This shift concentrates fleet utilization with specialized operators while pushing hardware vendors toward lease financing and residual value guarantees.
Commercial Drone Market Segmentation
Commercial drone procurement patterns diverge sharply across operational environments, with payload requirements and flight endurance dictating hardware selection. Understanding how application demands map to technology configurations and compliance frameworks exposes margin concentration points for vendors and service providers.
Technology:
Airframe architecture determines energy efficiency, payload capacity, and regulatory classification thresholds across deployment scenarios.
- Fixed-Wing:These platforms employ rigid airfoil designs optimized for extended-duration missions requiring linear flight paths. Large-scale soybean and corn operations in Brazil and the United States deploy fixed-wing units for multispectral crop mapping where endurance exceeds 90 minutes.
- Rotary-Wing:Multirotor configurations dominate unit shipments through vertical takeoff capability in confined construction sites and urban media production. Battery chemistry constraints limit flight times to 25-40 minutes, constraining use to inspection and short-range logistics.
- Hybrid:Tilt-rotor and VTOL-fixed-wing combinations merge maneuverability with range extension. Oil pipeline operators in Alberta and offshore wind technicians in the North Sea pilot hybrid platforms for corridor-based asset monitoring.
- Autonomous:Machine vision and edge-computing stacks enable reduced-pilot operations through waypoint programming and dynamic obstacle avoidance. EASA's risk-based categorization and FAA Part 107 waivers are accelerating certification for logistics corridors in Germany and Texas.
Mature deployment sits with Rotary-Wing. Newer deployment is concentrated in Autonomous.
Application:
Use-case economics separate capital-intensive fleet operators from intermittent service purchasers.
- Agricultural Monitoring:Variable-rate input application and NDVI crop health indexing drive rotary-wing adoption across Brazilian cerrado and US Midwest operations. FAA Part 107 remote pilot requirements create seasonal certification bottlenecks during planting and harvest windows.
- Surveillance:Border patrol and critical infrastructure protection missions favor fixed-wing endurance and thermal payload integration. Government procurement in the United States and Saudi Arabia concentrates volume with defense-adjacent vendors.
- Delivery Services:Last-mile logistics operators in Germany and France are expanding BVLOS pilot programs through ground-based radar detect-and-avoid networks. Payload weight restrictions and urban airspace congestion constrain route density.
- Infrastructure Inspection:Energy utilities and telecommunications firms deploy drones for transmission line and tower assessment. Australian mining companies and Canadian pipeline operators are shifting from ownership to per-inspection service contracts.
Revenue concentration clusters in Agricultural Monitoring. Steepest expansion trajectory appears in Delivery Services.
End User:
Customer procurement maturity shapes pricing power and contract structure preferences.
- Logistics:E-commerce fulfillment networks and medical supply distributors are piloting BVLOS corridor networks. German and French regulators are approving operational certificates faster than FAA processing timelines.
- Agriculture:Co-operative spraying services and plantation managers in India and Brazil represent volume demand. India's PLI subsidy scheme and state-level procurement programs are accelerating fleet deployment.
- Construction:Project managers use drones for earthwork volumetrics and progress documentation. Australian and Canadian mining and construction firms prefer drone-as-a-service contracts over capital purchase.
- Media:Film production and real estate marketing drive consumer-to-professional hardware transitions. Content creators prioritize gimbal stability and 4K transmission over flight endurance.
Established demand sits with Agriculture. Emerging demand concentrates in Logistics.
Regulatory Compliance:
Operational certification tiers gate market access and determine viable business models.
- BVLOS:Beyond-visual-line-of-sight authorization unlocks long-range logistics and maritime patrol missions. EASA framework expansions in Germany and France are outpacing FAA waiver processing capacity.
- Visual Line of Sight:Traditional pilot-aircraft visual contact requirements dominate current commercial operations. Construction and media sectors operate primarily within this constrained envelope.
- Part 107:FAA's remote pilot certification establishes baseline operational authority for commercial activity in the United States. Testing center capacity constraints create operator supply bottlenecks during seasonal demand spikes.
- Drone Regulations:National aviation authority frameworks outside the US-EU axis vary in pilot qualification and airspace integration requirements. India's DGFT and civil aviation notifications are harmonizing import and operational standards.
Current volume clusters in Visual Line of Sight. Regulatory momentum is building fastest around BVLOS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-polymer cell production clusters in China's Guangdong and Fujian provinces anchor global commercial drone supply chains, with Shenzhen manufacturing bases feeding component networks across export markets.
United States
Logistics operators in Texas and California are expanding BVLOS pilot programs for last-mile delivery corridors. FAA Part 107 waiver processing creates operational bottlenecks that EASA timelines in Europe currently outpace. The Dallas-Fort Worth metroplex hosts detect-and-avoid radar infrastructure enabling commercial corridor flights.
Germany
E-commerce fulfillment networks in the Rhine-Ruhr region are deploying autonomous platforms for inter-facility logistics. EASA's risk-based drone category system accelerates operational certificate approvals faster than FAA counterparts. Berlin-Brandenburg hosts ground-based radar networks enabling BVLOS delivery pilots through urban airspace.
China
Shenzhen manufacturing clusters dominate battery pack and carbon-fiber airframe assembly for global export markets. MIIT drone regulations and dual carbon goals shape domestic operational parameters and production standards. The Pearl River Delta concentration compresses component costs for integrated manufacturers serving professional segments.
Brazil
Soybean and corn operations in Mato Grosso and Goiás are deploying fixed-wing platforms for multispectral crop mapping across the cerrado belt. ANVISA and civil aviation frameworks govern agricultural spraying certification and operational altitudes. São Paulo state hosts service provider consolidation for plantation-scale fleet management.
India
Co-operative spraying services in Maharashtra and Gujarat are scaling rotary-wing deployments for cotton and sugarcane operations. The PLI scheme and state-level drone procurement programs subsidize fleet acquisition for agricultural mechanization. Karnataka's Bangalore-Tumkur corridor concentrates software development for autonomous flight stacks targeting domestic requirements.
Commercial Drone Market Vendor Landscape
Global majors compete with regional champions across supply chain integration and software autonomy dimensions. Market structure tilts toward consolidated hardware assembly with fragmented service provision layers. Three archetypes dominate: vertically integrated Chinese manufacturers with captive component supply, American autonomous software specialists, and defense-adjacent fixed-wing platform vendors. Competitive moves center on backward integration into battery cell production and strategic partnerships for BVLOS regulatory certification.
Among the integrated manufacturing tier, SZ DJI Technology Co. Ltd anchors Shenzhen-based production networks spanning consumer-to-professional transitions. Skydio, Inc. occupies a position exemplifying American autonomous flight software development, while AeroVironment Inc. represents defense-adjacent fixed-wing specialization for government procurement channels.
| Leading Market Players |
|---|
| SZ DJI Technology Co. Ltd |
| Skydio, Inc. |
| AeroVironment Inc. |
| Yuneec Holding Ltd |
| Autel Robotics |
| Parrot Group |
| Intel Corporation |
| Teal Drones |
| PrecisionHawk, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between BVLOS-autonomous platforms and VLOS-limited hardware manifests in both procurement premiums and component sourcing footprints. Premium-tier vendors bundle FAA Part 107 compliance documentation and EASA risk-category certification with airframe sales, while commodity-tier assemblers unbundle these services and source carbon-fiber structures from Shenzhen trading houses without captive battery cell production.
Pricing Analysis
Warranty and service-bundling arrangements separate integrated manufacturers from modular assemblers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects BVLOS certification status, battery energy density ratings, and after-sales support commitments. Pricing pressure stems from lithium-polymer cell cost volatility in China's Guangdong province. Agricultural co-operatives in Brazil and India exhibit highest price sensitivity, while defense-adjacent government procurement in the United States shows lowest elasticity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and emerging Buy American provisions for federal drone procurement are reshaping sourcing patterns for non-Chinese vendors. Manufacturing gravity centers on China, South Korea, and Taiwan for lithium-polymer cells, carbon-fiber composites, and machine vision chipsets. Cathode chemistry and gimbal servo motors represent critical input dependencies. Single-source vulnerability concentrates in Shenzhen battery pack assembly. Distribution runs through specialized industrial distributors and direct OEM relationships rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where remote pilot certification throughput caps service provider expansion and props pricing for qualified operators. The bottleneck in FAA Part 107 testing center capacity prevents rapid fleet scaling regardless of hardware availability.
For Market Incumbents: Deploy captive compliance teams to accelerate EASA risk-category documentation and FAA waiver processing. SZ DJI Technology Co. Ltd and Skydio, Inc. should deepen backward integration into lithium-polymer cell production to offset Guangdong supply volatility. Defensive positioning requires locking long-term service contracts with Australian mining and Canadian pipeline operators before drone-as-a-service consolidators capture recurring revenue streams.
For New Entrants and Emerging Players: Agricultural spraying co-operatives in Maharashtra and Gujarat represent the most penetrable white-space target given India's PLI subsidy tailwinds and state-level procurement programs. Hybrid hydrogen-electric retrofit services for Scandinavian forestry operators offer second-mover entry with lower capital intensity than full platform manufacturing. Channel partnerships with established detect-and-avoid radar infrastructure providers in Germany and France accelerate BVLOS operational certificate access without direct regulatory lobbying costs.
For Investors and Strategic Acquirers: Re-rating potential sits with autonomous software specialists given EASA AI Act compliance requirements and FAA Part 107 waiver automation tools. Long-term viability favors vendors with integrated hardware-software stacks and captive certification capabilities rather than pure-play airframe assemblers. The signal to watch is EASA operational certificate approval velocity relative to FAA processing timelines as a proxy for European logistics operator procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-polymer supply secures margin stability against Guangdong price volatility. |
| BVLOS Regulatory Certification Investment | FAA Part 107 waiver automation and EASA risk-category documentation unlock logistics corridor access. |
| Drone-as-a-Service Platform Launch | Per-inspection contracting captures Australian mining and Canadian construction demand shifting from ownership. |
| Hybrid Propulsion Technology Licensing | Fuel-cell retrofit partnerships penetrate Scandinavian forestry and Southeast Asian plantation markets. |
| Ground-Based Detect-and-Avoid Infrastructure Partnership | Radar network integration enables German and French urban airspace delivery pilot programs. |
Methodological Framework
SEC filings, EASA regulatory databases, and FAA Part 107 waiver records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with fleet operations managers at agricultural co-operatives, remote pilot certification instructors, BVLOS program leads at logistics operators, and procurement directors at energy utilities validated demand assumptions. Customs data from China's General Administration and India's DGFT anchored supply-side triangulation against bottom-up airframe shipment estimates.
Historical trendline analysis of rotary-wing and fixed-wing deployment patterns informed the projection framework across the analysis window. Segmentation modeling incorporated airframe architecture, application use-case, end-user procurement maturity, and regulatory compliance tier dimensions. CAGRs derived from unit economics trajectories in precision agriculture and delivery services, cross-referenced with battery chemistry cost curves and pilot certification throughput constraints.
Caveats apply where FAA testing center capacity expansion, EASA AI Act enforcement timing, or lithium-polymer supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about regulatory sandbox progression and subsidy program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Miniature Drone Market
UAV
Anti-Drone Technology Market
UAV
UAV Simulator Software Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Europe Commercial Drones Market
UAV
Electric Glider Market
UAV
Fuel Cell UAV Market
UAV
Europe Drone Services Market
UAV
Portable Drone Market
UAV
Ultra Micro Drone Market
UAV
Utility Drone Market
UAV
Global VTOL UAV Market
UAV
Drone Lens Market
UAV
Multirotor Drones Market
UAV
Delivery Drones Market
UAV
Asia-Pacific Tethered Drone Market