
 Aircraft Brake Calipers Market | 2026-2036
Aircraft Brake Calipers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Brake Calipers Market Analysis
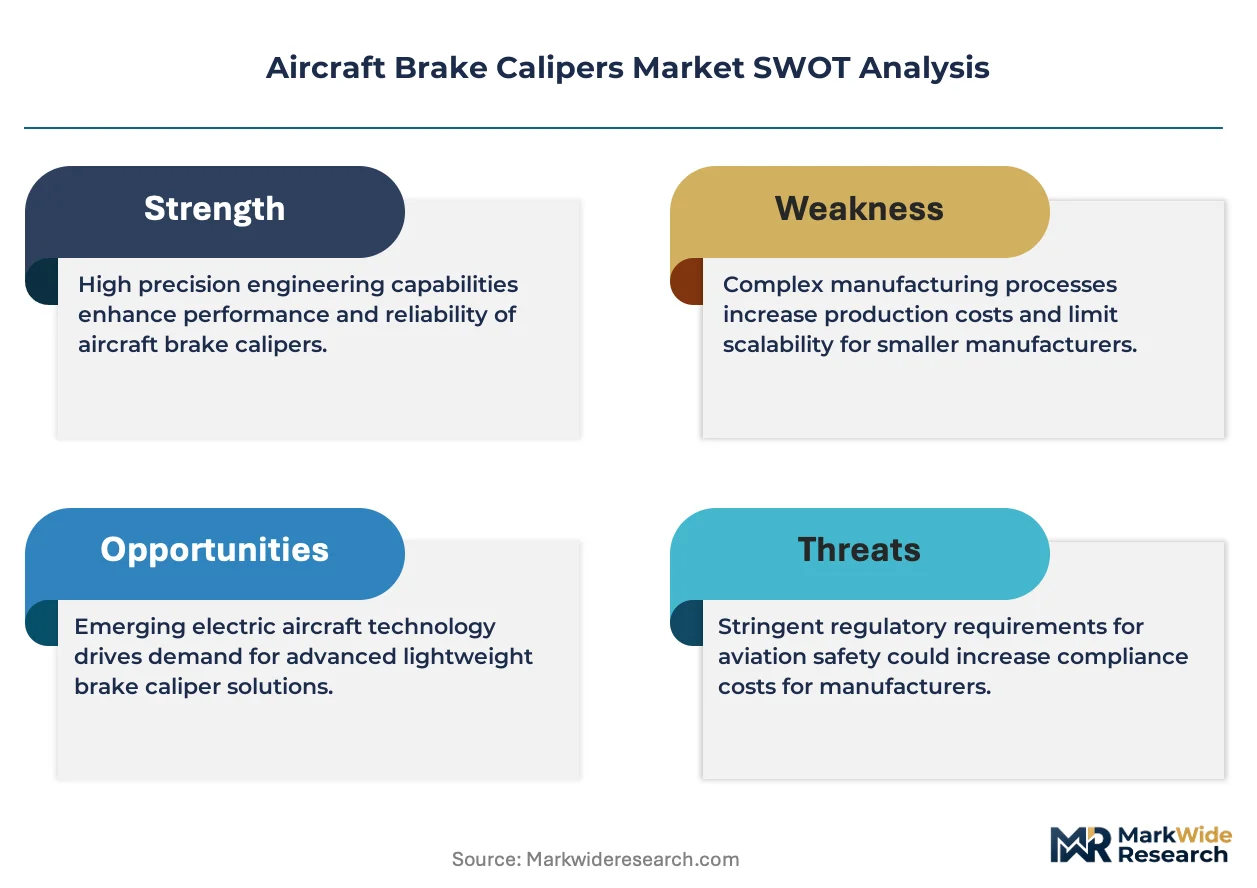
FAA Part 25 airworthiness standards is rebalancing the cost-of-entry calculus for new caliper suppliers by mandating extended thermal fatigue testing. Honeywell International Inc. leverages its integrated wheel and brake architecture to sustain aftermarket revenue streams. Safran anchors European supply chains through its landing systems division near Toulouse. Parker Hannifin Corporation competes on hydraulic-actuated caliper designs for regional jet platforms.
Aircraft brake calipers are hydraulically or electro-mechanically actuated clamping devices that apply friction to brake discs to decelerate landing gear rotation, typically manufactured from aluminum alloy or carbon-carbon composites to withstand temperatures exceeding 1,000°C during rejected takeoff events. Their primary purpose is converting kinetic energy into controlled thermal dissipation while maintaining structural integrity across repeated landing cycles. Electro-mechanical calipers represent the fastest-growing product category as airframers phase out hydraulic systems for more electric aircraft architectures. Carbon-carbon calipers command premium positioning in wide-body applications where weight reduction and thermal capacity justify material costs. Commercial aviation end users generate the largest volume pool, though military aviation sustains higher per-unit margins through specialized anti-skid integration requirements.
FAA, EASA, and CAAC collectively govern brake caliper certification through harmonized thermal capacity and fatigue life standards that determine market access eligibility. The EU Green Deal and ICAO carbon reduction frameworks indirectly shape demand by pressuring airframers toward lighter brake assemblies and longer replacement intervals. Stakeholders must monitor the pace of electro-mechanical standardization and position supply chains for dual-certification complexity across FAA-EASA jurisdictions.
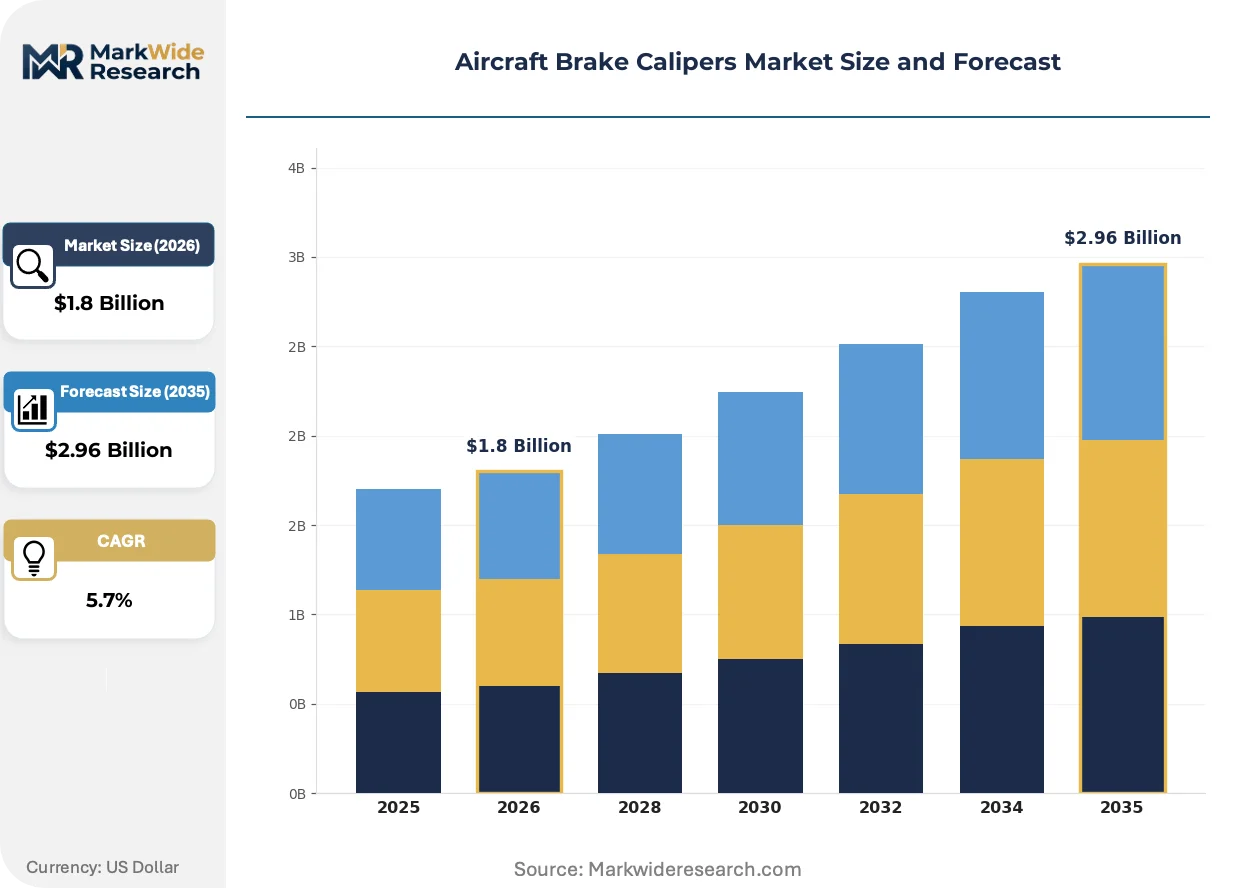
Market Dynamics
Electro-mechanical actuation architectures are compressing hydraulic caliper replacement cycles across commercial aviation, while EASA thermal fatigue mandates force material specification upgrades that favor carbon-carbon composite suppliers with existing certification portfolios.
Growth Catalysts
- EU Green Deal decarbonization pressure:Airframers face binding carbon reduction targets that accelerate lightweight brake assembly adoption, directly expanding carbon-carbon caliper demand for wide-body platforms.
- Military aviation procurement expansion:Defense budgets across NATO member states are extending fleet modernization programs, sustaining higher-margin replacement cycles for anti-skid integrated caliper systems.
- Electro-mechanical standardization:More electric aircraft architectures from Boeing and Airbus are phasing out hydraulic lines, creating pull-through demand for electrically actuated caliper designs with embedded sensors.
Market Restraints
- Carbon-carbon raw material concentration:Specialized carbon fiber precursor supply concentrates among Japanese and US chemical conglomerates, exposing caliper manufacturers to input cost volatility and allocation risk.
- FAA-EASA dual certification friction:Divergent thermal testing protocols between US and European regulators extend approval timelines for new caliper entrants, raising cost-of-entry barriers.
- Hydraulic system legacy lock-in:Regional jet and cargo aircraft fleets retain hydraulic brake architectures, limiting near-term addressable market for electro-mechanical substitutes.
Strategic Opportunities
- India defense aviation modernization:Indigenous fighter programs under the country's defense procurement corridors create demand for localized caliper production with technology transfer requirements.
- Aftermarket predictive maintenance integration:IoT-enabled brake wear sensors bundled with electro-mechanical calipers enable condition-based replacement contracts, shifting revenue toward recurring service streams.
- REACH-compliant material substitution:European chemical regulations are phasing legacy friction materials, opening positioning for ceramic-matrix composite caliper alternatives with superior thermal profiles.
Industry Challenges
- Thermal fatigue testing capacity scarcity:Extended FAA Part 25 certification cycles require specialized dynamometer facilities that face 18-month booking backlogs, compressing product launch windows.
- Electro-hydraulic hybrid integration complexity:Transitional aircraft architectures demand calipers compatible with both legacy hydraulic and emerging electric actuation, doubling validation engineering requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Brake Calipers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Calipers, Floating Calipers, Electro-Mechanical Calipers, Carbon-Carbon Calipers End User: Commercial Aviation, Military Aviation, General Aviation, Cargo Operations Material: Aluminum Alloy, Stainless Steel, Composite Materials, Cast Iron Installation Type: Retrofitting, OEM Installation, Aftermarket Replacement, Modular Systems |
| Companies Covered | Honeywell International Inc., Moog Inc., Safran, Sumitomo Precision Products Co. Ltd., Liebherr-International AG, Parker Hannifin Corporation, Collins Aerospace, NASCO Aircraft Brake Inc., Meggitt PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Brake Calipers Market Emerging Trajectories
Brake caliper engineering is pivoting toward electromechanical architectures that eliminate hydraulic fluid lines entirely, while regulatory thermal standards tighten and aftermarket service models unbundle from hardware sales.
Electro-mechanical brake actuation is electrifying commercial aviation hydraulic replacement cycles. Boeing's 787 and Airbus A350 programs have validated electrically actuated calipers for main landing gear applications. Regional jet OEMs are now mandating electric architectures for clean-sheet designs, compressing the addressable market for hydraulic-actuated suppliers.
REACH chemical restrictions and EU Green Deal carbon accounting rules are reshaping material qualification pathways. EASA mandates now require documented lifecycle thermal performance for all new brake caliper submissions. German and French suppliers are accelerating ceramic-matrix composite development to preempt regulatory exclusion of legacy friction materials.
Airline procurement departments are unbundling brake caliper hardware from maintenance contracts, forcing suppliers to compete on unit cost while separately pricing predictive wear monitoring. Low-cost carriers in Southeast Asia pioneered this split-tender approach. Legacy network carriers in Germany and the United States are now adopting similar procurement structures for narrow-body fleet renewals.
Aircraft Brake Calipers Market Segmentation
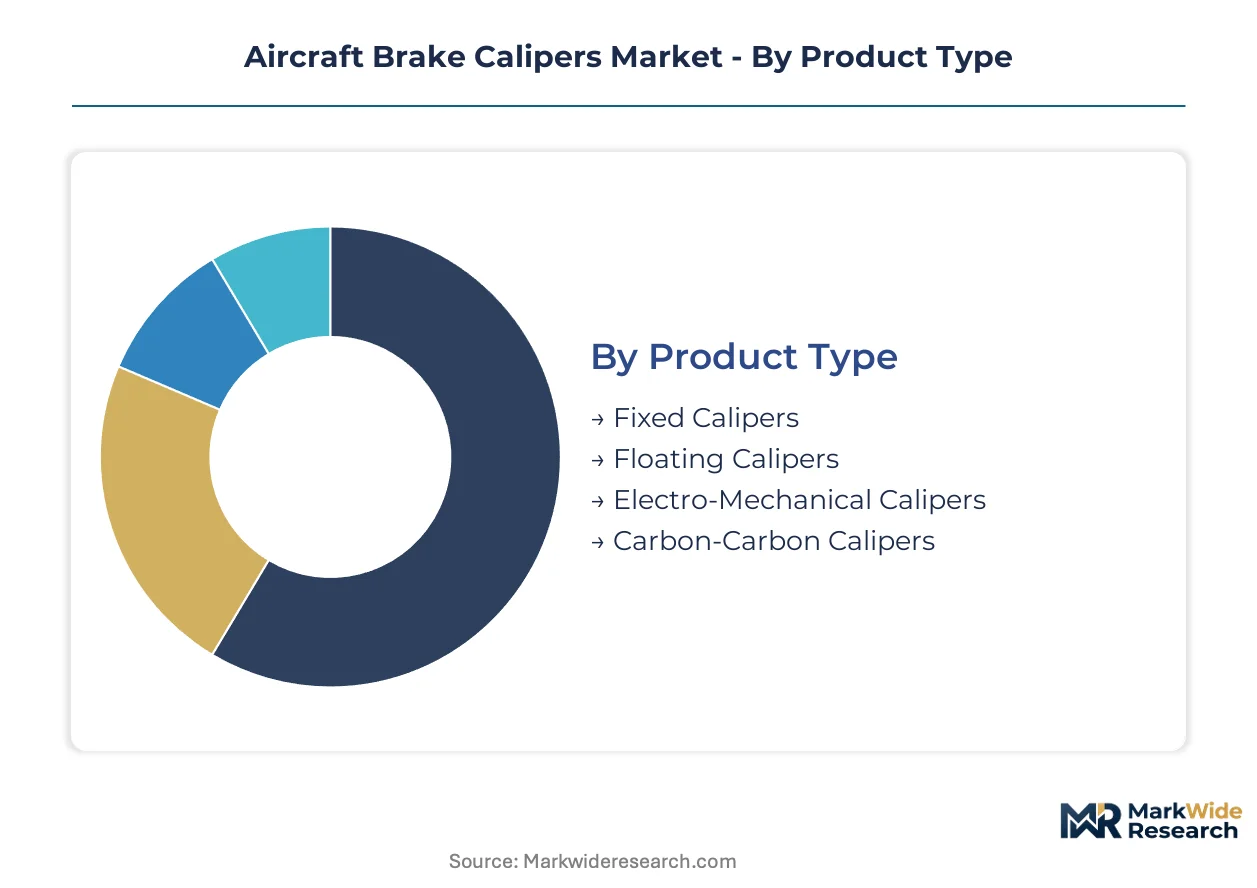
Brake caliper segmentation reveals divergent profit pools across actuation technologies and certification tiers. Product type determines thermal performance ceilings, while end-user categories separate volume-driven commercial contracts from military premium pricing.
Product Type:
Volume concentrates in legacy hydraulic architectures, yet margin accrues to certified electro-mechanical and carbon-carbon platforms.
- Electro-Mechanical Calipers:Electric motor-driven clamping mechanisms eliminate hydraulic fluid lines entirely, integrating position sensors for real-time wear telemetry. Boeing 787 and Airbus A350 programs validated these systems for main landing gear, with regional jet OEMs now mandating electric architectures for clean-sheet designs. FAA-EASA harmonization on electrical actuation standards is compressing approval timelines for second-source suppliers.
- Carbon-Carbon Calipers:Carbon fiber reinforced carbon matrix composites withstand temperatures exceeding 1,000°C during rejected takeoff events while delivering 40% weight reduction versus metallic alternatives. Wide-body platforms at Airbus Toulouse assembly lines specify these for maximum landing mass configurations. Japanese precursor supply concentration creates allocation risk during defense procurement surges.
- Fixed Calipers:Rigid mounting to the landing gear strut provides consistent pad alignment across high-cycle commercial operations.
- Floating Calipers:Sliding pin designs accommodate thermal expansion in regional jet and cargo applications where cost sensitivity dominates.
Today's leader: Carbon-Carbon Calipers. Tomorrow's challenger: Electro-Mechanical Calipers.
End User:
Procurement patterns split between fleet-scale airline tenders and defense procurement corridors with technology transfer mandates.
- Commercial Aviation:Global network carriers and low-cost operators generate the largest unit volumes through fleet renewal programs. Narrow-body procurement at Southwest Airlines and Ryanair drives standardization toward electro-mechanical platforms with predictive maintenance contracts bundled separately from hardware.
- Military Aviation:NATO defense budgets sustain higher per-unit margins through anti-skid integration requirements and extended qualification cycles. India's indigenous fighter programs under defense procurement corridors demand localized production with foreign technology transfer, reshaping supplier footprint.
- General Aviation:Business jet and turboprop operators favor retrofit-compatible caliper designs for legacy airframe extensions.
- Cargo Operations:Freighter conversions at Tel Aviv and Singapore maintenance hubs prioritize brake reliability over weight minimization for high-cycle utilization.
Commercial Aviation captures current volume. Military Aviation commands sustainable premium positioning.
Material:
REACH compliance deadlines are disqualifying legacy friction substrates while accelerating ceramic-matrix qualification pathways.
- Composite Materials:Ceramic-matrix and carbon-carbon formulations meet EASA thermal fatigue mandates for extended replacement intervals. German suppliers near Stuttgart anchor European development clusters for REACH-compliant alternatives to legacy asbestos-containing friction materials.
- Aluminum Alloy:Cast and forged aluminum dominates narrow-body and regional jet applications where thermal loads remain within metallic limits. Airbus Hamburg assembly lines specify aluminum calipers for A320 family production.
- Stainless Steel:Corrosion-resistant grades persist in maritime patrol and carrier-based military aircraft exposed to salt spray environments.
- Cast Iron:Remains cost-competitive for cargo freighter conversions with lower cycle counts and extended parking intervals.
Composite Materials are gaining share fastest. Aluminum Alloy retains near-term volume dominance.
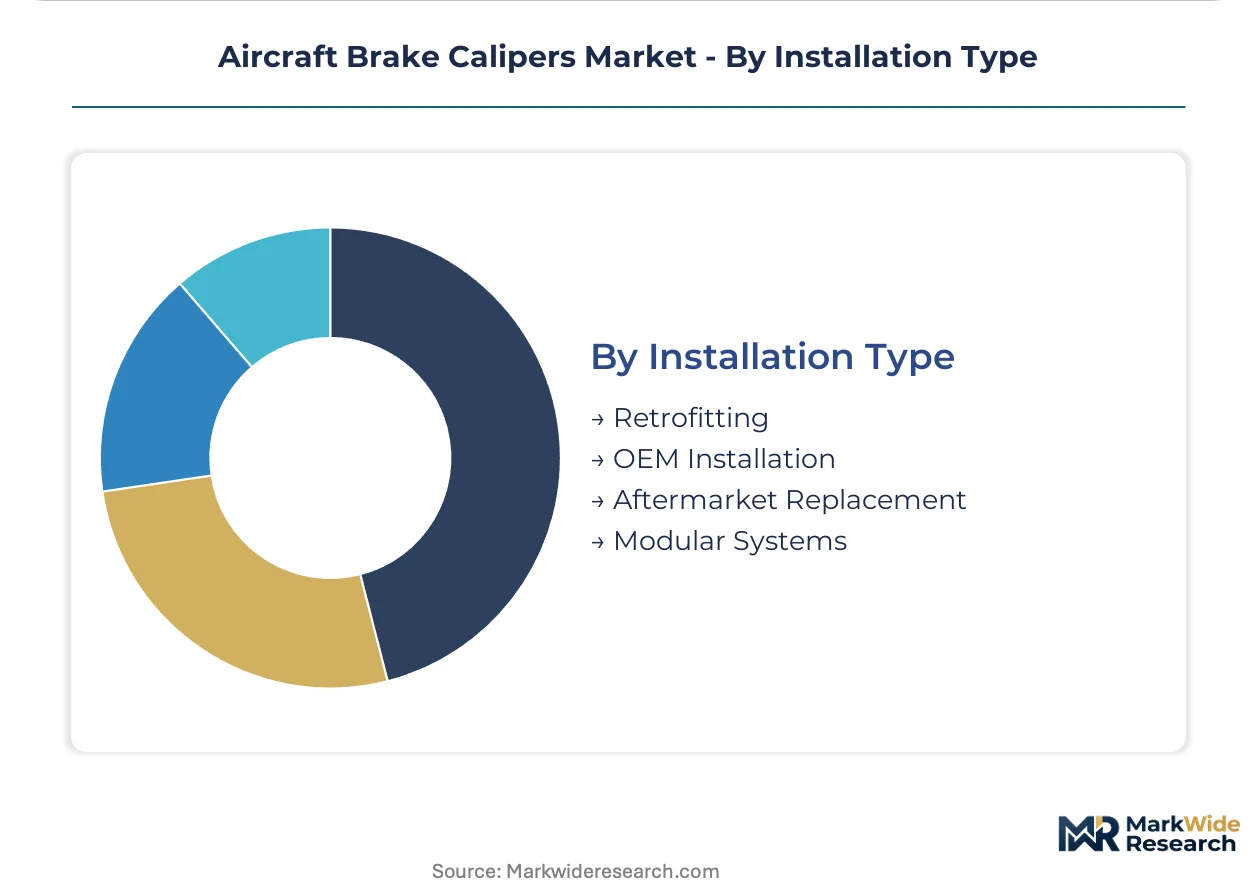
Installation Type:
Aftermarket unbundling is separating hardware procurement from maintenance service contracts across airline purchasing departments.
- OEM Installation:Airframer line-fit programs at Boeing Charleston and Airbus Mobile lock in caliper specifications for 20-year fleet lifecycles. Long-term pricing agreements with landing gear integrators limit supplier switching.
- Aftermarket Replacement:Condition-based replacement driven by IoT sensor data is shifting revenue toward recurring service streams. Lufthansa Technik and ST Engineering have pioneered predictive brake wear monitoring for hub-and-spoke operations.
- Retrofitting:Electro-mechanical conversion kits for legacy hydraulic architectures face certification cost barriers for aging regional jet fleets.
- Modular Systems:Quick-exchange caliper cartridges reduce aircraft-on-ground time for low-cost carriers with high daily utilization targets.
OEM Installation anchors supplier relationships. Aftermarket Replacement is expanding fastest as fleets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aircraft brake caliper manufacturing originated in post-war European and American aerospace clusters, with German precision engineering and US defense procurement establishing the foundational supplier base that persists today.
United States
Defense procurement expansion and commercial fleet renewal sustain demand across military and airline sectors. FAA Part 25 certification mandates govern thermal fatigue testing protocols for all new caliper submissions. Wichita, Kansas and Phoenix, Arizona host landing gear integration facilities where Honeywell and Parker Hannifin anchor domestic supply chains.
Germany
Airbus assembly line proximity drives caliper specification decisions for A320 and A350 programs. REACH chemical regulations are phasing legacy friction materials, accelerating ceramic-matrix composite development. Stuttgart and Hamburg industrial clusters concentrate brake system engineering talent and EASA certification expertise.
France
Toulouse-based landing systems divisions supply integrated wheel and brake architectures for wide-body platforms. EU Green Deal carbon accounting rules pressure airframers toward lighter brake assemblies with extended replacement intervals. The Occitanie region hosts Safran's primary aerospace manufacturing footprint.
United Kingdom
RAF procurement corridors and commercial aftermarket services sustain dual revenue streams for specialized suppliers. The country's national aerospace regulator enforces harmonized EASA thermal performance standards. Southwest England maintains legacy manufacturing infrastructure for regional jet brake system retrofits.
India
Indigenous fighter programs under defense procurement corridors create demand for localized production with technology transfer requirements. BIS standards and DGFT import substitution policies shape supplier qualification pathways. Bangalore and Hyderabad defense clusters are emerging as brake system integration hubs for domestic military aviation.
Aircraft Brake Calipers Market Vendor Landscape
The competitive structure tilts toward integrated aerospace conglomerates with captive landing gear divisions. Tier-one suppliers maintain dominance through airframer line-fit relationships and dual-certification portfolios across FAA-EASA jurisdictions. Two strategic archetypes prevail: diversified industrial conglomerates with aerospace divisions, and specialized brake system engineering houses. Capacity expansion in ceramic-matrix composites and strategic partnerships for electro-mechanical actuation represent the dominant competitive moves.
Among diversified conglomerates, Honeywell International Inc. and Parker Hannifin Corporation occupy positions spanning hydraulic legacy systems and electric actuation transitions. Safran anchors European supply concentration through its Toulouse-proximate landing systems division. Moog Inc. exemplifies the electro-mechanical specialist archetype, while Liebherr-International AG represents Swiss-German precision manufacturing heritage in aerospace components. Collins Aerospace and Meggitt PLC sit within the UK-US transatlantic supplier tier, with Sumitomo Precision Products Co. Ltd. representing Japanese carbon-carbon composite expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Moog Inc. |
| Safran |
| Sumitomo Precision Products Co. Ltd. |
| Liebherr-International AG |
| Parker Hannifin Corporation |
| Collins Aerospace |
| NASCO Aircraft Brake Inc. |
| Meggitt PLC |
| Others |
Supply Flow & Price Mechanics
Electro-mechanical actuation transitions are simultaneously compressing hydraulic caliper margins and concentrating supply among certified carbon-carbon composite suppliers with FAA-EASA dual certification portfolios. This technological pivot reshapes cost economics by elevating qualification barriers while devaluing legacy hydraulic production capacity.
Pricing Analysis
Bundled hardware-maintenance contracts are unbundling across airline procurement departments, with low-cost carriers pioneering split-tender structures that separate predictive wear monitoring from unit caliper sales. Three-tier pricing structure across premium carbon-carbon, standard aluminum-alloy, and economy cast-iron levels reflects certification grade and thermal performance tier. Cost compression in hydraulic calipers is intensifying because regional jet fleets retain legacy architectures with limited upgrade incentives. Cargo operators and narrow-body fleet managers exhibit highest price sensitivity, while wide-body procurement teams at network carriers prioritize weight reduction over unit cost.
Supply Chain Analysis
Freight cost volatility for carbon fiber precursor shipments from Japan and the United States is elevating landed costs for European caliper manufacturers dependent on overseas raw material feeds. Manufacturing concentrates in Germany, France, and the United States where EASA and FAA certification infrastructure anchors production decisions. Specialized carbon fiber precursor, ceramic-matrix composite substrates, and precision-machined aluminum forgings constitute critical input dependencies. Single-source vulnerability for Japanese carbon fiber supply creates allocation risk during defense procurement surges. Distribution runs through airframer line-fit programs at Boeing Charleston and Airbus Toulouse, with aftermarket channels served by landing gear integrators and MRO facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as airframers prioritize extended replacement intervals and thermal performance specifications over upfront unit cost minimization.
For Market Incumbents: Lock in carbon-carbon composite supply agreements with Japanese precursor suppliers before defense procurement surges trigger allocation constraints. Deepen backward integration into ceramic-matrix composite development to preempt REACH regulatory exclusion of legacy friction materials. Certification investment in electro-mechanical architectures defends against hydraulic system obsolescence. For New Entrants and Emerging Players: Direct-to-MRO digital procurement platforms offer entry pathways for aftermarket caliper suppliers lacking airframer line-fit relationships. India's defense procurement corridors present the most penetrable geography, with technology transfer mandates creating partnership openings with domestic landing gear integrators. Target predictive maintenance software bundling as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for specialized brake system engineering houses because EASA-FAA dual certification portfolios create scarce, defensible assets with long-dated revenue visibility. Five-to-ten-year viability hinges on electro-mechanical transition completion. Acquisition targets should demonstrate existing certification portfolios rather than development-stage technologies. Watch the pace of Boeing and Airbus clean-sheet program announcements as the inflection indicator for electro-mechanical demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Matrix Composite Development | REACH compliance deadlines at EASA are disqualifying legacy asbestos-containing friction substrates from new submissions. |
| Electro-Mechanical Certification Investment | FAA-EASA harmonization on electrical actuation standards compresses approval timelines for qualified second-source suppliers. |
| Backward Integration into Carbon Fiber Precursor | Japanese chemical conglomerate supply concentration exposes caliper manufacturers to input cost volatility and allocation risk. |
| Predictive Maintenance Platform Launch | IoT-enabled brake wear sensors bundled with electro-mechanical calipers enable condition-based replacement contracts at Lufthansa Technik. |
| India Defense Localization Partnership | Indigenous fighter programs under DGFT import substitution policies demand localized production with foreign technology transfer. |
Methodological Framework
Bottom-up commercial aviation and military procurement modeling reconciled against top-down carbon-carbon composite and aluminum alloy supply tracking forms the analytical core of this study. Primary interviews with airframer landing gear procurement directors, MRO facility maintenance planners, EASA certification engineers, defense procurement officers at NATO ministries, and carbon fiber precursor supply managers informed demand and supply assumptions. Secondary validation drew from FAA Part 25 airworthiness directives, EASA certification databases, customs trade records for aerospace components, SEC filings of listed aerospace conglomerates, and EU Green Deal implementation guidance documents.
Historical trendline analysis of brake caliper replacement cycles across Boeing and Airbus fleet data established baseline consumption patterns. The projection framework segments by actuation technology, material composition, end-user category, and installation type across the analysis window. CAGRs derive from fitted growth curves applied to fleet expansion projections and technology substitution rates. Industry-specific forecast inputs include airframer delivery schedules, defense budget appropriations for NATO member states, and REACH chemical restriction phase-out timelines.
Regulatory enforcement variance at FAA and EASA, carbon fiber precursor supply disruption events, and airframer program delays are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context and certification portfolio positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
Thrust Vector Control Market