
 United States Aerostat Systems Market | 2026-2036
United States Aerostat Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aerostat Systems Market Intelligence
Border security is repositioning as the dominant demand vertical for aerostat systems, displacing traditional advertising and event marketing applications that once anchored civilian procurement. Raytheon Technologies Corporation leverages its defense electronics integration expertise to capture premium surveillance contracts, while TCOM L.P. anchors the tethered aerostat segment through its persistent elevated platform technology. Raven Aerostar specializes in stratospheric balloon systems that extend mission endurance beyond conventional aerostat limits.
United States aerostat systems are buoyant, tethered aerial platforms typically filled with helium and operated at altitudes up to 15,000 feet, designed for persistent intelligence, surveillance, and reconnaissance missions lasting days or weeks. Their primary purpose centers on delivering continuous wide-area situational awareness without the fuel consumption or mechanical complexity of rotary-wing or fixed-wing alternatives. The military end user segment dominates procurement volume, while the hybrid product type category captures expanding margin pools as operators seek platforms capable of both stationary and relocatable deployment. Surveillance applications lead absolute spending, though communication relay configurations are gaining traction as mesh network architectures mature.
FAA regulations governing tethered aircraft operations shape commercial market access, requiring operators to navigate restricted airspace protocols and obtain specific waivers for extended-altitude missions. NHTSA and DHS frameworks further influence military-adjacent procurement through vehicle-mounted platform safety standards and border infrastructure integration mandates. Stakeholders must monitor evolving FAA rulemaking on beyond-visual-line-of-sight tethered operations, as these determinations will either unlock or constrain commercial expansion outside defense channels.
Market Dynamics
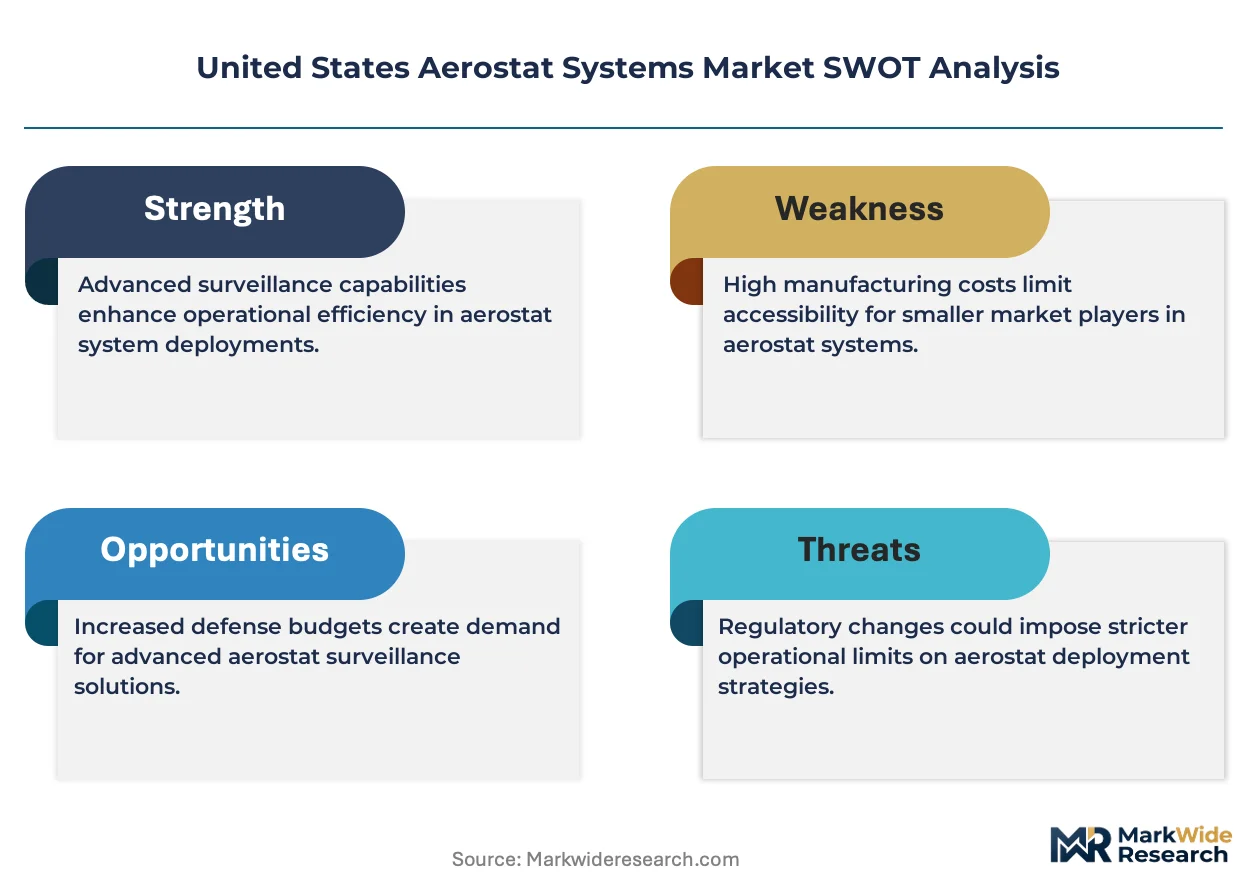
FAA certification requirements for tethered aircraft operations are tightening operational constraints while DHS border infrastructure mandates accelerate procurement cycles for persistent surveillance platforms. This regulatory friction is compressing vendor qualification timelines and reshaping competitive positioning around compliance capabilities rather than pure technical specifications.
Growth Catalysts
- Border Infrastructure Mandates:DHS directives for southern frontier surveillance are expanding federal procurement volumes for elevated persistent platforms. Federal installations in Texas and Arizona anchor the largest deployment clusters.
- Helium Supply Diversification:Strategic reserve releases and private storage infrastructure are stabilizing lift gas availability for extended-duration missions. This input security enables multi-week operational cycles.
- Mesh Network Architectures:Communication relay configurations are gaining traction as military end users integrate aerostats into distributed battlefield connectivity frameworks. Hybrid product types capture expanding procurement preference.
Market Restraints
- Helium Price Volatility:Industrial gas supply concentration creates input cost exposure for operators running extended-duration missions. Lift gas represents a significant recurring operational expenditure.
- FAA Airspace Restrictions:Beyond-visual-line-of-sight tethered operation waivers remain difficult to obtain for commercial operators. This regulatory friction constrains civilian market expansion outside defense channels.
- Fixed-Wing Drone Substitution:Rotary-wing and fixed-wing unmanned platforms offer greater relocatability for rapid response scenarios. These alternatives capture missions requiring frequent repositioning.
Strategic Opportunities
- Stratospheric Balloon Extension:Platforms operating above controlled airspace can bypass FAA tethered aircraft restrictions entirely. This altitude tier opens commercial applications currently blocked by waiver requirements.
- State-Level Emergency Management:Hurricane response and wildfire monitoring agencies represent underpenetrated demand verticals for rapid-deploy aerostat units. Florida and California emergency operations centers show procurement interest.
- Hybrid Platform Convergence:Systems combining stationary aerostat endurance with rapid deflation-relocation capability are capturing preference from military buyers seeking operational flexibility. This technology fusion expands addressable mission profiles.
Industry Challenges
- Tether Systems Engineering Talent:Specialized mechanical design expertise for high-altitude cable dynamics remains scarce. Vendors compete for aerodynamic and materials engineering capacity.
- Type Certification Timelines:FAA airworthiness qualification for novel aerostat configurations extends development cycles by multiple years. This compliance burden disadvantages smaller platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aerostat Systems Market |
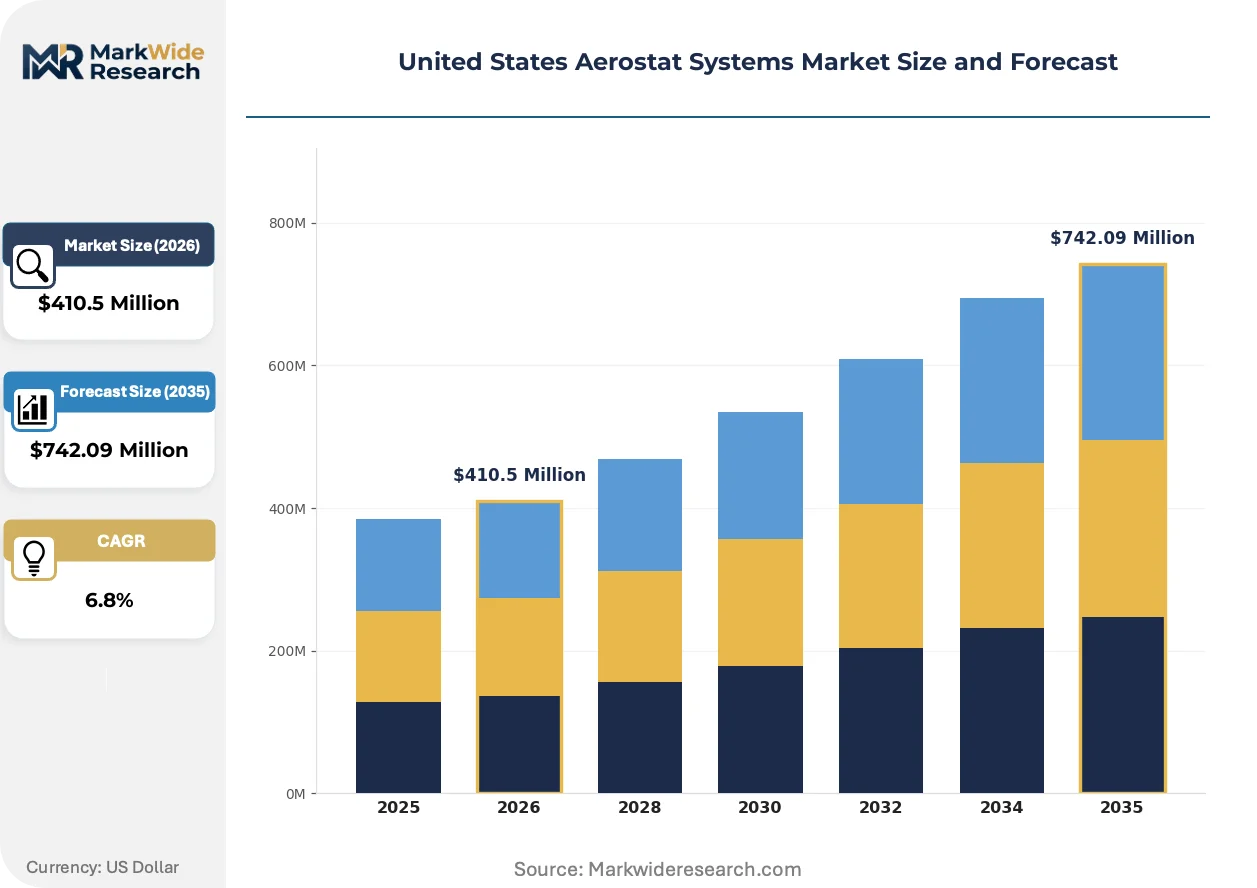
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $742.09 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Mobile, Hybrid, Tethered End User: Military, Civilian, Commercial, Research Application: Surveillance, Communication, Advertising, Border Security Deployment Mode: Onshore, Offshore, Permanent, Temporary |
| Companies Covered | Raytheon Technologies Corporation, Aerostar LLC, TCOM L.P., Drone Aviation Holding Corp., Northrop Grumman Corporation, Raven Aerostar, ILC Dover LP, Aeros Corp., Lockheed Martin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aerostat Systems Market Strategic Shifts & Innovations
Autonomous payload management systems are reshaping how surveillance data is processed and transmitted from elevated platforms. These advances are compressing the gap between raw sensor collection and actionable intelligence delivery.
Stratospheric balloon systems are overtaking conventional tethered aerostats for missions requiring multi-week endurance beyond 60,000 feet. Military research agencies are accelerating procurement of these platforms for communications and signals intelligence applications. This altitude tier is enabling persistent coverage footprints that fixed-site aerostats cannot match.
FAA rulemaking on beyond-visual-line-of-sight tethered operations is tightening certification pathways for commercial operators. The agency's restricted airspace protocols now require explicit coordination with regional air traffic control centers for extended-altitude missions. Commercial surveillance providers are responding by concentrating development resources on stratospheric platforms that operate above controlled airspace entirely.
Defense procurement patterns are rotating toward multi-mission platforms capable of surveillance, communications relay, and signals intelligence from common aerostat architecture. Military end users are consolidating vendor relationships around suppliers offering integrated payload suites rather than bare platforms. This preference shift is most visible in Army and Marine Corps expeditionary unit requirements.
United States Aerostat Systems Market Segmentation
Aerostat procurement patterns diverge sharply across operational contexts. Military buyers prioritize endurance and payload integration, while commercial operators navigate FAA certification constraints. Understanding these segment boundaries clarifies where technology investments concentrate versus where regulatory friction blocks market entry.
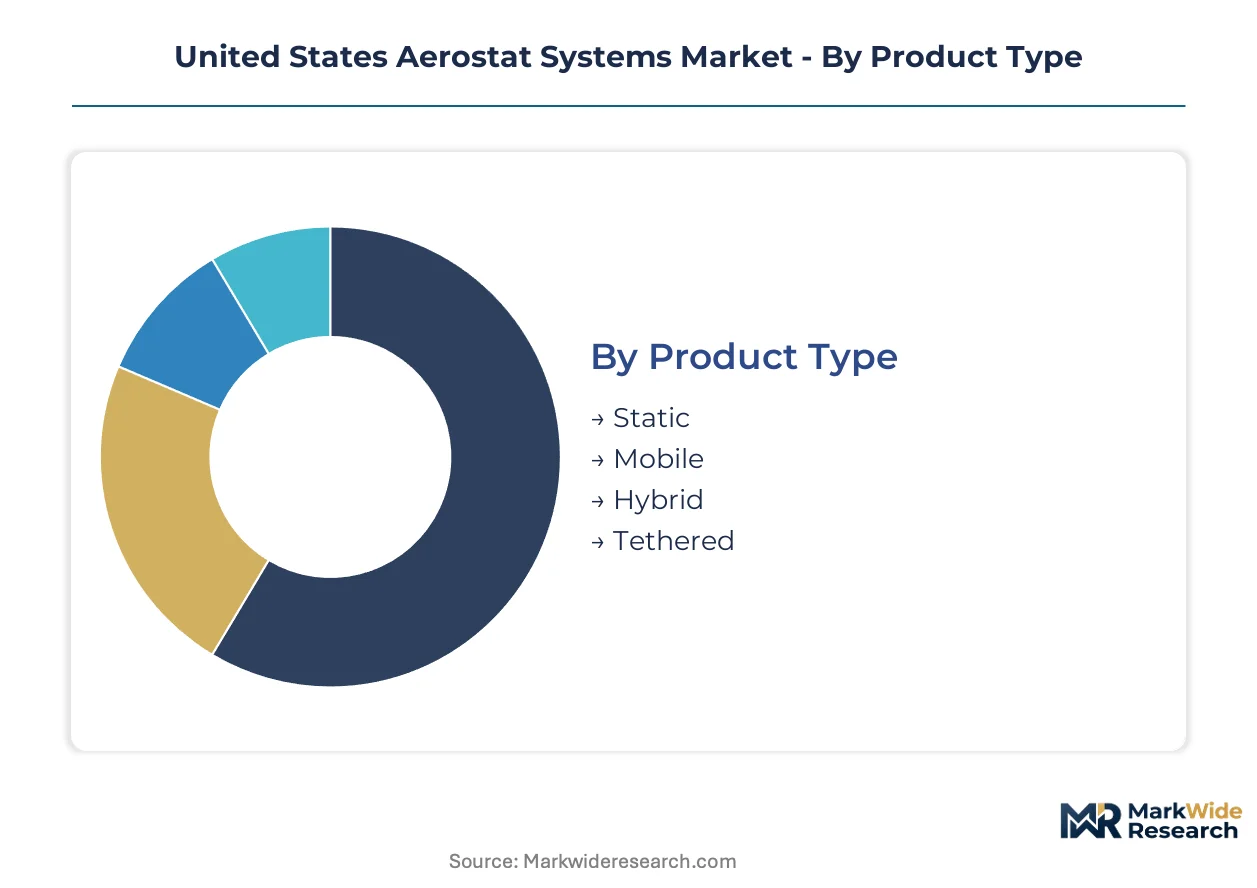
Product Type:
Volume concentrates in tethered platforms, while premium margins accrue to hybrid systems offering operational flexibility.
- Tethered:Helium-filled platforms anchored by high-strength cables dominate federal procurement for persistent surveillance. DHS border installations in Texas and Arizona anchor demand, driven by mandates for 24-hour southern frontier coverage.
- Hybrid:Systems combining stationary endurance with rapid deflation-relocation capability capture expanding military preference. Army expeditionary units prioritize these platforms for missions requiring both persistence and tactical mobility.
- Static:Fixed-site installations serve permanent surveillance nodes with minimal relocation requirements.
- Mobile:Vehicle-mounted units address rapid-response scenarios for emergency management agencies.
Mature deployment sits with Tethered platforms. Newer deployment is concentrated in Hybrid systems.
End User:
Military procurement anchors absolute spending, though civilian applications are gaining traction as stratospheric platforms bypass FAA restrictions.
- Military:Army and Marine Corps units drive procurement for intelligence, surveillance, and reconnaissance missions. Integrated payload suites—combining electro-optical sensors with signals intelligence—are consolidating vendor relationships around defense electronics specialists.
- Commercial:Persistent advertising and event marketing applications face headwinds from FAA beyond-visual-line-of-sight waiver requirements. Stratospheric balloon alternatives are redirecting development resources above controlled airspace.
- Civilian:State emergency management agencies in Florida and California represent emerging demand for hurricane response and wildfire monitoring.
- Research:Atmospheric science and telecommunications testing missions operate under experimental airworthiness certificates.
Established procurement patterns center on Military end users. Steepest expansion trajectory is emerging in Civilian emergency management applications.
Application:
Surveillance commands the largest absolute investment, while communication relay configurations are climbing fastest as mesh network architectures mature.
- Surveillance:Wide-area situational awareness missions leverage electro-optical and infrared payloads for continuous monitoring. Border Security agencies are displacing traditional advertising as the dominant demand vertical.
- Communication:Relay configurations integrate aerostats into distributed battlefield connectivity frameworks. Military research agencies are accelerating procurement for signals intelligence applications above 60,000 feet.
- Border Security:DHS directives for southern frontier infrastructure are expanding federal procurement volumes for elevated persistent platforms.
- Advertising:Aerial banner and video display applications have contracted as defense procurement crowds out civilian lift gas allocation.
Legacy deployment anchors in Surveillance missions. Fastest-growing application is Communication relay for distributed network architectures.
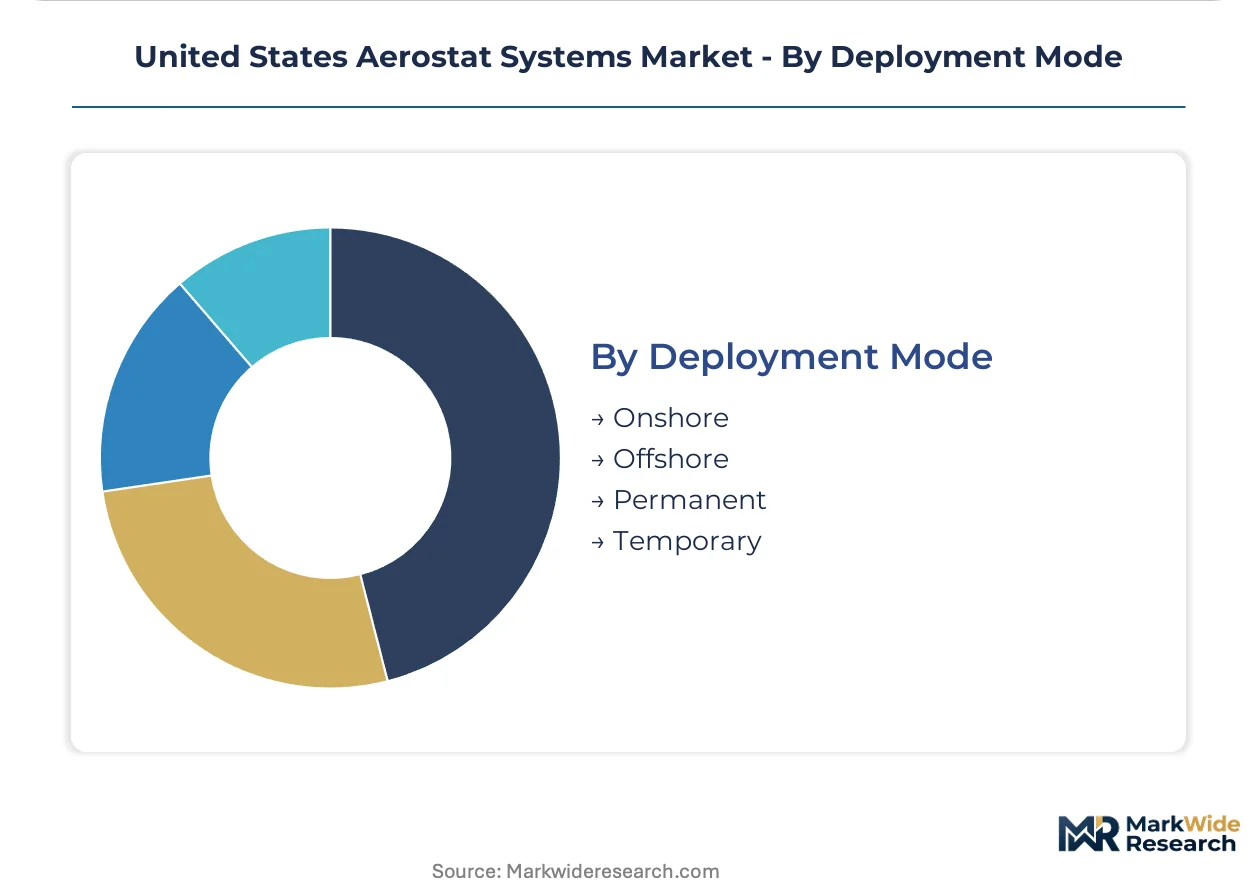
Deployment Mode:
Permanent installations dominate capital expenditure, though temporary deployments are expanding as hybrid platforms enable rapid repositioning.
- Permanent:Fixed-site aerostats at federal installations provide continuous coverage with dedicated ground infrastructure. Arizona and Texas anchor the largest concentration of these assets.
- Temporary:Rapid-deploy units support emergency response and expeditionary military operations. Hurricane response agencies in Florida are evaluating procurement for seasonal deployment cycles.
- Onshore:Continental deployments encompass all border surveillance and domestic military applications.
- Offshore:Maritime platforms for coastal monitoring and naval communications remain limited by corrosion engineering and tether dynamics challenges.
Capital deployment concentrates in Permanent installations. Operational flexibility is driving expansion in Temporary deployment modes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of aerostat platforms concentrates in defense contractor facilities across the southern and western United States, while operational deployment clusters anchor in Texas and Arizona border zones. Consumption patterns track federal procurement cycles rather than commercial demand, creating a geographic mismatch between manufacturing capacity and mission execution sites.
Texas
DHS border surveillance mandates drive persistent aerostat deployment along the Rio Grande corridor. FAA coordination with regional air traffic control centers governs extended-altitude operations above El Paso and McAllen. Raytheon Technologies maintains defense electronics integration facilities in the Dallas-Fort Worth metroplex, anchoring payload development for southern frontier missions.
Arizona
Federal installations near Yuma and Tucson host the densest concentration of tethered surveillance platforms outside Texas. NHTSA vehicle-mounted platform safety standards influence rapid-deploy unit specifications for desert operations. TCOM L.P. maintains operational support infrastructure in the Phoenix area, servicing persistent elevated platform technology for border infrastructure.
California
State emergency management agencies in Sacramento are evaluating seasonal aerostat procurement for wildfire monitoring across the Sierra Nevada foothills. FAA beyond-visual-line-of-sight waiver requirements constrain commercial operators in Los Angeles and San Diego metropolitan airspace. Raven Aerostar conducts stratospheric balloon development testing from facilities in the San Francisco Bay Area, extending mission endurance above controlled airspace.
Florida
Hurricane response agencies in Tallahassee represent emerging demand for rapid-deploy aerostat units during Atlantic storm seasons. FAA restricted airspace protocols require explicit coordination for temporary deployments near Miami and Orlando international airports. ILC Dover LP maintains pressure vessel engineering capabilities on the Space Coast, supporting aerostat envelope fabrication for military expeditionary requirements.
New Mexico
Army and Marine Corps expeditionary units train with hybrid aerostat platforms at White Sands Missile Range for intelligence, surveillance, and reconnaissance missions. FAA certification timelines for novel configurations extend development cycles for Albuquerque-based platform developers. Lockheed Martin Corporation leverages space and defense manufacturing infrastructure in the state to anchor integrated payload suite production.
United States Aerostat Systems Market Key Industry Players
Top-tier vendors anchor federal surveillance contracts, while mid-tier specialists compete on rapid-deploy and hybrid platform flexibility. The vendor base stratifies around defense electronics integrators, tethered aerostat fabricators, and stratospheric balloon innovators. Three archetypes dominate: persistent platform specialists, multi-mission payload integrators, and altitude-tier bypass strategists. Competitive moves concentrate on compliance capability investments and stratospheric airspace positioning rather than pure technical specification races.
Among defense electronics integrators, Raytheon Technologies Corporation and Lockheed Martin Corporation occupy positions exemplifying the multi-mission payload archetype, anchoring vendor relationships through integrated sensor and communications suites. TCOM L.P. sits within the persistent platform tier, representing tethered aerostat specialization for stationary endurance missions. Raven Aerostar exemplifies altitude-tier bypass strategy, positioning stratospheric balloon systems above FAA controlled airspace restrictions.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Aerostar LLC |
| TCOM L.P. |
| Drone Aviation Holding Corp. |
| Northrop Grumman Corporation |
| Raven Aerostar |
| ILC Dover LP |
| Aeros Corp. |
| Lockheed Martin Corporation |
| Others |
Cost & Logistics Intelligence
Defense contractor consolidation through private-equity roll-ups has concentrated aerostat platform ownership among three holding structures, tightening supply discipline while enabling coordinated pricing across federal procurement cycles. This ownership concentration aligns helium sourcing leverage with multi-year DHS contract pricing, embedding cost pass-through mechanisms that shield margins from lift gas volatility.
Pricing Analysis
Margin tightening in tethered platforms reflects FAA certification burden concentration among qualified vendors. Three-tier pricing structure across integrated-payload, bare-platform, and rapid-deploy configurations separates Raytheon-anchored defense electronics bundles from TCOM stationary systems and Raven Aerostar stratospheric alternatives. Cost-down pressure on commercial operators accelerates as stratospheric balloon bypass strategies redirect development resources above waiver requirements. Military end users show lowest price sensitivity given mission-critical mandates, while state emergency management agencies in Florida and California exhibit highest budget constraint responsiveness.
Supply Chain Analysis
Specialized aerodynamic and materials engineering talent scarcity in Texas, Arizona, and New Mexico defense corridors constrains platform development capacity. Helium supply draws from strategic reserve releases and private storage infrastructure concentrated in Kansas and Texas, with envelope fabrication resting on ILC Dover pressure vessel capabilities in Florida and Aeros Corp lighter-than-air manufacturing in California. Single-source vulnerability sits with high-altitude tether cable suppliers facing extended lead times. Distribution runs through prime contractor direct relationships with DHS and Army procurement offices, bypassing traditional aerospace distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable vendors as FAA type certification timelines and helium supply security requirements force weaker platform developers toward acquisition or exit. Stratospheric altitude positioning and hybrid platform flexibility are separating viable competitors from stranded technology bets.
For Market Incumbents: Anticipate fixed-wing drone substitution pressure by accelerating hybrid platform roadmaps that fuse stationary aerostat endurance with rapid deflation-relocation capability. Anchor vendor relationships through integrated payload suite offerings combining electro-optical sensors with signals intelligence, consolidating Army and Marine Corps expeditionary unit procurement around multi-mission architectures. Defensive capacity addition in Texas and Arizona border zones captures DHS infrastructure mandate expansion. For New Entrants and Emerging Players: State emergency management agencies represent the most penetrable demand vertical, with Florida hurricane response and California wildfire monitoring procurement cycles offering rapid-deploy entry points. Bypass FAA beyond-visual-line-of-sight waiver constraints entirely through stratospheric balloon development above controlled airspace. Channel partner relationships with regional air traffic control coordination specialists unlock temporary deployment contracts near restricted metropolitan airspace. For Investors and Strategic Acquirers: FAA rulemaking publication on beyond-visual-line-of-sight tethered operations is the leading indicator that commercial market expansion will either unlock or remain constrained to defense channels. Long-term viability over the next decade hinges on altitude-tier positioning rather than incremental tethered platform improvements. Acquisition targets should profile stratospheric balloon specialists with experimental airworthiness certificates and military research agency relationships, with helium supply diversification infrastructure as the critical signal to watch for input security validation.| Strategic Initiative | Industry Significance |
|---|---|
| Stratospheric Platform Development | Positions systems above FAA controlled airspace, bypassing waiver requirements that block commercial expansion. |
| Hybrid Architecture Convergence | Captures military preference by combining stationary endurance with rapid deflation-relocation capability for tactical flexibility. |
| Integrated Payload Suite Consolidation | Locks in Army and Marine Corps vendor relationships through multi-mission surveillance, communications, and signals intelligence offerings. |
| Helium Supply Infrastructure Investment | Secures lift gas availability for multi-week operational cycles through strategic reserve access and private storage partnerships. |
| State Emergency Management Partnership | Opens civilian demand channels in Florida hurricane response and California wildfire monitoring with seasonal deployment models. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across aerostat program managers at DHS and Army procurement offices, payload integration engineers at defense electronics contractors, FAA certification specialists, and state emergency management directors in Florida and California. FAA airworthiness qualification databases, DHS border infrastructure budget justifications, and helium market trade flow records provided validation layers. Bottom-up platform deployment counts triangulated against top-down federal procurement allocation analysis.
Granularity-level modeling addressed product type at the tethered-hybrid-static-mobile dimension, end user at military-commercial-civilian-research segmentation, and application across surveillance-communications-border security-advertising missions. CAGRs derived from federal budget trajectory analysis and state procurement pipeline evaluation across the projection horizon. Helium price scenario inputs and FAA rulemaking timeline assumptions shaped sensitivity boundaries.
Caveats apply where FAA beyond-visual-line-of-sight waiver policy shifts or helium supply disruption events could materially shift the outlook. Forecasts reflect assumptions on DHS border infrastructure mandate continuity and military expeditionary unit deployment patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Automated Weapon System Market
Unmanned Systems
Global Anti-Drone System Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Lidar Drone Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Drone Docking Station Market
Unmanned Systems
Autonomous Aircraft Software Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Drone Parachute System Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Anti-UAV Defence System (AUDS) Market
Unmanned Systems
Brazil ROV Market