
 Sonobuoy Market | 2026-2036
Sonobuoy Market Size, Share, and Industry Trends Forecast 2026-2036
Sonobuoy Market Intelligence
Maintenance and lifecycle support contracts are rebalancing revenue models away from pure hardware sales in the sonobuoy sector. Lockheed Martin leverages its integration role on maritime patrol platforms to bundle long-term sustainment with sonobuoy delivery. Thales Group anchors European supply through specialized acoustic processing capabilities. Ultra Electronics competes on underwater sensor miniaturization and signal fidelity.
A sonobuoy is a self-contained, expendable buoy equipped with hydrophones and radio transmitters that detects underwater acoustic signatures and relays data to surface or airborne receivers, typically operating at depths from ten to several hundred meters with battery life spanning minutes to hours depending on mission profile. Passive sonobuoys dominate operational inventories due to their lower detectability and extended listening duration, while directional sonobuoys command premium positioning in target-tracking scenarios where bearing accuracy determines engagement outcomes. Air-deployable systems lead procurement volumes tied to maritime patrol aircraft fleets, and multi-function sonobuoys represent the fastest-growing product category as navies consolidate sensor types to reduce logistics burden.
FAA certification governs air-deployable sonobuoy carriage and release mechanisms on military derivative aircraft operating in controlled airspace, while NATO STANAG 4283 standardizes acoustic performance and interoperability parameters for allied naval forces. The EU AI Act and emerging autonomous systems frameworks from EDA will shape next-generation sonobuoy designs incorporating unmanned deployment platforms. Stakeholders must monitor how software-defined acoustic processing and sovereign data-chain requirements reshape procurement specifications and vendor qualification pathways.
Market Dynamics
Software-defined acoustic processing is compressing hardware refresh cycles across naval procurement programs, forcing sonobuoy vendors to decouple sensor hardware from signal processing architectures to maintain platform relevance through mid-life upgrades.
Growth Catalysts
- Maritime Patrol Aircraft Modernization:The P-8A Poseidon fleet expansion across allied navies is generating sustained procurement volumes for air-deployable passive arrays, with NATO STANAG 4283 interoperability mandates ensuring standardized acoustic performance specifications.
- EU AI Act:Autonomous deployment platforms for expendable underwater sensors now face algorithmic transparency requirements, creating compliance-driven demand for explainable acoustic classification systems in European defense procurement.
- Multi-Function Consolidation:Navies are reducing logistics burden by replacing discrete sensor types with programmable sonobuoys capable of passive, active, and communications relay modes through firmware reconfiguration.
Market Restraints
- Lithium-Sulfur Battery Supply Concentration:Extended-duration sonobuoy missions depend on high-density power cells sourced predominantly from East Asian chemical processors, exposing procurement timelines to raw material allocation constraints.
- Acoustic Array Miniaturization Limits:Directional bearing accuracy in compact form factors encounters physical aperture constraints that degrade target localization precision below engagement thresholds in shallow-water environments.
- REACH Substance Restrictions:European environmental regulations are phasing out specific hydrophone potting compounds and anti-fouling coatings, forcing reformulation of proven designs with unvalidated long-term reliability profiles.
Strategic Opportunities
- Unmanned Surface Vehicle Integration:Expendable sonobuoy launch systems are converging with autonomous vessel platforms, enabling persistent barrier patrols without manned aircraft exposure in contested maritime zones.
- Australian Submarine Expansion:The AUKUS nuclear-powered submarine program is accelerating investment in integrated undersea surveillance networks, creating demand for sonobuoys as mobile, relocatable sensor nodes.
- Modular Open Systems Architecture:US Navy mandates for hardware-agnostic software interfaces are opening incumbent-dominated procurement to specialized acoustic processing vendors without full platform integration capabilities.
Industry Challenges
- Underwater Acoustics Expertise Scarcity:The specialized physics and signal processing talent pool for sonobuoy design is contracting as commercial sonar and medical imaging sectors compete for identical electromagnetic and vibration analysis competencies.
- Flight Certification Timeline Compression:FAA airworthiness validation for new carriage and release mechanisms on military derivative aircraft requires 18-36 month test cycles that misalign with rapid sensor technology refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sonobuoy Market |
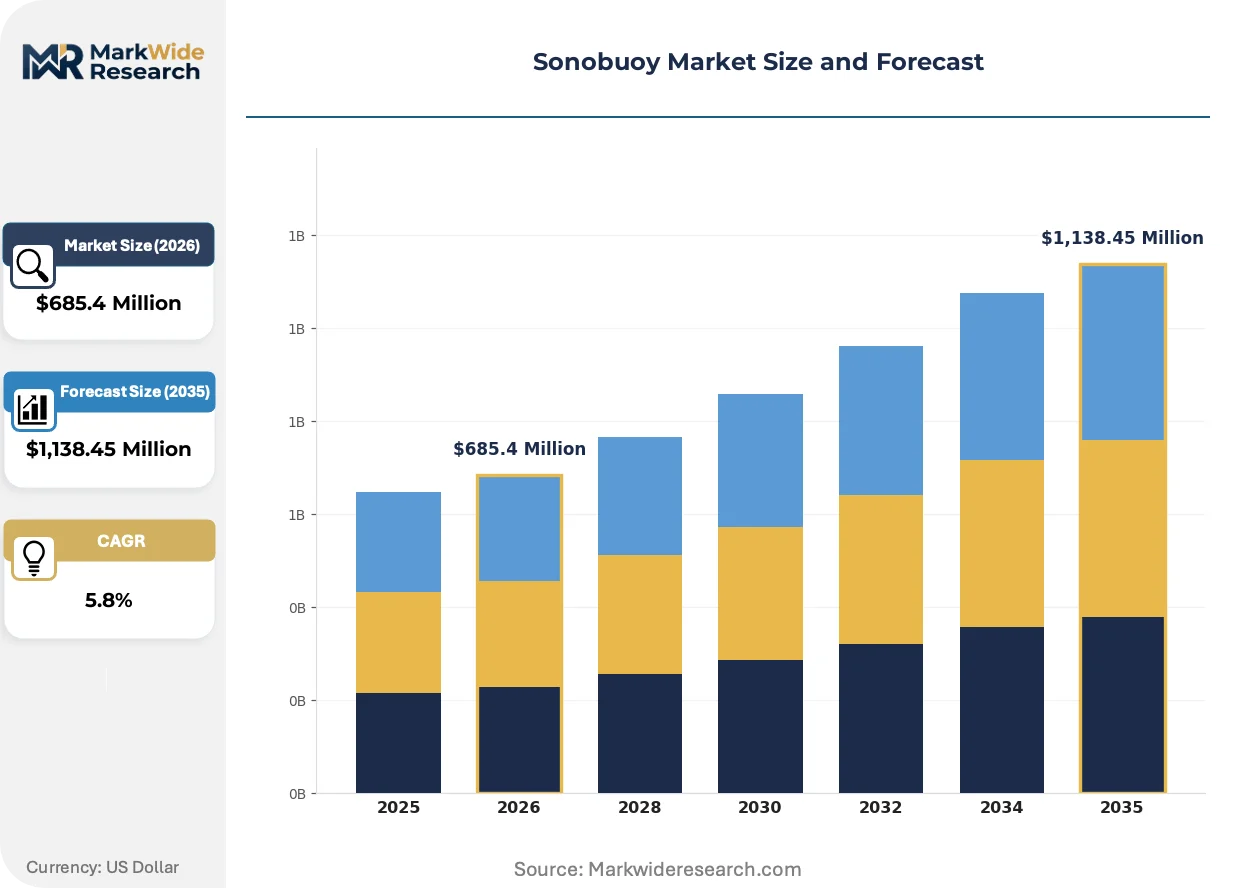
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Sonobuoys, Active Sonobuoys, Directional Sonobuoys, Multi-Function Sonobuoys Deployment Method: Air-Deployable, Surface-Ship Deployed, Underwater Deployment, Submarine Launched End User: Military, Research Institutions, Environmental Agencies, Commercial Operators Technology: Acoustic Sensors, Wireless Communication, Data Processing, Deployment Mechanisms |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Mission Systems, Thales Group, Ultra Electronics Holdings, Sparton Corporation, L3Harris Technologies, Northrop Grumman, ASELSAN AS, SAAB AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sonobuoy Market Strategic Shifts & Innovations
Acoustic detection architectures are fragmenting across sovereign data-chain requirements and unmanned platform integration, compressing traditional hardware-centric business models toward software-defined service relationships.
Digital signal processing hardware is converging with machine-learning inference engines at the sensor edge, enabling real-time target classification without raw acoustic data transmission to airborne platforms. Naval research laboratories in the United States and United Kingdom are fielding prototype arrays with embedded neural accelerators for torpedo, submarine, and biologic signature discrimination. This convergence is compressing the operational relevance of legacy analog preprocessing chains and forcing mid-tier suppliers to license algorithmic IP or exit directional sonobuoy segments entirely.
The EU AI Act's risk classification framework for autonomous defense systems is mandating algorithmic audit trails and human oversight protocols for acoustic target identification loops. European defense procurement agencies are embedding these requirements into technical specifications ahead of formal enforcement timelines, disqualifying black-box classification models from contested bid evaluations. Sonobuoy vendors with European manufacturing footprints are responding by architecting explainable decision trees and confidence-threshold alerting mechanisms that preserve operator intervention points.
Long-term sustainment contracts are displacing discrete hardware purchases as the dominant revenue mechanism in maritime patrol aircraft programs. Fleet operators in Australia and the United Kingdom are consolidating sonobuoy logistics, storage, and refresh scheduling under single-source agreements with platform integrators. This behavioral shift is visible most acutely in P-8A support contracts, where annual availability payments now exceed original equipment values within five-year windows.
Sonobuoy Market Segmentation
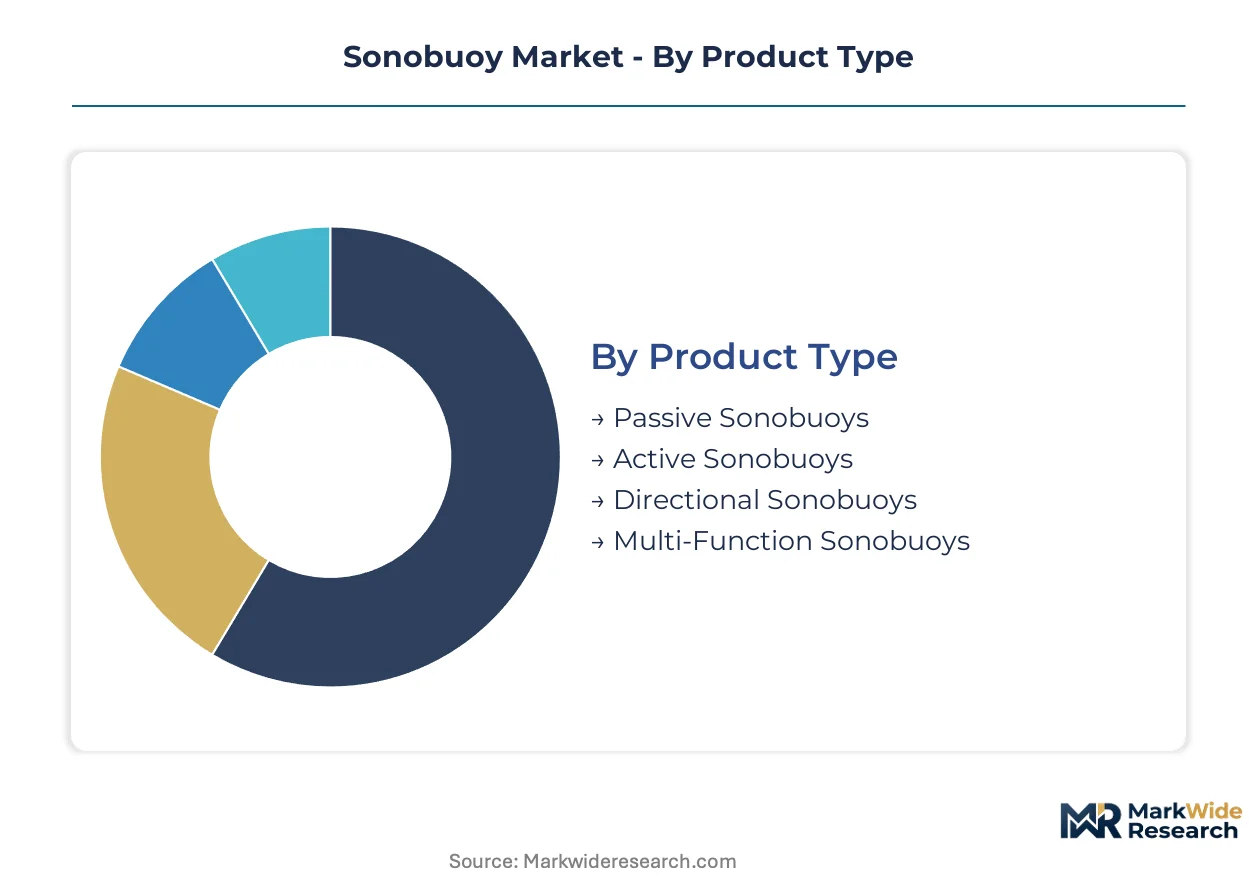
Sonobuoy procurement patterns diverge sharply across mission profiles, with antisubmarine warfare programs driving hardware specifications while research and environmental monitoring create parallel demand streams for modified acoustic packages. Understanding these segment boundaries clarifies where technology investments concentrate and where commoditization pressures emerge.
Product Type:
Supply concentration for finished sonobuoy systems tilts toward passive and directional variants, where specialized hydrophone manufacturing and calibration capabilities limit viable vendor pools.
- Passive Sonobuoys:Arrays of omnidirectional hydrophones detect radiated noise from submerged targets without emitting detectable signals. Naval procurement in the United States, the United Kingdom, and Australia prioritizes these systems for covert barrier patrols where platform survivability depends on emission control.
- Directional Sonobuoys:Beamforming hydrophone clusters enable bearing estimation to targets through phase-difference processing. Demand clusters in shallow-water engagement scenarios where localization precision determines torpedo firing solutions.
- Active Sonobuoys:Projector-hydrophone combinations generate acoustic pulses and analyze returns for target ranging.
- Multi-Function Sonobuoys:Programmable architectures switch between passive listening, active pinging, and communications relay modes through firmware updates.
Passive Sonobuoys absorb the bulk of installed capacity; Multi-Function Sonobuoys are expanding most quickly.
Deployment Method:
Cost tier stratification separates air-deployable systems—carrying FAA certification premiums—from surface and underwater alternatives with simpler integration requirements.
- Air-Deployable:Pneumatic or gravity-release mechanisms disperse sonobuoy patterns from maritime patrol aircraft at altitude. P-8A Poseidon fleet modernization across allied navies sustains procurement volumes for these systems.
- Surface-Ship Deployed:Rail or launcher systems on frigates and destroyers deploy sonobuoys for local area denial. Demand concentrates in convoy escort and littoral security missions where aircraft availability is constrained.
- Underwater Deployment:Unmanned underwater vehicles release sonobuoys at depth for persistent surveillance networks.
- Submarine Launched:Torpedo tube or signal ejector systems deploy self-propelled sonobuoys for offboard sensing.
Air-Deployable systems command the steepest expansion trajectory; Surface-Ship Deployed variants hold the largest existing inventory base.
End User:
Application-driven specification divergence splits military requirements—governed by NATO STANAG 4283—from civilian use cases with relaxed interoperability mandates.
- Military:Naval antisubmarine warfare programs specify acoustic performance thresholds, battery endurance, and environmental operating envelopes. Procurement cycles align with maritime patrol aircraft fleet refresh timelines.
- Research Institutions:Oceanographic laboratories deploy modified sonobuoys for marine mammal tracking, seismic survey validation, and acoustic propagation studies.
- Environmental Agencies:Fisheries management and protected species monitoring programs utilize passive acoustic packages with extended recording duration.
- Commercial Operators:Offshore energy and subsea cable industries employ sonobuoys for construction monitoring and threat detection.
Military end users absorb the bulk of installed capacity; Environmental Agencies are climbing the fastest as marine spatial planning expands acoustic baseline requirements.
Technology:
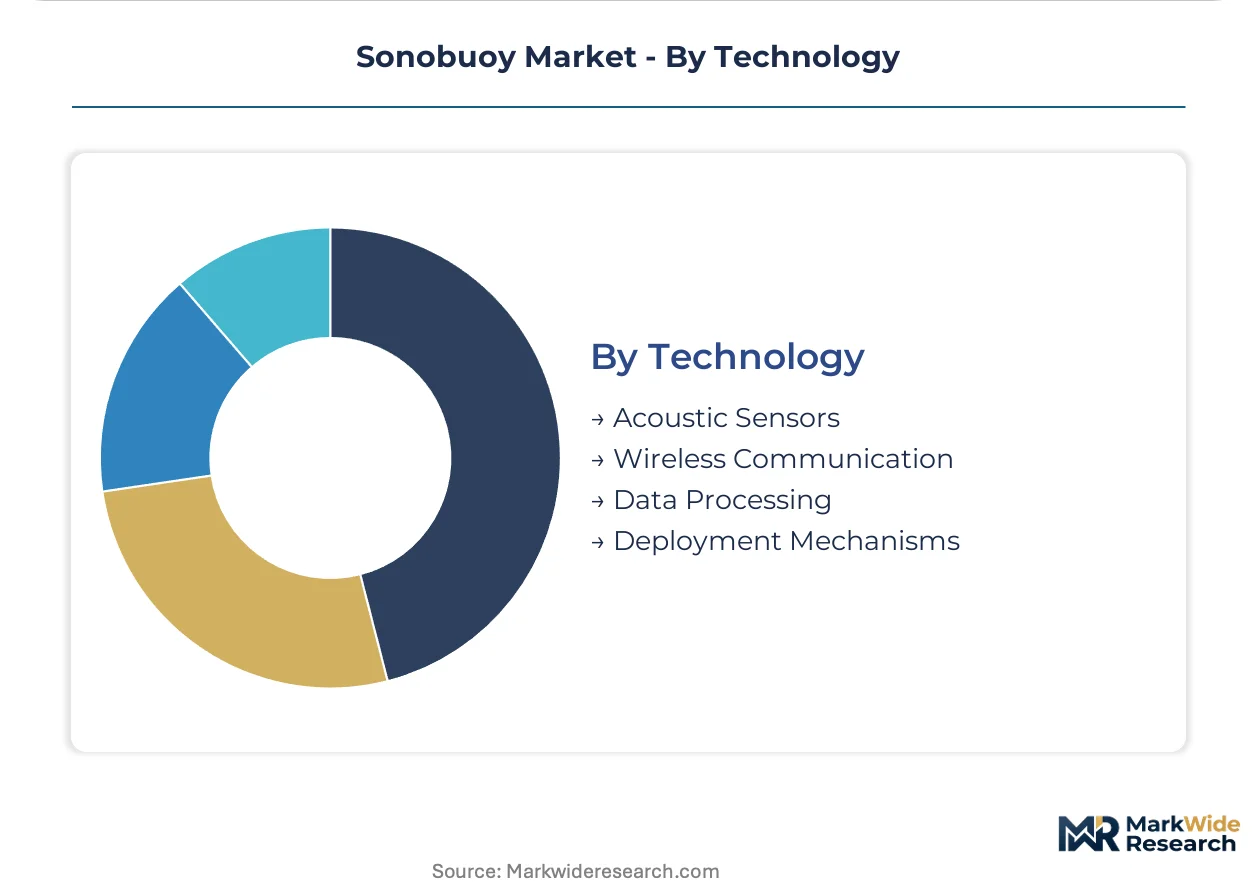
Margin distribution across the technology stack concentrates in data processing and acoustic sensor elements, where specialized physics expertise creates vendor differentiation.
- Acoustic Sensors:Piezoelectric hydrophone elements and array configurations determine detection range and bearing accuracy. Ceramic formulation and calibration precision separate premium suppliers from commodity producers.
- Wireless Communication:Radio frequency transmitters and satellite relay modules bridge submerged sensors to airborne or surface receivers.
- Data Processing:Edge computing architectures with neural accelerators enable real-time target classification without raw data transmission.
- Deployment Mechanisms:Carriage systems, parachute assemblies, and seawater activation circuits ensure reliable delivery and initialization.
Acoustic Sensors absorb the bulk of installed capacity; Data Processing is gaining share fastest as software-defined architectures displace analog preprocessing chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for sonobuoy systems clusters in defense industrial bases with maritime patrol aircraft integration capabilities, while operational demand concentrates in allied naval forces modernizing undersea surveillance networks. The United States, United Kingdom, and Australia drive procurement volumes through P-8A Poseidon fleet expansion and AUKUS submarine program coordination.
United States
P-8A Poseidon production at Boeing's Renton facility sustains air-deployable sonobuoy demand through integrated maritime patrol aircraft procurement. FAA certification requirements for carriage and release mechanisms govern military derivative aircraft operating in controlled airspace. Defense industrial activity concentrates in Maryland and Florida, where platform integrators coordinate sonobuoy logistics with fleet operators.
United Kingdom
Royal Air Force P-8A fleet establishment generates sustained sonobuoy procurement aligned with NATO STANAG 4283 interoperability mandates. The EU AI Act's algorithmic transparency requirements shape specifications for autonomous deployment platforms in European defense procurement. Acoustic processing capabilities cluster in Hampshire and Somerset, where specialized sensor manufacturers support maritime patrol operations.
Australia
AUKUS nuclear-powered submarine program accelerates investment in integrated undersea surveillance networks with sonobuoys as relocatable sensor nodes. TGA-equivalent defense certification frameworks govern acoustic system validation for allied technology integration. Industrial coordination centers in South Australia and Queensland, where submarine construction and maritime patrol bases concentrate infrastructure investment.
Japan
Maritime Self-Defense Force P-1 patrol aircraft procurement sustains regional demand for air-deployable passive arrays with extended battery endurance. METI industrial policy supports domestic hydrophone manufacturing and acoustic sensor calibration capabilities. Defense production clusters in Aichi and Kanagawa prefectures, where aerospace and maritime electronics suppliers coordinate platform integration.
Canada
CP-140 Aurora fleet life-extension programs generate sonobuoy refresh demand aligned with NATO acoustic interoperability standards. Health Canada environmental regulations influence anti-fouling coating formulations for Arctic operating conditions. Maritime patrol operations concentrate in Nova Scotia and British Columbia, where naval aviation bases coordinate Atlantic and Pacific surveillance missions.
Sonobuoy Market Key Industry Players
Top-tier vendors anchor platform integration contracts, while mid-tier specialists compete on acoustic sensor miniaturization and signal processing IP. The vendor base stratifies across full-system integrators with maritime patrol aircraft relationships, specialized hydrophone manufacturers with ceramic formulation expertise, and software-defined processing vendors leveraging modular open systems architecture mandates. Strategic moves concentrate on long-term sustainment contract capture and algorithmic IP licensing for edge-classification capabilities.
Within the platform integration tier, Lockheed Martin Corporation and Thales Group occupy positions bundling sonobuoy delivery with maritime patrol aircraft sustainment. Ultra Electronics Holdings exemplifies the specialized sensor archetype, competing on underwater acoustic detection fidelity. L3Harris Technologies represents the communications and processing vector, bridging sensor outputs to airborne receiver architectures.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Mission Systems |
| Thales Group |
| Ultra Electronics Holdings |
| Sparton Corporation |
| L3Harris Technologies |
| Northrop Grumman |
| ASELSAN AS |
| SAAB AB |
| Others |
Cost & Logistics Intelligence
Software-defined acoustic processing architectures are compressing hardware refresh cycles while simultaneously concentrating procurement leverage among platform integrators with maritime patrol aircraft relationships. This technological transition reshapes cost economics by decoupling sensor hardware from signal processing, forcing mid-tier vendors to license algorithmic IP or absorb margin erosion from commoditized analog components.
Pricing Analysis
Margin tightening in directional sonobuoy tiers reflects NATO STANAG 4283 certification premiums and ceramic hydrophone calibration precision requirements. Three-tier pricing structure across mission-critical, standard, and training-grade levels separates FAA-certified air-deployable systems from surface-ship alternatives. Cost-down pressure on passive array suppliers accelerates because multi-function consolidation reduces discrete sensor procurement volumes. Research institutions exhibit highest price sensitivity; naval antisubmarine warfare programs demonstrate lowest sensitivity due to mission-critical reliability thresholds.
Supply Chain Analysis
Piezoelectric ceramic supply rests on Japanese and German specialty material producers with proprietary formulation expertise. Lithium-sulfur battery cells draw from South Korean and Chinese chemical processors, while precision hydrophone calibration equipment feeds from United Kingdom and United States acoustic laboratories. Single-source vulnerability concentrates in high-density power cell allocation for extended-duration missions. Distribution runs through defense platform integrators bundling sonobuoy logistics with maritime patrol aircraft sustainment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
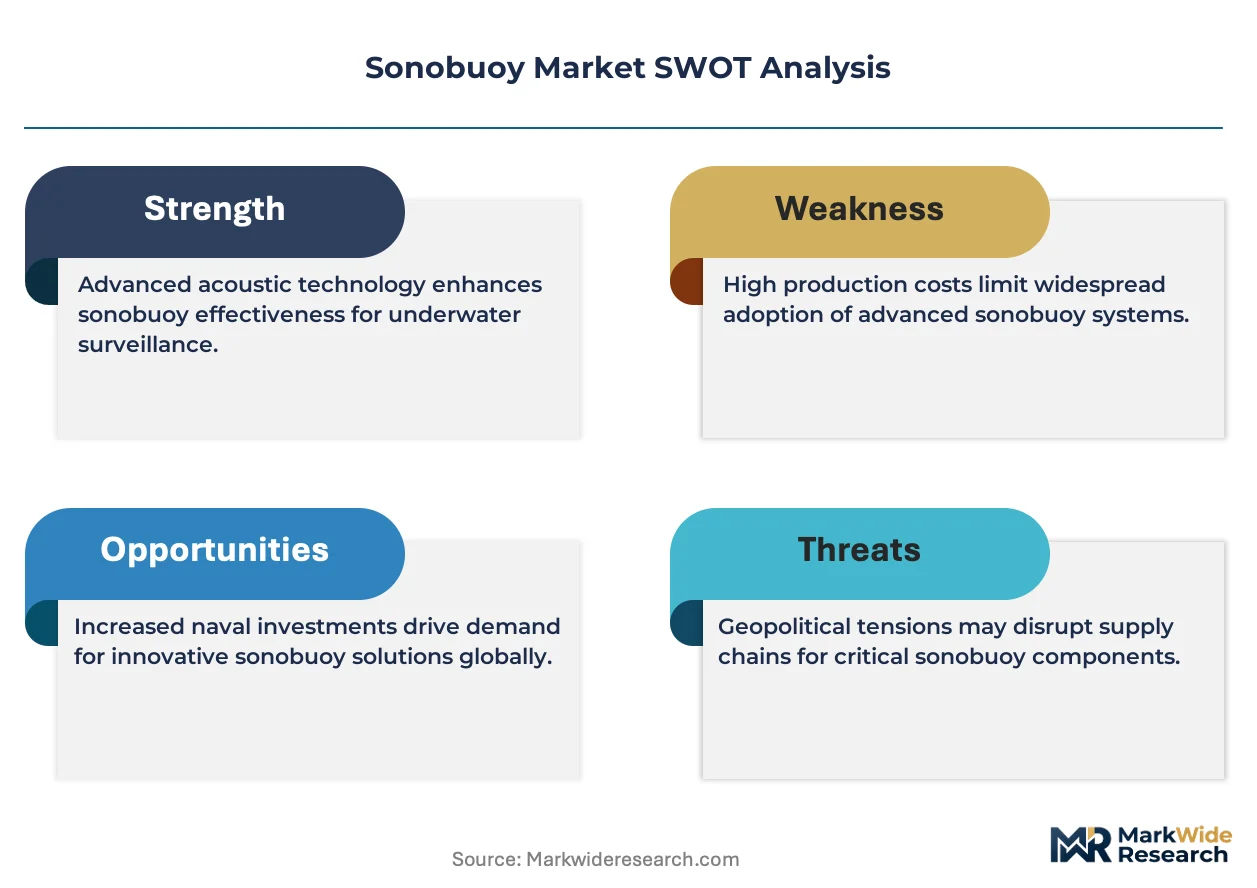
Specialized underwater acoustics expertise scarcity props pricing power for vendors with embedded physics talent, constraining rapid supply expansion regardless of procurement volume growth.
For Market Incumbents: Acquire acoustic processing algorithm IP to defend against software-defined processing vendors leveraging Modular Open Systems Architecture mandates. Capture long-term sustainment contracts with Royal Australian Air Force and Royal Air Force P-8A fleet operators to lock out specialized sensor competitors. Expand in-house lithium-sulfur battery testing capabilities to reduce East Asian chemical processor dependency exposure. For New Entrants and Emerging Players: Launch via unmanned surface vehicle integration partnerships targeting persistent barrier patrol applications in contested maritime zones. Penetrate environmental agency segments in Canada and Australia where marine spatial planning expands acoustic baseline requirements with relaxed NATO interoperability mandates. Lead with explainable acoustic classification systems compliant with EU AI Act algorithmic transparency requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integrator acquisition of specialized hydrophone manufacturers with ceramic formulation expertise. Five-to-ten year viability favors vendors with sovereign data-chain certification and edge-computing neural accelerator integration. Watch AUKUS submarine program funding allocation signals as inflection indicator for integrated undersea surveillance network investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic IP Licensing | Enables mid-tier suppliers to retain directional sonobuoy segment relevance against platform integrators. |
| Long-Term Sustainment Contract Capture | Locks revenue streams with Royal Australian Air Force and Royal Air Force P-8A fleet operators. |
| EU AI Act Compliance Architecture | Qualifies vendors for European defense procurement with explainable decision trees and audit trails. |
| Unmanned Platform Integration | Opens persistent barrier patrol applications without manned aircraft exposure in contested zones. |
| Ceramic Hydrophone Calibration Investment | Preserves premium positioning through piezoelectric element precision and array configuration expertise. |
Research Approach
Multi-period observation of maritime patrol aircraft fleet procurement schedules, NATO STANAG 4283 certification timelines, and AUKUS submarine program funding trajectories anchored the trend analysis, supplemented by interviews with naval aviation program officers, acoustic sensor R&D directors, defense procurement contract managers, and platform integration engineers. Secondary validation drew from FAA airworthiness certification databases, NATO standardization agreements, defense ministry budget appropriations, and customs trade records for piezoelectric ceramic and lithium-sulfur battery imports. Bottom-up vendor revenue triangulation against top-down fleet modernization spend estimates calibrated market sizing.
Segment-weighting across product type, deployment method, end user, and technology dimensions shaped the analytical framework across the projection horizon. Modeled dimensions included passive versus directional versus multi-function architectures, air-deployable versus surface-ship versus unmanned platform delivery, military versus research versus environmental agency demand, and acoustic sensor versus data processing versus deployment mechanism value capture. CAGRs derived from fleet expansion schedules and technology refresh cycle compression rates. Forecast inputs incorporated P-8A Poseidon production rates and EU AI Act implementation timelines.
Lithium-sulfur raw material allocation constraints, REACH substance restriction enforcement scope, and flight certification timeline compression are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on battery chemistry evolution and regulatory harmonization across allied procurement frameworks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Aerostat System Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Drone Battery System Market