
 Drill Collar Market | 2026-2036
Drill Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Collar Market Intelligence
Geothermal energy drilling is hardening as a demand vertical for drill collar suppliers, diverting capacity from conventional oilfield service channels. Hunting PLC leverages its North American manufacturing footprint to supply spiral and non-magnetic configurations for high-temperature geothermal wells. National Oilwell Varco anchors its position through integrated drill string packages that bundle collars with top drives and downhole tools. Schlumberger differentiates via digital twin-enabled collar fatigue monitoring that extends replacement interval forecasting for operators.
A drill collar is a thick-walled, heavy-walled tubular component positioned directly above the drill bit to provide weight on bit and maintain compressive force during drilling operations, typically manufactured from AISI 4145H modified alloy steel with yield strengths exceeding 110 ksi and outer diameters ranging from three to twelve inches. Spiral drill collars dominate premium applications where differential sticking risk in high-angle wells demands grooved outer profiles to reduce contact area with the formation. Non-magnetic drill collars represent the fastest-growing material configuration, driven by measurement-while-drilling and logging-while-drilling tool compatibility requirements in directional drilling programs. Standard steel collars remain the volume anchor in vertical well markets across the Middle East and onshore North America, where cost sensitivity overrides advanced material specifications.
API Specification 7-1 governs dimensional tolerances, material grades, and inspection protocols for drill collar manufacturing, while ISO 11960 provides complementary quality management benchmarks for oilfield equipment suppliers. The EPA's methane emissions rules for oil and gas operations indirectly shape collar demand by accelerating drilling efficiency investments that reduce non-productive time and associated venting. Stakeholders must monitor how API's ongoing standard revision cycle addresses hydrogen embrittlement risks from high-pressure hydrogen sulfide service environments.
Market Dynamics
Horizontal drilling intensity in the Permian Basin is compressing replacement cycles for heavyweight drill pipe, while API 7-1 specification revisions are forcing manufacturers to retool material traceability systems. These dual pressures are restructuring supplier-operator relationships around certified compliance rather than price competition.
Growth Catalysts
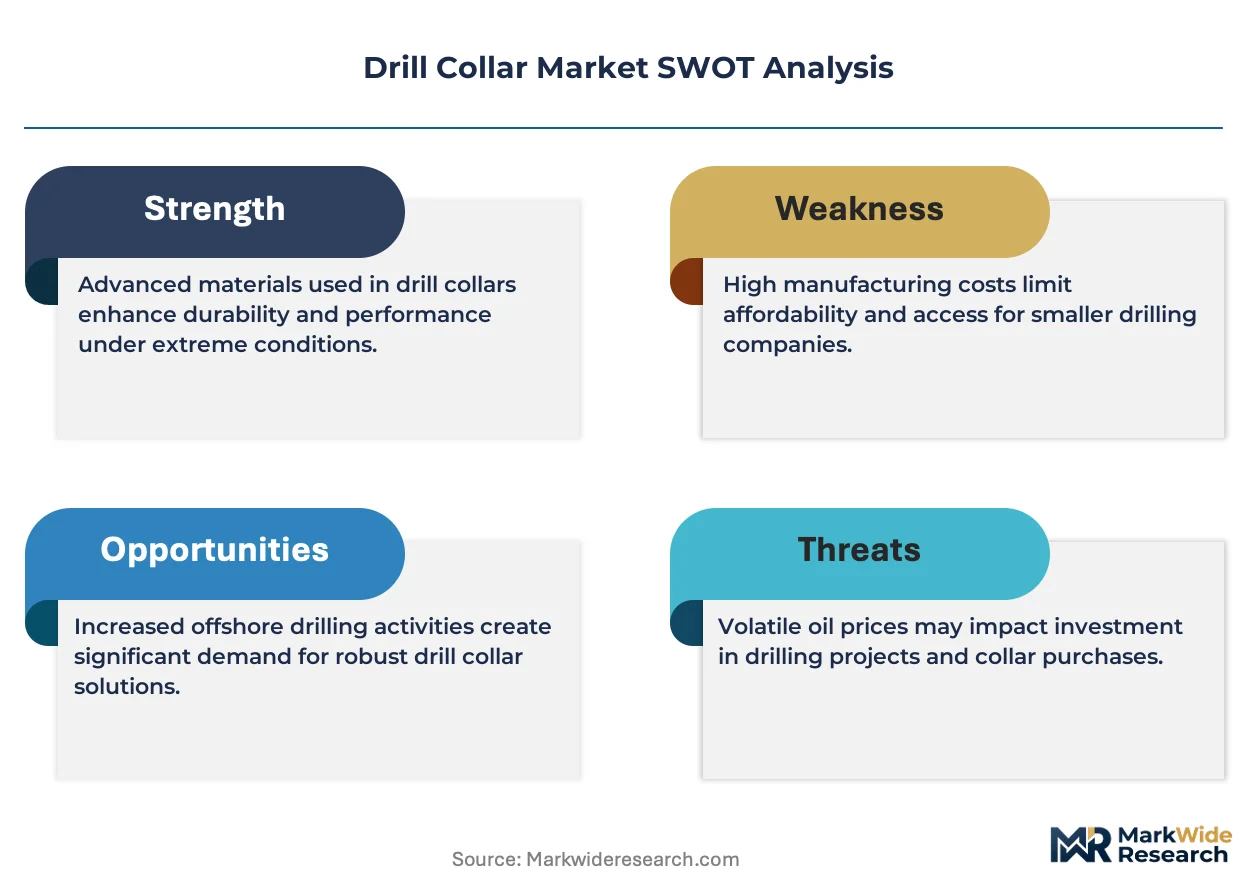
- EPA methane emissions rules:Accelerated drilling efficiency investments reduce non-productive time and associated venting, hardening demand for premium collar configurations that minimize connection failures.
- Geothermal energy drilling:High-temperature well programs in the western United States divert manufacturing capacity from conventional oilfield channels, opening parallel revenue streams for non-magnetic collar suppliers.
- Measurement-while-drilling compatibility:Directional drilling programs in the North Sea require non-magnetic material specifications that command material premiums over standard steel configurations.
Market Restraints
- Alloy steel input volatility:AISI 4145H modified bar stock pricing fluctuates with scrap metal and molybdenum markets, compressing mill margin predictability.
- Single-source forging concentration:Premium collar production clusters with specialized open-die forgers in Ohio and Pennsylvania, creating geographic supply vulnerability.
- Technical limitation in hydrogen sulfide service:Hydrogen embrittlement risks in sour gas environments constrain collar life and require expensive material upgrades beyond standard specifications.
Strategic Opportunities
- Underpenetrated geothermal vertical:Iceland and Kenya drilling programs lack established collar supply chains, creating first-mover positioning for API-certified manufacturers.
- Digital twin convergence:Fatigue monitoring systems that integrate collar sensor data with predictive analytics are compressing replacement interval forecasting into subscription revenue models.
- EU Green Deal methane intensity standards:Proposed import tariffs on high-emission crude will favor drilling contractors using premium collars that reduce connection leaks and non-productive time.
Industry Challenges
- Ultrasonic inspection technician scarcity:API 7-1's tightened defect detection protocols require certified NDT specialists that forgers struggle to recruit and retain.
- ISO 11960 compliance timeline compression:Quality management system recertification cycles are accelerating as major operators audit suppliers against evolving benchmark protocols.
- Legacy drill string integration friction:New premium collar designs must maintain thread compatibility with decades-old pipe inventories in active service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Collar Market |
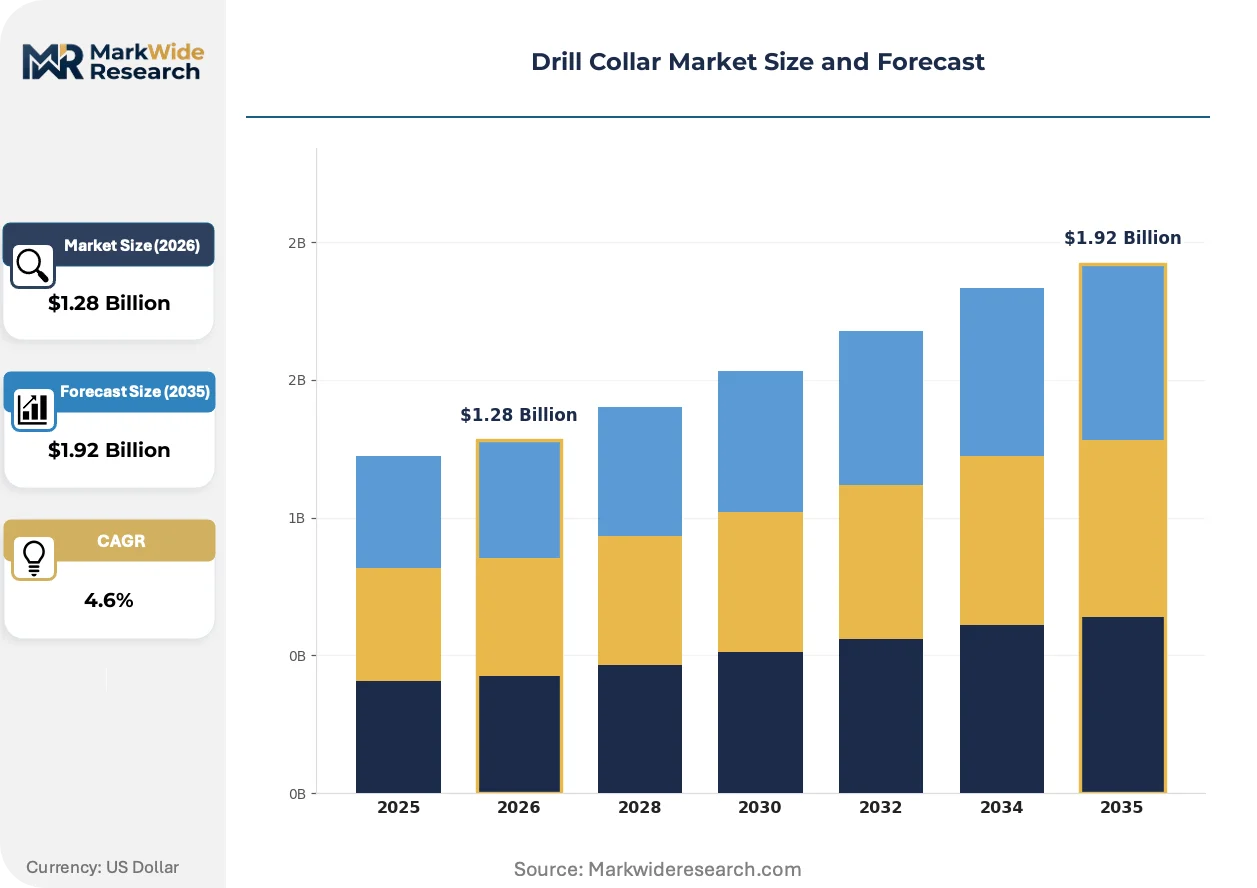
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drill Collars, Spiral Drill Collars, Heavyweight Drill Pipe, Non-magnetic Drill Collars End User: Oil & Gas Industry, Mining Industry, Water Well Drilling, Geothermal Energy Material: Steel, Alloy, Composite, Titanium Size: Standard Size, Custom Size, Large Diameter, Small Diameter |
| Companies Covered | Workstrings International, Hunting PLC, National Oilwell Varco, Schlumberger, International Drilling Services Ltd, American Oilfield Tools, Texas Steel Conversion Inc, China Vigor Drilling Oil Tools and Equipment Co Ltd, Weatherford International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Collar Market Strategic Shifts & Innovations
Material science advances and digital instrumentation are converging to transform drill collars from passive weight components into intelligent, condition-monitored assets. This shift is reshaping supplier value propositions toward integrated system performance rather than standalone product specifications.
Non-magnetic stainless steel alloys with enhanced corrosion resistance are converging with permanent magnet motor drilling systems in high-temperature geothermal applications. Operators in the western United States are specifying these configurations for wells exceeding 300°F bottom-hole temperatures. The technology is converging with downhole power generation requirements, compressing the addressable market for conventional magnetic collars in directional programs.
API's ongoing 7-1 revision cycle is tightening material traceability from melt source through final inspection, with particular scrutiny on heat treatment records. European operators are demanding REACH-compliant surface coatings that eliminate hexavalent chromium conversion treatments. North American forgers are responding by certifying alternative passivation processes that maintain thread galling resistance.
Rental and managed-pressure-drilling service contracts are displacing outright purchase as the dominant procurement channel for premium collar configurations. Major drilling contractors in the Gulf of Mexico are bundling collar supply into integrated drill string packages with performance guarantees. This shift is most visible in offshore markets where capital discipline favors operating lease structures over balance-sheet ownership of specialized equipment.
Drill Collar Market Segmentation
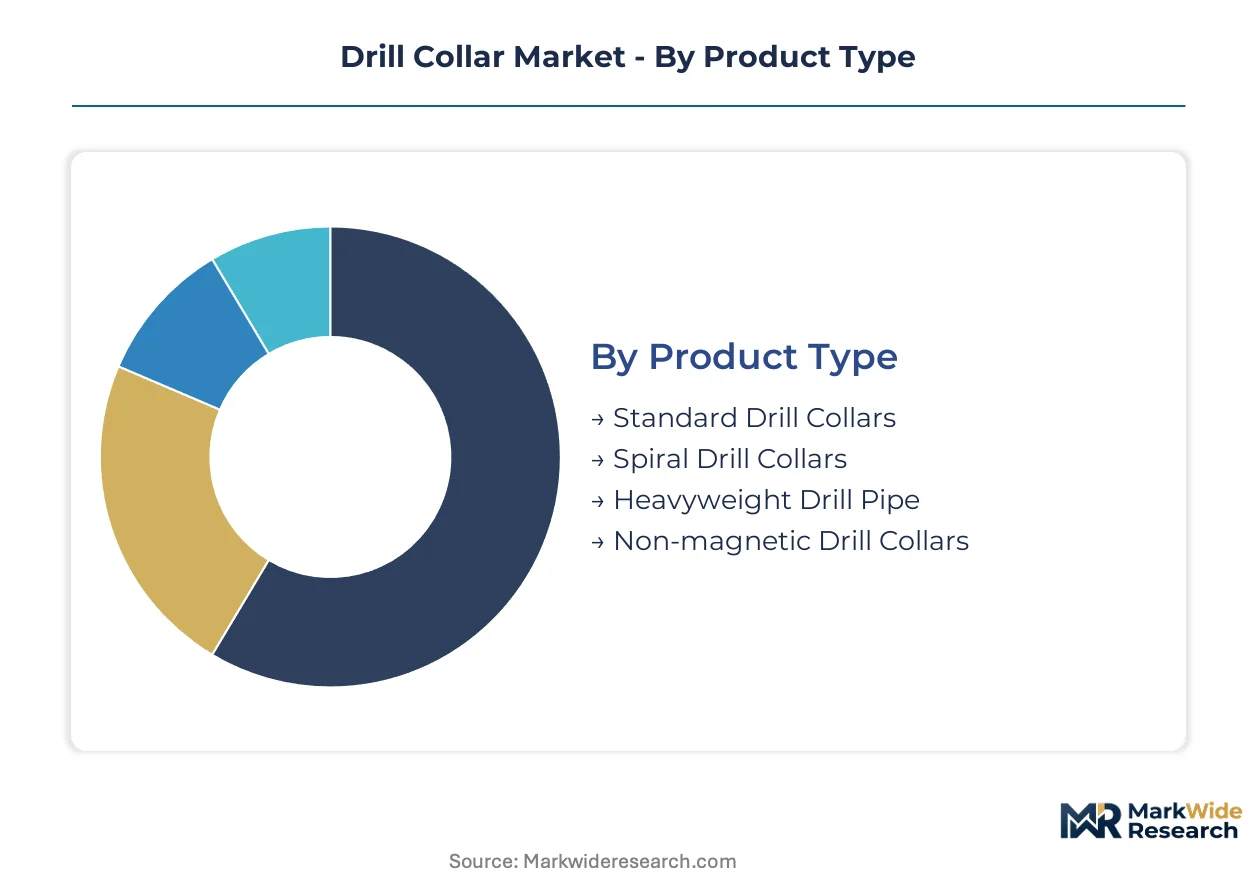
Drill collar procurement patterns diverge sharply across product configurations and end-use applications. Replacement cycle timing, material specification requirements, and directional drilling intensity create distinct demand profiles that reshape supplier priorities.
Product Type:
Upgrade cycles accelerate where differential sticking risks and measurement-while-drilling compatibility reshape operator specifications.
- Standard Drill Collars:AISI 4145H modified alloy steel construction dominates vertical well programs across the Middle East and onshore United States. Demand concentrates in cost-sensitive markets where API 7-1 compliance satisfies operator requirements without material premiums.
- Spiral Drill Collars:Grooved outer profiles reduce formation contact area in high-angle wells. The Permian Basin's horizontal drilling intensity sustains replacement demand where differential sticking incidents compress procurement cycles.
- Heavyweight Drill Pipe:Transitional weight specifications bridge standard collars and drill pipe in extended-reach applications.
- Non-magnetic Drill Collars:Stainless steel alloys enable measurement-while-drilling tool compatibility in directional programs.
Volume placements concentrate in Standard Drill Collars; the faster expansion belongs to Non-magnetic Drill Collars.
End User:
Cost tier differentiation separates commodity procurement from premium specification markets across energy extraction verticals.
- Oil & Gas Industry:Offshore exploration programs in the Gulf of Mexico command premium non-magnetic and spiral configurations. EPA methane emissions rules accelerate drilling efficiency investments that favor connection-reliable collar specifications.
- Geothermal Energy:High-temperature well programs in the western United States divert manufacturing capacity from conventional oilfield channels. Bottom-hole temperatures exceeding 300°F require corrosion-resistant stainless specifications.
- Mining Industry:Blast hole and exploration drilling drives standard steel demand with shorter asset life cycles.
- Water Well Drilling:Municipal and agricultural groundwater projects prioritize cost-minimized standard configurations.
Procurement value concentrates in Oil & Gas; Geothermal Energy climbs the fastest as a demand vertical.
Material:
Application severity and magnetic interference tolerance dictate material selection across drilling environments.
- Steel:AISI 4145H modified bar stock anchors volume production for vertical wells. Scrap metal and molybdenum price volatility compress mill margin predictability in standard specification markets.
- Alloy:Enhanced yield strengths exceeding 110 ksi serve high-pressure hydrogen sulfide environments. Hydrogen embrittlement risks in sour gas service constrain collar life and necessitate expensive upgrades beyond baseline specifications.
- Composite:Lightweight alternatives address specialized coiled tubing and workover applications.
- Titanium:Extreme corrosion resistance commands niche deployment in ultra-sour environments.
Production tonnage concentrates in Steel; Alloy specifications gain share fastest in directional and sour service programs.
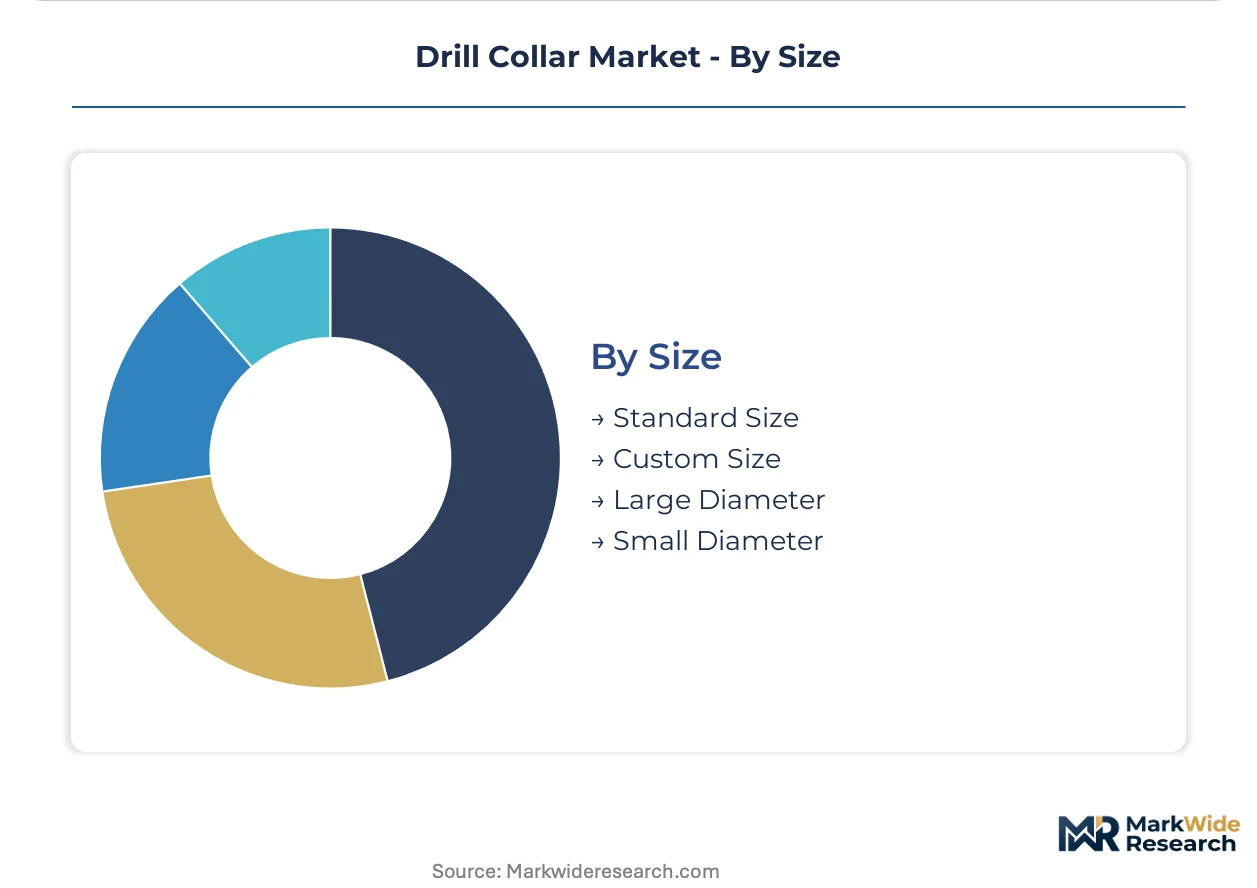
Size:
Customer type and well architecture complexity drive diameter specification clustering.
- Standard Size:Three to twelve inch outer diameters satisfy conventional rotary drilling programs. API 7-1 dimensional tolerances govern interchangeability with decades-old pipe inventories.
- Large Diameter:Extended-reach and ultra-deep wells require enhanced stiffness for weight-on-bit transmission.
- Custom Size:Managed pressure drilling and specialized bottom-hole assemblies demand non-standard configurations.
- Small Diameter:Slim-hole exploration and workover applications prioritize maneuverability over compressive load capacity.
Shipment volumes concentrate in Standard Size; Custom Size specifications expand most quickly in integrated drill string packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in oil-producing regions concentrate manufacturing capacity and drive procurement clustering for premium drill collar specifications.
United States
Horizontal drilling intensity in the Permian Basin compresses replacement cycles for heavyweight drill pipe configurations. EPA methane emissions rules accelerate drilling efficiency investments that favor connection-reliable collar specifications. Houston anchors the Gulf of Mexico offshore supply chain where integrated drill string packages dominate procurement.
Saudi Arabia
High-pressure sour gas development programs command alloy specifications exceeding standard AISI 4145H yield strengths. The country's national oil company drives material traceability requirements that align with API 7-1 revision cycles. Dhahran-based fabrication clusters serve offshore exploration in the Arabian Gulf with premium non-magnetic configurations.
China
Domestic shale development in Sichuan-Chongqing tight gas formations sustains volume demand for standard steel collars. GB standards and MIIT industrial policy shape local certification requirements for oilfield equipment suppliers. Tianjin and Shanghai manufacturing bases export spiral and non-magnetic configurations to Southeast Asian drilling contractors.
Norway
North Sea directional drilling programs require measurement-while-drilling compatibility that commands non-magnetic material premiums. EU Green Deal methane intensity standards favor drilling contractors using premium collars that reduce connection leaks and non-productive time. Stavanger clusters subsea technology suppliers serving extended-reach wells in harsh environment fields.
Brazil
Pre-salt ultra-deepwater development drives demand for large-diameter collars with enhanced stiffness for weight-on-bit transmission. ANVISA and environmental licensing requirements shape equipment import protocols for offshore contractors. Rio de Janeiro anchors the national oil company's supply chain coordination for floating production drilling programs.
Drill Collar Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service companies controlling premium offshore channels while regional forgers serve cost-sensitive onshore markets. The structure concentrates around three tiers: full-service drill string packagers, specialized collar manufacturers with heat-treatment capabilities, and commodity forgers supplying standard API specifications. Capacity expansion and strategic partnerships dominate competitive moves as players respond to API 7-1 traceability mandates.
Among US-based integrated service providers, Hunting PLC and National Oilwell Varco occupy positions that exemplify the full-service archetype through bundled equipment offerings. Schlumberger anchors the digital-enabled tier with sensor-integrated collar systems. Chinese fabricators including China Vigor Drilling Oil Tools and Equipment Co Ltd represent the scale-driven export segment serving emerging market drilling contractors.
| Leading Market Players |
|---|
| Workstrings International |
| Hunting PLC |
| National Oilwell Varco |
| Schlumberger |
| International Drilling Services Ltd |
| American Oilfield Tools |
| Texas Steel Conversion Inc |
| China Vigor Drilling Oil Tools and Equipment Co Ltd |
| Weatherford International |
| Others |
Cost & Logistics Intelligence
API 7-1 specification revisions forcing material traceability system upgrades are compressing margins for standard collar forgers while amplifying pricing power for certified premium suppliers. Buyers now face extended lead times and qualification costs that stratify procurement budgets across compliance tiers.
Pricing Analysis
Expedited delivery premiums dominate contract negotiations as operators compress drilling schedules to meet EPA methane emissions compliance deadlines. Three-tier pricing structure across premium non-magnetic, standard spiral, and economy vertical-well configurations reflects certification grade and heat-treatment documentation depth. Cost compression in standard steel collars is intensifying because Chinese export capacity floods spot markets. Mining contractors and agricultural water-well drillers exhibit highest price sensitivity; Gulf of Mexico offshore contractors accept material premiums for integrated drill string packages with performance guarantees.
Supply Chain Analysis
Direct-to-drilling-contractor channels handle integrated package demand from major Gulf of Mexico operators, while distributor networks serve spot procurement for replacement cycles. Manufacturing gravity centers on Ohio and Pennsylvania open-die forgers, Tianjin and Shanghai export fabricators, and Dhahran-based premium specialists. The supply chain draws from AISI 4145H modified bar stock, molybdenum alloying elements, and non-magnetic stainless steel feedstock. Single-source forging concentration in the US Midwest creates geographic supply vulnerability. Distribution runs through oilfield service company rental fleets and managed-pressure-drilling contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified heat-treatment capacity scarcity props pricing for API 7-1 compliant suppliers, creating durable margin structures for incumbents with traceability infrastructure already deployed.
For Market Incumbents: Extend digital twin-enabled fatigue monitoring subscriptions to capture recurring revenue from collar replacement forecasting. Defend against Hunting PLC and National Oilwell Varco integrated package competition by certifying alternative REACH-compliant surface coatings that eliminate hexavalent chromium conversion treatments. Backward integration into specialized open-die forging secures capacity amid Ohio and Pennsylvania supplier concentration. For New Entrants and Emerging Players: Enter via Iceland and Kenya geothermal drilling programs where established collar supply chains remain underdeveloped. Target high-temperature well specifications exceeding 300°F bottom-hole temperatures in the western United States where corrosion-resistant stainless alloys command material premiums. Partner with directional drilling contractors in the North Sea requiring measurement-while-drilling compatibility to bypass incumbent rental fleet relationships. For Investors and Strategic Acquirers: Re-rating potential sits with API-certified manufacturers possessing heat-treatment documentation infrastructure given ongoing 7-1 revision cycles. Long-term viability favors specialists with geothermal energy drilling exposure diverting capacity from oilfield service channels. Monitor ultrasonic inspection technician recruitment rates as an inflection indicator for quality compliance bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| API 7-1 Certification Investment | Material traceability documentation satisfies operator audit requirements and commands contract premiums. |
| Geothermal Capacity Diversification | High-temperature well programs in Kenya and Iceland open parallel revenue streams beyond oilfield channels. |
| Digital Twin Integration | Sensor-enabled collar fatigue monitoring extends replacement intervals into subscription revenue models. |
| REACH-Compliant Coating Certification | Alternative passivation processes maintain thread galling resistance for European operator procurement. |
| Ultrasonic Inspection Technician Training | Certified NDT specialist pipelines address API 7-1 tightened defect detection protocol requirements. |
Research Approach
Independent corroboration across drilling contractor procurement directors, open-die forging plant managers, and oilfield equipment distribution channel partners underwrites the qualitative findings. Primary fieldwork included interviews with API certification auditors, geothermal project developers in the western United States, and North Sea directional drilling operators. Secondary validation drew from API specification revision documentation, EPA methane emissions rulemaking records, ISO 11960 quality management protocols, and customs trade data for AISI 4145H bar stock imports. Bottom-up shipment data from collar manufacturers triangulates against top-down drilling activity metrics from operator capital expenditure disclosures.
Rate-of-change decomposition separates volume drivers by product configuration, material specification, end-use vertical, and regional drilling intensity across the projection horizon. Segmentation modeling incorporates drill collar type, material grade tier, end-user industry, and size specification dimensions. CAGRs derive from replacement cycle compression analysis in horizontal drilling programs and capacity diversion trends into geothermal applications. Forecast inputs include Permian Basin rig count trajectories and EU Green Deal methane intensity standard implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alloy steel input volatility and single-source forging disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Coal Mining Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Shale Shakers Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
LNG Storage Tank Market