
 Drone Wind Turbine Blade Inspection Market | 2026-2036
Drone Wind Turbine Blade Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Wind Turbine Blade Inspection Market Insights
Asset-light leasing models for drone inspection fleets is narrowing the capital barrier for regional service providers seeking entry into wind farm maintenance contracts. SZ DJI Technology Co., Ltd. leverages its manufacturing scale to dominate consumer-to-commercial platform transitions. SkySpecs, Inc. anchors its position through specialized autonomous flight software purpose-built for turbine proximity operations. Cyberhawk Innovations Limited differentiates by controlling the full data-to-insight workflow for utility-scale asset managers.
Drone wind turbine blade inspection encompasses unmanned aerial systems equipped with stabilized sensor payloads that capture surface and subsurface structural data from rotating or static blades, typically operating at distances under 15 meters with centimeter-scale positioning accuracy. The primary industrial purpose is to detect leading-edge erosion, lightning damage, delamination, and adhesive joint fatigue before catastrophic failure occurs. Visual inspection and thermal inspection modalities currently lead deployment volumes, though 3D mapping is capturing expanding share where digital twin integration drives repeat-service value. Subscription services are emerging as the fastest-growing service model as wind farm operators shift from episodic damage response toward continuous condition monitoring.
FAA Part 107 and beyond-visual-line-of-sight waiver frameworks shape operational parameters for US-based inspection providers, while EASA drone regulation harmonizes certification standards across European member states. The EU Green Deal's offshore wind targets are forcing national regulators to streamline airspace integration for automated turbine surveys. Stakeholders must monitor evolving detect-and-avoid mandates and sensor payload certification requirements that will determine which hardware-software combinations qualify for utility procurement.
Market Dynamics
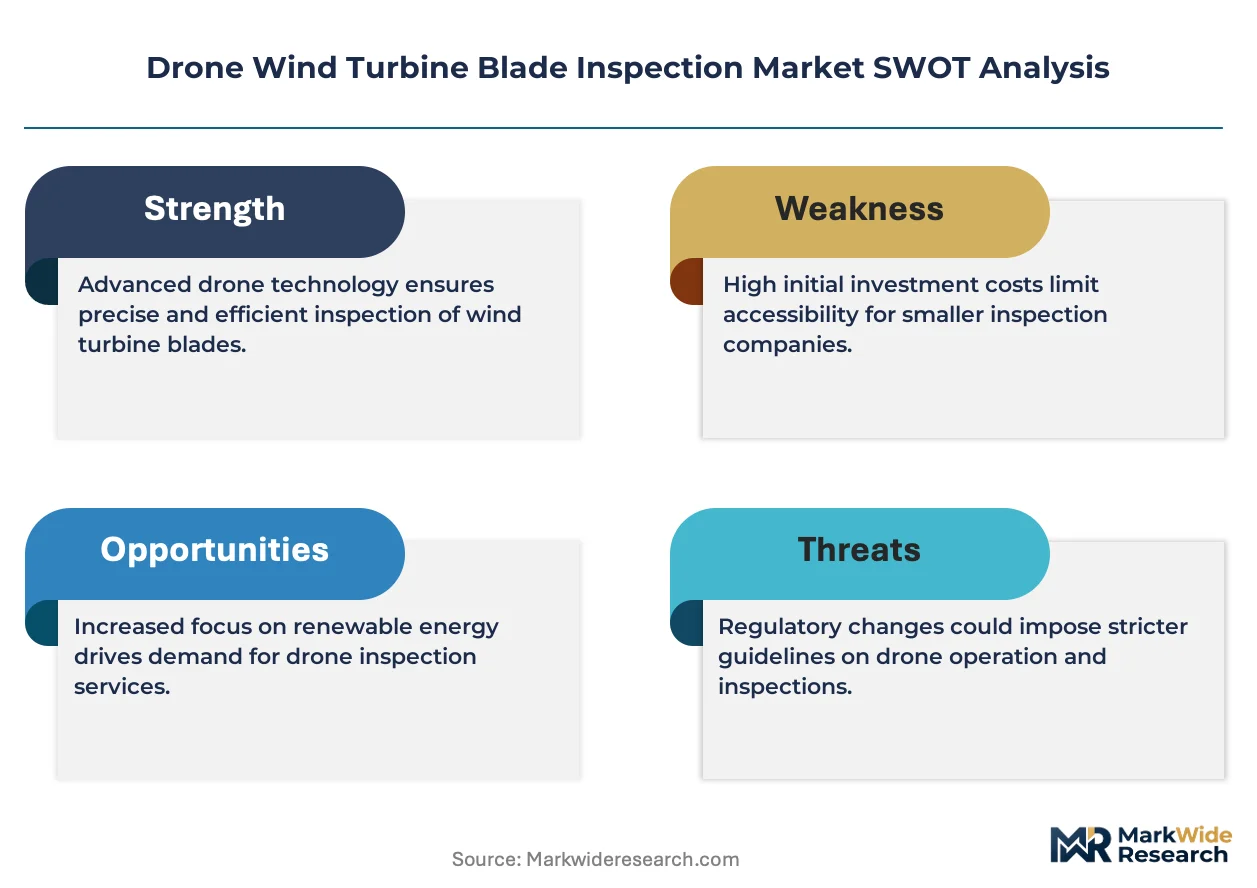
Offshore wind farm operators are consolidating inspection procurement around autonomous drone platforms that eliminate rope-access technician deployment, compressing survey cycles from weeks to hours while satisfying EU Green Deal-mandated structural monitoring protocols.
Growth Catalysts
- EU Green Deal Offshore Targets:The European Commission's binding renewable capacity mandates force national regulators to automate blade monitoring across North Sea wind clusters.
- Lightning Damage Detection:Thermal imaging payloads now identify conductive path degradation before catastrophic blade failure, driving replacement demand from German and Danish operators.
- Beyond-Visual-Line-of-Sight Waivers:FAA Part 107 exemptions in the United States enable single-operator coverage of multi-turbine arrays without ground crew repositioning.
Market Restraints
- Sensor Payload Certification Bottlenecks:EASA's evolving type-certification requirements for stabilized gimbal systems delay hardware deployment across European waters.
- Lithium-Ion Battery Supply Concentration:Cell manufacturing concentrates in East Asian suppliers, exposing inspection fleet operators to input cost volatility and logistics disruption.
- Optical Limitations in Precipitation:Visual and thermal modalities degrade below operational thresholds in North Sea marine conditions, forcing weather-dependent scheduling.
Strategic Opportunities
- Digital Twin Integration:3D mapping convergence with blade asset management software creates recurring subscription revenue from repeat-scan comparison analytics.
- United Kingdom Round 4 Leasing:Crown Estate seabed allocations for floating offshore wind expand addressable turbine populations requiring specialized proximity flight protocols.
- Subscription Service Migration:Continuous condition monitoring contracts displace episodic damage response, locking multi-year revenue from German utility-scale operators.
Industry Challenges
- Detect-and-Avoid System Integration:Automated turbine proximity operations require real-time obstacle mapping that exceeds current off-the-shelf collision avoidance hardware capabilities.
- Data-to-Insight Pipeline Bottlenecks:Utility asset managers face analyst shortages capable of interpreting thermographic delamination signatures at fleet-scale throughput.
- Legacy SCADA System Interoperability:Blade condition data feeds encounter protocol incompatibilities with existing wind farm management platforms, forcing middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Wind Turbine Blade Inspection Market |
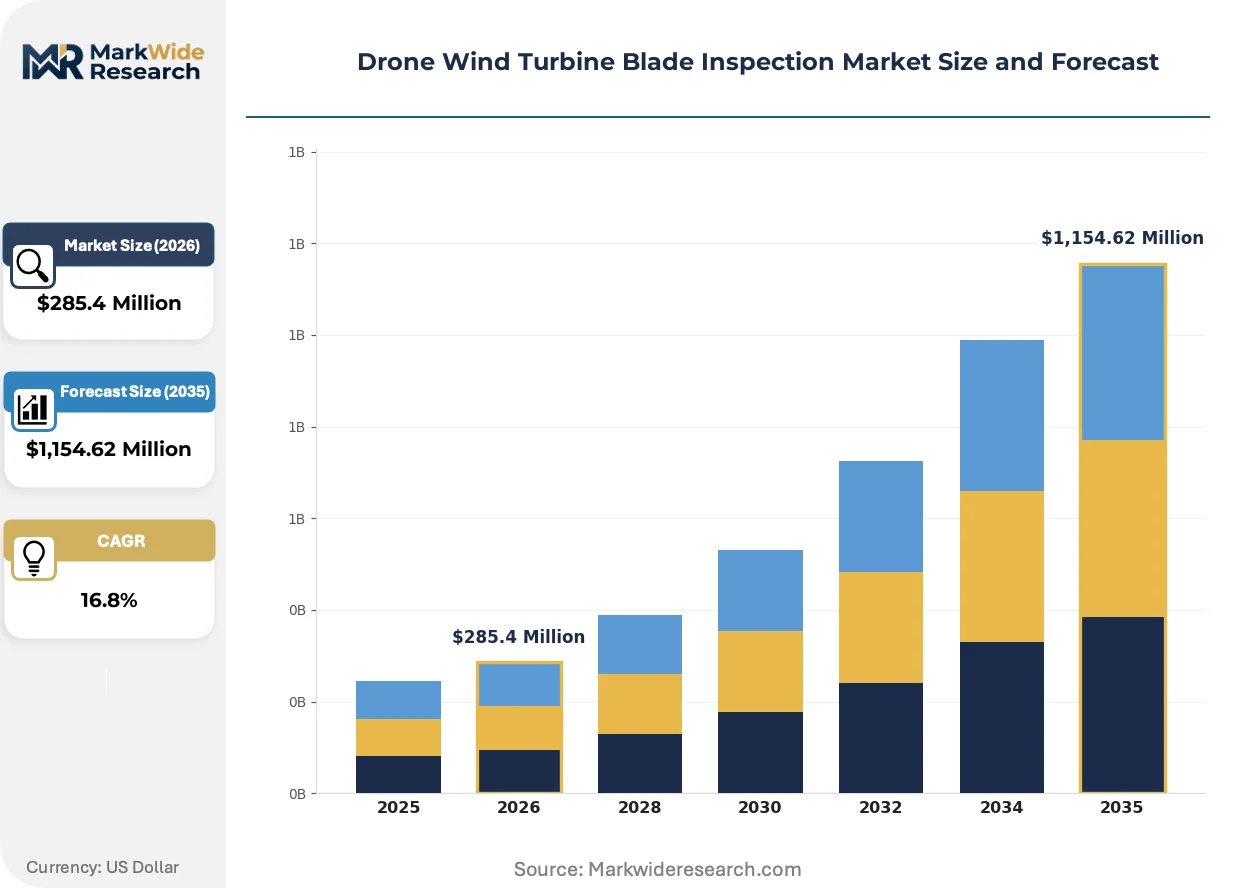
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Inspection Type: Visual Inspection, Thermal Inspection, Ultrasonic Inspection, 3D Mapping Technology: LiDAR, RGB Cameras, Infrared Cameras, Drone-based Sensors Service Model: On-Demand Services, Subscription Services, Full-Service Agreements, Project-Based Services End User: Wind Farm Operators, Maintenance Providers, Utility Companies, Asset Managers |
| Companies Covered | Percepto Ltd., AeroVironment, Inc., SZ DJI Technology Co., Ltd., Acecore Technologies, Voliro, SkySpecs, Inc., PrecisionHawk, Inc., GEV Wind Power, Cyberhawk Innovations Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Wind Turbine Blade Inspection Market Trends and Innovations
Sensor fusion architectures and autonomous flight software are compressing the inspection value chain, eliminating pilot-in-the-loop requirements while embedding predictive analytics directly into turbine maintenance workflows.
Photogrammetry-based 3D reconstruction is virtualizing physical blade inventories into geometrically precise digital assets. Offshore wind farm operators in Denmark and Germany are deploying these models at quarterly intervals. The technology is virtualizing traditional manual measurement protocols and enabling crack-propagation tracking without repeat climbs.
EASA drone regulation harmonization is standardizing certification pathways across European member states. The framework reduces type-approval duplication costs for inspection hardware manufacturers. Offshore wind clusters in the North Sea benefit most, with operators consolidating procurement around cross-border qualified platform vendors.
Asset-light leasing models are fragmenting buyer concentration across regional service providers. Smaller maintenance contractors now access enterprise-grade drone fleets without capital deployment. This pattern concentrates in the United Kingdom, where Crown Estate leaseholders face compressed O&M budget cycles.
Drone Wind Turbine Blade Inspection Market Segmentation
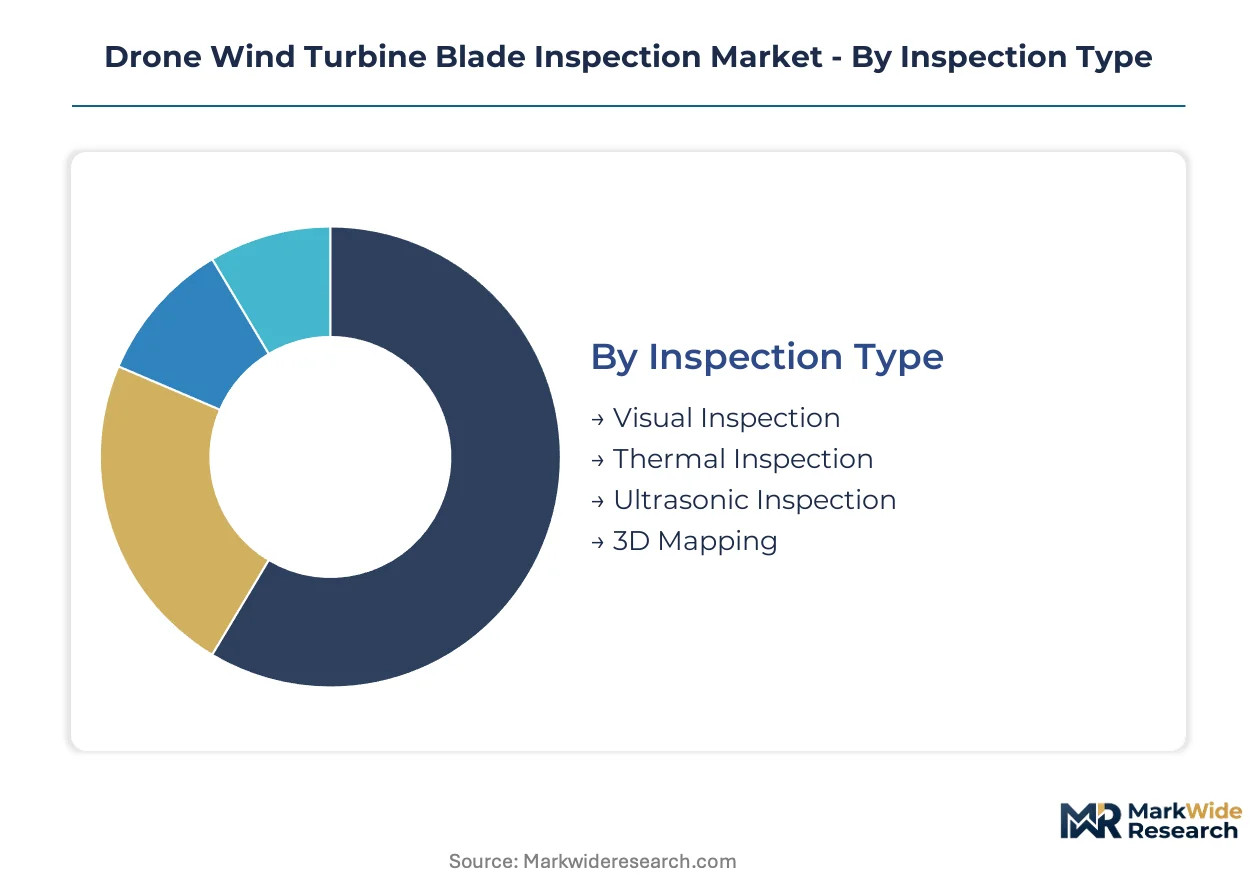
Drone turbine inspection vendors configure service portfolios around blade condition severity and operator O&M maturity. Segment boundaries determine hardware payload selection, flight autonomy levels, and recurring revenue capture.
Inspection Type:
After-sales intensity varies sharply across modalities, with thermal and 3D mapping demanding continuous algorithm updates and analyst interpretation support.
- Visual Inspection:RGB camera payloads capture surface defects including leading-edge erosion and lightning strike entry points at sub-centimeter resolution. German and Danish offshore clusters deploy this modality for routine screening cycles, though precipitation limitations in North Sea conditions constrain scheduling windows.
- Thermal Inspection:Infrared sensors detect subsurface delamination and adhesive joint fatigue through thermal gradient anomalies. United Kingdom Round 4 leaseholders are consolidating procurement around thermal-first protocols for floating offshore arrays where rope access proves prohibitively expensive.
- Ultrasonic Inspection:Contact-based thickness measurement requires specialized landing platforms or robotic arm deployment, limiting applicability to static turbine conditions.
- 3D Mapping:Photogrammetry reconstruction enables crack propagation tracking through repeat-scan comparison analytics.
By volume, Visual Inspection leads. By growth pace, 3D Mapping is ahead.
Technology:
Cost tier separation runs from commodity RGB sensors to precision LiDAR units requiring EASA type certification.
- LiDAR:Laser scanning generates millimeter-accurate point clouds for geometric deviation analysis in blade manufacturing quality control and in-service deformation monitoring. Premium pricing reflects stabilization gimbal complexity and detect-and-avoid integration requirements.
- RGB Cameras:Stabilized visible-spectrum imaging dominates fleet deployment volumes through DJI platform compatibility and FAA Part 107 operational simplicity.
- Infrared Cameras:Uncooled microbolometer arrays identify conductive path degradation from lightning damage before catastrophic failure.
- Drone-based Sensors:Integrated payload architectures combine multiple modalities with edge computing for real-time defect classification.
RGB Cameras capture the largest installed base. LiDAR claims the steepest expansion trajectory among premium tiers.
Service Model:
Customer type determines contract structure, with utility-scale operators migrating from transactional damage response toward integrated condition monitoring.
- On-Demand Services:Episodic deployment following severe weather events or suspected damage reports. Regional maintenance contractors in the United Kingdom favor this structure for Crown Estate leaseholders with compressed capital cycles.
- Subscription Services:Quarterly or monthly inspection schedules with guaranteed analyst throughput and trending analytics. German utility-scale operators are locking multi-year agreements to satisfy EU Green Deal structural monitoring mandates.
- Full-Service Agreements:Integrated hardware, flight operations, and maintenance decision support bundled under single-vendor accountability.
- Project-Based Services:Finite-scope deployment for pre-construction blade inventory documentation or warranty dispute resolution.
On-Demand Services retain the largest transaction count. Subscription Services are gaining share fastest as procurement consolidates around continuous monitoring.
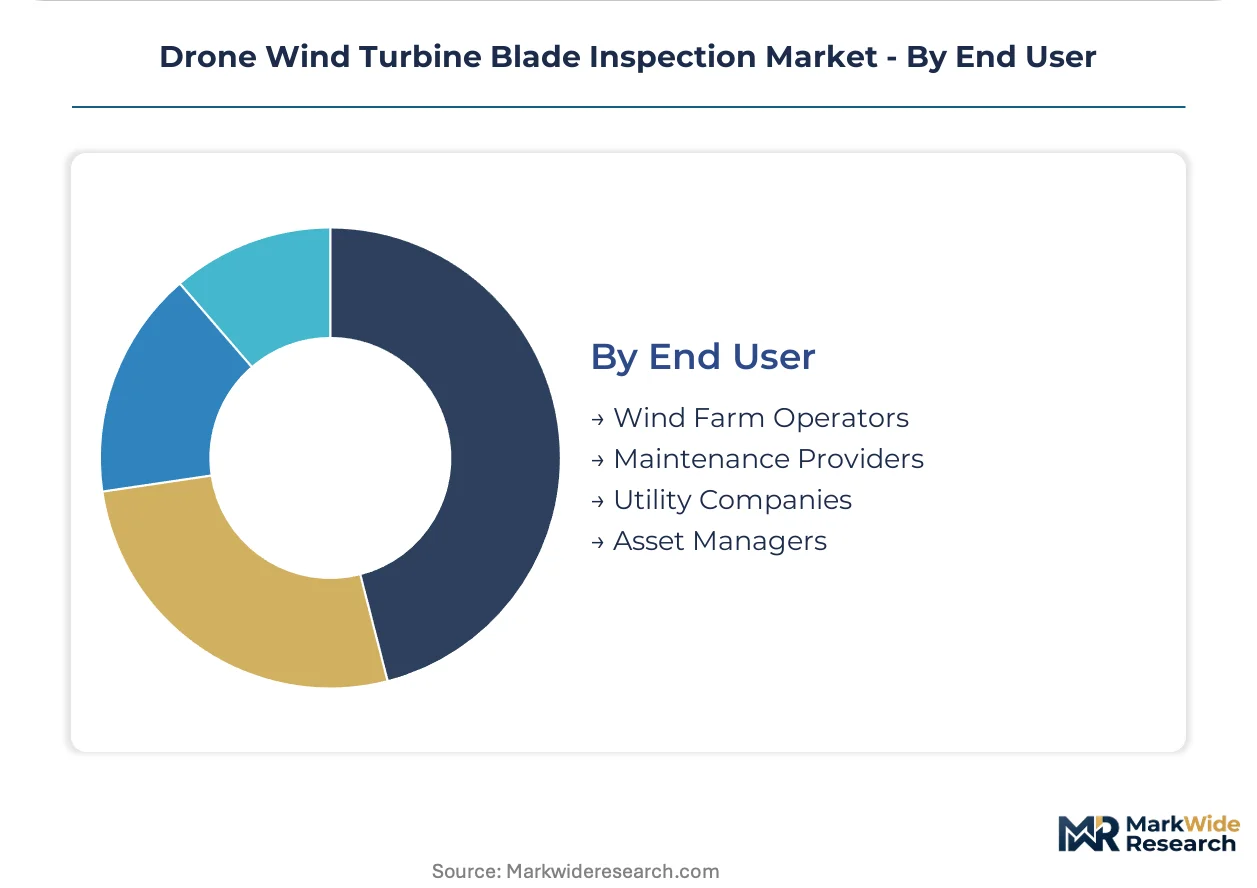
End User:
Application context shapes payload requirements and data delivery formats, from operational uptime prioritization to financial asset valuation.
- Wind Farm Operators:Direct owners prioritize turbine availability metrics and integrate inspection data with existing SCADA maintenance workflows. Offshore operators in Denmark and Germany are standardizing autonomous drone protocols to eliminate technician deployment risks.
- Maintenance Providers:Third-party service contractors require platform versatility across multiple turbine OEM specifications and leaseholder reporting standards.
- Utility Companies:Integrated energy majors demand fleet-scale analytics and regulatory compliance documentation for Green Deal reporting.
- Asset Managers:Financial owners utilize inspection data for residual value assessment and insurance premium negotiation.
Wind Farm Operators account for the dominant procurement volume. Asset Managers are expanding most quickly as institutional ownership of renewable infrastructure deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's binding offshore wind targets are forcing automation mandates across North Sea jurisdictions. National regulators in Germany, Denmark, and the United Kingdom are streamlining airspace integration for turbine proximity operations. This policy pressure concentrates procurement in waters where rope-access technician costs prove prohibitive.
Germany
Utility-scale operators in the North Sea and Baltic Sea clusters are consolidating procurement around autonomous drone protocols. The Federal Aviation Office harmonizes operational waivers with EASA drone regulation to accelerate fleet deployment. Industrial concentration centers on Hamburg and Bremerhaven, where port infrastructure supports offshore maintenance logistics for blade inspection service providers.
United Kingdom
Crown Estate Round 4 seabed allocations for floating offshore wind are expanding addressable turbine populations requiring specialized flight operations. The Civil Aviation Authority processes beyond-visual-line-of-sight exemptions for multi-turbine array coverage. Scottish waters host concentrated floating wind pilot projects where drone-based structural monitoring displaces traditional technician deployment.
Denmark
Ørsted and Vestas supply chain proximity creates integrated demand for blade condition data feeding into manufacturing quality feedback loops. The Danish Transport Authority maintains streamlined certification pathways for stabilized sensor payloads. The Port of Esbjerg anchors North Sea logistics, with regional service providers leasing enterprise-grade drone fleets under asset-light models.
United States
Great Plains wind operators and Texas Gulf Coast offshore leaseholders are adopting FAA Part 107 waiver frameworks for automated turbine surveys. The Federal Aviation Administration processes detect-and-avoid system exemptions enabling single-operator coverage of multi-turbine arrays. Oklahoma and Iowa host concentrated onshore wind clusters where episodic damage response is migrating toward continuous condition monitoring contracts.
China
Dual carbon goals and provincial renewable capacity targets are accelerating domestic drone inspection platform development. The Civil Aviation Administration of China issues operational certificates for offshore wind proximity flights in Jiangsu and Guangdong waters. The Yangtze River Delta concentrates manufacturing scale for lithium-ion battery supply feeding inspection fleet operators.
Drone Wind Turbine Blade Inspection Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with utility-scale wind farm operators. The vendor base organizes around three strategic archetypes: manufacturing-scale platform vendors, specialized autonomous flight software developers, and full-service data-to-insight workflow controllers. Competitive positioning hardens through M&A activity targeting sensor payload certification capabilities and strategic partnerships securing beyond-visual-line-of-sight operational waivers.
Among autonomous flight specialists, SkySpecs, Inc. and Cyberhawk Innovations Limited exemplify the software-centric archetype, while SZ DJI Technology Co., Ltd. anchors the manufacturing-scale tier. These three entities occupy distinct competitive positions without overlapping core capabilities. The specialized players represent pure-play exposure to turbine proximity automation, whereas the manufacturing-scale entity controls hardware cost curves across multiple industrial applications.
| Leading Market Players |
|---|
| Percepto Ltd. |
| AeroVironment, Inc. |
| SZ DJI Technology Co., Ltd. |
| Acecore Technologies |
| Voliro |
| SkySpecs, Inc. |
| PrecisionHawk, Inc. |
| GEV Wind Power |
| Cyberhawk Innovations Limited |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Esbjerg maritime freight corridors govern lithium-ion battery logistics costs for European inspection fleet operators, compressing hardware margins while amplifying price spreads between EASA-certified and uncertified sensor payloads. This corridor dynamic concentrates procurement power among German and Danish wind farm operators who negotiate volume-scale subscription discounts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with EASA type-certified gimbal systems commanding subscription premiums over FAA Part 107-compliant alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and analyst throughput guarantees. Cost compression in the economy tier intensifies because asset-light leasing models fragment buyer concentration among regional UK maintenance contractors. Utility-scale operators in Germany demonstrate lowest price sensitivity due to EU Green Deal compliance mandates, while Crown Estate leaseholders in the United Kingdom exhibit highest sensitivity amid compressed O&M budget cycles.
Supply Chain Analysis
Export control restrictions on stabilized imaging components limit flows from US and Japanese suppliers to Chinese drone platform integrators, elongating certification timelines for integrated payload architectures. Hardware manufacturing concentrates in China, South Korea, and Taiwan, with lithium-ion cell production anchored in the Yangtze River Delta. Stabilized gimbal assemblies and uncooled microbolometer arrays constitute critical input dependencies. Single-source vulnerability runs through East Asian battery suppliers exposed to logistics disruption. Distribution runs through port-centric logistics hubs at Bremerhaven, Esbjerg, and Hull serving North Sea wind clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward utility-scale wind farm operators as procurement consolidates around multi-year subscription contracts, fragmenting regional service provider margins. German and Danish operator consolidation around autonomous protocols accelerates this concentration.
For Market Incumbents: Build regulatory certification moats through EASA detect-and-avoid system approvals before hardware mandates tighten. Deepen sensor payload certification capabilities through targeted R&D investment in thermal imaging algorithms. Acquire specialist autonomous flight software developers to defend against pure-play automation entrants. Secure beyond-visual-line-of-sight operational waivers in UK and German jurisdictions to lock out challenger platforms. For New Entrants and Emerging Players: Floating offshore wind arrays in UK Round 4 lease areas represent the most penetrable entry point given specialized proximity flight protocol requirements unmet by incumbent tooling. Asset-light leasing models for regional maintenance contractors in Scotland and Wales offer second-tier white-space access. Partner with Crown Estate leaseholders facing compressed capital cycles to establish reference accounts before utility-scale procurement consolidation hardens. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant drone inspection divisions lacking turbine-specific flight software. Long-term viability centers on digital twin integration capabilities and recurring subscription revenue capture rather than transactional inspection volumes. Monitor EASA detect-and-avoid mandate implementation timelines as inflection indicator for platform consolidation windows. Material acceleration in FAA Part 107 waiver processing velocity would signal expanded addressable market for autonomous specialists.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Detect-and-Avoid Certification | Qualifies hardware-software combinations for utility procurement across German and Danish waters. |
| Digital Twin Platform Integration | Locks multi-year subscription revenue from Ørsted and Vestas supply chain proximity. |
| Beyond-Visual-Line-of-Sight Waiver Expansion | Enables single-operator coverage of multi-turbine arrays in UK Round 4 floating wind zones. |
| Sensor Payload Certification Investment | Accelerates type-approval timelines constrained by evolving EASA gimbal requirements. |
| Asset-Light Leasing Model Deployment | Fragments buyer concentration among regional UK contractors facing Crown Estate budget pressures. |
Research Methodology
Desk research of EASA regulatory filings, FAA waiver databases, and Crown Estate lease documentation preceded structured interviews with offshore wind farm operations directors, drone fleet procurement managers, and autonomous flight software engineers. Primary fieldwork with utility-scale operators in Germany, Denmark, and the United Kingdom validated secondary data on subscription contract structures and sensor payload deployment patterns. Bottom-up triangulation across inspection volume estimates and top-down cross-checks against EU Green Deal capacity targets anchored market sizing.
Assumptions held fixed include EASA regulatory harmonization timelines and lithium-ion battery cost curves, while variables tested included FAA waiver processing velocity and floating offshore wind deployment rates. Segmentation modeling spanned inspection modality, service model maturity, and end-user procurement sophistication across the projection horizon. CAGRs derived from installed base expansion in North Sea clusters and replacement demand from lightning damage detection protocols. Forecast inputs incorporated SCADA integration penetration rates and analyst throughput constraints.
Practitioners should monitor EASA detect-and-avoid mandate finalization and FAA Part 107 regulatory reinterpretation for early signals of platform qualification shifts. Forecasts reflect these assumption sets without contingency for abrupt regulatory reversal. Material shifts in EU Green Deal offshore wind capacity commitments or East Asian battery supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
United Kingdom Wind Energy Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market