
 Wellhead Equipment Market | 2026-2036
Wellhead Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wellhead Equipment Market Intelligence
API 6A is realigning the cost-of-entry calculus for wellhead equipment suppliers by mandating enhanced material traceability and pressure-testing protocols. TechnipFMC leverages its integrated subsea production systems to anchor long-term contracts with deepwater operators. Baker Hughes competes through advanced metallurgy capabilities that sustain performance in high-pressure high-temperature reservoirs. National Oilwell Varco dominates land-based wellhead replacement cycles across North American shale basins.
Wellhead equipment comprises the surface and subsurface assemblies that suspend casing strings, seal annular spaces, and control pressure during drilling and production operations, typically manufactured from chrome-molybdenum alloy steel rated for pressures exceeding 15,000 psi. Christmas trees represent the most technically complex product category, with margin pools concentrating in subsea configurations that integrate hydraulic control systems and blowout preventers. Offshore application demand is outpacing onshore growth, driven by pre-salt and deepwater field developments where wellhead integrity failures carry catastrophic cost exposure. Steel remains the dominant material specification, though alloy adoption is accelerating in HPHT wells where sulfide stress cracking resistance determines field life.
The US Bureau of Safety and Environmental Enforcement enforces well control regulations that mandate blowout preventer redundancy and real-time monitoring capabilities, while Norway's Petroleum Safety Authority imposes functional safety standards that shape subsea equipment design specifications. Brazil's national petroleum regulator requires local content thresholds that influence supplier qualification and manufacturing location decisions for pre-salt projects. Stakeholders must monitor regulatory divergence between deepwater jurisdictions to align certification investments with contract eligibility requirements.
Market Dynamics
Deepwater operators are forcing a structural recalibration of supplier capabilities as pre-salt and HPHT reservoirs demand wellhead systems rated beyond 20,000 psi with integrated monitoring architectures.
Growth Catalysts
- Brazil's pre-salt expansion:Petrobras-led developments in the Santos Basin are accelerating procurement of subsea wellhead assemblies with enhanced fatigue resistance specifications.
- API 6A certification tightening:Material traceability mandates are elevating qualification barriers, concentrating contract awards among suppliers with captive forging and heat-treatment capabilities.
- Shale infrastructure replacement:Permian and Bakken operators are retiring 15-year-old wellhead installations, creating recurring demand for high-pressure-rated Christmas trees and casing heads.
Market Restraints
- Alloy steel price volatility:Chrome-molybdenum billet costs swing with nickel and molybdenum commodity indices, compressing fabrication margins for pressure-containing components.
- Subsea supplier concentration:Deepwater wellhead system integration depends on a narrow base of manufacturers with subsea test facility access, creating single-source vulnerability for operators.
- Local content mandates:Brazil's ANP requirements force foreign suppliers to establish domestic fabrication partnerships, extending qualification timelines and capital deployment.
Strategic Opportunities
- Digital twin integration:Real-time wellhead integrity monitoring through sensor-embedded flanges is creating aftermarket service revenue streams for equipment vendors.
- West African deepwater:Senegal and Mauritania offshore developments are opening new procurement corridors for subsea production system integrators.
- Carbon capture wellhead adaptation:CO2 injection specifications are driving demand for modified sealing architectures in depleted reservoir repurposing projects.
Industry Challenges
- Weld procedure qualification bottlenecks:API 6A Section 7 welding engineer certification scarcity delays production ramp-ups for new fabrication facilities.
- Legacy system interoperability:Brownfield wellhead replacement requires custom adapter spools to mate modern BOP stacks with vintage casing programs, extending engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellhead Equipment Market |
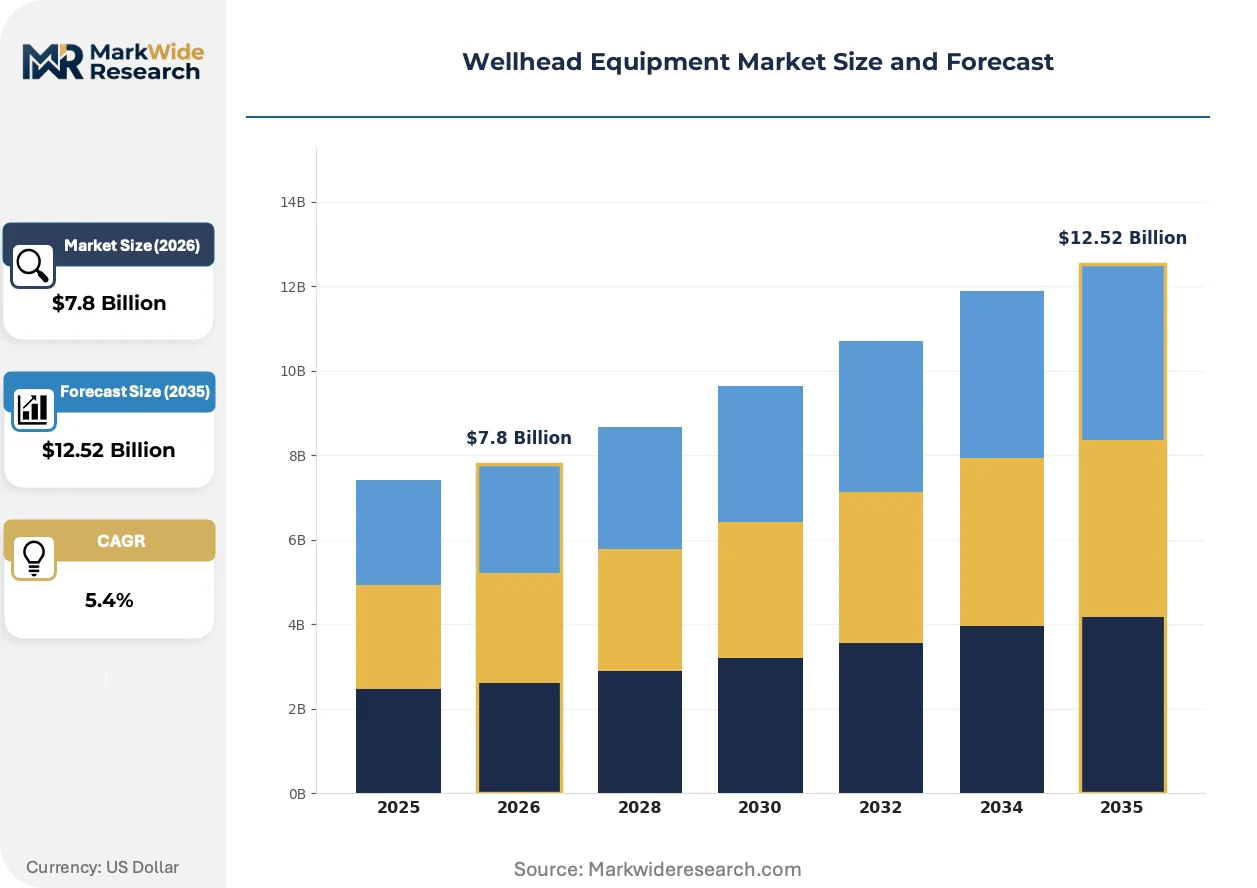
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Christmas Trees, Blowout Preventers, Control Systems, Wellhead Flanges Application: Onshore, Offshore, Enhanced Oil Recovery, Subsea End User: Oil & Gas Operators, Service Companies, EPC Contractors, Independents Material: Steel, Cast Iron, Composite, Alloy |
| Companies Covered | TechnipFMC, Weir Group, Schlumberger, Halliburton, Weatherford International, Baker Hughes, Aker Solutions, Dril-Quip, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellhead Equipment Market Strategic Shifts & Innovations
Metallurgical advances and real-time monitoring architectures are compressing the performance gap between subsea and surface wellhead reliability, while procurement patterns favor integrated system providers over component specialists.
Additive manufacturing of nickel-alloy choke components is rewriting spare parts logistics for remote offshore installations. Operators in the Norwegian North Sea are qualifying laser-powder-bed-fusion choke trim for emergency replacement scenarios. This fabrication method is compressing lead times from sixteen weeks to seventy-two hours for critical flow control elements.
The US Bureau of Safety and Environmental Enforcement is mandating dual shear ram redundancy and real-time BOP monitoring through its Well Control Rule amendments. Offshore drillers must retrofit existing subsea stacks or face operational restrictions in federal waters. Gulf of Mexico deepwater contractors are absorbing these compliance costs through five-year equipment lease restructuring.
Integrated service contracts are displacing discrete equipment purchases among capital-constrained shale operators. Permian independents now lease Christmas tree assemblies with embedded maintenance and recertification obligations. This financing structure is most pronounced among private equity-backed producers with leveraged balance sheets.
Wellhead Equipment Market Segmentation
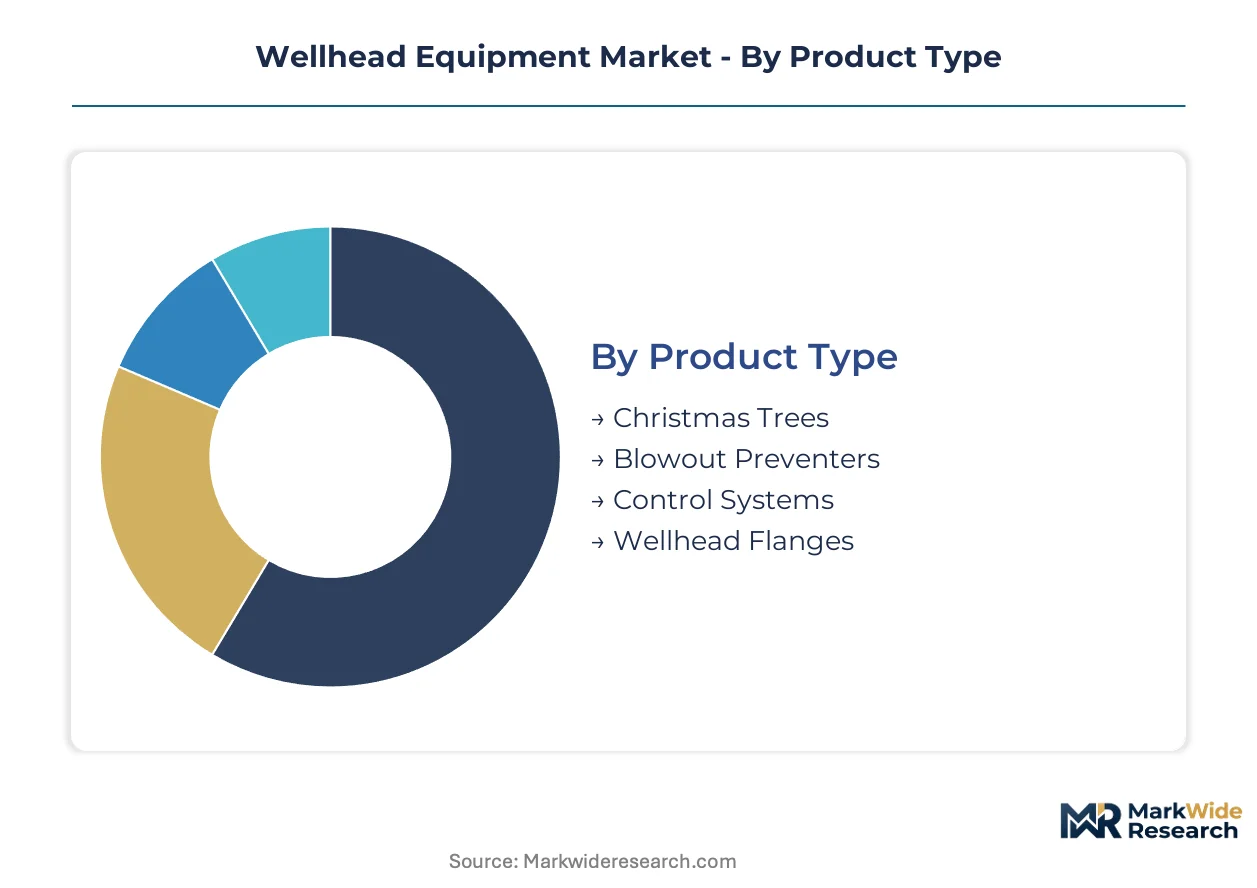
Wellhead equipment procurement patterns diverge sharply across product categories and deployment environments. API 6A certification tiers create distinct supplier qualification barriers that reshape competitive dynamics within each segment cluster.
Product Type:
API 6A certification intensity varies by product complexity, with subsea-rated assemblies demanding the most exhaustive material traceability and pressure-testing documentation.
- Christmas Trees:These assemblies integrate master valves, wing valves, chokes, and gauges to control production flow and pressure. Deepwater operators in Brazil's Santos Basin specify fatigue-resistant configurations rated beyond 20,000 psi for pre-salt developments.
- Blowout Preventers:Stack configurations with annular and ram-type preventers provide emergency well control during drilling operations. US Gulf Coast drillers face BSEE mandates for dual shear ram redundancy and real-time monitoring capabilities that elevate procurement costs.
- Control Systems:Hydraulic and electro-hydraulic units transmit commands to subsea valves and chokes.
- Wellhead Flanges:High-pressure sealing interfaces connect casing heads to BOP stacks and production trees.
Christmas Trees sit at the top of the volume ranking, with Control Systems climbing the fastest.
Application:
Capital deployment intensity scales with water depth and reservoir pressure, concentrating margin capture in frontier offshore developments.
- Offshore:Platform and subsea installations require corrosion-resistant metallurgy and integrated monitoring architectures. Norway's Petroleum Safety Authority imposes functional safety standards that shape equipment specifications for North Sea developments.
- Subsea:Seabed-deployed wellheads with remotely operated connector systems eliminate surface infrastructure. Senegal and Mauritania offshore fields are opening new procurement corridors for integrated production system providers.
- Onshore:Land-based drilling and production operations utilize simplified wellhead configurations.
- Enhanced Oil Recovery:CO2 and thermal injection applications demand modified sealing geometries.
Offshore commands the largest capital allocation per installation, while Subsea applications are expanding most quickly.
End User:
Contracting structures diverge between integrated operators with captive engineering capabilities and capital-constrained independents seeking leased equipment solutions.
- Oil & Gas Operators:Majors and national oil companies specify integrated subsea production systems with long-term service agreements. Petrobras anchors demand through pre-salt field development programs with stringent local content requirements.
- Independents:Private equity-backed shale producers favor leased Christmas tree assemblies with embedded maintenance obligations to preserve balance sheet capacity.
- Service Companies:Drilling contractors and well intervention specialists procure rental wellhead components for project-specific deployment.
- EPC Contractors:Engineering-procurement-construction firms source wellhead packages as part of integrated facility builds.
Oil & Gas Operators dominate absolute procurement volume, with Independents gaining share fastest through equipment-as-a-service adoption.
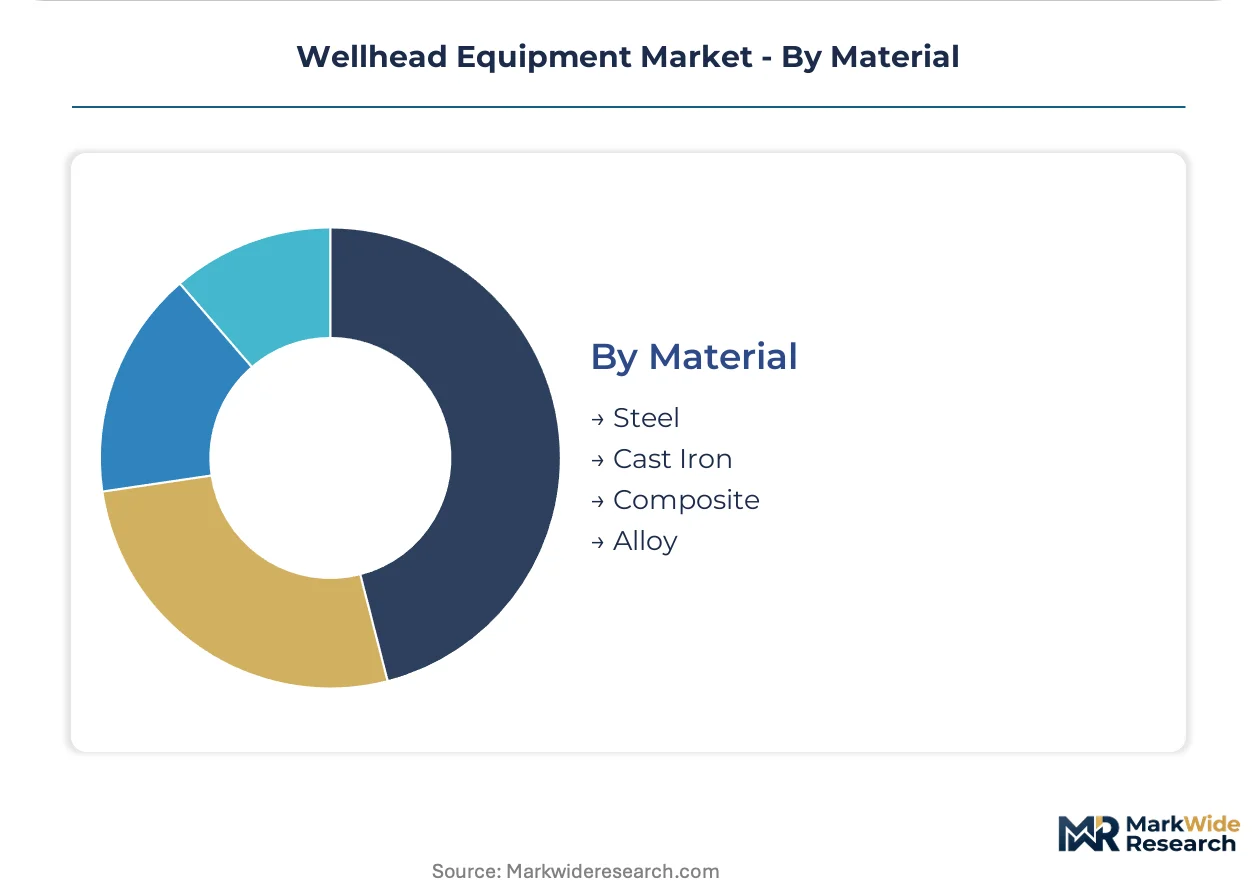
Material:
Alloy selection determines sulfide stress cracking resistance and operational envelope in high-pressure high-temperature reservoirs.
- Alloy:Chrome-molybdenum and nickel-based compositions withstand HPHT conditions and sour gas environments. Material traceability mandates under tightening API 6A protocols favor suppliers with captive forging and heat-treatment capabilities.
- Steel:Carbon and low-alloy grades remain the baseline specification for standard pressure ratings.
- Cast Iron:Limited to low-pressure surface applications with minimal corrosion exposure.
- Composite:Non-metallic alternatives are emerging for specific corrosive service conditions.
Steel retains the highest shipment volume, with Alloy specifications climbing the fastest as pre-salt and HPHT developments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater engineering talent clusters anchor procurement decisions across four major basins. Reservoir pressure specialists concentrate near frontier developments. Regulatory divergence shapes supplier qualification investments.
United States
Gulf of Mexico drillers drive demand for dual shear ram BOP configurations and real-time monitoring systems. The Bureau of Safety and Environmental Enforcement mandates Well Control Rule compliance with five-year retrofit deadlines. Houston anchors the supplier ecosystem, with fabrication yards in Louisiana assembling high-pressure Christmas trees for ultra-deepwater contracts.
Brazil
Petrobras pre-salt developments in the Santos Basin require subsea wellheads rated beyond 20,000 psi with fatigue-resistant metallurgy. The ANP enforces local content thresholds that force foreign suppliers into domestic fabrication partnerships. Macaé and Rio de Janeiro host qualification centers where subsea system integrators meet national content requirements.
Norway
North Sea HPHT fields demand alloy steel wellheads with sulfide stress cracking resistance. The Petroleum Safety Authority imposes functional safety standards that shape subsea equipment design specifications. Stavanger concentrates engineering capabilities for integrated production systems serving mature basin redevelopment.
China
Deepwater exploration in the South China Sea accelerates procurement of subsea wellhead assemblies with indigenous control systems. The Ministry of Emergency Management enforces well control regulations through the State Administration of Work Safety. Tianjin and Shenzhen house fabrication facilities where state-backed oilfield service companies qualify subsea connectors.
Saudi Arabia
Offshore Manifa and Zuluf developments sustain demand for high-pressure wellhead flanges and casing heads. The Saudi Aramco engineering standards specify API 6A compliance with enhanced material traceability for sour service applications. Dhahran anchors procurement decision-making, with Dammam fabrication yards supplying replacement cycles for aging platform infrastructure.
Wellhead Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across wellhead equipment tiers. Integrated oilfield service providers leverage subsea production system portfolios to anchor long-term contracts. Three archetypes dominate: full-system integrators with hydraulic control capabilities, component specialists with captive forging assets, and regional fabricators serving land-based replacement cycles. M&A activity concentrates test facility access and API 6A certification assets. Strategic partnerships with national oil companies secure local content compliance in pre-salt and Middle East markets.
Among US-based integrated service providers, TechnipFMC and Baker Hughes exemplify the full-system archetype with subsea production capabilities. National Oilwell Varco occupies a position within land-based replacement cycles across North American shale basins. These three anchors represent divergent competitive vectors: deepwater integration, advanced metallurgy, and onshore scale.
| Leading Market Players |
|---|
| TechnipFMC |
| Weir Group |
| Schlumberger |
| Halliburton |
| Weatherford International |
| Baker Hughes |
| Aker Solutions |
| Dril-Quip |
| National Oilwell Varco |
| Others |
Cost & Logistics Intelligence
Chrome-molybdenum billet indices on the London Metal Exchange cascade through forging and heat-treatment tiers into three distinct pricing bands for pressure-containing components. API 6A certification intensity separates captive-capability suppliers from contract-dependent fabricators, with nickel and molybdenum volatility compressing margins at the alloy-intensive premium tier.
Pricing Analysis
Bundled equipment-as-a-service contracts are displacing unbundled transactional purchases among capital-constrained shale operators. Three-tier pricing structure across premium, standard, and economy levels reflects API 6A certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because alloy steel price volatility transfers directly from commodity indices to fabrication quotes. Private equity-backed independents exhibit highest price sensitivity through lease-versus-buy calculus, while deepwater majors absorb premium tier pricing for integrated subsea production systems.
Supply Chain Analysis
Single-source vulnerability sits with subsea test facility access concentrated among integrated system providers in Houston, Stavanger, and Macaé. Forging capacity draws from the US Gulf Coast, Germany, and Japan for high-pressure alloy components. Chrome-molybdenum billet, nickel-alloy choke trim, and hydraulic control units constitute critical input dependencies. Tariff exposure on specialty steel imports threatens margin stability for European fabricators serving North Sea projects. Distribution runs through EPC contractor procurement offices and direct operator contracts for deepwater developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where BSEE Well Control Rule amendments and ANP local content mandates generate recurring equipment replacement demand.
For Market Incumbents: Extend API 6A certification assets into digital twin aftermarket services to capture recurring revenue from sensor-embedded wellhead installations. Deepen backward integration into captive forging capacity to defend margin position against alloy price volatility. Threat substitution from additive manufacturing choke components demands metallurgy R&D investment to maintain performance differentiation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in subsea control systems offers entry traction through electro-hydraulic unit specialization. West African deepwater procurement corridors in Senegal and Mauritania present the most penetrable geography with limited incumbent qualification. Target carbon capture wellhead adaptation projects with modified sealing architecture expertise as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing ANP-compliant Brazilian partnerships and API 6A captive heat-treatment capabilities. Long-term viability centers on test facility access and national oil company relationship depth rather than component manufacturing scale alone. Watch pre-salt project sanctioning velocity as the inflection signal for subsea wellhead demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Investment | Captive forging and heat-treatment capabilities concentrate contract awards among qualified suppliers. |
| Digital Twin Integration | Sensor-embedded flanges create aftermarket service revenue streams for equipment vendors. |
| Local Content Partnership | ANP-compliant Brazilian fabrication joint ventures unlock Petrobras pre-salt procurement eligibility. |
| Alloy Metallurgy R&D | HPHT and sour service specifications drive sulfide stress cracking resistance differentiation. |
| West African Market Entry | Senegal and Mauritania offshore developments open new procurement corridors for subsea integrators. |
Research Approach
Bottom-up operator procurement modeling reconciled against top-down forging capacity tracking forms the analytical core of this study. Primary interviews with subsea project engineers, drilling contractor procurement leads, API certification auditors, and EPC contract managers combined with secondary validation from BSEE enforcement data, ANP local content filings, and specialty steel trade statistics. Triangulation across supply-side capacity registers and demand-side contract award databases ensures cross-verification.
Historical trendline analysis of wellhead equipment shipments across product categories, application environments, and material specifications established baseline growth patterns. Segmentation dimensions modeled include product type complexity, deployment depth tier, end-user contracting structure, and regional regulatory framework. CAGRs were derived from fitted trend projections incorporating pre-salt development timelines, shale infrastructure replacement cycles, and HPHT field sanctioning rates.
Caveats apply where alloy commodity price spikes, welding engineer certification bottlenecks, or regulatory enforcement delays could materially shift the outlook. Forecasts reflect documented assumptions about deepwater project economics and national oil company capital allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Pumpjack Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Indonesia Oil and Gas Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Drilling Services Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market