
 LNG Loading Skid Market | 2026-2036
LNG Loading Skid Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Loading Skid Market Insights
Gulf Coast cryogenic equipment fabricators is hardening as LNG export capacity expands. Chart Industries leverages backward integration into cold-box manufacturing to sustain margin control. CCLPEC anchors its position through geographic dominance across Asia-Pacific coastal terminals. Furui Group specializes in cryogenic valve assemblies that differentiate its skid offerings from standardized competitors.
An LNG loading skid is a modular, prefabricated transfer system engineered for cryogenic fluid handling, typically constructed with stainless steel piping rated for minus 162 degrees Celsius and integrated with vacuum-insulated transfer arms to prevent boil-off gas losses during marine or truck loading operations. Automated loading skids now lead technology investments as terminal operators prioritize zero-manning protocols and real-time leak detection, while manual configurations retain share in remote bunkering stations where capital constraints persist. Cryogenic pumps represent the fastest-growing technology segment because throughput demands at mega-scale export facilities are outstripping centrifugal pump capacity limits.
The US Coast Guard enforces 33 CFR standards for marine transfer systems, forcing skid manufacturers to certify emergency shutdown sequencing and fire-safe valve actuation. China's SAMR administers GB standards for pressure equipment that govern cryogenic piping weld procedures and material traceability. The EU F-Gas Regulation and REACH framework collectively shape refrigerant containment specifications and material compliance documentation burdens. Stakeholders must monitor how divergent national pressure equipment codes affect modular skid certification portability across terminal projects.
Market Dynamics
Automated loading skids are compressing manning levels at coastal terminals while vacuum-insulated transfer arms eliminate boil-off gas losses, forcing fabricators to certify zero-manning protocols and real-time leak detection systems.
Growth Catalysts
- EU F-Gas Regulation:Tightening containment standards for cryogenic equipment are compelling terminal operators to replace aging transfer infrastructure with certified skid systems.
- Small-scale LNG import facilities:Coastal China is multiplying distributed receiving points that demand modular, rapidly deployable loading skids over fixed terminal builds.
- Cryogenic pump technology:Throughput demands at mega-scale export facilities are outstripping centrifugal pump capacity limits, driving investment in advanced cryogenic pumping systems.
Market Restraints
- Stainless steel input volatility:Piping rated for minus 162 degrees Celsius requires specialized alloys whose prices fluctuate with nickel and chromium markets.
- Geographic supply concentration:Gulf Coast cryogenic equipment fabricators dominate fabrication capacity, creating bottleneck risks for non-US terminal projects.
- Certification portability friction:Divergent national pressure equipment codes between US 33 CFR, China's GB standards, and EU directives complicate modular skid certification across jurisdictions.
Strategic Opportunities
- Remote bunkering stations:Arctic shipping routes and island economies present underpenetrated demand for manual-configured skids where capital constraints persist.
- Dual carbon goals:China's MEE enforcement of emissions targets is accelerating coal-to-gas switching that requires small-scale LNG infrastructure.
- AI-driven predictive maintenance:Convergence of IoT sensors and machine learning is enabling new service revenue streams around skid uptime guarantees.
Industry Challenges
- Cryogenic welding certification:Qualified technicians for stainless steel piping weld procedures remain scarce relative to project pipeline demands.
- Legacy system integration:Terminal operators face complex retrofit requirements when connecting automated skids to existing SCADA architectures.
- Material traceability documentation:REACH framework and GB standards impose burdensome documentation requirements that extend procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Loading Skid Market |
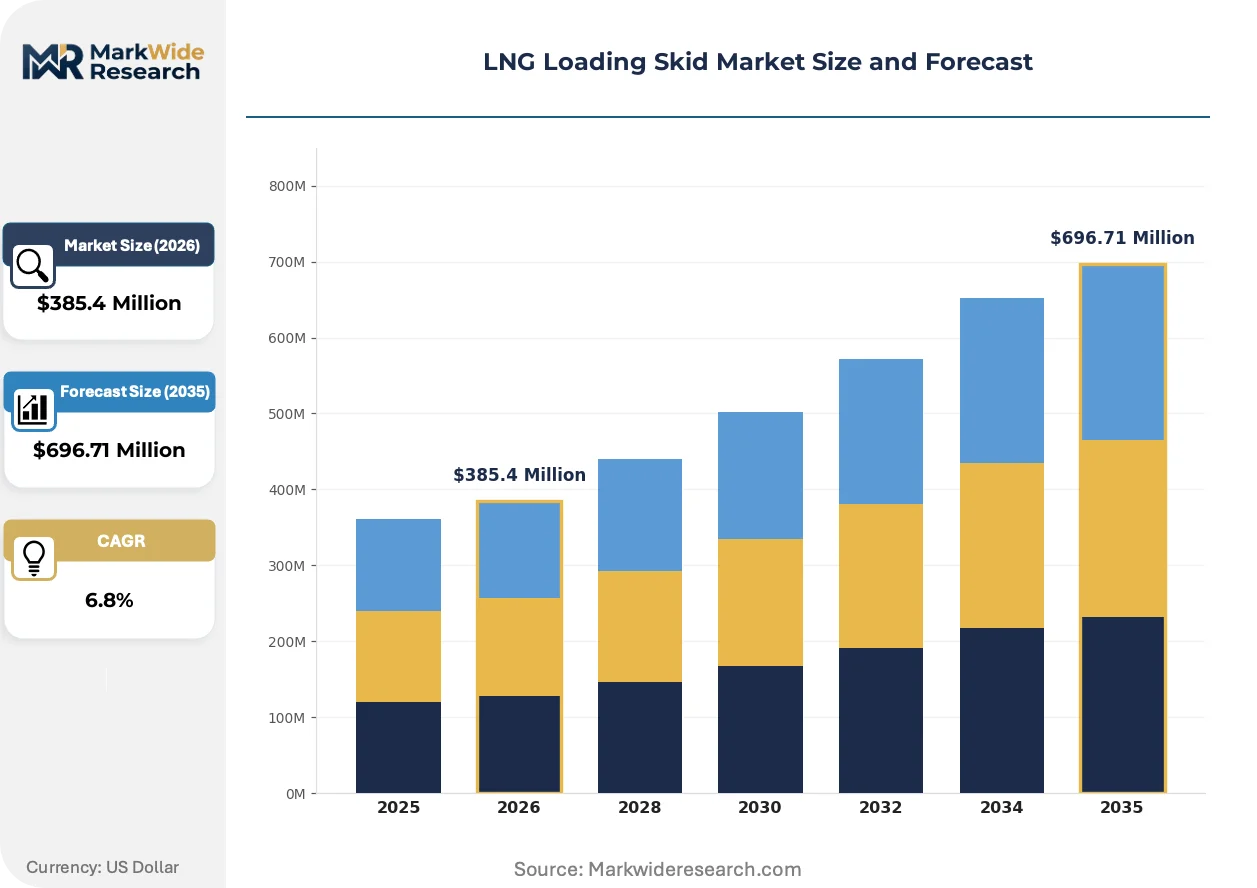
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Loading Skids, Bottom-Loading Skids, Manual Loading Skids, Automated Loading Skids Technology: Cryogenic Pumps, Valves, Control Systems, Monitoring Equipment End User: Utilities, Industrial Users, Shipping Companies, LNG Terminals Application: Export Loading, Import Operations, Vessel Refueling, Storage Transfers |
| Companies Covered | Carbis Loadtec Group, CCLPEC, Chart Industries, Furui Group, Hamina, Woodfield Systems, HUADE, Chongqing Endurance Industry Stock, S&S Technical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Loading Skid Market Trends and Innovations
Vacuum-insulated transfer arms and AI-enabled leak detection are rewriting operational protocols at marine terminals, while regulatory divergence between US, EU, and Asian jurisdictions is fragmenting certification pathways.
Automated loading skids equipped with zero-manning protocols are rewriting terminal staffing models. Major export facilities in Qatar and Australia are adopting these systems to reduce operational expenditure and insurance liability. The technology is rewriting competitive bidding criteria, as automation capability now outweighs capital cost in operator evaluations.
The EU F-Gas Regulation is mandating stepped reductions in fluorinated gas emissions from cryogenic containment systems. Equipment suppliers must now certify refrigerant leak rates below specified thresholds to maintain CE marking eligibility. Marine loading arms and valve assemblies face the steepest compliance burden, driving fabricators toward all-welded designs that eliminate gasket failure points.
Terminal operators are unbundling after-sales service contracts from initial equipment procurement, preferring performance-based agreements tied to uptime metrics. Japanese utilities pioneered this shift at LNG terminals in Osaka and Chita. Chinese coastal importers are now replicating the model, pressuring skid vendors to maintain regional spare parts inventories and certified technician pools.
LNG Loading Skid Market Segmentation
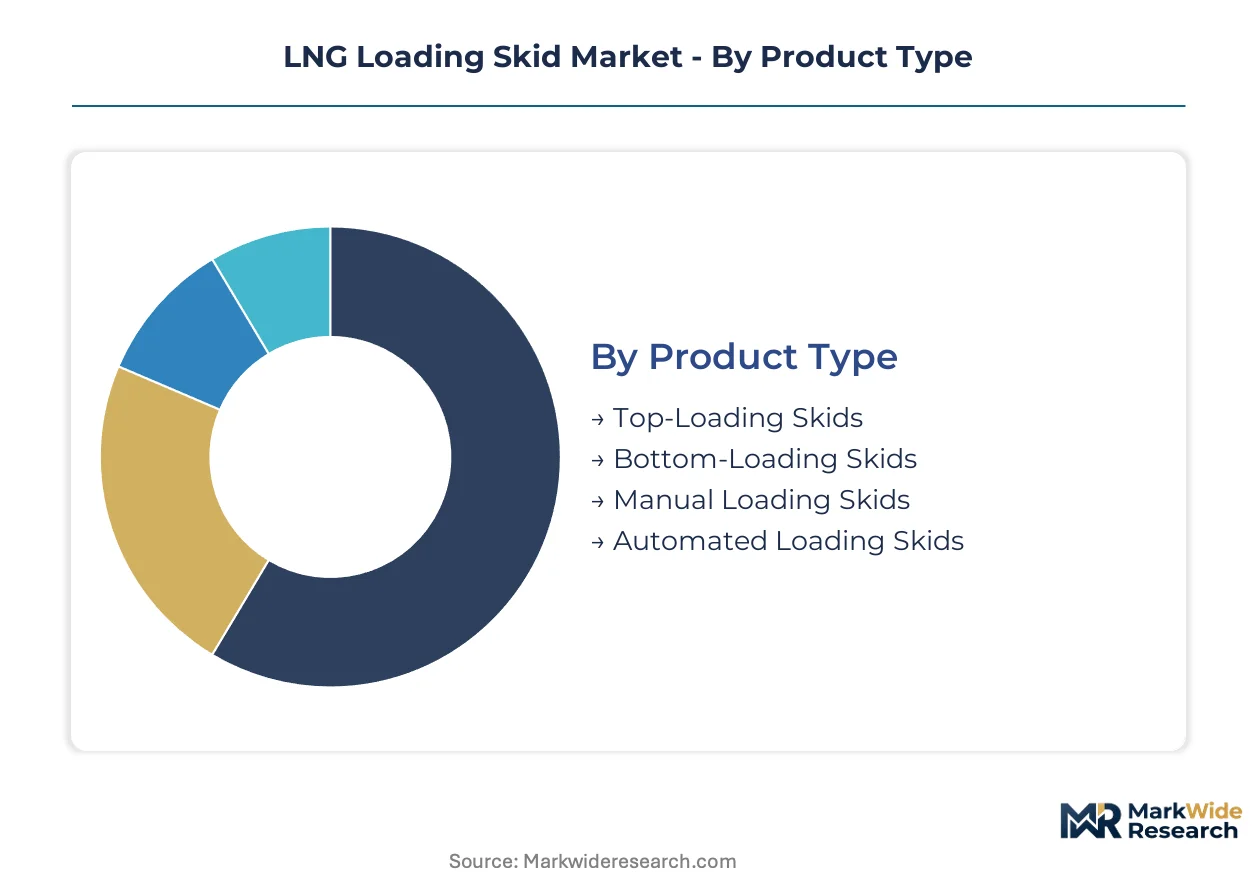
Terminal operators select skid configurations based on throughput requirements, automation mandates, and integration complexity with existing cryogenic infrastructure. Product and technology choices cascade through procurement decisions, determining capital intensity and operational staffing models.
Product Type:
Capital allocation intensity separates terminal operators choosing between manual configurations and fully automated systems.
- Automated Loading Skids:Systems integrate zero-manning protocols with real-time leak detection and emergency shutdown sequencing certified to 33 CFR standards. Qatar and Australian export facilities prioritize these configurations to compress operational expenditure and insurance liability.
- Manual Loading Skids:Prefabricated transfer systems with operator-attended valve actuation and visual monitoring protocols. Arctic bunkering stations and remote island economies specify these skids where capital constraints override automation mandates.
- Top-Loading Skids:Marine transfer configurations with elevated loading arm geometry for vessel manifold access.
- Bottom-Loading Skids:Truck and railcar transfer systems with underground or low-profile piping architecture.
Volume sits with manual configurations in distributed installations; growth tilts toward automated systems at mega-scale export terminals.
Technology:
Throughput bottlenecks at marine terminals are reshaping component specification priorities.
- Cryogenic Pumps:Centrifugal and reciprocating pump assemblies rated for minus 162 degrees Celsius fluid handling. Mega-scale export facilities in the US Gulf Coast and Qatar are outstripping conventional centrifugal capacity limits, forcing specification of advanced cryogenic pumping architectures.
- Control Systems:PLC-based automation platforms with SCADA integration and predictive maintenance algorithms. Japanese utilities at Osaka and Chita terminals pioneered performance-based service contracts tied to uptime metrics delivered through these systems.
- Valves:Fire-safe actuated valve assemblies with all-welded designs eliminating gasket failure points under EU F-Gas Regulation containment thresholds.
- Monitoring Equipment:IoT sensor arrays enabling AI-driven leak detection and predictive maintenance revenue streams.
Procurement weight concentrates in cryogenic pumps; specification velocity is climbing fastest for monitoring equipment with predictive capabilities.
End User:
Regulatory exposure and throughput scale differentiate buyer requirements across terminal categories.
- LNG Terminals:Large-scale import and export facilities with marine berth infrastructure and cryogenic storage tanks. Coastal China is multiplying small-scale receiving points that demand modular, rapidly deployable skids over fixed terminal builds.
- Shipping Companies:Vessel operators requiring bunkering infrastructure for LNG-fueled fleets. Arctic shipping routes present underpenetrated demand for manual-configured skids at remote refueling points.
- Utilities:Power generation and gas distribution companies executing coal-to-gas switching under China's MEE emissions enforcement.
- Industrial Users:Manufacturing facilities with on-site LNG storage for process heat and power generation.
Contract value aggregates at LNG terminals; expansion is steepest among shipping companies building bunkering networks.
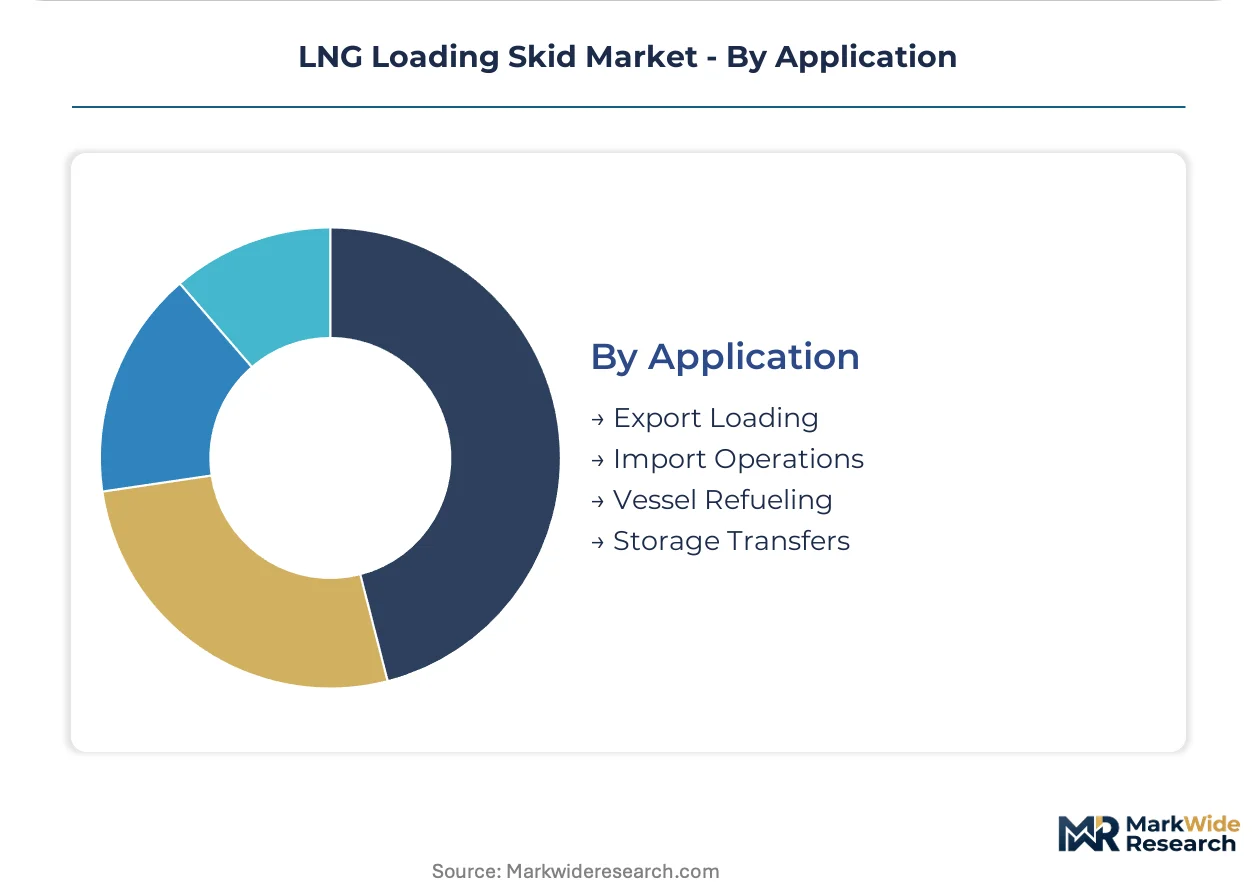
Application:
Flow direction and custody transfer requirements determine skid specification complexity.
- Export Loading:Marine transfer operations from liquefaction facilities to carrier vessels. US Coast Guard 33 CFR standards enforce emergency shutdown sequencing and fire-safe valve actuation certification for these systems.
- Vessel Refueling:Bunkering operations for LNG-fueled ships at port and offshore locations. China's SAMR administers GB standards for pressure equipment that govern cryogenic piping weld procedures in these applications.
- Import Operations:Unloading and regasification terminal transfer systems.
- Storage Transfers:Intra-terminal movements between cryogenic storage tanks and process units.
System complexity peaks at export loading; deployment frequency is expanding most quickly for vessel refueling along coastal routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized stainless steel alloy production in Pittsburgh and the Ohio Valley anchors North American cryogenic equipment manufacturing. Gulf Coast fabrication clusters supply export terminals across Qatar, Australia, and emerging Asian markets. Divergent national pressure equipment codes create certification friction for modular skid vendors operating across multiple jurisdictions.
United States
Gulf Coast liquefaction capacity expansion drives demand for marine transfer systems rated to US Coast Guard 33 CFR standards. The FERC permitting process governs new export terminal infrastructure, mandating emergency shutdown sequencing certification. Houston-area fabricators cluster around Port Arthur and Corpus Christi terminals where cryogenic pump specifications are outstripping conventional centrifugal limits.
China
Coastal provinces multiply small-scale LNG receiving points requiring rapidly deployable modular skids over fixed terminal builds. SAMR administers GB standards for pressure equipment that govern cryogenic piping weld procedures and material traceability. Yangtze River Delta terminals in Jiangsu and Zhejiang concentrate demand for automated loading configurations with zero-manning protocols.
Japan
Osaka and Chita terminals pioneered performance-based service contracts tied to uptime metrics delivered through integrated control systems. METI oversees energy infrastructure standards that shape procurement specifications for cryogenic containment equipment. Kansai region utilities are unbundling after-sales contracts from initial equipment procurement, pressuring vendors to maintain regional spare parts inventories.
Germany
Industrial gas users and bunkering infrastructure along the Rhine corridor specify cryogenic transfer systems compliant with EU F-Gas Regulation containment thresholds. The ECHA REACH framework imposes material traceability documentation burdens that extend procurement timelines for stainless steel piping. Ruhr Valley manufacturing clusters and Hamburg port facilities represent concentrated demand for vacuum-insulated transfer arm retrofits.
Qatar
Mega-scale North Field expansion projects specify advanced cryogenic pumping architectures exceeding conventional centrifugal capacity limits. The country's national petroleum regulator enforces marine transfer safety standards aligned with international shipping protocols. Ras Laffan Industrial City concentrates fabrication demand for automated skids with real-time leak detection and fire-safe valve actuation systems.
LNG Loading Skid Market Competitive Landscape
Global majors compete with regional champions across certification portability and automation capability. The vendor base stratifies into three tiers: integrated cryogenic equipment conglomerates with backward integration into cold-box manufacturing, regional fabricators dominating specific coastal terminal clusters, and specialized valve assembly shops differentiating through component-level expertise. Competitive moves center on geographic expansion into China's multiplying small-scale terminals and technology licensing partnerships for AI-driven predictive maintenance platforms.
Among Asia-Pacific fabricators, CCLPEC anchors the regional champion archetype through geographic dominance across coastal terminals. Chart Industries exemplifies the integrated conglomerate model with captive supply of cold-box manufacturing. Furui Group occupies the component specialist position, differentiating skid offerings through cryogenic valve assembly expertise. These three represent distinct competitive vectors: regional coverage, vertical integration depth, and sub-system specialization.
| Leading Market Players |
|---|
| Carbis Loadtec Group |
| CCLPEC |
| Chart Industries |
| Furui Group |
| Hamina |
| Woodfield Systems |
| HUADE |
| Chongqing Endurance Industry Stock |
| S&S Technical |
| Others |
Pricing and Supply Chain Analysis
Qualified cryogenic welding technicians concentrated in Pittsburgh and the Ohio Valley command wage premiums that widen pricing spreads between premium-certified and standard-grade skid systems. Labor-cost differentials between Gulf Coast fabrication clusters and emerging Asian assembly points compress margins at the economy tier while sustaining premium pricing for 33 CFR-certified configurations.
Pricing Analysis
Warranty and service-bundling unbundling is fragmenting procurement structures across terminal operator segments. Three-tier pricing structure across premium, standard, and economy levels separates fully automated zero-manning systems from manual configurations and basic transfer skids. Price differentiation hinges on certification grade and after-sales service intensity. Pricing pressure stems from stainless steel alloy volatility as nickel and chromium markets fluctuate. Small-scale coastal importers in China exhibit highest price sensitivity; mega-scale export facilities in Qatar and Australia prioritize automation capability over capital cost.
Supply Chain Analysis
Reverse-logistics flows for cryogenic pump refurbishment and valve assembly remanufacturing are underdeveloped, constraining circularity in high-value components. Fabrication capacity concentrates in the United States, China, and Germany. Supply chains draw from specialized stainless steel alloy production, vacuum-insulated piping, and fire-safe actuated valve assemblies. Single-source vulnerability sits with Gulf Coast cryogenic equipment fabricators serving non-US terminal projects. Distribution runs through EPC contractors and direct terminal operator procurement with extended lead times for certified weld procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
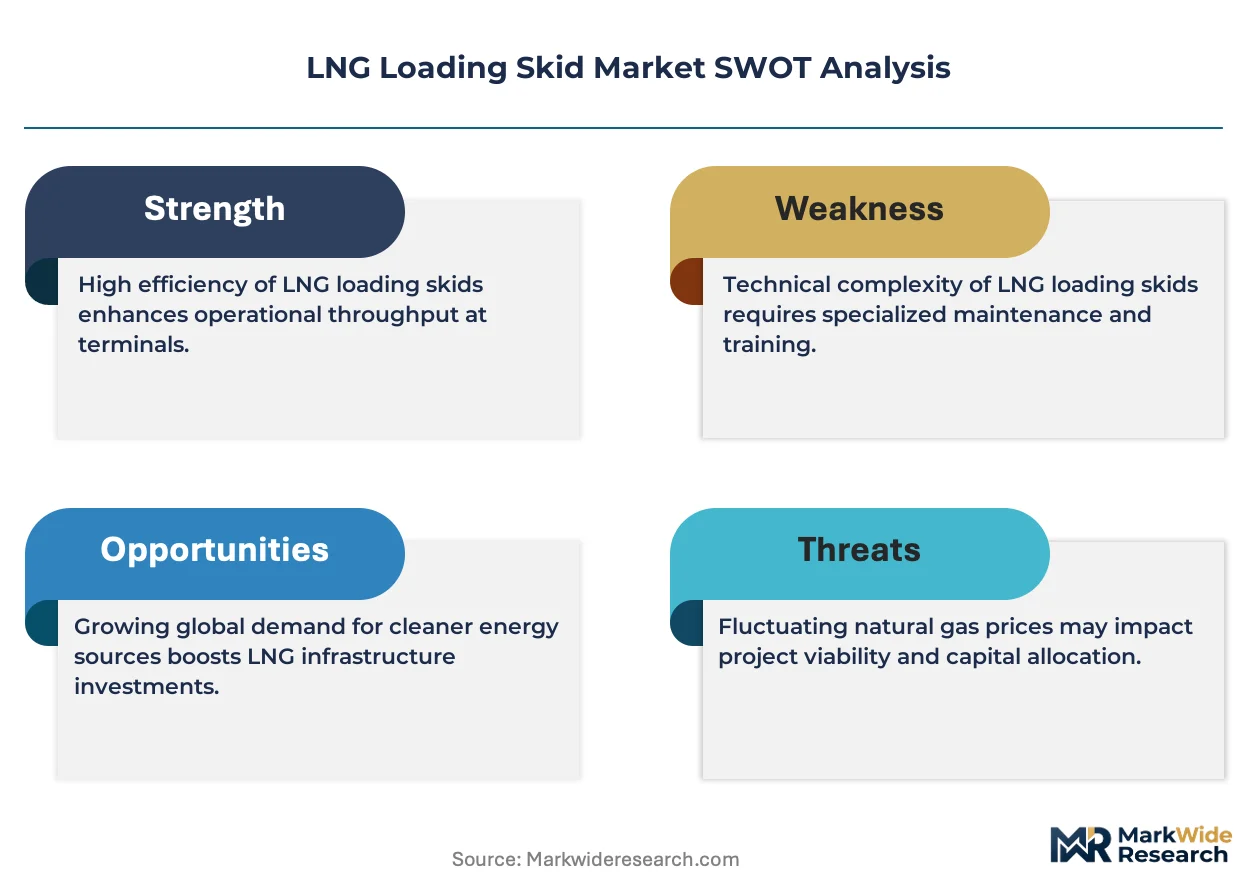
Consolidation pressure is intensifying as certification portability friction and material traceability documentation burdens force sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into cold-box manufacturing to sustain margin control against stainless steel input volatility. Expand certified technician pools in Asia-Pacific coastal clusters to capture unbundled after-sales service contracts. The EU F-Gas Regulation tightening containment standards threatens non-compliant competitors. Geographic expansion into China's Yangtze River Delta terminals represents a critical defensive lever.
For New Entrants and Emerging Players: Capture remote Arctic bunkering station demand where capital constraints override automation mandates and incumbent presence remains thin. Target manual-configured skid specifications for island economies and emerging shipping routes. Performance-based service contracts tied to uptime metrics offer a differentiated go-to-market angle against equipment-centric vendors.
For Investors and Strategic Acquirers: Re-rating potential sits with component-specialist fabricators given AI-driven predictive maintenance convergence enabling new service revenue streams. Long-term viability favors sub-system specialists with cryogenic valve assembly expertise over pure-play skid integrators. Monitor FERC permitting velocity and SAMR GB standards enforcement as inflection indicators for capacity expansion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Box Manufacturing | Chart Industries leverages captive supply to control margin compression from stainless steel volatility. |
| Performance-Based Service Contract Unbundling | Japanese utilities at Osaka and Chita terminals pioneered uptime-guarantee procurement structures. |
| AI-Driven Predictive Maintenance Platform Development | IoT sensor arrays and machine learning convergence enable new recurring revenue from skid uptime guarantees. |
| Geographic Expansion into Small-Scale Coastal Terminals | China's multiplying distributed receiving points demand modular, rapidly deployable configurations over fixed builds. |
| Certification Investment for 33 CFR and GB Standards Portability | Divergent national pressure equipment codes complicate modular skid certification across Qatar, Australia, and US Gulf Coast projects. |
Research Methodology
Independent corroboration across terminal operator procurement directors, cryogenic equipment fabricators, and EPC project managers underwrites the qualitative findings. Primary interviews with maintenance directors at LNG terminals, OEM procurement teams, and aftermarket service heads were validated against customs data, FERC filings, and IEA energy infrastructure reports. Bottom-up project pipeline assessments and top-down terminal capacity forecasts were triangulated to anchor market sizing.
Comparable-period anchoring to historical terminal commissioning cycles and cryogenic pump deployment trajectories structured the projection horizon. The analytical framework modeled segmentation across automation level, pump technology tier, and end-user category throughout the forecast period. CAGRs were derived from throughput capacity expansion schedules and small-scale facility deployment velocities. Cryogenic welding certification scarcity and divergent national pressure equipment codes served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation enforcement trajectories and stainless steel alloy price volatility. Forecasts reflect documented assumptions around terminal operator automation adoption curves and regulatory harmonization progress. Practitioners should monitor FERC export terminal permitting velocity and SAMR GB standards implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Japan AI in Oil and Gas Market