
 Middle East and Africa Early Production Facility Market | 2026-2036
Middle East and Africa Early Production Facility Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Early Production Facility Market Foresight
Offshore brownfield redevelopment by national oil companies is decoupling from traditional greenfield timelines as operators prioritize accelerated first-oil schedules over permanent facility investments. Halliburton leverages its integrated project management portfolio to anchor large-scale EPFC contracts across Saudi Arabia's offshore expansions. Weatherford International sustains competitive positioning through its artificial lift and completions technology leadership in mature West African basins. Pyramid E&C specializes in modular processing skids tailored for Nigeria's shallow-water marginal field operators.
Early Production Facilities are temporary or semi-permanent hydrocarbon processing installations designed to achieve first-oil within 12-24 months, typically employing modular process trains with throughput capacities of 10,000-150,000 barrels per day to bridge gaps before permanent infrastructure commissioning. Modular Systems dominate the technology landscape due to their transportability and reduced fabrication lead times, while FPSO configurations capture premium margins in deep-water West African pre-salt developments. Processing Equipment represents the most mature product category with established vendor bases, whereas Support Vessels face fastest-growing demand driven by subsea intervention complexity in Angola's Block 15 and 17 renewals.
Saudi Aramco's IKTVA program and Nigeria's NOGICD Act are tightening local content thresholds, forcing international contractors to deepen Nigerian and Saudi fabrication partnerships or risk disqualification from national oil company tenders. The UAE's MOHAP technical standards for offshore safety systems, combined with Angola's petroleum ministry environmental licensing requirements, add compliance layers that favor contractors with established regional regulatory navigation capabilities. Stakeholders must monitor how Ghana's Petroleum Commission revises its local participation framework for upcoming offshore licensing rounds, as this will reshape contractor consortium structures and equipment sourcing obligations across the Gulf of Guinea.
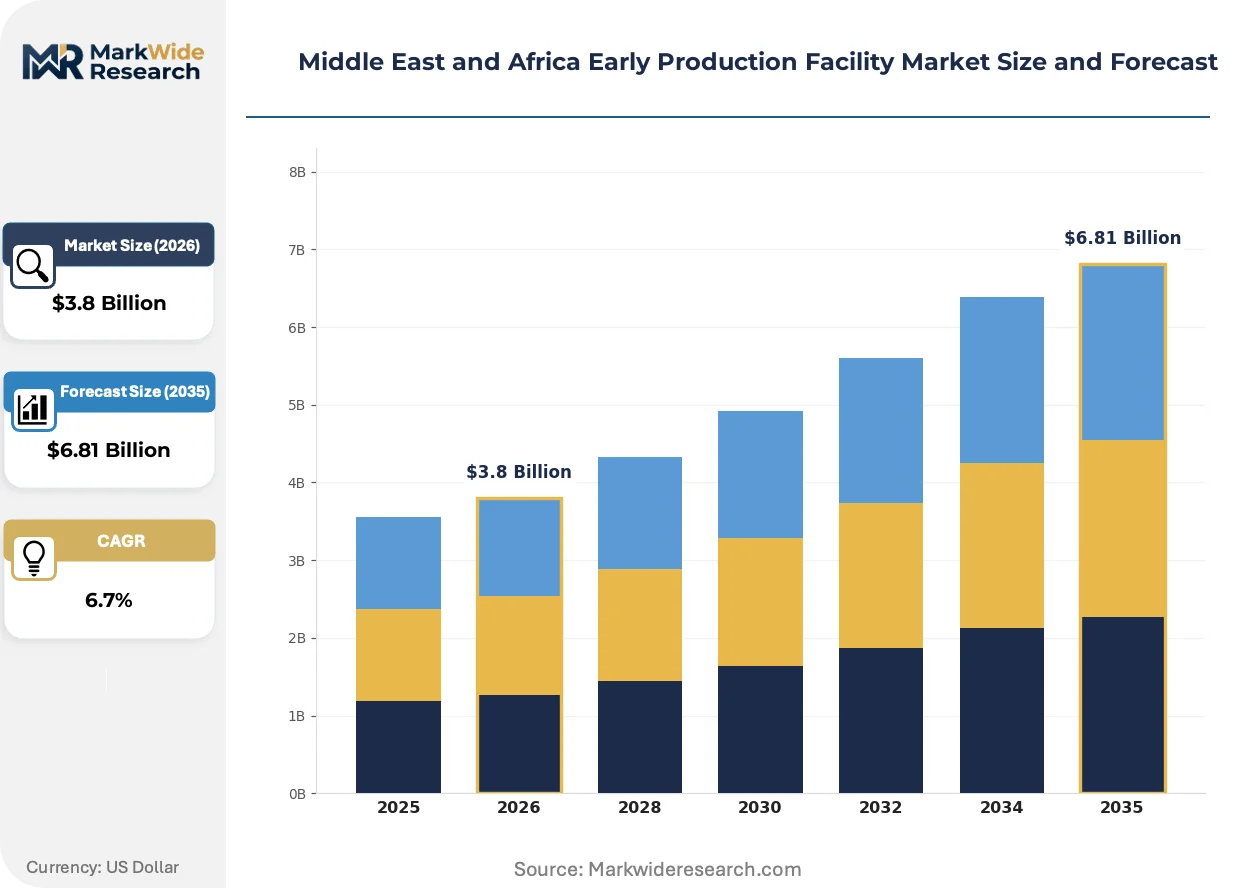
Market Dynamics
Accelerated first-oil mandates from national oil companies are compressing project timelines and forcing contractors toward modular fabrication partnerships over permanent facility construction. This structural pressure is reshaping contractor qualification frameworks across Saudi Arabia, Nigeria, and Angola.
Growth Catalysts
- Local Content Mandates:Saudi Aramco's IKTVA program and Nigeria's NOGICD Act are compelling international engineering firms to establish in-country fabrication yards, expanding domestic supply capacity.
- Brownfield Rehabilitation Backlog:Nigeria's shallow-water Niger Delta fields require rapid production restoration, creating sustained demand for temporary processing infrastructure.
- Modular Fabrication:Standardized skid-mounted process trains are slashing deployment timelines from 36 months to under 18 months for marginal field operators.
Market Restraints
- Steel Input Volatility:Fluctuating alloy and structural steel prices from East Asian suppliers are compressing EPC contractor margins on fixed-price EPFC contracts.
- Specialized Vessel Concentration:Heavy-lift and pipelay vessel availability concentrates among Singapore and South Korean yards, creating bottleneck risks for West African offshore installations.
- Technical Limitation:Current modular gas compression systems face throughput ceilings around 150,000 barrels per day, constraining applicability to mega-field developments.
Strategic Opportunities
- Angolan Deep-Water Pre-Salt:Block 15 and 17 renewal campaigns are generating demand for FPSO-integrated early production configurations with extended tieback capabilities.
- UAE Regulatory Tailwind:MOHAP technical standards for offshore safety systems are mandating upgraded process safety instrumentation, opening retrofit opportunities for existing modular facilities.
- Digital Twin Convergence:Integration of real-time process simulation with predictive maintenance platforms is enabling remote operations and reducing offshore staffing requirements.
Industry Challenges
- Skilled Welder Shortage:ASME-certified pressure vessel fabrication specialists are scarce across Nigerian and Saudi fabrication yards, extending quality control timelines.
- Certification Complexity:Dual compliance with API standards and country-specific petroleum ministry licensing is elongating equipment approval cycles by four to six months.
- Legacy Integration Friction:Connecting modular early production trains to aging platform infrastructure in mature Saudi offshore fields requires custom engineering and subsea intervention planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Early Production Facility Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Modular Systems, FPSO, TLP, Semi-Submersibles End User: Oil & Gas Companies, Independent Producers, Contractors, Government Agencies Installation: Onshore, Offshore, Shallow Water, Deep Water Product Type: Processing Equipment, Storage Facilities, Pipeline Infrastructure, Support Vessels |
| Companies Covered | Halliburton, Weatherford International, Petrocil Engineers and Consultants, TETRA Technologies, Pyramid E&C, Frames Group, Expro Group, Global Process Systems, OilSERV, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Early Production Facility Market Shifts & Advancements
Digitalization of process control systems and intensifying local content enforcement are converging to reshape how early production facilities are engineered, fabricated, and deployed across the Middle East and Africa.
Subsea modular boosting technology is absorbing installation and operational risk for deep-water pre-salt developments. Sonangol and TotalEnergies are deploying these systems in Angola's Block 17 to maintain production from high-pressure reservoirs. The technology is absorbing capital that would otherwise flow to permanent platform investments, compressing payback periods for marginal field economics.
Nigeria's NOGICD Act amendments are tightening Nigerian content thresholds for engineering design and fabrication services. International contractors must now demonstrate 50% local labor participation and domestic steel sourcing to qualify for NNPC tenders. Nigerian marginal field operators are responding by consolidating procurement through indigenous consortiums to meet compliance requirements.
Performance-based service contracts are displacing traditional equipment lease arrangements in Saudi offshore expansions. Saudi Aramco now ties contractor payments to uptime guarantees and production rate thresholds rather than day-rate structures. This shift is most visible in the Marjan and Zuluf field developments, where integrated project management contracts dominate tender awards.
Middle East and Africa Early Production Facility Market Segmentation
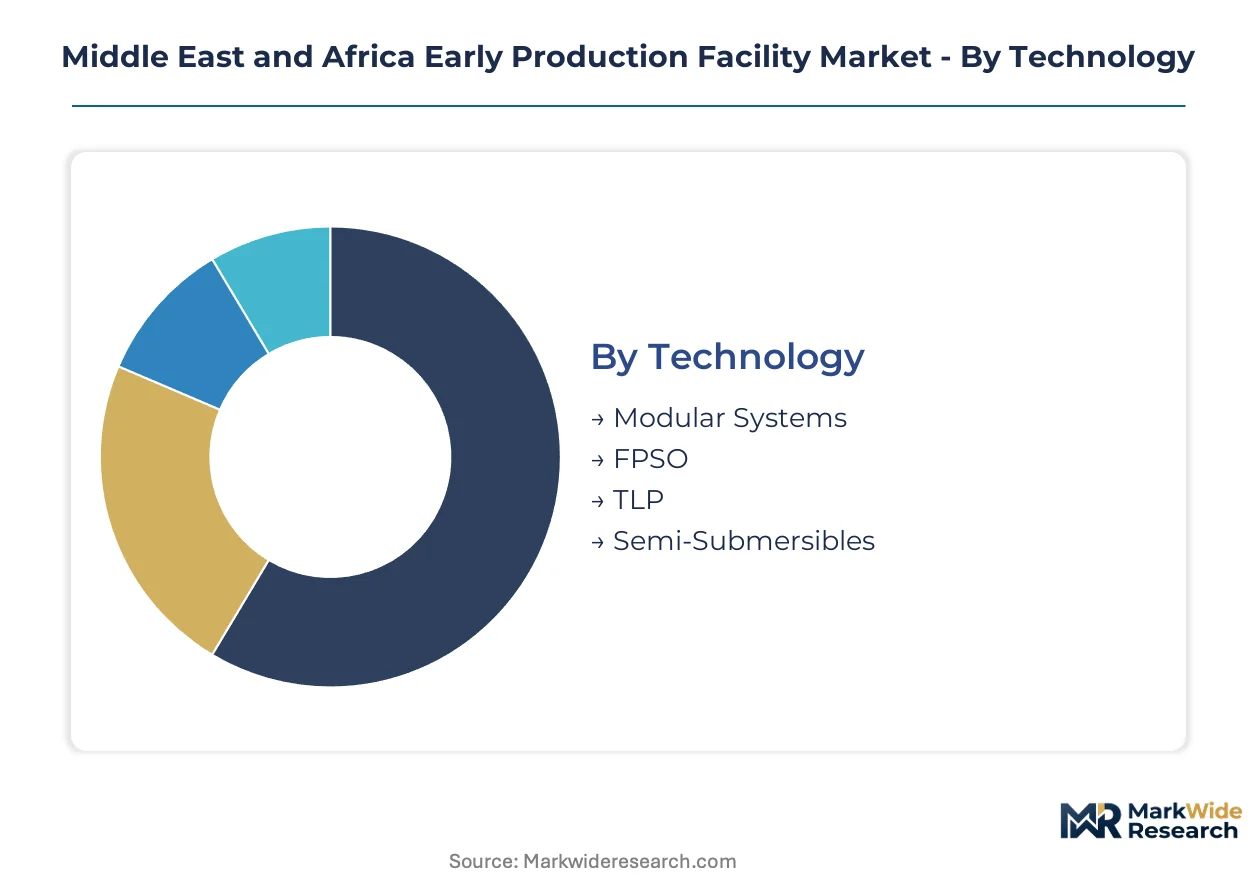
Early production facility procurement varies sharply by technical complexity and regulatory exposure. Operators select configurations based on water depth, reservoir pressure, and speed-to-first-oil requirements rather than permanent infrastructure economics.
Technology:
Customization intensity spans from fully standardized skid packages to bespoke floating production architectures engineered for specific field conditions.
- Modular Systems:Prefabricated process skids integrate separation, compression, and metering on transportable frames. Nigerian marginal field operators in the Niger Delta deploy these for 12-18 month first-oil schedules under NOGICD Act local content mandates.
- FPSO:Floating production storage and offloading vessels combine processing topsides with hydrocarbon storage. Angolan deep-water pre-salt developments in Block 15 and 17 drive demand for extended tieback configurations with 150,000+ barrel per day throughput.
- TLP:Tension leg platforms moor to seabed tendons for vertical stability. Applications concentrate in West African mid-water developments requiring dry-tree well access.
- Semi-Submersibles:Column-stabilized hulls withstand harsh metocean conditions. Saudi Arabia's offshore Red Sea frontier exploration favors these for mobility between appraisal wells.
Most installed capacity flows through Modular Systems. Expansion is steepest in FPSO configurations.
End User:
Procurement authority concentrates with entities controlling reserves access and development timelines.
- Oil & Gas Companies:Integrated national oil companies and international majors specify facility requirements and hold long-term lease contracts. Saudi Aramco's Marjan and Zuluf expansions anchor regional demand through integrated project management tenders.
- Independent Producers:Smaller operators lacking permanent infrastructure rely on rental early production systems. Nigeria's marginal field awardees source modular packages through indigenous consortiums to satisfy local content thresholds.
- Contractors:Engineering procurement fabrication construction firms lease equipment to project-specific joint ventures. Halliburton and Weatherford anchor EPFC contracts across West African shallow-water rehabilitation.
- Government Agencies:State petroleum ministries and national oil companies direct strategic reserve development. Sonangol's Block 17 renewal campaigns specify subsea modular boosting integration.
Contracting volume clusters with Oil & Gas Companies. Procurement flexibility is expanding fastest among Independent Producers.
Installation:
Water depth and seabed geology dictate structural loading, mooring complexity, and intervention access methods.
- Onshore:Desert terrain facilities in Saudi Arabia's Empty Quarter and UAE onshore fields employ truckable modular process trains with minimal foundation requirements.
- Offshore:Platform-tied installations in mature Saudi offshore fields require custom engineering to connect with aging infrastructure.
- Shallow Water:Niger Delta rehabilitation and Saudi Arabia's Safaniya field drive demand for jackup-supported modular systems in sub-100 meter depths.
- Deep Water:Angolan pre-salt and emerging Mozambique developments absorb FPSO and semi-submersible capacity in 1,000+ meter environments.
Shallow Water hosts the greatest installed base. Deep Water is climbing the fastest as pre-salt reserves enter development.
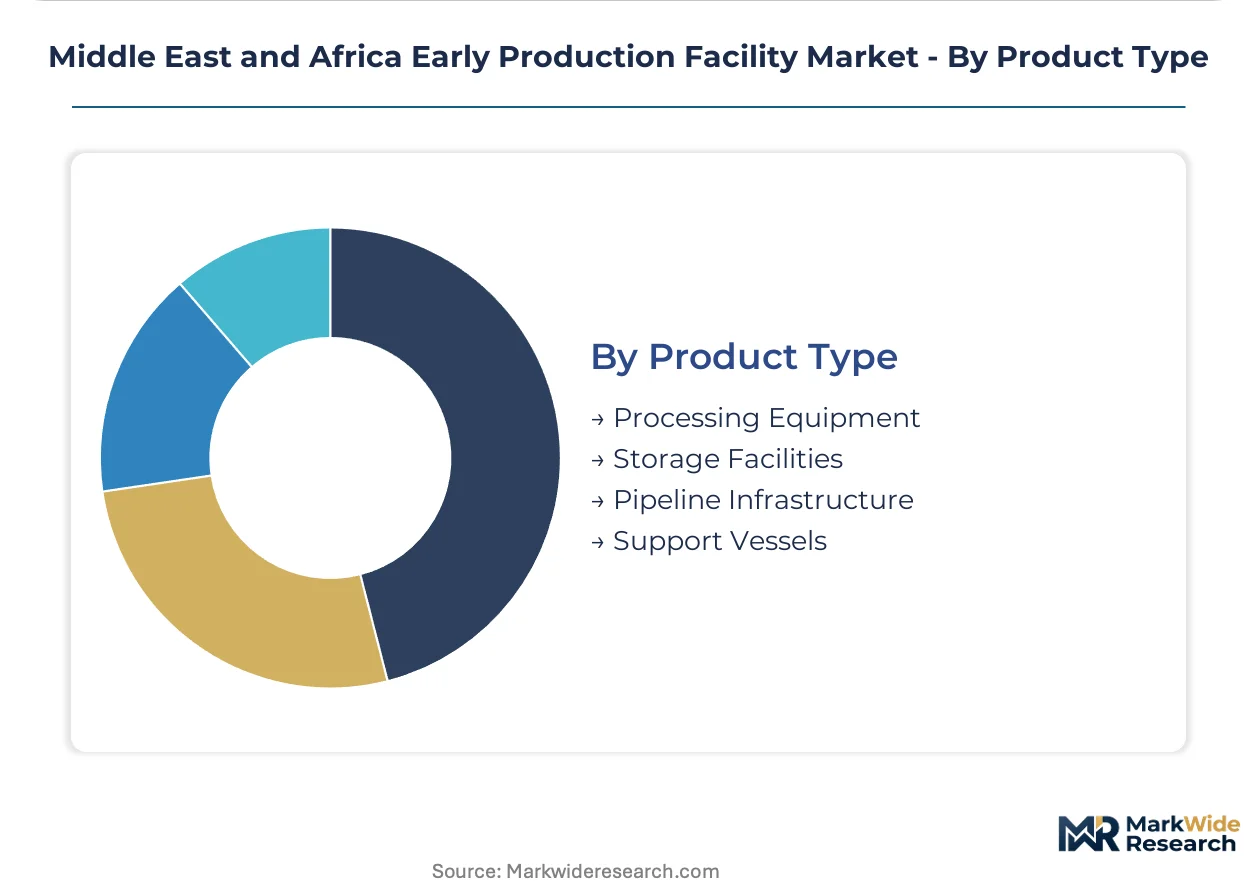
Product Type:
Margin structure varies from commoditized pressure vessels to specialized marine assets with concentrated supplier bases.
- Processing Equipment:Separators, compressors, and dehydration units constitute the core process train. Saudi fabrication yards under IKTVA localization pressure expand ASME-certified pressure vessel capacity.
- Storage Facilities:Crude oil tanks and condensate spheres provide surge capacity. FPSO-integrated storage dominates West African export logistics.
- Pipeline Infrastructure:Subsea flowlines and risers connect wells to processing hubs. Angola's Block 15 renewal requires extended tieback engineering.
- Support Vessels:Heavy-lift, pipelay, and intervention craft enable offshore installation and maintenance. Singapore and South Korean yard concentration creates bottleneck risks for West African projects.
Processing Equipment represents the largest revenue pool. Support Vessels face the steepest demand expansion driven by subsea intervention complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redirecting early production facility procurement toward jurisdictions with streamlined permitting and established fabrication ecosystems. National oil companies in Saudi Arabia and Nigeria leverage localization mandates to capture supply chain value domestically. Contractors respond by deepening in-country partnerships or accepting margin compression from regulatory complexity.
Saudi Arabia
Offshore brownfield expansions at Marjan and Zuluf fields absorb modular processing capacity under accelerated first-oil schedules. Saudi Aramco's IKTVA program mandates domestic fabrication thresholds, compelling international engineering firms to joint-venture with Saudi-owned yards. Dammam's King Salman Energy Park anchors ASME-certified pressure vessel manufacturing for offshore project demand.
Nigeria
Shallow-water Niger Delta rehabilitation creates sustained demand for temporary processing infrastructure among marginal field operators. The Nigerian Content Development and Monitoring Board enforces 50% local labor participation and domestic steel sourcing under NOGICD Act amendments. Port Harcourt fabrication clusters consolidate procurement through indigenous consortiums to satisfy compliance requirements.
Angola
Deep-water pre-salt developments in Block 15 and 17 generate demand for FPSO-integrated early production configurations with extended tieback capabilities. Sonangol's petroleum ministry environmental licensing requirements add compliance layers favoring contractors with established regulatory navigation experience. Luanda serves as the coordination hub for subsea modular boosting installations.
United Arab Emirates
Offshore safety system upgrades under MOHAP technical standards create retrofit opportunities for existing modular facilities across mature fields. The country's petroleum regulator mandates upgraded process safety instrumentation, opening equipment replacement cycles. Jebel Ali industrial zone concentrates fabrication capacity serving regional offshore project demand.
Egypt
Mediterranean offshore exploration campaigns in the Zohr gas field extension absorb semi-submersible and jackup-supported modular systems. The Egyptian General Petroleum Corporation prioritizes rapid deployment configurations to accelerate production from new discoveries. Alexandria's maritime industrial base supports vessel integration and topside module assembly.
Middle East and Africa Early Production Facility Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated project management firms capturing premium-margin EPFC contracts while regional fabricators compete on localization compliance. The vendor base organizes into three tiers: global engineering houses with turnkey capabilities, regional specialists in modular skid fabrication, and indigenous consortiums formed to satisfy local content mandates. Strategic moves concentrate on joint-venture formation for in-country yard access and technology licensing partnerships for subsea boosting systems.
Among the integrated service tier, Halliburton anchors large-scale EPFC contracting across Saudi offshore expansions through its project management portfolio. Weatherford International occupies a position in artificial lift and completions technology serving mature West African basins. Pyramid E&C exemplifies the regional specialist archetype, concentrating on modular processing skids tailored for Nigeria's shallow-water marginal field operators.
| Leading Market Players |
|---|
| Halliburton |
| Weatherford International |
| Petrocil Engineers and Consultants |
| TETRA Technologies |
| Pyramid E&C |
| Frames Group |
| Expro Group |
| Global Process Systems |
| OilSERV |
| Others |
Supply & Pricing Matrix
Modular fabrication standardization is compressing deployment timelines from 36 months to under 18 months while simultaneously concentrating procurement power among contractors with captive Saudi and Nigerian yard capacity. This dual shift rewards engineering firms that absorbed upfront localization costs under IKTVA and NOGICD Act mandates, squeezing margins for competitors still sourcing from East Asian fabrication hubs.
Pricing Analysis
Direct-to-NOC contracting eliminates distributor markups for integrated EPFC packages, while equipment-only vendors face 15-25 point compression from procurement consortiums. Three-tier pricing structure across premium, standard, and economy levels separates Halliburton-led integrated project management from regional skid fabricators and indigenous NOGICD-compliant consortiums. Cost compression in standard modular packages is intensifying because Saudi Aramco ties payments to uptime guarantees rather than day-rate structures. Marginal field operators in Nigeria's Niger Delta exhibit highest price sensitivity, whereas Sonangol's Block 17 renewals prioritize technical capability over capital efficiency.
Supply Chain Analysis
Saudi Aramco's IKTVA program and Nigeria's NOGICD Act are forcing international contractors to joint-venture with Dammam and Port Harcourt fabrication yards, fragmenting previously concentrated East Asian supply. Structural steel and alloy pressure vessel inputs draw from South Korean, Chinese, and domestic Saudi mills. Single-source vulnerability concentrates in heavy-lift and pipelay vessel availability from Singapore and South Korean yards. Distribution runs through national oil company tender platforms and indigenous consortium procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as brownfield rehabilitation backlogs across Nigeria and Saudi Arabia sustain demand for accelerated first-oil solutions regardless of oil price cycles.
For Market Incumbents: Hedge against margin compression by deepening captive fabrication capacity in Dammam's King Salman Energy Park and Port Harcourt clusters. Secure ASME-certified welder pipelines through technical training joint ventures before Nigerian Content Development and Monitoring Board thresholds tighten further. Anchor integrated project management contracts through performance-based service structures that tie payments to production rate thresholds rather than equipment lease day-rates. For New Entrants and Emerging Players: Nigeria's marginal field awardees lacking permanent infrastructure represent the most penetrable buyer archetype. These operators require 12-18 month first-oil modular packages but lack technical staff to specify complex process trains. Enter through indigenous consortium structures that satisfy NOGICD Act local labor and domestic steel sourcing mandates, positioning as the engineering-design partner to Nigerian fabrication yards. For Investors and Strategic Acquirers: Valuations sit cheapest among regional modular skid specialists with established Saudi or Nigerian yard joint ventures but limited integrated project management scale. Long-term viability rests on whether contractors can convert equipment-only relationships into performance-based service contracts. Watch whether Ghana's Petroleum Commission revises local participation frameworks for upcoming offshore licensing rounds as the signal for Gulf of Guinea contract flow redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture for In-Country Yard Access | Saudi Aramco's IKTVA program mandates domestic fabrication thresholds for EPFC qualification. |
| Performance-Based Service Contract Conversion | Saudi Aramco ties contractor payments to uptime guarantees at Marjan and Zuluf fields. |
| Subsea Modular Boosting Technology Licensing | Sonangol and TotalEnergies deploy these systems in Angola's Block 17 pre-salt developments. |
| Indigenous Consortium Formation | Nigeria's NOGICD Act amendments require 50% local labor participation for NNPC tender access. |
| Digital Twin Platform Integration | Real-time process simulation reduces offshore staffing requirements for remote operations. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with EPFC contract managers, national oil company procurement officers, Nigerian Content Development and Monitoring Board officials, and ASME-certified fabrication yard supervisors combined with secondary validation from customs trade data, petroleum ministry licensing records, SEC filings of integrated service companies, and project development databases tracking Saudi offshore expansions. Triangulation across these sources anchored volume estimates.
Historical trendline analysis of early production facility deployments across the analysis window informed projection frameworks. Segmentation dimensions modeled include technology type, water depth installation category, end-user procurement authority, and product type margin structure. CAGRs were derived from fitted growth curves applied to disclosed contract values and announced field development timelines. Forecast inputs incorporated IKTVA and NOGICD Act compliance cost absorption rates and modular fabrication lead time compression trends.
Underlying measurement precision varies by segment; FPSO-integrated configurations and Saudi offshore brownfield expansions carry tighter precision than emerging Mozambique deep-water developments. Forecasts reflect documented assumptions regarding national oil company capital allocation continuity and localization mandate enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
3D Printing in Oil and Gas Market