
 Middle East and Africa Drilling Market | 2026-2036
Middle East and Africa Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Drilling Market Foresight
Saudi Arabia's rig fleet expansion is broadening the supply base for high-specification land and offshore units. Schlumberger Limited leverages integrated drilling and evaluation technologies across Ghawar and Safaniya fields. Baker Hughes Company sustains directional drilling leadership through automated rotary steerable systems. ADES International Holding anchors jackup rig presence in Egyptian and Saudi waters through fleet modernization programs.
Middle East and Africa drilling encompasses the mechanical penetration of subsurface formations using rotary, directional, or coiled tubing methods to create boreholes for hydrocarbon extraction, geothermal energy, or geological assessment. Rotary systems deploy tricone or polycrystalline diamond compact bits with weighted drilling fluids circulating at pressures up to 15,000 psi to manage downhole temperatures exceeding 150°C in deep carbonate reservoirs. Directional and managed pressure technologies command premium positioning as operators navigate high-pressure, high-temperature formations where conventional methods risk wellbore instability. Onshore deployment dominates volume, while ultra deepwater segments concentrate margin pools off West Africa and in the Red Sea frontier.
Saudi Aramco Oil Co. operates under the country's national petroleum regulator, while Nigerian upstream activities fall under the Petroleum Industry Act administered by the Nigerian Upstream Petroleum Regulatory Commission. Environmental compliance with the EU Green Deal's carbon border adjustments affects export-oriented African producers serving European offtakers. Stakeholders must weigh rig automation investments against local content requirements that mandate domestic crew participation and equipment sourcing across Gulf and North African jurisdictions.
Market Dynamics
Managed pressure drilling systems are compressing wellbore instability risks in high-pressure, high-temperature carbonate formations across Saudi Arabia and the UAE, forcing rig fleet modernization cycles that favor automated rotary steerable capabilities over conventional directional equipment.
Growth Catalysts
- Petroleum Industry Act framework:Nigeria's upstream regulatory overhaul is consolidating licensing authority under the Nigerian Upstream Petroleum Regulatory Commission, accelerating offshore bidding rounds and rig deployment timelines in West African waters.
- Deepwater exploration budgets:National oil companies across the Gulf Cooperation Council are redirecting capital toward ultra-deepwater Red Sea and West Africa prospects, creating demand for high-specification jackup and semisubmersible units.
- Digital rig automation:Automated pipe handling and real-time downhole telemetry are reducing non-productive time in complex carbonate reservoirs, with Saudi Aramco and ADNOC mandating integrated drilling evaluation packages for new contracts.
Market Restraints
- Specialized alloy supply concentration:Premium drillstring components and high-pressure blowout preventer systems depend on limited forging capacity concentrated in East Asian supply chains, exposing operators to extended lead times and input cost volatility.
- EU Green Deal carbon border adjustments:Export-oriented African producers serving European offtakers face compliance cost pressures that compress drilling budget flexibility for marginal field developments in Nigeria and Angola.
- Managed pressure drilling technical thresholds:Narrow operational windows in formations exceeding 150°C and 15,000 psi limit application of conventional pressure control methods, constraining rig deployment options in frontier deepwater blocks.
Strategic Opportunities
- Egyptian offshore licensing:Unawarded blocks in the Mediterranean and Red Sea present white space for jackup rig operators with managed pressure capabilities, as ENI and BP accelerate exploration in the Zohr gas field periphery.
- Geothermal drilling convergence:Heat-resistant polycrystalline diamond compact bit technologies developed for oil and gas HPHT applications are transferring to geothermal resource assessment in Ethiopia's Rift Valley and Kenya's Olkaria fields.
- Local content mandates:Saudi Arabia's In-Kingdom Total Value Add program and Nigeria's domestic crew participation requirements are creating structured partnerships between international drilling contractors and regional service providers.
Industry Challenges
- Directional drilling specialist shortages:Automated rotary steerable system operation and managed pressure drilling engineering require skill sets that outpace regional training pipeline capacity across Gulf and North African jurisdictions.
- Dual certification timelines:Rig upgrades must simultaneously satisfy API standards and emerging EU Green Deal carbon intensity disclosures, extending equipment qualification cycles for units targeting European-destined production.
- Legacy SCADA integration:Digital rig automation platforms face interoperability friction with existing wellsite control architectures, complicating fleet-wide telemetry standardization for operators with mixed-vendor rig portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Drilling Market |
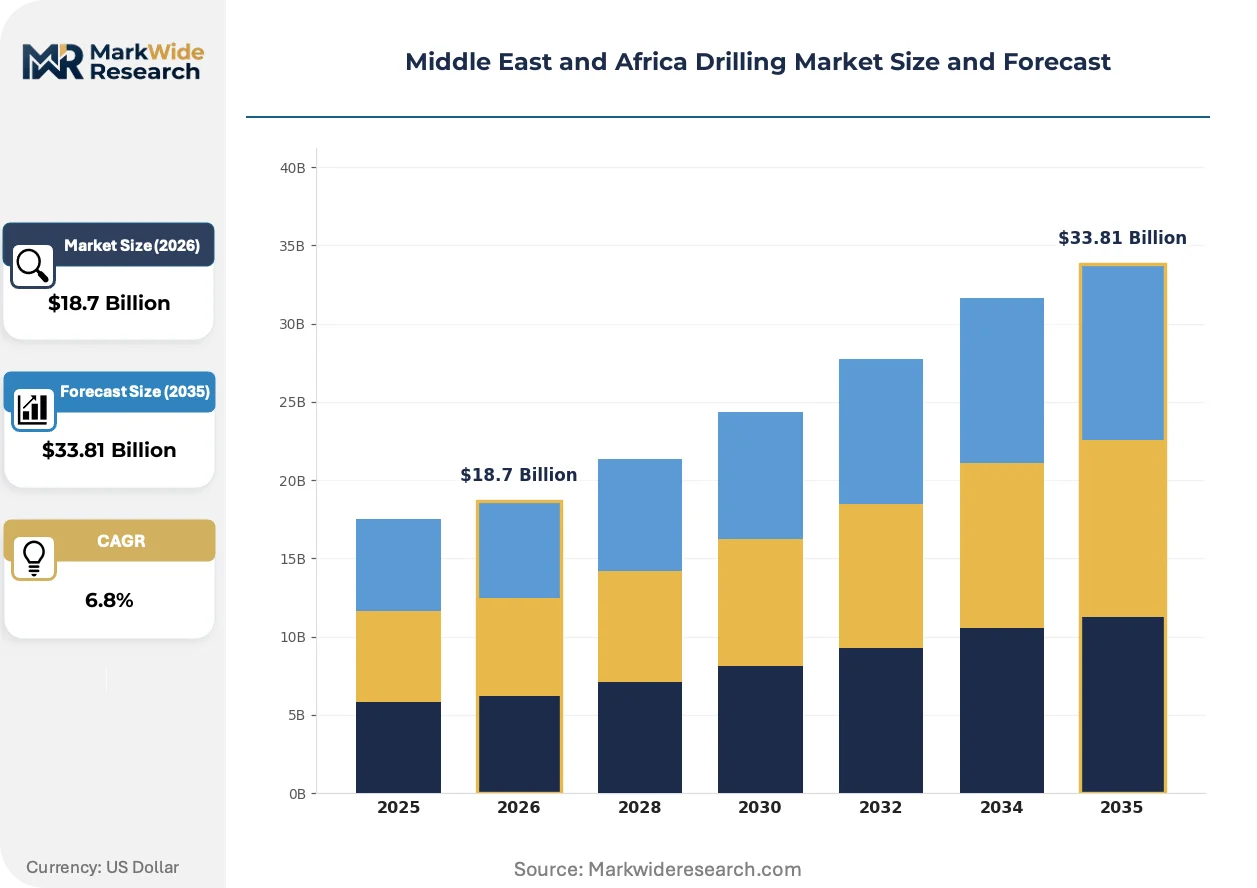
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Rotary, Directional, Managed Pressure, Coiled Tubing End User: Oil & Gas Companies, Independent Producers, Service Providers, Government Entities Application: Onshore Drilling, Offshore Drilling, Exploration, Production Deployment: Land, Shallow Water, Deep Water, Ultra Deep Water |
| Companies Covered | Arabian Drilling Company (ADC), Schlumberger Limited, Baker Hughes Company, Weatherford International PLC, Transocean Ltd., Saudi Aramco Oil Co., Halliburton Company, ADES International Holding, CNOOC International Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Drilling Market Shifts & Advancements
Real-time downhole data streams are compressing decision cycles in directional drilling operations, while regulatory carbon accounting and procurement model restructuring reshape contractor-operator relationships across the Middle East and Africa.
Managed pressure drilling systems are integrating dynamic annular pressure control with automated choke manipulation to maintain constant bottomhole pressure in narrow-margin formations. Saudi Aramco and ADNOC are mandating these capabilities for all high-pressure exploration wells in the Ghawar and Upper Zakum fields. This integration is collapsing the distinction between drilling and completion engineering teams, forcing organizational restructuring among integrated service providers.
The EU Green Deal's carbon border adjustment mechanism is imposing emissions disclosure requirements on crude oil imports into European refineries. Nigerian and Angolan operators must now document wellsite fuel consumption and flaring intensity to maintain offtake contracts with European traders. Ultra-deepwater projects off West Africa are most affected, with TotalEnergies and Shell requiring certified low-carbon drilling packages for new development wells.
Performance-based drilling contracts are displacing day-rate structures in Saudi Arabia and the UAE, transferring non-productive time risk from national oil companies to drilling contractors. Schlumberger and Baker Hughes are accepting footage-based or target-depth pricing for integrated project tenders in the Safaniya and Bab fields. This shift is most visible in offshore Saudi Arabia, where ADES International and Arabian Drilling Company compete on guaranteed mechanical drilling rates rather than rig availability metrics.
Middle East and Africa Drilling Market Segmentation
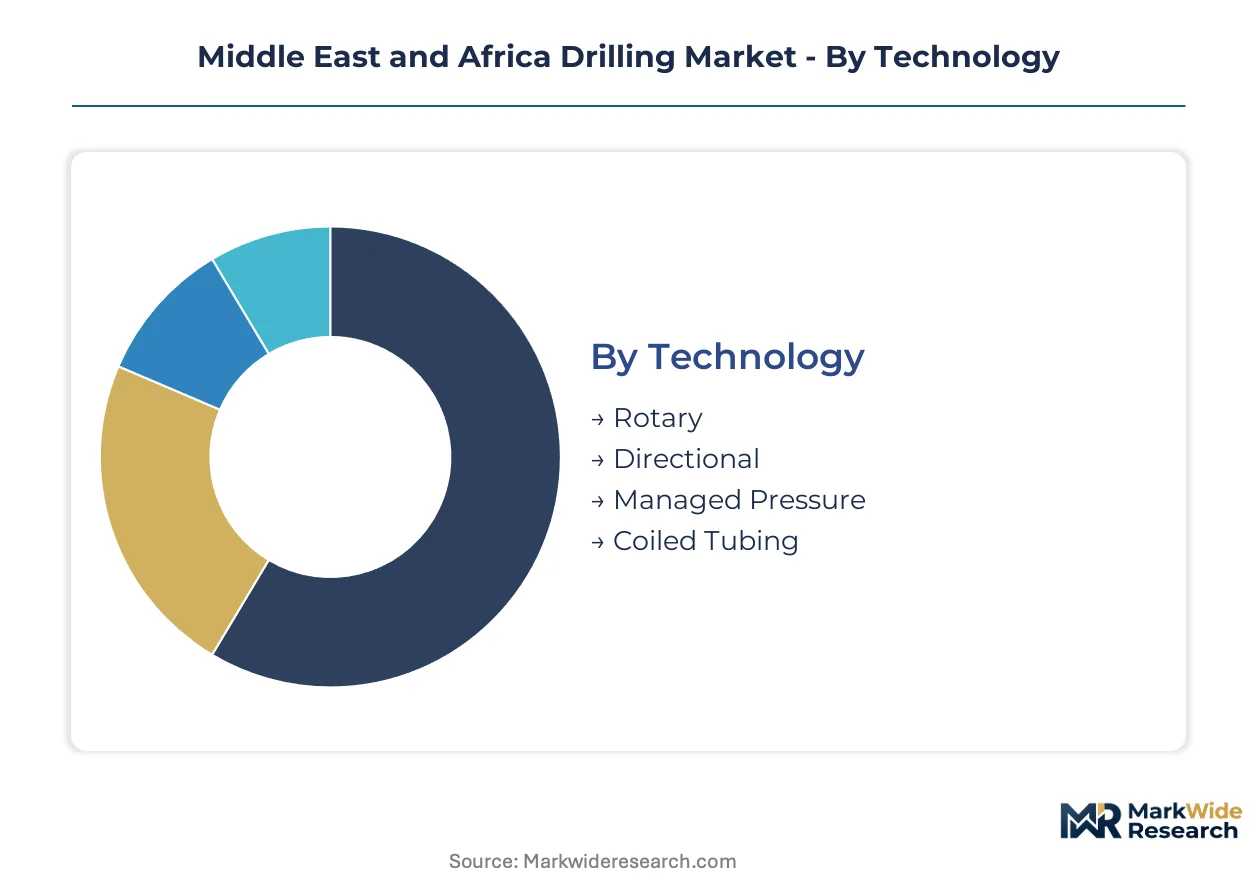
Technology differentiation determines rig fleet modernization priorities across Middle East and Africa drilling operations. Each segment category reflects distinct procurement criteria, operational thresholds, and contractor capability requirements that shape competitive positioning in high-pressure carbonate and deepwater frontier environments.
Technology:
Upgrade cycles favor automated systems that compress non-productive time in narrow-margin formations where conventional methods risk wellbore instability.
- Rotary:Conventional rotary systems deploy tricone or polycrystalline diamond compact bits with weighted drilling fluids circulating at pressures up to 15,000 psi. Demand concentrates in Saudi Arabia's mature onshore fields where Ghawar and Safaniya redevelopment programs prioritize cost-efficient mechanical penetration over directional complexity.
- Directional:Automated rotary steerable systems enable precise wellbore trajectory control through high-temperature carbonate formations exceeding 150°C. ADNOC and Saudi Aramco mandate these capabilities for offshore development wells in the Upper Zakum and Marjan fields where reservoir contact optimization drives economics.
- Managed Pressure:Dynamic annular pressure control systems maintain constant bottomhole pressure in formations with narrow operational windows. Nigerian deepwater blocks and Red Sea frontier prospects require these technologies to manage wellbore stability risks.
- Coiled Tubing:Continuous pipe technology enables re-entry drilling and well intervention without conventional rig mobilization. Mature field workover programs in Egypt's Western Desert and Abu Dhabi's onshore concessions deploy these units for cost-efficient production enhancement.
Rotary systems sit at the top of the volume ranking, with managed pressure drilling climbing the fastest as frontier exploration intensifies.
End User:
Procurement authority concentrates with entities controlling reserve access and capital allocation for multi-year drilling campaigns.
- Oil & Gas Companies:Integrated operators with reserve ownership mandate integrated drilling evaluation packages and real-time telemetry standards. Saudi Aramco and ADNOC drive specifications for high-specification jackup and semisubmersible units through performance-based contract structures.
- Independent Producers:Smaller operators without integrated service capabilities rely on drilling contractors for turnkey project delivery. Nigeria's marginal field awardees under the Petroleum Industry Act framework source managed pressure capabilities through structured service agreements.
- Service Providers:Integrated drilling contractors assume non-productive time risk under footage-based pricing models. Schlumberger and Baker Hughes compete for integrated project tenders across GCC national oil company portfolios.
- Government Entities:State regulators and national petroleum authorities set technical standards and local content mandates. Saudi Arabia's In-Kingdom Total Value Add program and Nigeria's domestic crew participation requirements shape contractor selection criteria.
Oil and gas companies command the largest procurement volume, with independent producers expanding most quickly under new licensing frameworks.
Application:
Activity type determines equipment specification, contract duration, and margin structure across the project lifecycle.
- Onshore Drilling:Land-based operations dominate total rig count across Saudi Arabia, UAE, and Kuwait where carbonate reservoir development favors high-horsepower land rigs. Saudi Aramco's rig fleet expansion targets automated pipe handling and real-time downhole measurement for Ghawar field redevelopment.
- Offshore Drilling:Jackup and semisubmersible operations concentrate in UAE, Saudi Arabia, and West Africa where water depths and reservoir pressures demand dynamic positioning and managed pressure capabilities. ADES International anchors presence in Egyptian and Saudi waters through fleet modernization.
- Exploration:Frontier drilling in Red Sea and West Africa ultra-deepwater blocks requires high-specification units with dual blowout preventer redundancy. ENI and BP accelerate Mediterranean and Red Sea licensing rounds that demand jackup rigs with pressure control sophistication.
- Production:Infill drilling and sidetrack operations in mature fields prioritize mechanical drilling rate efficiency over exploration-grade specifications. Zohr gas field periphery development in Egypt emphasizes cost-per-foot optimization.
Onshore drilling maintains volume leadership, with offshore exploration showing the steepest expansion trajectory as licensing rounds accelerate.
Deployment:
Water depth classification determines rig type, day-rate structure, and supply chain complexity for mobilization and demobilization.
- Land:Desert and arid environment operations across Saudi Arabia, Kuwait, and Algeria require cooling systems and dust mitigation for electronic control packages. High-horsepower AC rigs with automated pipe handling dominate newbuild programs.
- Shallow Water:Jackup rigs operating in water depths below 400 feet support UAE and Qatar offshore field development. ADNOC's Upper Zakum expansion and QatarEnergy's North Field projects sustain demand for premium cantilever units.
- Deep Water:Semisubmersible and drillship operations in 1,500-5,000 foot water depths concentrate off West Africa and in the Red Sea. Nigerian and Angolan licensing rounds under the Petroleum Industry Act framework target these depths for pre-salt and post-salt prospects.
- Ultra Deep Water:Operations exceeding 5,000 feet require dual-gradient drilling and managed pressure integration. TotalEnergies and Shell mandate certified low-carbon drilling packages for new West African development wells facing EU Green Deal carbon border compliance.
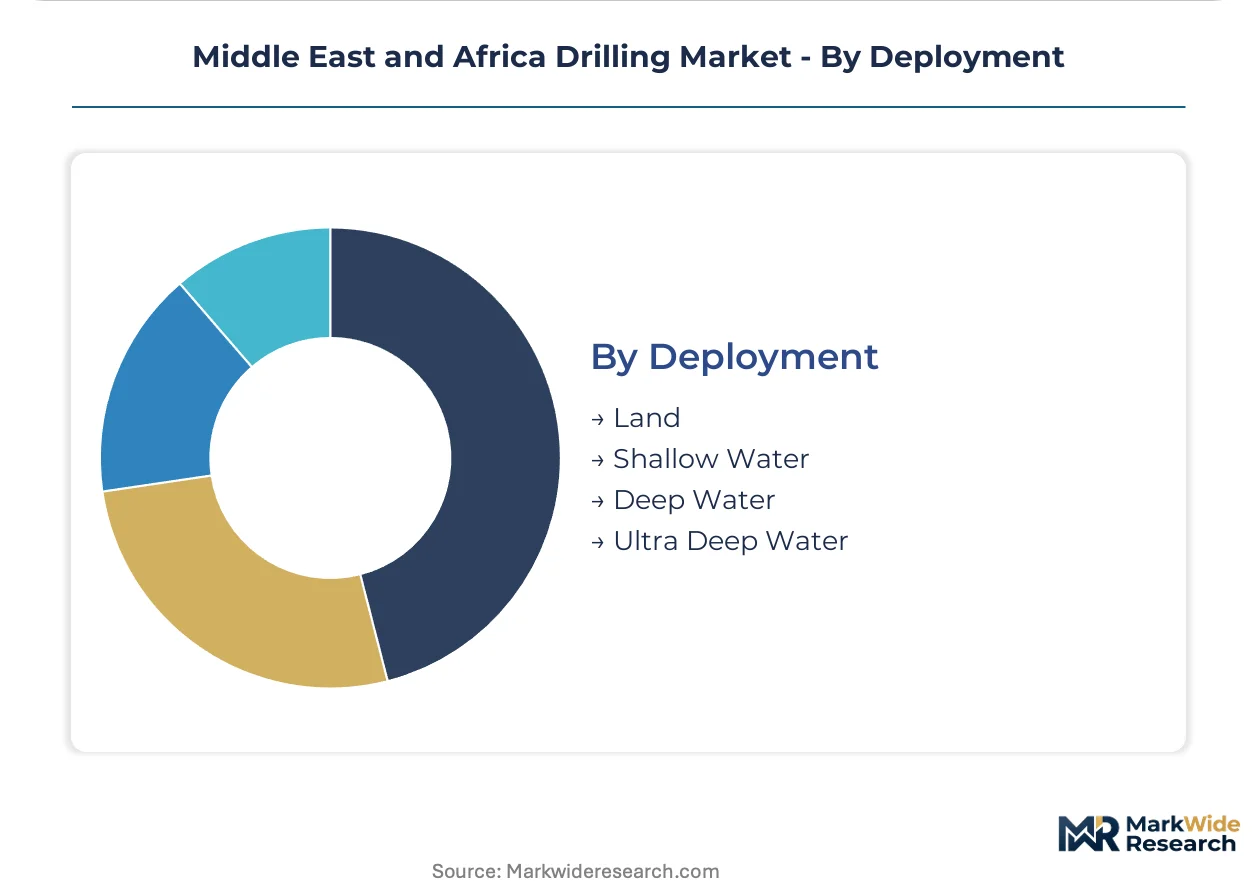
Land deployment captures the highest rig count, with ultra deep water gaining share fastest as frontier exploration budgets redirect toward Red Sea and West Africa prospects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting drilling investment toward jurisdictions with streamlined permitting and lower carbon compliance burdens. Operators are relocating high-specification rig deployment from European-destined production zones toward Gulf Cooperation Council markets where national oil companies absorb environmental disclosure costs. This migration concentrates capital in markets with performance-based contract structures and integrated service frameworks.
Saudi Arabia
Saudi Aramco's rig fleet expansion targets Ghawar and Safaniya field redevelopment with automated pipe handling and real-time downhole measurement systems. The In-Kingdom Total Value Add program mandates domestic crew participation and equipment sourcing for all new drilling contracts. Dhahran anchors the Eastern Province drilling cluster where Arabian Drilling Company and ADES International compete for integrated project tenders.
United Arab Emirates
ADNOC's Upper Zakum and Bab field developments drive demand for premium jackup rigs with managed pressure capabilities and dynamic positioning systems. The country's national petroleum regulator enforces technical standards for high-pressure exploration wells exceeding 150°C formation temperatures. Abu Dhabi concentrates offshore licensing activity where ENI and BP accelerate Mediterranean and Red Sea frontier exploration.
Nigeria
The Petroleum Industry Act framework consolidates licensing authority under the Nigerian Upstream Petroleum Regulatory Commission, accelerating offshore bidding rounds in deepwater blocks. Marginal field awardees source managed pressure capabilities through structured service agreements with integrated drilling contractors. Lagos anchors West African drilling procurement where independent producers compete for rig availability against national oil company campaigns.
Egypt
Unawarded Mediterranean and Red Sea blocks present white space for jackup rig operators with managed pressure capabilities as ENI and BP expand Zohr gas field periphery development. The Egyptian General Petroleum Corporation regulates offshore licensing rounds with emphasis on cost-per-foot optimization for mature field workovers. Cairo concentrates contractor procurement decisions for Western Desert onshore programs and Nile Delta shallow water projects.
Angola
Pre-salt and post-salt ultra-deepwater prospects attract semisubmersible and drillship deployment for water depths exceeding 5,000 feet. TotalEnergies and Shell mandate certified low-carbon drilling packages to satisfy EU Green Deal carbon border adjustment requirements for European-destined crude exports. Luanda anchors deepwater service provider clustering where rig upgrades must simultaneously satisfy API standards and emerging EU carbon intensity disclosures.
Middle East and Africa Drilling Market Competitive Landscape
Gulf Cooperation Council national oil companies anchor one tier of demand concentration; international integrated service providers hold technology leadership in automated systems. The market structures around performance-based contract migration that transfers non-productive time risk from operators to contractors. Three archetypes dominate: state-affiliated drilling contractors with fleet modernization programs, integrated service providers accepting footage-based pricing, and independent rig operators targeting frontier exploration blocks. Competitive dynamics center on strategic partnerships with regional service providers and capacity expansion in high-specification jackup and semisubmersible units.
Within the integrated service provider tier, Schlumberger Limited and Baker Hughes Company exemplify technology-led positioning through automated rotary steerable and managed pressure drilling capabilities. ADES International Holding occupies a position among Eastern Mediterranean and Red Sea-focused contractors with jackup fleet modernization programs. These three entities represent distinct competitive vectors: technology integration, regional fleet scale, and national oil company partnership structures.
| Leading Market Players |
|---|
| Arabian Drilling Company (ADC) |
| Schlumberger Limited |
| Baker Hughes Company |
| Weatherford International PLC |
| Transocean Ltd. |
| Saudi Aramco Oil Co. |
| Halliburton Company |
| ADES International Holding |
| CNOOC International Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into high-pressure blowout preventer forging anchors supply positions and pricing power for integrated drilling contractors serving Gulf Cooperation Council national oil companies. Saudi Arabia's In-Kingdom Total Value Add program and Nigeria's domestic crew mandates force foreign operators to absorb local content premiums, compressing margins for non-integrated service providers while shielding state-affiliated contractors from cost volatility.
Pricing Analysis
Direct-to-NOC contract structures eliminate distributor margins and compress pricing transparency between integrated service providers and national oil company procurement teams. Performance-based contracts with footage-based or target-depth pricing dominate Saudi Aramco and ADNOC tenders, transferring non-productive time risk from operators to contractors and narrowing price differentiation between Schlumberger and Baker Hughes bids. Cost compression in conventional rotary drilling intensifies as Arabian Drilling Company and ADES International expand fleet capacity in Saudi waters. Marginal field awardees under Nigeria's Petroleum Industry Act framework exhibit highest price sensitivity, while ultra-deepwater Red Sea and West Africa exploration programs show lowest sensitivity due to technical threshold requirements.
Supply Chain Analysis
Premium alloy forging for drillstring components and high-pressure blowout preventer systems rests on concentrated capacity in South Korea, Japan, and China, exposing Middle East and African operators to extended lead times and input cost volatility. Specialized metallurgy for HPHT applications, polycrystalline diamond compact bit substrates, and dynamic annular pressure control equipment feed from East Asian supply chains with limited alternative sourcing. Single-source vulnerability concentrates in subsea wellhead connectors and managed pressure drilling control systems. Distribution runs through integrated service provider logistics hubs in Dhahran, Abu Dhabi, and Lagos, with rig mobilization coordinated through regional port infrastructure serving Red Sea and West African offshore blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East and Africa drilling operates as a late-cycle quality story where operator procurement gravitates toward automated rotary steerable and managed pressure capabilities that command premium positioning over conventional directional equipment.
For Market Incumbents: Acquire high-specification jackup and semisubmersible rig assets with integrated managed pressure drilling packages to defend against fleet modernization cycles favoring automated systems over conventional directional equipment. Expand backward integration into blowout preventer forging partnerships with East Asian suppliers to mitigate lead time volatility and input cost pressure from concentrated alloy supply chains. For New Entrants and Emerging Players: Digital-channel route partnerships with national oil company procurement platforms offer lowest-friction entry into Egyptian Mediterranean and Red Sea licensing rounds where ENI and BP accelerate frontier exploration. Target unawarded blocks in the Zohr gas field periphery and Nigerian deepwater pre-salt prospects as most penetrable white-space segments, leveraging structured service agreements with marginal field awardees under the Petroleum Industry Act framework. For Investors and Strategic Acquirers: Consolidation pressure builds where state-affiliated drilling contractors with fleet modernization programs compete against integrated service providers accepting footage-based pricing risk. Long-term viability favors contractors with captive high-specification rig capacity and national oil company partnership structures. Signal to watch: ADNOC and Saudi Aramco procurement shifts toward guaranteed mechanical drilling rate contracts rather than rig availability metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Pressure Drilling Integration | Saudi Aramco and ADNOC mandates for Ghawar and Upper Zakum fields collapse drilling-completion engineering boundaries. |
| Fleet Modernization Programs | ADES International and Arabian Drilling Company jackup upgrades target Red Sea and Egyptian Mediterranean frontier blocks. |
| Local Content Partnership Structuring | In-Kingdom Total Value Add and Nigerian domestic crew requirements force foreign contractor joint ventures with regional service providers. |
| Performance-Based Contract Migration | Footage-based pricing transfers non-productive time risk from national oil companies to Schlumberger and Baker Hughes. |
| Carbon Disclosure Certification | EU Green Deal border adjustments require TotalEnergies and Shell to mandate low-carbon drilling packages for Angolan ultra-deepwater exports. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractor operations executives, national oil company procurement directors, rig fleet managers, and petroleum regulatory commission officials with secondary validation through customs trade data, SEC filings of listed drilling contractors, national petroleum regulator licensing databases, and Gulf Cooperation Council energy ministry production disclosures. Bottom-up rig count and utilization modeling triangulated against top-down capital expenditure forecasts from national oil company budget announcements.
Segment-weighting approaches distributed value across rotary, directional, managed pressure, and coiled tubing technology tiers, with end-user splits between integrated operators, independent producers, service providers, and government entities. Deployment classifications across land, shallow water, deep water, and ultra-deepwater water depths informed supply-demand balancing. CAGRs derived from rig fleet expansion announcements, licensing round timelines, and frontier exploration budget redirections. Forecast inputs incorporated HPHT well complexity indices and EU Green Deal carbon border compliance cost assumptions.
The model assumes a particular technology adoption path; alternative pathways for managed pressure drilling standardization in conventional carbonate formations would alter the outlook. Forecasts reflect assumptions regarding Saudi Aramco and ADNOC procurement continuity, Nigerian Petroleum Industry Act implementation pacing, and East Asian alloy forging capacity expansion. A small set of named triggers warrants ongoing watch: EU carbon border adjustment enforcement tightening, Red Sea ultra-deepwater licensing acceleration, and directional drilling specialist training pipeline expansion across Gulf and North African jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Proppant Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
North America Shale Market