
 GCC and North Africa Coiled Tubing Market | 2026-2036
GCC and North Africa Coiled Tubing Market Size, Share, and Industry Trends Forecast 2026-2036
GCC and North Africa Coiled Tubing Market Intelligence
Offshore production optimization is repositioning capital allocation across the GCC and North Africa coiled tubing landscape. Baker Hughes Company leverages its integrated well intervention portfolio to anchor deepwater contracts in Saudi Arabian waters. Halliburton sustains manufacturing scale through regional service bases in the UAE and Oman. Schlumberger Limited dominates technology leadership in real-time telemetry systems for coiled tubing operations.
Coiled tubing consists of continuous-length steel or composite pipe manufactured in diameters typically ranging from one to three and one-half inches, spooled onto large reels for repeated deployment into oil and gas wells without jointed connections. Its primary industrial purpose centers on live-well intervention, enabling operators to circulate fluids, perform mechanical workovers, and convey logging tools while maintaining wellbore pressure control. Intervention services command the largest revenue share among service types, reflecting the region's substantial inventory of aging wells requiring remediation across Kuwait's Burgan field and Libya's Sirte Basin. Well stimulation applications within the onshore segment are expanding fastest as hydraulic and mechanical technologies unlock tighter carbonate formations in Oman and Algeria.
Saudi Aramco's well integrity standards, modeled on API specifications and enforced through the country's national oil company procurement frameworks, shape product certification requirements for tubing fatigue ratings and connection performance. The UAE's civil defense and environmental regulations, administered through the Abu Dhabi National Oil Company supplier qualification system, restrict market access to service providers meeting specific HSE and equipment inspection protocols. Stakeholders must monitor how automated coiled tubing systems reshape labor requirements and capital intensity across North African markets where operator budgets remain sensitive to hydrocarbon price volatility.
Market Dynamics
Mature field rehabilitation across Saudi Arabia and Algeria is compressing intervention cycle times as national regulators tighten well integrity mandates. Service providers face mounting pressure to deploy continuous tubing systems capable of extended-reach laterals while maintaining pressure control.
Growth Catalysts
- SFDA well integrity protocols:Saudi Arabia's national oil company procurement frameworks now mandate API-compliant fatigue ratings for all coiled tubing deployed in Ghawar and Safaniya fields.
- Carbonate stimulation demand:Hydraulic and mechanical unlocking of tight formations in Oman's interior basins is accelerating well intervention programs.
- Digital monitoring convergence:Real-time telemetry integration with coiled tubing units is reducing non-productive time across Kuwait's Burgan field operations.
Market Restraints
- Steel alloy input volatility:Chrome-molybdenum tubing grades face price pressure from concentrated metallurgical supply chains in East Asia.
- Composite material technical ceilings:Current polymer matrix coiled tubing lacks the pressure ratings required for deep HPHT wells in Algeria's Hassi Messaoud complex.
- ADNOC supplier qualification barriers:The UAE's civil defense and environmental protocols restrict market access to providers meeting specific HSE and equipment inspection standards.
Strategic Opportunities
- Libya's Sirte Basin rehabilitation:Aging well stock across the country's central petroleum province offers untapped intervention volume as security conditions stabilize.
- Automated rig-up systems:Labor-reducing coiled tubing deployment equipment addresses North African operator sensitivity to hydrocarbon price volatility.
- MOHAP environmental compliance incentives:The UAE's federal health authority is aligning procurement preferences with reduced-emission well intervention technologies.
Industry Challenges
- Specialized welder scarcity:Fatigue-resistant tubing connection certification requires qualified personnel pools that remain thin across North African service bases.
- Legacy SCADA integration friction:Digital coiled tubing monitoring systems face protocol mismatches with decades-old wellhead control architectures in Algeria's mature fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC and North Africa Coiled Tubing Market |
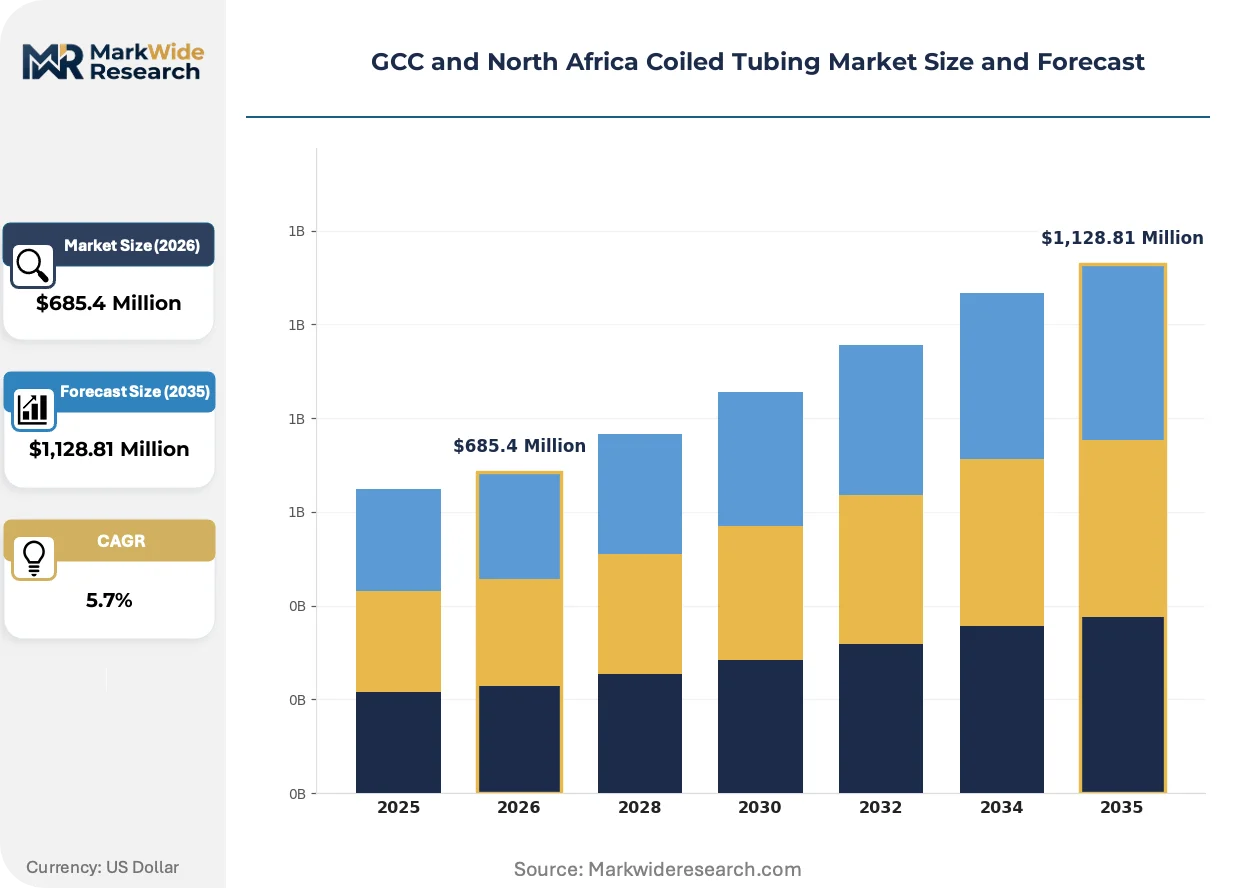
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,128.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Completion, Intervention, Well Abandonment Application: Onshore, Offshore, Production Optimization, Well Stimulation End User: Oil & Gas Operators, Service Providers, EPC Contractors, Independent Producers Technology: Mechanical, Hydraulic, Electric, Automated Systems |
| Companies Covered | Weatherford International plc, Elite Coil Tubing Solutions Saudi Co., Baker Hughes Company, ASECO, Emirates Western, Schlumberger Limited, Archer Limited, SLB, Halliburton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC and North Africa Coiled Tubing Market Strategic Shifts & Innovations
Equipment architecture and service delivery models across the GCC and North Africa coiled tubing sector are fragmenting as operators demand greater operational flexibility. Three distinct movements are reshaping competitive positioning.
Composite-reinforced coiled tubing is modularizing field deployment configurations. Operators in Oman's tight carbonate plays are adopting spoolable pipe systems that reduce rig-up footprint by sixty percent versus conventional steel units. This technology is modularizing service provider asset bases, allowing regional players to compete for contracts previously reserved for integrated majors with heavy crane fleets.
SFDA enforcement of API RP 5C5 connection performance standards is compressing supplier qualification timelines. The Saudi regulator's well integrity mandates now require documented fatigue test data for every tubing string deployed in national oil company fields. Premium connection manufacturers with pre-certified product lines are capturing procurement share from fabricators lacking Saudi-specific validation.
Integrated service contracting is displacing discrete equipment rental across Abu Dhabi's offshore concessions. ADNOC's operating companies are bundling coiled tubing with pressure pumping and wireline services under single-provider frameworks. This consolidation is most visible in the Upper Zakum field, where bundled intervention packages now dominate tender structures.
GCC and North Africa Coiled Tubing Market Segmentation
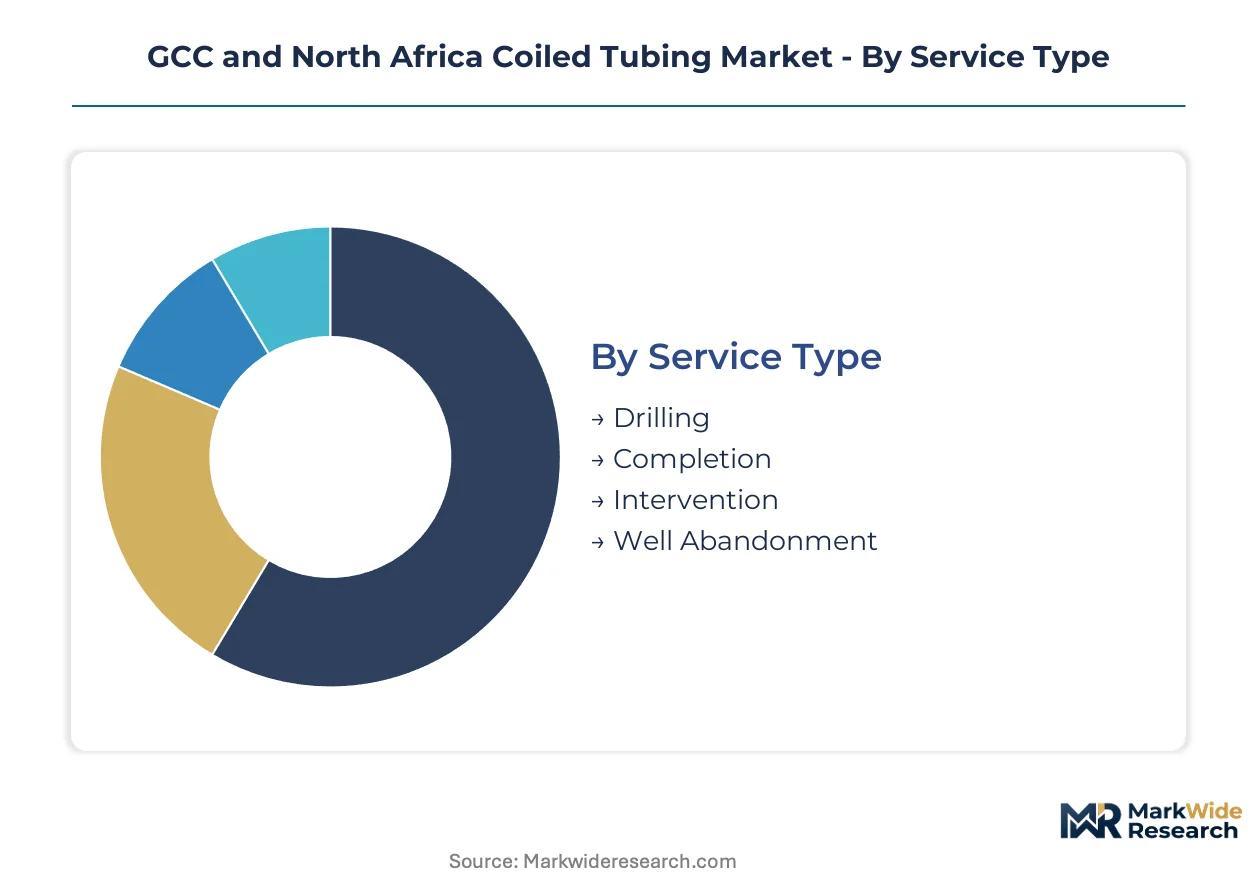
Service differentiation across the GCC and North Africa coiled tubing landscape reflects divergent capital cycles between mature field rehabilitation and new development. Equipment specifications and deployment protocols vary sharply across intervention, completion, and abandonment workflows, creating distinct supplier qualification requirements.
Service Type:
Upgrade cycles for coiled tubing units correlate directly with regulatory enforcement intensity across Saudi Arabia and Algeria.
- Intervention:Live-well circulation and mechanical workover operations utilize continuous tubing to maintain pressure control during remedial operations. Demand concentrates in Ghawar and Safaniya fields where SFDA well integrity mandates compress replacement timelines for fatigue-critical strings.
- Completion:Initial well preparation and zone isolation services deploy specialized tubing configurations for sand control and gravel pack operations. Growth is accelerating in Oman's tight carbonate formations where extended-reach laterals require continuous conduit deployment.
- Drilling:Underbalanced and slim-hole drilling applications employ coiled tubing as a drill string alternative in specific reservoir conditions.
- Well Abandonment:Plug and abandonment services utilize coiled tubing for cement placement and barrier verification in end-of-life wells across Libya's Sirte Basin.
Volume placements concentrate in Intervention; the faster expansion belongs to Completion.
Application:
Cost-tier differentiation separates premium offshore specifications from standardized onshore deployments.
- Onshore:Desert and interior basin operations dominate tubing consumption across Saudi Arabia's central province and Algeria's Hassi Messaoud complex. Standardized steel grades with API-compliant connections satisfy most intervention requirements in these mature fields.
- Well Stimulation:Hydraulic and acid fracturing applications require pressure-rated tubing strings capable of handling corrosive chemical environments. Carbonate unlocking in Oman and Algeria is driving specialized metallurgy demand for high-pressure injection services.
- Offshore:Platform and subsea interventions command premium fatigue ratings and real-time telemetry integration for deepwater pressure control.
- Production Optimization:Sustained yield enhancement through velocity string installation and artificial lift conveyance represents a recurring revenue stream.
Onshore deployments retain the largest installed base; Well Stimulation is climbing the fastest.
End User:
Customer-type fragmentation shapes procurement patterns from integrated national oil companies to specialized independents.
- Oil & Gas Operators:Saudi Aramco, ADNOC, and Sonatrach dominate tubing consumption through direct procurement frameworks specifying API fatigue ratings and connection performance standards.
- Service Providers:Baker Hughes, Halliburton, and Schlumberger maintain captive tubing inventories aligned with regional service base requirements and national oil company qualification protocols.
- EPC Contractors:Engineering and construction firms bundle coiled tubing services within integrated field development packages, particularly in Abu Dhabi's offshore concession awards.
- Independent Producers:Smaller operators in Libya and Egypt rely on rental-based access to coiled tubing units without dedicated capital deployment.
Procurement authority rests with Oil & Gas Operators; Independent Producers are gaining share fastest.
Technology:
Margin structures diverge sharply between conventional mechanical systems and digitally integrated automated platforms.
- Mechanical:Conventional hydraulic and pressure-driven tubing deployment remains the workhorse technology across North African markets sensitive to capital intensity. Standard rig-up configurations with manual control systems satisfy baseline intervention requirements in Algeria and Libya.
- Automated Systems:Reduced-crew deployment equipment with integrated monitoring and autonomous pressure control is penetrating Saudi Arabian and UAE operations where labor costs and safety protocols drive technology substitution.
- Hydraulic:Fluid-power actuation systems dominate well stimulation and circulation applications requiring precise pressure management.
- Electric:All-electric tubing units with variable frequency drives offer precision control for logging tool conveyance and delicate mechanical interventions.
Mechanical systems retain volume dominance; Automated Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia produces the majority of regional coiled tubing demand while the UAE concentrates service provider headquarters and manufacturing scale. Algeria and Oman generate substantial consumption through mature field rehabilitation programs. Libya represents latent capacity pending security stabilization.
Saudi Arabia
Ghawar and Safaniya field operators deploy continuous tubing for extended-reach laterals and live-well interventions. SFDA enforcement of API RP 5C5 connection standards compresses supplier qualification timelines for fatigue-critical strings. Eastern Province clusters around Dhahran and Dammam host the densest concentration of service bases and equipment yards.
United Arab Emirates
ADNOC procurement frameworks bundle coiled tubing with pressure pumping and wireline services under single-provider contracts. MOHAP environmental compliance incentives align federal health authority preferences with reduced-emission well intervention technologies. Abu Dhabi's Upper Zakum offshore field anchors premium-tier demand for real-time telemetry integration.
Algeria
Sonatrach intervention programs across Hassi Messaoud target HPHT well conditions exceeding current composite tubing pressure ratings. The country's national oil company procurement specifications mirror API fatigue standards with additional desert durability requirements. Illizi and Ouargla basins concentrate onshore rehabilitation activity.
Oman
Interior basin carbonate stimulation accelerates specialized metallurgy demand for high-pressure acid and hydraulic fracturing services. Petroleum Development Oman tight formation unlocking drives extended-reach lateral deployment configurations. Muscat service corridors link fabrication facilities to interior drilling camps.
Libya
Sirte Basin aging well stock offers intervention volume as National Oil Corporation rehabilitation budgets expand. The country's civil conflict legacy leaves well integrity standards fragmented across operating subsidiaries. Tripoli and Benghazi logistics corridors remain primary supply chain chokepoints pending infrastructure normalization.
GCC and North Africa Coiled Tubing Market Key Industry Players
Top-tier vendors anchor integrated service contracting, while regional specialists and equipment fabricators occupy mid-market positions. The vendor base stratifies across three tiers: international majors with captive manufacturing, regional service companies with qualified rental fleets, and independent tubing fabricators supplying non-critical strings. Dominant competitive moves include ADNOC-style bundled service packaging and SFDA-driven pre-certification of connection systems.
Within the integrated major tier, Baker Hughes Company, Halliburton, and Schlumberger Limited exemplify archetypes of technology leadership and manufacturing scale. These entities occupy positions spanning digital telemetry integration, regional service base networks, and pre-qualified product lines aligned with Saudi and Emirati procurement frameworks. Regional specialists such as Elite Coil Tubing Solutions Saudi Co. and Emirates Western represent qualified rental and fabrication capabilities calibrated to national oil company supplier protocols.
| Leading Market Players |
|---|
| Weatherford International plc |
| Elite Coil Tubing Solutions Saudi Co. |
| Baker Hughes Company |
| ASECO |
| Emirates Western |
| Schlumberger Limited |
| Archer Limited |
| SLB |
| Halliburton |
| Others |
Cost & Logistics Intelligence
API RP 5C5 pre-certification divergence separates premium connection manufacturers from commodity fabricators across GCC procurement frameworks, compressing qualification timelines for Saudi Aramco and ADNOC contracts while relegating uncertified suppliers to spot-market pricing in North African basins. This certification ladder simultaneously reshapes inventory positioning, with pre-qualified vendors holding regional safety stock near Dhahran and Abu Dhabi while uncertified players rely on concentrated East Asian mill shipments with extended lead times.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent over spot inventory pricing dominate contract structures for SFDA-mandated fatigue-rated strings in Saudi Arabia's Ghawar field. Project-based long-term offtake agreements anchor pricing for integrated majors with captive manufacturing, while rental-based spot transactions serve Libyan independents. Price differentiation rests on API certification tier and volume scale, with bulk procurement by Sonatrach commanding standard-grade discounts. Cost compression in commodity steel grades is intensifying due to chrome-molybdenum input volatility from East Asian metallurgical supply chains. Independent producers in Egypt and Libya exhibit highest price sensitivity; ADNOC bundled service contractors show least.
Supply Chain Analysis
Domestic-content mandates under Saudi Aramco's IKTVA program and ADNOC's In-Country Value requirements are reshaping sourcing patterns toward local fabrication facilities in Dammam and Abu Dhabi. Raw material supply concentrates in China, Japan, and South Korea for high-grade steel alloys and polymer matrix composites. Component dependencies span fatigue-resistant welding consumables, precision connection threading equipment, and real-time telemetry sensors. Single-source vulnerability in specialized chrome-molybdenum grades poses structural risk given concentrated East Asian mill capacity. Distribution runs through service company captive inventories aligned with national oil company qualification protocols, supplemented by regional rental fleets for non-critical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into fatigue-rated connection manufacturing and pre-certification testing capacity represents the critical competitive race, as SFDA and ADNOC procurement frameworks reward in-house API RP 5C5 validation capabilities while penalizing third-party-dependent suppliers with compressed margins and extended qualification cycles.
For Market Incumbents: Anticipate displacement from automated coiled tubing systems by acquiring regional specialists with certified connection portfolios in Saudi Arabia and the UAE. Prioritize backward integration into metallurgical testing facilities to secure SFDA pre-certification timelines. Defensive consolidation around real-time telemetry integration addresses Schlumberger's technology leadership threat in digital monitoring convergence.
For New Entrants and Emerging Players: Launch via rental-based service models targeting Libya's Sirte Basin rehabilitation as security conditions stabilize, exploiting fragmented well integrity standards and limited incumbent presence. The most penetrable white-space sits in automated rig-up systems for North African operators sensitive to hydrocarbon price volatility. Go-to-market angle: labor-reducing deployment equipment bundled with basic intervention services.
For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing ADNOC supplier qualification and pre-certified API connection portfolios given bundled contracting convergence in Abu Dhabi's offshore concessions. Long-term viability over the mid-decade horizon favors automated system integrators over conventional mechanical rental fleets. Signal to watch: ADNOC tender structures shifting from discrete equipment rental to single-provider intervention packages.
| Strategic Initiative | Industry Significance |
|---|---|
| API RP 5C5 Pre-Certification Investment | SFDA enforcement compresses supplier qualification timelines for Ghawar and Safaniya field contracts. |
| Automated Rig-Up System Deployment | Labor-reducing equipment addresses North African operator budget sensitivity to oil price volatility. |
| Composite Tubing Pressure Rating Extension | Polymer matrix advancement targets HPHT well conditions in Algeria's Hassi Messaoud complex. |
| Real-Time Telemetry Integration | Digital monitoring convergence reduces non-productive time across Kuwait's Burgan field operations. |
| Libya Service Base Reactivation | Sirte Basin aging well stock offers intervention volume as National Oil Corporation budgets expand. |
Research Approach
Independent corroboration across service company operations directors, national oil company procurement officers, and metallurgical testing engineers underwrites the qualitative findings in this study. Primary interviews with coiled tubing unit managers, ADNOC supplier qualification leads, and SFDA regulatory affairs specialists combined with secondary validation from API specification databases, SEC filings of integrated service majors, and customs records of steel alloy imports. Bottom-up equipment fleet counts and top-down national oil company expenditure patterns were triangulated to anchor volume estimates.
Comparable historical periods spanning mature field rehabilitation cycles and regulatory enforcement phases anchored the projection framework across the analysis window. Segmentation dimensions modeled include service type, application tier, end-user procurement authority, and technology integration level. CAGRs were derived from equipment replacement timelines correlated with regulatory mandate implementation and intervention program expansion rates. Industry-specific forecast inputs encompass SFDA well integrity protocol adoption curves and ADNOC bundled contracting penetration.
Chrome-molybdenum price volatility, Libya security condition normalization, and composite tubing pressure rating advancement are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and national oil company capital allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market