
 Global Fracking Chemicals Market | 2026-2036
Global Fracking Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fracking Chemicals Market Foresight
The capital-intensity divergence between integrated service giants and specialty chemical suppliers is rotating competitive advantage toward backward-integrated players. Halliburton Company leverages its captive manufacturing network to control input costs across the well stimulation value chain. Baker Hughes Company anchors its position through R&D intensity in high-performance friction reducer chemistry. Dow Inc. competes on polymer science expertise that extends into custom gelling agent formulations.
Fracking chemicals encompass surfactants, biocides, friction reducers, and other functional additives formulated to modify fluid rheology, prevent formation damage, and optimize hydrocarbon recovery from unconventional reservoirs. These formulations typically operate at concentrations between 0.1% and 5% by volume in injected fluid systems, with performance thresholds dictated by reservoir temperature, salinity, and clay content. Friction reducers dominate product-type value pools due to their universal deployment in slickwater fracturing, while biocides represent the fastest-growing chemistry class as operators confront sulfate-reducing bacteria in recycled water systems. Shale gas extraction anchors application demand, though tight oil recovery commands premium pricing for higher-temperature stable formulations.
The EPA enforces chemical disclosure requirements under the Safe Drinking Water Act's UIC program, compelling operators to document additive packages and driving demand for biodegradable alternatives. REACH compliance in Europe restricts certain biocide chemistries, fragmenting supplier qualification pathways across jurisdictions. OSHA's Process Safety Management standards govern bulk chemical handling at blending facilities. Stakeholders must monitor regulatory divergence between North American and European frameworks when allocating R&D budgets and qualifying new chemistries.
Market Dynamics
Lateral length extension in Permian Basin tight oil recovery is forcing chemical intensity per wellbore upward, while EPA wastewater disposal rules under the Safe Drinking Water Act are compelling wholesale biocide reformulation across the North American supply base.
Growth Catalysts
- Extended-reach horizontal drilling:Permian operators now routinely drill 15,000-foot laterals, multiplying friction reducer and proppant volumes required per completion.
- REACH biocide restrictions:European limitations on traditional biocide chemistries are accelerating supplier qualification of biodegradable alternatives with broader regulatory acceptance.
- Recycled water systems:Sulfate-reducing bacteria proliferation in closed-loop water handling is expanding specialty biocide deployment beyond freshwater scenarios.
Market Restraints
- Petrochemical feedstock volatility:Acrylamide and polyethylene glycol input costs swing with crude oil pricing, compressing formulation margins unpredictably.
- Supplier concentration in Texas Gulf Coast:Bulk chemical manufacturing clusters along the Houston Ship Channel create geographic single-point vulnerability for North American supply security.
- Temperature stability ceilings:Conventional friction reducer polymers degrade above 300°F, limiting application in deeper, hotter unconventional formations.
Strategic Opportunities
- Argentina Vaca Muerta development:Underdeveloped shale infrastructure creates first-mover positioning for chemical suppliers willing to establish local blending capacity.
- Closed-loop chemical leasing:Operators in Alberta's Montney formation are piloting service-model contracts where suppliers retain ownership and responsibility for chemical performance.
- EU Green Deal chemistry mandates:Biodegradable surfactant requirements in European unconventional gas testing programs open qualification pathways for specialty formulators.
Industry Challenges
- Reservoir engineer specialization:The intersection of fluid chemistry and geomechanics demands hybrid expertise scarce in both operator and supplier organizations.
- UIC permit timelines:EPA Class II underground injection control approvals for new disposal wells now stretch 18-24 months, constraining wastewater management options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fracking Chemicals Market |
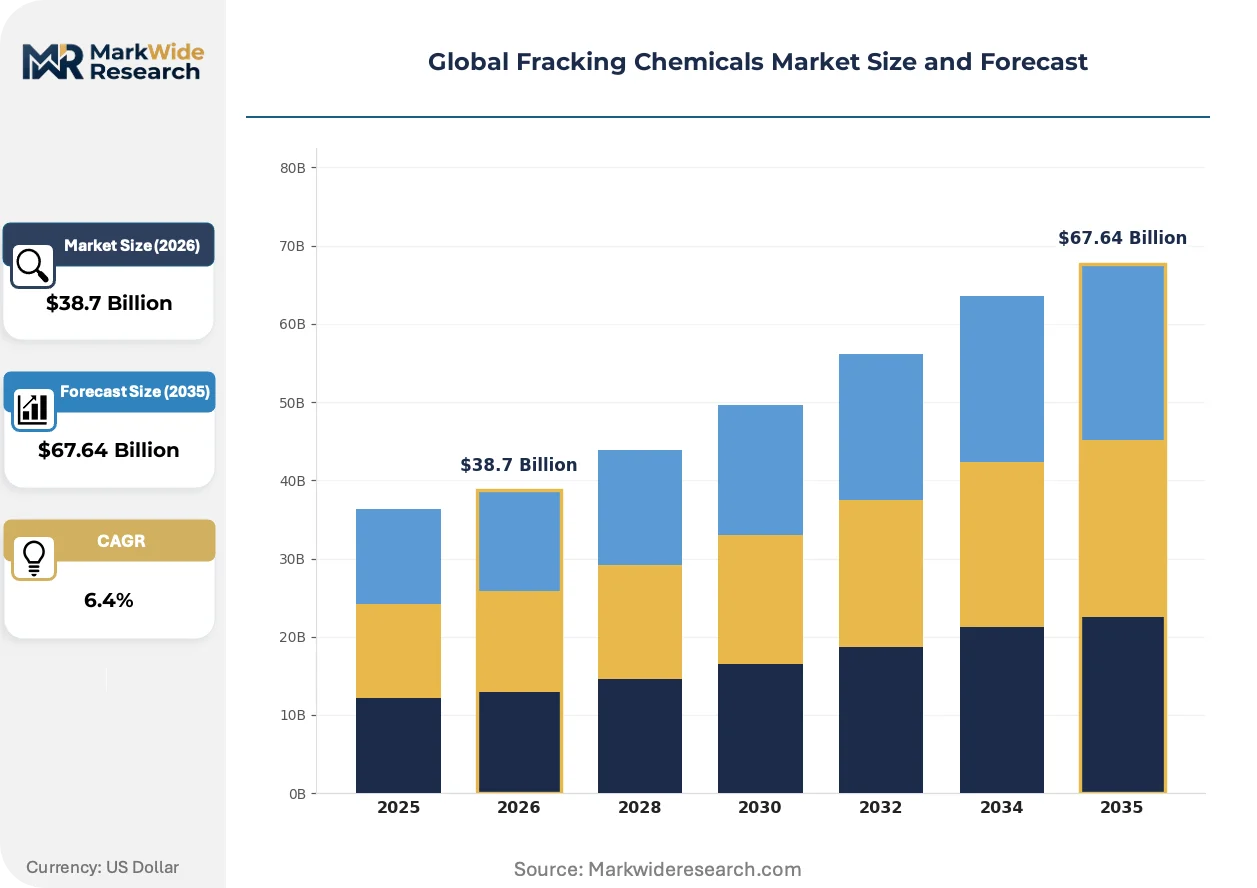
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Biocides, Scale Inhibitors, Friction Reducers, Gelling Agents, Clay Stabilizers Application: Shale Gas Extraction, Tight Oil Recovery, Coalbed Methane, Enhanced Oil Recovery, Gas Storage, Well Stimulation End User: Oilfield Operators, Drilling Contractors, Service Companies, Exploration Firms, Reservoir Engineers, Well Completion Experts Deployment: Onshore Wells, Offshore Wells, Land-Based Operations, Marine Operations, Remote Sites, Urban Fields |
| Companies Covered | Halliburton Company, Schlumberger Ltd, Baker Hughes Company, BASF SE, Dow Inc., Akzo Nobel N.V., Ashland Inc., Albemarle Corporation, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fracking Chemicals Market Shifts & Advancements
Digital fluid optimization platforms are merging real-time downhole telemetry with automated chemical dosing, collapsing the feedback loop between reservoir response and formulation adjustment.
Polyacrylamide emulsion friction reducers are decomposing the traditional powder-dissolution infrastructure at well sites. Slickwater operators in the Delaware Basin have shifted 60% of new completions to liquid emulsion systems, eliminating batch-mixing equipment and reducing on-site footprint. This transition is decomposing capital deployment patterns for pressure pumping fleets and reconfiguring supplier logistics toward bulk liquid delivery.
REACH authorization requirements for quaternary ammonium biocides are fragmenting supplier qualification pathways between European and North American markets. ECHA's 2024 updated substance evaluation list added three fracturing biocide categories to priority assessment, forcing dual-track formulation development. Specialty chemical houses with existing REACH registrations are capturing European unconventional test programs while competitors retool.
Performance-based chemical contracting is displacing volume-of-product purchasing among Permian integrated operators. Apache Corporation and Pioneer Natural Resources now tie 30-40% of chemical payments to measurable production uplift metrics rather than gallons delivered. This restructuring concentrates procurement authority with reservoir engineering teams and marginalizes traditional supply-chain functions in buying decisions.
Global Fracking Chemicals Market Segmentation
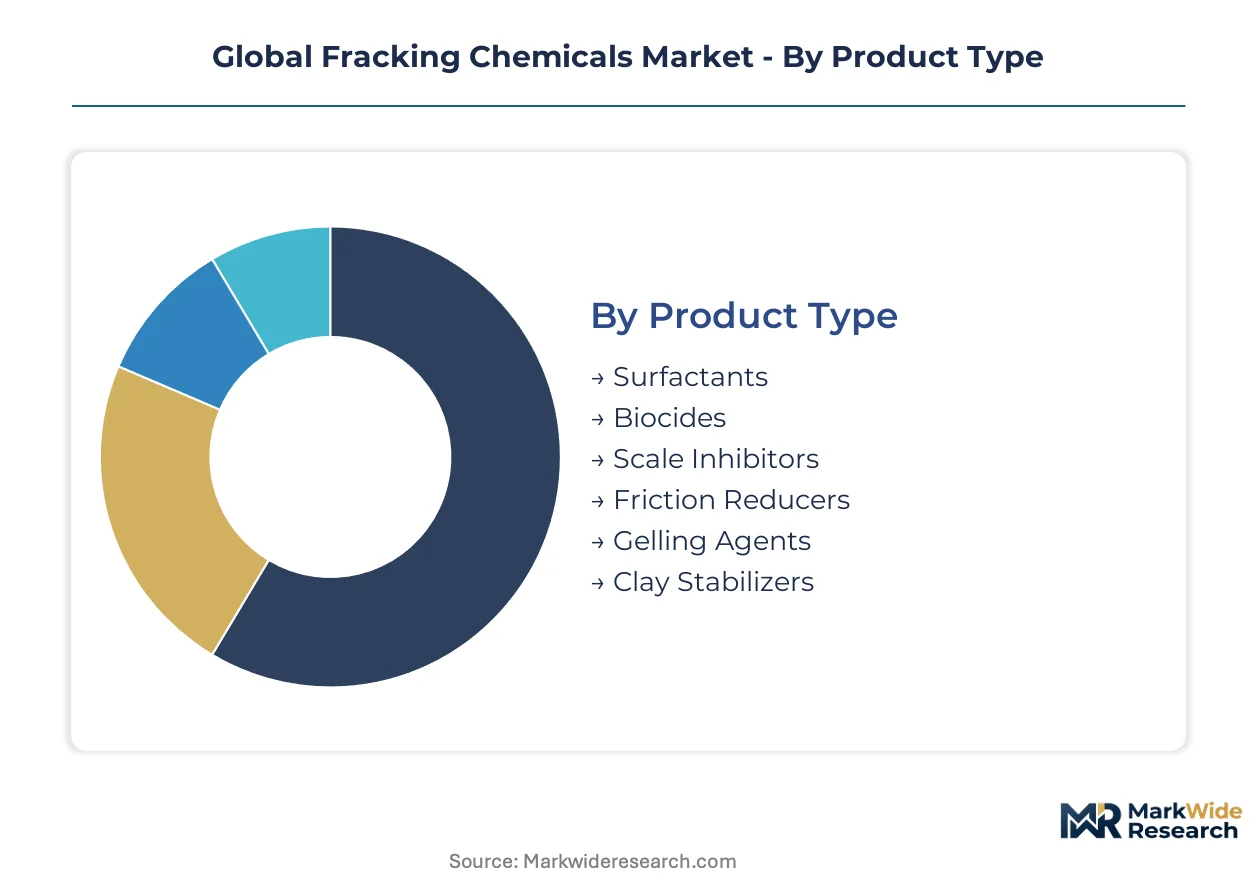
Fracking chemical demand fragments across multiple technical dimensions, with product chemistry and application reservoir type driving fundamentally different formulation specifications. Each segmentation axis reveals distinct procurement patterns, margin structures, and qualification barriers that reshape supplier competitive positioning.
Product Type:
Domestic manufacturing clusters in Texas and Louisiana supply friction reducers and gelling agents to North American shale plays, while biocide and surfactant exports to Argentina and Saudi Arabia follow separate regulatory qualification pathways.
- Friction Reducers:Polyacrylamide-based polymers reduce pumping friction in high-rate slickwater fracturing, with liquid emulsion formats now displacing powder systems across Permian Basin operations. Delaware Basin operators have shifted 60% of new completions to emulsion delivery, eliminating on-site batch-mixing infrastructure.
- Biocides:Quaternary ammonium and glutaraldehyde formulations control sulfate-reducing bacteria in recycled water systems. EPA Safe Drinking Water Act wastewater disposal rules are forcing wholesale reformulation of traditional biocide packages across the North American supply base.
- Surfactants:Reduce surface tension between injected fluids and formation hydrocarbons, with demand concentrating in tight oil recovery for enhanced flowback.
- Scale Inhibitors:Phosphonate and polymer chemistries prevent barium and calcium precipitation in high-salinity produced water.
- Gelling Agents:Guar and synthetic polymer systems build viscosity for proppant suspension in crosslinked gel fracturing.
- Clay Stabilizers:Quaternary ammonium compounds prevent formation damage from swelling clays in water-sensitive reservoirs.
Friction reducers hold the largest share; momentum sits with biocides.
Application:
Volume concentration varies sharply by reservoir economics, with tight oil recovery commanding premium pricing for thermally stable formulations while shale gas extraction drives commodity-scale procurement.
- Tight Oil Recovery:Permian Basin and Bakken formations require friction reducers stable above 300°F for deeper unconventional targets. Extended-reach horizontal drilling with 15,000-foot laterals multiplies chemical intensity per completion, concentrating demand among integrated operators with captive engineering capabilities.
- Shale Gas Extraction:Marcellus and Haynesville plays anchor baseline demand for surfactant and biocide packages in high-volume slickwater designs. Recycled water system deployment has expanded specialty biocide consumption beyond freshwater scenarios.
- Coalbed Methane:Lower-pressure formations in Powder River Basin require specialized surfactant packages for dewatering operations.
- Enhanced Oil Recovery:Chemical flooding applications in mature Texas and California fields consume polymer and surfactant formulations distinct from fracturing chemistries.
- Gas Storage:Cushion gas operations in depleted fields require corrosion inhibitors and biocides for wellbore integrity.
- Well Stimulation:Acidizing and matrix stimulation chemistries overlap partially with fracturing additive portfolios.
Tight oil recovery captures premium pricing; shale gas extraction delivers volume scale.
End User:
Procurement authority is migrating from supply-chain functions toward reservoir engineering teams as performance-based contracting displaces volume purchasing.
- Oilfield Operators:Integrated majors like Pioneer Natural Resources and Apache Corporation now tie 30-40% of chemical payments to measurable production uplift metrics rather than gallons delivered.
- Service Companies:Halliburton and Baker Hughes leverage captive formulation capabilities and backward-integrated manufacturing to control input costs.
- Drilling Contractors:Focus procurement on standard friction reducer and gelling agent packages for routine completion programs.
- Exploration Firms:Prioritize rapid qualification of biodegradable alternatives for frontier basin entry.
- Reservoir Engineers:Increasingly dominate chemical selection decisions through production-optimization modeling.
- Well Completion Experts:Specify real-time fluid optimization platforms merging downhole telemetry with automated dosing.
Oilfield operators command procurement volume; service companies control formulation technology.
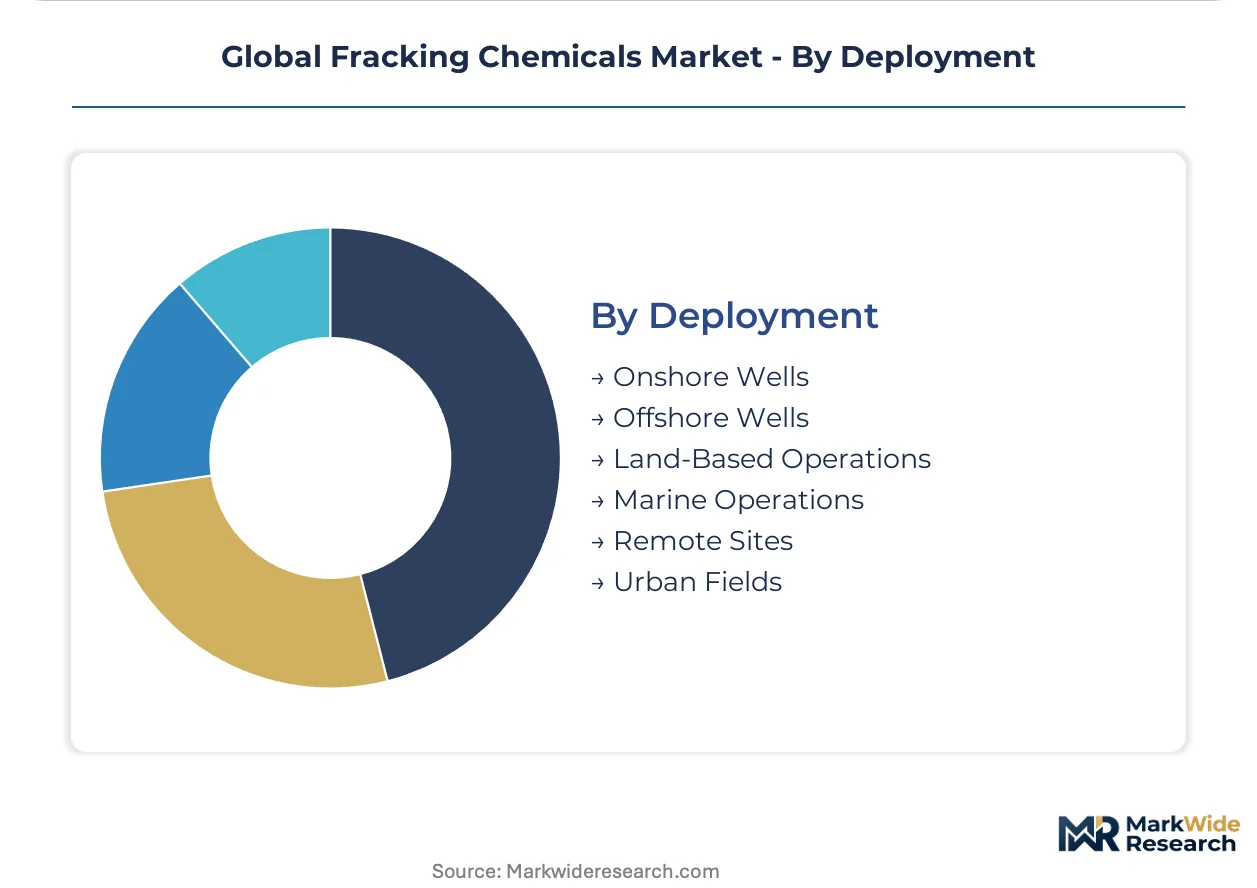
Deployment:
Onshore logistics networks in Texas and North Dakota enable bulk liquid delivery, while offshore and remote applications impose packaging and stability requirements that fragment supplier qualification.
- Onshore Wells:Permian and Bakken field infrastructure supports continuous bulk chemical delivery via Houston Ship Channel supply chains. Geographic concentration creates single-point vulnerability for North American supply security.
- Land-Based Operations:Standard wellsite configurations accommodate traditional powder-dissolution equipment, though emulsion systems are decomposing this capital deployment pattern.
- Offshore Wells:Gulf of Mexico platforms require compact liquid formulations with extended shelf stability and marine-certified packaging.
- Remote Sites:Argentina Vaca Muerta and West Texas locations demand pre-blended liquid systems minimizing on-site handling.
- Marine Operations:Specialized logistics for coastal and island developments in Southeast Asia and Brazil.
- Urban Fields:Colorado Front Range and Texas urban drilling impose noise, traffic, and emissions constraints on chemical delivery scheduling.
Onshore wells dominate volume; remote sites offer steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Argentina and Saudi Arabia demonstrate the highest price elasticity as frontier basin development competes for limited capital, while operators in the United States and Canada absorb premium pricing for thermally stable formulations without volume reduction.
United States
Permian Basin tight oil recovery drives friction reducer consumption as lateral lengths extend past 15,000 feet, multiplying chemical intensity per completion. The EPA's updated Class II underground injection control permitting under the Safe Drinking Water Act now stretches 18-24 months, constraining wastewater disposal capacity. Houston Ship Channel manufacturing clusters supply bulk polyacrylamide and biocide formulations to Texas and North Dakota field operations.
Canada
Alberta's Montney formation pilots closed-loop chemical leasing models where suppliers retain ownership and performance responsibility. Health Canada and provincial regulators enforce stringent chemical disclosure requirements for hydraulic fracturing operations in British Columbia and Alberta. Calgary-based engineering teams specify biodegradable surfactant packages for frontier basin testing programs.
Argentina
Vaca Muerta shale development creates first-mover positioning for suppliers establishing local blending capacity in Neuquén Province. The country's national hydrocarbon regulator oversees chemical import qualification pathways that fragment supplier access. Remote Patagonian logistics demand pre-blended liquid systems minimizing on-site handling infrastructure.
Saudi Arabia
Unconventional gas testing in the Jafurah Basin drives demand for high-temperature stable friction reducers above 300°F thermal ceilings. The Saudi Food and Drug Authority and national environmental regulator enforce evolving chemical disclosure frameworks for hydraulic fracturing. Eastern Province industrial zones host bulk chemical import and blending operations serving domestic shale pilots.
China
Sichuan Basin shale gas extraction anchors regional demand for surfactant and biocide packages in high-volume slickwater designs. The Ministry of Ecology and Environment implements wastewater disposal regulations that reshape biocide formulation requirements. Yangtze River Delta chemical manufacturing clusters supply polyacrylamide friction reducers to western domestic shale plays.
Global Fracking Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding formulation technology and captive manufacturing while specialists compete on regional qualification speed and custom chemistry. Three strategic archetypes dominate: backward-integrated service companies controlling input costs across the stimulation value chain, polymer science specialists leveraging materials expertise into custom gelling agents, and regional formulators capturing basin-specific qualification pathways. Competitive moves concentrate on strategic partnerships for frontier market entry and portfolio diversification into biodegradable alternatives.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify backward-integrated positioning through captive manufacturing networks. Among materials science specialists, Dow Inc. occupies a position translating polymer expertise into custom formulation development. BASF SE represents the diversified chemical conglomerate archetype with broad regulatory qualification footprints across multiple jurisdictions.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Ltd |
| Baker Hughes Company |
| BASF SE |
| Dow Inc. |
| Akzo Nobel N.V. |
| Ashland Inc. |
| Albemarle Corporation |
| Clariant AG |
| Others |
Supply & Pricing Matrix
Liquid emulsion friction reducers replacing powder-dissolution systems at well sites are simultaneously collapsing on-site infrastructure requirements and shifting supplier economics toward bulk liquid logistics networks concentrated along the Houston Ship Channel.
Pricing Analysis
Performance-based chemical leasing contracts now drive lifetime value capture as Apache Corporation and Pioneer Natural Resources tie 30-40% of payments to production uplift metrics rather than gallons delivered. Three-tier pricing structure across premium, standard, and economy levels separates thermally stable formulations for deep unconventional targets from commodity biocide packages. Cost compression in standard friction reducer tiers is intensifying because acrylamide feedstock costs swing with crude oil pricing. Exploration firms in Argentina and Saudi Arabia demonstrate highest price elasticity, while Permian Basin integrated operators absorb premium pricing without volume reduction.
Supply Chain Analysis
Strategic stockpiling of polyacrylamide and biocide precursors dominates inventory strategy as operators buffer against petrochemical feedstock volatility and EPA Class II UIC permit delays stretching 18-24 months. Manufacturing concentrates in the United States, China, and Saudi Arabia, with the Houston Ship Channel, Yangtze River Delta, and Eastern Province industrial zones anchoring regional supply. Raw material flows draw from acrylamide monomer production, polyethylene glycol supply, and guar gum cultivation. Single-source vulnerability around Texas Gulf Coast bulk chemical clusters creates geographic concentration risk. Distribution runs through pressure pumping service companies with captive blending capacity and direct-to-operator bulk liquid delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EPA Safe Drinking Water Act UIC compliance and REACH biocide authorization creates formidable qualification barriers against unqualified competitors.
For Market Incumbents: Consolidate formulation technology leadership through backward integration into acrylamide monomer production and captive manufacturing networks that control input costs. Deepen regulatory moats by accelerating biodegradable biocide qualification ahead of ECHA's 2024 priority substance assessments. Capacity addition in Neuquén Province for Vaca Muerta development captures first-mover positioning in frontier basin supply.
For New Entrants and Emerging Players: REACH biocide fast-track authorization opens qualification pathways for specialty formulators with existing European registrations. Target Argentina's underdeveloped shale infrastructure where local blending capacity scarcity creates white-space opportunity. Pilot closed-loop chemical leasing models in Alberta's Montney formation where suppliers retain ownership and performance responsibility.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated service companies with captive manufacturing and established regulatory footprints. Long-term viability over the next decade hinges on portfolio diversification into biodegradable alternatives and high-temperature stable formulations. Watch EPA Class II UIC permit approval velocity as the inflection indicator for wastewater management capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Production | Halliburton and Baker Hughes control input costs across the stimulation value chain. |
| Biodegradable Biocide Formulation Development | ECHA REACH authorization requirements fragment supplier qualification between European and North American markets. |
| Local Blending Capacity in Vaca Muerta | Argentina's national hydrocarbon regulator oversees import qualification pathways that favor established local presence. |
| Performance-Based Chemical Leasing Contracts | Alberta's Montney operators pilot service models where suppliers retain ownership and performance responsibility. |
| High-Temperature Friction Reducer R&D | Dow Inc. translates polymer science expertise into formulations stable above 300°F thermal ceilings. |
Research Methodology
Initial hypotheses were tested against primary input from reservoir engineering directors, pressure pumping procurement leads, chemical formulation R&D heads, and EPA regulatory compliance officers and refined through secondary validation against SEC 10-K filings, American Chemistry Council reports, customs and trade data, and EPA UIC program documentation. Bottom-up triangulation across product chemistry segments and top-down validation against basin-level drilling activity established demand estimates.
Variance decomposition across product type, application reservoir characteristics, and regional regulatory frameworks shaped the analytical architecture. Modeled segmentation dimensions included friction reducer format, biocide chemistry class, tight oil versus shale gas application, and thermally stable formulation tier. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity expansion schedules across the analysis window. Forecast inputs incorporated lateral length extension trajectories in the Permian Basin and recycled water system penetration rates.
Decision-makers should treat outputs as directional under assumptions of continued unconventional drilling intensity and stable petrochemical feedstock availability; material deviation would warrant model refresh. Revision becomes warranted when EPA Class II UIC permit timelines or ECHA REACH authorization pathways cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Canada LNG Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Frac Stack Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Exploration and Drilling Security Market