
 LNG Storage Tank Market | 2026-2036
LNG Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Storage Tank Market Analysis
The EU Green Deal's methane emissions reduction targets is pivoting European LNG terminal operators toward full-containment membrane systems and advanced boil-off gas recovery. Chart Industries sustains technology leadership in cryogenic equipment manufacturing for small-scale LNG distribution. McDermott International, Ltd anchors large-scale EPC execution for integrated liquefaction and storage complexes across the Gulf Coast and Middle East. GTT dominates membrane containment technology licensing, with its NO96 and Mark III systems installed in the majority of global LNG carrier and onshore tank fleets.
LNG storage tanks are engineered cryogenic vessels designed to contain liquefied natural gas at temperatures near minus 162 degrees Celsius, utilizing double-wall construction with perlite vacuum insulation or membrane containment systems to minimize thermal ingress and vaporization losses. Their primary purpose is to enable seasonal demand balancing, strategic energy reserves, and continuous supply to regasification terminals, peak-shaving facilities, and marine bunkering operations. Membrane tanks capture expanding share in new terminal construction due to lower capital intensity and site adaptability, while spherical tanks retain niche dominance in high-seismic zones requiring inherent structural resilience. Onshore installations generate the dominant revenue pool, though offshore floating storage and regasification unit integrations are gaining traction as coastal land access tightens.
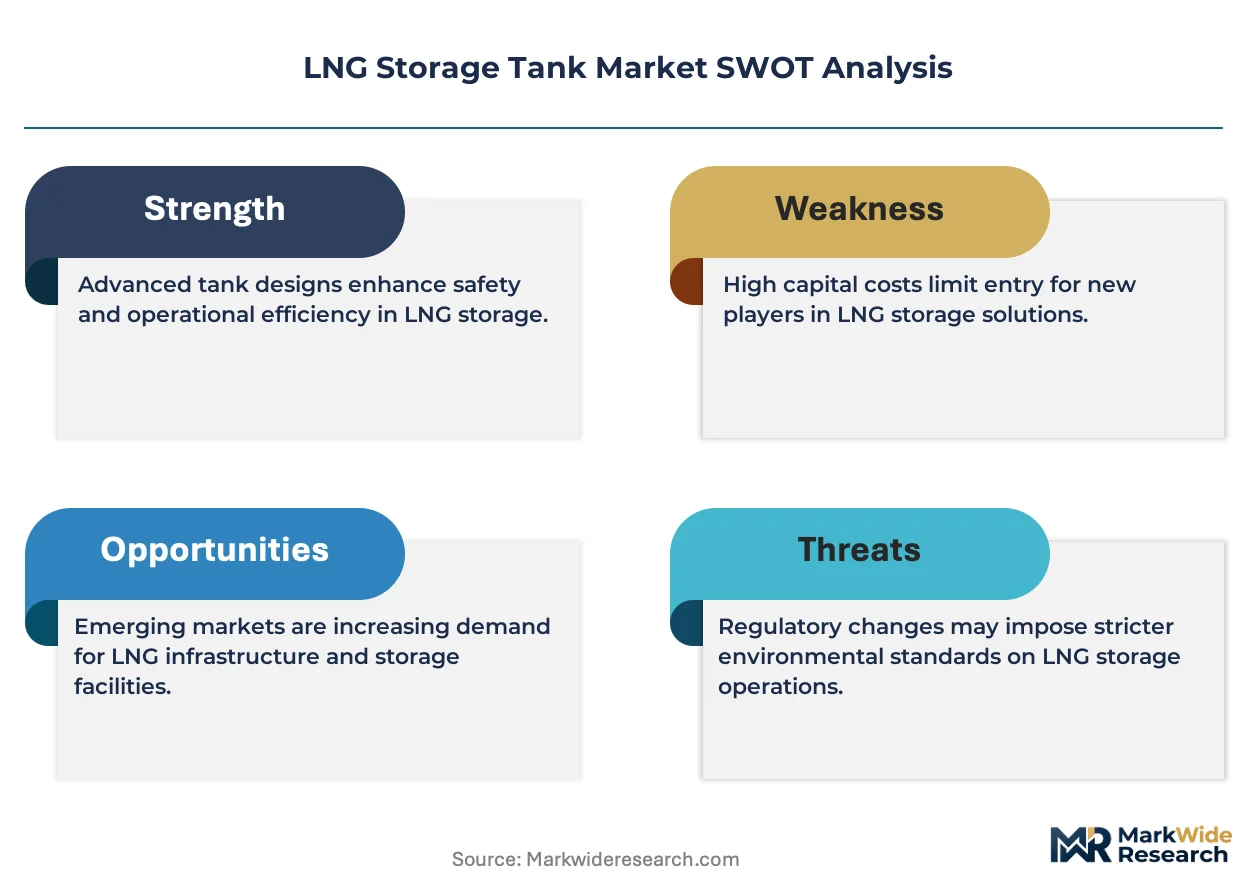
FERC governs siting and safety standards for US LNG peak-shaving and export terminal storage, while the EU F-Gas Regulation constrains refrigerant selections in boil-off gas reliquefaction cycles. Japan's METI enforces stringent seismic design codes through JIS standards that directly dictate tank foundation and anchoring specifications. China GB standards and SAMR certification requirements shape local content rules and pressure equipment conformity for import terminal expansions. Stakeholders must track evolving carbon border adjustment mechanisms and methane intensity benchmarking as these frameworks increasingly condition offtake agreements and terminal access rights.
Market Dynamics
Membrane containment systems are capturing incremental share from full-containment concrete designs as terminal operators prioritize capital efficiency and site flexibility in constrained coastal zones. The shift compresses construction timelines and reduces foundation requirements.
Growth Catalysts
- EU Green Deal methane targets:European terminal operators face binding emissions reduction mandates that accelerate boil-off gas recovery investments and full-containment membrane retrofits.
- Power utility diversification:Asian electric utilities are expanding LNG import infrastructure to displace coal-fired baseload generation and meet air quality commitments.
- Nickel-alloy steel advances:Cryogenic-grade 9% nickel formulations extend tank design life beyond 40 years while cutting thermal ingress rates.
Market Restraints
- Nickel price volatility:9% nickel steel plate constitutes 35-45% of tank material costs, exposing EPC contractors to commodity swings.
- Skilled welder scarcity:Cryogenic vessel certification requires ASME Section IX qualified welders concentrated in South Korea, Japan, and the US Gulf Coast.
- Seismic code fragmentation:Japan's METI enforces JIS-specific foundation designs incompatible with Eurocode or ACI standards, forcing redundant engineering.
Strategic Opportunities
- Small-scale LNG distribution:Cryogenic equipment suppliers are targeting bunkering terminals and truck-loading facilities with sub-30,000 cubic meter tank configurations.
- Floating storage integration:Coastal land constraints in Japan and South Korea are pushing regasification projects toward offshore FSRU-tank hybrid designs.
- China import terminal expansion:SAMR certification pathways and GB standard harmonization create localized supply chain openings for membrane system licensors.
Industry Challenges
- ASME Section VIII certification timelines:Pressure vessel qualification cycles extend 18-24 months, delaying project FIDs and compressing contractor margins.
- Legacy spherical tank retrofit complexity:Existing high-seismic installations require bespoke foundation reinforcement to accommodate membrane containment conversions.
- Boil-off gas reliquefaction integration:F-Gas Regulation refrigerant constraints force simultaneous redesign of storage and processing subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Storage Tank Market |
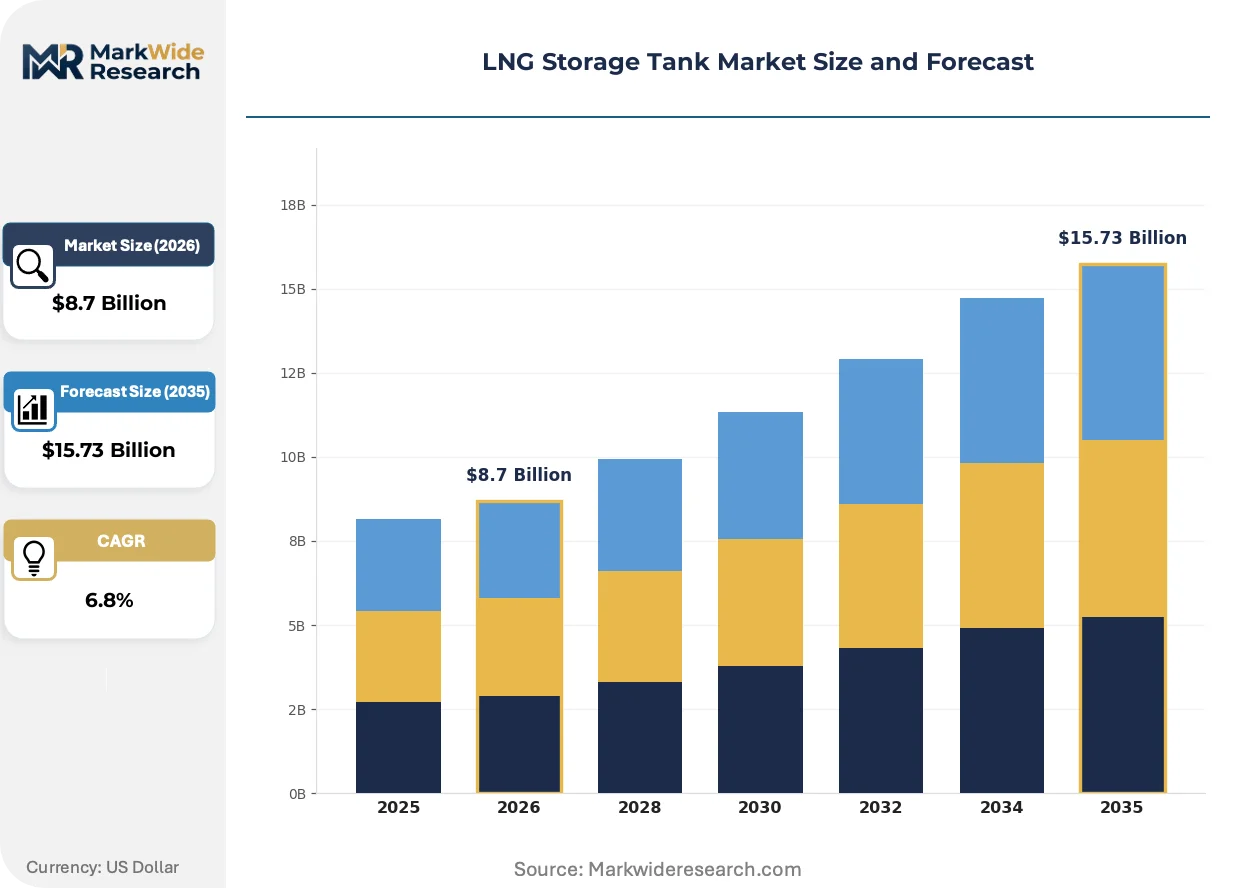
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Spherical Tanks, Membrane Tanks Material: Steel, Aluminum, Stainless Steel, Composite Installation: Onshore, Offshore, Underground, Aboveground End User: Industrial, Commercial, Marine, Energy |
| Companies Covered | McDermott International, Ltd, GTT, Chart Industries, Inc., Mitsubishi Heavy Industries, Ltd, Kawasaki Heavy Industries, Ltd., CIMC Enric, IHI Corporation, Baker Hughes Company, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Storage Tank Market Emerging Trajectories
Pre-fabricated tank modules and digital twin commissioning are compressing construction schedules while elevating quality assurance precision. These shifts reward suppliers with modular manufacturing capabilities and integrated project delivery expertise.
Membrane containment technology is modularizing tank construction through pre-fabricated membrane panel systems shipped to site for field assembly. Japanese and South Korean shipyards with LNG carrier experience are transferring this methodology to onshore terminals. The approach is modularizing project execution by enabling parallel civil and mechanical workstreams, cutting site labor requirements by half.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerants in boil-off gas reliquefaction cycles, forcing terminal operators toward mixed-refrigerant or nitrogen-expansion alternatives. Equipment suppliers must redesign compressor trains and heat exchanger packages to accommodate lower-GWP working fluids. European import terminals face the steepest compliance curves, with retrofit deadlines compressing procurement timelines.
Terminal operators are unbundling long-term EPC contracts into separate storage tank, regasification, and civil work packages to improve cost transparency and risk allocation. Chinese and Middle Eastern buyers are driving this fragmentation, pitting specialized tank contractors against integrated project developers. The shift is most pronounced in Gulf Coast export terminal expansions, where developers seek to optimize contractor selection across each subsystem.
LNG Storage Tank Market Segmentation
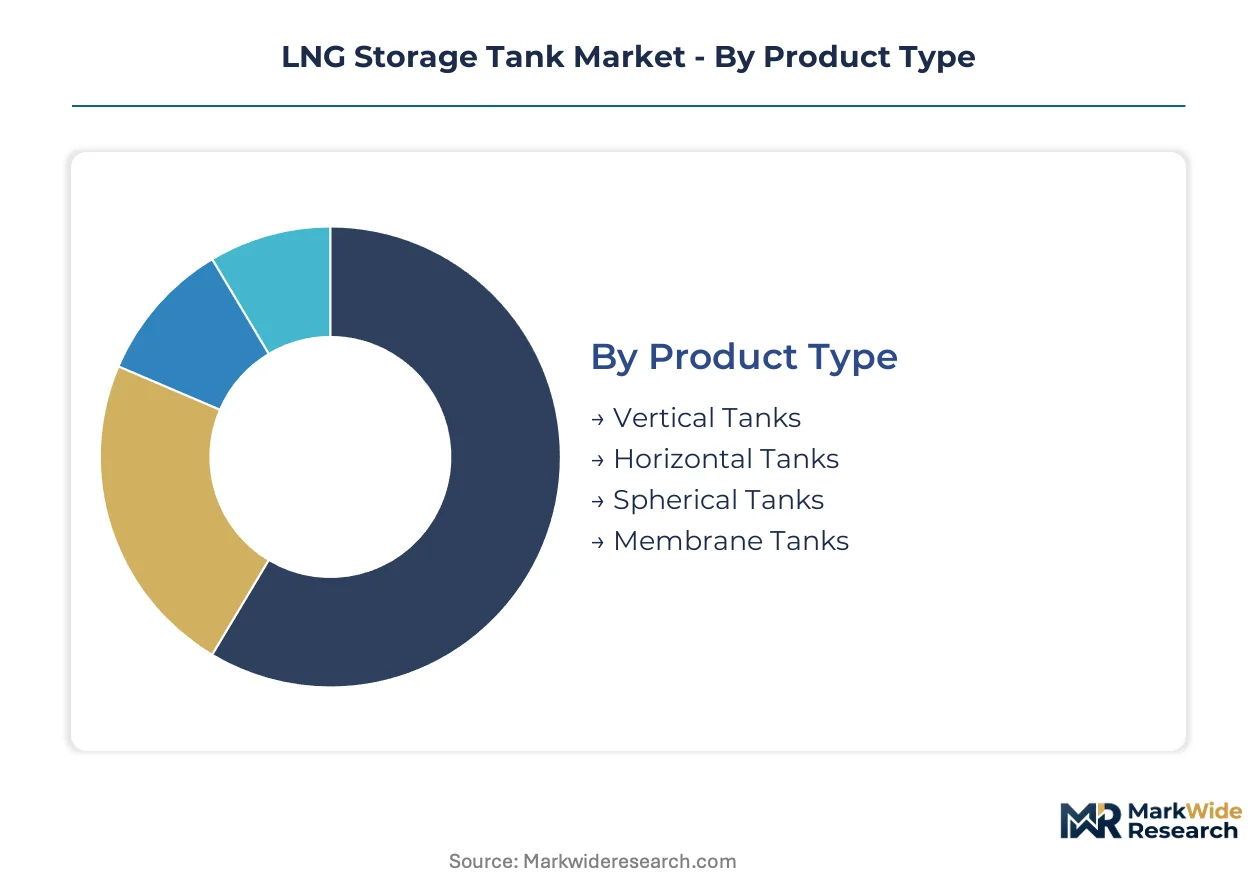
LNG storage tank procurement decisions hinge on certification pathways, seismic zone classifications, and boil-off rate specifications that vary sharply across tank geometries and containment systems. Segmentation reveals how terminal operators balance capital efficiency against regulatory compliance and site-specific constraints.
Product Type:
ASME Section VIII certification governs pressure vessel design across all configurations, though membrane systems additionally require GTT or CST licensing agreements for proprietary containment technology.
- Vertical Tanks:Cylindrical double-wall vessels with perlite vacuum insulation dominate onshore import terminal installations. Demand concentrates in China and Japan where space constraints favor footprint-efficient designs and METI seismic codes mandate reinforced foundation anchoring.
- Membrane Tanks:Pre-fabricated panel systems utilizing corrugated stainless steel membranes and rigid polyurethane foam insulation enable modular construction timelines. Chinese terminal expansions under SAMR certification pathways are absorbing capacity from Korean shipyards transferring LNG carrier expertise to onshore applications.
- Horizontal Tanks:Low-profile configurations suit peak-shaving facilities and truck-loading terminals with height restrictions.
- Spherical Tanks:Inherent structural resilience retains dominance in Japan's high-seismic zones despite higher capital intensity per cubic meter.
Leading the category by volume: Vertical Tanks. Growing fastest: Membrane Tanks.
Material:
Material selection directly determines weld qualification requirements, with 9% nickel steel demanding ASME Section IX certified welders concentrated in South Korea, Japan, and the US Gulf Coast.
- Steel:Cryogenic-grade 9% nickel formulations withstand minus 162 degrees Celsius operating temperatures while extending design life beyond 40 years. Japanese and Korean fabricators maintain supply chain control through captive rolling mill relationships.
- Stainless Steel:Austenitic grades dominate membrane containment secondary barriers and cryogenic piping systems. European terminal operators under EU Green Deal methane targets specify enhanced nickel content to reduce thermal ingress and boil-off rates.
- Aluminum:Lightweight properties suit small-scale distribution tanks and marine bunkering applications.
- Composite:Glass-reinforced polymer liners emerge in niche underground installations requiring corrosion resistance.
Dominant by installed base: Steel. Expanding most quickly: Stainless Steel.
Installation:
Installation mode dictates foundation engineering standards, with FERC governing US onshore siting while Japan's METI enforces JIS-specific seismic designs incompatible with Eurocode or ACI alternatives.
- Onshore:Aboveground and underground configurations at regasification terminals generate the dominant revenue pool. Chinese import terminal expansions under GB standards and SAMR certification are driving capacity additions along coastal provinces.
- Offshore:Floating storage and regasification unit integrations gain traction as coastal land access tightens in Japan and South Korea. FSRU-tank hybrid designs bypass terrestrial permitting timelines while accommodating seasonal demand swings.
- Aboveground:Standard configuration for large-scale baseload terminals with direct jetty access.
- Underground:Strategic reserve applications and urban peak-shaving facilities leverage thermal stability and reduced security exposure.
Highest revenue concentration: Onshore. Steepest expansion trajectory: Offshore.
End User:
End-user categories align with distinct procurement specifications, with energy sector buyers prioritizing full-containment systems while marine operators emphasize compact footprint and rapid bunkering cycles.
- Energy:Power utilities across Asia-Pacific drive baseload terminal demand as coal displacement accelerates. Chinese state-owned enterprises and Japanese regional utilities anchor procurement volumes under long-term take-or-pay structures.
- Industrial:Petrochemical feedstock and process heating applications in South Korea and Taiwan require dedicated storage at manufacturing complexes.
- Marine:LNG bunkering terminals and dual-fuel vessel fueling infrastructure expand along Singapore, Rotterdam, and US Gulf Coast port authorities.
- Commercial:Small-scale distribution and peak-shaving utilities serve municipal gas networks and remote power generation.
Primary demand source: Energy. Gaining share fastest: Marine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qinzhou Port anchors China's LNG import expansion, with membrane tank installations accelerating along Guangxi and Fujian coastlines under SAMR certification pathways. Terminal operators in Japan and South Korea face land constraints that push capacity toward offshore FSRU-tank hybrid designs. European developers under EU Green Deal methane targets prioritize boil-off gas recovery retrofits at Rotterdam and Barcelona facilities.
China
State-owned enterprises expand import terminal capacity across Guangdong and Jiangsu provinces to displace coal-fired baseload generation. SAMR certification requirements and GB standard harmonization shape local content rules for pressure equipment conformity. Yangtze River Delta clusters concentrate membrane system fabrication as Korean shipyards transfer LNG carrier expertise to onshore applications.
Japan
Regional utilities deepen LNG dependence for power generation while metropolitan land scarcity constrains greenfield terminal development. METI enforces JIS-specific seismic design codes that dictate tank foundation and anchoring specifications incompatible with Eurocode alternatives. Osaka Bay industrial corridors retain spherical tank dominance in high-seismic zones requiring inherent structural resilience.
South Korea
Electric utilities expand storage capacity to support industrial feedstock demand and seasonal peak-shaving operations. MFDS-aligned pressure vessel standards intersect with captive 9% nickel steel supply chains controlled by domestic fabricators. Ulsan and Geoje shipyard complexes leverage LNG carrier construction experience for modular membrane tank panel production.
United States
Gulf Coast export terminal developers unbundle EPC contracts to optimize contractor selection across storage, liquefaction, and civil subsystems. FERC governs siting and safety standards for peak-shaving and export facility storage tanks. Texas and Louisiana industrial corridors concentrate cryogenic-grade steel fabrication capacity serving integrated liquefaction and storage complexes.
Germany
Terminal operators at Wilhelmshaven and Brunsbüttel accelerate full-containment membrane retrofits to meet EU Green Deal methane emissions reduction targets. ECHA-aligned refrigerant constraints under F-Gas Regulation force redesign of boil-off gas reliquefaction cycles toward mixed-refrigerant alternatives. North Sea port clusters integrate storage expansions with hydrogen import infrastructure planning.
LNG Storage Tank Market Vendor Landscape
The competitive structure tilts toward technology licensors and specialized EPC contractors rather than integrated conglomerates. A concentrated tier of membrane containment specialists and cryogenic equipment fabricators captures premium-margin segments, while regional steel tank constructors compete on civil works integration. Two strategic archetypes dominate: proprietary technology licensors controlling containment system IP, and full-service EPC contractors executing integrated liquefaction-storage complexes. Technology licensing agreements and modular manufacturing partnerships constitute the dominant competitive moves, with second-tier fabricators seeking membrane panel subcontracts to bypass ASME certification barriers.
Among technology-centric specialists, GTT exemplifies the proprietary licensor archetype through its NO96 and Mark III membrane systems. McDermott International, Ltd occupies the integrated EPC position for large-scale terminal execution. Chart Industries, Inc. represents the cryogenic equipment fabrication tier targeting small-scale distribution and bunkering infrastructure. These three anchors illustrate how competitive positioning fragments across IP control, project scale, and application specialization rather than consolidating around unified platform offerings.
| Leading Market Players |
|---|
| McDermott International, Ltd |
| GTT |
| Chart Industries, Inc. |
| Mitsubishi Heavy Industries, Ltd |
| Kawasaki Heavy Industries, Ltd. |
| CIMC Enric |
| IHI Corporation |
| Baker Hughes Company |
| Linde plc |
| Others |
Supply Flow & Price Mechanics
EU Green Deal methane mandates are forcing terminal operators toward full-containment membrane retrofits and boil-off gas recovery systems, compelling EPC contractors to absorb nickel-alloy steel volatility while membrane system licensors capture premium pricing for proprietary NO96 and Mark III technologies.
Pricing Analysis
Throughput-guaranteed performance contracts anchor pricing for large-scale terminal installations, with membrane containment systems commanding 15-25% premiums over conventional concrete designs due to reduced civil works and faster commissioning. Price differentiation separates GTT-licensed membrane technologies from unlicensed steel tank fabricators competing on local content compliance. Cost compression in spherical tank retrofits is intensifying because Japanese METI seismic codes require bespoke foundation reinforcement. Chinese state-owned enterprises exhibit lowest price sensitivity given SAMR certification mandates, while European independent terminal developers face acute budget constraints under F-Gas Regulation compliance deadlines.
Supply Chain Analysis
Transoceanic freight costs for pre-fabricated membrane panels from Korean shipyards to Chinese terminal sites add 8-12% to landed equipment costs, compressing contractor margins on fixed-price EPC contracts. Supply concentrates in South Korea, Japan, and China, with Ulsan and Geoje complexes controlling membrane panel fabrication and Yangtze River Delta clusters absorbing transferred LNG carrier expertise. The supply chain draws from captive 9% nickel steel rolling mills, specialized cryogenic insulation suppliers, and ASME Section IX certified welder pools concentrated in three national hubs. Single-source vulnerability permeates GTT's monopoly on NO96 and Mark III membrane licensing. Distribution runs through EPC contractor-led integrated project delivery for baseload terminals, with modular panel subcontracts bypassing certification barriers for second-tier fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with technology licensors and EPC contractors pursuing captive control over cryogenic-grade steel supply chains and membrane panel fabrication capacity to defend margin structures against nickel price volatility.
For Market Incumbents: Deepen backward integration into 9% nickel steel supply through captive rolling mill partnerships or long-term offtake agreements with Japanese and Korean fabricators. Lock in ASME Section IX certified welder pools through apprenticeship programs in the US Gulf Coast to counter skilled labor scarcity. Defend technology licensing revenues by accelerating Mark III membrane iterations ahead of CST competitive pressure. For New Entrants and Emerging Players: Small-scale LNG bunkering terminals represent the most penetrable buyer archetype, with Singapore, Rotterdam, and US Gulf Coast port authorities expanding dual-fuel vessel fueling infrastructure. Target sub-30,000 cubic meter tank configurations where Chart Industries' cryogenic equipment dominance remains incomplete. Pursue modular manufacturing partnerships with Korean shipyards transferring LNG carrier expertise to onshore applications as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors membrane containment technology specialists with SAMR certification pathways already established. Long-term viability hinges on exposure to China import terminal expansion and European boil-off gas retrofit cycles. Acquisition targets should demonstrate proven GTT or CST licensing relationships plus modular panel production capabilities. Watch FSRU-tank hybrid project FIDs in Japan and South Korea as the inflection indicator for offshore floating storage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | GTT's NO96 and Mark III IP control generates recurring royalty streams from global terminal expansions. |
| Modular Manufacturing Partnership | Korean shipyard transfer of LNG carrier panel fabrication to onshore terminals compresses construction timelines. |
| Backward Integration into Nickel Steel | Captive 9% nickel supply chains insulate EPC margins from commodity volatility and plate availability constraints. |
| ASME Certification Investment | Section VIII and Section IX qualification cycles create 18-24 month barriers protecting incumbent fabricator positions. |
| FSRU-Tank Hybrid Development | Offshore floating storage bypasses Japanese and South Korean coastal land permitting constraints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across EPC project directors, terminal operator engineering leads, cryogenic equipment procurement managers, and membrane system licensing executives. FERC siting databases, SAMR certification registries, METI facility approval records, and EU ETS emissions disclosures provided project-level validation. Bottom-up tank installation counts triangulated against top-down terminal capacity announcements across the analysis window.
Data-stream reconciliation across membrane system shipment records, 9% nickel steel import manifests, and EPC contract award databases informed the analytical framework. Segmentation dimensions modeled encompassed tank geometry, containment technology, material grade, installation mode, and end-use application. CAGRs derived from regression analysis of historical capacity additions against announced project pipelines, with nickel price scenarios and welder availability constraints incorporated as sensitivity inputs.
Revisions become necessary when F-Gas Regulation compliance deadlines shift, METI seismic codes are amended, or nickel price volatility exceeds modeled bands. Forecasts reflect documented assumptions regarding project FID conversion rates and SAMR certification timeline standardization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Drilling Services Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Slickline Services Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Vietnam Oil and Gas Upstream Market