
 Offshore Oil and Gas Paints and Coatings Market | 2026-2036
Offshore Oil and Gas Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Oil and Gas Paints and Coatings Market Analytics
Buyer concentration among production companies is expanding as national oil companies consolidate offshore lease portfolios and centralize coating procurement through long-term framework agreements. PPG Industries sustains technology leadership in fouling-control chemistries for warm-water FPSO hulls. Jotun A/S anchors its position through integrated supply relationships with North Sea drilling contractors. Hempel A/S differentiates via specialized subsea coating systems designed for cathodic protection compatibility at extreme depths.
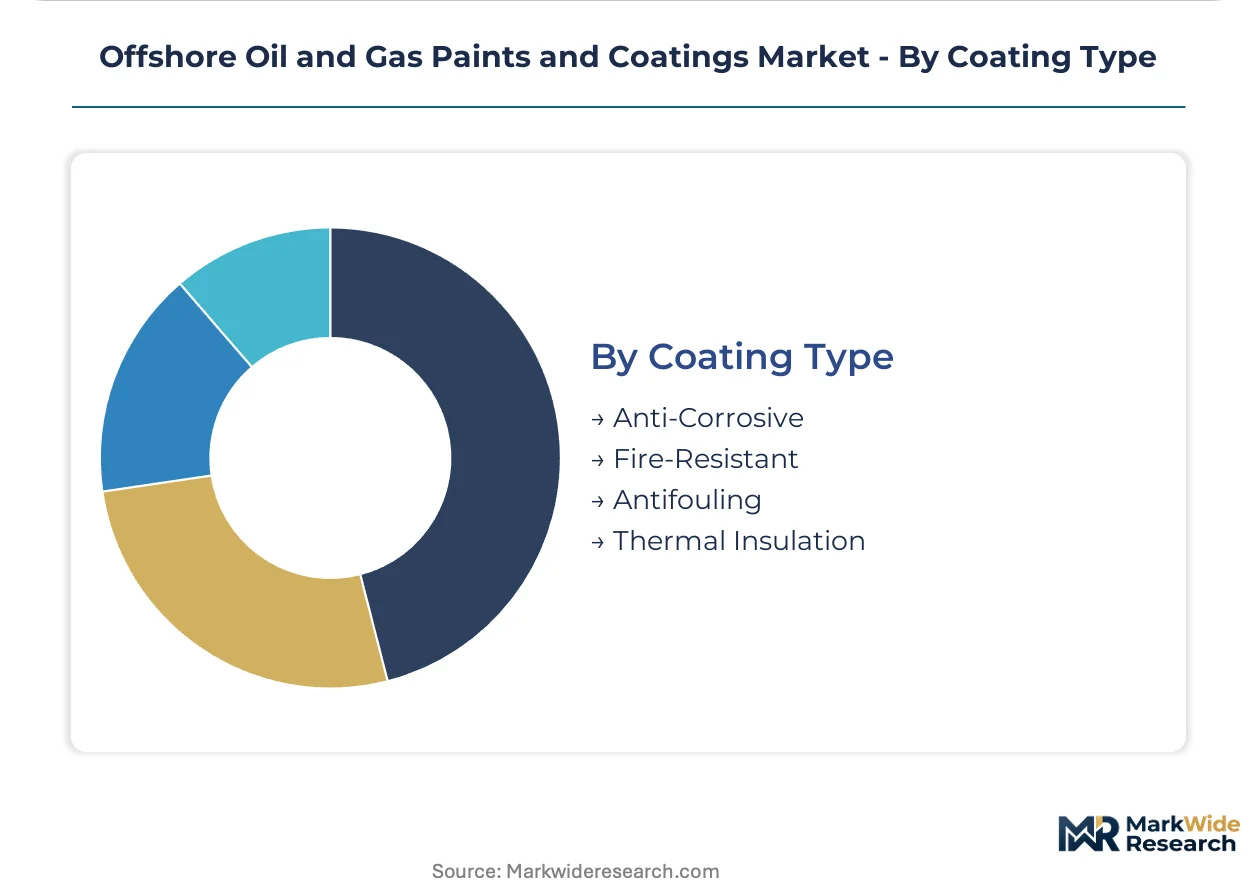
Offshore oil and gas paints and coatings comprise high-performance polymer systems engineered to withstand saline immersion, hydrocarbon exposure, and ultraviolet degradation in marine environments, typically formulated with zinc-rich primers, glass-flake reinforced epoxies, or polysiloxane topcoats applied through airless spray or plural-component methods to achieve dry-film thicknesses exceeding 500 microns. These systems primarily function to extend steel infrastructure service life, prevent corrosion-induced structural failure, and maintain thermal efficiency of subsea flowlines and risers. Epoxy formulations dominate the product type landscape due to their adhesion strength and chemical resistance in splash-zone applications, while polyurethane topcoats command premium positioning for their gloss retention and abrasion performance on superstructures. Within coating types, anti-corrosive systems represent the mature volume base, whereas thermal insulation coatings constitute the fastest-expanding margin pool as operators push into high-pressure high-temperature reservoirs.
NORSOK M-501 in Norway, API RP 5L2 in the United States, and the EU F-Gas Regulation collectively constrain formulation choices and elevate compliance costs for suppliers seeking multi-regional qualification. Brazil's national petroleum regulator enforces ANP technical standards that mandate specific coating performance verification for pre-salt field equipment, creating localized entry barriers. Stakeholders must monitor the divergence between regional qualification protocols and the accelerating material substitution driven by per- and polyfluoroalkyl substance restrictions.
Market Dynamics
Deepwater exploration economics are compressing coating specification cycles as operators demand single-source accountability for 25-year asset protection in Brazil's pre-salt basins and the Gulf of Mexico.
Growth Catalysts
- Pre-salt field development:Petrobras-led projects in Brazil require specialized thermal insulation coatings for ultra-deep installations, creating sustained demand pull for qualified suppliers.
- NORSOK M-501 standardization:Norwegian regulatory harmonization across North Sea drilling contractors reduces qualification duplication and accelerates coating system deployment.
- Cathodic protection integration:Glass-flake reinforced epoxies compatible with impressed current systems are extending subsea infrastructure service life beyond original design specifications.
Market Restraints
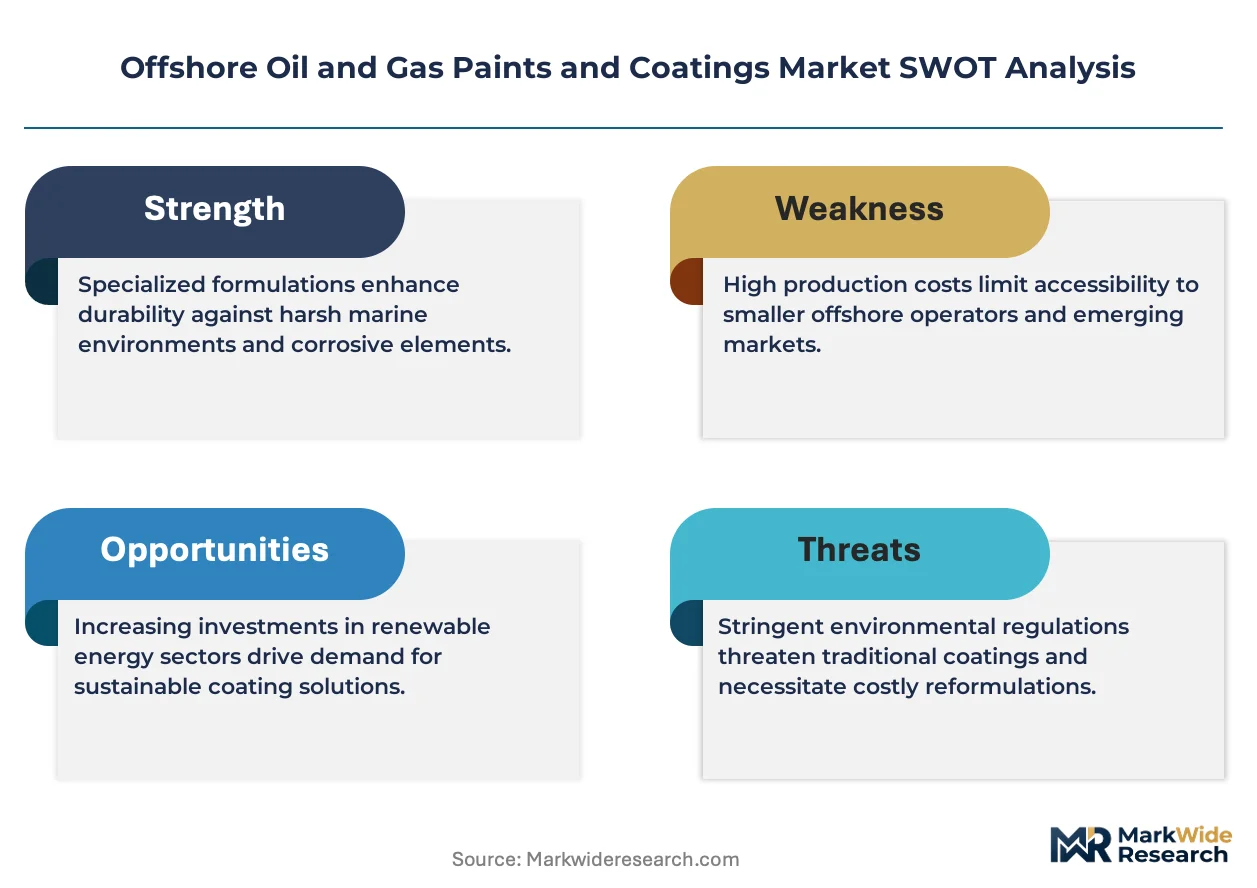
- Zinc raw material volatility:Zinc-rich primer formulations face input cost pressure from concentrate supply concentration in Australia and Peru.
- PFAS restriction cascade:EU F-Gas Regulation and emerging state-level prohibitions in the US are forcing reformulation of fluoropolymer-based fouling control systems.
- Qualification timeline compression:API RP 5L2 verification protocols require 10,000-hour salt spray testing, extending supplier entry cycles to 18-24 months.
Strategic Opportunities
- Decommissioning coatings:North Sea asset retirement programs create demand for temporary corrosion protection systems during 20-year well abandonment phases.
- Digital coating monitoring:Integration of embedded sensors with polysiloxane topcoats enables real-time film thickness verification on FPSO superstructures.
- Carbon capture compatibility:Amine-resistant coating systems for offshore injection platforms represent unqualified white space as CCS clusters form off Norway and the UK.
Industry Challenges
- Spray application certification:Qualified plural-component applicators for 500+ micron dry-film thickness systems remain scarce in West Africa and Southeast Asia.
- Multi-standard compliance:Suppliers must maintain parallel qualification dossiers for ANP technical standards, NORSOK M-501, and API specifications without harmonized reciprocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Oil and Gas Paints and Coatings Market |
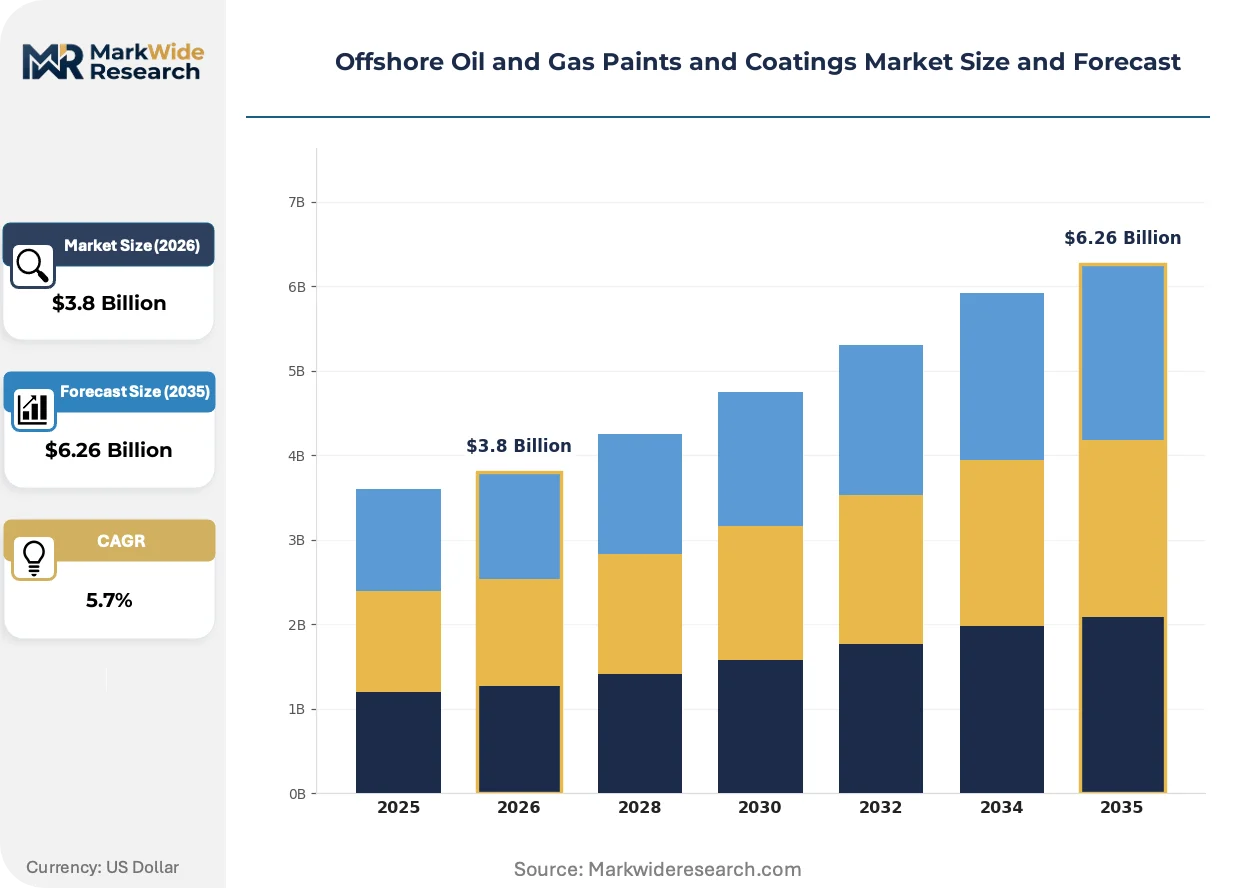
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd Application: Marine Structures, FPSO, Subsea Equipment, Pipelines End User: Exploration Companies, Production Companies, Service Providers, Contractors Coating Type: Anti-Corrosive, Fire-Resistant, Antifouling, Thermal Insulation |
| Companies Covered | Hempel A/S, Axalta Coating Systems, PPG Industries, Inc., RPM International, BASF SE, Akzo Nobel N.V., Jotun A/S, Kansai Paints, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Oil and Gas Paints and Coatings Market Evolving Landscape
Coating specification authority is migrating from engineering contractors to national oil companies, compressing supplier lists and privileging integrated service capabilities over standalone product performance.
Silane-modified epoxy technology is decentralizing subsea coating supply chains by enabling ambient-cure application without heated plural-component equipment. Independent drilling contractors in Southeast Asia are adopting these systems for marginal field tiebacks. The technology is decentralizing procurement authority from major integrated service companies to regional installation specialists.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon propellants from spray-applied coating systems. Formulators are pivoting to waterborne or high-solids alternatives with equivalent sag resistance. Anti-fouling coating categories face the steepest compliance cost escalation, with Mediterranean and Baltic Sea operators advancing adoption timelines by 24 months.
Framework agreement consolidation is compressing coating supplier rosters at Petrobras, Equinor, and BP. Long-term procurement commitments now bundle specification development, inventory management, and offshore application services. Brazil's pre-salt drilling programs exhibit the most pronounced concentration, with three-year master service agreements displacing spot purchasing for hull and subsea systems.
Offshore Oil and Gas Paints and Coatings Market Segmentation
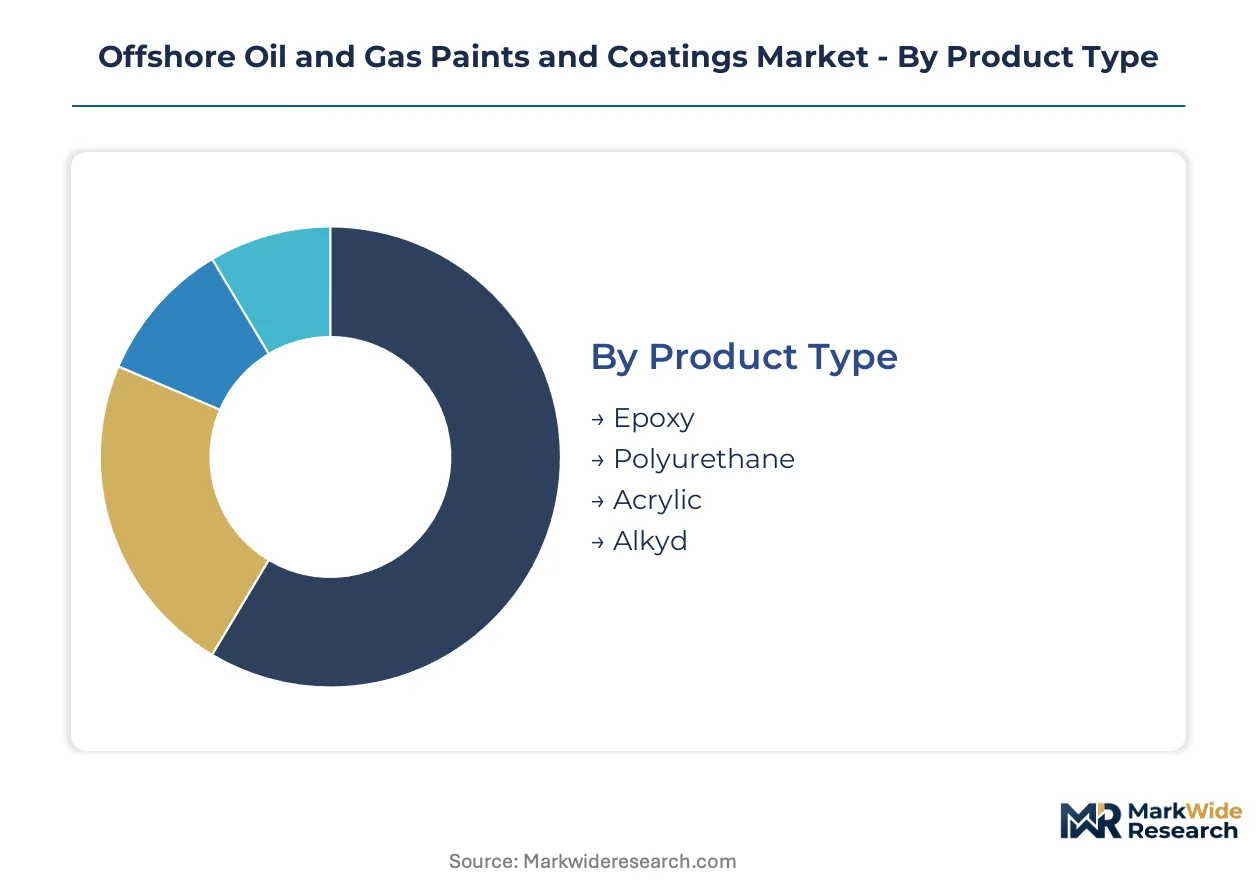
Segmentation in offshore paints and coatings tracks how procurement authority migrates across different asset classes and operator types. Specification divergence between deepwater production systems and shallow-water infrastructure creates distinct margin pools for suppliers.
Product Type:
Cost tier separates buyers seeking 25-year asset protection from those prioritizing application speed and rework flexibility.
- Epoxy:Glass-flake reinforced formulations deliver adhesion strength exceeding 15 MPa on blast-cleaned steel, essential for splash-zone protection on North Sea platforms. Demand concentrates among production companies operating in Norway's harsh marine environments where NORSOK M-501 compliance is mandatory.
- Polyurethane:Aliphatic topcoats retain gloss above 80% after accelerated weathering, commanding premium positioning for FPSO superstructures requiring minimal maintenance during 20-year charter terms. Brazilian operators specify these systems for pre-salt fleet hulls where appearance standards influence charter rates.
- Acrylic:Waterborne formulations serve temporary corrosion protection during decommissioning phases, favored by North Sea asset retirement contractors for their low-VOC compliance with EU F-Gas Regulation phase-down schedules.
- Alkyd:Conventional solvent-borne systems retain niche demand for internal tank linings and non-critical structural steel in mature Gulf of Mexico fields where specification authority has devolved to regional maintenance contractors.
Epoxy leads volumes today; polyurethane is gaining share fastest.
Application:
Application environment dictates cure chemistry, film thickness requirements, and qualification burden for suppliers.
- Marine Structures:Fixed platforms and jack-up rigs require zinc-rich primers at 75-125 microns dry film thickness, with thermal spray aluminum alternatives specified for fireproofing in Norwegian waters. Demand clusters around UK and Norwegian North Sea decommissioning programs.
- FPSO:Hull coating systems must balance anti-fouling performance with cathodic protection compatibility across 25-year design lives. Petrobras framework agreements bundle specification development with inventory management for Brazil's expanding pre-salt fleet.
- Subsea Equipment:Syntactic foam-backed epoxies insulate flowlines and risers in high-pressure high-temperature reservoirs. ANP technical standards mandate specific performance verification for pre-salt field equipment, creating localized entry barriers.
- Pipelines:Fusion-bonded epoxy and three-layer polyethylene systems dominate subsea line pipe, with thermal insulation coatings applied via automated girth-weld stations at spoolbase facilities.
Marine structures anchor current procurement volumes; subsea equipment shows the steepest expansion trajectory.
End User:
Customer type determines whether coatings are procured through framework agreements or spot purchasing.
- Exploration Companies:Wildcat operators prioritize rapid mobilization and temporary protection systems for drilling rigs on short-term contracts. Southeast Asian independents favor silane-modified epoxies enabling ambient-cure application without heated plural-component equipment.
- Production Companies:National oil companies and majors centralize coating procurement through multi-year master service agreements. Equinor, BP, and Petrobras have compressed supplier rosters to three-year bundles covering specification, inventory, and offshore application.
- Service Providers:Drilling contractors and installation specialists seek single-source accountability for asset protection across charter fleets. Jotun A/S anchors its position through integrated supply relationships with North Sea drilling contractors.
- Contractors:Regional fabrication yards compete on coating throughput and qualification speed. Scarce plural-component applicators for 500+ micron systems in West Africa and Southeast Asia constrain local capacity.
Production companies concentrate procurement authority today; contractors are capturing specification influence fastest.
Coating Type:
Functional requirement separates mature volume categories from emerging margin opportunities.
- Anti-Corrosive:Zinc-rich primers and glass-flake epoxies constitute the established volume base, with qualification dossiers maintained for NORSOK M-501, API RP 5L2, and ANP standards simultaneously. Raw material volatility in zinc concentrate supply from Australia and Peru pressures formulation costs.
- Thermal Insulation:Syntactic epoxy systems prevent hydrate formation and paraffin deposition in ultra-deep installations. Petrobras-led pre-salt projects in Brazil require specialized solutions for water depths exceeding 2,000 meters.
- Fire-Resistant:Intumescent coatings expand under heat exposure to protect structural steel for 120-minute ratings. Norwegian platforms mandate these systems for living quarters and process areas under PSA regulations.
- Antifouling:Fluoropolymer-based foul-release coatings face forced reformulation as EU F-Gas Regulation and US state-level prohibitions cascade through supply chains. Mediterranean and Baltic Sea operators have accelerated adoption timelines by 24 months.
Anti-corrosive systems dominate current volumes; thermal insulation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified coating applicators concentrate in coastal industrial zones where offshore fabrication yards cluster near deepwater basins. These workforce pools anchor regional supply capacity for subsea and FPSO projects.
Norway
North Sea decommissioning programs and Johan Sverdrup expansion sustain demand for NORSOK M-501 qualified systems. The Petroleum Safety Authority enforces strict documentation for fire-resistant coatings on platform living quarters. Stavanger and Bergen host the densest concentration of certified plural-component applicators serving Equinor's framework agreements.
Brazil
Pre-salt field development drives procurement of thermal insulation coatings for ultra-deep installations beyond 2,000 meters. The national petroleum regulator mandates ANP technical standards verification for subsea equipment qualification. Rio de Janeiro's shipyard corridor concentrates coating application capacity for Petrobras-led FPSO newbuilds.
United States
Gulf of Mexico deepwater projects require API RP 5L2 compliant systems for 25-year asset protection. The EPA oversees VOC emissions from marine coating operations in coastal zones. Houston and New Orleans anchor the supplier qualification infrastructure serving Chevron and Shell's central procurement functions.
United Kingdom
North Sea asset retirement programs generate demand for temporary corrosion protection during extended abandonment phases. The Health and Safety Executive regulates offshore coating application through offshore installation management protocols. Aberdeen maintains specialist applicator pools for platform maintenance and decommissioning campaigns.
China
Domestic offshore wind-to-oil tieback projects expand specification scope for splash-zone protection systems. The Ministry of Ecology and Environment enforces GB standards for marine coating VOC content. Dalian and Qingdao shipyards develop in-house coating capabilities for state-owned offshore operators.
Offshore Oil and Gas Paints and Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The market structure concentrates around three-to-five integrated suppliers holding multi-year framework agreements with national oil companies. Strategic archetypes include full-service coating system integrators, regional application specialists, and raw material formulators with direct offshore service arms. Competitive moves center on qualification dossier expansion across NORSOK, API, and ANP standards simultaneously, plus backward integration into zinc-rich primer raw material sourcing.
Among European coating specialists, Hempel A/S and Jotun A/S occupy positions within the integrated supply tier for North Sea drilling contractors. PPG Industries represents the diversified conglomerate archetype with fouling-control chemistry capabilities. These three companies exemplify how qualification breadth across multiple regulatory jurisdictions anchors competitive positioning in framework-driven procurement environments.
| Leading Market Players |
|---|
| Hempel A/S |
| Axalta Coating Systems |
| PPG Industries, Inc. |
| RPM International |
| BASF SE |
| Akzo Nobel N.V. |
| Jotun A/S |
| Kansai Paints |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Zinc concentrate feedstock from Australian and Peruvian mining operations flows through three distinct pricing tiers before reaching offshore platform fabricators. Long-term offtake contracts for zinc-rich primer raw materials anchor premium coating system costs, while spot-market exposure pressures economy-grade alkyd formulations for mature Gulf of Mexico maintenance work.
Pricing Analysis
Bundled service packages versus unbundled product-only sales split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates NORSOK M-501 certified systems from API-compliant alternatives and non-certified maintenance grades. Price differentiation hinges on qualification dossier breadth and cathodic protection integration complexity. Cost compression in economy tiers intensifies because zinc raw material volatility concentrates upstream supply. Exploration companies operating short-term drilling contracts exhibit highest price sensitivity, while Petrobras and Equinor procurement teams prioritize 25-year lifecycle value over unit cost.
Supply Chain Analysis
Certification and qualification gating restricts coating system supply to suppliers maintaining parallel NORSOK M-501, API RP 5L2, and ANP technical standard dossiers. Geographic supply concentration centers on Norway, Brazil, and the United States where qualified applicator pools cluster near fabrication yards. Raw material dependencies draw from zinc concentrate, epoxy resin feedstocks, and glass-flake reinforcement supply chains. Single-source vulnerability in zinc concentrate sourcing from Australia and Peru creates structural risk exposure. Distribution runs through master service agreements bundling specification development, inventory management, and offshore application services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as deepwater operators shift procurement toward 25-year asset protection specifications. Thermal insulation coating demand for Brazil's pre-salt ultra-deep installations exemplifies this premium specification migration.
For Market Incumbents: Lock in framework agreement renewals with Petrobras, Equinor, and BP before qualification timelines compress further. Invest in backward integration into zinc-rich primer raw material sourcing to defend margins against concentrate price volatility. Expand NORSOK M-501 certification maintenance capabilities to offset emerging silane-modified epoxy substitution threats from Southeast Asian applicators. For New Entrants and Emerging Players: The price-point gap between premium NORSOK-certified systems and economy-grade maintenance coatings creates entry space for mid-tier API-compliant specialists. Target decommissioning contractors in the United Kingdom seeking temporary corrosion protection with waterborne acrylic formulations. Pursue direct qualification with ANP technical standards for Brazil's pre-salt subsea equipment segment as the most penetrable geography. For Investors and Strategic Acquirers: Consolidation pressure builds where qualification burden outpaces R&D investment capacity for sub-500 million revenue coating specialists. Long-term viability favors integrated suppliers with multi-standard dossiers spanning production company framework agreements. Acquisition target archetype: regional applicators with NORSOK certification and existing Equinor or BP relationships. Watch for silane-modified epoxy adoption acceleration in Southeast Asia as inflection indicator for decentralized procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Dossier Expansion | Multi-standard compliance across NORSOK, API, and ANP opens Petrobras and Equinor procurement channels. |
| Backward Integration into Zinc Sourcing | Captive concentrate supply from Australian or Peruvian operations insulates margin from raw material volatility. |
| Silane-Modified Epoxy Platform Development | Ambient-cure chemistry enables Southeast Asian independent contractors to bypass heated plural-component equipment requirements. |
| Decommissioning Service Capability Buildout | Temporary corrosion protection systems capture North Sea asset retirement program demand from BP and Shell. |
| Digital Coating Monitoring Integration | Embedded sensor partnerships with FPSO operators like Petrobras create recurring service revenue attachment. |
Research Methodology
Bottom-up offshore asset modeling reconciled against top-down coating supplier production tracking forms the analytical core. Primary interviews with coating procurement managers at national oil companies, technical directors at marine fabrication yards, and qualified plural-component applicators in Norway and Brazil combined with secondary validation from API specification documentation, NORSOK M-501 certification registries, and ANP technical standard filings. Customs data on zinc concentrate imports and epoxy resin trade flows triangulated against bottom-up demand estimates.
Historical trendline analysis of coating specification cycles and qualification timeline compression informed projection frameworks across the analysis window. Segmentation dimensions modeled include product chemistry tier, application environment depth, end-user procurement authority type, and regional regulatory cluster. CAGRs derived from asset installation schedules and replacement cycle assumptions for subsea flowlines and FPSO hulls. Thermal insulation coating penetration rates for high-pressure high-temperature reservoirs and PFAS regulatory phase-down schedules served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for silane-modified ambient-cure epoxies would alter the outlook if Southeast Asian independent adoption accelerates beyond baseline assumptions. Forecasts reflect qualification timeline stability and zinc concentrate supply continuity assumptions. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or Petrobras pre-salt development pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Downhole Tools Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Oilfield Chemicals Market