
 Kuwait Oilfield Services Market | 2026-2036
Kuwait Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Oilfield Services Market Insights
Project finance tied to long-term drilling contracts is reshaping competitive entry in Kuwait's oilfield services sector. Schlumberger Ltd. leverages its integrated drilling technology portfolio to anchor major well construction programs. Halliburton Company sustains its position through specialized completion systems tailored to Kuwait's reservoir conditions. Baker Hughes Co. differentiates via advanced production optimization tools deployed across the country's mature fields.
Kuwait oilfield services encompass technical activities spanning drilling, completion, production, and well intervention, typically executed under high-pressure high-temperature specifications exceeding 150°C and 10,000 psi to maintain hydrocarbon flow from carbonate reservoirs. These services enable sustained extraction from Kuwait's Burgan and Greater Burgan fields, which collectively rank among the world's largest sandstone and carbonate oil accumulations. Drilling services command the largest revenue share due to continuous infill drilling requirements, while enhanced oil recovery technologies represent the fastest-expanding technology segment as Kuwait Petroleum Corporation pursues tertiary recovery targets. Well services generate concentrated margin pools through workover and intervention contracts on aging wells with declining natural productivity.
Kuwait's Ministry of Oil and the national regulator for petroleum activities enforce production-sharing terms and local content requirements that shape contractor selection and technology transfer obligations. Environmental standards aligned with Kuwait Environment Public Authority mandates constrain flaring practices and drive demand for closed-loop drilling systems and produced water management solutions. Stakeholders must monitor KPC's capital allocation shifts between greenfield development and brownfield enhancement to align service portfolios with the dominant spending trajectory.
Market Dynamics
Kuwait Petroleum Corporation's KPC 2040 strategy is redirecting capital flows toward tertiary recovery technologies, compressing contractor selection cycles and elevating technical qualification thresholds for oilfield service providers.
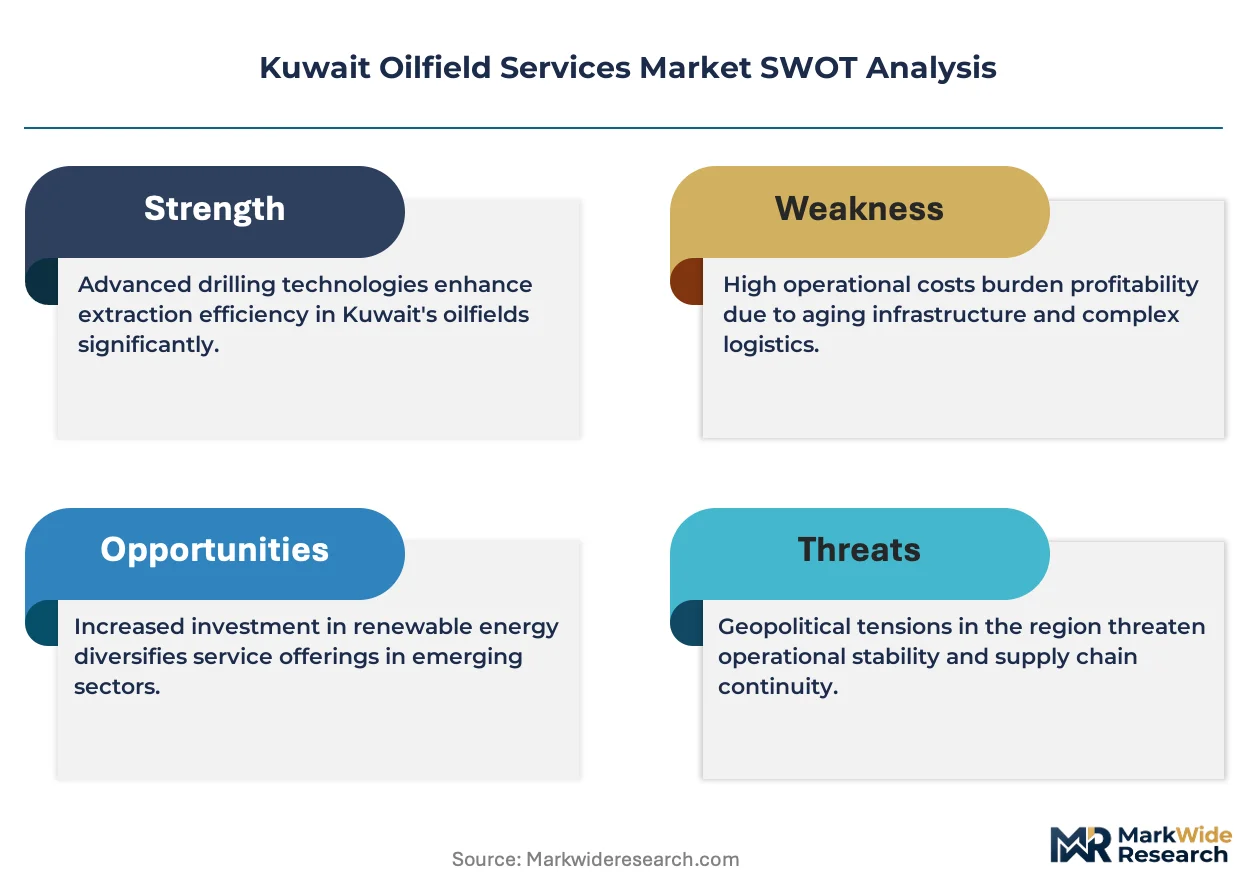
Growth Catalysts
- Enhanced Oil Recovery Mandates:Kuwait's national oil company targets under the KPC 2040 framework are accelerating demand for chemical flooding and thermal injection services across mature carbonate reservoirs.
- Heavy Oil Development:Expansion of heavy oil extraction projects in the Burgan field is extending drilling and completion contract durations for specialized high-viscosity production systems.
- Local Content Requirements:Kuwait's Ministry of Oil enforcement of production-sharing terms with technology transfer obligations is creating structured pathways for international service firms to establish in-country capabilities.
Market Restraints
- Specialized Equipment Concentration:High-pressure high-temperature drilling hardware supply concentrates among a limited set of international manufacturers, creating procurement bottlenecks for Kuwaiti operators.
- Carbonate Reservoir Complexity:Technical limitations in predicting fracture propagation through heterogeneous carbonate formations elevate non-productive time risks during horizontal drilling programs.
- Environmental Compliance Friction:Kuwait Environment Public Authority mandates on flaring reduction and produced water management impose capital-intensive retrofit requirements on legacy production infrastructure.
Strategic Opportunities
- Closed-Loop Drilling Systems:Regulatory pressure from Kuwait Environment Public Authority on drilling waste management is creating white space for solids control and fluid recycling technology providers.
- Digital Twin Convergence:Integration of reservoir simulation with real-time drilling data analytics is virtualizing well planning workflows for Kuwait's infill drilling programs.
- Workover Service Expansion:Aging well stock across Greater Burgan fields presents underpenetrated demand for intervention and artificial lift optimization services.
Industry Challenges
- HPHT Certification Timelines:Extended qualification periods for equipment rated above 150°C and 10,000 psi compress project mobilization schedules and strain contractor working capital.
- Reservoir Characterization Skill Gaps:Shortage of geoscientists with carbonate-specific expertise limits execution velocity for complex horizontal well construction programs in Kuwait's southeastern oilfields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Oilfield Services Market |
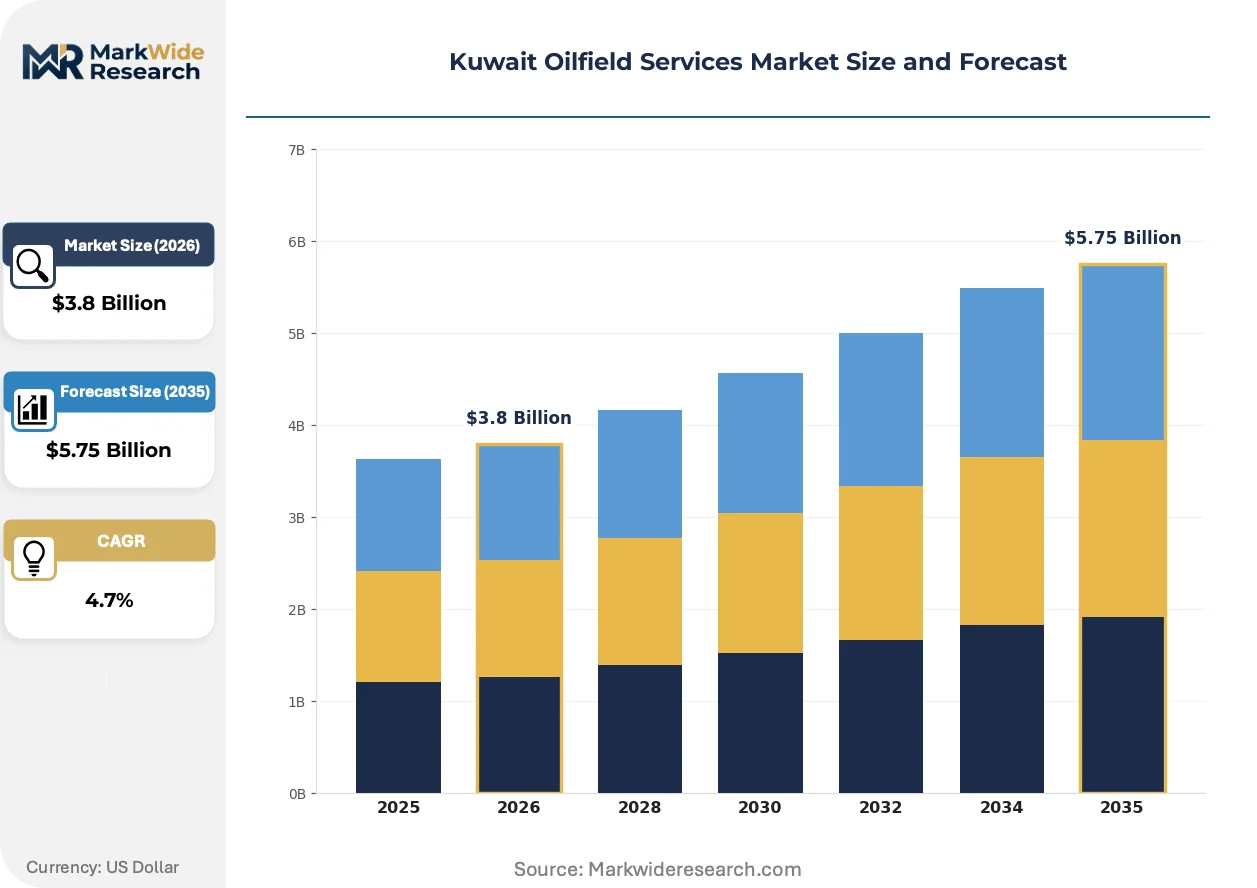
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Completion, Production, Well Services Technology: Enhanced Oil Recovery, Hydraulic Fracturing, Seismic Analysis, Well Logging End User: National Oil Companies, Independent Operators, Service Providers, EPC Contractors Application: Onshore, Offshore, Heavy Oil, Natural Gas |
| Companies Covered | Kuwait Petroleum Corporation, Schlumberger Ltd., Halliburton Company, Baker Hughes Co., Weatherford International plc, Fugro NV, KCA Deutag Alpha Limited, Saipem Spa, Petrofac Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Oilfield Services Market Trends and Innovations
Digital infrastructure deployment and environmental compliance automation are restructuring how Kuwaiti operators procure and deploy oilfield services across the production lifecycle.
Real-time drilling optimization platforms are virtualizing well construction workflows by integrating downhole measurement tools with surface automation systems. Kuwait Oil Company and other national operators are deploying these systems across infill drilling campaigns to compress non-productive time. The technology is virtualizing traditional mudlogging and directional drilling service boundaries into unified performance-based contracts.
Kuwait Environment Public Authority mandates on zero-flare targets and produced water reinjection are forcing rapid adoption of closed-loop production systems. These regulations require real-time emissions monitoring and automated shutdown protocols at wellhead facilities. The regulatory shift most affects mature field operators in the Burgan area, who are retrofitting gas compression and water treatment infrastructure to maintain production licenses.
Service contract unbundling is fragmenting historical integrated vendor relationships as Kuwait Petroleum Corporation subsidiaries adopt modular procurement for discrete drilling, completion, and intervention phases. This behavioral shift disrupts long-term alliance structures and elevates competition among specialized technology providers. The pattern is most visible in heavy oil development blocks where KPC is piloting performance-based compensation tied to production uplift rather than day-rate billing.
Kuwait Oilfield Services Market Segmentation
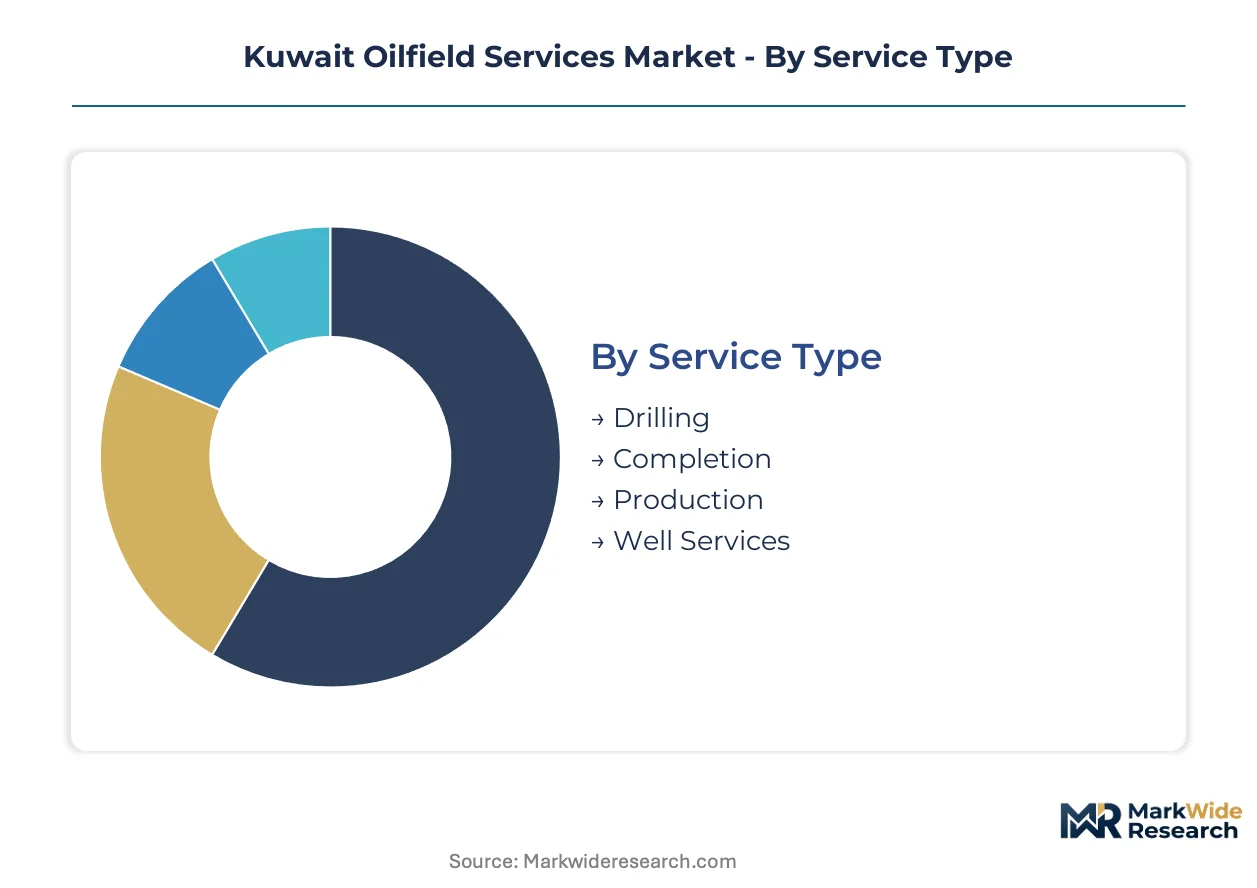
Segmentation reveals how Kuwait Petroleum Corporation allocates capital across distinct technical capabilities and operational environments. Each dimension exposes different margin structures, qualification barriers, and contract tenures that shape vendor positioning.
Service Type:
Cycle times vary dramatically: drilling contracts stretch across 18-24 months while well services turn over in 30-90 day increments, creating divergent working capital pressures for providers.
- Drilling:Encompasses directional drilling, managed pressure drilling, and casing running operations executed under HPHT specifications exceeding 150°C and 10,000 psi. Kuwait Oil Company concentrates demand in the southeastern oilfields for continuous infill drilling programs targeting carbonate reservoirs with complex fracture networks.
- Production:Covers artificial lift systems, surface facility maintenance, and flow assurance services sustaining output from mature Burgan field wells. Operators in the Greater Burgan area prioritize production optimization contracts tied to barrel uplift guarantees rather than fixed day rates.
- Completion:Includes multistage fracturing, intelligent completions, and sand control installations sealing wellbores for production readiness.
- Well Services:Delivers workover, intervention, and plug-and-abandonment operations on aging well stock across Kuwait's onshore fields.
Drilling anchors the volume base while well services gains share at the steepest rate as KPC accelerates brownfield intervention spending.
Technology:
Cost tiers separate proven conventional methods from capital-intensive advanced recovery systems requiring extended pilot validation before field-wide deployment.
- Enhanced Oil Recovery:Chemical flooding, thermal injection, and gas injection technologies targeting tertiary recovery from carbonate reservoirs with declining natural drive mechanisms. Kuwait Petroleum Corporation's KPC 2040 strategy redirects capital toward these systems across mature Burgan field sectors where primary recovery rates plateau.
- Hydraulic Fracturing:Multistage stimulation using proppant and fluid systems designed for high-temperature carbonate formations with heterogeneous permeability profiles. Heavy oil development blocks in the southeastern oilfields generate concentrated demand for specialized high-viscosity fracturing fluids.
- Seismic Analysis:3D and 4D seismic surveys mapping fracture networks and fluid contacts in heterogeneous carbonate reservoirs.
- Well Logging:Wireline and logging-while-drilling measurements characterizing formation properties, fluid saturations, and mechanical stresses.
Well logging anchors the volume base while enhanced oil recovery climbs the fastest as tertiary recovery mandates reshape KPC's technology procurement priorities.
End User:
Customer type determines contract structure: national operators favor integrated performance-based agreements while independents and contractors pursue discrete service procurement.
- National Oil Companies:Kuwait Petroleum Corporation and Kuwait Oil Company dominate capital allocation, directing spending through production-sharing frameworks with embedded local content and technology transfer obligations. These entities consolidate procurement authority for drilling and completion programs exceeding $100 million contract values.
- EPC Contractors:Engineering-procurement-construction firms package oilfield services into integrated field development contracts, assuming execution risk for greenfield heavy oil projects in the Burgan area.
- Independent Operators:Limited presence in Kuwait due to concession structures favoring national control over hydrocarbon resources.
- Service Providers:International oilfield service firms operating as subcontractors under KPC-directed master service agreements.
National oil companies anchor the volume base while EPC contractors expand most quickly as KPC pilots integrated project delivery models for heavy oil development.
Application:
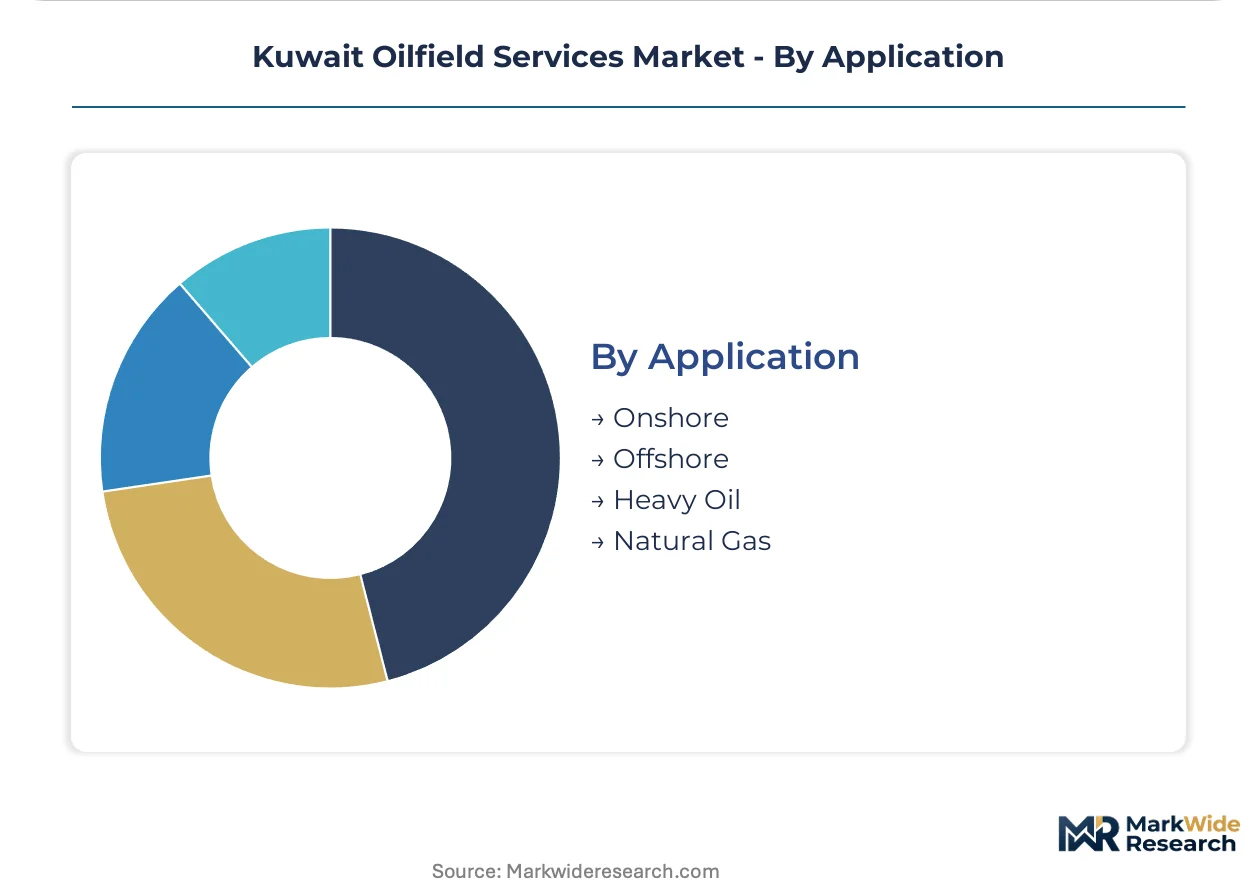
Geographic deployment splits between established onshore infrastructure and frontier offshore exploration with radically different logistics and technical risk profiles.
- Onshore:Drilling, completion, and production services deployed across Kuwait's southeastern oilfields including Burgan, Magwa, and Ahmadi fields with established pipeline and processing infrastructure. Kuwait Oil Company concentrates infill drilling and workover activity in this segment where road-accessible locations minimize mobilization costs.
- Heavy Oil:Specialized thermal recovery and viscosity reduction services targeting high-density crude in the Burgan field's deeper horizons. KPC's heavy oil development program extends contract durations for providers with thermal EOR expertise and high-temperature production systems.
- Offshore:Limited current activity with potential future exploration in Kuwait's northern territorial waters.
- Natural Gas:Associated gas handling, compression, and processing tied to oil production operations.
Onshore anchors the volume base while heavy oil gains share fastest as KPC accelerates thermal recovery pilots in high-viscosity reservoir zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Kuwait's southeastern oilfields exceeds that of frontier heavy oil blocks, where technical complexity and equipment scarcity compress contractor margins. This asymmetry shapes capital allocation across Kuwait Petroleum Corporation's operational geography. Regional demand concentrates where established infrastructure meets carbonate reservoir maturity.
Southeastern Oilfields
Burgan, Magwa, and Ahmadi fields generate concentrated demand for infill drilling and workover services under Kuwait Oil Company's continuous development programs. Kuwait Environment Public Authority mandates on flaring reduction drive retrofit spending across this mature cluster. Road-accessible well sites in the Ahmadi district minimize mobilization costs for drilling contractors executing HPHT well construction.
Heavy Oil Development Blocks
Thermal recovery pilots in deeper Burgan horizons extend contract durations for specialized viscosity reduction services. KPC 2040 strategy targets redirect capital toward these high-density crude zones, elevating technical qualification thresholds. The Minagish and Umm Gudair heavy oil clusters anchor pilot deployment of steam-assisted gravity drainage systems.
Greater Burgan Periphery
Aging well stock across Magwa and Ahmadi field extensions generates underpenetrated demand for intervention and artificial lift optimization. Kuwait Petroleum Corporation's brownfield enhancement spending concentrates here, prioritizing barrel uplift guarantees over fixed day rates. Workover activity intensifies in the Burgan field's waterflood-mature sectors where natural productivity decline accelerates.
Offshore Northern Territorial Waters
Limited current activity with potential future exploration shapes long-term equipment positioning strategies for international service firms. Kuwait Oil Company maintains seismic survey programs mapping prospective structures beyond established onshore infrastructure. Frontier logistics requirements in these waters differ radically from road-accessible southeastern fields, elevating offshore-capable contractor premiums.
West Kuwait Jurassic Gas Fields
Deep gas development in the Jurassic carbonate trend creates specialized demand for high-pressure completion systems and sour gas handling infrastructure. Kuwait Petroleum Corporation's diversification beyond oil production redirects some capital toward these technically challenging zones. The Ratqa and Umm Niqa fields represent the primary concentration of non-associated gas drilling activity.
Kuwait Oilfield Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete drilling, completion, and production technologies. Kuwait's oilfield services structure concentrates around integrated providers anchoring multi-year master service agreements with Kuwait Petroleum Corporation subsidiaries. Three archetypes dominate: full-service platform vendors bundling drilling through production optimization; specialized technology providers delivering HPHT-rated equipment and digital systems; and regional engineering-procurement-construction firms packaging services into integrated field development contracts. Competitive moves center on performance-based contract conversion away from day-rate billing and in-country capability expansion to satisfy local content requirements.
Within the integrated platform tier, Schlumberger Ltd., Halliburton Company, and Baker Hughes Co. occupy positions exemplifying full-service archetypes with technology portfolios spanning the well lifecycle. These entities represent the primary anchors for Kuwait Oil Company's major drilling and completion programs, with their integrated offerings structuring procurement patterns across the Burgan field development. Weatherford International plc and KCA Deutag Alpha Limited sit within specialized drilling and well construction segments, their positioning reflecting focused technical capabilities rather than platform breadth. Saipem Spa and Petrofac Limited exemplify the EPC integrator archetype, packaging oilfield services into field development contracts where execution risk transfer to contractors shapes competitive positioning. Fugro NV represents the geoscience and survey specialization tier, its positioning tied to reservoir characterization and seismic analysis supporting Kuwait's infill drilling programs.
| Leading Market Players |
|---|
| Kuwait Petroleum Corporation |
| Schlumberger Ltd. |
| Halliburton Company |
| Baker Hughes Co. |
| Weatherford International plc |
| Fugro NV |
| KCA Deutag Alpha Limited |
| Saipem Spa |
| Petrofac Limited |
| Others |
Pricing and Supply Chain Analysis
HPHT equipment certification bottlenecks compress contractor margins while simultaneously concentrating supply chain leverage among a narrow tier of qualified manufacturers, creating pricing tier spreads that separate integrated platform providers from component specialists. Kuwait Petroleum Corporation's local content mandates compound this dynamic by forcing technology transfer investments that reshape procurement economics across drilling and completion services.
Pricing Analysis
Industrial OEM buyers anchor day-rate contracting structures for drilling and completion services, though KPC 2040 strategy pilots are displacing fixed-rate models with performance-based compensation tied to barrel uplift guarantees. Price differentiation separates integrated master service agreements bundling multiple lifecycle phases from discrete transactional procurement for single-service interventions. Cost compression in well services is intensifying because aging well stock expansion attracts lower-qualified regional competitors. National oil companies exhibit least price sensitivity due to embedded technology transfer obligations, while independent contractors face acute margin pressure from qualification overhead.
Supply Chain Analysis
Export-control regimes limiting high-pressure drilling hardware flows constrain equipment availability for Kuwait's 10,000 psi-plus well construction programs. Manufacturing concentrates in the United States, Norway, and Singapore for HPHT-rated blowout preventers and managed pressure drilling systems. Raw material dependencies include specialty steel alloys, high-temperature elastomers, and tungsten carbide cutting structures. Single-source vulnerability concentrates in downhole measurement-while-drilling tool suppliers certified for carbonate reservoir conditions. Distribution runs through KPC-directed master service agreements rather than spot procurement, with Schlumberger, Halliburton, and Baker Hughes anchoring multi-year framework contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's oilfield services market functions as a defensive-moat arena where regulatory entrenchment through local content requirements and HPHT certification barriers protects incumbent positions against rapid competitive displacement.
For Market Incumbents: Pre-empt emerging specialized technology providers by accelerating in-country manufacturing commitments for high-temperature drilling hardware before KPC tightens local content thresholds. Capture brownfield intervention capacity through targeted capability expansion in Greater Burgan workover services, where aging well stock growth outpaces qualified service availability. Anchor master service agreement renewals by embedding digital twin and real-time optimization platforms into performance-based contract structures.
For New Entrants and Emerging Players: Pursue closed-loop drilling systems and solids control technology niches where Kuwait Environment Public Authority regulatory pressure creates procurement white space outside established integrated vendor relationships. Target heavy oil thermal recovery pilot blocks in the Minagish and Umm Gudair clusters, where extended contract durations and specialized viscosity reduction expertise requirements limit incumbent replication speed. Enter through joint venture structures with regional engineering-procurement-construction firms to satisfy technology transfer obligations without full qualification overhead.
For Investors and Strategic Acquirers: KPC 2040 capital reallocation toward tertiary recovery technologies reshapes the acquisition landscape by elevating enhanced oil recovery capability premiums above conventional drilling asset valuations. Position for five-to-ten year horizon returns by targeting specialized carbonate reservoir characterization and HPHT equipment manufacturing archetypes with embedded KPC relationship pathways. Monitor Kuwait Environment Public Authority zero-flare enforcement intensity as the signal indicating retrofit spending acceleration and associated service demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| HPHT Equipment Localization | Establishes in-country manufacturing to satisfy KPC local content mandates and compress procurement cycles. |
| Performance-Based Contract Conversion | Shifts revenue model from day-rate billing to barrel uplift guarantees aligned with KPC 2040 targets. |
| Closed-Loop Drilling System Deployment | Captures regulatory-driven demand from Kuwait Environment Public Authority waste management mandates. |
| Digital Twin Platform Integration | Virtualizes well planning workflows for Kuwait Oil Company infill drilling optimization programs. |
| Brownfield Intervention Capacity Buildout | Addresses underpenetrated demand across Greater Burgan aging well stock for artificial lift optimization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Kuwait Oil Company drilling program managers, Halliburton and Baker Hughes regional technology directors, KPC procurement committee members, and Kuwait Environment Public Authority compliance officers. Secondary validation drew from KPC 2040 strategy documentation, Kuwait Ministry of Oil production-sharing framework disclosures, SEC filings of listed oilfield service majors, and IEA Middle East oil supply databases. Bottom-up service contract value aggregation was triangulated against top-down KPC capital expenditure allocation estimates.
Calibration against historical contract award patterns and KPC spending trajectory announcements shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology tier, end-user category, and application geography, with heavy oil development and enhanced oil recovery penetration treated as distinct growth vectors. CAGRs were derived from contract duration-weighted spending flows and technology adoption curve positioning. Forecast inputs incorporated KPC's stated tertiary recovery targets and Kuwait Environment Public Authority regulatory enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by specialized EOR technology providers would shift outcomes beyond modeled ranges. Material shifts in KPC capital allocation between greenfield development and brownfield enhancement, or accelerated zero-flare enforcement by Kuwait Environment Public Authority, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Frac Tree Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Pumpjack Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Vietnam Oil and Gas Market