
 Shale Shakers Market | 2026-2036
Shale Shakers Market Size, Share, and Industry Trends Forecast 2026-2036
Shale Shakers Market Analysis
EPA methane emissions rules are expanding the cost-of-entry calculus for solids control equipment across US shale plays. Halliburton Company leverages integrated wellsite service bundling to sustain pricing power in the Permian and DJ basins. Schlumberger Limited anchors its position through automated shaker monitoring systems that reduce non-productive time on multi-well pads. National Oilwell Varco dominates offshore-ready shaker fabrication with API-certified designs.
Shale shakers are vibrating-screen separation devices that process drilling fluid to remove cuttings, typically operating at 6-8 G-force with mesh sizes ranging from API 20 to API 325. Their primary purpose is preserving drilling fluid rheology while minimizing waste volume and disposal costs. Linear motion shaker configurations lead onshore deployments due to superior conveyance of sticky formations, while elliptical units command premium placement in high-rate geothermal and extended-reach drilling where screen blinding resistance determines uptime. Oil extraction applications generate the deepest margin pools because operators prioritize fluid recovery over disposal speed, whereas waste management buyers emphasize throughput volume and equipment durability.
OSHA workplace exposure limits and EPA Resource Conservation and Recovery Act provisions govern cuttings handling and worker proximity to vibrating equipment, pushing manufacturers toward enclosed skid designs and remote monitoring interfaces. API RP 13C provides the definitive screen labeling standard that buyers use to compare separation performance claims across vendors. Stakeholders must weigh capital allocation between incremental mesh technology improvements and full-system automation that reduces labor exposure and fluid dilution rates.
Market Dynamics
API RP 13C mesh calibration mandates are compressing vendor differentiation and forcing capital redeployment toward automated shaker monitoring architectures that reduce non-productive time on multi-well pads.
Growth Catalysts
- EPA methane emissions rules:The US EPA's expanded methane monitoring requirements are elevating solids control equipment to critical-path status in drilling economics, accelerating replacement cycles for legacy shaker fleets.
- Permian Basin density:West Texas and southeastern New Mexico pad drilling intensification is concentrating demand for high-G-force linear motion configurations that handle sticky formations without screen blinding.
- Geothermal extended-reach drilling:Elliptical shaker technology is displacing conventional units in high-rate thermal applications where screen longevity under thermal cycling determines project returns.
Market Restraints
- API-certified mesh supply concentration:Precision wire cloth fabrication for API RP 13C-compliant screens clusters among a narrow supplier base in Germany and the United States, creating input bottleneck risk.
- Stainless steel price volatility:316-grade stainless mesh material costs fluctuate with nickel and molybdenum commodity markets, compressing fabrication margins unpredictably.
- OSHA vibration exposure limits:Workplace proximity restrictions for vibrating equipment are mandating enclosed skid designs that add 15-20% to base system cost without commensurate performance gain.
Strategic Opportunities
- Argentina Vaca Muerta development:Neuquén Basin unconventional drilling expansion presents first-mover positioning for automated shaker systems as international operators scale Argentine shale programs.
- EU Green Deal drilling waste directives:European Union circular economy mandates on oilfield waste minimization are creating regulatory tailwinds for closed-loop solids control integration.
- Remote monitoring + predictive screen replacement:Convergence of IoT vibration sensors and machine learning algorithms is enabling uptime-guarantee service models that capture recurring revenue from capital-constrained contractors.
Industry Challenges
- API RP 13C certification timeline:Third-party mesh verification protocols add 8-12 weeks to new product introduction cycles, delaying revenue recognition for iterative screen designs.
- Multi-vendor control system integration:Automated shaker monitoring architectures must interface with legacy rig data networks lacking standardized communication protocols, extending field commissioning durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shale Shakers Market |
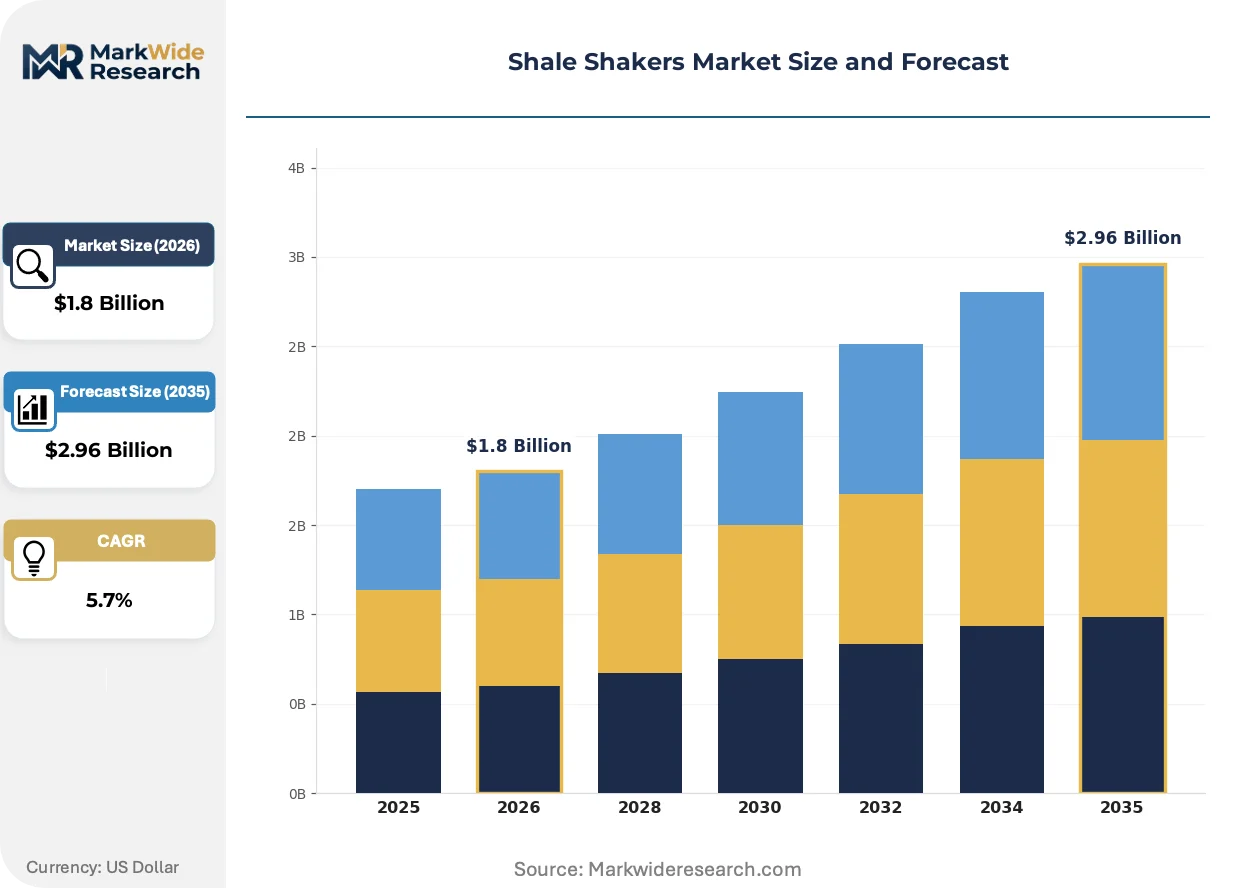
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Linear, Circular, Elliptical, Others Application: Oil Extraction, Gas Extraction, Drilling Operations, Waste Management End User: Oil & Gas Companies, Mineral Extraction, Environmental Services, Construction Technology: Vibrating, Centrifugal, Hydrocyclone, Gravity Separation |
| Companies Covered | Halliburton Company, Schlumberger Limited, National Oilwell Varco, Derrick Equipment Company, Baker Hughes, Weatherford International, GN Solids Control, DEL Corporation, Aipu Solids Control, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shale Shakers Market Emerging Trajectories
Shale shaker architecture is converging on autonomous operation models that compress labor exposure while tightening fluid rheology control, with three distinct vectors reshaping competitive positioning.
Modular shaker skids with plug-and-play motor and deck configurations are modularizing field upgrade pathways for drilling contractors facing formation variability across pad programs. Permian Basin operators are adopting these units fastest, swapping linear motion for elliptical decks between Wolfcamp and Bone Spring intervals without crane-assisted rig-down. This flexibility is modularizing capital deployment away from dedicated single-purpose systems toward reconfigurable assets that amortize across heterogeneous well profiles.
EPA Resource Conservation and Recovery Act enforcement on oil-based mud cuttings is tightening disposal liability chains, compelling operators to specify shaker systems with maximum fluid recovery efficiency. The regulatory pressure is elevating premium mesh specifications over economy alternatives in US onshore procurement criteria, with waste management contractors absorbing compliance cost pass-throughs.
Contractor procurement committees are consolidating vendor relationships around integrated wellsite service bundles that subsume shaker maintenance under broader fluids management agreements. This behavioral shift is compressing standalone equipment sales channels in the Permian and DJ basins, favoring service-anchored suppliers with captive solids control expertise over pure-play manufacturers.
Shale Shakers Market Segmentation
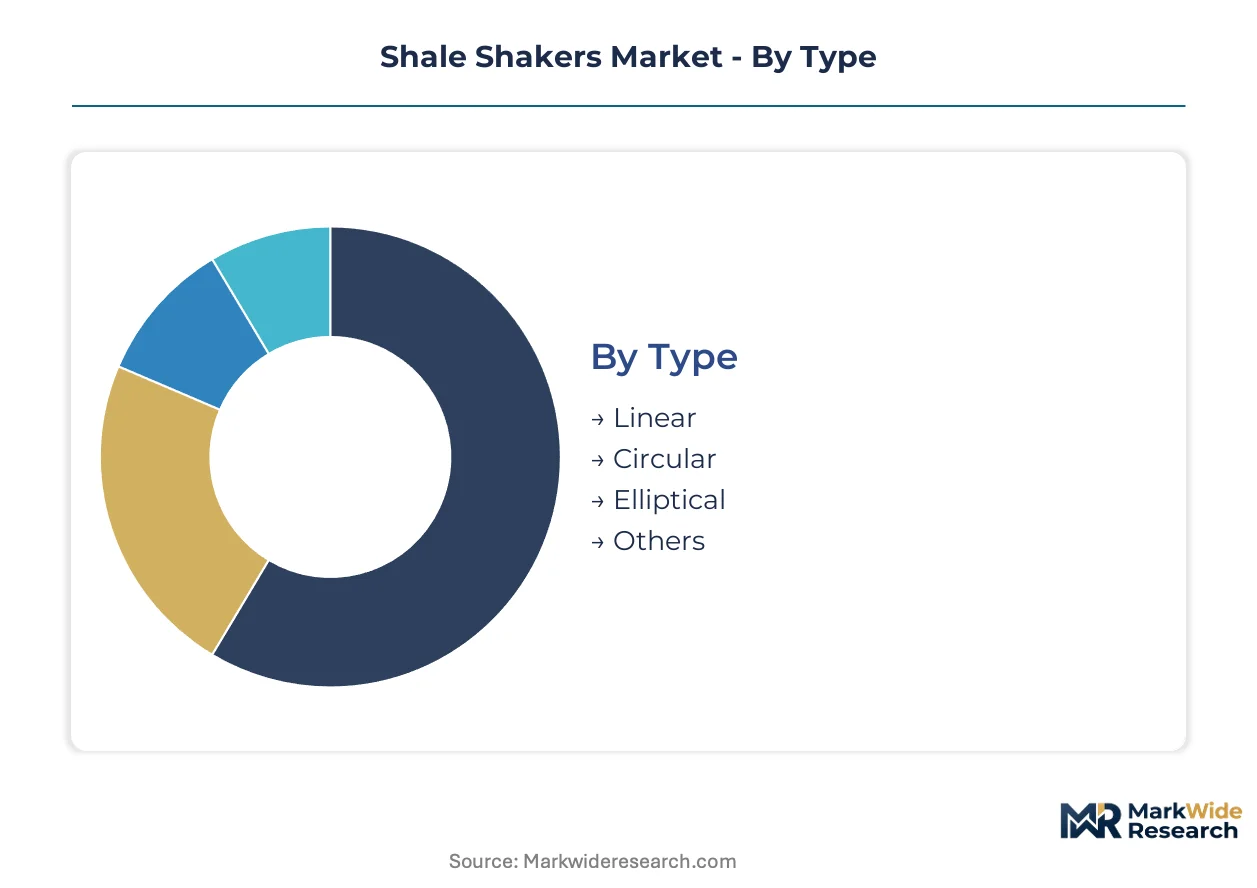
Shale shaker procurement decisions hinge on formation characteristics, fluid type, and pad drilling intensity. Each segmentation dimension reveals distinct margin structures and replacement cycle dynamics that vendors must navigate.
Type:
Motion geometry determines conveyance efficiency and screen longevity under specific downhole conditions.
- Linear:Dual-motor synchronized vibration generates straight-line motion that excels at transporting gumbo clay and sticky cuttings without screen blinding. Permian Basin operators deploy these most heavily for Wolfcamp and Bone Spring intervals where high-angle wells produce cohesive solids.
- Elliptical:Three-dimensional vibration pattern distributes G-force variably across the deck surface, extending screen life in high-rate geothermal and extended-reach drilling where thermal cycling stresses mesh integrity. Neuquén Basin Vaca Muerta development is accelerating uptake of these units.
- Circular:Single-motor orbital motion suits low-volume workover rigs and shallow vertical wells with minimal solids loading.
- Others:Specialized motion hybrids including dual-frequency and variable-ellipse configurations address niche deepwater and HPHT applications.
Linear configurations lead on scale; elliptical units lead on momentum.
Application:
Fluid recovery priority versus disposal speed determines equipment specification tier and service bundling approach.
- Oil Extraction:Synthetic and oil-based mud systems command maximum fluid recovery efficiency to preserve expensive base fluid inventories. Operators prioritize premium mesh specifications and automated monitoring that minimizes dilution rates and waste volume.
- Gas Extraction:Water-based mud dominance in dry gas drilling shifts emphasis toward throughput volume and rapid cuttings conveyance rather than fluid reclamation precision.
- Drilling Operations:Integrated wellsite service contracts subsume shaker maintenance under broader fluids management agreements, compressing standalone equipment sales channels.
- Waste Management:Third-party disposal contractors emphasize equipment durability and standardized parts interchangeability across heterogeneous rig fleets.
Oil extraction commands the deepest margin pools; waste management concentrates volume procurement.
End User:
Capital deployment flexibility and technical staffing depth separate buyer tiers.
- Oil & Gas Companies:Integrated operators and large independents specify automated shaker monitoring architectures that reduce labor exposure and non-productive time on multi-well pads.
- Mineral Extraction:Mining drillers apply adapted shale shaker technology to core drilling and exploration programs with lower G-force requirements but extreme abrasion resistance demands.
- Environmental Services:Remediation contractors repurpose surplus oilfield equipment for soil washing and groundwater treatment applications, prioritizing acquisition cost over performance optimization.
- Construction:Horizontal directional drilling for pipeline and utility installation uses compact skid-mounted units with rapid mobilization specifications.
Oil and gas operators lead on technology adoption; environmental services expand the installed base fastest.
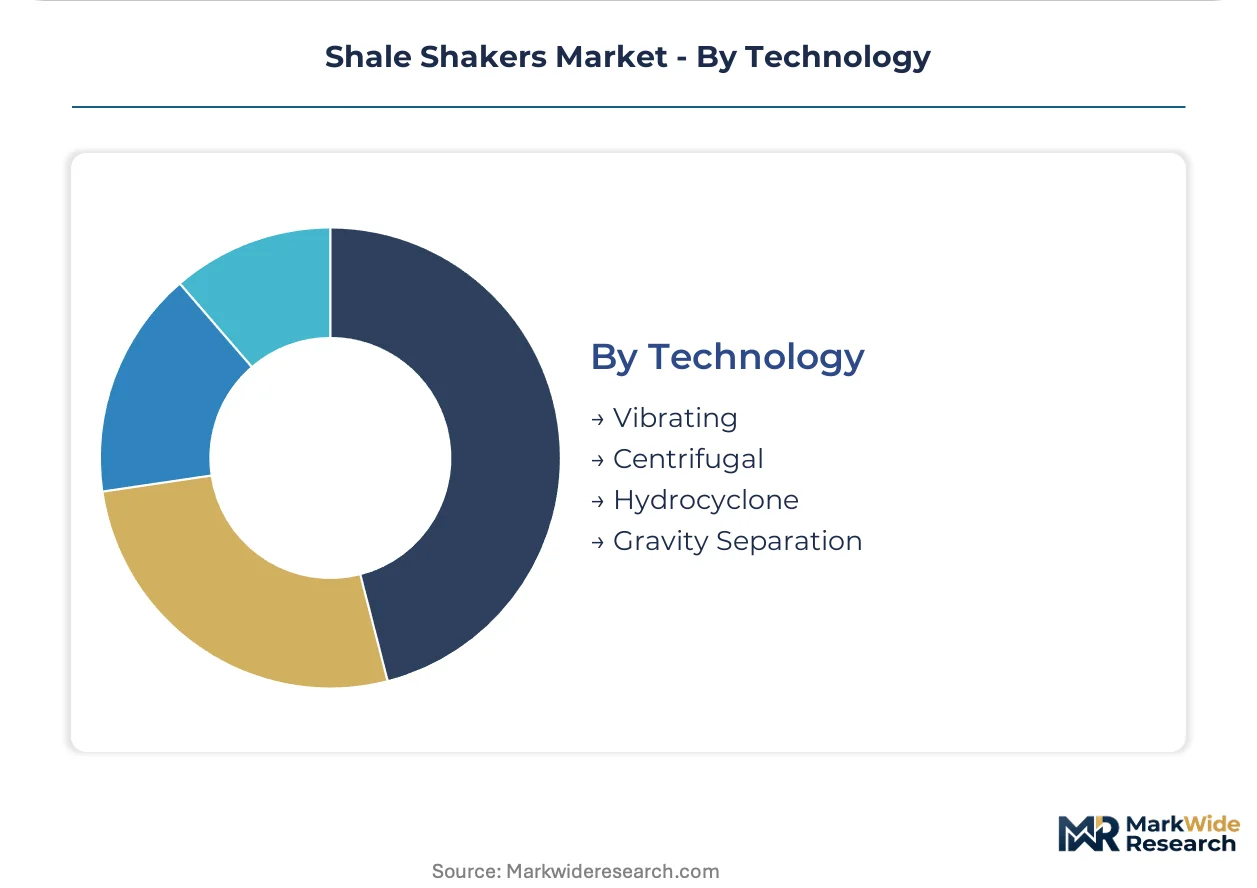
Technology:
Separation mechanism selection reflects solids size distribution, fluid rheology, and downstream processing requirements.
- Vibrating:Mechanical excitation through eccentric weights or electromagnetic drives remains the dominant architecture, with API RP 13C mesh calibration standards governing performance claims across vendors.
- Centrifugal:Decanter centrifuges handle ultra-fine solids below API 325 mesh that vibrating screens cannot capture, typically deployed downstream as polishing units.
- Hydrocyclone:Desanders and desilters remove sand and silt-size particles before fluid reaches the shaker, reducing screen loading and extending mesh life.
- Gravity Separation:Settling pits and flotation cells address large-volume low-value waste streams where mechanical separation economics fail.
Vibrating technology anchors the installed base; centrifugal systems gain share in closed-loop solids control integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum engineers and solids control technicians concentrate most heavily in the Permian Basin of West Texas and southeastern New Mexico, where pad drilling intensity sustains the deepest talent pools for high-G-force shaker operations worldwide.
United States
EPA methane emissions rules and OSHA workplace exposure limits are compressing replacement cycles for legacy shaker fleets while mandating enclosed skid designs. The Permian Basin anchors domestic demand, with operators in Midland and Odessa deploying automated monitoring systems to reduce non-productive time on multi-well pads.
Argentina
Neuquén Basin unconventional drilling expansion in Vaca Muerta is accelerating first-mover positioning for elliptical shaker technology suited to extended-reach thermal applications. The country's national energy regulator has tightened drilling waste handling protocols, pushing international operators toward closed-loop solids control integration in the Añelo and Loma Campana clusters.
China
Sinopec and PetroChina are expanding shale gas programs in the Sichuan-Chongqing region, concentrating demand for linear motion configurations that handle sticky formations in the Fuling and Weirong fields. The Ministry of Ecology and Environment has strengthened drilling waste discharge standards, elevating premium mesh specifications in procurement criteria.
Saudi Arabia
Saudi Aramco's unconventional gas development in the Jafurah Basin is driving specification-tier upgrades for high-G-force shaker systems. The Saudi Standards, Metrology and Quality Organization has aligned local equipment certification with API RP 13C screening standards, favoring vendors with proven desert operating envelopes in the Eastern Province.
Norway
Equinor's Barents Sea and North Sea drilling programs sustain offshore-ready shaker fabrication demand with API-certified designs. The Norwegian Environment Agency's zero-discharge mandates for drilling cuttings are compelling operators to specify maximum fluid recovery efficiency, concentrating premium equipment procurement around Stavanger and Bergen supply bases.
Shale Shakers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that tilts toward consolidated service bundling in North American onshore basins. Tiered vendor relationships stratify between integrated wellsite service providers and standalone equipment fabricators. Two dominant archetypes emerge: diversified oilfield service conglomerates leveraging captive fluids expertise, and specialized solids control manufacturers competing on mesh technology differentiation. Capacity expansion in automated shaker monitoring architectures and strategic partnerships for multi-vendor control system integration represent the primary competitive vectors reshaping positioning.
Among diversified service conglomerates, Halliburton Company and Schlumberger Limited occupy positions exemplifying the integrated wellsite bundling archetype, while National Oilwell Varco anchors the offshore-ready fabrication tier with API-certified design specialization. These three entities collectively represent the competitive spectrum spanning service-anchored suppliers with captive solids control expertise and pure-play manufacturers competing on equipment performance specifications.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| National Oilwell Varco |
| Derrick Equipment Company |
| Baker Hughes |
| Weatherford International |
| GN Solids Control |
| DEL Corporation |
| Aipu Solids Control |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up solids control specialists have consolidated regional service networks across the Permian and DJ basins, compressing standalone equipment margins while elevating bundled service pricing power for integrated wellsite providers.
Pricing Analysis
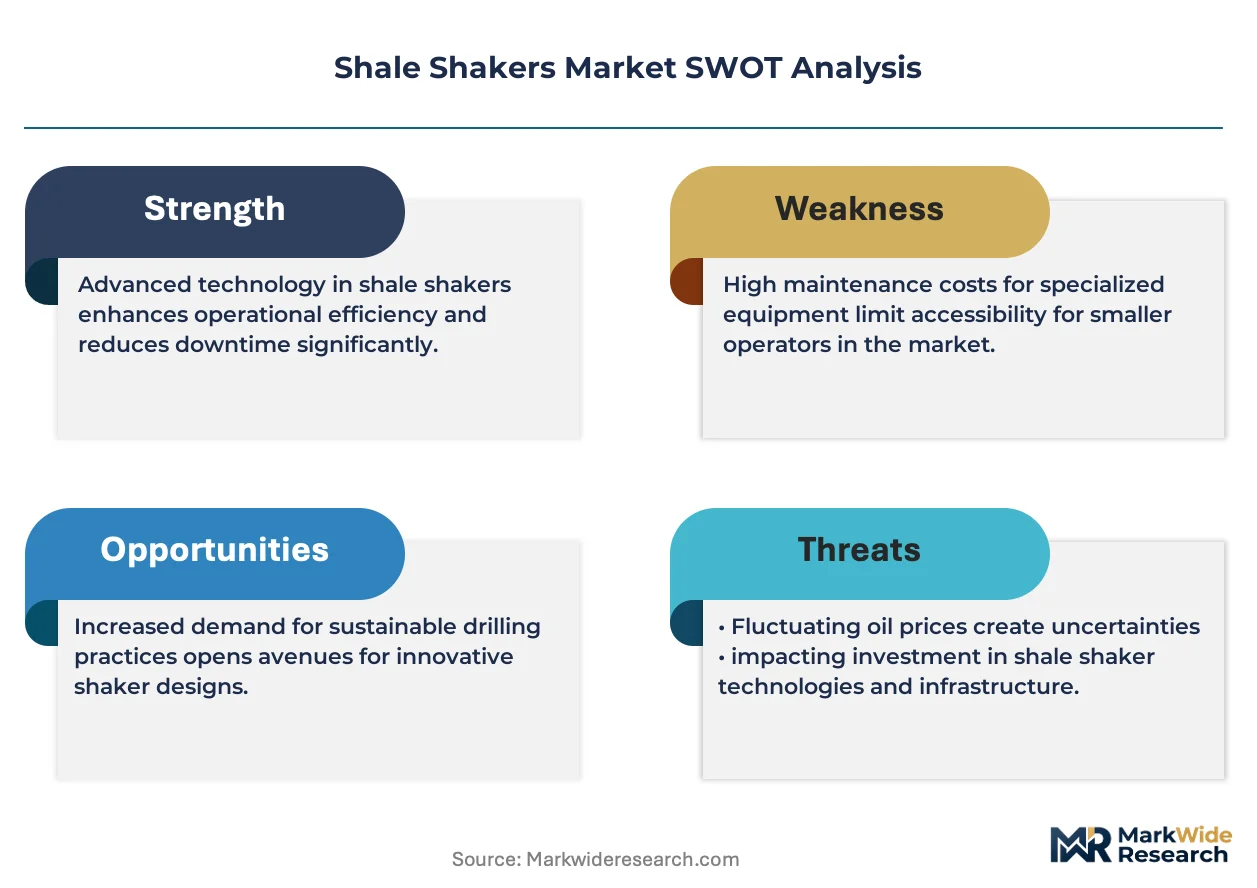
The bundled-vs-unbundled service split stratifies pricing power across vendor tiers. Three-tier pricing structure across premium, standard, and economy levels separates API RP 13C-certified automated systems from basic linear configurations and refurbished legacy units. Cost compression in the standard tier is intensifying because stainless steel mesh input costs fluctuate with nickel commodity markets. Waste management contractors exhibit the highest price sensitivity due to volume procurement mandates, while integrated oil and gas operators prioritize fluid recovery efficiency over unit economics.
Supply Chain Analysis
Workforce availability constraints in Houston and Oklahoma City fabrication hubs are extending lead times for precision wire cloth assembly. Manufacturing concentrates in Germany and the United States for API-certified mesh, with motor and vibration component sourcing anchored in China and Japan. Supply chain risk centers on single-source vulnerability for 316-grade stainless steel wire cloth from specialized German suppliers. Distribution runs through rig-equipment rental networks and direct OEM relationships with drilling contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in shale shakers rests on the shift toward automated monitoring architectures that reduce fluid dilution rates and labor exposure costs on multi-well pads.
For Market Incumbents: Anticipate consolidation pressure from integrated service bundling by diversifying into predictive screen replacement service models. Capture recurring revenue from capital-constrained contractors through uptime-guarantee contracts. Defend against pure-play mesh technology specialists by deepening API RP 13C certification investment and multi-vendor control system integration capabilities.
For New Entrants and Emerging Players: Direct-to-contractor digital procurement platforms offer the lowest-friction entry path for automated shaker monitoring software. Target Argentina's Neuquén Basin Vaca Muerta development for first-mover positioning in elliptical shaker deployments. Emphasize remote diagnostics and predictive maintenance algorithms as the primary go-to-market wedge against established service conglomerates.
For Investors and Strategic Acquirers: Valuations sit cheapest among standalone equipment fabricators lacking captive fluids management expertise. Five-to-ten year viability favors vendors with integrated wellsite service bundling capabilities and automated monitoring IP. Watch EPA methane enforcement intensity as the primary inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Shaker Monitoring Deployment | Schlumberger and Halliburton architectures reduce non-productive time on multi-well pads. |
| API RP 13C Mesh Certification Investment | Precision wire cloth fabrication from German suppliers locks in premium pricing tiers. |
| Argentina Market Entry Partnership | Vaca Muerta drilling expansion in Neuquén Basin demands elliptical shaker technology. |
| Closed-Loop Solids Control Integration | EU Green Deal directives and EPA RCRA enforcement elevate fluid recovery specifications. |
| Predictive Screen Replacement Service Model | IoT vibration sensors and machine learning enable recurring revenue from contractors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included drilling contractors, solids control technicians, rig procurement managers, and API certification specialists. Secondary validation drew from EPA enforcement databases, OSHA workplace exposure filings, API RP 13C technical documentation, and customs records for stainless steel wire cloth imports. Bottom-up rig-count modeling and top-down equipment replacement cycle analysis were cross-referenced for triangulation.
Comparable historical periods anchored the projection horizon to prior regulatory enforcement cycles and commodity price inflections. Segmentation dimensions included motion geometry type, application priority, end-user capital deployment tier, and technology mechanism. CAGRs were derived from equipment unit economics and replacement rate modeling across the analysis window. Forecast inputs incorporated Permian Basin pad drilling intensity and EPA methane rule compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for autonomous shaker operation would alter the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and stainless steel commodity price stability. Material deviation in EPA methane rule implementation or API RP 13C certification timeline delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Planned LNG Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Well Testing Services Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Oilfield Drilling Elevator Market