
 US Oil and Gas Infrastructure Market | 2026-2036
US Oil and Gas Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
US Oil and Gas Infrastructure Market Analysis
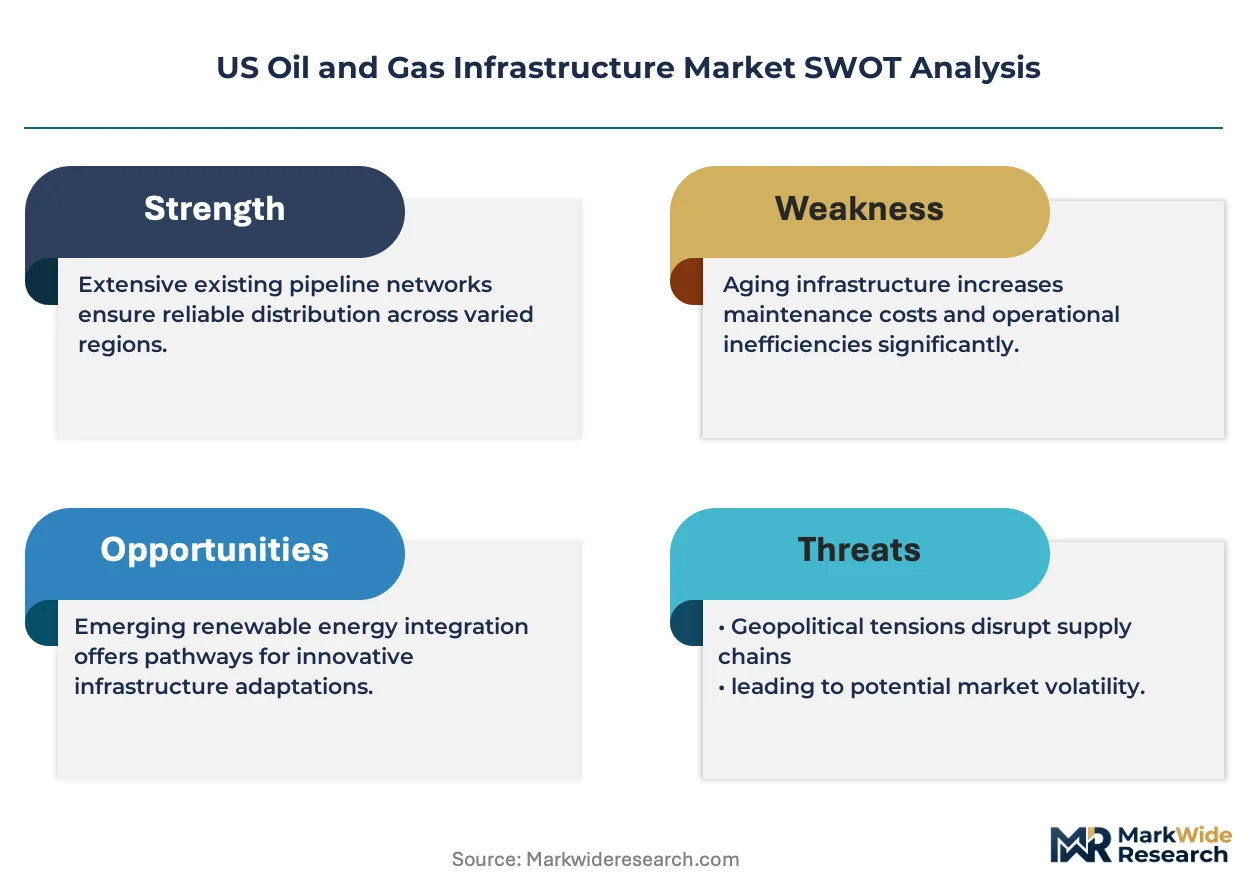
API 1169 pipeline construction inspector certification is collapsing the pool of qualified contractors eligible for federally regulated projects. Energy Transfer leverages its integrated pipeline network across Texas and the Mid-Continent to sustain cost advantages in crude and NGL logistics. Kinder Morgan dominates interstate natural gas transportation with the largest regulated pipeline footprint in North America. Williams specializes in gathering and processing infrastructure in the Appalachian and Haynesville basins.
US oil and gas infrastructure encompasses the physical systems—steel pipelines typically operating at 800-1,440 psi, above-ground storage tanks with 40-80 year design lives, and compressor stations spaced every 50-100 miles—that extract, process, store, and transport hydrocarbons from wellhead to end market. Pipeline systems anchor capital deployment as producers seek debottlenecking solutions for constrained Permian and Bakken takeaway capacity. SCADA and IoT Solutions segments are capturing disproportionate investment as operators automate leak detection and pressure monitoring to reduce manual inspection costs. Refinery infrastructure remains structurally mature with margin pools shifting toward Gulf Coast complex coking and export-oriented facilities.
PHMSA enforces pipeline integrity management rules under 49 CFR Part 195, while EPA methane emissions standards under the Clean Air Act shape equipment replacement cycles across production and midstream assets. OSHA process safety management requirements govern refinery and compressor station operations, particularly in high-consequence areas along populated corridors. Stakeholders must weigh federal permitting timelines against state-level environmental reviews as project developers evaluate brownfield expansions versus greenfield corridor development.
Market Dynamics
PHMSA's integrity management mandates under 49 CFR Part 195 are compressing project timelines as operators race to retrofit aging transmission corridors before regulatory deadlines. This enforcement wave is restructuring contractor qualification requirements and accelerating capital redeployment toward automated monitoring systems.
Growth Catalysts
- Permian Basin takeaway debottlenecking:Producers are expanding pipeline lateral networks to connect Midland Basin wells to Gulf Coast export terminals. FERC certificate applications for interstate projects have surged in response.
- EPA methane emissions standards:Equipment replacement cycles across compressor stations and production facilities are driving demand for low-emission pneumatic controllers and leak detection hardware.
- LNG export terminal buildout:Gulf Coast liquefaction capacity additions require parallel investment in feedgas pipeline interconnects and storage cavern development.
Market Restraints
- Specialized steel input volatility:API 5L line pipe specifications constrain supplier pools to domestic mills and approved foreign sources, exposing projects to tariff and alloy surcharge fluctuations.
- Right-of-way acquisition friction:Interstate corridor development faces eminent domain litigation timelines that extend project schedules by 18-36 months in contested corridors.
- Geographic contractor concentration:Qualified pipeline construction labor concentrates in Texas and Louisiana, creating wage pressure and scheduling conflicts during peak build seasons.
Strategic Opportunities
- Haynesville gathering modernization:Legacy Appalachian infrastructure designs are being adapted for high-pressure Haynesville shale production, opening retrofit contracts for compression and dehydration assets.
- Carbon capture pipeline networks:45Q tax credit enhancements are spurring Class VI well drilling and CO2 trunk line proposals across the Permian and Gulf Coast industrial corridors.
- SCADA-IoT convergence:Real-time pressure monitoring and predictive maintenance platforms are penetrating smaller midstream operators previously served by manual inspection regimes.
Industry Challenges
- API 1169 inspector certification scarcity:Federally regulated projects require certified construction inspectors, yet examination pass rates and training program capacity lag project demand.
- Brownfield integration complexity:New automation layers must interface with legacy SCADA protocols and mechanical safety systems installed across decades of incremental upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Oil and Gas Infrastructure Market |
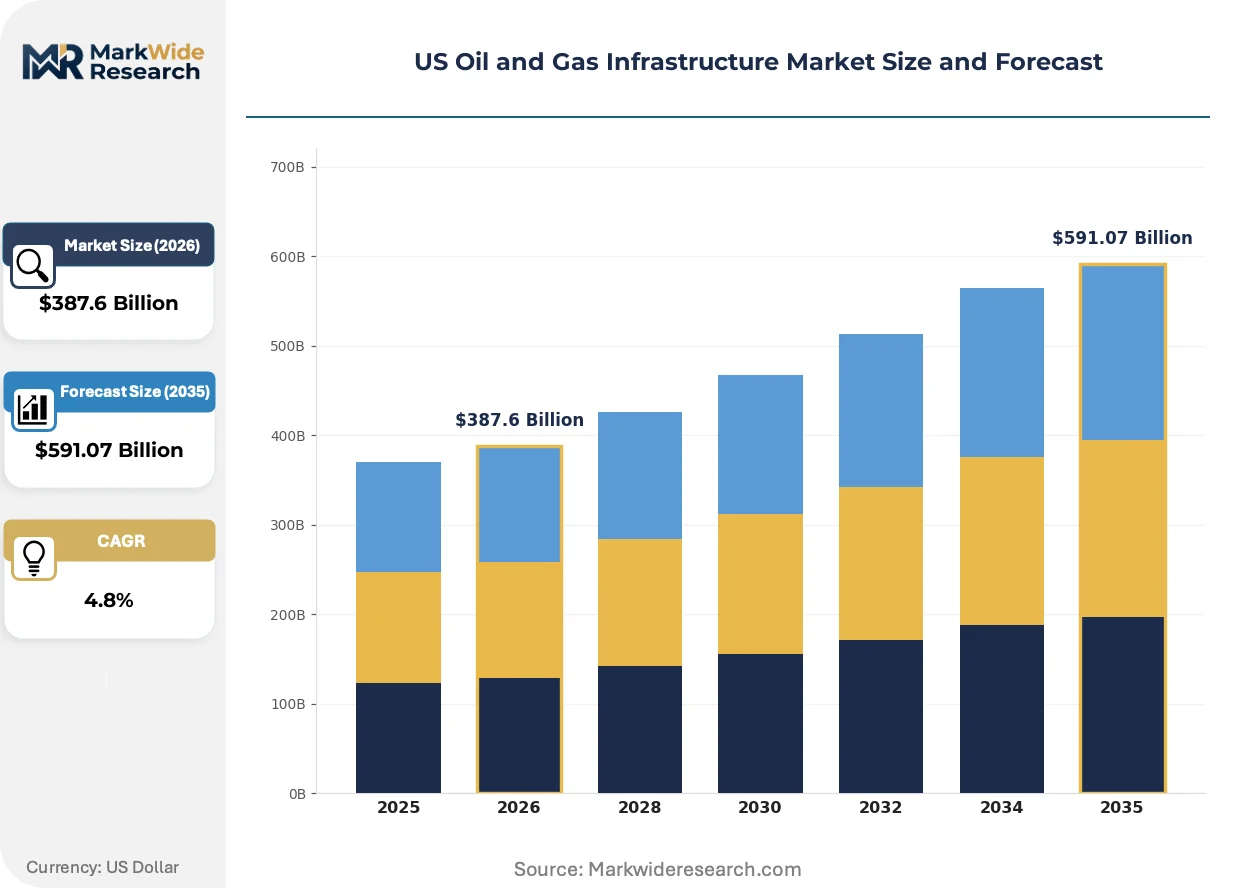
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pipeline, Refinery, Storage Tank, Compressor Station Service Type: Exploration, Drilling, Production, Transportation End User: Utilities, Industrial Sector, Government, E&P Companies Technology: Automation, SCADA, IoT Solutions, DCS |
| Companies Covered | Energy Transfer, Enterprise Products Partners, Kinder Morgan, Williams, ONEOK, Enbridge, Chevron, ExxonMobil, Halliburton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Oil and Gas Infrastructure Market Emerging Trajectories
Automation is penetrating pipeline operations at the sensor layer, compressing inspection labor costs while elevating cybersecurity exposure. This shift is redefining operator skill requirements and vendor qualification standards.
Drone-based aerial leak detection is supplanting foot patrol and helicopter survey methods for long-haul transmission corridors. Midstream operators in the Permian and Bakken basins are deploying methane-sensing UAV fleets at 40% of new pipeline miles. This technology is enabling 10x survey frequency at comparable unit costs while reducing personnel exposure to remote terrain hazards.
OSHA process safety management enforcement is intensifying for compressor station operations in high-consequence areas along populated corridors. Inspection citation rates for mechanical integrity programs have risen sharply in the Marcellus and Utica shale regions. Gathering system operators are responding by consolidating maintenance vendor relationships and standardizing procedure documentation across multi-state footprints.
Buyers are unbundling after-sales service contracts from original equipment procurement for compressor stations and metering skids. Large midstream operators now separately negotiate field service agreements with third-party maintenance providers rather than accepting captive OEM service terms. This pattern is most visible among Permian and Haynesville producers managing multi-vendor asset fleets exceeding 500 million cubic feet per day of throughput capacity.
US Oil and Gas Infrastructure Market Segmentation
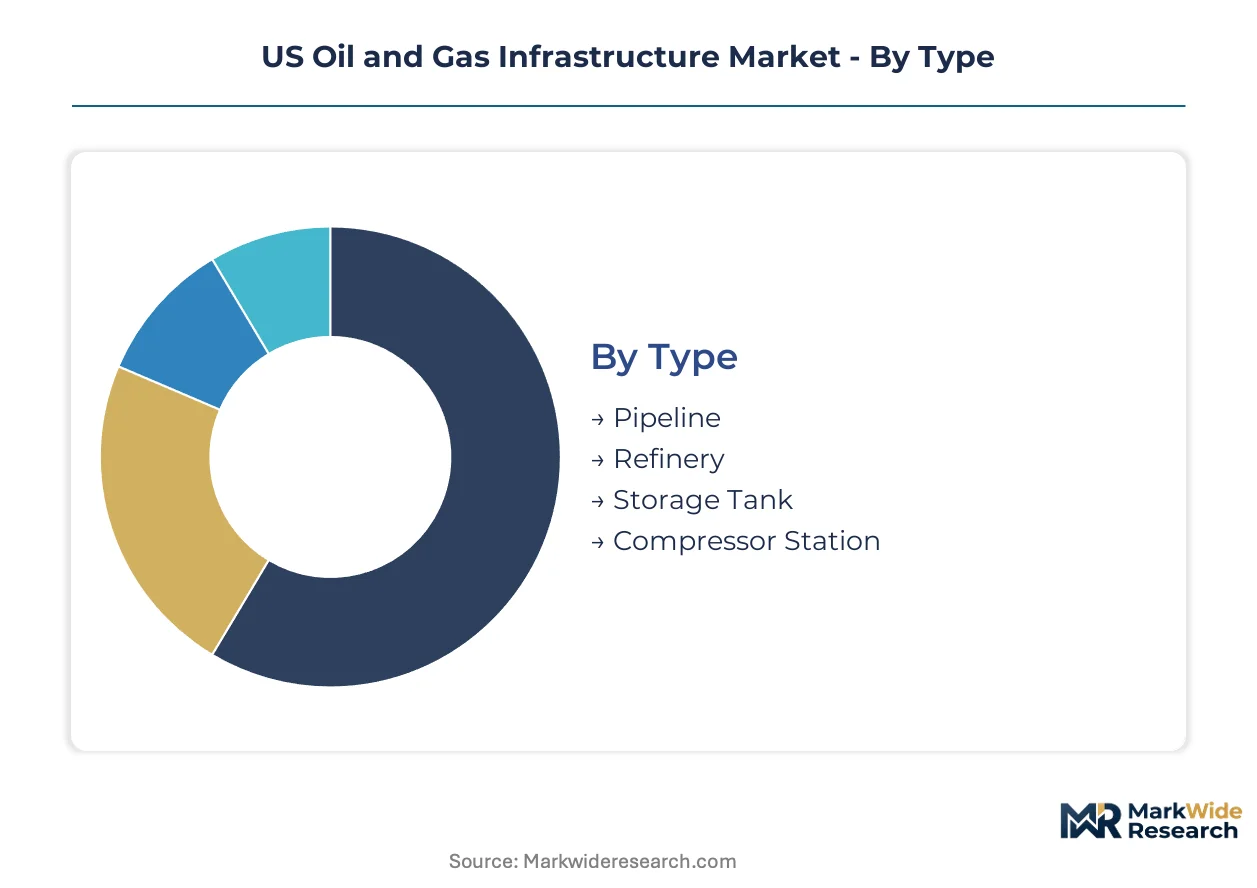
Segmentation reveals how capital allocation splits across asset classes and operational phases in US oil and gas infrastructure. Each dimension carries distinct regulatory exposure, margin profiles, and contractor qualification requirements that shape investment decisions.
Type:
FERC interstate certificate requirements and PHMSA integrity mandates create divergent compliance burdens across physical asset categories.
- Pipeline:Steel transmission systems operating at 800-1,440 psi transport crude, natural gas, and NGLs across state boundaries. Permian Basin producers are expanding lateral networks to connect Midland wells to Gulf Coast export terminals, with FERC certificate applications surging for interstate projects.
- Refinery:Complex coking and hydrocracking facilities along the Gulf Coast process heavy sour crudes for export markets. Margin pools are shifting toward these export-oriented facilities as domestic demand plateaus and international product differentials widen.
- Storage Tank:Above-ground tanks with 40-80 year design lives provide buffer capacity for crude and refined products. Demand concentrates at Gulf Coast marine terminals serving VLCC loading operations.
- Compressor Station:Mechanical facilities spaced every 50-100 miles maintain pressure on natural gas transmission lines. EPA methane standards are driving replacement cycles for pneumatic controllers and compressor seals.
Pipeline handles the majority of throughput; SCADA-enabled compressor stations are climbing the fastest on share as automation penetrates midstream operations.
Service Type:
Capital intensity and regulatory scrutiny escalate as hydrocarbons progress from subsurface extraction to interstate commerce.
- Exploration:Seismic surveying and lease acquisition activities precede drilling commitments. Permian and Haynesville operators are expanding 3D seismic coverage to identify stacked pay zones.
- Drilling:Horizontal well construction with extended laterals dominates shale development. Rig counts in the Permian and Bakken basins respond directly to WTI price bands and hedge positions.
- Production:Wellhead operations encompass artificial lift, water handling, and initial separation. EPA methane regulations are forcing equipment upgrades at tank batteries and pneumatic device networks.
- Transportation:Midstream logistics connect production to processing, storage, and end markets. PHMSA's 49 CFR Part 195 integrity mandates are compressing project timelines for aging transmission corridors.
Transportation commands the dominant capital share; production service demand is expanding most quickly as methane compliance drives retrofit spending.
End User:
Contract structures and credit profiles vary sharply across buyer categories, from investment-grade utilities to privately held E&P operators.
- Utilities:Local distribution companies and gas-fired power generators require firm transportation capacity. FERC rate-case procedures govern long-term contract negotiations for interstate pipeline service.
- Industrial Sector:Petrochemical complexes and refineries purchase feedstock and logistics services under take-or-pay arrangements. Gulf Coast chemical expansions are anchoring NGL fractionation demand.
- Government:Strategic Petroleum Reserve operations and military fuel supply chains represent direct federal procurement. DOE storage cavern maintenance contracts follow federal acquisition regulations.
- E&P Companies:Upstream operators contract for gathering, processing, and takeaway capacity. Permian producers are prioritizing dedicated pipeline laterals over common-carrier alternatives.
E&P companies dominate discretionary infrastructure spending; industrial offtake agreements are gaining share fastest as petrochemical buildout accelerates.
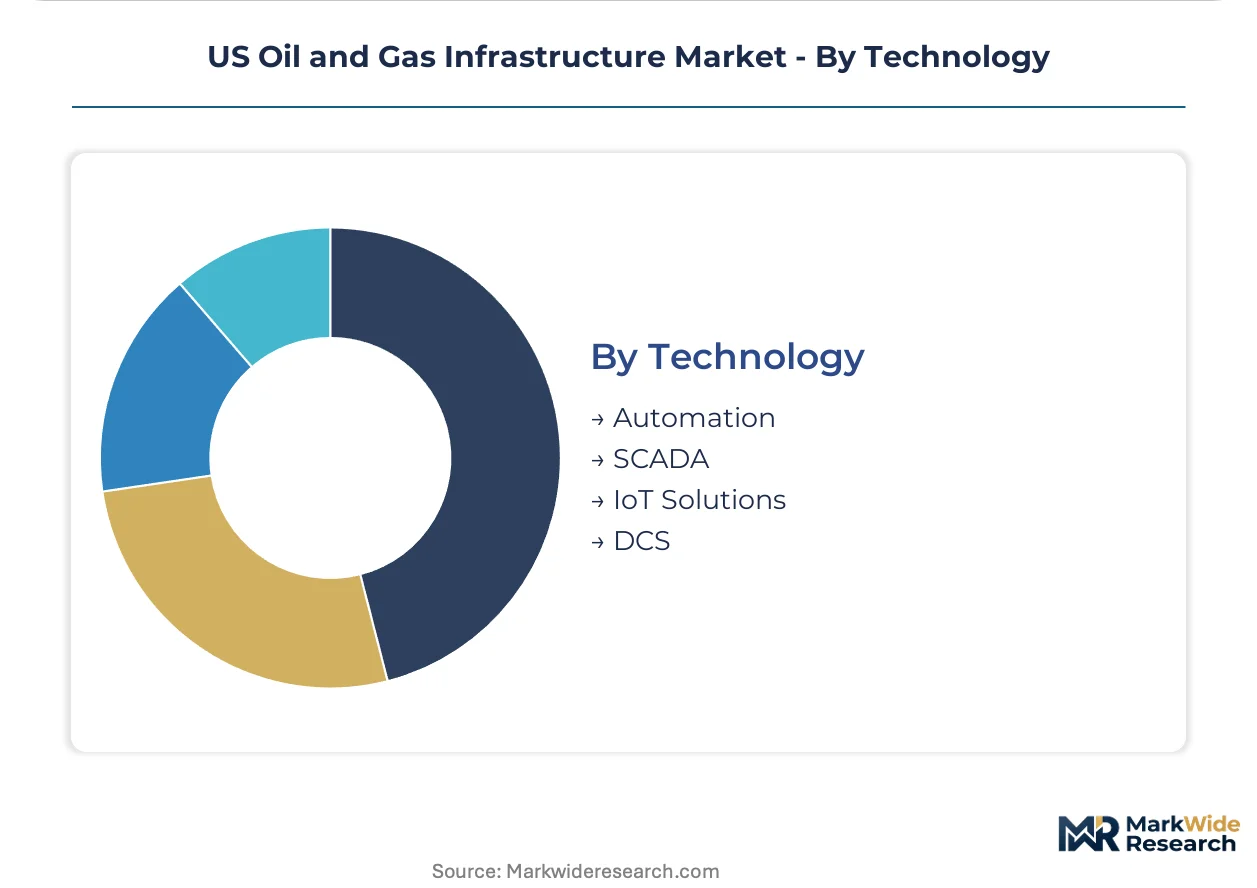
Technology:
Cybersecurity requirements and interoperability standards are reshaping vendor qualification for control systems.
- Automation:Programmable logic controllers and robotic inspection systems reduce manual intervention. Drone-based aerial leak detection is supplanting foot patrol for 40% of new pipeline miles in the Permian and Bakken.
- SCADA:Supervisory control and data acquisition platforms enable centralized monitoring of pressure, flow, and valve status. PHMSA regulations are accelerating replacement of legacy serial protocols.
- IoT Solutions:Wireless sensor networks deliver real-time equipment health and emissions data. Smaller midstream operators previously served by manual inspection are adopting predictive maintenance platforms.
- DCS:Distributed control systems govern refinery and gas processing unit operations. OSHA process safety management citations are rising for mechanical integrity program gaps at compressor stations.
SCADA anchors installed base value; IoT Solutions are on the steepest expansion trajectory as sensor costs decline and cloud analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors national infrastructure investment, with Texas and Louisiana hosting the densest concentration of pipelines, export terminals, and processing facilities. Interstate natural gas networks radiate from Appalachian and Permian production basins toward Atlantic and Gulf Coast demand centers.
Texas
Permian Basin producers are expanding lateral pipeline networks to connect Midland wells to Gulf Coast LNG export terminals. PHMSA's 49 CFR Part 195 integrity mandates are compressing retrofit timelines for aging transmission corridors crossing the state. Houston anchors the national midstream engineering sector, with specialized construction contractors clustering along the Ship Channel.
Louisiana
Gulf Coast liquefaction capacity additions require parallel investment in feedgas pipeline interconnects and salt dome storage caverns. EPA methane emissions standards are forcing equipment replacement cycles at compressor stations serving the Haynesville shale. Lake Charles and Cameron Parish host the most active LNG terminal construction sites.
Pennsylvania
Marcellus shale gathering systems are consolidating as operators respond to OSHA process safety management enforcement in high-consequence populated corridors. FERC interstate certificate applications for takeaway capacity to Gulf Coast markets have surged. Pittsburgh anchors Appalachian midstream engineering and project management capacity.
Oklahoma
Mid-Continent pipeline interconnects serve as critical aggregation points for Permian, Anadarko, and Arkoma basin production. API 1169 inspector certification scarcity is creating contractor qualification bottlenecks for federally regulated projects. Cushing remains the designated delivery point for domestic crude futures pricing.
North Dakota
Bakken shale takeaway capacity constraints are driving pipeline lateral investments toward rail and river terminal alternatives. PHMSA integrity management deadlines are accelerating capital redeployment toward automated monitoring systems on older transmission lines. Williston Basin production growth is outpacing regional processing and logistics infrastructure.
US Oil and Gas Infrastructure Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic footprint dimensions. The market structure concentrates around integrated midstream conglomerates with FERC-regulated interstate networks, while specialized gathering operators retain regional strongholds. Three archetypes dominate: scale-driven pipeline transporters with multi-basin footprints, basin-focused gathering and processing specialists, and integrated majors with captive midstream assets. Competitive moves center on brownfield capacity expansions and strategic joint ventures to share greenfield corridor development risk.
Within the scale-driven tier, Energy Transfer and Kinder Morgan exemplify integrated network operators with contiguous pipeline systems spanning multiple production basins. Williams occupies a position among basin-focused specialists with concentrated Appalachian and Haynesville infrastructure footprints. These three companies anchor the competitive landscape through their regulated interstate certificates and established right-of-way corridors.
| Leading Market Players |
|---|
| Energy Transfer |
| Enterprise Products Partners |
| Kinder Morgan |
| Williams |
| ONEOK |
| Enbridge |
| Chevron |
| ExxonMobil |
| Halliburton |
| Others |
Supply Flow & Price Mechanics
Ninety-day API 5L line pipe lead times from domestic mills concentrate procurement leverage among Texas and Louisiana-based contractors, compressing margin capture for projects dependent on tariff-exposed foreign alloy sources. This inventory-to-supply alignment reinforces tiered pricing power across federally regulated transmission builds versus non-jurisdictional gathering systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FERC-certificated interstate projects from state-regulated intrastate lines and private gathering systems. Price differentiation rests on API 1169 inspector certification requirements and PHMSA compliance documentation depth. Cost compression in standard-tier gathering infrastructure is intensifying because Haynesville and Permian producers are unbundling after-sales service from original equipment procurement. E&P companies with sub-investment-grade credit profiles exhibit the highest price sensitivity, while integrated majors with captive midstream assets demonstrate the least.
Supply Chain Analysis
Inbound logistics costs from Gulf Coast port congestion and specialized heavy-haul capacity constraints are elevating landed costs for 36-inch diameter line pipe and compressor station skids. Domestic manufacturing draws from Ohio and Pennsylvania steel mills, German valve and metering component suppliers, and Canadian pressure vessel fabricators. Single-source vulnerability concentrates in API 5L X70 and X80 grade plate supply from a limited domestic mill pool. Distribution runs through Houston Ship Channel staging yards and Cushing inventory aggregation points before final mile deployment to Permian and Bakken well pads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US oil and gas infrastructure market sits at a platform-economics inflection where SCADA-IoT convergence is redefining vendor qualification standards and unbundling traditional OEM service relationships.
For Market Incumbents: Shield FERC-regulated interstate corridors from margin erosion by accelerating brownfield automation retrofits ahead of PHMSA integrity deadlines. Deepen backward integration into specialized construction labor pools through captive training programs for API 1169 certification pipelines, insulating project timelines from contractor scarcity. For New Entrants and Emerging Players: Differentiate on predictive maintenance platforms targeting sub-scale midstream operators below 500 million cubic feet per day throughput capacity. Haynesville gathering system modernization presents the most penetrable white-space, with carbon capture pipeline networks offering a second entry vector anchored to 45Q tax credit economics. For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility-archetype play because FERC rate-case procedures entrench incumbent pipeline networks with irreplaceable right-of-way corridors and contracted cash flow visibility. Target acquisition archetypes include Appalachian and Haynesville basin-focused gathering specialists with compression and dehydration asset concentrations. The signal to watch is Class VI well permitting velocity for CO2 sequestration projects as a proxy for carbon capture trunk line demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PHMSA Compliance Automation | IoT-enabled leak detection platforms reduce manual inspection labor costs while satisfying 49 CFR Part 195 integrity mandates. |
| Haynesville Gathering Modernization | High-pressure shale production adaptations open retrofit contracts for compression and dehydration assets across Louisiana and East Texas. |
| Carbon Capture Pipeline Development | 45Q tax credit enhancements spur Class VI well drilling and CO2 trunk line proposals across Permian industrial corridors. |
| API 1169 Certification Pipeline | Captive inspector training programs insulate project timelines from federally mandated construction qualification bottlenecks. |
| After-Sales Service Unbundling | Separate field service negotiations with third-party maintenance providers displace captive OEM service terms for compressor stations. |
Methodological Framework
Initial hypotheses were tested against primary input from midstream engineering directors, FERC regulatory counsel, EPC project managers, and compressor station maintenance heads and refined through secondary validation against EIA storage and flow data, FERC certificate application filings, PHMSA incident and enforcement databases, and pipeline construction permit records. Bottom-up project-level aggregation triangulated against top-down sector spend estimates derived from SEC 10-K capital expenditure disclosures.
Variance decomposition across the projection horizon isolates volume drivers from price and mix effects, with segmentation modeled by infrastructure type, service phase, end-user credit tier, and technology adoption curve. CAGRs were derived from fitted growth trajectories anchored to observable capacity additions and regulatory deadline schedules, incorporating Permian takeaway debottlenecking timelines, EPA methane compliance equipment replacement cycles, and LNG export terminal feedgas interconnect commitments.
The analysis sits within stated boundaries; outcomes outside sustained WTI price bands supporting Permian and Bakken drilling economics, or accelerated PHMSA enforcement timelines compressing retrofit windows, would require recalibration. Forecasts reflect documented assumptions regarding FERC certificate approval velocities and specialized steel input availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Artificial Lift Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Crown Block Market
Oil & Gas
Well Cementing Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market