
 Coiled Tubing System Market | 2026-2036
Coiled Tubing System Market Size, Share, and Industry Trends Forecast 2026-2036
Coiled Tubing System Market Analytics
The shift from single-source tubing procurement to multi-vendor qualification programs is recalibrating supply chain risk for North American operators. Halliburton leverages captive steel sourcing and in-house reel manufacturing to control lead times across its coiled tubing fleet. Baker Hughes Company differentiates through high-strength alloy metallurgy for sour-service environments. Schlumberger Limited anchors its position via integrated well intervention packages that bundle tubing units with real-time downhole diagnostics.
Coiled tubing systems consist of continuous, seam-welded or seamless steel pipe spooled onto large-diameter reels, typically manufactured to API 5ST or equivalent specifications with outer diameters ranging from one to four inches and wall thicknesses engineered for specific wellbore pressures. These systems enable continuous circulation during well intervention, eliminating threaded connections and reducing trip times compared to conventional jointed pipe. Well intervention applications command the largest revenue share due to mature field remediation demand across North America and the Middle East. Drilling applications represent the fastest-expanding segment as operators deploy coiled tubing for slim-hole re-entry and underbalanced drilling in depleted reservoirs. Onshore deployment dominates unit volumes, though offshore specifications command premium pricing for corrosion-resistant alloys and enhanced fatigue resistance.
API 5ST standards govern dimensional tolerances, mechanical properties, and hydrostatic testing protocols for coiled tubing strings used in oilfield service. The EPA regulates hydraulic fracturing chemical disclosure and wastewater handling, indirectly shaping coiled tubing utilization patterns in shale basins. OSHA mandates fall protection and pressure-control training for coiled tubing crews operating high-pressure pumping equipment. Stakeholders must monitor evolving state-level methane emission rules and carbon intensity benchmarks that could alter deployment economics for gas-lift and nitrogen circulation services.
Market Dynamics
The migration toward extended-reach laterals in unconventional shale formations is restructuring coiled tubing utilization patterns, forcing operators to prioritize fatigue-resistant alloys and real-time downhole monitoring over conventional equipment specifications.
Growth Catalysts
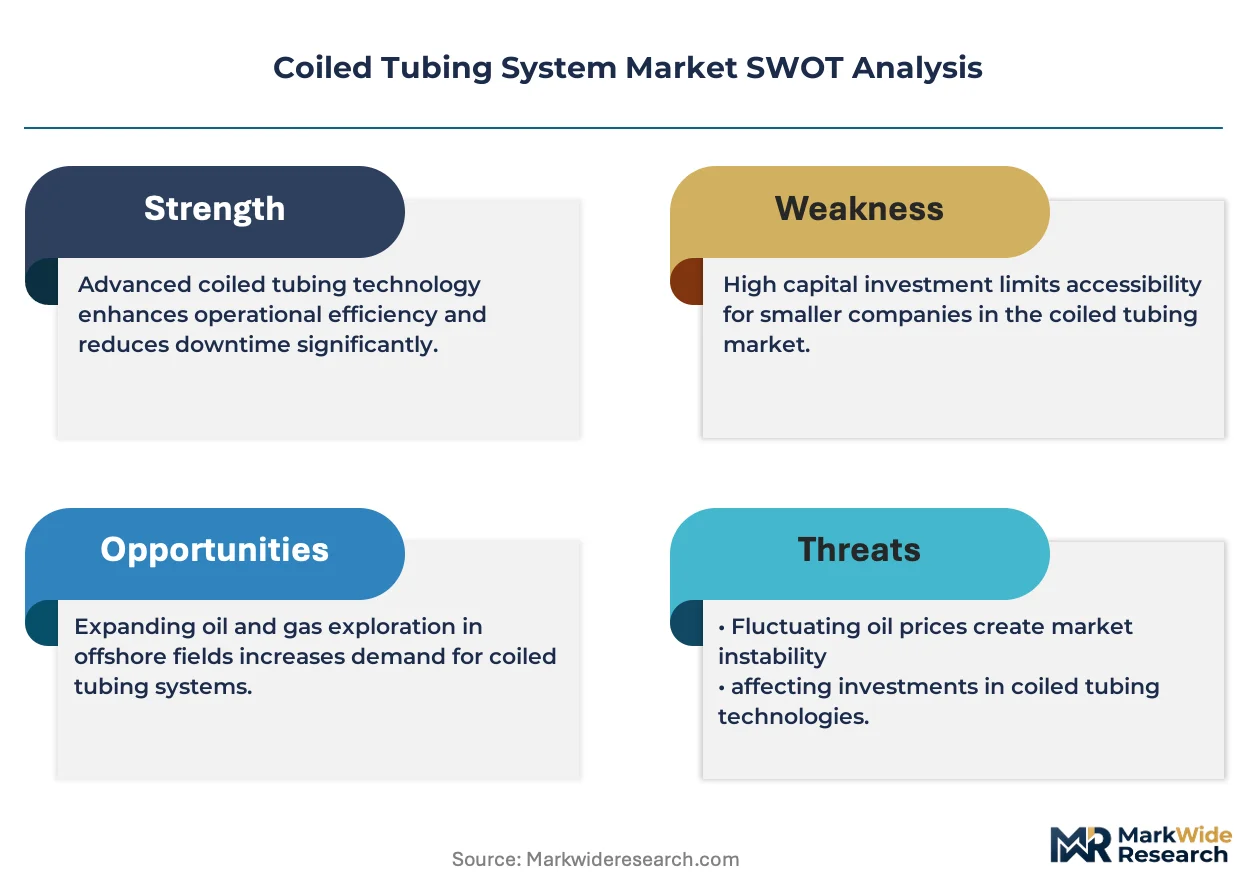
- API 5ST Specification Upgrades:Tighter dimensional tolerances and enhanced hydrostatic testing protocols are elevating tubing reliability for high-pressure shale interventions, compelling fleet operators to refresh aging strings.
- Permian Basin Activity Concentration:Unconventional operators in West Texas and southeastern New Mexico are deploying coiled tubing units for continuous circulation in multi-mile laterals, sustaining equipment utilization rates.
- Offshore Sour-Service Demand:Gulf of Mexico shelf developments require corrosion-resistant alloys for hydrogen sulfide environments, creating premium-grade tubing pull-through.
Market Restraints
- Specialized Steel Input Volatility:Chromium-molybdenum alloy prices fluctuate with mining output from South African and Kazakhstani suppliers, compressing fabrication margins.
- Reel Manufacturing Concentration:Large-diameter reel fabrication capacity clusters among a limited set of North American metalworking facilities, extending lead times during demand surges.
- Threaded Pipe Substitution:Conventional jointed tubing retains cost advantages for shallow, low-pressure workovers in mature onshore fields.
Strategic Opportunities
- Middle East Gas-Lift Expansion:Saudi Arabian and Qatari operators are evaluating coiled tubing for deep gas well deliquification, representing underpenetrated deployment territory.
- Real-Time Diagnostics Convergence:Fiber-optic telemetry integration with coiled tubing strings is converging with automated well intervention platforms, enabling precision depth control.
- US Methane Emission Rules:EPA leak detection and repair mandates are accelerating nitrogen circulation services for wellbore cleanouts, favoring continuous tubing deployment over snubbing units.
Industry Challenges
- Fatigue-Testing Certification Bottlenecks:API 5ST cycle-testing protocols require extended laboratory timelines, delaying new product qualification.
- High-Pressure Equipment Integration:Coiled tubing crews must synchronize pumping spreads with live-well control systems, demanding cross-functional competency development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coiled Tubing System Market |
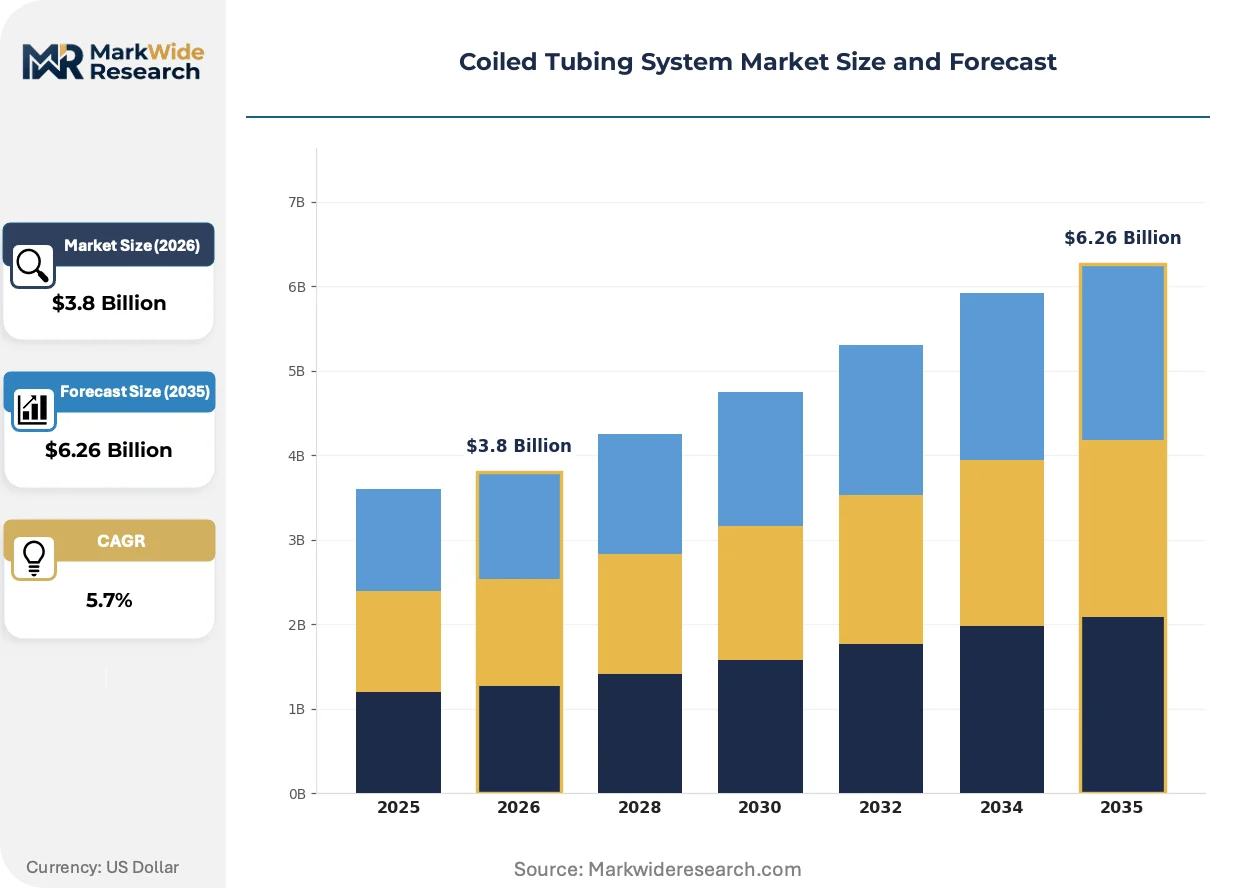
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coiled Tubing, Reels, Connectors, Equipment Application: Well Intervention, Drilling, Completion, Workover End User: Oil & Gas Operators, Service Companies, Engineering Firms, Contractors Deployment: Onshore, Offshore, Remote Locations, Urban Areas |
| Companies Covered | Halliburton, Schlumberger Limited, Baker Hughes Company, Weatherford International plc, NOV, Calfrac Well Services Ltd., Step Energy Services Ltd., Archer Limited, Nabors Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coiled Tubing System Market Evolving Landscape
Equipment intelligence and metallurgical advancement are displacing legacy intervention economics, compressing the gap between diagnostic capability and mechanical execution in downhole operations.
Composite-reinforced coiled tubing is converging with conventional steel architectures to deliver weight reduction for ultra-deep deployments. Operators in the Gulf of Mexico shelf are piloting hybrid strings for subsea interventions, reducing crane load requirements while maintaining pressure ratings. This convergence is compressing the technical boundary between coiled tubing and wireline service envelopes.
OSHA fall protection mandates and pressure-control training requirements are tightening crew certification standards for high-pressure pumping operations. Service companies must document competency matrices for personnel operating live-well equipment, elevating labor costs but reducing incident liability. North American onshore basins are absorbing these compliance investments fastest due to workforce mobility constraints.
Multi-vendor qualification programs are displacing single-source tubing procurement among Permian Basin operators. Integrated independents now maintain approved supplier lists across three to four fabricators, reducing concentration risk but fragmenting volume commitments. This pattern is most pronounced among supermajor-affiliated service providers managing capital discipline mandates.
Coiled Tubing System Market Segmentation
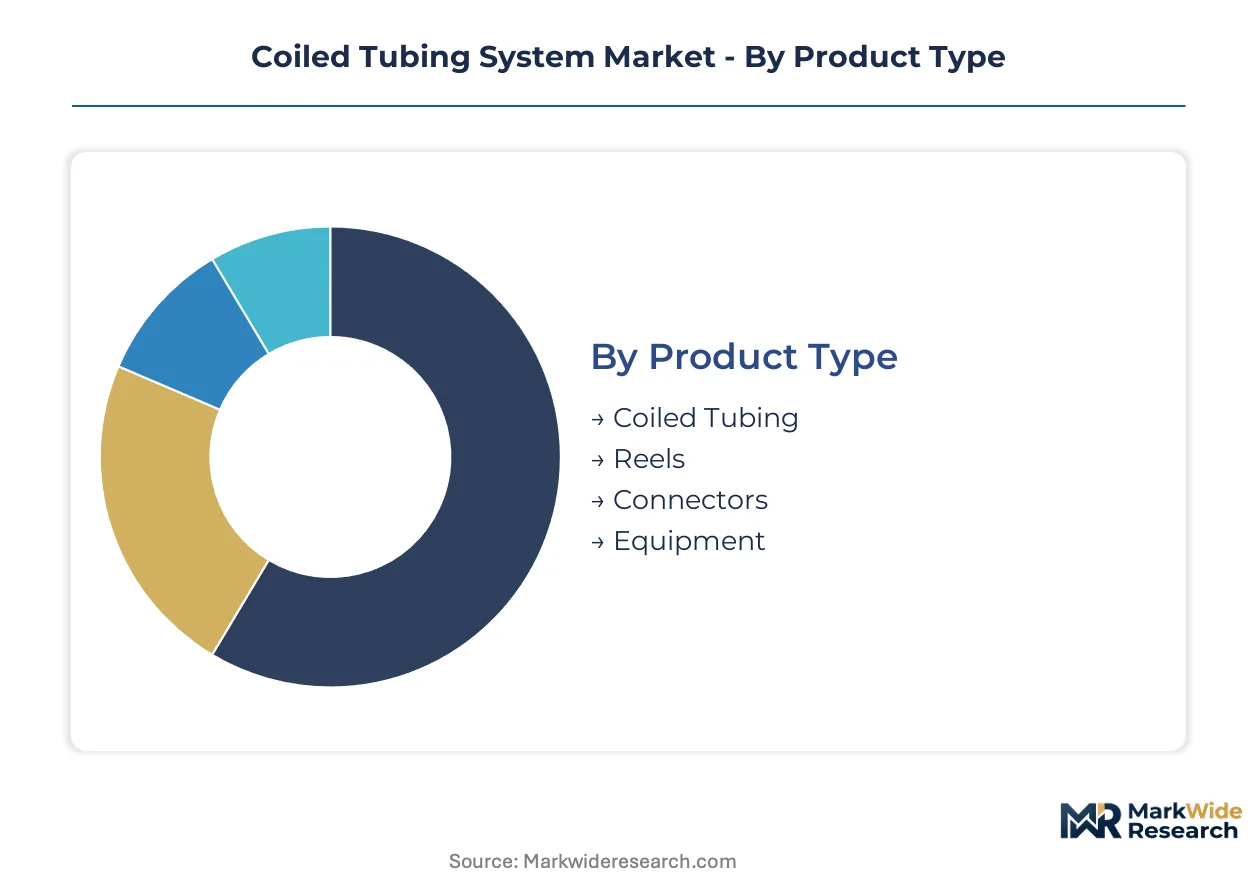
Segmentation in coiled tubing systems reveals how equipment specifications, operational environments, and procurement authority distribute value across the supply chain. Understanding these divisions exposes where fabrication margins concentrate and where qualification barriers protect incumbent positions.
Product Type:
Supply concentration in steel metallurgy and reel fabrication capacity shapes competitive dynamics across equipment categories.
- Coiled Tubing:Continuous seam-welded or seamless steel pipe manufactured to API 5ST specifications with outer diameters from one to four inches. Demand clusters around fatigue-resistant chromium-molybdenum alloys for Permian Basin extended-reach laterals where cycle-life requirements exceed 10,000 pressure cycles.
- Reels:Large-diameter spooling systems typically exceeding 20 feet in drum diameter, fabricated from high-strength structural steel. Fabrication capacity concentrates among North American metalworking facilities in Texas and Oklahoma, extending lead times during demand surges as operators refresh aging fleet equipment.
- Connectors:Pressure-rated quick-connect fittings enabling rapid string assembly without threaded makeup.
- Equipment:Injector heads, stripper assemblies, and pressure control stacks that constitute the surface handling system.
Today's leader: Coiled Tubing. Tomorrow's challenger: Reels.
Application:
Operational intensity and well complexity determine equipment specification tiers across service envelopes.
- Well Intervention:Mature field remediation including nitrogen circulation, acid stimulation, and mechanical cleanouts. North American shale operators deploy continuous circulation for multi-mile laterals, sustaining utilization rates above conventional workover economics.
- Drilling:Slim-hole re-entry and underbalanced drilling in depleted reservoirs. This segment climbs fastest as operators target bypassed pay zones with reduced formation damage risk compared to conventional overbalanced techniques.
- Completion:Fracturing fluid placement and proppant conveyance in multistage unconventional wells.
- Workover:Routine maintenance and repair operations in mature onshore fields.
Well Intervention commands current volume. Drilling gains share fastest on technical differentiation.
End User:
Procurement authority and capital allocation discipline segment the customer base by risk tolerance and fleet ownership models.
- Oil & Gas Operators:Supermajors and large independents specifying equipment for captive use or integrated service packages. Saudi Aramco and QatarEnergy evaluate coiled tubing for deep gas deliquification, representing underpenetrated deployment territory with stringent sour-service metallurgy requirements.
- Service Companies:Halliburton, Baker Hughes, and Schlumberger maintain owned fleets and drive equipment refresh cycles through multi-vendor qualification programs that fragment volume commitments across fabricators.
- Engineering Firms:Technical consultants specifying equipment for operator-directed projects.
- Contractors:Regional service providers leasing equipment or operating under day-rate contracts.
Service Companies dominate equipment procurement. Operators are consolidating specification authority.
Deployment:
Environmental exposure and logistics infrastructure segment pricing power and corrosion resistance requirements.
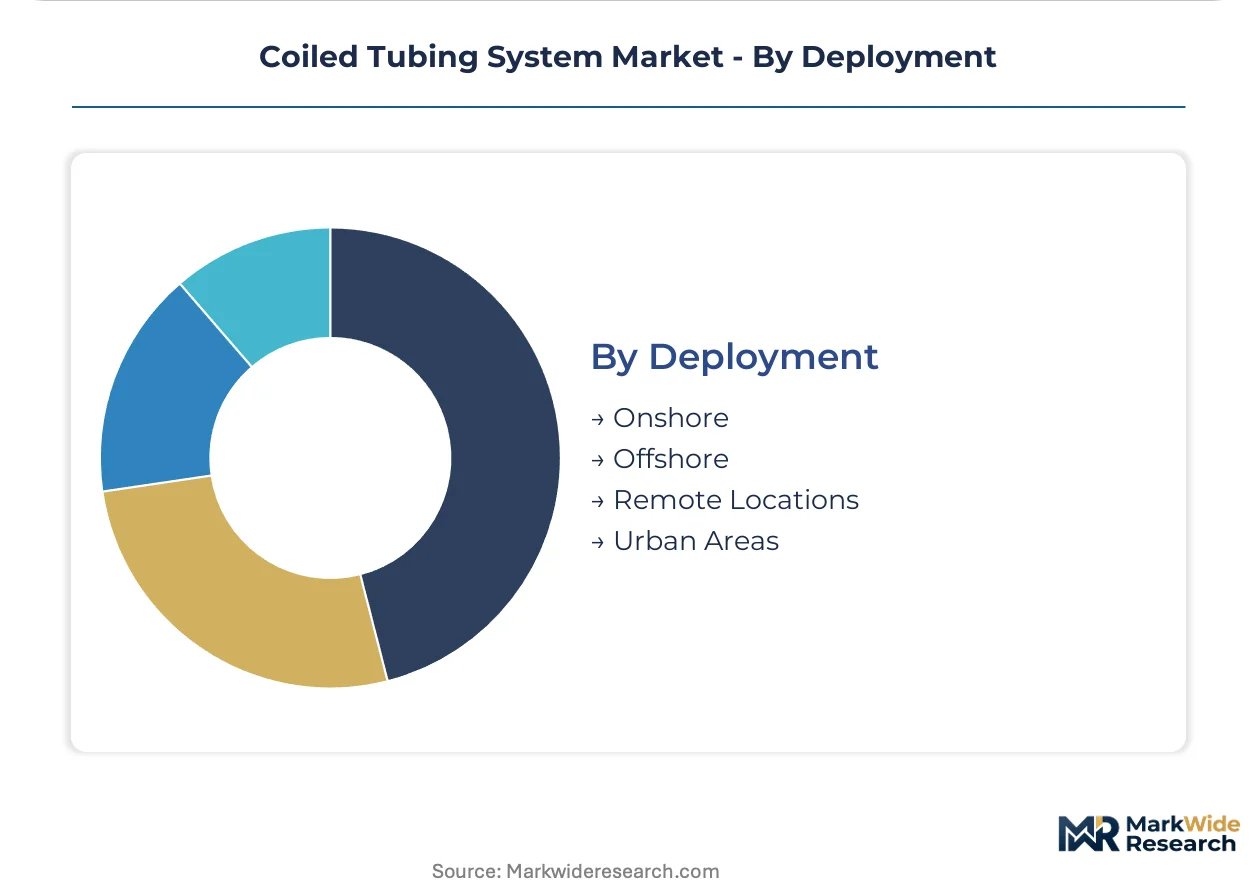
- Onshore:West Texas, southeastern New Mexico, and Oklahoma account for the majority of unit volumes. EPA methane emission rules accelerate nitrogen circulation services, favoring continuous tubing deployment over snubbing units for wellbore cleanouts.
- Offshore:Gulf of Mexico shelf developments command premium pricing for corrosion-resistant alloys and enhanced fatigue resistance in hydrogen sulfide environments. Subsea interventions require hybrid composite-reinforced strings to reduce crane load requirements.
- Remote Locations:Arctic and desert environments with limited infrastructure and extreme temperature cycling.
- Urban Areas:Noise-constrained operations requiring enclosed pressure control and reduced surface footprint.
Onshore delivers volume scale. Offshore captures margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in steel sourcing and fabrication compliance is redirecting coiled tubing manufacturing toward jurisdictions with lower alloy processing costs, while end-use demand concentrates in shale basins with the most permissive drilling permit regimes.
United States
Permian Basin operators in West Texas and southeastern New Mexico deploy coiled tubing for continuous circulation in multi-mile laterals, sustaining equipment utilization rates above conventional workover economics. EPA methane emission rules accelerate nitrogen circulation services, favoring continuous tubing deployment over snubbing units for wellbore cleanouts. Houston anchors the largest concentration of reel fabrication capacity and service company headquarters.
Canada
Montney and Duvernay shale operators evaluate coiled tubing for underbalanced drilling in depleted reservoirs, reducing formation damage risk compared to conventional overbalanced techniques. Health Canada and provincial regulators enforce sour-service metallurgy standards for hydrogen sulfide environments. Calgary-based engineering firms specify equipment for operator-directed projects across the Western Canadian Sedimentary Basin.
Saudi Arabia
Saudi Aramco evaluates coiled tubing for deep gas well deliquification, representing underpenetrated deployment territory with stringent sour-service metallurgy requirements. SFDA and national oil company procurement standards govern equipment qualification timelines. Dhahran and the Eastern Province concentrate technical evaluation capacity for high-pressure gas field applications.
China
Sinopec and PetroChina deploy coiled tubing for mature field remediation in Shengli and Daqing oil provinces, sustaining domestic fabrication demand. MIIT and GB standards govern dimensional tolerances for indigenous equipment procurement. Shandong Province hosts the largest concentration of domestic reel manufacturing capacity.
Norway
Equinor and Aker BP specify corrosion-resistant alloys for subsea interventions in the North Sea, commanding premium pricing for enhanced fatigue resistance. Petroleum Safety Authority Norway mandates fall protection and pressure-control training for offshore coiled tubing crews. Stavanger anchors the largest technical specification authority for hybrid composite-reinforced strings.
Coiled Tubing System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite-reinforced architectures and automated intervention platforms. The vendor base stratifies across three tiers: integrated oilfield service conglomerates with captive fleet ownership, independent tubing fabricators supplying multi-vendor qualification programs, and regional equipment lessors operating under day-rate contracts. Dominant competitive moves include backward integration into steel sourcing and reel manufacturing, plus strategic partnerships with fiber-optic telemetry providers.
Among Houston-based integrated service providers, Halliburton, Baker Hughes Company, and Schlumberger Limited exemplify the conglomerate archetype. These entities anchor equipment procurement authority through owned fleet refresh cycles and bundled well intervention packages. Their positioning reflects the market's gravitational pull toward integrated service envelopes that combine mechanical tubing deployment with real-time downhole diagnostics.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger Limited |
| Baker Hughes Company |
| Weatherford International plc |
| NOV |
| Calfrac Well Services Ltd. |
| Step Energy Services Ltd. |
| Archer Limited |
| Nabors Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Multi-vendor qualification programs among Permian Basin operators are forcing fabricators to absorb certification costs while competing on cycle-life guarantees, compressing margins on standard-grade strings and widening spreads for fatigue-resistant alloys.
Pricing Analysis
Chromium-molybdenum alloy costs pass through directly to tubing quotes, with South African and Kazakhstani mining volatility feeding into quarterly contract adjustments. Pricing stratifies across API 5ST-certified premium strings, standard well intervention grades, and economy-tier workover specifications. Cost compression in standard grades is intensifying because operators fragment volume commitments across three to four approved suppliers. Independent operators exhibit highest price sensitivity, while supermajor-affiliated service providers prioritize fatigue-cycle guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Halliburton, Baker Hughes, and Schlumberger mandate approved supplier lists spanning multiple fabricators, preventing single-source concentration. Manufacturing gravity centers on Texas, Oklahoma, and Shandong Province for reel fabrication and continuous pipe welding. Raw material feeds draw from chromium-molybdenum alloy suppliers, high-strength structural steel mills, and fiber-optic telemetry providers. Tariff exposure on specialty steel imports from Kazakhstan poses structural vulnerability. Distribution runs through service company fleet procurement channels and regional equipment lessor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fabrication costs in Shandong Province undercut North American metalworking by double-digit spreads, while EPA methane rules and OSHA certification mandates in the United States sustain premium pricing for compliant equipment.
For Market Incumbents: Acquire captive reel manufacturing capacity to compress lead times during Permian demand surges. Secure backward integration into chromium-molybdenum alloy sourcing to buffer South African supply disruptions. Invest in fiber-optic telemetry partnerships before real-time diagnostics converge with automated intervention platforms. For New Entrants and Emerging Players: Begin with sour-service metallurgy qualification for Saudi Aramco and QatarEnergy gas-lift evaluations, the most penetrable deployment territory. Target hybrid composite-reinforced architectures for Gulf of Mexico subsea interventions where crane load constraints create technical differentiation. Pursue equipment-leasing models under day-rate contracts to bypass fleet ownership capital barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with independent tubing fabricators holding API 5ST certification and multi-vendor program approval. Long-term viability hinges on fatigue-testing laboratory capacity and alloy processing relationships rather than assembly scale. Watch for EPA methane rule enforcement intensity as the inflection signal for nitrogen circulation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Captive chromium-molybdenum supply buffers Kazakhstani mining volatility for Permian fabricators. |
| Fiber-Optic Telemetry Partnership | Real-time downhole diagnostics integration commands premium pricing in extended-reach lateral deployments. |
| Multi-Vendor Qualification Program | Approved supplier status with Halliburton and Baker Hughes fragments volume but secures baseline utilization. |
| Composite-Reinforced String Development | Hybrid architectures reduce crane loads for Equinor subsea interventions in the North Sea. |
| API 5ST Fatigue-Testing Laboratory Expansion | In-house cycle-testing capability accelerates new product qualification against certification bottlenecks. |
Research Methodology
Direct dialogue with coiled tubing fleet managers, API certification laboratory directors, Permian Basin procurement leads, and North Sea subsea intervention engineers grounded qualitative findings. Secondary validation drew from EPA methane emission filings, OSHA pressure-control training mandates, API 5ST specification documents, and SEC 10-K disclosures from integrated service providers. Bottom-up equipment unit economics triangulated against top-down shale basin activity projections.
Bottom-up modeling aggregated tubing string refresh cycles, reel manufacturing capacity utilization, and regional deployment intensity across the analysis window. Segmentation dimensions included product type, application envelope, end-user procurement authority, and deployment environment. CAGRs derived from equipment replacement timelines and unconventional shale lateral length trajectories. Forecast inputs incorporated chromium-molybdenum alloy price indices and state-level methane regulation adoption curves.
Caveats apply where South African mining disruptions, EPA enforcement intensity variations, or composite-reinforced string technical failures could materially shift the outlook. Deviation in Permian Basin drilling permit issuance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Intelligent Pigging Services Market