
 Africa Oil Country Tubular Goods (OCTG) Market | 2026-2036
Africa Oil Country Tubular Goods (OCTG) Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Oil Country Tubular Goods (OCTG) Market Outlook
Supply chain routes into African oilfields are tilting toward regional stocking hubs and integrated mill-direct programs. Tenaris SA leverages its Argentine-Brazilian manufacturing base to anchor delivery timelines for West African offshore projects. Vallourec SA competes through premium threading technology and localized inspection services in Angola and Nigeria. Jindal Saw Ltd extends its position via cost-competitive carbon steel casing for onshore workover campaigns.
Oil Country Tubular Goods encompass seamless and welded steel pipes manufactured to API 5CT specifications, with yield strengths ranging from H-40 to Q-125 grades, designed to withstand downhole pressure, corrosive fluids, and mechanical loads during drilling, completion, and production operations. Casing strings dominate capital allocation in deepwater budgets where high-collapse grades command sustained margin pools. Alloy steel grades are displacing carbon alternatives in sour service environments across Nigerian delta fields. Drill pipe demand tracks jackup and semi-submersible rig deployment schedules off Mozambique and Tanzania.
Nigeria's Department of Petroleum Resources enforces well integrity standards that mandate third-party inspection of imported tubulars, while Angola's national oil company imposes local content thresholds on procurement spend. API 5CT and ISO 11960 certification requirements create non-tariff barriers that filter out non-compliant suppliers from tender rounds. Stakeholders must monitor rig count trajectories and local content enforcement intensity as the primary demand signals for inventory positioning and partnership structures.
Market Dynamics
Deepwater exploration economics in West Africa are compressing procurement cycles for premium casing strings, forcing operators to pre-position high-collapse grade inventory before rig contracts finalize.
Growth Catalysts
- Angolan Local Content Mandates:Sonangol's procurement rules require minimum domestic spend thresholds, creating captive demand for inspection and threading services hosted in Luanda.
- API 5CT Specification Upgrades:Revised material standards for sour service environments are pulling corrosion-resistant alloy adoption across Nigerian delta fields.
- Mozambique LNG Feedstock Requirements:Offshore development timelines for Rovuma Basin fields are synchronizing drill pipe orders with floating production facility construction schedules.
Market Restraints
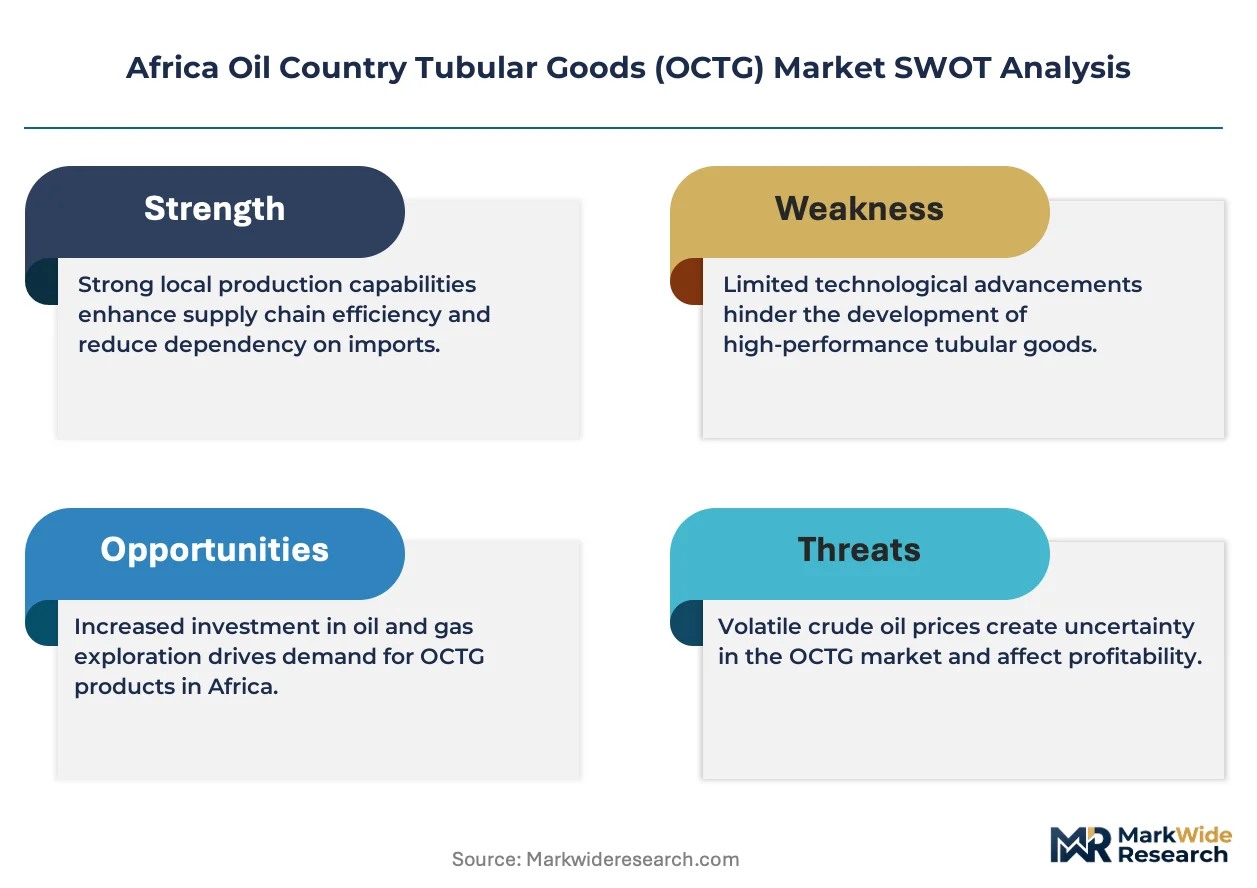
- Scrap Steel Price Volatility:Electric arc furnace input costs for seamless pipe mills fluctuate with Turkish and Chinese export pricing, compressing margin predictability for carbon steel grades.
- Single-Source Premium Threading:Proprietary connection technologies from European licensors concentrate high-end supply, creating bottleneck risk for Q-125 casing strings in Nigerian deepwater tenders.
- Carbon Steel Substitution Ceiling:Sour service limits in high-H2S formations prevent downgrade from CRA to carbon alternatives, locking operators into premium material cost structures.
Strategic Opportunities
- Tanzania Unconventional Prospects:Onshore rift basin exploration is opening demand for cost-optimized tubing strings below API premium grades.
- Integrated Mill-Direct Programs:Argentine-Brazilian manufacturing bases are anchoring consolidated shipment routes that bypass European transshipment hubs.
- Nigerian Well Integrity Enforcement:Department of Petroleum Resources third-party inspection mandates are creating service revenue pools for certified testing facilities in Port Harcourt and Lagos.
Industry Challenges
- CRA Welding Qualification Shortage:Corrosion-resistant alloy pipe fitters with ASME Section IX credentials are concentrated in South African and Egyptian labor pools, creating mobilization delays for East African projects.
- API 5CT Certification Backlogs:Accredited lab capacity for Q-125 yield testing is throttling supplier qualification timelines for premium tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Oil Country Tubular Goods (OCTG) Market |
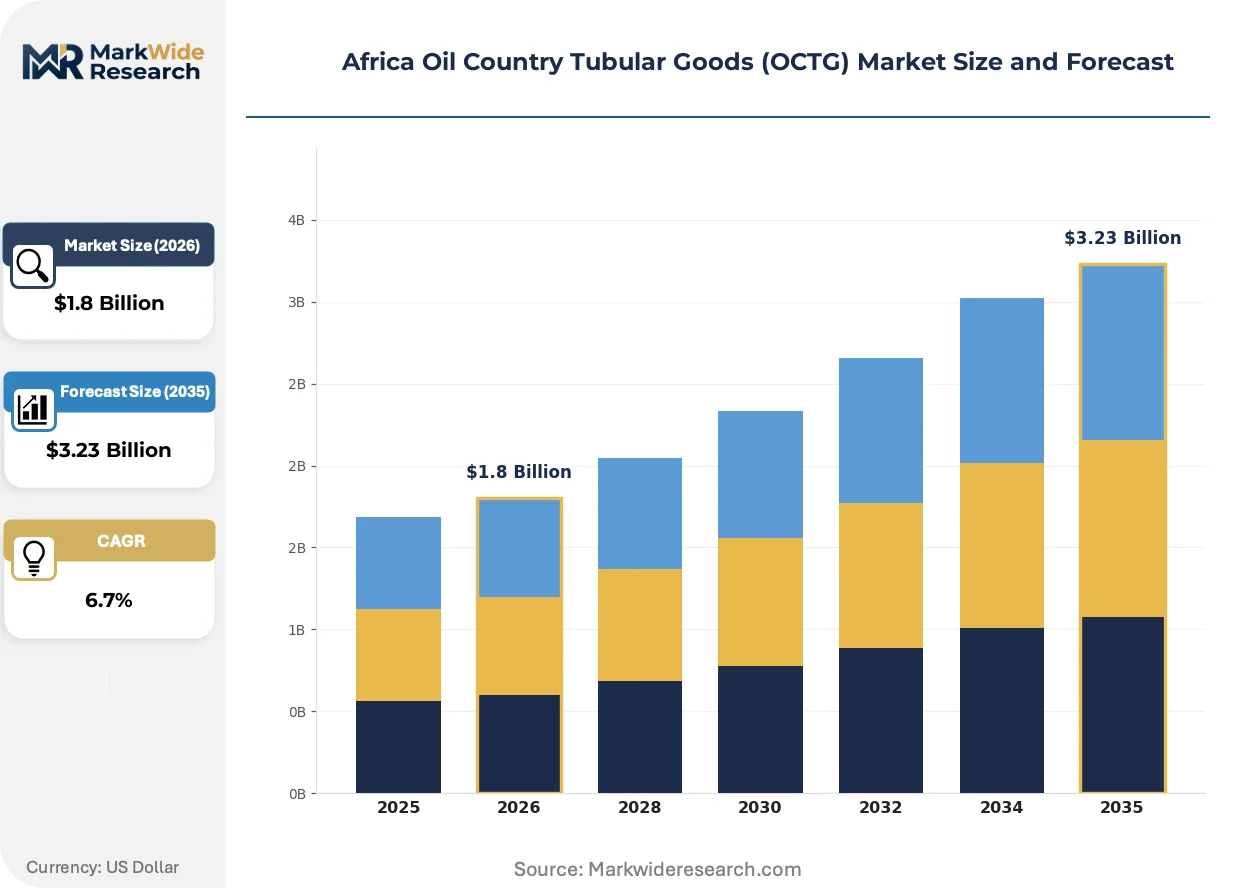
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
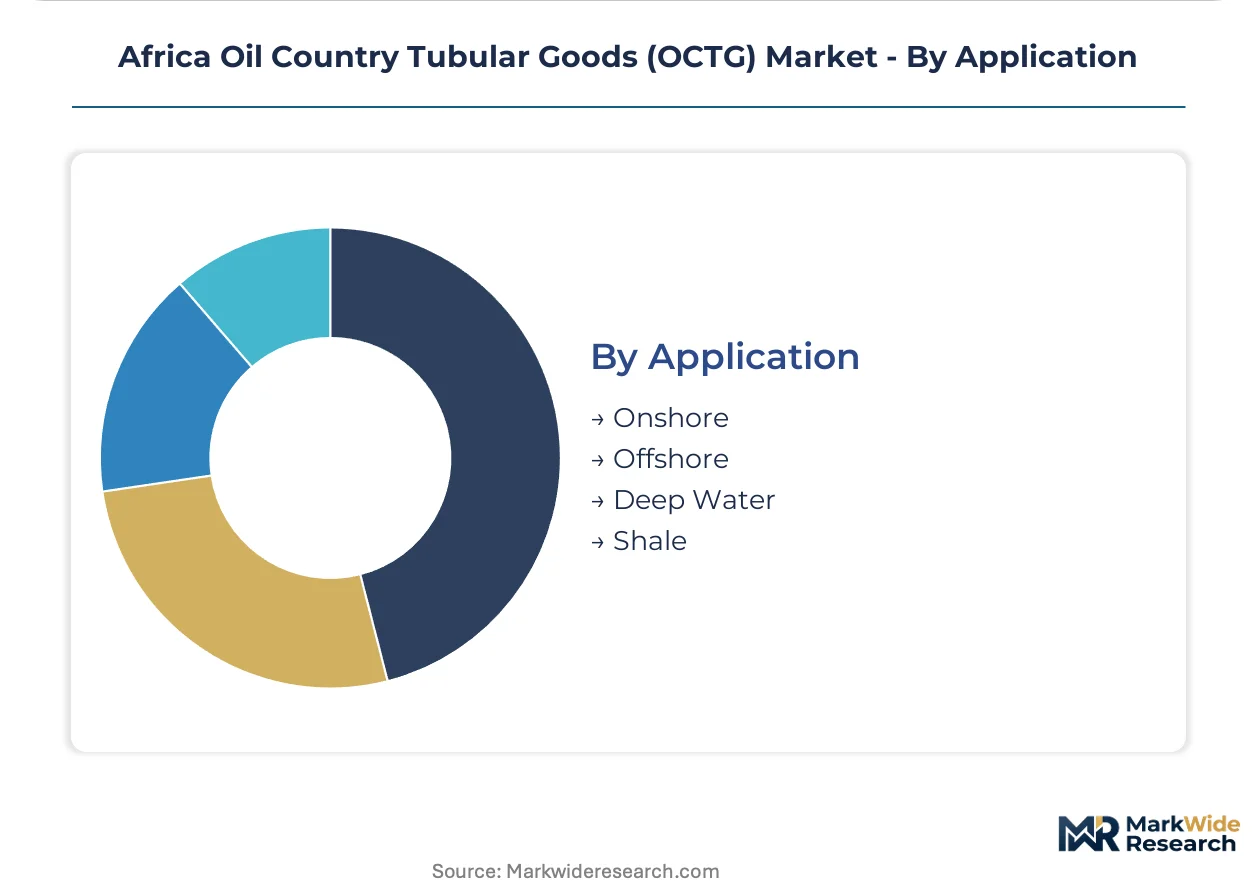
| Segmentation | Product Type: Line Pipe, Casing, Tubing, Drill Pipe Material: Carbon Steel, Alloy Steel, Stainless Steel, Others End User: Exploration, Production, Midstream, Service Providers Application: Onshore, Offshore, Deep Water, Shale |
| Companies Covered | Tenaris SA, Vallourec SA, National-Oilwell Varco Inc, Nippon Steel Corporation, ArcelorMittal SA, TMK Group, Jindal Saw Ltd, TPCO Enterprise Inc, JFE Steel Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Oil Country Tubular Goods (OCTG) Market Strategic Shifts
Material science advances and procurement model compression are restructuring how operators specify, source, and deploy tubular strings across African offshore and onshore campaigns.
Corrosion-resistant alloy metallurgy with enhanced chromium-molybdenum formulations is rendering obsolete carbon steel casing in high-H2S Nigerian delta formations. International oil companies operating OML blocks are mandating CRA specifications for all new wells regardless of initial reservoir souring assessments. This specification ratchet is collapsing the addressable market for standard API grades in West Africa's most productive basins.
Nigeria's Department of Petroleum Resources well integrity standards now require documented traceability from mill heat number to final installation. Operators must maintain digital chain-of-custody records for third-party inspector verification at rig site receipt. This compliance architecture favors suppliers with integrated manufacturing-to-logistics control over fragmented trading house arrangements.
Pre-commitment inventory placement is displacing just-in-time procurement for deepwater projects off Angola and Mozambique. National oil companies are demanding stocked availability of high-collapse grades before issuing final rig contracts, transferring carrying cost risk to tubular suppliers. This shift concentrates working capital requirements among integrated mills with regional hub capacity.
Africa Oil Country Tubular Goods (OCTG) Market Segmentation
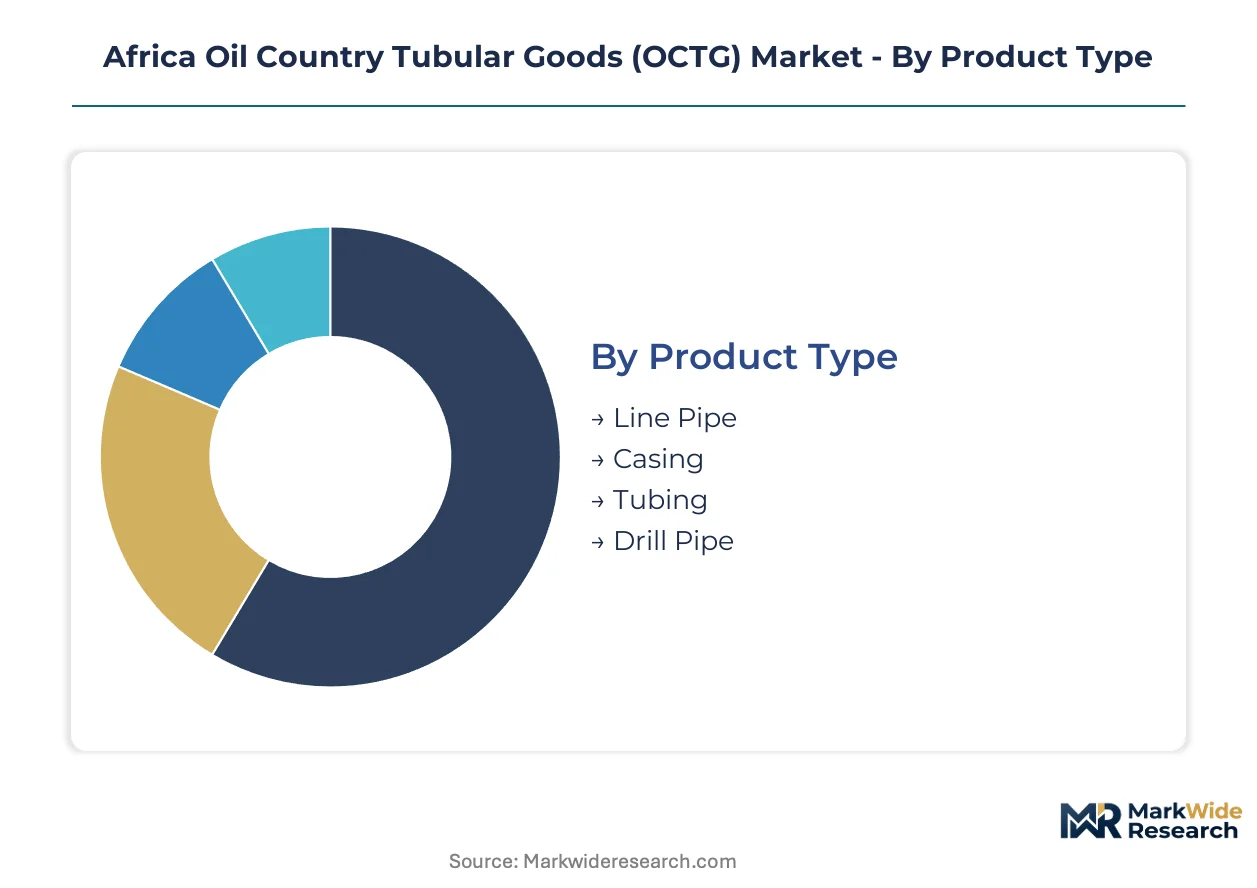
OCTG procurement in African basins splits across four dimensions that dictate metallurgical specifications, inspection protocols, and inventory positioning strategies for suppliers. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning across West and East African markets.
Product Type:
The use-case spectrum spans surface infrastructure through downhole pressure containment, with each product category commanding differentiated technical specifications and capital allocation intensity in operator budgets.
- Casing:Seamless or welded steel strings manufactured to API 5CT grades H-40 through Q-125, designed to withstand formation pressure and prevent borehole collapse during drilling and completion. Nigerian deepwater projects concentrate demand for high-collapse grades above P-110, where pre-positioned inventory mandates from Sonangol and NNPC transfer carrying cost risk to mill-direct suppliers.
- Tubing:Production conduit installed inside casing to transport hydrocarbons to surface, available in standard and premium threaded configurations. Workover campaigns across Angola's mature offshore fields and Nigeria's onshore delta sustain recurring demand for corrosion-resistant alloy tubing in sour service environments.
- Drill Pipe:Heavy-walled seamless tube with tool joints welded to each end, transmitting torque and circulating drilling fluid during borehole creation. Rig deployment schedules off Mozambique and Tanzania synchronize procurement with jackup and semi-submersible contract awards.
- Line Pipe:Longitudinal or spiral-welded pipe for surface gathering and transmission infrastructure. Midstream expansion in Nigeria's Niger Delta and Angola's Cabinda exclave drives grade X52 through X70 specification demand.
Established volume favors Casing; emerging adoption favors Drill Pipe as East African offshore rig counts climb.
Material:
Cost tier stratification separates commodity carbon grades from premium alloy formulations, with selection criteria increasingly dictated by formation chemistry rather than upfront capital minimization.
- Alloy Steel:Chromium-molybdenum enhanced formulations delivering superior tensile strength and sour service resistance. Nigerian Department of Petroleum Resources well integrity standards now mandate CRA specifications for all new wells in delta blocks regardless of initial H2S assessments, collapsing the addressable market for carbon alternatives in West Africa's most productive basins.
- Carbon Steel:Standard API 5CT grades for low-corrosion environments and surface casing applications. Onshore workover campaigns in Tanzania's rift basins and mature Nigerian fields sustain demand where formation chemistry permits downgrade from alloy specifications.
- Stainless Steel:Austenitic and duplex grades for extreme corrosive environments and completion accessories. Premium completion hardware in Angolan deepwater pre-salt developments commands 316L and super-duplex specifications.
- Others:Titanium, nickel alloys, and composite materials for specialized high-temperature high-pressure applications. Experimental deployment in Nigerian ultra-deepwater test wells remains constrained by welding qualification shortages.
Carbon Steel retains volume leadership; Alloy Steel gains share fastest as sour service mandates expand.
End User:
Customer type fragmentation splits procurement authority between national oil companies, international operators, and service contractors, each with distinct technical specification control and local content compliance obligations.
- Production:Operating companies managing producing assets and replacement tubing programs. Mature field operators across Angola's Block 0 and 15 prioritize cost-optimized carbon steel for workover economics.
- Exploration:Wildcat drilling campaigns and appraisal programs requiring premium casing strings. Nigerian deepwater exploration budgets concentrate procurement of Q-125 grades with proprietary premium connections.
- Service Providers:Drilling contractors and rental companies supplying tubulars as part of integrated service packages. International contractors operating in Mozambique's Rovuma Basin bundle drill pipe with rig packages.
- Midstream:Pipeline operators and gas processing facility developers. Nigeria LNG Train 7 expansion and Angola LNG maintenance cycles drive line pipe specifications.
Production commands current spend; Exploration steers premium technology adoption.
Application:
Geographic deployment context dictates pressure rating requirements, logistics complexity, and regulatory inspection intensity across the African continent's diverse operating environments.
- Deep Water:Borehole sections below 500 meters water depth requiring high-collapse casing and premium threaded connections. Angolan pre-salt and Nigerian Bonga field developments synchronize procurement with floating production facility construction schedules.
- Offshore:Shelf and marginal field developments in water depths to 500 meters. Nigerian shallow-water concessions and Mozambique's initial Rovuma Basin phases sustain jackup-accessible demand.
- Onshore:Land-based drilling across rift basins and deltaic terrains. Tanzania's emerging unconventional prospects and Nigeria's Niger Delta workovers favor cost-optimized tubing below API premium grades.
- Shale:Unconventional reservoir development requiring horizontal drilling and hydraulic fracturing compatibility. Limited current activity in North African shale plays constrains segment scale.
Deep Water absorbs premium investment; Onshore presents volume expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sonangol's local content mandates and NNPC's well integrity enforcement are redirecting procurement flows toward regional stocking hubs. National oil companies across West and East Africa now require pre-positioned inventory before rig contract finalization.
Nigeria
Deepwater exploration in the Bonga field and Niger Delta workover campaigns sustain demand for Q-125 casing and corrosion-resistant alloy tubing. The Department of Petroleum Resources mandates third-party inspection and digital chain-of-custody traceability from mill heat number to installation. Port Harcourt and Lagos host certified testing facilities capturing service revenue from compliance architecture.
Angola
Pre-salt development timelines synchronize high-collapse grade procurement with floating production facility construction schedules. Sonangol imposes minimum domestic spend thresholds, creating captive demand for threading and inspection services in Luanda. Block 0 and Block 15 mature field operators prioritize cost-optimized carbon steel for workover economics.
Mozambique
Rovuma Basin offshore development drives drill pipe orders tracking jackup and semi-submersible rig deployment schedules. LNG feedstock requirements from onshore processing facilities constrain tubular delivery windows. Maputo serves as the logistics coordination point for consolidated mill-direct shipments bypassing European transshipment.
Tanzania
Onshore rift basin exploration opens demand for cost-optimized tubing strings below API premium grades. Unconventional prospects in frontier blocks favor carbon steel specifications where formation chemistry permits downgrade from alloy alternatives. Dar es Salaam anchors regional distribution for East African land-based drilling campaigns.
South Africa
ASME Section IX-certified welders for corrosion-resistant alloy pipe concentrate in Gauteng and Western Cape labor pools, creating mobilization bottlenecks for East African projects. Accredited lab capacity for Q-125 yield testing throttles supplier qualification timelines. Durban hosts the primary port infrastructure for southern African OCTG transshipment.
Africa Oil Country Tubular Goods (OCTG) Market Competitive Environment
On the supply side, the industry is consolidating around integrated mills with regional hub capacity and fragmented trading houses losing share to mill-direct programs. Argentine-Brazilian manufacturing bases anchor consolidated shipment routes that bypass European transshipment. Two strategic archetypes dominate: premium threading specialists with proprietary connection technologies, and cost-competitive carbon steel producers serving onshore workover economics. Capacity expansion and strategic partnerships represent the dominant competitive vectors as suppliers pre-position inventory to meet pre-commitment mandates.
Among the integrated mill cohort, Tenaris SA and Vallourec SA exemplify the premium-tier positioning anchored by regional manufacturing footprints. Jindal Saw Ltd occupies a position within the cost-optimized segment serving carbon steel demand for mature field workovers. These three companies represent the spectrum of competitive positioning from high-collapse grade specialists to volume-driven standard grade suppliers.
| Leading Market Players |
|---|
| Tenaris SA |
| Vallourec SA |
| National-Oilwell Varco Inc |
| Nippon Steel Corporation |
| ArcelorMittal SA |
| TMK Group |
| Jindal Saw Ltd |
| TPCO Enterprise Inc |
| JFE Steel Corporation |
| Others |
Value Chain & Pricing Dynamics
Luanda's threading and inspection service clusters concentrate premium-grade OCTG finishing capacity, translating Sonangol's local content mandates into pricing power for compliant suppliers while excluding non-anchored trading houses from tender participation. This geographic supply concentration allows integrated mills to capture margin premiums on Q-125 casing strings destined for Angolan pre-salt developments.
Pricing Analysis
API 5CT certification level creates the primary spread between commodity carbon grades and corrosion-resistant alloy specifications, with Nigerian Department of Petroleum Resources well integrity standards mandating CRA adoption regardless of initial reservoir souring assessments. Three-tier pricing structure across premium CRA, standard carbon, and economy workover grades reflects this compliance-driven stratification. Cost compression in carbon steel tiers is intensifying because Turkish and Chinese scrap export volatility feeds directly into electric arc furnace input costs. Mature field operators across Angola's Block 0 and 15 exhibit the highest price sensitivity, while Nigerian deepwater exploration budgets show inelastic demand for proprietary premium connections.
Supply Chain Analysis
Argentine-Brazilian manufacturing bases anchor seamless pipe production for West African delivery, with Tenaris SA's Argentine mills and Vallourec SA's Brazilian facilities holding dominant contract-manufacturing positions for regional hub stocking. Raw material dependencies draw from Turkish scrap steel exports, Chinese billet shipments, and chromium-molybdenum alloy feedstocks. Single-source vulnerability concentrates in proprietary threading technologies licensed from European specialists, creating bottleneck risk for Q-125 grades in Nigerian deepwater tenders. Distribution runs through Port Harcourt, Lagos, and Luanda regional hubs that bypass European transshipment for mill-direct programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite materials and non-metallic tubular alternatives represent an emerging substitution threat that incumbent steel OCTG suppliers must navigate through metallurgical innovation and specification lock-in strategies.
For Market Incumbents: Build certification moats around API 5CT and ISO 11960 accreditation to filter non-compliant competitors from Nigerian and Angolan tender rounds. Deepen backward integration into corrosion-resistant alloy feedstock supply to offset chromium-molybdenum price volatility. Pre-position high-collapse grade inventory in Luanda and Port Harcourt regional hubs to satisfy Sonangol and NNPC pre-commitment mandates before rig contract finalization. For New Entrants and Emerging Players: Tanzania's onshore rift basin exploration represents the most penetrable entry point for cost-optimized carbon steel tubing below API premium grades. Mozambique's Rovuma Basin drill pipe demand synchronized with jackup rig deployment schedules offers a second white-space target. A bundled service model combining tubular supply with ASME Section IX-certified welding crews addresses the CRA fitter shortage constraining East African project timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated mills with regional hub capacity over fragmented trading houses losing share to mill-direct programs. Long-term viability hinges on captive supply of premium threading technology and corrosion-resistant alloy metallurgy capabilities. The signal to watch is rig count trajectories in Nigerian deepwater and Angolan pre-salt blocks as the primary demand inflection indicator for inventory positioning cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Hub Capacity Expansion | Port Harcourt and Luanda stocking facilities satisfy NNPC and Sonangol pre-commitment mandates before rig contract awards. |
| Corrosion-Resistant Alloy Metallurgy Investment | Enhanced chromium-molybdenum formulations render carbon steel obsolete in Nigerian delta sour service environments. |
| Third-Party Inspection Service Certification | Department of Petroleum Resources compliance architecture creates recurring revenue pools for certified testing facilities. |
| Mill-Direct Program Consolidation | Argentine-Brazilian manufacturing bases anchor shipment routes bypassing European transshipment bottlenecks. |
| Proprietary Threading Technology Licensing | Premium connection intellectual property concentrates high-end supply and filters non-compliant suppliers from tender participation. |
Study Parameters
The analysis maps seamless casing, welded tubing, drill pipe, and line pipe sub-sectors, each validated through drilling contractors, national oil company procurement officers, third-party inspection facility managers, and corrosion-resistant alloy metallurgists. Primary interviews with rig fleet operators and EPC contractors in Nigeria, Angola, and Mozambique combined with secondary validation from API certification databases, customs import records, and national oil company tender documentation. Bottom-up rig count modeling and top-down hydrocarbon production forecasts provided triangulation across the analysis window.
Assumptions held fixed include current API 5CT specification standards and existing local content enforcement intensity in Nigeria and Angola, while variables included exploration budget trajectories and scrap steel price volatility. Segmentation dimensions encompassed product type, material grade, end-user category, and application context across deepwater, offshore, and onshore deployment. CAGRs were derived from rig deployment schedules and tubular consumption coefficients per well type. Forecast inputs included jackup and semi-submersible contract awards off Mozambique and Tanzania, plus Nigerian deepwater exploration budget allocations.
Stress conditions across scrap steel price volatility, local content mandate enforcement intensity, and Q-125 yield testing accreditation backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and exploration budget commitment levels. Quarterly review of rig count trajectories, local content enforcement intensity, and API 5CT certification backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Canada LNG Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Shale Shakers Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market