
 Oil and Gas Downhole Cables Market | 2026-2036
Oil and Gas Downhole Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Downhole Cables Market Outlook
Subscription-based cable integrity monitoring is realigning how operators contract for downhole electrical infrastructure. Prysmian Group leverages its submarine cable expertise to anchor deepwater project bids. Nexans Group sustains manufacturing scale across European and North American facilities. W. L. Gore & Associates specializes in fluoropolymer insulation systems for high-temperature well environments.
Oil and gas downhole cables are armored electrical and optical conductors engineered to withstand pressures exceeding 15,000 psi and temperatures above 200°C, transmitting power, control signals, and real-time sensor data between surface equipment and downhole tools. Electro-optical cables command premium positioning due to their dual-function architecture combining copper conductors with fiber optic elements. High-temperature cables represent the fastest-growing technology segment as operators push into hotter reservoir zones. Well monitoring applications generate recurring demand cycles tied to field maturation profiles across offshore and onshore installations.
API standards govern material selection and pressure testing protocols for US offshore deployments, while ISO 13628-5 shapes international subsea production system cable specifications. The EU F-Gas Regulation and REACH chemical restrictions are influencing insulation compound formulations for European-sourced cables. Stakeholders must weigh qualification timelines against reservoir depletion schedules when selecting cable architectures for multi-decade field developments.
Market Dynamics
Deepwater field electrification is compressing procurement cycles as operators bundle cable systems with subsea power distribution architectures, forcing suppliers to requalify products under integrated performance warranties rather than discrete component specifications.
Growth Catalysts
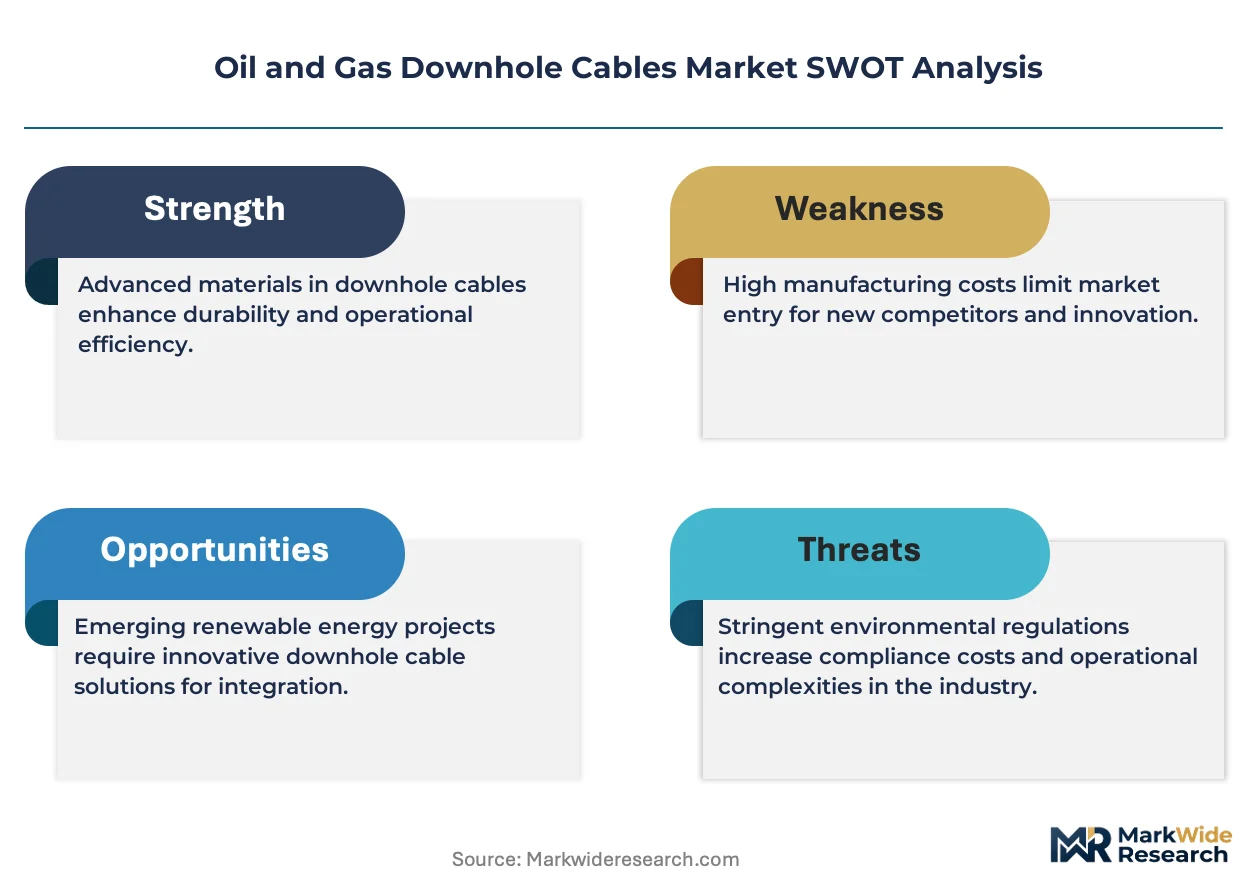
- API 11D1 Certification Mandates:US Gulf Coast operators now require validated pressure-rated assemblies for all new subsea tiebacks, tightening supplier qualification pools and favoring incumbent cable manufacturers with established test records.
- High-Temperature Reservoir Access:Operators pushing into formations exceeding 200°C are replacing standard polymer insulations with fluoropolymer systems, expanding addressable demand for specialty cable architectures.
- Brazil Pre-Salt Development:Petrobras-led deepwater campaigns in the Santos Basin are generating concentrated demand for electro-optical cables combining power transmission with distributed fiber sensing.
Market Restraints
- Copper Price Volatility:Conductor materials constitute 35-45% of finished cable costs, exposing manufacturers to London Metal Exchange fluctuations that compress margin visibility on fixed-price EPC contracts.
- European Fluoropolymer Supply Concentration:F-Gas Regulation restrictions on perfluorinated compound production have consolidated insulation resin supply among three qualified European compounders, creating single-source vulnerability for high-temperature cable lines.
- Subsea Connector Interoperability Limits:Proprietary wet-mate interfaces from leading subsea equipment suppliers lock cable integrators into specific termination architectures, fragmenting procurement flexibility.
Strategic Opportunities
- Middle East HPHT Gas Development:Saudi Aramco and ADNOC sour gas projects targeting 230°C bottom-hole temperatures are opening demand for next-generation insulation systems beyond current API qualification envelopes.
- Integrated Cable-Monitoring Subscriptions:Operators are unbundling integrity verification from capital sales, creating recurring revenue streams through fiber-optic distributed temperature and acoustic monitoring services.
- REACH-Compliant Compound Innovation:ECHA restrictions on legacy flame retardants are incentivizing bio-based insulation formulations that could reset European qualification standards and displace incumbent material suppliers.
Industry Challenges
- Subsea Electrical Engineering Talent Scarcity:The specialized knowledge base for high-pressure electrical system design is concentrating among retiring specialists at major oilfield service firms, constraining supplier technical service capacity.
- ISO 13628-5 Recertification Timelines:Revised material testing protocols are extending qualification cycles to 18-24 months, misaligning supplier R&D calendars with operator field development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Downhole Cables Market |
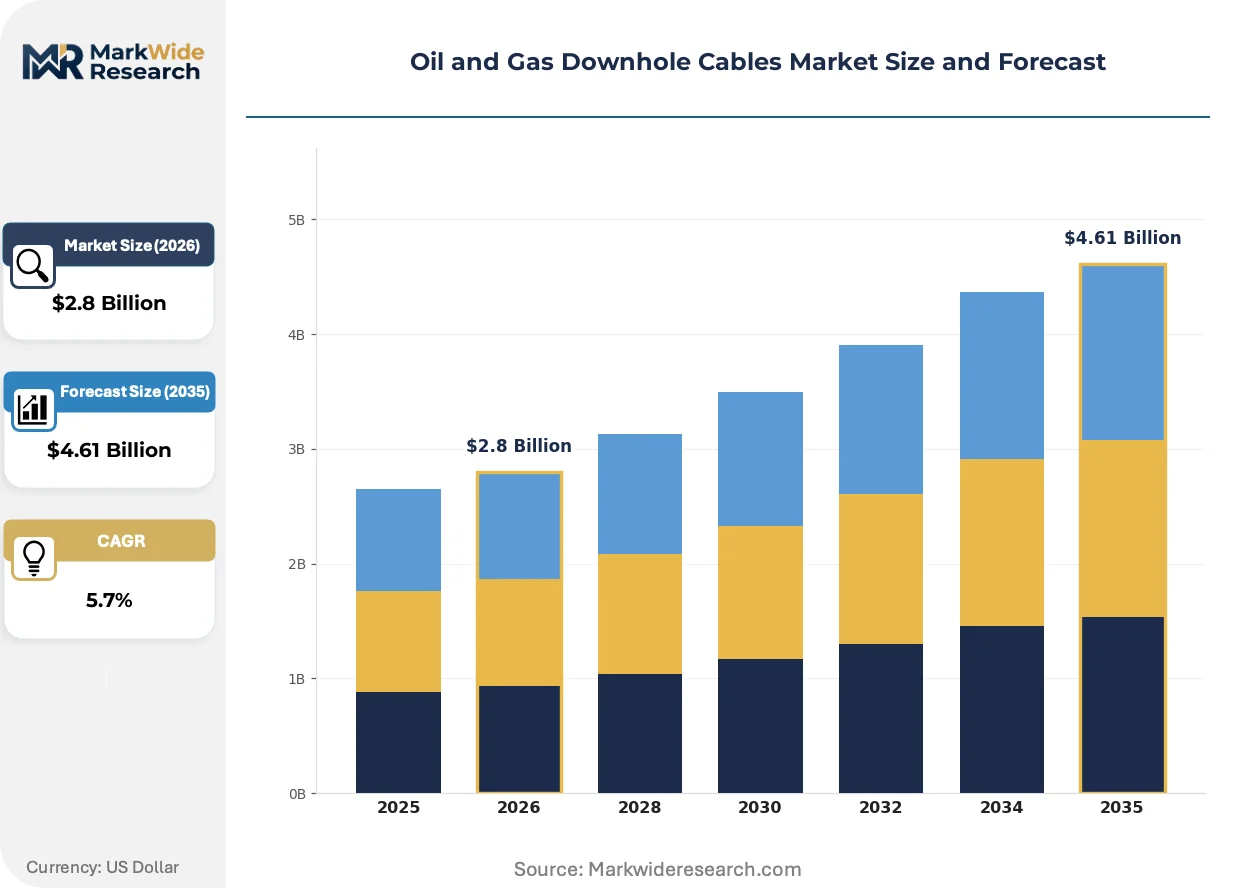
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Optical Cables, Power Cables, Fiber Optic Cables, Communication Cables Technology: Hybrid Cables, Deep Water Technology, Pressure-Resistant Cables, High-Temperature Cables Application: Exploration, Production, Well Monitoring, Data Acquisition Installation Type: Onshore, Offshore, Deep Water, Ultra-Deep Water |
| Companies Covered | Prysmian Group, Belden Inc., Nexans Group, ElandCables, NKT A/S, AFL, Galaxy Wire & Cable, W. L. Gore & Associates, LS Cable & System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Downhole Cables Market Strategic Shifts
Electro-optical cable architectures are displacing discrete power and fiber installations as the default specification for intelligent well completions, compressing installation complexity while expanding real-time reservoir monitoring capabilities.
Fluoropolymer insulation systems engineered for continuous operation above 220°C are electrifying the high-temperature cable segment as operators access deeper, hotter reservoirs in the US Gulf of Mexico and Middle East. Major integrated operators are specifying these materials for all new HPHT completions regardless of current temperature requirements, anticipating future reservoir conditions. This technology is electrifying competitive positioning by separating compound-qualified suppliers from commodity cable manufacturers lacking materials science depth.
The EU F-Gas Regulation is forcing reformulation of perfluorinated insulation compounds used in subsea cable jackets, accelerating development of hydrofluoroolefin and bio-based alternatives among European compounders. Manufacturers serving North Sea and Mediterranean projects must now dual-qualify legacy and next-generation materials, extending product development cycles. Subsea production system contractors are absorbing these compliance costs through modified EPC contract terms, passing regulatory risk to cable integrators.
Integrated service contracts are compressing the traditional equipment-procurement boundary as operators bundle cable supply with installation, commissioning, and lifecycle monitoring under single-source agreements. This consolidation is displacing discrete component vendors who lack subsea construction capabilities or fiber-sensing analytics platforms. The US Gulf Coast deepwater basin exhibits the most advanced contracting evolution, with supermajors now mandating integrated cable-performance warranties spanning 25-year field lives.
Oil and Gas Downhole Cables Market Segmentation
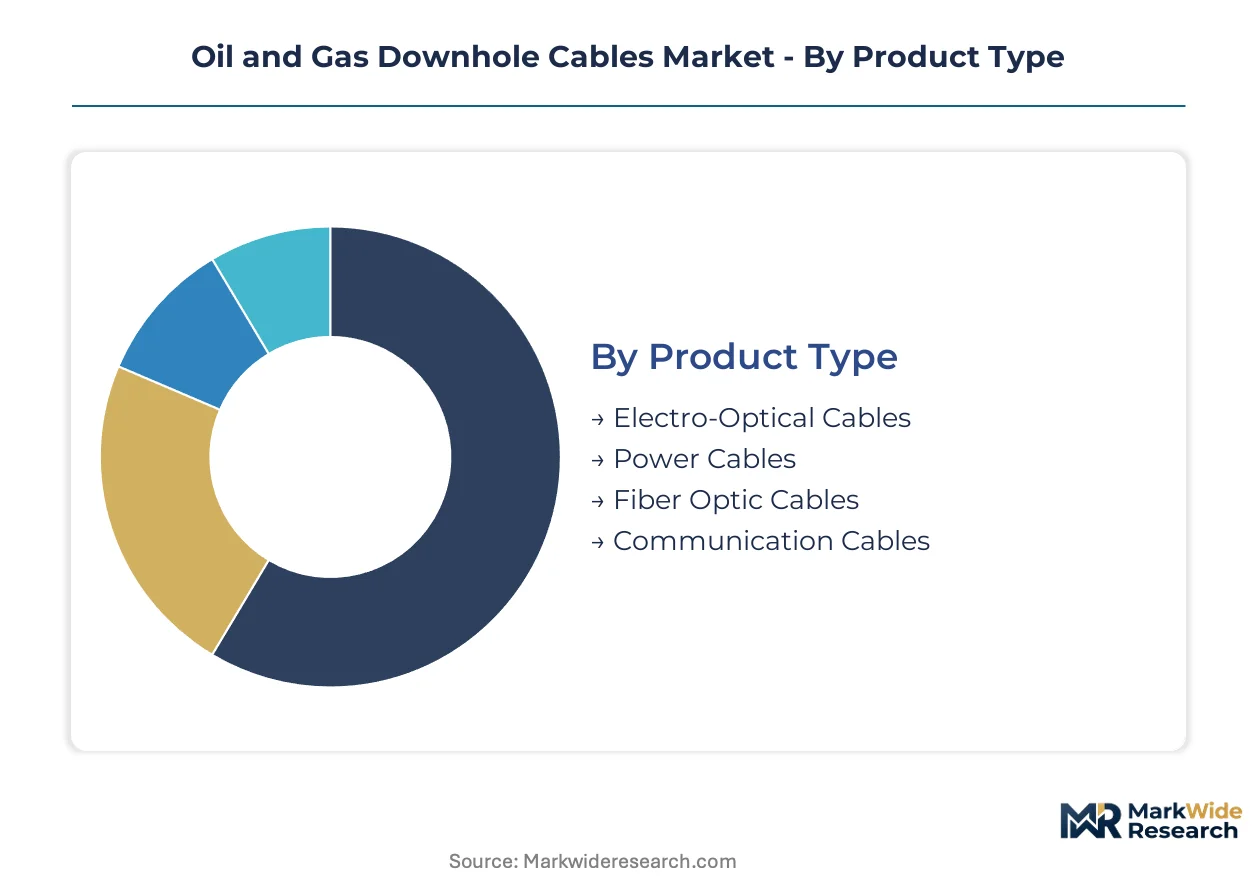
Downhole cable procurement decisions hinge on reservoir depth, pressure ratings, and telemetry requirements. Operators segment purchases by well architecture complexity, with deepwater electrification bundling multiple cable technologies into unified subsea distribution systems.
Product Type:
Capital intensity varies sharply across conductor architectures, with electro-optical systems demanding premium qualification investments and fiber-only deployments requiring minimal pressure-testing overhead.
- Electro-Optical Cables:Hybrid copper-fiber constructions transmit power and real-time sensor data through single armored assemblies. Santos Basin operators specify these for intelligent completions requiring distributed temperature sensing alongside electric submersible pump feeds.
- Power Cables:Multi-conductor copper configurations deliver electricity to downhole artificial lift systems and subsea distribution hardware. US Gulf Coast deepwater projects absorb the majority of high-amperage specifications as electrification replaces hydraulic well intervention.
- Fiber Optic Cables:Pure silica waveguides enable distributed acoustic and temperature monitoring without electrical conductivity. Middle East gas developments favor these for permanent reservoir surveillance in sour service conditions.
- Communication Cables:Low-voltage twisted pairs transmit control signals between surface automation systems and downhole valves. Onshore shale operators in the Permian Basin deploy these for rod pump optimization networks.
Power cables absorb the bulk of installed capacity; electro-optical cables are expanding most quickly.
Technology:
Qualification timelines separate incumbent suppliers from new entrants, with pressure-testing protocols creating 18-month barriers to market participation.
- High-Temperature Cables:Fluoropolymer-insulated conductors withstand continuous operation above 220°C in HPHT reservoirs. Saudi Aramco sour gas projects in the Empty Quarter are qualifying next-generation formulations beyond current API envelopes.
- Deep Water Technology:Steel-armored assemblies rated for 3,000+ meter water depths incorporate synthetic fiber strength members to reduce hanging weight. Brazil pre-salt developments anchor demand as Petrobras extends field tiebacks farther from host platforms.
- Hybrid Cables:Modular architectures combine power, fiber, and hydraulic lines in unified umbilical cross-sections. North Sea operators favor these for subsea boosting stations requiring multiple utility feeds.
- Pressure-Resistant Cables:Elastomeric seals and metallic barriers maintain dielectric integrity above 15,000 psi. Gulf of Mexico ultra-deepwater wells specify these for bottom-hole pressure gauges and permanent monitoring systems.
Deep water technology commands the largest qualification expenditure; high-temperature cables are gaining share fastest.
Application:
Revenue cyclicality differs by field life stage, with exploration demand spiking during drilling campaigns and production applications generating steady replacement schedules.
- Well Monitoring:Permanent downhole gauge installations track pressure, temperature, and flow characteristics across field life. Mature North Sea assets drive recurring demand as operators extend plateau production through real-time reservoir management.
- Production:Artificial lift power supply and subsea distribution networks form the core installed base. US shale operators deploy these at scale across multi-well pad developments in the Eagle Ford and Bakken formations.
- Exploration:Logging-while-drilling and measurement-while-drilling cables withstand temporary deployment in appraisal wells. Offshore frontier basins including Suriname and Guyana generate concentrated demand during drilling ramp-ups.
- Data Acquisition:Seismic and microseismic monitoring cables deploy temporarily for reservoir characterization. Permian Basin operators use these for frac hit detection and parent-child well interference studies.
Production applications carry the heaviest capital deployment; well monitoring is climbing the fastest.
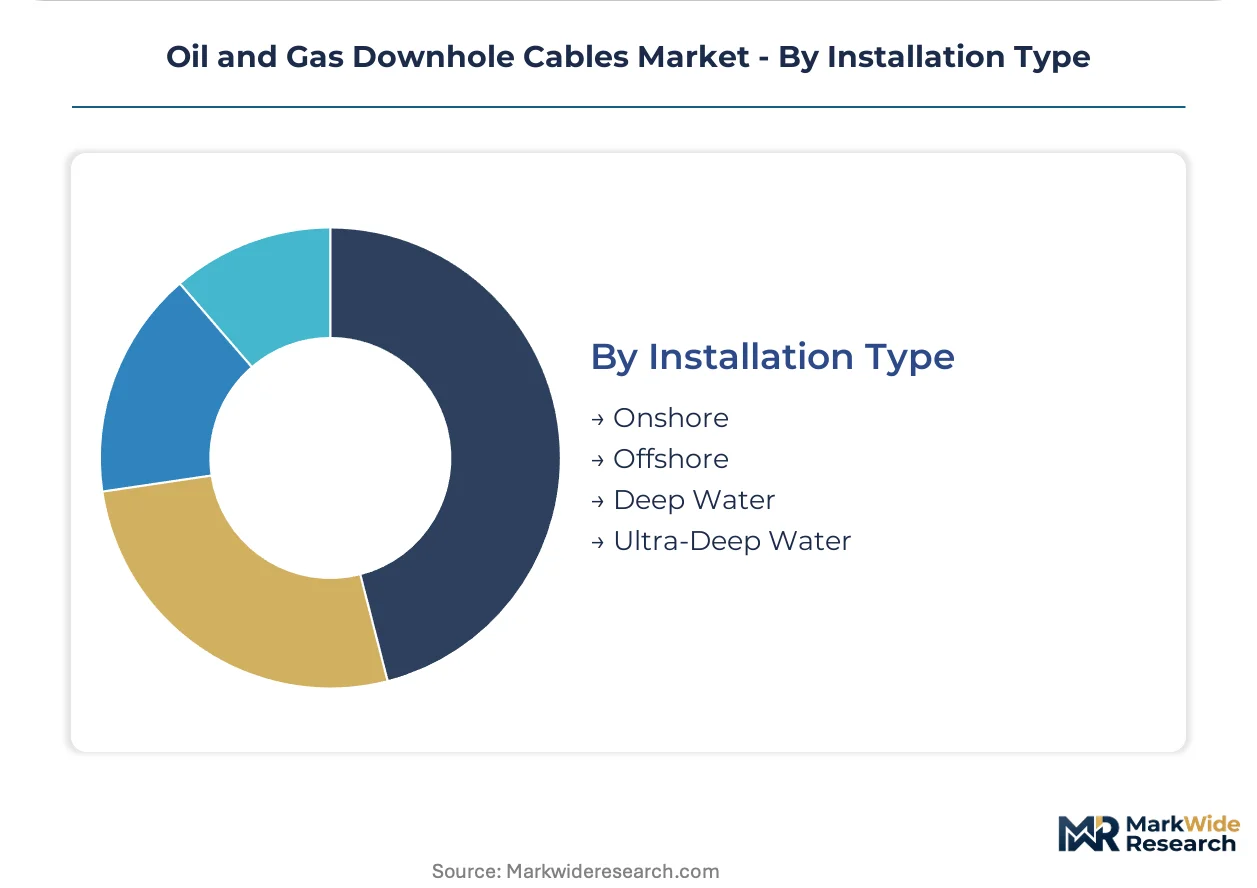
Installation Type:
Water depth determines armor complexity and installation vessel requirements, with ultra-deepwater specifications multiplying per-meter costs relative to onshore equivalents.
- Deep Water:Installations between 400 and 1,500 meters require dynamic positioning vessels and steel tube armoring. Angola Block 15 developments exemplify typical West African demand for this water depth band.
- Ultra-Deep Water:Beyond 1,500 meters, buoyancy-controlled installations and synthetic rope armoring become necessary. US Gulf of Mexico Lower Tertiary trends anchor this segment as Shell and Chevron advance Paleogene discoveries.
- Offshore:Shelf and platform-tied installations up to 400 meters utilize conventional steel wire armoring. Southeast Asian developments in Malaysia and Indonesia concentrate demand for jackup-accessible specifications.
- Onshore:Land-based deployments face minimal pressure requirements but demand rodent-resistant armoring and extended temperature cycling. US Permian and DJ Basin horizontal wells specify these for electric frac monitoring and artificial lift.
Offshore installations retain the largest footprint; ultra-deep water is expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Europe and North America while consumption concentrates in offshore basins spanning the US Gulf Coast, Brazil, and the Middle East. This geographic split creates qualification bottlenecks as cable systems must ship to remote drilling provinces. Procurement timelines stretch where local content rules mandate in-region sourcing.
United States
Deepwater electrification in the Gulf of Mexico drives demand for pressure-rated assemblies exceeding 15,000 psi. FERC oversees offshore power distribution standards affecting subsea cable specifications. Houston anchors the domestic supply chain, with fabricators clustered along the Ship Channel serving Shell and Chevron Lower Tertiary developments.
Brazil
Petrobras pre-salt campaigns in the Santos Basin generate concentrated orders for electro-optical cables combining power feeds with distributed sensing. ANP regulates subsea system certification timelines. The Niterói industrial corridor hosts cable termination facilities supporting 3,000-meter water depth installations.
Saudi Arabia
HPHT sour gas projects targeting 230°C bottom-hole temperatures open demand for next-generation fluoropolymer insulation. SFDA oversees chemical compliance for subsea production chemicals affecting cable jacket materials. The Eastern Province oilfield cluster around Dhahran drives qualification programs for extended-reach gas wells.
Norway
North Sea field electrification mandates subsea power distribution systems bundling cables with renewable energy tie-ins. The Norwegian Petroleum Directorate enforces ISO 13628-5 compliance for all new subsea installations. Stavanger hosts engineering centers coordinating cable specification for Equinor and Aker BP developments.
China
Offshore expansion in the South China Sea creates demand for deepwater armored assemblies. MIIT governs domestic cable manufacturing standards through GB certification protocols. The Bohai Bay cluster near Tianjin concentrates fabrication capacity serving CNOOC shallow-water platform electrification programs.
Oil and Gas Downhole Cables Market Competitive Environment
Top-tier vendors anchor integrated subsea project contracting, while mid-scale specialists compete on material qualification speed. The vendor base stratifies across three tiers: full-service subsea contractors bundling cable supply with installation, compound-qualified cable manufacturers with API test records, and regional fabricators serving onshore replacement markets. Dominant competitive moves include backward integration into fluoropolymer compounding and strategic partnerships with subsea equipment OEMs to secure wet-mate connector access.
Within the materials-specialist tier, W. L. Gore & Associates exemplifies fluoropolymer insulation expertise, while Prysmian Group and Nexans Group occupy positions spanning submarine cable manufacturing scale and deepwater project execution capability. These three anchors represent distinct archetypes: compound science depth, integrated energy infrastructure scale, and European-North American manufacturing footprint respectively.
| Leading Market Players |
|---|
| Prysmian Group |
| Belden Inc. |
| Nexans Group |
| ElandCables |
| NKT A/S |
| AFL |
| Galaxy Wire & Cable |
| W. L. Gore & Associates |
| LS Cable & System |
| Others |
Value Chain & Pricing Dynamics
API 11D1 certification tiers split the market into qualified incumbents commanding project premiums and commodity fabricators competing on copper weight pricing, with this bifurcation concentrating procurement power among Gulf Coast operators who bundle cable supply with integrated performance warranties. The divergence feeds back into supply chain design: certified manufacturers maintain captive fluoropolymer compounding relationships while uncertified competitors source standard elastomers through spot resin markets.
Pricing Analysis
Margin tightening in high-temperature cable tiers reflects F-Gas Regulation compliance costs and extended ISO 13628-5 recertification timelines. Project-based long-term contracting dominates, with price differentiation anchored in API certification grade and fluoropolymer insulation compound pedigree. Cost compression accelerates in power cable commoditized segments as EPC contractors consolidate procurement volumes. Onshore shale operators exhibit highest price sensitivity; deepwater supermajors prioritize 25-year performance warranties over unit cost.
Supply Chain Analysis
Brazilian local-content mandates under ANP regulations are reshaping sourcing patterns, forcing international cable integrators to establish Niterói termination facilities. Manufacturing concentrates in Italy, France, and the United States, drawing fluoropolymer resins from three qualified European compounders. Single-source vulnerability pervades high-temperature insulation supply. Distribution runs through subsea equipment OEMs who specify proprietary wet-mate interfaces, fragmenting downstream channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 11D1 certification functions as a cost-of-compliance moat, with 18-24 month qualification timelines creating barrier-to-entry protection for incumbent manufacturers holding validated pressure-test records.
For Market Incumbents: To counter copper price volatility eroding fixed-price EPC margins, deepen backward integration into fluoropolymer compounding and secure long-term resin offtake agreements with European suppliers. Anchor capacity expansion in the US Gulf Coast corridor to capture bundled electrification contracts from Shell and Chevron Lower Tertiary developments.
For New Entrants and Emerging Players: Capture Middle East HPHT gas project demand for 230°C insulation systems beyond current API qualification envelopes, where Saudi Aramco and ADNOC sour gas campaigns face limited qualified supplier pools. Enter through joint qualification programs with established subsea equipment OEMs lacking in-house cable manufacturing.
For Investors and Strategic Acquirers: Re-rating potential sits with compound-qualified cable manufacturers given integrated service contract consolidation favoring full-lifecycle providers. Long-term viability hinges on fiber-sensing analytics platform ownership. Watch Petrobras pre-salt electrification spend as inflection indicator for electro-optical cable demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Captive resin supply secures margin protection against F-Gas Regulation supply concentration. |
| Integrated Service Contract Positioning | Bundled cable-installation-monitoring offerings displace discrete component vendors in Gulf Coast deepwater. |
| API 11D1 Certification Investment | Validated pressure-test records unlock Petrobras and US supermajor procurement pools. |
| Fiber-Optic Distributed Sensing Platform Development | Recurring monitoring revenue streams transform capital equipment sales into subscription economics. |
| Middle East HPHT Qualification Programs | 230°C insulation development opens Saudi Aramco and ADNOC sour gas project demand. |
Study Parameters
Document review covered API specification databases, ISO 13628-5 test protocols, and ANP regulatory filings, complemented by interviews with subsea project engineers at major integrated operators, procurement leads at drilling contractors, fluoropolymer compound technical directors, and subsea equipment OEM product managers. Secondary validation drew from FERC offshore power distribution standards, ECHA REACH restriction updates, and Petrobras development plan disclosures. Bottom-up cable demand modeling triangulated against top-down field development capital expenditure tracking.
Historical qualification timeline analysis cross-referenced against expert panel input on recertification cycle extensions. The analytical framework segmented by product architecture, technology tier, application life cycle stage, and water depth installation band across the projection horizon. CAGRs derived from regression against offshore drilling rig deployment forecasts and subsea tree order backlogs. Industry-specific inputs incorporated fluoropolymer resin supply constraints and local-content rule evolution in Brazil and Saudi Arabia.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility, F-Gas Regulation amendment timing, and subsea electrical engineering talent scarcity constraining supplier technical service capacity. Forecasts reflect documented assumptions regarding reservoir depletion schedules and electrification substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
LNG Bunkering Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Smart Well Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Natural Gas Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market