
 Dosing Bottles Market | 2026-2036
Dosing Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Dosing Bottles Market Analysis
Pharmaceutical-grade compliance tiers is reorganizing competitive dynamics across the dosing bottles landscape. Gerresheimer leverages integrated glass-forming and pharmaceutical coating capabilities to sustain leadership in high-barrier amber dosing bottles for light-sensitive formulations. Berry Global anchors North American supply through multi-layer plastic extrusion platforms serving generic drug distributors. Nolato competes on precision molding tolerances for dropper-tip assemblies used in ophthalmic and pediatric applications.
Dosing bottles are calibrated dispensing containers engineered to deliver precise liquid volumes, typically constructed from borosilicate glass, amber-tinted soda-lime glass, or multilayer polypropylene with extractables-tested elastomeric closures, and manufactured under ISO 15378 pharmaceutical packaging standards to ensure dosing accuracy within ±5% variance for oral, ophthalmic, and nasal drug administration. Plastic dosing bottles lead volume due to cost scalability and breakage resistance in home healthcare channels, while glass variants command margin pools in biologic and high-potency drug segments where USP Type I inertness is mandatory. Amber dosing bottles represent the fastest-growing product tier as photostable packaging demand rises for vitamin D, monoclonal antibody, and cannabinoid formulations requiring UV-blocking below 450 nanometers.
FDA 21 CFR Part 211, EU MDR, and ISO 15378 collectively shape material qualification, closure integrity testing, and batch-level traceability requirements that determine market access for dosing bottle suppliers. EPA and ECHA REACH frameworks further constrain plasticizer and additive chemistries in pediatric-facing formats, pushing converters toward validated extractables profiles. Stakeholders must monitor evolving pharmacopeial monographs and state-level pharmaceutical waste regulations to anticipate specification shifts before they disrupt qualification timelines.
Market Dynamics
Pharmaceutical packaging compliance tiers are compressing supplier margins while concentrating volume among integrated manufacturers capable of simultaneous glass-forming, coating, and closure assembly under single-site ISO 15378 certification. This structural force favors capital-heavy players with captive pharmaceutical-grade resin and borosilicate feedstock arrangements.
Growth Catalysts
- EU MDR child-resistant mandates:Tightened closure integrity testing requirements for pediatric liquid formulations are disqualifying single-source converters without in-house torque validation labs.
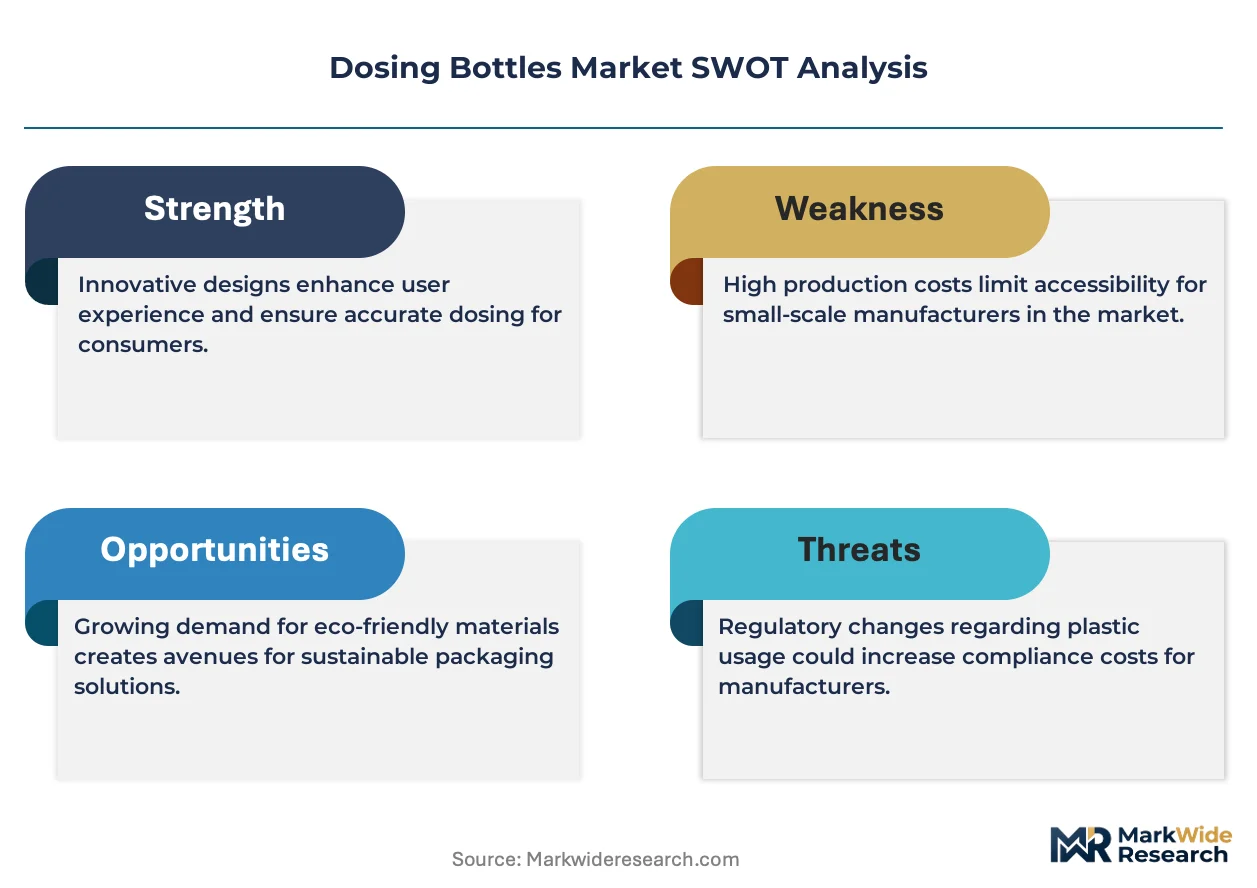
- Home healthcare infusion:Self-administered biologic therapies requiring precise micro-dosing are pulling amber glass demand into chronic disease management channels previously dominated by hospital pharmacy.
- Photostable packaging chemistry:UV-blocking below 450 nanometers is becoming mandatory for vitamin D and cannabinoid stability, accelerating specification upgrades across compounding pharmacies.
Market Restraints
- Borosilicate glass supply concentration:German and Italian furnace operators control pharmaceutical-grade tubing output, exposing buyers to energy cost pass-through and batch allocation limits.
- Extractables validation burden:ECHA REACH constraints on plasticizer chemistries force pediatric-facing formats through 18-24 month USP <661.1> migration studies before commercial qualification.
- Pre-filled syringe substitution:Single-use injectable formats are capturing share in ophthalmic and emergency medicine segments where dosing bottles previously dominated.
Strategic Opportunities
- Saudi Arabia localization:SFDA pharmaceutical packaging localization incentives are creating first-mover advantages for converters establishing Jeddah-based ISO 15378 facilities ahead of 2030 import substitution targets.
- Connected dosing compliance:Near-field communication tags embedded in closure assemblies enable dose-tracking for clinical trial sponsors and value-based contract pharmacy networks.
- Dual-chamber mixing bottles:Separated liquid-powder compartments for reconstitutable biologics address stability challenges in temperature-compromised distribution corridors.
Industry Challenges
- Pharmaceutical packaging engineering talent:Shortages of specialists trained simultaneously in extractables toxicology, glass forming mechanics, and automated vision inspection are extending new product introduction timelines.
- Multi-site qualification synchronization:Brand owners requiring identical dosing variance performance across geographically distributed molding operations face batch release complexity under FDA 21 CFR Part 211.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dosing Bottles Market |
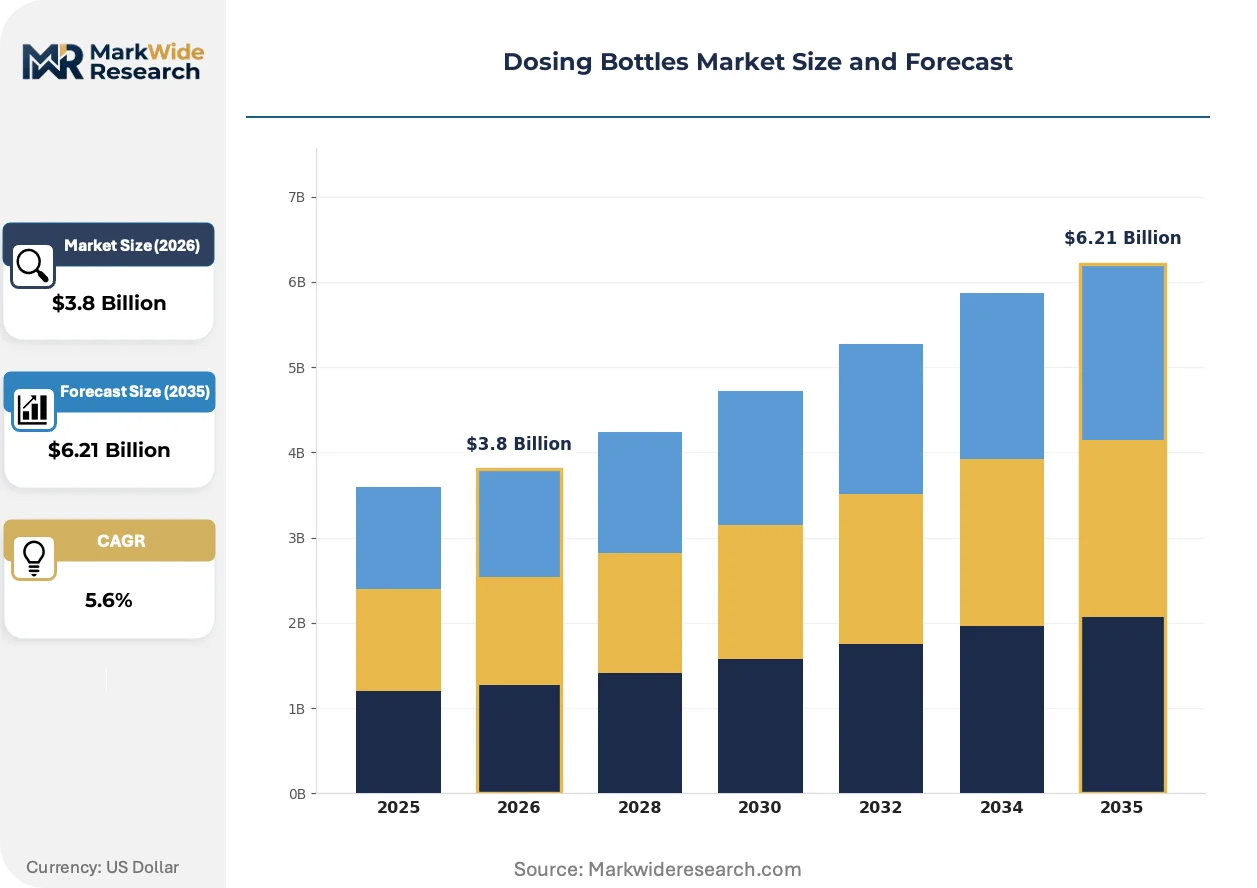
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Amber, Dropper Capacity: 30ml, 60ml, 100ml, 200ml Closure Type: Screw Cap, Dropper Cap, Pump Cap, Disc Top End User: Pharmacies, Hospitals, Laboratories, Home Healthcare |
| Companies Covered | Gerresheimer, Berry Global, Nolato, AptarGroup, Bormioli Pharma, SGD Pharma, Amcor, Silgan, West Pharmaceutical Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dosing Bottles Market Emerging Trajectories
Precision dosing mechanisms are converging with connected health infrastructure, reshaping how pharmaceutical packaging demonstrates value beyond containment. These shifts favor suppliers capable of integrating mechanical calibration with digital traceability.
Micro-piston pump inserts molded from cyclic olefin polymer are miniaturizing unit-dose accuracy from milliliter to microliter precision for ophthalmic steroid suspensions. Compounding pharmacies and specialty generics distributors are adopting these formats to reduce overfill waste and extend beyond-use dating. The technology is miniaturizing dosing bottle geometries while compressing fill-finish line changeover requirements.
EPA and ECHA REACH frameworks are tightening permissible extractables profiles for pediatric and geriatric liquid medications, forcing converters to validate alternative elastomer formulations. Suppliers without in-house toxicology screening capabilities face 12-18 month specification delays. Amber glass and multilayer polypropylene formats with pre-qualified closure systems are capturing preference among risk-averse brand owners.
Hospital pharmacy procurement groups are consolidating annual dosing bottle contracts around suppliers offering integrated serialization and aggregation services. Direct purchasing from generic drug distributors is displacing traditional wholesale channel relationships in North American and Western European markets. Germany's hospital procurement alliances are most advanced in demanding real-time inventory visibility as a contract precondition.
Dosing Bottles Market Segmentation
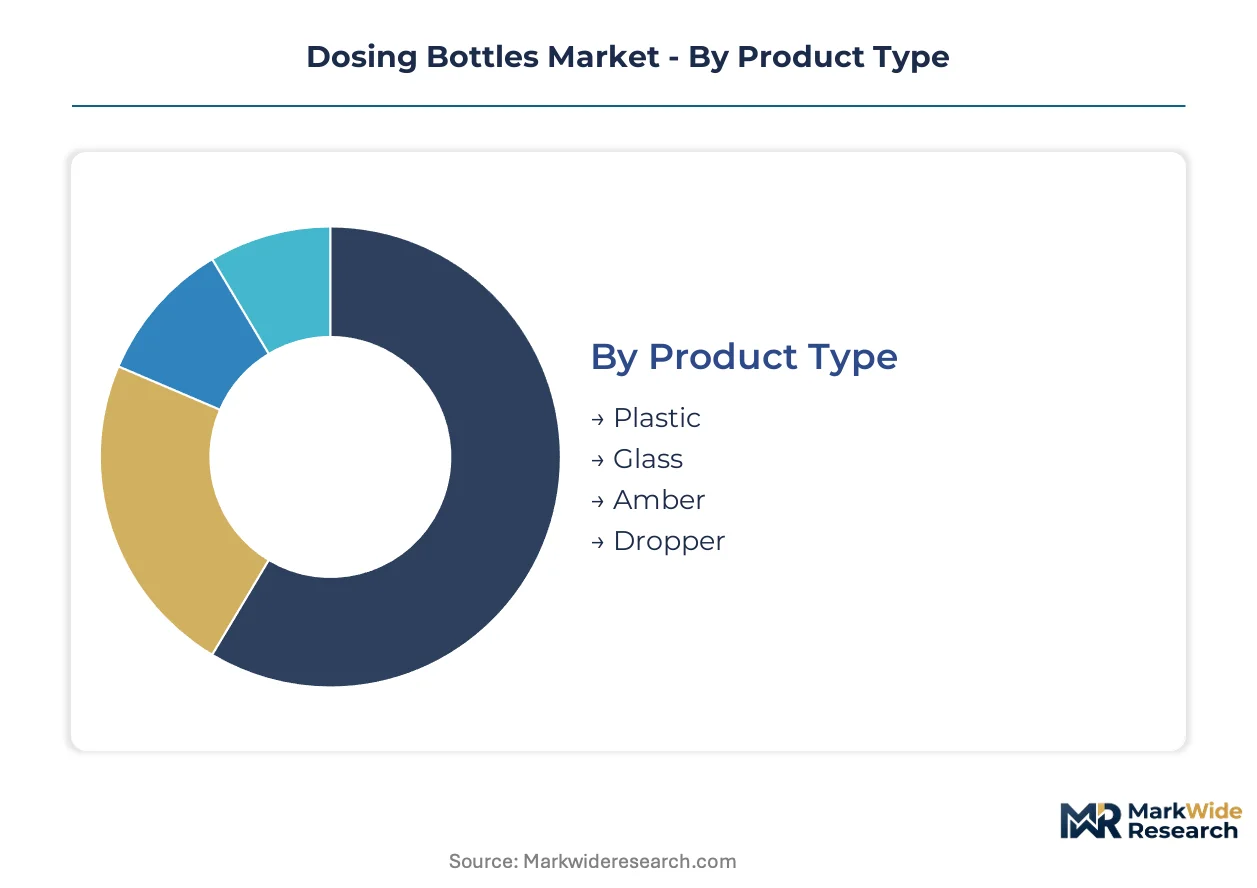
Dosing bottle specifications cascade through pharmaceutical supply chains with distinct channel requirements. Product material, capacity, and closure configurations align to end-user compliance tiers and distribution economics.
Product Type:
Channel economics favor plastic formats in high-volume generic distribution, while glass variants anchor regulated biologic channels requiring USP Type I certification.
- Plastic:Polypropylene and multilayer extrusion formats dominate home healthcare and retail pharmacy channels where breakage resistance and cost scalability matter. Generic drug distributors in North America and Western Europe consolidate procurement around validated extractables profiles from Berry Global and Nolato supply bases.
- Glass:Borosilicate and soda-lime constructions serve hospital pharmacy and compounding operations demanding thermal stability and inert drug contact surfaces. German furnace operators anchor supply through Gerresheimer and Bormioli Pharma, with batch allocation constraints tightening under energy cost pass-through.
- Amber:UV-blocking below 450 nanometers protects light-sensitive formulations including vitamin D, monoclonal antibodies, and cannabinoid suspensions.
- Dropper:Calibrated tip assemblies deliver microliter precision for ophthalmic and pediatric liquid medications.
By volume, Plastic leads. By growth pace, Amber is ahead.
Capacity:
Unit-dose calibration requirements vary by therapy duration and reconstitution protocols, with smaller formats concentrating in clinical trial and pediatric segments.
- 30ml:Single-course antibiotic and ophthalmic steroid suspensions. Precision-molded micro-piston inserts from cyclic olefin polymer are miniaturizing geometries for ophthalmic applications.
- 60ml:Standard oral liquid generics for 7-14 day regimens. Hospital pharmacy procurement groups in Germany consolidate annual contracts around this format with integrated serialization requirements.
- 100ml:Chronic disease management therapies including biologic reconstitutions. Self-administration trends in home healthcare are pulling amber glass demand into this capacity tier.
- 200ml:Family-size vitamin and supplement formats in retail pharmacy channels.
By shipment frequency, 60ml dominates. By specification upgrade activity, 100ml shows the steepest expansion trajectory.
Closure Type:
Child-resistant mandates from FDA 21 CFR Part 211 and EU MDR are disqualifying converters without in-house torque validation capabilities.
- Screw Cap:Standard threaded closures for oral liquids with tamper-evident bands. Generic distributors favor pre-qualified screw cap systems to compress 18-24 month USP migration study timelines.
- Dropper Cap:Integrated bulb and tip assemblies for precise volume control. Nolato competes on precision molding tolerances for ophthalmic and pediatric dropper-tip configurations.
- Pump Cap:Metered-dose actuation for viscous suspensions and topical formulations.
- Disc Top:Flip-lid dispensing for single-hand operation in geriatric and arthritis patient populations.
By regulatory qualification burden, Dropper Cap commands premium positioning. By volume scale, Screw Cap maintains the largest installed base.
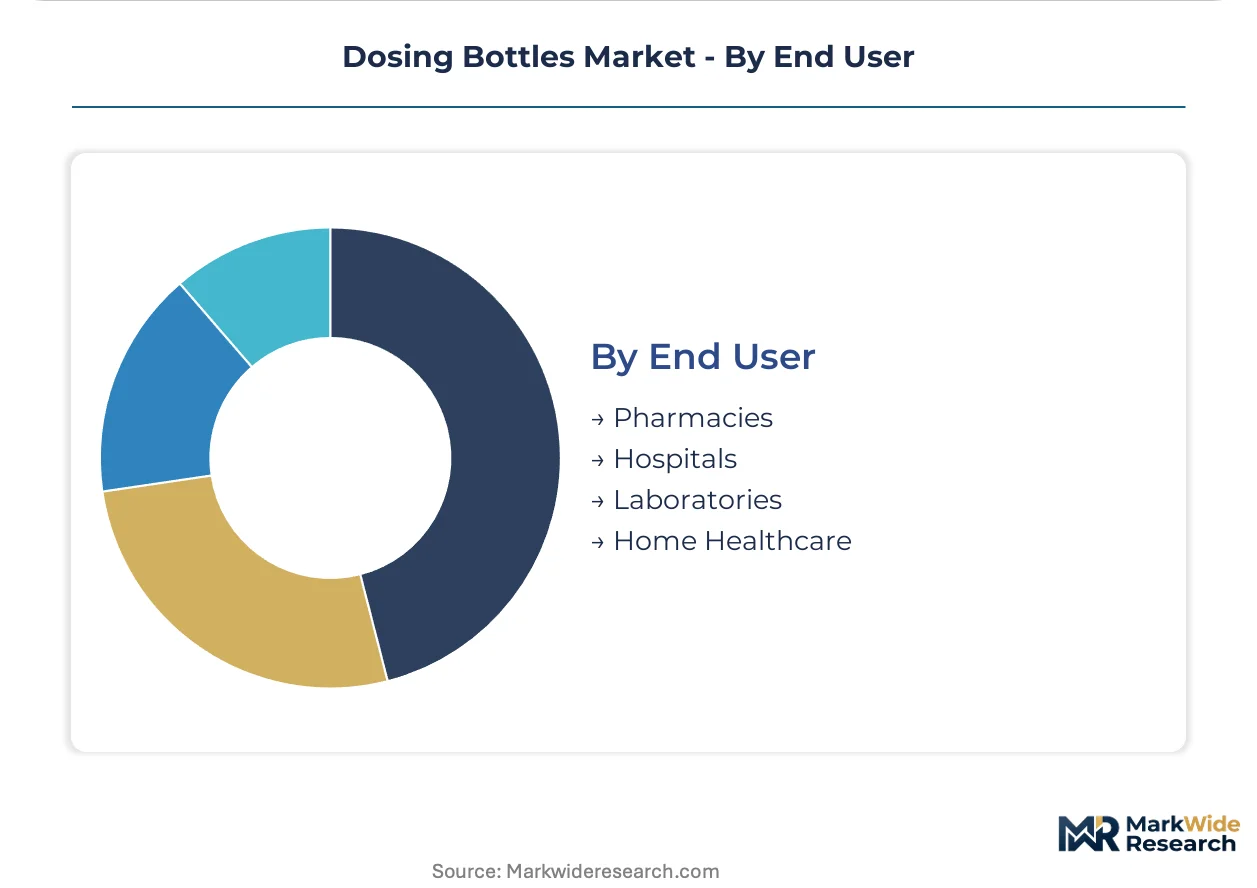
End User:
Procurement centralization varies sharply across end-user categories, with hospital alliances demanding real-time inventory visibility as a contract precondition.
- Pharmacies:Retail and compounding operations specifying amber glass for photostable requirements and multilayer plastic for cost-sensitive generics. Direct purchasing from distributors is displacing wholesale channel relationships in North American markets.
- Hospitals:Pharmacy procurement groups consolidating contracts around integrated serialization and aggregation services. Germany's hospital alliances are most advanced in mandating dose-tracking infrastructure.
- Laboratories:Clinical trial sponsors requiring connected dosing compliance through near-field communication tags embedded in closure assemblies.
- Home Healthcare:Self-administered biologic therapies pulling precision micro-dosing formats into chronic disease management channels.
By contract value concentration, Hospitals lead. By format innovation pull, Home Healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in pharmaceutical-grade packaging tilt toward net exporters in Western Europe and North America, while Asia-Pacific markets absorb inbound volumes to serve expanding domestic generic drug production. Currency-adjusted logistics costs and regulatory proximity shape cross-border sourcing decisions more than raw material availability.
Germany
Gerresheimer and Bormioli Pharma anchor specialized glass dosing bottle production in the country's western industrial corridor. EU MDR compliance requirements tighten child-resistant closure mandates, disqualifying converters without in-house torque validation capabilities. The Ruhr Valley and Bavaria host concentrated pharmaceutical packaging engineering talent pools.
United States
Home healthcare infusion trends pull amber glass demand into chronic disease management channels previously dominated by hospital pharmacy. FDA 21 CFR Part 211 shapes material qualification and batch-level traceability requirements that determine market access for suppliers. Berry Global anchors North American supply through multi-layer plastic extrusion platforms.
China
Domestic generic drug manufacturers scale unit-dose liquid medication output, driving import substitution in pharmaceutical-grade plastic formats. NMPA standards converge toward ISO 15378 pharmaceutical packaging benchmarks. The Yangtze River Delta clusters precision molding operations serving both domestic and export contract manufacturing organizations.
India
CDSCO regulatory alignment with USP and EP standards accelerates qualification timelines for export-oriented pharmaceutical packaging converters. Compounding pharmacies and specialty generics distributors adopt micro-piston pump inserts for ophthalmic applications. Gujarat and Maharashtra host concentrated plastic dosing bottle fabrication for regulated drug delivery.
Saudi Arabia
SFDA pharmaceutical packaging localization incentives create first-mover advantages for converters establishing Jeddah-based ISO 15378 facilities. Import substitution targets for 2030 reshape procurement patterns for hospital pharmacy groups. The Western Region concentrates demand from expanding domestic biologics manufacturing capacity.
Dosing Bottles Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory qualification dimensions. The supplier base compresses toward integrated manufacturers capable of simultaneous glass-forming, coating, and closure assembly under single-site certification. Three archetypes dominate: furnace-backed glass specialists, multi-layer extrusion platforms, and precision molding contractors for dropper-tip assemblies. Competitive moves center on captive pharmaceutical-grade resin arrangements and backward integration into borosilicate feedstock supply.
Among Germany-based fabricators, Gerresheimer AG and Bormioli Pharma S.p.A. occupy positions exemplifying furnace-integrated glass-forming capabilities. Berry Global, Inc. represents the scale-driven plastic extrusion archetype across North American distribution channels. Nolato AB sits within the precision molding tier for calibrated dispensing mechanisms. These three anchors illustrate how geographic proximity to pharmaceutical manufacturing clusters and regulatory expertise shape sustainable positioning.
| Leading Market Players |
|---|
| Gerresheimer |
| Berry Global |
| Nolato |
| AptarGroup |
| Bormioli Pharma |
| SGD Pharma |
| Amcor |
| Silgan |
| West Pharmaceutical Services |
| Others |
Supply Flow & Price Mechanics
Pre-filled syringe substitution for ophthalmic and emergency medicine applications simultaneously redistributes manufacturing gravity toward injectable assembly sites and compresses pricing power for traditional dosing bottle converters in those segments. This displacement dynamic forces amber glass and multilayer plastic suppliers to defend position through certification-tier differentiation rather than volume scale.
Pricing Analysis
Hospital pharmacy procurement groups anchor contract-based long-term offtake structures across the dosing bottles landscape. Price differentiation hinges on ISO 15378 certification tier and captive borosilicate feedstock arrangements, with furnace-integrated German suppliers commanding premium positioning over resin-dependent converters. Cost compression in pediatric-facing plastic formats is intensifying because ECHA REACH extractables validation timelines extend 18-24 months. Generic drug distributors exhibit highest price sensitivity, while biologic manufacturers prioritize USP Type I inertness over unit cost.
Supply Chain Analysis
Inventory buffers for pharmaceutical-grade borosilicate tubing have compressed to eight-week cycles under German and Italian furnace allocation constraints. Raw material supply draws from soda-lime glass feedstock, medical-grade polypropylene resin, and cyclic olefin polymer for micro-piston inserts. Single-source vulnerability concentrates in Ruhr Valley and Bavaria glass-forming operations exposed to energy cost pass-through. Distribution runs through hospital pharmacy procurement alliances in Germany and direct purchasing channels displacing wholesale relationships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dosing bottles market sits at a post-pandemic normalization phase where home healthcare infusion trends and biologic self-administration create cyclical recovery tailwinds for precision packaging formats.
For Market Incumbents: Consolidate torque validation capabilities and in-house toxicology screening to defend against EU MDR disqualification of single-source converters without integrated closure testing labs. Deepen backward integration into borosilicate feedstock through captive furnace arrangements or long-term allocation contracts with German and Italian operators. Prioritize ISO 15378 single-site certification synchronization across geographically distributed molding operations to compress batch release complexity under FDA 21 CFR Part 211. For New Entrants and Emerging Players: Lead with connected dosing compliance formats embedding near-field communication tags for clinical trial sponsors and value-based contract pharmacy networks. Target Saudi Arabia's Western Region hospital pharmacy groups ahead of 2030 import substitution deadlines, establishing Jeddah-based ISO 15378 facilities under SFDA localization incentives. Position through dual-chamber mixing bottle architectures addressing stability challenges in temperature-compromised distribution corridors for reconstitutable biologics. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors furnace-backed glass specialists with integrated coating and closure assembly capabilities. Long-term viability over a five-to-ten-year window rests on regulatory qualification moats rather than manufacturing scale alone. Acquisition focus should center on precision molding contractors for dropper-tip assemblies serving ophthalmic and pediatric applications. Watch for inflection in Saudi SFDA enforcement timelines and German hospital alliance real-time inventory visibility mandates as demand pull-through signals.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Single-Site Certification | Eliminates multi-site batch release complexity under FDA 21 CFR Part 211 traceability requirements. |
| Captive Borosilicate Feedstock Arrangement | Insulates margin position from German furnace energy cost pass-through and allocation limits. |
| Connected Dosing Compliance Integration | Enables dose-tracking infrastructure for clinical trial sponsors and value-based pharmacy contracts. |
| Saudi Arabia Localization Facility | Captures first-mover advantage under SFDA 2030 import substitution incentives for hospital procurement. |
| Dual-Chamber Mixing Bottle Development | Addresses biologic stability requirements in temperature-compromised distribution corridors. |
Methodological Framework
The analysis maps glass-forming, plastic extrusion, and precision molding sub-sectors, each validated through procurement directors at hospital pharmacy alliances, regulatory affairs leads at pharmaceutical packaging converters, and supply chain managers at generic drug distributors. Primary interview intelligence triangulates against FDA 21 CFR Part 211 guidance documents, EMA MDR technical specifications, ISO 15378 certification databases, and customs trade flow records. Bottom-up capacity assessments and top-down demand modeling converge through iterative stakeholder feedback loops.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models material type, capacity tier, closure configuration, and end-user procurement channel as core segmentation dimensions. CAGRs derive from regression analysis of historical shipment patterns and forward-looking qualification pipeline visibility. Forecast inputs incorporate EU MDR implementation timelines, SFDA localization policy enforcement, and home healthcare infusion penetration curves.
Underlying assumptions cover regulatory compliance stability, borosilicate furnace operational continuity, and resin supply chain normalization, with deviation risk concentrated in energy cost volatility affecting German glass-forming economics and ECHA REACH extractables profile revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Argentina Container Glass Market