
 Russia Glass Packaging Market | 2026-2036
Russia Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Glass Packaging Market Analytics
Russia's extended producer responsibility framework for packaging waste is shifting procurement criteria across the glass value chain. Sisecam leverages its integrated soda ash-to-container operations to sustain cost advantages in southern Russia. Verallia Packaging anchors premium bottle supply for spirits exporters through its specialized furnace configurations. Avangard-Glass, JSC dominates the standard-container segment for domestic food producers, while SCHOTT Pharma differentiates in tubular glass for injectable pharmaceuticals.
Glass packaging denotes rigid containers formed from silica-based melts, typically comprising sand, soda ash, and limestone in proportions yielding thermal shock resistance between 40°C and 60°C for standard borosilicate grades, with primary purpose being inert product protection across food, pharmaceutical, and chemical applications. The bottles category leads value contribution due to spirits and wine demand, while pharmaceutical-grade containers represent the fastest-growing end-use segment as domestic drug manufacturing expands under import substitution mandates. Jars retain mature volume profiles in preserved food applications, whereas closures generate concentrated margin pools through proprietary sealing technologies.
Russia's national technical regulation system, aligned with EAEU TR 005/2011 on packaging safety, shapes mandatory migration limits and recyclability thresholds for all domestic glass container producers. The Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing enforces sanitary-epidemiological compliance, particularly for pharmaceutical and food-contact applications. Stakeholders must monitor evolving EAEU harmonization timelines and domestic recycling infrastructure investments to calibrate capacity and specification strategies.
Market Dynamics
Russia's extended producer responsibility framework is compressing container specifications across the glass value chain, forcing manufacturers to redesign for lighter weights while maintaining EAEU TR 005/2011 migration limits. This regulatory pressure intersects with import substitution mandates in pharmaceuticals and spirits modernization to reshape procurement criteria.
Growth Catalysts
- Extended Producer Responsibility Mandates:Russia's packaging waste regulations under EAEU harmonization are accelerating furnace upgrades toward energy-efficient configurations. Domestic producers must meet recyclability thresholds by 2026.
- Pharmaceutical Import Substitution:Tubular glass demand from domestic drug manufacturers is expanding as federal procurement rules prioritize local suppliers. SCHOTT Pharma and regional players are adding capacity.
- Spirits Export Modernization:Premium bottle procurement from Moscow-based distillers is rising as producers target CIS and Asian markets with differentiated packaging.
Market Restraints
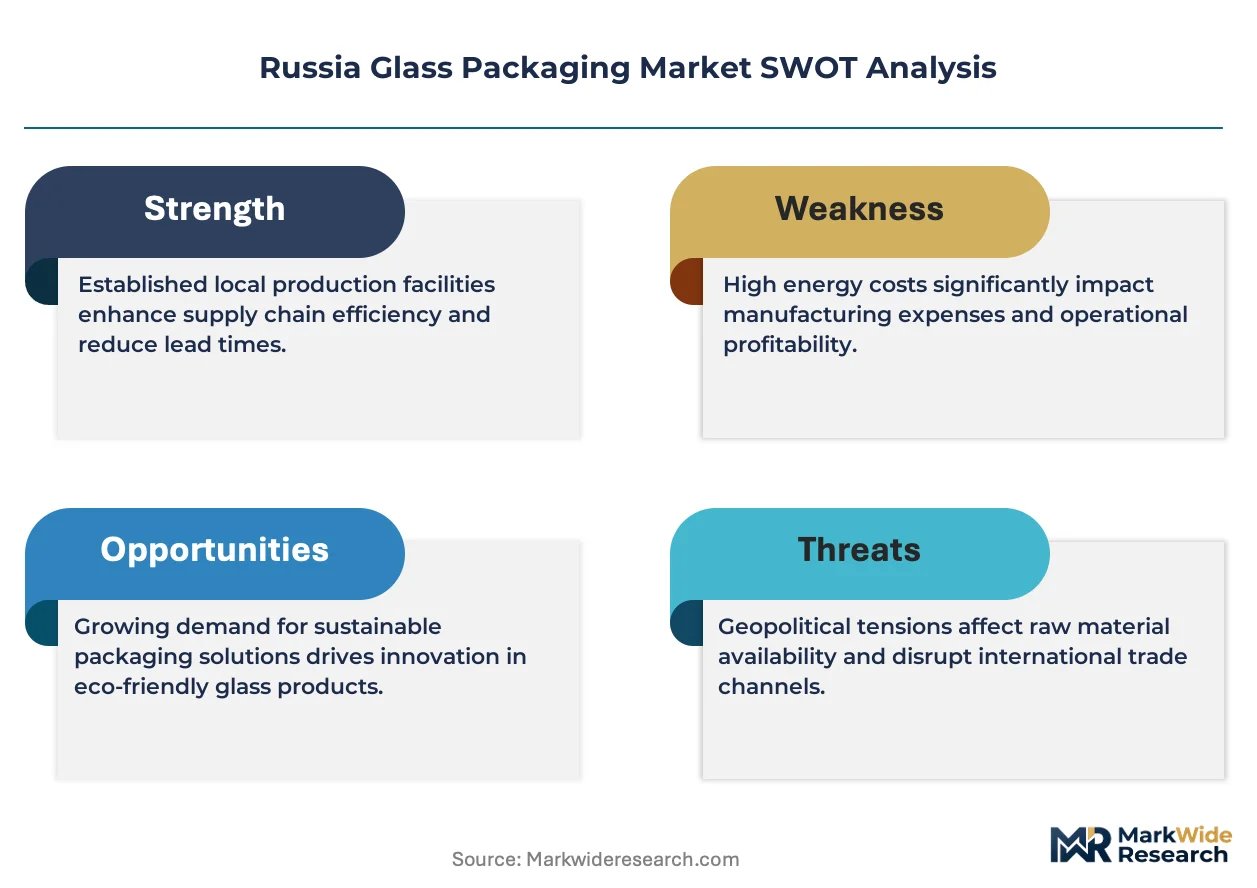
- Natural Gas Cost Volatility:Furnace operations depend on pipeline gas pricing, which fluctuates with federal tariff adjustments and seasonal demand spikes from residential heating.
- Soda Ash Supply Concentration:Sisecam's captive production in southern Russia limits third-party access to key raw material, constraining new entrant expansion.
- Polymer Substitution in Food:PET jars and multilayer plastics are displacing glass in mid-tier preserved food segments where weight and breakage costs outweigh premium positioning.
Strategic Opportunities
- Northwestern Federal District Underpenetration:Saint Petersburg's food processing cluster lacks localized glass supply, creating white space for container plants serving Baltic export corridors.
- Pharmaceutical Serialization Convergence:Integration of track-and-trace systems with molded markings is enabling compliance-ready packaging for Federal Service for Surveillance in Consumer Rights Protection mandates.
- Lightweighting Technology Adoption:Thin-wall container designs below 250 grams for standard wine bottles are opening premium positioning at reduced material cost.
Industry Challenges
- Furnace Rebuild Capex Intensity:Cold repairs and capacity expansions require 24-36 month payback periods under current energy pricing, constraining balance sheet flexibility for mid-tier producers.
- EAEU Harmonization Timeline Uncertainty:Pending technical regulation updates for pharmaceutical glass are delaying specification finalization and procurement commitments from domestic drug manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Glass Packaging Market |
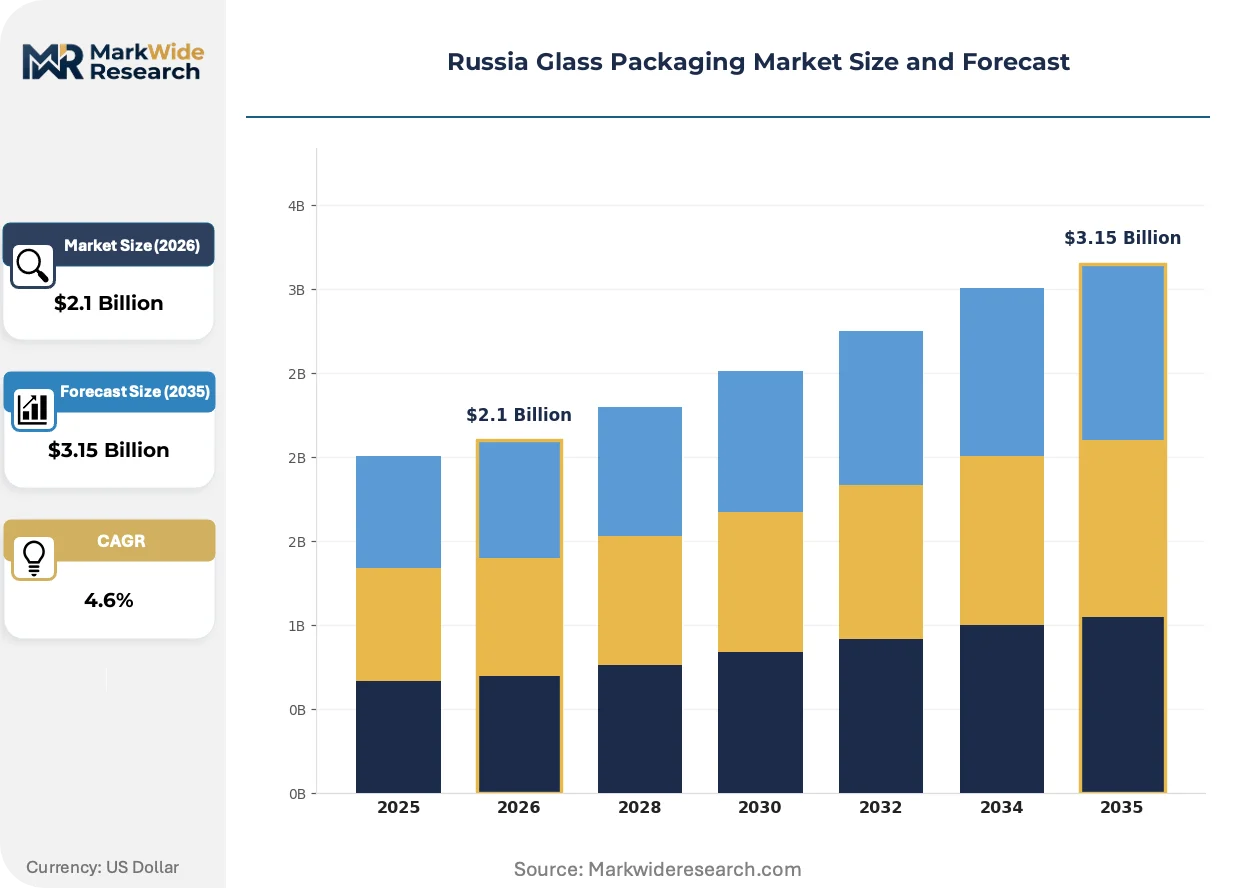
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Closures End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Verallia Packaging, Sisecam, Avangard-Glass, JSC, SCHOTT Pharma, Trade House Mirtorg, Ardagh Group, Krasnoye Echo LLC, SLODES LLC, Saverglass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Glass Packaging Market Evolving Landscape
Digital marking technologies and furnace automation are compressing production cycles while EAEU regulatory convergence is standardizing container specifications across the customs union. These forces are reshaping how Russian producers compete on compliance speed and specification flexibility.
Electrochemical etching and laser coding systems are integrating with molded-in serialization for pharmaceutical and spirits applications. Domestic drug manufacturers under Federal Service for Surveillance in Consumer Rights Protection mandates are adopting these systems fastest, with implementation timelines compressing from 18 months to 8 months. This technology is integrating compliance infrastructure directly into container production, reducing post-molding processing steps and enabling real-time batch verification.
EAEU TR 005/2011 amendments are tightening migration limits for heavy metals in food-contact glass, with enforcement expanding from Moscow-based producers to regional plants. Manufacturers are reformulating batch compositions to reduce lead and cadmium traces below 0.01 mg/dm² thresholds. Pharmaceutical-grade containers face the steepest compliance ramps, with tubular glass producers investing in dedicated furnace lines to segregate medical and food-contact production.
Direct procurement contracts between distillers and container plants are consolidating volume previously fragmented through distributors. Moscow-based spirits exporters are negotiating multi-year supply agreements with furnace-specific capacity reservations, displacing spot-market purchasing. This pattern concentrates most visibly in the Central Federal District, where food and beverage conglomerates anchor procurement decisions for premium bottle specifications.
Russia Glass Packaging Market Segmentation
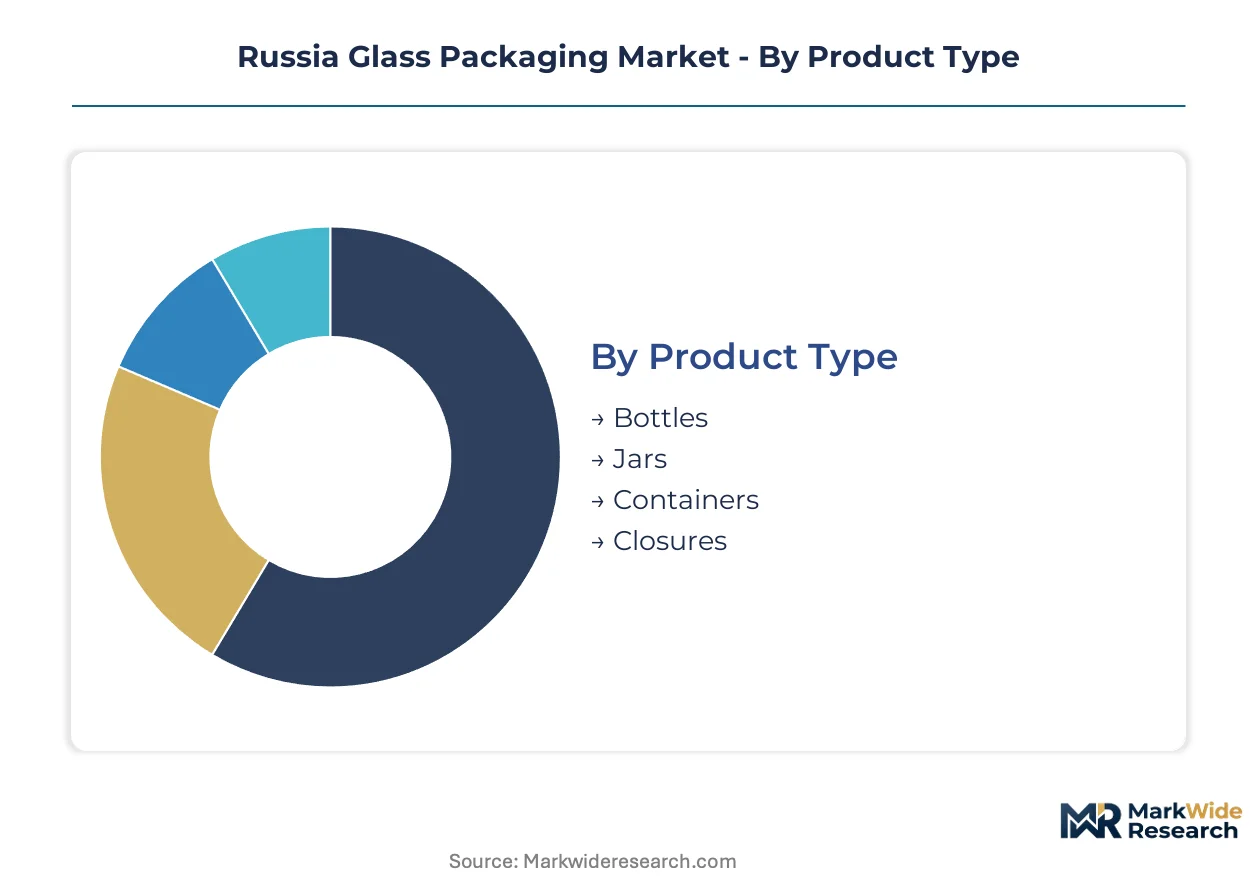
Glass packaging segmentation in Russia follows specification hierarchies that separate premium spirits and pharmaceutical applications from commodity food containers. Each axis—product form, end-use, size class, and channel—carries distinct margin profiles and regulatory exposure under EAEU TR 005/2011.
Product Type:
Thermal shock resistance and wall thickness specifications differentiate container categories across furnace configurations.
- Bottles:Borosilicate and soda-lime melts with thermal shock resistance between 40°C and 60°C serve spirits and wine producers. Demand concentrates in the Central Federal District where Moscow-based distillers anchor premium procurement for CIS and Asian export markets.
- Jars:Wide-mouth containers with thicker walls accommodate thermal processing for preserved foods. Avangard-Glass dominates standard specifications for domestic food producers facing polymer substitution pressure from PET alternatives in mid-tier segments.
- Containers:Rectangular and specialized forms for chemical and industrial applications require modified batch compositions.
- Closures:Proprietary sealing technologies generate concentrated margin pools through threaded and lug finishes.
Mature deployment sits with Jars in preserved food applications. Newer deployment is concentrated in Bottles as spirits modernization accelerates.
End User:
Regulatory stringency and import substitution mandates create divergent procurement criteria across customer verticals.
- Food & Beverage:Spirits producers drive premium bottle specifications while preserved food manufacturers face cost pressure from polymer alternatives. EAEU migration limits for heavy metals are tightening batch composition requirements across all food-contact production.
- Pharmaceuticals:Tubular glass for injectable drugs represents the steepest expansion trajectory as federal procurement rules prioritize domestic suppliers. SCHOTT Pharma and regional players are adding dedicated furnace capacity to segregate medical from food-contact production.
- Cosmetics:Decorative finishes and color customization serve premium positioning in urban retail channels.
- Chemicals:Acid-resistant formulations and specialized annealing protocols address industrial reagent containment.
Volume leadership belongs to Food & Beverage. Regulatory complexity and margin expansion are climbing fastest in Pharmaceuticals.
Size:
Weight reduction targets under extended producer responsibility frameworks are compressing specifications across dimensional classes.
- Small:Sub-200ml containers for spirits miniatures and pharmaceutical vials require precision molding. Lightweighting initiatives target wall thickness reduction below 2mm while maintaining EAEU structural integrity standards.
- Medium:Standard wine and spirits formats between 375ml and 750ml dominate furnace throughput scheduling. Direct procurement contracts with distillers are consolidating volume previously fragmented through distributors.
- Large:1-2 liter formats for food service and bulk chemical applications.
- Extra Large:Industrial and institutional containers above 2 liters with reinforced bases.
Production scheduling prioritizes Medium formats. Lightweighting investment flows most heavily toward Small specifications.
Distribution Channel:
Channel structure determines specification flexibility and batch size economics for container producers.
- Direct Sales:Multi-year supply agreements with furnace-specific capacity reservations are displacing spot-market purchasing among Moscow-based spirits exporters. Verallia Packaging anchors this channel through specialized furnace configurations for premium bottle supply.
- Wholesale:Aggregated demand from regional food processors requires standardized specifications and inventory holding.
- Retail:Cosmetic and specialty food packaging with shorter lead times and decorative customization.
- Online:Emerging channel for sample quantities and specialized pharmaceutical procurement.
Contract concentration is highest in Direct Sales. Channel development is advancing most quickly in Online for pharmaceutical track-and-trace compliance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors Russia's glass packaging demand through its concentration of spirits exporters and food conglomerates. The Central Federal District generates the majority of volume offtake as premium bottle procurement accelerates for CIS and Asian markets.
Central Federal District
Spirits modernization and premium bottle export programs drive procurement intensity. EAEU TR 005/2011 enforcement concentrates first on Moscow-based producers before regional rollout. The Moscow Oblast corridor hosts Verallia Packaging's specialized furnace operations serving distillery direct contracts.
Northwestern Federal District
Saint Petersburg's food processing cluster lacks localized glass supply, creating capacity white space. Extended producer responsibility frameworks push Baltic corridor exporters toward lighter-weight specifications. The Leningrad Oblast industrial zone attracts import substitution investment for pharmaceutical tubular glass.
Southern Federal District
Sisecam's integrated soda ash-to-container operations sustain cost advantages in Rostov and Krasnodar regions. Federal tariff adjustments on natural gas influence furnace economics across Black Sea coastal plants. The Rostov-on-Don agglomeration serves preserved food manufacturers with standard-container output.
Volga Federal District
Avangard-Glass dominates commodity jar production for regional food processors facing PET substitution pressure. EAEU harmonization timelines for pharmaceutical glass delay specification commitments from domestic drug manufacturers. The Nizhny Novgorod-Samara corridor concentrates mid-tier container capacity for chemical and industrial applications.
Ural Federal District
Chemical-resistant container demand from industrial reagent producers shapes batch composition requirements. The country's national packaging safety regulator extends sanitary-epidemiological compliance audits beyond Moscow to regional plants. The Yekaterinburg-Chelyabinsk manufacturing belt develops specialized annealing protocols for acid-resistant formulations.
Russia Glass Packaging Market Competitive Landscape
The competitive structure tilts toward integrated material producers with captive raw material access. Domestic specialists and multinational subsidiaries occupy distinct specification tiers without significant overlap. Three archetypes dominate: soda ash-integrated container giants, premium spirits-focused furnace operators, and pharmaceutical-grade tubular glass specialists. Capacity reservation contracts and lightweighting technology licensing represent the dominant competitive moves as extended producer responsibility deadlines approach.
Within the integrated-material tier, Sisecam exemplifies upstream control through southern Russia soda ash production. Verallia Packaging occupies a position among premium-tier furnace operators serving Moscow-based spirits exporters. Avangard-Glass, JSC anchors the standard-container segment for domestic food producers, while SCHOTT Pharma represents the pharmaceutical-grade specialization archetype. These four names illustrate how procurement criteria fragmentation—between premium export bottles, commodity food jars, and medical-grade tubular glass—prevents direct competition across specification boundaries.
| Leading Market Players |
|---|
| Verallia Packaging |
| Sisecam |
| Avangard-Glass, JSC |
| SCHOTT Pharma |
| Trade House Mirtorg |
| Ardagh Group |
| Krasnoye Echo LLC |
| SLODES LLC |
| Saverglass |
| Others |
Value Network & Pricing Analysis
Specialized furnace engineering talent concentration in the Central Federal District widens labor-cost differentials between Moscow-based premium bottle producers and regional commodity plants, compressing pricing-tier spreads as lightweighting investments demand uniform technical capability.
Pricing Analysis
Furnace throughput guarantees anchor value-based pricing for premium spirits bottles, with Moscow-based distillers reserving dedicated capacity years ahead. Three-tier pricing structure across premium export-grade, standard domestic, and economy food-container levels separates Verallia's specialized configurations from Avangard-Glass commodity output. Cost compression in the economy tier intensifies because PET substitution erodes volume leverage for preserved food jars. Regional food processors exhibit highest price sensitivity, while pharmaceutical manufacturers under import substitution mandates accept premium positioning for EAEU-compliant tubular glass.
Supply Chain Analysis
Skilled furnace operations and batch chemistry expertise availability concentrates in southern Russia and the Moscow corridor, constraining new entrant expansion. Raw material sourcing draws from Sisecam's captive soda ash production in Rostov, imported limestone from Kazakhstan, and natural gas pipeline networks across the Black Sea coastal zone. Single-source vulnerability sits with Sisecam's upstream control over soda ash supply to third-party container plants. Distribution runs through direct procurement contracts with distillery capacity reservations, displacing wholesale spot-market purchasing in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility deadlines compressing toward 2026 are forcing furnace rebuild investments beyond mid-tier balance sheet capacity, eliminating subscale players unable to fund energy-efficient upgrades.
For Market Incumbents: Cement market position through captive soda ash integration or long-term supply agreements insulating against Sisecam's upstream leverage. Lock in multi-year distillery direct contracts with furnace-specific capacity reservations before EAEU harmonization finalizes pharmaceutical glass specifications. Prioritize lightweighting technology licensing to regional competitors seeking compliance shortcuts, converting regulatory pressure into recurring revenue.
For New Entrants and Emerging Players: Northwestern Federal District food processors lacking localized glass supply present the most penetrable buyer archetype, particularly Baltic corridor exporters seeking lighter-weight specifications. Pharmaceutical tubular glass under EAEU pending technical regulations offers white space as domestic drug manufacturers await specification clarity. Pursue joint venture structures with existing furnace operators to bypass 24-36 month cold repair payback barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with soda ash-integrated container specialists given extended producer responsibility catalysts tightening raw material access. Five-to-ten year viability favors upstream-controlled assets over pure-play converters facing feedstock squeeze. Monitor EAEU TR 005/2011 pharmaceutical glass amendment publication as inflection signal for domestic drug manufacturer procurement commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash | Sisecam's Rostov operations demonstrate how captive raw material supply insulates margin from feedstock volatility. |
| Furnace Energy Efficiency Upgrade | Cold repair investments toward 2026 EAEU recyclability thresholds compress payback periods for early movers. |
| Pharmaceutical Serialization Integration | Laser coding systems meeting Federal Service for Surveillance mandates reduce post-molding processing steps. |
| Lightweighting Technology Licensing | Thin-wall container designs below 250 grams open premium positioning at reduced material intensity. |
| Direct Procurement Contract Consolidation | Multi-year distillery agreements displace fragmented distributor purchasing in Central Federal District. |
Research Methodology
Multi-period observation of furnace capacity utilization, EAEU regulatory amendment timelines, and spirits export volume trajectories anchored the trend analysis, supplemented by interviews with plant operations directors, distillery procurement leads, pharmaceutical manufacturing executives, and regional distribution channel managers. Secondary validation drew from customs trade records, EAEU technical regulation filings, federal energy tariff disclosures, and container industry association capacity surveys. Bottom-up plant-level production estimates triangulated against top-down end-use demand aggregation.
Input-output matrices mapping silica sand, soda ash, and natural gas feedstock flows to furnace output specifications across product type, end-use vertical, size class, and distribution channel dimensions structured the projection framework. CAGRs were derived from segmented volume build-ups calibrated to regulatory deadline impacts and import substitution procurement shifts. Natural gas pricing volatility and EAEU harmonization timeline uncertainty served as scenario sensitivity inputs.
Revisions become necessary when EAEU pharmaceutical glass specification finalization delays, federal natural gas tariff restructuring, or soda ash supply disruptions materialize beyond modeled assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Poland Container Glass Market