
 Injectable Drug Packaging Market | 2026-2036
Injectable Drug Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Drug Packaging Market Foresight
Biologics manufacturing is repositioning demand toward advanced containment systems as monoclonal antibodies and cell therapies require specialized barrier properties. West Pharmaceutical Services leverages its elastomer and device integration expertise to serve high-value biologics customers. Gerresheimer AG anchors European supply of borosilicate glass vials and polymer syringes through its German manufacturing footprint. SCHOTT AG dominates specialty glass innovation, sustaining leadership in alkali-free formulations for sensitive biologics.
Injectable drug packaging encompasses primary containers, closure systems, and delivery devices engineered to maintain sterility, stability, and dosing precision for parenteral pharmaceuticals. These systems employ materials such as borosilicate glass with hydrolytic resistance class HC1, cyclic olefin polymers with moisture barriers below 0.5 g/m²/day, and halobutyl rubber stoppers with particle counts controlled to USP <788> limits. Prefilled syringes are capturing share from traditional vial formats as pharmaceutical companies seek to reduce medication errors and streamline administration workflows. Glass vials retain structural importance for lyophilized products where thermal stability and inert contact surfaces remain non-negotiable. Plastic and composite materials are expanding fastest in single-use autoinjector cartridges where break resistance and design flexibility outweigh glass performance advantages.
The FDA enforces container closure integrity testing under USP <1207> while the EMA's Annex 1 revision mandates barrier isolation technology for sterile injectable filling operations. ISO 15378 and GMP certification frameworks govern material traceability and quality management systems across supplier networks. Stakeholders must monitor evolving regulatory divergence between FDA emphasis on leachable and extractable profiling and EMA requirements for visual inspection automation.
Market Dynamics
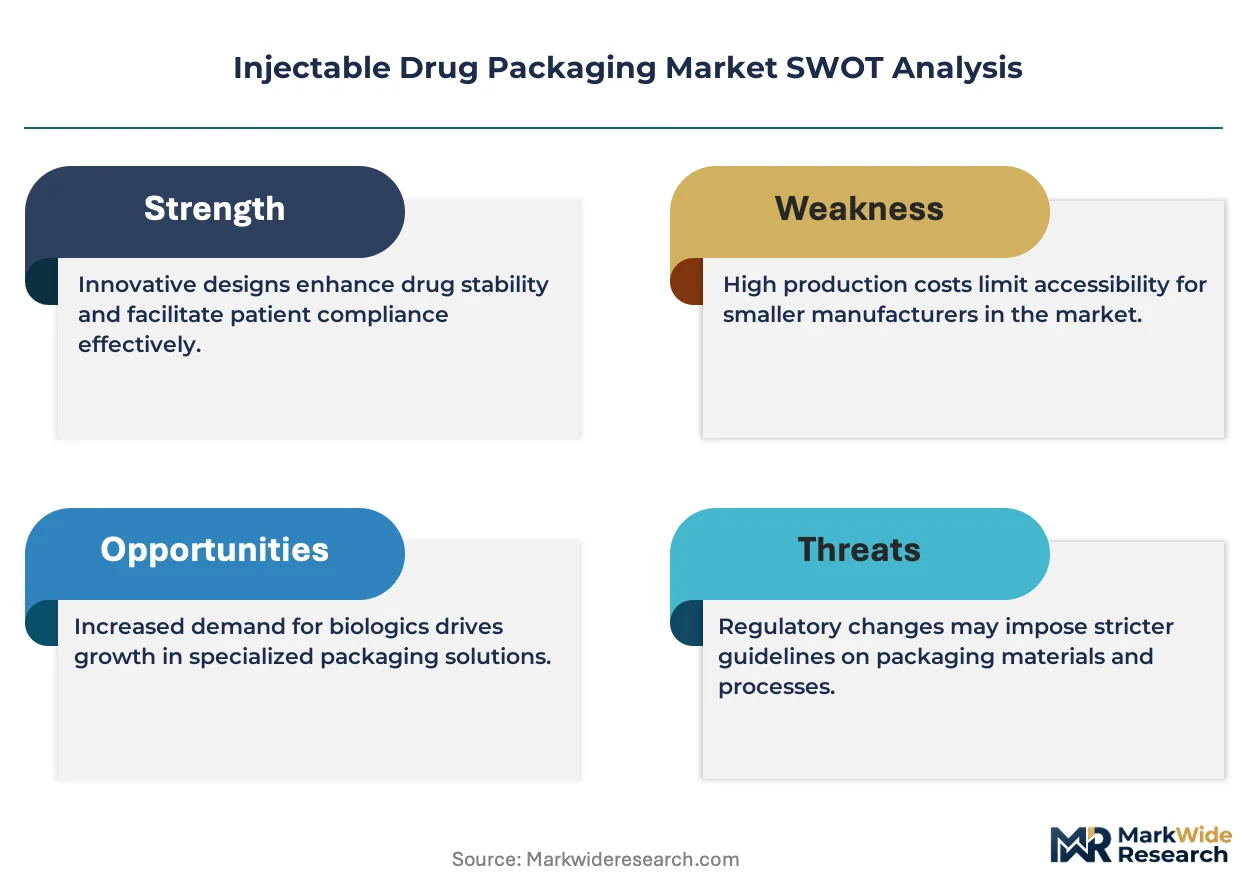
The Injectable Drug Packaging Market is undergoing structural compression as biologics manufacturing migrates from multi-dose vials toward single-use containment systems engineered for sensitive protein formulations. This shift demands entirely new material specifications and sterility assurance protocols.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing mandate accelerates barrier isolation technology adoption across European fill-finish operations, forcing upgrades to closed-system processing.
- Cell Therapy Manufacturing:Autologous and allogeneic cell therapies require cryogenic-compatible containers with validated seal integrity below minus 150 degrees Celsius, creating specialized demand for polymer-based formats.
- German Glass Production Cluster:Concentrated borosilicate manufacturing expertise in Bavaria and Thuringia anchors regional supply security for high-value biologics customers.
Market Restraints
- Specialty Polymer Feedstock Volatility:Cyclic olefin polymer resin prices fluctuate with benzene derivative markets, compressing margins for syringe and cartridge converters.
- Glass Supply Concentration:Three German and Japanese producers control alkali-free borosilicate formulation know-how, creating single-source vulnerability for sensitive biologics.
- Extractables Profiling Burden:FDA leachable studies under USP 1664 extend qualification timelines by 18-24 months for new elastomer formulations.
Strategic Opportunities
- Indian Contract Manufacturing Expansion:CDSCO manufacturing license reforms and PLI scheme incentives position India for prefilled syringe assembly and secondary packaging.
- Connected Delivery Convergence:Integration of NFC-enabled adherence sensors with disposable autoinjectors creates differentiated value for diabetes and multiple sclerosis therapies.
- Japan Precision Polymer Demand:PMDA quality management requirements for high-viscosity biologics favor Japanese suppliers with sub-micron dimensional tolerance capabilities.
Industry Challenges
- ISO 15378 Auditor Shortage:Certified pharmaceutical packaging quality management auditors remain scarce, extending certification timelines for new manufacturing sites.
- Legacy Vial Line Retrofit Complexity:Converting existing glass vial washing and depyrogenation tunnels for isolator-based filling requires substantial capital and validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Drug Packaging Market |
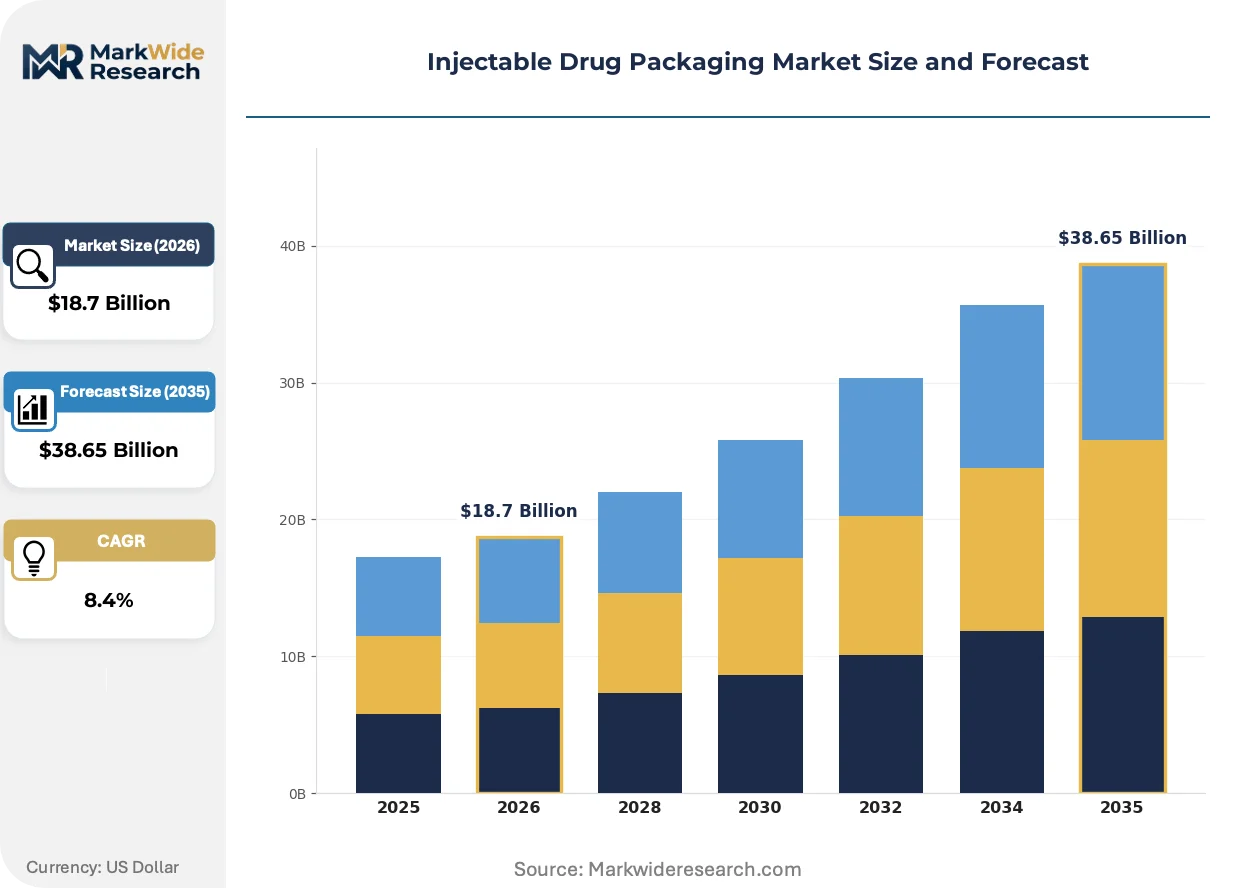
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Syringes, Vials, Ampoules, Cartridges Material: Glass, Plastic, Rubber, Composite End User: Pharmaceutical Companies, Hospitals, Clinics, Contract Manufacturers Certification: ISO, GMP, FDA Approved, CE Mark |
| Companies Covered | West Pharmaceutical Services, Becton, Dickinson and Company, Gerresheimer AG, SCHOTT AG, Stevanato Group, Nipro Corporation, AptarGroup, Terumo Corporation, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Drug Packaging Market Shifts & Advancements
Container closure systems are converging with drug delivery devices as pharmaceutical companies seek to compress time-to-market and reduce medication error liability. Material science advances and regulatory harmonization efforts are simultaneously reshaping supplier qualification protocols.
Ready-to-use (RTU) container formats are consolidating supplier relationships in the fill-finish ecosystem. Contract manufacturers and large pharmaceutical firms are adopting RTU vials, syringes, and cartridges pre-sterilized and pre-assembled by packaging specialists. This model eliminates glass-to-glass contact during washing and depyrogenation, reducing particle generation risks. The structural consequence is margin compression for equipment manufacturers of traditional washing tunnels while consolidating volume with integrated packaging-device suppliers.
REACH substance restrictions and the EU Green Deal are forcing reformulation of rubber closure components. ECHA scrutiny of nitrosamine precursors in accelerator systems is driving halobutyl compounders toward sulfur-cure alternatives with equivalent compression set performance. European pharmaceutical manufacturers are qualifying these next-generation elastomers ahead of anticipated regulatory deadlines, creating temporary dual-sourcing complexity during transition periods.
Hospital and clinic procurement of prefilled formats is displacing traditional vial-and-syringe workflows in therapeutic areas with high dosing frequency. Rheumatology and endocrinology practices in the United States and Germany are standardizing on autoinjector and pen systems to reduce pharmacy compounding burden and improve adherence metrics. This behavioral shift concentrates purchasing power with integrated delivery device suppliers capable of combining container, closure, and injection mechanism in single-source contracts.
Injectable Drug Packaging Market Segmentation
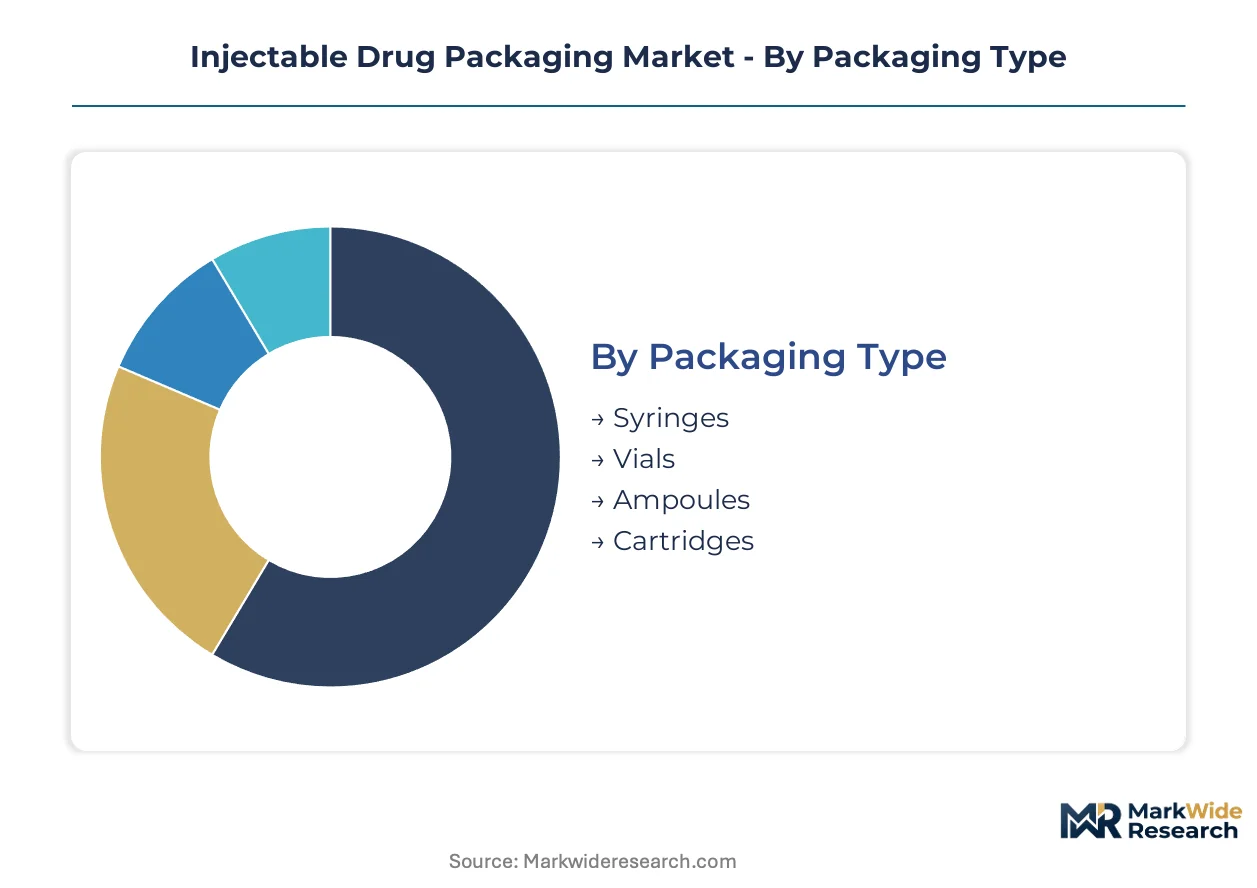
Injectable drug packaging segmentation reflects divergent technical requirements across biologics stability profiles, administration workflows, and regulatory submission pathways. Material selection and format geometry directly determine compatibility with sensitive protein formulations and automated filling lines.
Packaging Type:
Standalone primary containers dominate high-volume biologics, while embedded systems in autoinjectors and pen devices serve chronic disease management.
- Syringes:Prefilled formats integrate luer-lock or staked-needle configurations with cyclic olefin barrel materials. Demand concentrates in Germany and Japan for diabetes and multiple sclerosis therapies where self-administration protocols reduce clinic burden.
- Vials:Borosilicate glass with hydrolytic resistance class HC1 remains essential for lyophilized monoclonal antibodies. Glass-to-glass contact risks during traditional washing drive migration toward ready-to-use formats supplied by German manufacturers.
- Ampoules:Single-dose glass containers serve emergency and anesthetic applications requiring immediate access without reconstitution steps.
- Cartridges:Pen-injector compatible formats with precise plunger fit tolerances support high-viscosity biologics in rheumatology and endocrinology.
Vials lead volumes today; syringes are gaining share fastest.
Material:
Cost tiers separate premium alkali-free formulations from standard borosilicate and commodity polymer alternatives.
- Glass:Type I borosilicate with controlled hydrolytic resistance dominates parenteral applications where inert contact surfaces prevent protein aggregation. SCHOTT and Gerresheimer anchor German production of alkali-free specialty grades for cell therapies.
- Plastic:Cyclic olefin polymers and cyclic olefin copolymers deliver moisture barriers below 0.5 g/m²/day with break resistance for wearable injector applications. Japanese suppliers command premium positioning through sub-micron dimensional tolerances.
- Rubber:Halobutyl and bromobutyl elastomer formulations with sulfur-cure or peroxide-cure systems provide gas permeation control and needle reseal integrity.
- Composite:Multi-layer barrier films and polymer-coated glass hybrids address oxygen-sensitive biologics requiring extended shelf stability.
Glass leads volumes today; plastic formats are climbing the fastest.
End User:
Application intensity varies from high-throughput fill-finish operations to point-of-care administration with divergent sterility assurance requirements.
- Pharmaceutical Companies:Integrated drug-device combination product developers specify container closure systems during early-phase formulation. Internal packaging engineering teams at firms like West Pharmaceutical Services coordinate elastomer, glass, and device integration.
- Contract Manufacturers:CDMOs operating under EMA Annex 1 mandates adopt barrier isolation technology and ready-to-use formats to minimize validation overhead across client programs.
- Hospitals:Pharmacy compounding operations favor prefilled syringes to reduce medication error liability and streamline high-frequency dosing protocols.
- Clinics:Outpatient rheumatology and endocrinology practices standardize on autoinjector systems with adherence tracking capabilities.
Pharmaceutical companies lead volumes today; contract manufacturers are expanding most quickly.
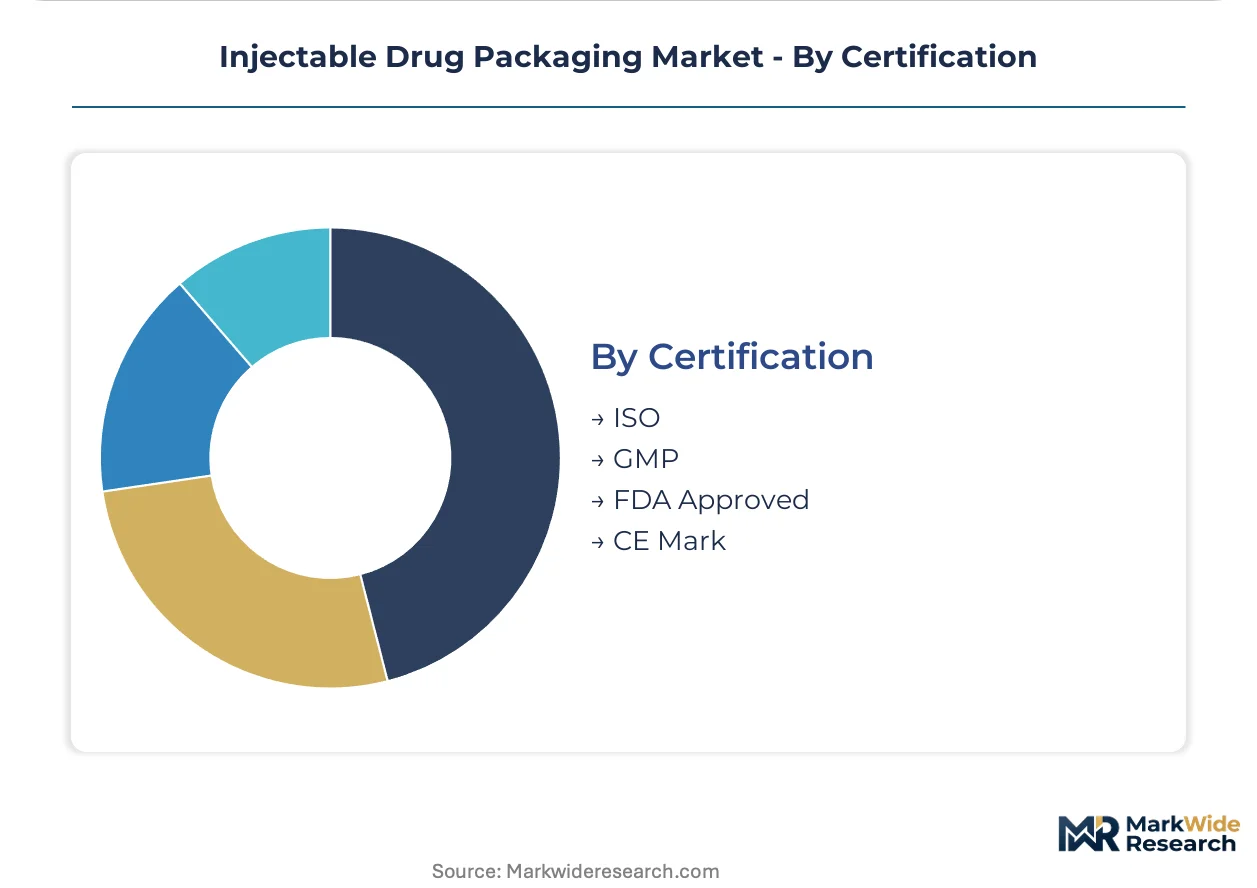
Certification:
Margin structures separate premium-certified formats from standard-grade alternatives with divergent qualification timelines.
- ISO:ISO 15378 pharmaceutical packaging quality management certification governs material traceability and risk management systems across supplier networks.
- GMP:EU GMP Annex 1 and FDA cGMP requirements mandate environmental monitoring and container closure integrity validation for sterile injectable operations.
- FDA Approved:Drug master file submissions and type III drug master file references support New Drug Application packaging components with established extractables profiles.
- CE Mark:Medical Device Regulation compliance applies to prefilled syringes and autoinjector systems classified as class IIa or IIb devices in Europe.
GMP certification leads volumes today; FDA-approved formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing injectable drug packaging production toward jurisdictions with harmonized standards and concentrated supplier ecosystems, as manufacturers seek to minimize duplicate qualification costs across FDA and EMA submission pathways.
United States
Biologics fill-finish capacity expansion around Boston and Research Triangle Park is absorbing ready-to-use vial and syringe formats for cell therapy manufacturing. FDA container closure integrity testing under USP 1207 is tightening validation protocols for barrier isolation systems. West Pharmaceutical Services anchors elastomer and device integration supply from Pennsylvania and Arizona facilities.
Germany
EMA Annex 1 sterile manufacturing mandates are accelerating isolator technology adoption across Bavarian and Thuringian fill-finish operations. REACH substance restrictions are forcing halobutyl rubber compounders toward sulfur-cure reformulations ahead of regulatory deadlines. Gerresheimer and SCHOTT dominate alkali-free borosilicate production from Mainz and Mitterteich, supplying European biologics customers.
Japan
PMDA quality management requirements for high-viscosity biologics are concentrating demand for sub-micron tolerance polymer syringes. METI industrial policy supports precision molding capabilities for diabetes and multiple sclerosis autoinjector applications. Nipro and Terumo command premium positioning through Osaka and Tokyo-region manufacturing clusters.
India
CDSCO manufacturing license reforms and PLI scheme incentives are positioning Indian contract manufacturers for prefilled syringe assembly and secondary packaging. Domestic biologics production growth is creating localized demand for glass vial and rubber closure supply. Hyderabad and Ahmedabad clusters are attracting German and Japanese packaging specialists for technology transfer partnerships.
Switzerland
Swissmedic alignment with EMA Annex 1 is reinforcing Basel-region biologics manufacturing investment in closed-system processing. Precision polymer and glass sourcing from neighboring German suppliers minimizes cross-border qualification overhead. Roche and Novartis captive demand sustains specialized containment system development for monoclonal antibody portfolios.
Injectable Drug Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging-device suppliers capturing prefilled format growth while standalone glass and elastomer producers defend lyophilized vial positions. Market structure concentrates around three German and Japanese anchors for alkali-free borosilicate, creating single-source vulnerability for sensitive biologics. Strategic archetypes include integrated delivery device developers, specialty glass formulators, and regional polymer converters. Dominant competitive moves encompass backward integration into elastomer compounding and strategic partnerships for connected delivery convergence.
Within the integrated delivery device tier, West Pharmaceutical Services and Becton, Dickinson and Company occupy positions spanning elastomer, glass, and autoinjector integration. Among European specialty glass formulators, Gerresheimer AG and SCHOTT AG exemplify the concentrated production expertise anchoring regional supply security. These five entities collectively represent the structural consolidation around barrier technology and material science capabilities that define competitive positioning in biologics containment.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Becton, Dickinson and Company |
| Gerresheimer AG |
| SCHOTT AG |
| Stevanato Group |
| Nipro Corporation |
| AptarGroup |
| Terumo Corporation |
| SGD Pharma |
| Others |
Supply & Pricing Matrix
Specialized borosilicate glass technicians concentrated in Bavaria and Thuringia command wage premiums that widen spreads between premium alkali-free formulations and standard hydrolytic resistance grades. Labor-cost differentials between German glassworks and Indian assembly operations sustain three-tier pricing architecture across certification levels.
Pricing Analysis
Distributor markups on ready-to-use formats compress as pharmaceutical companies consolidate volume with integrated packaging-device suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved drug master file formats from ISO-certified alternatives and uncertified commodity grades. Pricing pressure stems from REACH-driven elastomer reformulation costs passing through to closure compounders. Contract manufacturers exhibit highest price sensitivity due to multi-client validation overhead, while cell therapy developers prioritize seal integrity over unit economics.
Supply Chain Analysis
Freight costs for borosilicate glass tubing from Germany to Indian fill-finish operations have reshored some prefilled syringe assembly to European CDMOs. Supply concentrates in Germany, Japan, and India, with alkali-free formulation know-how anchored in Mainz and Mitterteich. Raw material dependencies include benzene-derived cyclic olefin polymers, sulfur-cure halobutyl rubber accelerators, and lithium-based glass clarifiers. Single-source vulnerability for specialty glass creates structural risk if German production faces energy disruption. Distribution runs through direct OEM contracts for high-volume biologics and medical device distributors for autoinjector systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in injectable drug packaging rests on ready-to-use format adoption eliminating glass-to-glass particle risks and commanding price premiums over traditional washed vials.
For Market Incumbents: Anticipate EMA Annex 1 compliance deadlines by accelerating isolator technology deployment across European fill-finish networks. Backward integration into elastomer compounding secures supply continuity amid REACH-driven reformulation cycles. Consolidate volume with cell therapy developers through cryogenic-compatible container qualification programs. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships targeting Indian CDMOs seeking barrier isolation technology transfer. White-space opportunities concentrate in connected delivery convergence for diabetes adherence monitoring and sulfur-cure halobutyl alternatives ahead of nitrosamine precursor restrictions. Penetrate through precision polymer tolling for Japanese high-viscosity biologics suppliers. For Investors and Strategic Acquirers: Integrated delivery device developers are the most active acquirers in this space, seeking elastomer and glass capabilities to complete combination product portfolios. Long-term viability favors suppliers with validated extractables profiles and isolator-ready format portfolios. Watch FDA container closure integrity guidance evolution as inflection indicator for barrier technology investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Ready-to-Use Format Expansion | Eliminates glass-to-glass contact risks during washing while consolidating supplier relationships with fill-finish operators. |
| Backward Integration into Elastomer Compounding | Secures captive supply of halobutyl formulations amid ECHA scrutiny of accelerator systems. |
| Barrier Isolator Technology Deployment | Addresses EMA Annex 1 sterile manufacturing mandates across European biologics fill-finish operations. |
| Connected Delivery Convergence | Integrates NFC-enabled adherence sensors with disposable autoinjectors for diabetes and multiple sclerosis therapies. |
| Cryogenic Container Qualification | Validates seal integrity below minus 150 degrees Celsius for autologous and allogeneic cell therapy manufacturing. |
Research Methodology
Multiple input streams — primary interviews with packaging engineering directors, regulatory affairs specialists, and hospital pharmacy procurement managers, alongside secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged fill-finish operations leaders at contract manufacturers, elastomer compounders, and glass tubing specialists across German, Japanese, and Indian manufacturing clusters. Secondary sources encompassed FDA drug master file submissions, EMA Annex 1 revision documentation, ISO 15378 certification registries, and USP extractables study publications.
Historical volume trajectories were cross-referenced against panel input from packaging strategists to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include packaging type, material formulation, end-user archetype, certification tier, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions incorporating biologics pipeline expansion rates, sterility assurance technology adoption curves, and contract manufacturing outsourcing trends.
Several conditions sit outside the modeled scope, including sudden regulatory divergence between FDA and EMA container closure requirements, catastrophic supply disruption at German glass production facilities, and breakthrough alternative materials displacing borosilicate for lyophilized applications. Forecasts reflect assumptions about sustained biologics manufacturing growth and harmonized quality standards adoption. Stakeholders should weight assumptions against their own operating context and validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market