
 Austria Container Glass Market | 2026-2036
Austria Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Container Glass Market Insights
Food and beverage packaging is shifting toward premium spirits and craft beer segments that favor distinctive bottle shapes and heavier base weights. Vetropack Austria GmbH leverages its Stockerau furnace complex to sustain high-volume output for beer and wine clients across Central Europe. Stoelzle Oberglas GmbH specializes in pharmaceutical and cosmetic flacons, competing on narrow-neck precision and cobalt-blue UV protection. Cristallo Glas GmbH anchors the artisanal segment with hand-finished decorated glass for regional distilleries.
Container glass refers to hollow-ware formed from molten silica sand, soda ash, and limestone, typically produced in regenerative end-fired furnaces operating at 1,500–1,600°C, then annealed to relieve thermal stress for mechanical durability in filling-line handling. Its primary commercial purpose is to provide chemically inert, impermeable, and infinitely recyclable packaging for liquids and semi-solids. Bottles dominate volume throughput in the 251–500ml and 501–1000ml capacity tiers, where standardized molds and high line speeds protect margin pools. Jars in the food preservation channel show faster growth as Austrian consumers reject single-use plastics for sauces and preserves. Soda lime glass remains the baseline packaging type by tonnage, though borosilicate vials command premium pricing in pharmaceutical end use where thermal shock resistance and hydrolytic stability meet pharmacopeial standards.
Austrian container glass production falls under EU REACH registration for chemical substances in coatings and inks, the EU Green Deal's packaging and packaging waste regulation with escalating recycled-content thresholds, and national implementation through Austria's Verpackungsverordnung administered by the Ministry of Climate Action. These frameworks compel furnace operators to raise cullet ratios and document lifecycle emissions, directly shaping furnace technology investment and raw-material sourcing. Stakeholders must monitor whether proposed EU carbon border adjustments on imported glass articles redirect sourcing toward domestic melt capacity or accelerate cross-border furnace consolidation.
Market Dynamics
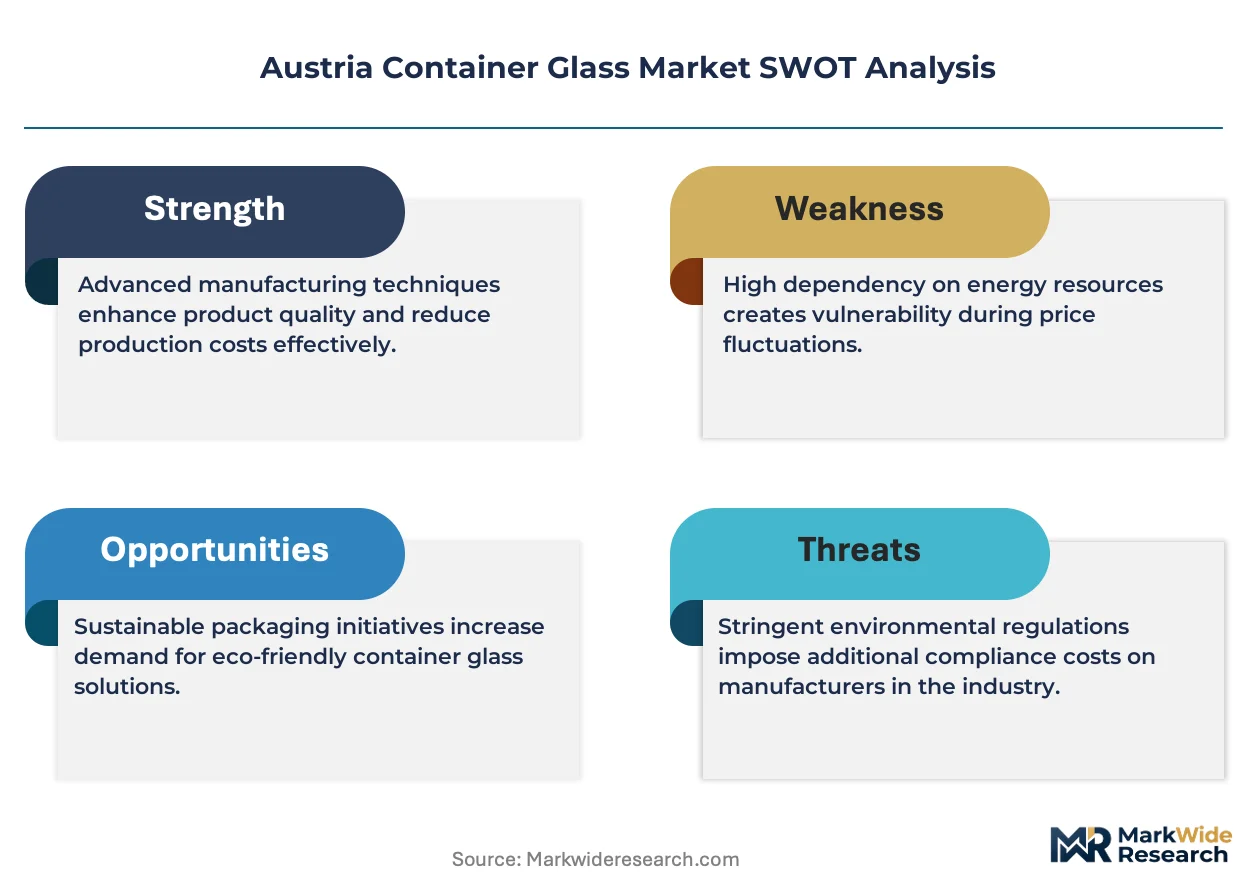
The EU Green Deal's escalating recycled-content mandates are forcing Austrian furnace operators to reconfigure melt chemistry and cullet handling systems, compressing margins for operators slow to adapt.
Growth Catalysts
- Verpackungsverordnung thresholds:Austria's national packaging ordinance compels brands to source domestic glass with verified post-consumer cullet, locking in local furnace demand.
- Pharmaceutical flacon precision:Narrow-neck borosilicate vials for injectables command premium pricing as CDSCO and EMA tighten pharmacopeial hydrolytic stability standards.
- Vienna-Stockerau production cluster:Concentrated melt capacity along the Danube corridor slashes logistics costs for Central European beverage exporters.
Market Restraints
- Natural gas price volatility:Regenerative end-fired furnaces burn methane at 1,500–1,600°C, exposing operators to TTF hub price spikes that erode melt economics.
- Cullet quality fragmentation:Inconsistent post-consumer glass collection across Austrian municipalities degrades batch chemistry, forcing costly manual sorting.
- Aluminum can substitution:Lightweight metal packaging captures share in standard beer volumes where brand differentiation matters less than shelf price.
Strategic Opportunities
- Upper Austria artisanal distilleries:Hand-finished decorated bottles for regional schnapps and liqueurs escape commodity pricing through heritage storytelling.
- EU carbon border adjustment:Proposed CBAM on imported glass articles would redirect sourcing toward domestic Austrian melt capacity.
- Electrified furnace pilots:Plasma and hybrid-electric melting technologies converge with renewable grid capacity to decarbonize production.
Industry Challenges
- Refractory engineer scarcity:Specialized furnace maintenance expertise is concentrating among retiring technicians, threatening uptime at aging Stockerau assets.
- REACH documentation burdens:Ceramic ink and organic coating suppliers face ECHA registration delays that stall new decoration launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Container Glass Market |
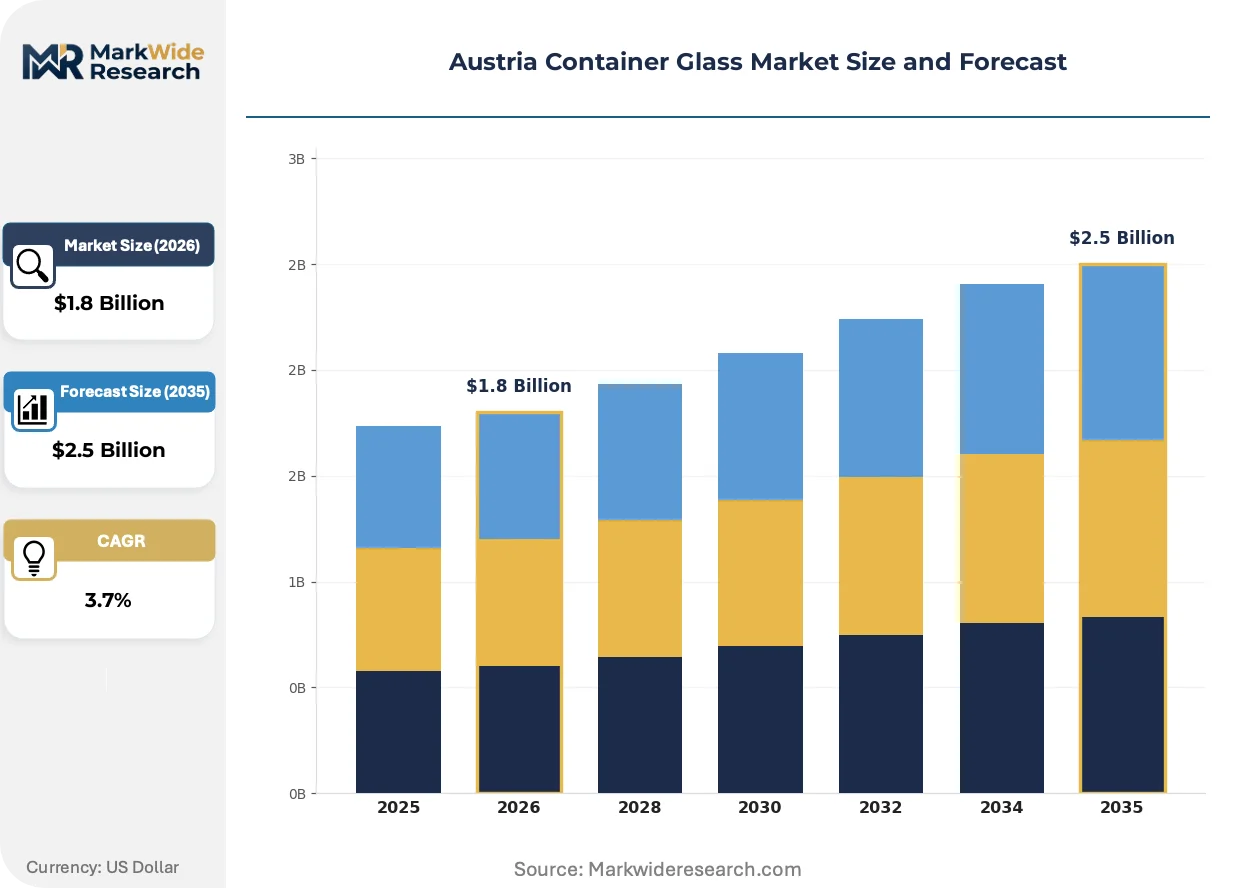
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Goods Capacity: 0-250ml, 251-500ml, 501-1000ml, 1001-2000ml Packaging Type: Soda Lime Glass, Borosilicate Glass, Laminated Glass, Decorated Glass |
| Companies Covered | Vetropack Austria GmbH, Stoelzle Oberglas GmbH, Cristallo Glas GmbH, Etivera Verpackungstechnik GmbH, Muller Glas & Co Handelsgesellschaft mbH, Stölzle Glass Group, Vetropack Group, Beatson Clark Ltd, Ardagh Group S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Container Glass Market Trends and Innovations
Active furnace decarbonization and lightweighting chemistry are compressing traditional melt protocols while regulatory documentation burdens intensify.
Electrified melting using plasma torch and hybrid-electric regenerative systems is overtaking conventional natural gas firing in Austrian pilot installations. Vetropack and Stoelzle are retrofitting end-fired furnaces with electrode arrays to cut scope 1 emissions ahead of EU ETS tightening. This shift is enabling carbon-neutral product lines that command green premiums from export clients in Germany and Switzerland.
EU Green Deal packaging waste regulation mandates 35% recycled content in glass by 2030, rising to 65% by 2040. Austrian operators must install automated optical sorting and cullet pre-heating to hit these thresholds without quality degradation. Premium cosmetic flacons face the steepest compliance costs due to color consistency requirements.
Direct procurement relationships between distilleries and Stoelzle Oberglas are displacing traditional distributor intermediaries in the artisanal spirits channel. Brand owners now specify mold designs and cobalt-blue UV protection directly, compressing lead times from twelve weeks to six. This pattern is most visible in Vienna's craft gin and amaro segments.
Austria Container Glass Market Segmentation
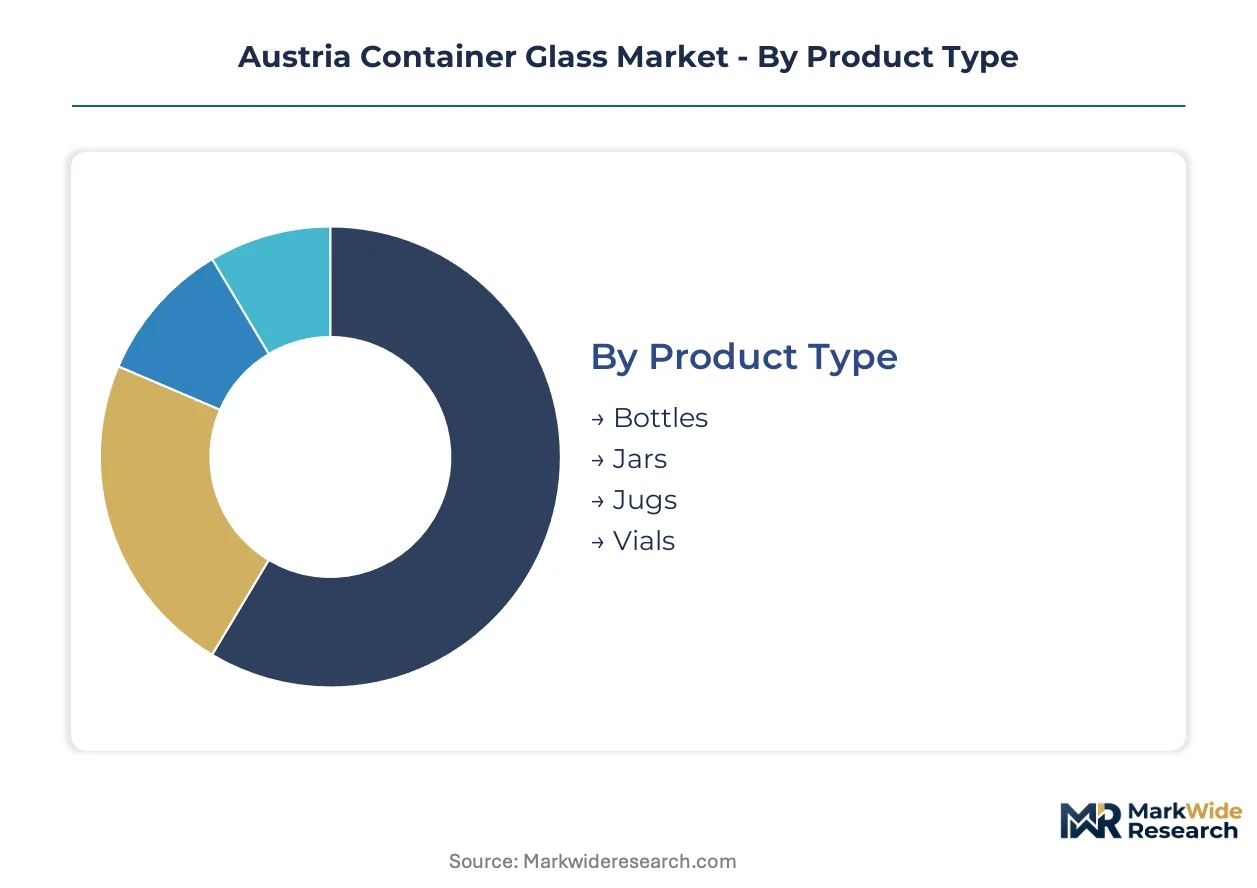
Austrian container glass demand fragments across four structural dimensions, each governing distinct furnace configurations and margin profiles. Product type and capacity tiers determine melt chemistry and mold investment, while end-user specifications dictate surface treatment and compliance documentation burdens.
Product Type:
Standalone packaging formats dominate volume throughput, whereas specialized pharmaceutical containers embed within regulated supply chains with stricter documentation.
- Bottles:Hollow-ware formed in standardized neck-finish configurations serves beer, wine, and spirits filling lines across Central Europe. Vienna's beverage exporters drive demand in the 330ml and 750ml standards where Stockerau furnace output secures supply continuity.
- Jars:Wide-mouth containers with lug or continuous thread closures preserve sauces, preserves, and condiments. Austrian consumers rejecting single-use plastics for household food storage are accelerating jar demand faster than bottle growth.
- Jugs:Large-format handled containers for bulk beverage and food service applications.
- Vials:Small-volume narrow-neck containers for pharmaceutical and laboratory use.
Volume placements concentrate in Bottles; the faster expansion belongs to Jars.
End User:
Cost-tier stratification separates commodity beverage contracts from premium pharmaceutical and cosmetic specifications demanding certified batch traceability.
- Food & Beverage:Beer, wine, spirits, and packaged foods account for the dominant share of Austrian melt tonnage. Vetropack Stockerau and Ried furnaces optimize for high-speed beer bottle output serving export corridors into Germany, Czech Republic, and Switzerland.
- Pharmaceuticals:Borosilicate vials and ampoules for injectables require hydrolytic stability certification under EMA pharmacopeial standards. Stoelzle Oberglas commands premium positioning through cobalt-blue UV protection and narrow-neck precision molding.
- Cosmetics:Flacons and perfume bottles with decorative surface treatments.
- Household Goods:Storage containers and general-purpose glassware for domestic use.
Food & Beverage anchors volume scale; Pharmaceuticals delivers the steepest margin expansion.
Capacity:
Application-driven volume bands align with filling line automation levels and logistics economics across Austrian production clusters.
- 0-250ml:Miniature spirits, pharmaceutical samples, and cosmetic trial sizes.
- 251-500ml:Standard beer bottles and single-serve beverage formats. This tier captures the highest mold utilization rates at Stockerau, where standardized 330ml and 500ml configurations run continuous campaigns.
- 501-1000ml:Wine bottles and multi-serve food containers. Austrian wine cooperatives in Lower Austria and Burgenland concentrate demand here, with 750ml Bordeaux and Burgundy shapes dominating export-bound output.
- 1001-2000ml:Magnum wine formats, spirits decanters, and bulk food storage. Limited production runs and custom mold requirements restrict this tier to artisanal distilleries and specialty contracts.
251-500ml and 501-1000ml tiers absorb the dominant furnace hours; sub-250ml formats are climbing fastest on pharmaceutical and premium spirits sampling trends.
Packaging Type:
Maturity gradients separate century-old soda lime mass production from emerging electrified and decorated formats bearing compliance premiums.
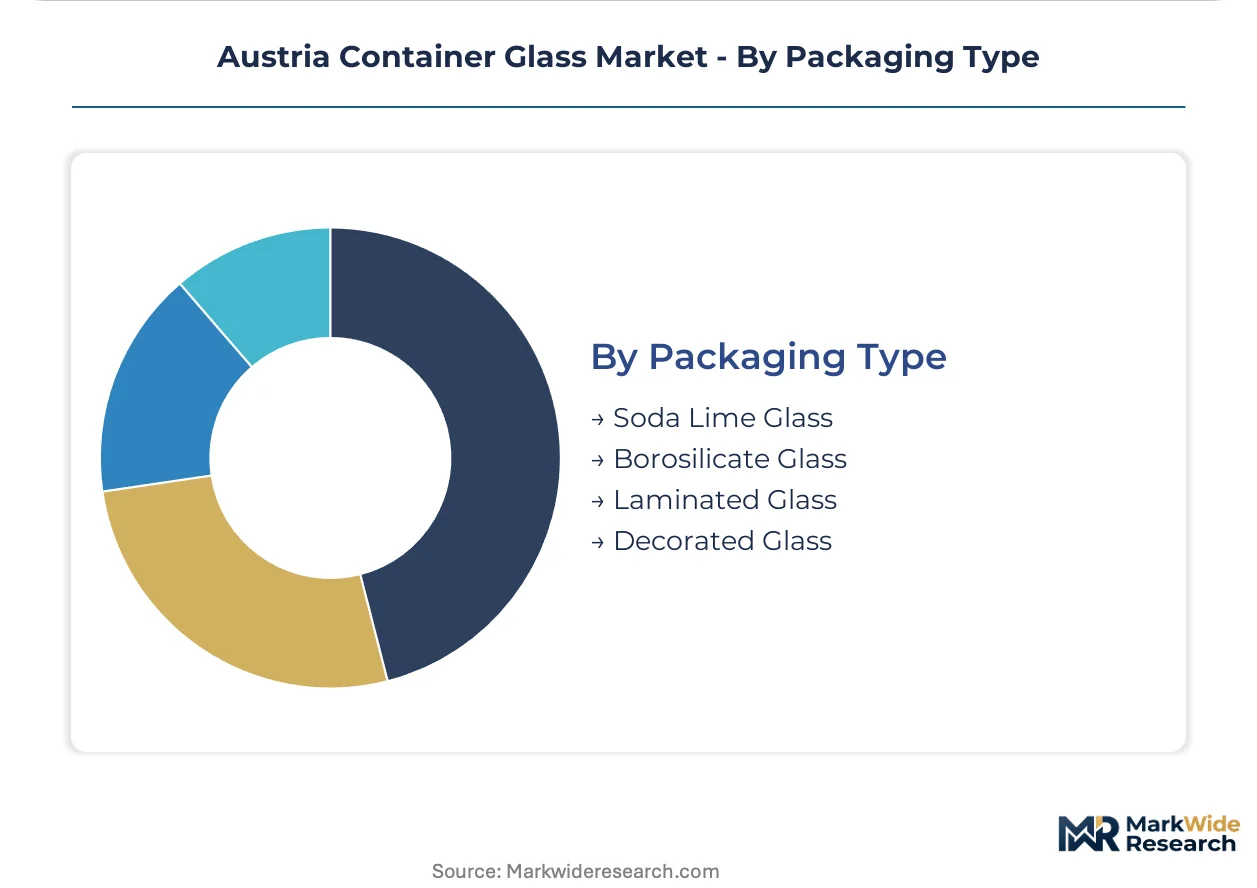
- Soda Lime Glass:Silica-soda-lime compositions melted in regenerative furnaces at 1500–1600°C constitute the baseline packaging substrate. This chemistry dominates Austrian output by tonnage, serving commodity beverage and food applications where cost minimization outweighs thermal performance.
- Borosilicate Glass:Boron oxide additions confer thermal shock resistance and hydrolytic stability for pharmaceutical and laboratory end uses. Stoelzle Oberglas specializes in this chemistry for EMA-compliant injectable vials commanding price multiples over soda lime equivalents.
- Laminated Glass:Interlayer-reinforced constructions for safety-critical applications.
- Decorated Glass:Ceramic ink, acid etching, and applied relief treatments for premium brand differentiation. Cristallo Glas GmbH anchors this segment with hand-finishing for regional distilleries, while automated decoration lines at larger furnaces serve scaled cosmetic contracts.
Soda Lime Glass retains volume dominance; Decorated Glass is gaining share fastest on premium spirits and craft positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Vienna-Stockerau production cluster anchors Austrian melt capacity, leveraging Danube logistics corridors and EU Green Deal compliance incentives to serve Central European export markets.
Germany
Bavarian beverage brands source heavily from Austrian furnaces for premium beer and spirits packaging. The country's national packaging ordinance enforces strict recycled-content verification, compelling cross-border procurement with documented cullet ratios. Munich and Nuremberg distributors maintain direct supply relationships with Upper Austrian glassworks.
Czech Republic
Bohemian craft breweries and Moravian wine cooperatives drive demand for decorated bottles and standard wine formats. EU REACH registration requirements for ceramic coatings shape supplier qualification protocols. Brno-based logistics hubs consolidate Austrian glass shipments for redistribution throughout Central Europe.
Switzerland
Swiss pharmaceutical and cosmetic houses procure borosilicate vials and cobalt-blue flacons from Styrian specialists. Swissmedic pharmacopeial standards for hydrolytic stability narrow the supplier base to EMA-certified Austrian furnaces. Basel and Zurich headquarters negotiate direct mold specifications with Stoelzle Oberglas.
Hungary
Budapest distilleries and Tokaj wine exporters represent expanding demand for hand-finished decorated glass. The country's implementation of EU packaging waste directives lags Austrian thresholds, creating regulatory arbitrage for early-compliant exporters. Győr automotive suppliers increasingly specify Austrian glass for technical fluid containers.
Slovakia
Bratislava beverage bottlers and Košice food processors rely on Danube-borne Austrian supply for jar and bottle formats. Slovak national environmental agency enforcement of extended producer responsibility schemes tightens gradually. The Trnava industrial zone hosts filling lines calibrated specifically for Vetropack Stockerau output specifications.
Austria Container Glass Market Competitive Landscape
Top-tier vendors anchor high-volume furnace operations, while mid-scale specialists occupy premium niches requiring pharmacopeial certification or artisanal finishing. The market structure concentrates around three furnace complexes along the Danube corridor, with secondary players serving decoration and distribution layers. Strategic archetypes include integrated melt-to-decorate operators, precision pharmaceutical specialists, and regional trading intermediaries. Competitive moves center on electrified furnace retrofits and direct procurement relationships displacing traditional distribution channels.
Among Austrian-based producers, Vetropack Austria GmbH, Stoelzle Oberglas GmbH, and Cristallo Glas GmbH occupy distinct tier positions. Vetropack represents the scale-driven archetype with continuous campaign furnace operations. Stoelzle exemplifies the precision-specialist position serving regulated pharmaceutical and cosmetic end uses. Cristallo Glas anchors the artisanal tier where hand-finishing commands heritage premiums from regional distilleries.
| Leading Market Players |
|---|
| Vetropack Austria GmbH |
| Stoelzle Oberglas GmbH |
| Cristallo Glas GmbH |
| Etivera Verpackungstechnik GmbH |
| Muller Glas & Co Handelsgesellschaft mbH |
| Stölzle Glass Group |
| Vetropack Group |
| Beatson Clark Ltd |
| Ardagh Group S.A. |
| Others |
Pricing and Supply Chain Analysis
Electrified furnace retrofits across the Stockerau corridor are compressing melt economics while concentrating procurement leverage among buyers with multi-year offtake commitments. EU ETS carbon pricing and natural gas volatility are forcing operators to renegotiate contract structures that embed energy-cost pass-through clauses, fundamentally reshaping how pricing power distributes across the value chain.
Pricing Analysis
Lead-time premiums for six-week mold-to-delivery cycles command substantial markups over standard twelve-week campaigns in the artisanal spirits channel. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified borosilicate vials from commodity soda-lime beer bottles and spot-market jar formats. Cost compression in standard beverage tiers is intensifying because aluminum can substitution erodes volume commitments. Private-label beer bottlers exhibit the highest price sensitivity, while Swiss pharmaceutical houses accept premium positioning for pharmacopeial-grade flacons.
Supply Chain Analysis
Direct-to-distillery channels are displacing traditional distributor intermediaries for decorated glass orders in Vienna's craft gin segment. Melt capacity concentrates in Austria, Germany, and the Czech Republic, with raw material sourcing drawing from German silica sand deposits, Czech soda ash, and recycled domestic cullet. Single-source vulnerability in natural gas supply from Russian pipeline corridors remains the dominant structural risk. Distribution runs through Danube barge networks and cross-border rail corridors serving Central European filling lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cullet preprocessing and captive renewable energy generation is becoming the decisive competitive lever as EU Green Deal mandates harden. Players securing upstream control over batch chemistry and scope 1 emissions will capture margin expansion unavailable to merchant-market operators.
For Market Incumbents: Hedge against aluminum can substitution by locking multi-year offtake agreements with Bavarian craft breweries before 2030 recycled-content thresholds tighten. Secure electrode array partnerships for hybrid-electric furnace retrofits at Stockerau assets to defend melt economics against TTF price spikes. Prioritize in-house production of optical sorting equipment to reduce cullet-quality fragmentation costs.
For New Entrants and Emerging Players: E-commerce-enabled direct procurement platforms offer the most penetrable route into Upper Austria's artisanal distillery segment, where heritage storytelling commands price premiums unavailable to commodity suppliers. Target hand-finished decorated bottles for regional schnapps producers in Burgenland and Lower Austria. Pursue white-label mold design services that compress lead times from twelve weeks to six for craft gin brand owners.
For Investors and Strategic Acquirers: Re-rating potential sits with precision pharmaceutical specialists given EMA pharmacopeial standard tightening and Swissmedic certification requirements. Long-term viability over the coming decade hinges on electrified furnace technology deployment and verified carbon-neutral product lines. Monitor EU carbon border adjustment implementation timelines as the critical inflection indicator for domestic melt capacity utilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Furnace Retrofit | Plasma torch installations at Stockerau cut scope 1 emissions ahead of EU ETS tightening. |
| Backward Integration into Cullet Preprocessing | Captive optical sorting secures 65% recycled-content compliance without quality degradation. |
| Direct Procurement Platform Launch | Digital channels displace distributor intermediaries in Vienna craft gin and amaro segments. |
| Pharmacopeial Certification Investment | EMA hydrolytic stability standards narrow supplier base for Swiss injectable vial demand. |
| Renewable Energy Power Purchase Agreement | Grid-scale wind and solar offtake enables carbon-neutral product lines commanding green premiums. |
Research Methodology
Multi-period observation of furnace utilization rates, cullet price indices, and EU ETS carbon allowance trends anchored the trend analysis, supplemented by interviews with plant managers at Austrian melt facilities, procurement leads at Bavarian beverage brands, pharmaceutical packaging engineers, and distribution channel partners across Central Europe. Secondary validation drew from EU customs trade data, ECHA REACH registration filings, Verpackungsverordnung implementation notices, and furnace technology patent disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic projections.
Segment-weighting across product type, end-use application, capacity tier, and packaging chemistry governed the analytical framework throughout the projection horizon. CAGRs were derived from regression analysis of historical production volumes against regulatory mandate implementation schedules and energy cost trajectories. Forecast inputs incorporated natural gas price volatility scenarios, electrified furnace deployment timelines, and cross-border trade flow assumptions for Central European export corridors.
The model holds under stable EU Green Deal implementation schedules and gradual TTF price normalization; deviation in carbon border adjustment timing or abrupt cullet supply disruptions would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Israel Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Dosing Bottles Market