
 North America Glass Bottles/Containers Market | 2026-2036
North America Glass Bottles/Containers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glass Bottles/Containers Market Foresight
Asset-light leasing models for furnace rebuilds and oxygen-generation equipment is narrowing the capital barrier for mid-tier producers seeking capacity expansion. O-I Glass, Inc leverages its vertical integration from silica mining to finished container production across multiple US states. Ardagh Group S.A. sustains competitive throughput via large-scale furnace operations on both sides of the US-Mexico border. Saint-Gobain North America anchors its position through specialized borosilicate and pharmaceutical-grade glass formulations.
Glass bottles and containers are rigid packaging vessels formed from silica sand, soda ash, limestone, and cullet, melted at approximately 1500°C and shaped by blow-and-blow or press-and-blow forming; their inert surface provides oxygen and moisture barriers for sensitive contents. Beverage containers dominate volume throughput due to carbonated soft drink and craft beer demand, while pharmaceutical vials command premium margins through stringent USP Type I borosilicate requirements. Cosmetic jars occupy a specialized niche where decoration intensity and small-batch color flexibility determine supplier selection.
FDA sets pharmaceutical glass standards under USP Chapter 660, while EPA enforces emissions limits on glass furnace operations under Clean Air Act provisions; OSHA mandates silica exposure controls that affect batch house operations across US facilities. Mexico's environmental regulator imposes parallel furnace emission rules that shape cross-border plant economics. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple US states and Canadian provinces that could shift post-consumer cullet collection economics.
Market Dynamics
Furnace rebuild cycles and oxygen-fuel conversion investments are compressing production economics across the North American container glass sector, forcing mid-tier producers toward asset-light leasing models or exit.
Growth Catalysts
- Extended Producer Responsibility frameworks:California and Oregon's post-consumer cullet mandates are tightening collection infrastructure, pulling recycled feedstock into domestic furnace supply chains.
- Premium spirits decoration intensity:Bourbon and tequila brands are expanding embossed and colored glass specifications, driving premiumization in Kentucky and Jalisco manufacturing corridors.
- Pharmaceutical USP Type I demand:Injectable drug packaging requirements under FDA Chapter 660 are locking in borosilicate volume commitments for parenteral vial producers.
Market Restraints
- Silica sand logistics concentration:High-purity silica deposits cluster near the Great Lakes and southeastern US, creating inbound freight exposure for Southwestern furnace operators.
- Natural gas price volatility:Melting energy constitutes the dominant variable cost input, with Henry Hub fluctuations directly compressing margin stability across continuous furnace operations.
- Aluminum can substitution:Beverage brands are expanding lightweight metal packaging for single-serve formats, constraining glass volume growth in carbonated soft drinks.
Strategic Opportunities
- Mexico manufacturing corridor expansion:Cross-border furnace operations near Monterrey and Guadalajara offer tariff-advantaged export positioning into US Southwest distribution networks.
- Lightweighting technology convergence:Thin-wall forming combined with predictive furnace control is opening material efficiency gains without structural integrity compromise.
- Cosmetic small-batch flexibility:Premium skincare brands are requesting rapid color change capability and short-run decoration, rewarding agile furnace scheduling over scale economies.
Industry Challenges
- Refractory specialist scarcity:Furnace rebuild and hot repair operations require disappearing craft expertise in silica crown and checker assembly.
- EPA Title V permitting timelines:Clean Air Act compliance certification for new or modified glass melting furnaces stretches 18-24 months, freezing capacity response speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glass Bottles/Containers Market |
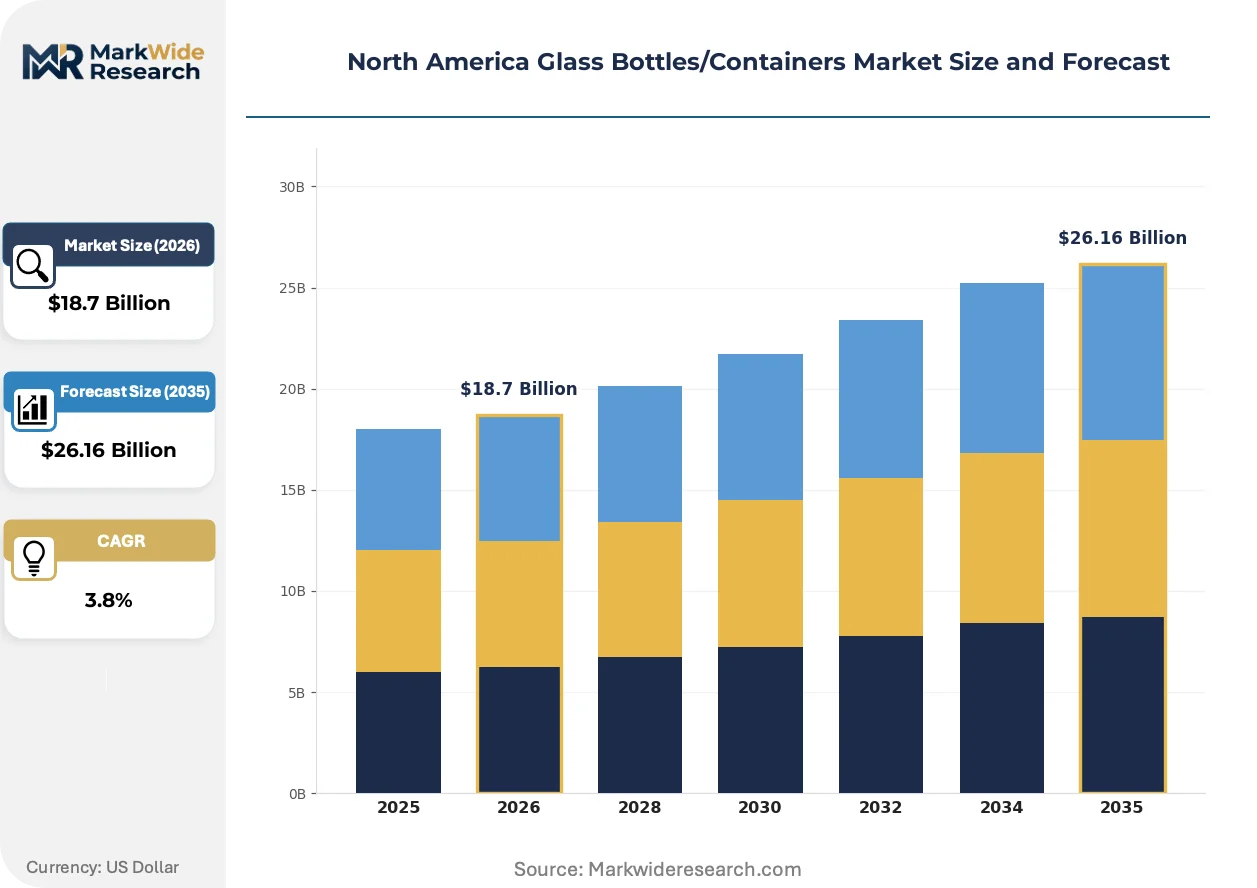
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
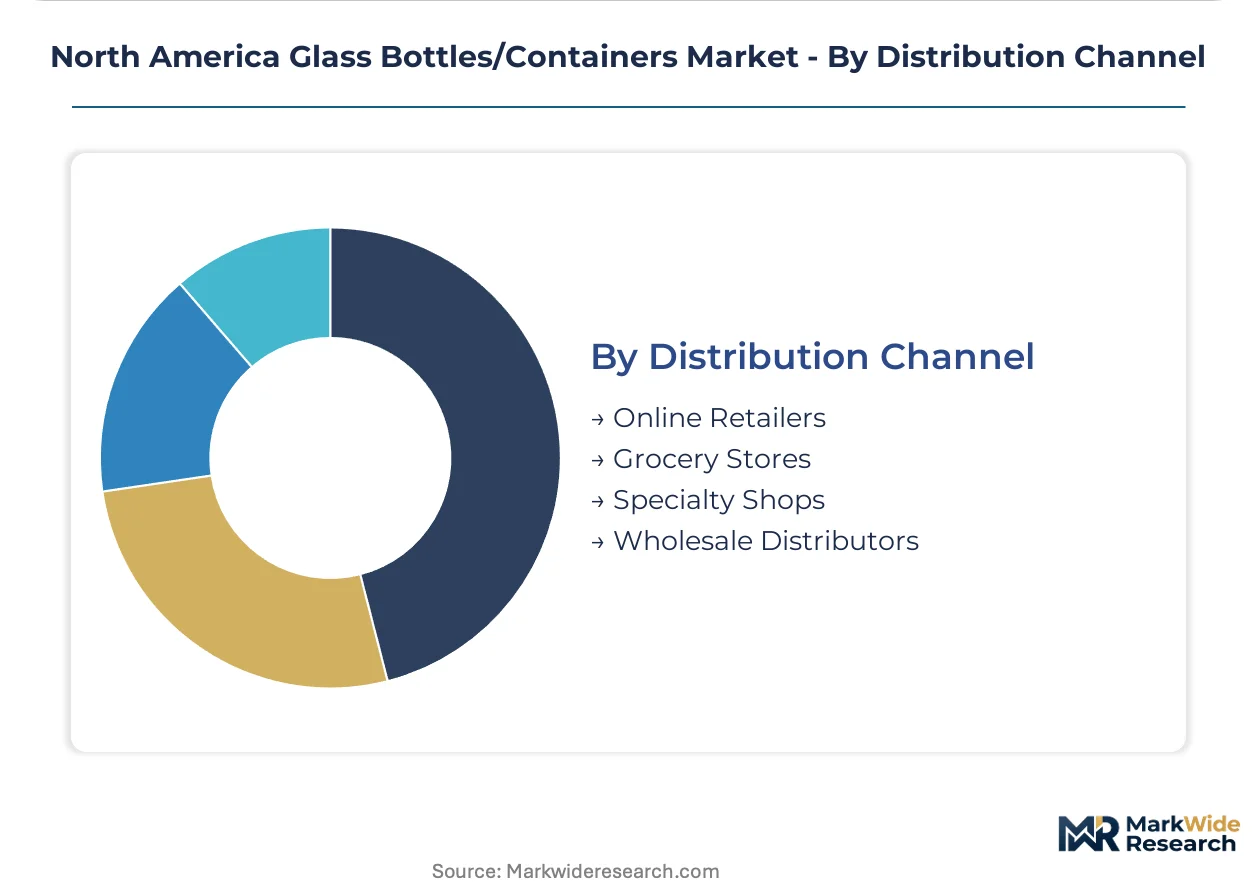
| Segmentation | Product Type: Wine Bottles, Beverage Containers, Cosmetic Jars, Pharmaceutical Vials End User: Food Industry, Personal Care, Pharmaceutical Companies, Chemical Manufacturers Capacity: Small (Up to 250ml), Medium (251ml - 500ml), Large (501ml - 1000ml), Extra Large (Over 1000ml) Distribution Channel: Online Retailers, Grocery Stores, Specialty Shops, Wholesale Distributors |
| Companies Covered | O-I Glass, Inc, Ardagh Group S.A., Anchor Glass Container Corporation, Gerresheimer AG, Vitro Packaging, Saint-Gobain North America, Stoelzle Glass Group, Kaufman Container, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glass Bottles/Containers Market Shifts & Advancements
Electrification of melting technology and predictive quality systems are restructuring capital deployment patterns across North American container glass manufacturing, compressing the traditional furnace economics playbook.
Plasma-assisted melting and hybrid electric-boost furnace architectures are collapsing the historical correlation between scale and thermal efficiency. Mid-size producers in Ohio and Pennsylvania are piloting 50-tonne daily capacity electric furnaces that match specific energy consumption of legacy 300-tonne gas-fired units. This technology is collapsing the minimum viable scale threshold for profitable container glass production.
EPA's pending Maximum Achievable Control Technology standards for glass furnace emissions are tightening particulate and nitrogen oxide limits under Clean Air Act Section 112. Installations lacking regenerative thermal oxidizers or advanced baghouse systems face retrofit capital burdens exceeding furnace rebuild costs. Pharmaceutical-grade borosilicate producers are responding earliest, prioritizing emission control investments to protect USP certification continuity.
Direct-to-brand procurement contracts are displacing traditional distributor intermediaries in premium beverage and cosmetic segments. Craft distilleries in Texas and Tennessee are contracting furnace operators for dedicated production runs with proprietary mold specifications. This channel compression is most visible in the US Southeast, where container glass plants are establishing in-house design studios to capture decoration specification authority from brand marketing teams.
North America Glass Bottles/Containers Market Segmentation

Segmentation in the North American container glass sector reveals how furnace scheduling, decoration complexity, and regulatory compliance requirements fragment production economics across distinct customer clusters. Each dimension exposes different margin structures and capital intensity thresholds that reshape supplier selection criteria.
Product Type:
Mature formats dominate furnace throughput while emerging specialty categories command pricing premiums through technical barriers.
- Beverage Containers:Standard amber and flint glass formulations serve carbonated soft drinks, craft beer, and ready-to-drink cocktails across high-volume continuous furnace operations. Kentucky and Wisconsin breweries anchor regional demand clusters where lightweighting specifications tighten.
- Pharmaceutical Vials:USP Type I borosilicate glass meets FDA Chapter 660 requirements for parenteral drug packaging, with thermal shock resistance and alkali leach limits specified for injectable stability. New Jersey and North Carolina biopharma corridors concentrate demand as sterile fill-finish capacity expands.
- Wine Bottles:Heavy-wall Bordeaux and Burgundy profiles with punt bottoms remain the standard for premium vineyard bottling, though screw-cap neck finishes are displacing traditional cork closures in entry-tier segments.
- Cosmetic Jars:Small-batch color flexibility and post-mold decoration intensity determine supplier selection for premium skincare brands requesting rapid furnace changeovers.
Beverage containers handle the majority of throughput; pharmaceutical vials are the fastest mover on share.
End User:
Customer type determines whether procurement prioritizes unit cost minimization or specification compliance intensity.
- Food Industry:Sauce, condiment, and preserve packagers specify wide-mouth jars with vacuum lug closures, with Indiana and California processing facilities driving seasonal demand spikes.
- Pharmaceutical Companies:Sterile manufacturing requirements under FDA cGMP mandate dedicated production lines with documented batch traceability and particle contamination controls.
- Personal Care:Fragrance and skincare brands request proprietary mold designs with embossed logos and metallic decoration, rewarding agile furnace scheduling over scale economies.
- Chemical Manufacturers:Industrial solvent and reagent packaging demands chemical-resistant soda-lime formulations with UN-certified closure systems for hazardous material transport.
Food industry procurement absorbs the highest absolute volume; pharmaceutical companies are expanding most quickly on contract value.
Capacity:
Volume tier aligns with distribution channel economics and brand positioning strategy across the price spectrum.
- Medium (251ml - 500ml):Standard wine bottles and spirits flasks occupy this core range where decoration premiums concentrate and mold changeover frequency optimizes furnace utilization.
- Small (Up to 250ml):Perfume minis, pharmaceutical ampoules, and sampler formats command per-unit premiums that offset lower line speeds and specialized handling requirements.
- Large (501ml - 1000ml):Magnum wine formats and family-size food jars serve club store and restaurant supply channels with reduced per-ounce packaging costs.
- Extra Large (Over 1000ml):Bulk chemical containers and display-grade spirit bottles face limited furnace compatibility and specialized logistics requirements.
Medium capacity formats carry the dominant production share; small formats are climbing the fastest as premium miniaturization trends accelerate.
Distribution Channel:
Channel structure determines whether glass suppliers engage directly with brand owners or through inventory-carrying intermediaries.
- Wholesale Distributors:Beverage and food service intermediaries aggregate demand across multiple brands, requiring standardized pallet configurations and just-in-time replenishment to regional warehouses.
- Online Retailers:E-commerce fulfillment demands damage-resistant secondary packaging and parcel-compatible case counts that depart from traditional retail pack sizes.
- Grocery Stores:Private-label and national brand shelf-stable categories specify high-volume, low-variation formats compatible with automated case packing and retail-ready displays.
- Specialty Shops:Craft distilleries and boutique cosmetics brands request short-run custom molds with proprietary decoration, bypassing distributor markups through direct furnace contracting.
Wholesale distributors channel the greatest volume throughput; specialty shops are gaining share fastest as brand-direct procurement compresses traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium beverage brand procurement teams concentrate in Kentucky bourbon corridors and Jalisco tequila districts, driving demand for embossed and colored glass specifications. Pharmaceutical sterile fill-finish operators cluster in New Jersey and North Carolina biopharma corridors. Container glass furnace operators position near high-purity silica deposits and cross-border distribution nodes.
United States
Kentucky bourbon distilleries and Tennessee craft spirits producers are expanding embossed glass specifications for premium shelf differentiation. EPA Title V permitting under the Clean Air Act stretches 18-24 months for new furnace installations, freezing rapid capacity response. Ohio and Pennsylvania host mid-size producers piloting electric-boost furnace architectures that collapse minimum viable scale thresholds.
Mexico
Jalisco tequila brands are driving colored glass demand through heritage packaging aesthetics for export markets. The environmental regulator imposes parallel furnace emission rules to EPA standards, shaping cross-border plant economics. Monterrey and Guadalajara manufacturing corridors offer tariff-advantaged positioning into US Southwest distribution networks.
Canada
Craft breweries in Ontario and Quebec are requesting lightweighted bottles for reduced freight costs in export channels. Extended producer responsibility frameworks in multiple provinces are tightening post-consumer cullet collection infrastructure. The Great Lakes region anchors silica sand logistics for cross-border furnace feedstock.
North America Glass Bottles/Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered furnace capacity segments. The market structure consolidates around large-scale integrated operators with captive silica mining and multi-state production networks, while mid-tier producers pursue asset-light leasing models for oxygen-generation equipment and furnace rebuilds. Two strategic archetypes dominate: vertically integrated volume players with backward integration into raw material sourcing, and agile specialists capturing premium decoration contracts through rapid color-change capability. Competitive moves concentrate on cross-border capacity positioning and lightweighting technology licensing.
Among North American integrated operators, O-I Glass, Inc and Ardagh Group S.A. exemplify the scale-driven archetype with multi-state furnace networks spanning silica mining through finished container production. Saint-Gobain North America occupies a specialist position through borosilicate and pharmaceutical-grade formulations that command premium pricing under USP Type I certification requirements. These three companies represent distinct competitive vectors: volume integration, cross-border tariff optimization, and technical specification leadership.
| Leading Market Players |
|---|
| O-I Glass, Inc |
| Ardagh Group S.A. |
| Anchor Glass Container Corporation |
| Gerresheimer AG |
| Vitro Packaging |
| Saint-Gobain North America |
| Stoelzle Glass Group |
| Kaufman Container |
| Berlin Packaging |
| Others |
Supply & Pricing Matrix
Henry Hub natural gas volatility compresses margin stability across continuous furnace operations while simultaneously widening spreads between oxygen-fuel converted and legacy regenerative furnace output. This input-cost instability rewards producers with captive silica mining and long-term fuel hedging, reshaping tier boundaries between integrated majors and leasing-dependent mid-tiers.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks and silica sand spot markets dominate procurement between furnace operators and beverage brand owners. Price differentiation rests on USP Type I certification tier and decoration complexity, with pharmaceutical vials commanding premiums against commodity amber beer bottles. Pricing pressure intensifies in standard flint glass as aluminum can substitution accelerates in single-serve carbonated formats. Mass-market beverage packagers exhibit acute price sensitivity, while craft spirits brands prioritize mold exclusivity over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have proliferated among distributors serving grocery and food service channels, squeezing working capital for mid-tier furnace operators. Raw material sourcing draws from high-purity silica deposits near the Great Lakes, Mexican soda ash from Coahuila, and limestone from Ohio River valley quarries. Single-source vulnerability concentrates in specialized borosilicate cullet for pharmaceutical-grade melting. Distribution runs through wholesale beverage distributors and direct-to-brand procurement studios in Kentucky and Jalisco manufacturing corridors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage brand consolidation into multinational portfolios concentrates procurement volume and specification authority among fewer buyers with dedicated supply chain teams. This buyer-power shift compresses intermediary margins and rewards furnace operators with direct contracting capabilities.
For Market Incumbents: Insulate USP Type I certification continuity through regenerative thermal oxidizer investments ahead of EPA Maximum Achievable Control Technology standards. Deepen backward integration into silica mining near the Great Lakes to offset inbound freight exposure for Southwestern furnace networks. Prioritize oxygen-fuel conversion leasing models to preserve capital flexibility against natural gas price swings.
For New Entrants and Emerging Players: Small-batch cosmetic color flexibility in Pennsylvania and Ohio represents the most penetrable entry point, where premium skincare brands reward rapid furnace changeovers over scale economies. Electric-boost furnace architectures at 50-tonne daily capacity collapse minimum viable scale thresholds previously guarded by integrated majors. Pursue direct contracting with craft distilleries in Texas and Tennessee seeking proprietary mold specifications.
For Investors and Strategic Acquirers: EPA Title V permitting timelines reshaping the acquisition landscape favor targets with grandfathered air quality permits or completed regenerative thermal oxidizer installations. Long-term viability centers on cross-border furnace positioning with tariff-advantaged access to US Southwest distribution. Monitor California and Oregon extended producer responsibility implementation as the signal for cullet collection infrastructure investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxygen-Fuel Furnace Conversion | Reduces melting energy intensity and aligns with EPA Clean Air Act emission limits. |
| Backward Integration into Silica Mining | Captive high-purity sand supply secures feedstock quality and freight cost control. |
| Electric-Boost Furnace Piloting | Mid-size producers in Ohio and Pennsylvania match legacy thermal efficiency without scale. |
| Direct-to-Brand Design Studios | In-house decoration specification authority captures premium spirits and cosmetic contracts. |
| Cross-Border Capacity Expansion | Monterrey and Guadalajara corridors offer tariff-advantaged US Southwest market access. |
Research Methodology
Desk research of trade association publications, EPA enforcement databases, and customs import records preceded structured interviews with furnace operations managers, beverage brand procurement directors, pharmaceutical packaging engineers, and cosmetic brand supply chain leads. Secondary validation drew from SEC 10-K filings of publicly traded container glass producers, state environmental regulator permit databases, and silica sand mining lease records. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-border trade flow analysis.
Assumptions held fixed across the analysis window include EPA Title V permitting timelines, Henry Hub natural gas price bands, and extended producer responsibility implementation schedules in California and Oregon. Segmentation dimensions modeled encompass product type, end-user industry, capacity tier, and distribution channel. CAGRs were derived from production capacity utilization rates and end-user demand growth trajectories. Forecast inputs incorporated furnace rebuild cycle timing and lightweighting technology adoption curves.
Stress conditions across natural gas price volatility, silica sand logistics disruption, and aluminum can substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction, accelerated EPA emission standard tightening, or breakthrough electric melting technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Austria Container Glass Market