
 Paragon Glass Jar Market | 2026-2036
Paragon Glass Jar Market Size, Share, and Industry Trends Forecast 2026-2036
Paragon Glass Jar Market Analytics
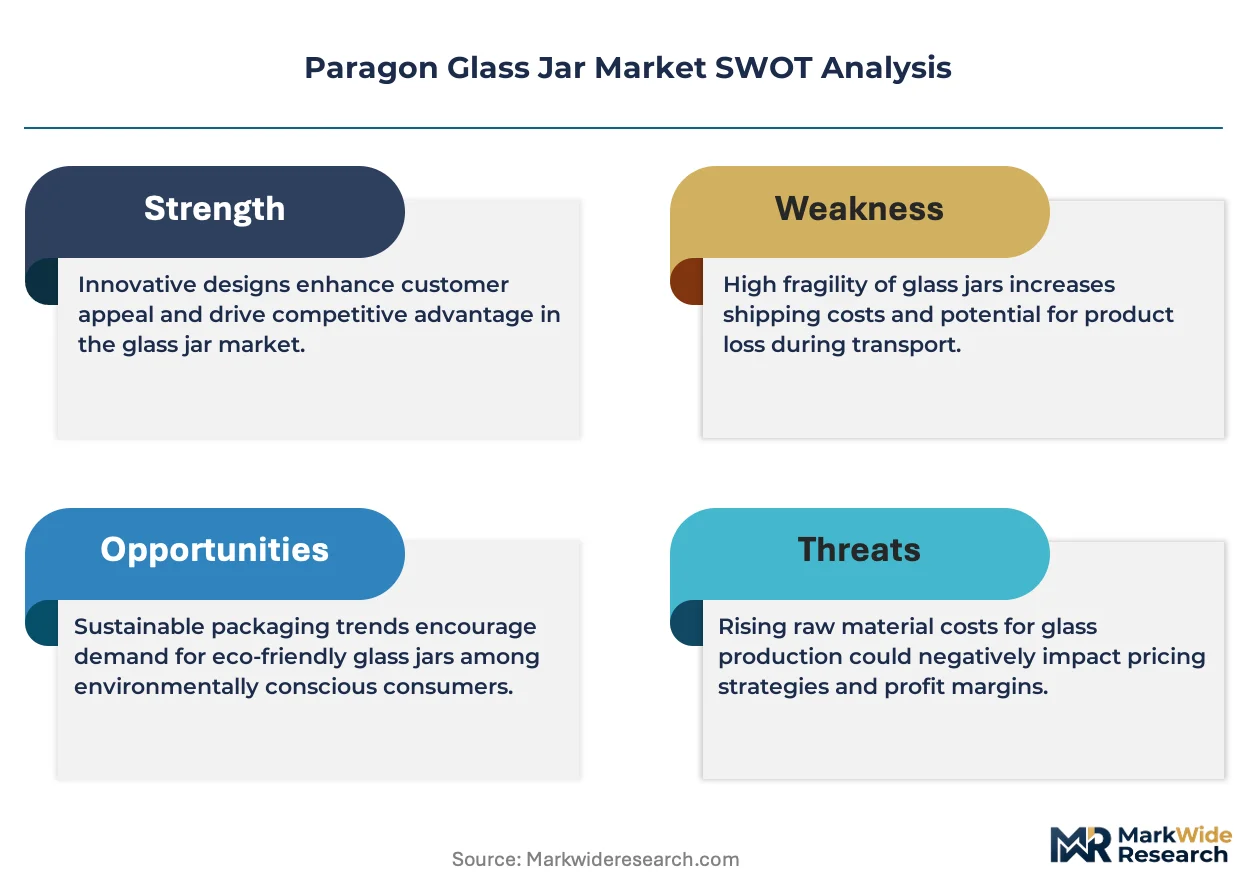
E-commerce direct-to-consumer channels is reshaping how paragon glass jars reach end buyers, with subscription box services and online specialty food retailers bypassing traditional wholesale distribution. Berlin Packaging leverages its North American fulfillment network to sustain rapid replenishment for digital-native food brands. Ball Corporation anchors industrial-scale production through its metal-and-glass hybrid manufacturing footprint. O-I Glass, Inc. competes on furnace efficiency and recycled cullet integration across multiple continents.
A paragon glass jar denotes a tall, narrow-walled cylindrical container formed from soda-lime silica glass, typically featuring a continuous thread finish for metal or plastic closures and manufactured through blow-and-blow or press-and-blow forming at temperatures exceeding 1,200°C. Its elongated profile maximizes shelf-facing efficiency while minimizing headspace, making it preferred for viscous food products, candles, and apothecary applications. Standard jars dominate volume throughput in commercial food processing, while specialty jars command margin premiums through custom embossing and colored glass options. Decorative jars are gaining traction in home décor and gift segments where aesthetic differentiation drives replacement purchases. Storage jars retain steady household demand through modular pantry organization trends.
FDA food-contact substance regulations govern closure compatibility and thermal shock thresholds for jars distributed in the United States, while the EU F-Gas Regulation and REACH framework constrain fluorinated coating chemistries used in decorative surface treatments. Germany's national packaging ordinance, implementing EU directives, mandates minimum recycled glass quotas that elevate cullet sourcing costs for manufacturers serving European buyers. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will alter cost structures for imported glassware.
Market Dynamics
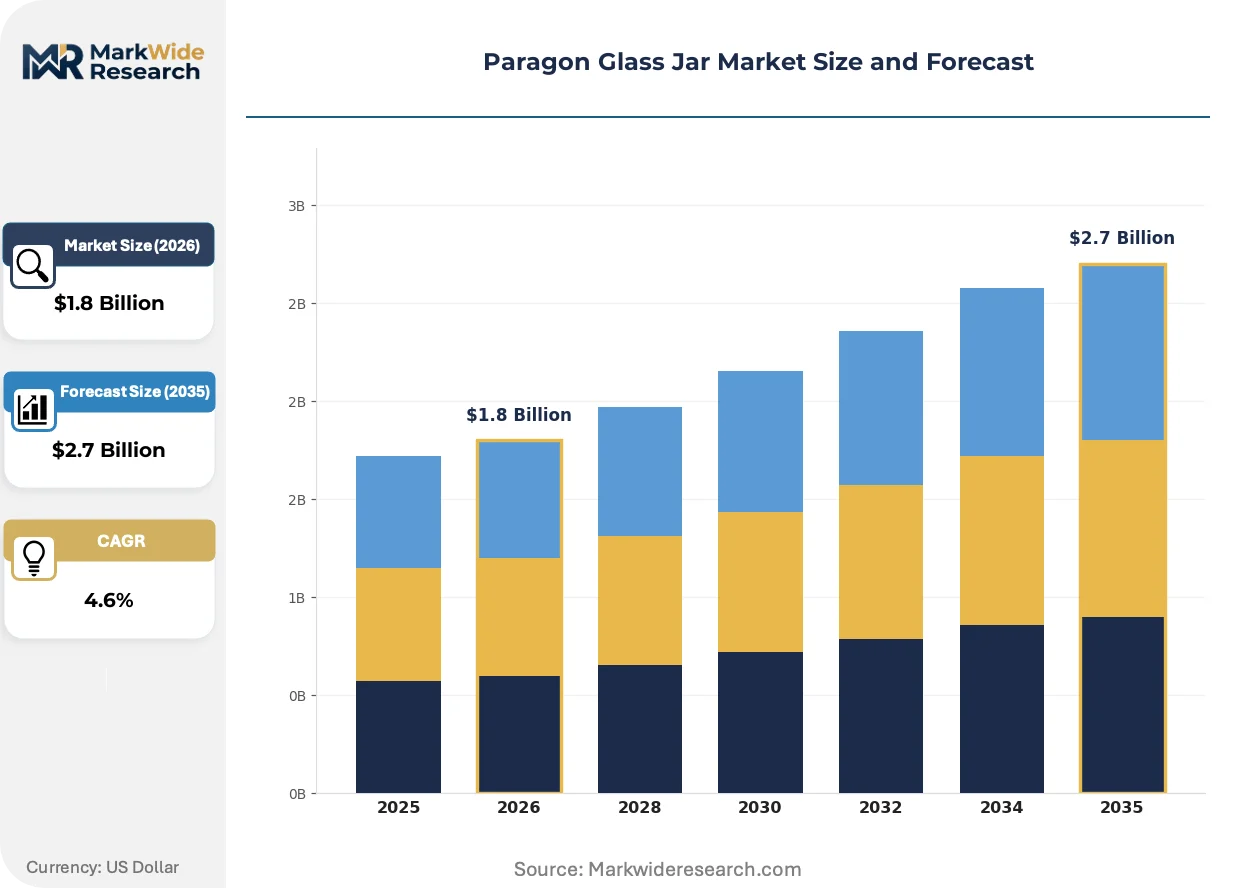
EU Packaging and Packaging Waste Regulation mandates are compressing recycled glass sourcing economics while e-commerce direct-to-consumer channels reconfigure distribution topology for specialty food packaging buyers.
Growth Catalysts
- Recycled Content Mandates:Germany's national packaging ordinance implementing EU directives establishes minimum cullet quotas that elevate demand for furnace-ready recycled glass feedstock. Specialty food producers respond by specifying premium paragon jars with verified post-consumer content.
- Artisanal Food Expansion:Craft preserve and condiment makers in Berlin and Hamburg clusters are converting to tall-profile glass packaging for shelf differentiation and premium positioning. These producers favor continuous-thread finishes for tamper-evident metal closures.
- Modular Pantry Organization:Household storage applications are gaining velocity through stackable jar systems designed for vertical cabinet efficiency. Consumers prioritize uniform cylindrical profiles that maximize cubic utilization in residential kitchens.
Market Restraints
- Natural Gas Price Volatility:Soda-lime silica melting requires furnace temperatures exceeding 1,200°C, making glass production acutely sensitive to European energy input costs. German manufacturers face margin compression when benchmark gas prices spike.
- Fluorinated Coating Constraints:EU REACH framework and F-Gas Regulation limit decorative surface treatment chemistries available for colored and embossed specialty jars. Apothecary and candle segments lose certain aesthetic differentiation options.
- Aluminum Can Substitution:Metal packaging captures share in viscous food categories where thermal shock resistance matters less than logistics weight reduction. Industrial-scale food processors evaluate hybrid metal-and-glass formats.
Strategic Opportunities
- Subscription Box Penetration:Digital-native food brands bypass wholesale distribution through curated monthly delivery services. Paragon jar suppliers can embed directly into these replenishment workflows.
- Carbon Border Adjustment Positioning:EU carbon border mechanisms will penalize imported glassware with high embodied emissions. German furnace operators with integrated cullet streams gain cost advantage against non-European competitors.
- Candle and Home Décor Pivot:Decorative jar variants command margin premiums through custom embossing and colored glass options. Aesthetic differentiation drives replacement purchases in gift and interior design channels.
Industry Challenges
- Furnace Refractory Expertise Scarcity:Blow-and-blow and press-and-blow forming require specialized thermal engineering knowledge. German glassworks compete for limited talent pools capable of optimizing cullet integration rates.
- Extended Producer Responsibility Compliance:Evolving EU schemes impose complex tracking and fee structures on packaging producers. Stakeholders must build data infrastructure for lifecycle accountability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paragon Glass Jar Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Jars, Decorative Jars, Storage Jars, Specialty Jars End User: Households, Restaurants, Bakeries, Retail Stores Application: Food Storage, Beverage Packaging, Home Décor, Craft Use Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berlin Packaging, MJS PACKAGING, Ball Corporation, Anchor Hocking, Vanjoin Hubei Industry, Ardagh Group, Piramal Glass, Bormioli Rocco, O-I Glass, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paragon Glass Jar Market Evolving Landscape
Electrification of glass melting and digital-native distribution models are restructuring how paragon jars are manufactured, regulated, and procured across European food packaging value chains.
Hybrid electric-boosted furnace technology is collapsing the carbon intensity differential between virgin and high-cullet glass production. German manufacturers adopting plasma-assisted melting achieve thermal uniformity at lower fossil fuel inputs. O-I Glass furnace efficiency investments now target 90% recycled content thresholds without quality degradation.
EU F-Gas Regulation amendments are constraining fluoropolymer liner chemistries in metal closures paired with paragon jars. Closure manufacturers reformulate gasket materials to maintain hermetic seals under thermal shock. Specialty food exporters to Germany must certify alternative barrier technologies through ECHA substance evaluation.
Direct procurement from specialty food brands is displacing traditional distributor intermediaries in jar sourcing. Berlin-based craft producers negotiate specifications directly with packaging converters, compressing lead times and enabling custom embossing runs. This channel shift concentrates demand intelligence with digital-native buyers rather than legacy wholesale networks.
Paragon Glass Jar Market Segmentation
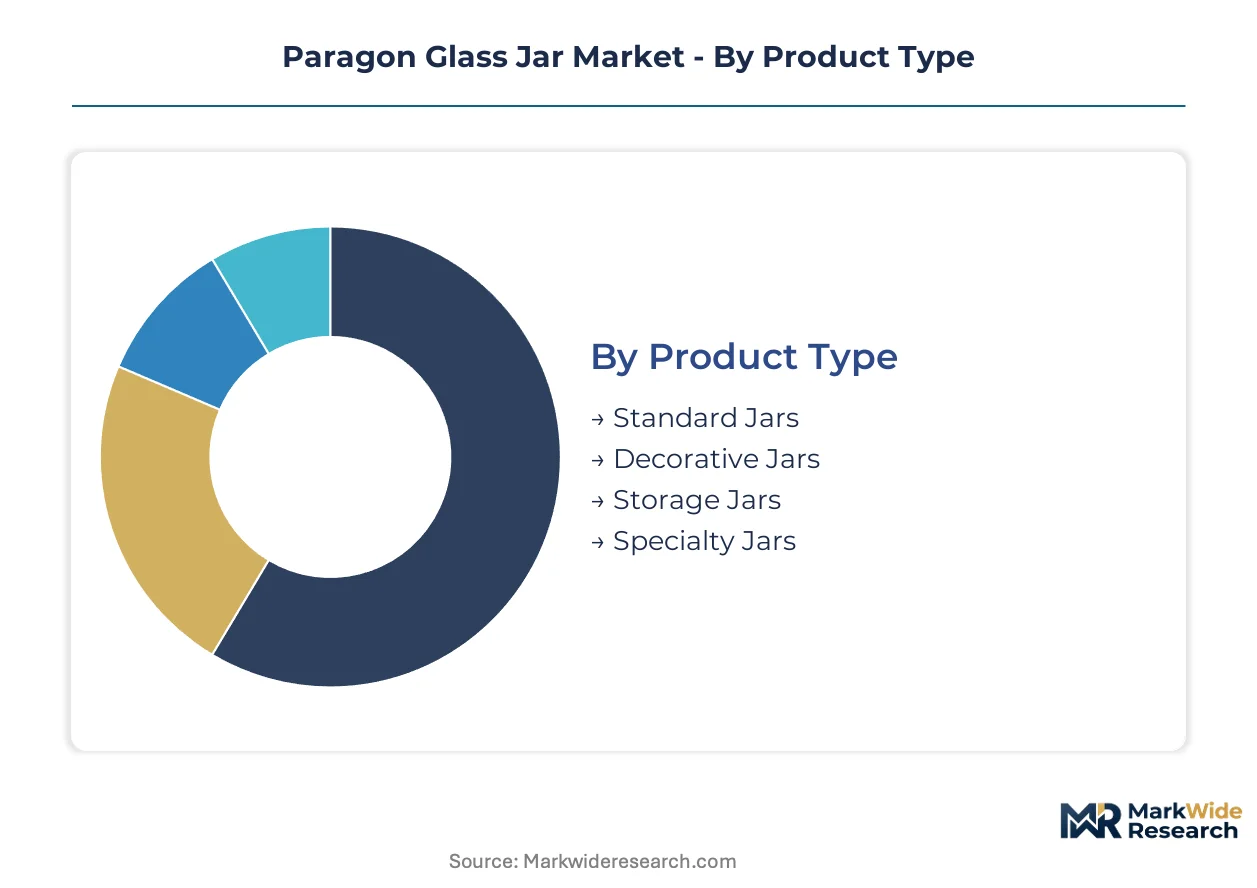
Paragon glass jar procurement patterns diverge sharply across product tiers and use contexts. Manufacturers configure furnace runs and finishing lines around these segment-specific demand profiles rather than treating the category as uniform commodity glassware.
Product Type:
Mature formats anchor commercial throughput while emerging variants capture margin expansion through customization premiums.
- Standard Jars:Continuous-thread cylindrical containers produced through blow-and-blow forming at 1,200°C furnace temperatures. Food processors in Germany specify these for viscous preserves and condiments where hermetic metal closures and thermal shock resistance matter. Standard jars retain volume leadership; specialty jars hold the steepest expansion curve.
- Specialty Jars:Custom-embossed or colored glass variants commanding premium positioning through aesthetic differentiation. Berlin craft food brands and Hamburg artisanal producers specify tall-profile specialty formats for shelf-facing efficiency and brand signaling in direct-to-consumer channels.
- Decorative Jars:Surface-treated containers for candle and home décor applications where visual appeal drives replacement purchases. EU REACH and F-Gas Regulation constrain fluorinated coating chemistries available for these finishes.
- Storage Jars:Modular cylindrical systems designed for vertical pantry organization and stackable cabinet efficiency. German households prioritize uniform profiles maximizing cubic utilization in residential kitchens.
Standard jars dominate tonnage through industrial food contracts; specialty jars expand fastest via craft brand direct procurement.
End User:
Customer type stratification runs from mass household replacement cycles to concentrated commercial procurement with specification authority.
- Households:Residential buyers purchasing through retail and e-commerce channels for pantry organization and home preservation. Modular stackable systems gain traction through social media-driven kitchen aesthetic trends.
- Restaurants:Food service operations specifying paragon formats for in-house preserve programs and condiment service. Berlin and Hamburg independent restaurants source directly from packaging converters, bypassing traditional wholesale distribution.
- Bakeries:Artisanal producers requiring tamper-evident closures for shelf-stable fillings and spreads. These operators favor continuous-thread finishes compatible with metal lug caps.
- Retail Stores:Specialty food retailers and subscription box curators procuring custom-embossed jars for private label and gift assortments. Digital-native brands in this channel negotiate specifications directly with glass converters.
Households generate the broadest demand base; retail stores and restaurants together drive the fastest specification innovation.
Application:
Use-case segmentation separates functional food-contact requirements from aesthetic-driven non-food applications with divergent regulatory exposure.
- Food Storage:FDA-governed and EU food-contact compliance for viscous preserves, condiments, and dry goods. German craft producers specify tall narrow-walled profiles minimizing headspace oxidation for artisanal products.
- Beverage Packaging:Thermal shock-resistant formats for ready-to-drink and concentrate applications. Soda-lime silica composition must withstand pasteurization temperature differentials.
- Home Décor:Candle vessels and interior design objects where colored glass and custom embossing command margin premiums. This application escapes food-contact regulatory burden but faces EU F-Gas constraints on decorative coatings.
- Craft Use:Small-batch apothecary and DIY applications requiring hermetic seals without industrial-scale volume commitments. Berlin maker communities drive demand for mixed-size assortments.
Food storage retains volume concentration; home décor climbs fastest as candle and gift segments expand.
Size:
Capacity tiering aligns with pantry modularity standards and commercial processing line configurations.
- Small:Single-serve and sampler formats for subscription box inclusion and hotel amenity programs. These sizes maximize shelf-facing density for premium positioning.
- Medium:Standard household pantry units matching modular organization system dimensions. German kitchen cabinet manufacturers coordinate with jar suppliers on cubic efficiency standards.
- Large:Commercial food service and family-size formats for bulk preserve production. Restaurants and bakeries specify these for operational efficiency in high-turnover applications.
- Extra Large:Industrial-scale and display formats for retail merchandising and professional kitchen bulk storage. Limited demand concentration in specialty food manufacturing clusters.
Medium sizes dominate unit volume through household pantry standardization; small formats gain share fastest via subscription commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput infrastructure anchors Germany's role as the primary European distribution hub for paragon glass jar imports and re-export to Nordic markets.
Germany
Artisanal food producers in Berlin and Hamburg clusters drive specialty jar procurement for premium preserves and condiments. The national packaging ordinance implementing EU directives mandates minimum recycled glass quotas that elevate cullet sourcing costs. O-I Glass operates furnace facilities with integrated recycled feedstock streams serving these urban manufacturing zones.
United States
FDA food-contact substance regulations govern closure compatibility standards for jars distributed across interstate commerce. Specialty food brands leverage e-commerce direct-to-consumer channels to bypass traditional wholesale distribution networks. Ball Corporation maintains industrial-scale production capacity through its metal-and-glass hybrid manufacturing footprint.
China
GB standards and SAMR oversight constrain decorative surface treatment chemistries for export-oriented glassware production. The dual carbon goals framework pressures furnace operators to electrify melting processes and reduce coal-derived energy inputs. Zhengzhou and Shandong industrial clusters concentrate blow-and-blow forming capacity for international buyers.
Italy
EU REACH framework limits fluorinated coating applications on colored and embossed specialty jars destined for apothecary segments. Bormioli Rocco anchors domestic production expertise in furnace thermal engineering and cullet integration optimization. Emilia-Romagna and Lombardy regions host concentrated glassworks serving Mediterranean export routes.
India
FSSAI compliance requirements shape food-contact packaging specifications for domestic viscous preserve applications. Piramal Glass operates manufacturing assets positioned to serve both local artisanal producers and export markets. Maharashtra and Gujarat industrial corridors concentrate soda-lime silica melting capacity with rising recycled content adoption.
Paragon Glass Jar Market Competitive Landscape
On the supply side, the industry is consolidating around furnace-scale operators with integrated cullet streams and regional packaging specialists with direct-to-brand digital channels. Three archetypes dominate: industrial-scale glass manufacturers with multi-continent furnace networks, mid-cap converters serving craft food clusters through custom specification capabilities, and hybrid metal-and-glass packaging conglomerates. Competitive moves concentrate on strategic partnerships with subscription box curators and capacity expansion in high-cullet furnace technology.
Among North American fabricators, Berlin Packaging exemplifies the digital-native distribution archetype through its fulfillment network positioning. Ball Corporation occupies the industrial-scale tier with hybrid manufacturing scope. O-I Glass, Inc. anchors the furnace efficiency segment with multi-continent recycled cullet integration capabilities.
| Leading Market Players |
|---|
| Berlin Packaging |
| MJS PACKAGING |
| Ball Corporation |
| Anchor Hocking |
| Vanjoin Hubei Industry |
| Ardagh Group |
| Piramal Glass |
| Bormioli Rocco |
| O-I Glass, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese furnace operations compresses margin structures for export-oriented paragon jar producers, forcing European converters toward premium specialty tiers where specification authority offsets commodity pricing pressure.
Pricing Analysis
Volume-discount tiering separates custom-embossed specialty jars from standard blow-and-blow formats. Pricing stratifies across premium, standard, and economy tiers based on cullet content certification and continuous-thread finish complexity. Cost compression in standard jars intensifies as German energy input volatility feeds through to furnace economics. Craft food brands in Berlin show least price sensitivity; industrial food processors exhibit highest elasticity to unit cost shifts.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for decorative jar imports. Glass production concentrates in China, Germany, and Italy, with Zhengzhou and Shandong clusters feeding export demand. Soda-lime silica feedstock, natural gas energy inputs, and metal closure components anchor material dependencies. Single-source vulnerability persists in furnace-ready cullet streams. Distribution runs through Hamburg port infrastructure for Nordic re-export and direct-to-brand digital channels for craft food clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paragon jar procurement is accelerating as a service-attach opportunity as subscription box fulfillment and custom embossing services expand faster than commodity container hardware.
For Market Incumbents: Insulate furnace economics through backward integration into cullet collection networks and captive natural gas hedging instruments. Aluminum can substitution in viscous food categories threatens volume share; respond with thermal shock-resistant hybrid formats. Capacity addition in Emilia-Romagna leverages existing Italian glassworks expertise. For New Entrants and Emerging Players: Pursue modular pantry organization systems through stackable small-format assortments targeting German household retail channels. Candle and home décor applications present the most penetrable segment given EU F-Gas constraints on incumbent decorative coating portfolios. Direct procurement relationships with Berlin-based craft producers offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility schemes and carbon border adjustments will revalue integrated cullet-stream assets. Target mid-cap converters with direct-to-brand digital channels and furnace efficiency investments. Watch EU Packaging and Packaging Waste Regulation enforcement timing as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Collection | Secures furnace-ready recycled feedstock streams ahead of EU quota mandates. |
| Direct-to-Brand Digital Channel Development | Bypasses wholesale intermediaries for Berlin craft food producer relationships. |
| Hybrid Electric-Boosted Furnace Investment | Collapses carbon intensity differential for high-recycled-content glass production. |
| Subscription Box Fulfillment Partnership | Embeds paragon jars into curated monthly delivery workflows for digital-native brands. |
| Custom Embossing and Colored Glass Capability | Captures margin premiums in candle and home décor aesthetic differentiation segments. |
Research Methodology
A standing panel of furnace operations managers, packaging procurement leads at specialty food brands, closure manufacturing engineers, and e-commerce fulfillment directors provided ongoing calibration. Primary interviews combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA substance evaluations, German customs trade data, and SEC disclosures from listed glass manufacturers. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Scenario-bracketing around natural gas price volatility and recycled cullet availability framed the projection horizon. Segmentation dimensions modeled include product type tier, end-user category, application use-case, and size capacity across the analysis window. CAGRs derived from furnace throughput trends, craft food brand formation rates, and subscription commerce penetration curves.
Macroeconomic conditions sit as an overlay; deviation in European energy input costs or EU carbon border adjustment implementation timing would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement and technology adoption without guarantee of realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Boston Round Glass Bottle Market